
North America Wire and Cable Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 37.71 Billion |
| Market Size (2026) | USD 39.45 Billion |
| Market Size (2031) | USD 49.44 Billion |
| Growth Rate (2026 - 2031) | 4.62 % |
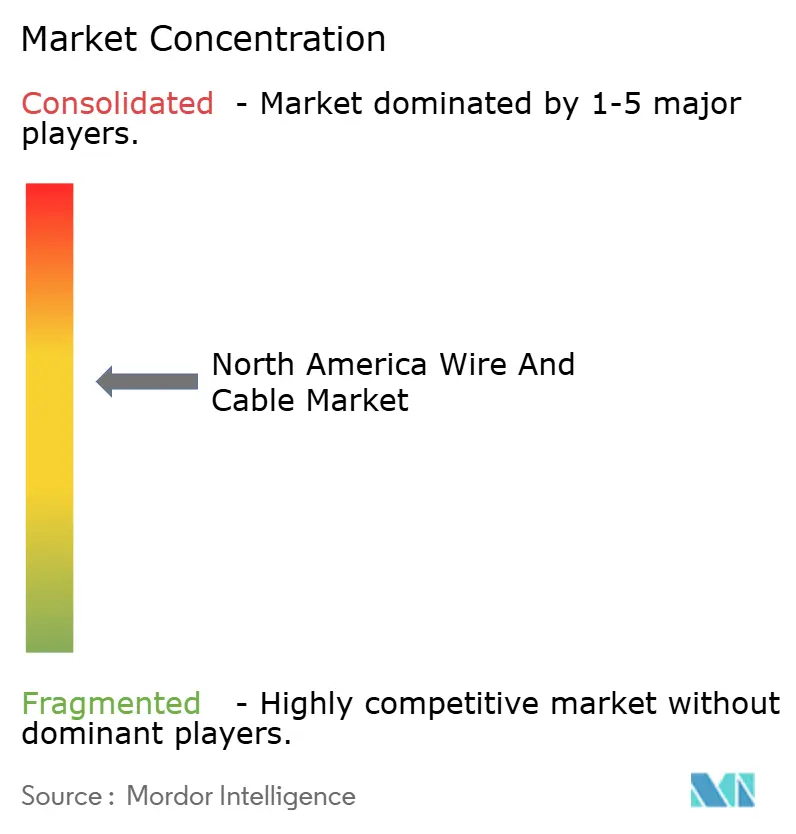
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
North America Wire and Cable Market Analysis by 黑料不打烊
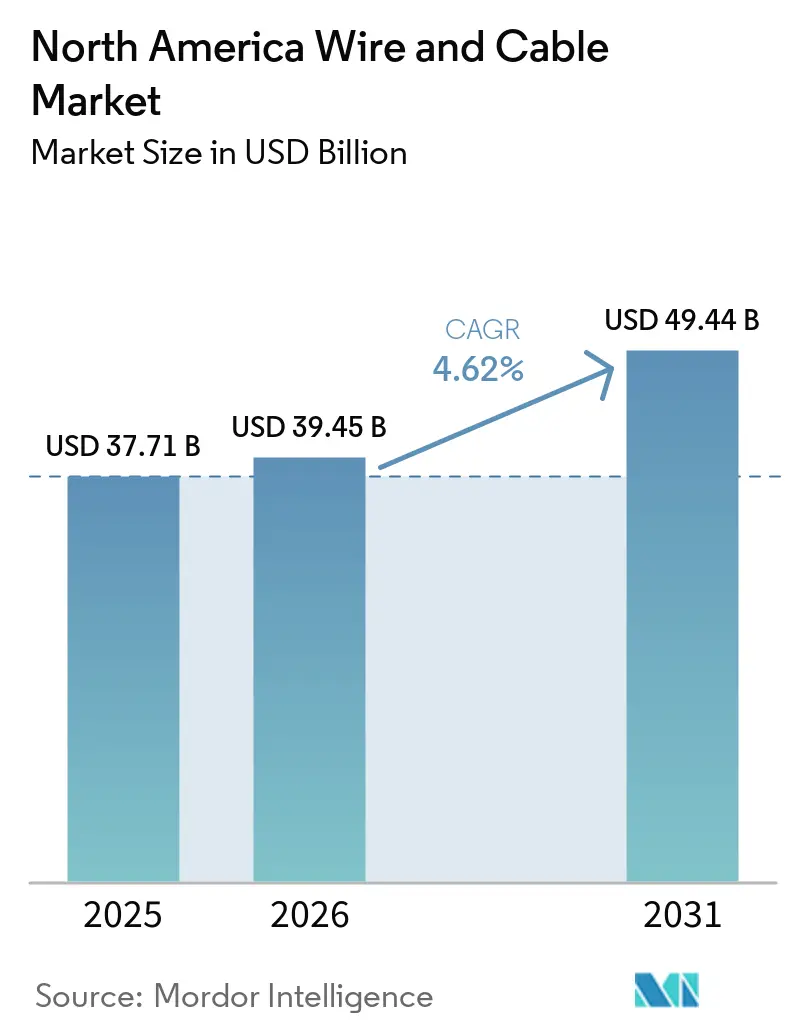
The North America wire and cable market size is expected to grow from USD 37.71 billion in 2025 to USD 39.45 billion in 2026 and is forecast to reach USD 49.44 billion by 2031 at 4.62% CAGR over 2026-2031. This expansion mirrors accelerating grid-modernization programs funded by the Bipartisan Infrastructure Law, a surge in renewable-energy interconnections, and hyperscale data-center construction that together underpin multi-year purchasing pipelines for regional manufacturers. Utilities are re-weighting procurement priorities toward supply-chain resilience over lowest-price bids, incentivizing domestic capacity additions under Buy America content thresholds.[1]U.S. Department of Energy, “Evaluating Electricity Procurement Options for Federal Agencies,” ENERGY.GOV Composite-core conductors, high-density fiber designs, and hybrid power-data cables are gaining traction as utilities and data-center operators seek higher current-carrying headroom and embedded monitoring capabilities. Meanwhile, copper-price volatility and skilled-labor shortages are prompting manufacturers to embed dynamic-pricing clauses and invest in automation to protect margins and sustain delivery schedules.
Key Report Takeaways
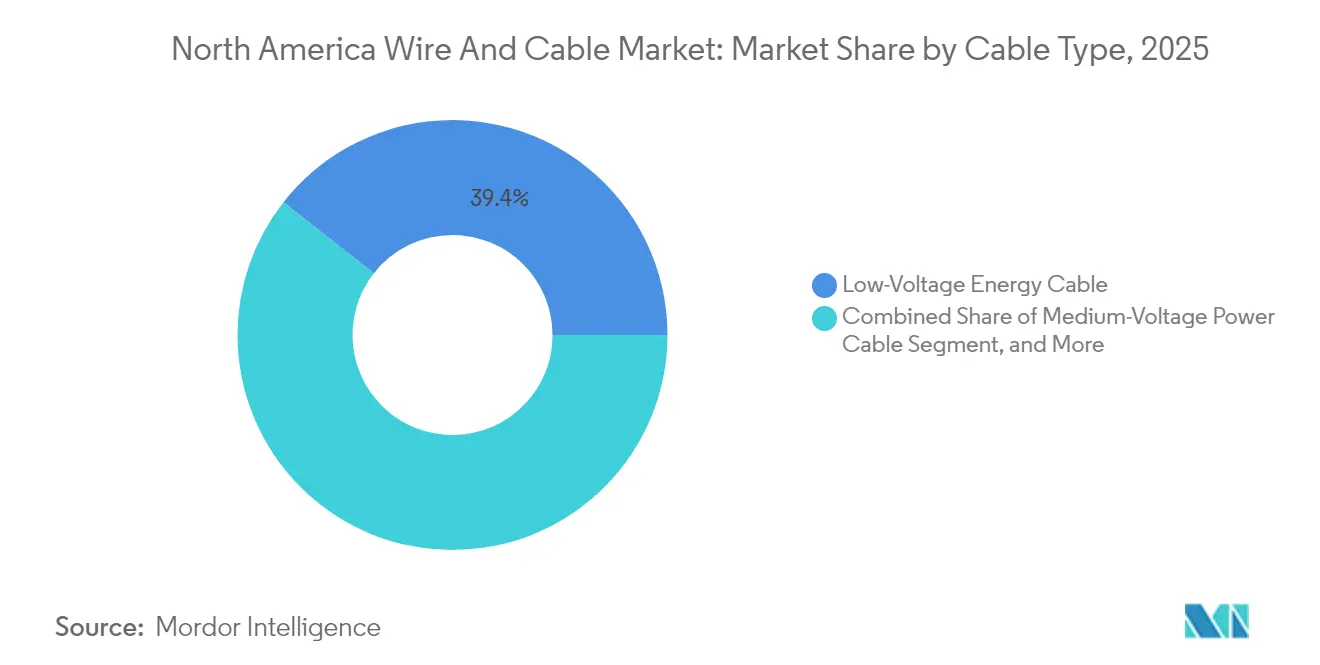
- By cable type, low-voltage energy cables led with 39.40% revenue share of the North America wire and cable market in 2025, while fiber-optic variants are projected to post the fastest 6.12% CAGR to 2031.
- By voltage rating, the < 1 kV class accounted for a 42.30% share of the North America wire and cable market in 2025; the 36-69 kV bracket is expected to register the highest 6.03% CAGR through 2031.
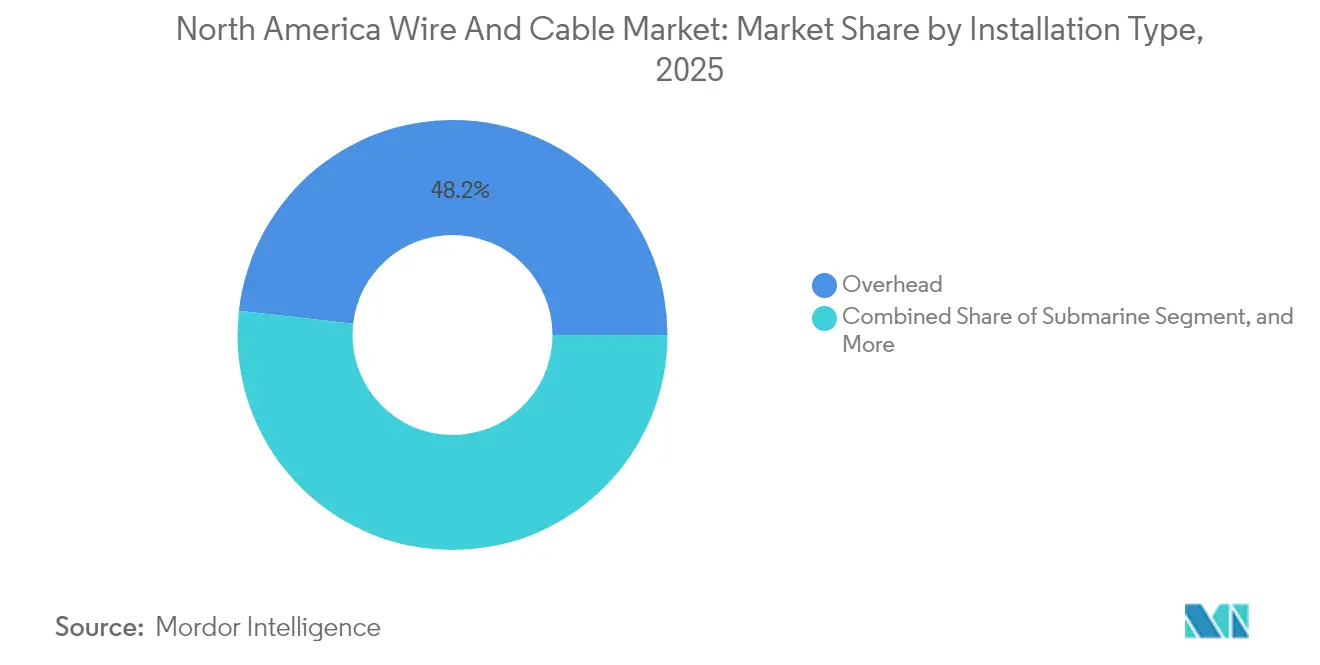
- By installation type, overhead lines dominated at 48.20% share of the North America wire and cable market in 2025, whereas submarine projects are forecast to expand at a 5.86% CAGR over the same period.
- By conductor material, copper maintained a 52.70% share of the North America wire and cable market in 2025, while composite/high-strength core designs are on track for a 5.57% CAGR to 2031.
- By end-user industry, construction contributed a 30.30% share of the North America wire and cable market in 2025; telecommunications and data centers are anticipated to achieve a 5.99% CAGR to 2031.
- By country, the United States commanded 82.10% revenue of the North America wire and cable market in 2025, and Mexico is set to grow the quickest at a 5.68% CAGR through 2031.
- Prysmian, Southwire, and CommScope collectively held about 46% of 2024 shipments, underscoring moderate market concentration.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Worldwide, activity is shaped by contributions from multiple regions, with North america representing one of the more structurally developed among them. The global report on wire and cable market by 黑料不打烊 reflects how these regional layers combine into a single system.
Market Trends and Insights
Drivers Impact Analysis of North America Wire and Cable Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising investments in infrastructure modernisation | +1.2% | United States, Canada | Medium term (2-4 years) |
| Accelerated smart-grid and grid-hardening roll-outs | +0.9% | North America | Long term (≥ 4 years) |
| Utility-scale renewable energy cabling demand surge | +0.8% | United States, Mexico | Medium term (2-4 years) |
| Edge-data-centre and hyperscale fibre build-out wave | +0.7% | United States, Canada | Short term (≤ 2 years) |
| "Buy-America" sourcing clauses in Bipartisan Infrastructure Law | +0.5% | United States | Medium term (2-4 years) |
| HVDC underground links for offshore-wind clusters | +0.3% | United States, Canada | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Infrastructure-modernization spending
A dedicated USD 65 billion federal allocation for grid upgrades is accelerating the replacement of aging conductors with advanced aluminum-composite and high-temperature designs, while USD 2.5 billion in resilience grants has shifted utility preferences toward underground routes and fire-resistant insulation.[2]U.S. Department of Energy, “Energy and Project Procurement Development Services,” ENERGY.GOV Domestic-content clauses guarantee local manufacturers sustained order visibility, enabling plants to run at higher asset-utilization rates. Municipal utilities and rural co-operatives are also tapping performance-contracting frameworks that bundle design, build, and maintenance services, compressing project lead times to within two-year budget cycles.
Smart-grid and grid-hardening roll-outs
Utilities piloting fiber-optic temperature-sensing strands across distribution lines obtain real-time ampacity data, deferring costly reconductoring and reducing wildfire risk; Minnesota’s deployment illustrates the proof of concept. Parallel grid-hardening budgets, such as PG&E’s USD 6 billion annual outlay, are steering demand toward insulated tree-wire and covered conductor systems able to withstand extreme weather. Regulatory cybersecurity mandates further elevate specifications for hybrid power-fiber cables that support secure data channels alongside energy transfer.
Utility-scale renewable cabling demand
Offshore wind developments now specify 525 kV HVDC export links with ≥ 2 GW capacity, pushing submarine-cable suppliers to expand steel-armored production lines. Solar and battery-storage farms are standardizing on 1,500 V DC-rated connectors, a shift that multiplies copper and aluminum consumption per megawatt. Long-term supply agreements between independent power producers and cable makers lock in volumes across multi-phase buildouts, smoothing revenue curves for both parties.
Edge-data-center and hyperscale fiber wave
AI training clusters require 800 G to 1.6 T optics, raising fiber counts to 864 strands within ≤ 10 mm diameters; rollable-ribbon formats from OFS satisfy these density targets. At the edge, micro-duct deployments in metro rights-of-way favor ruggedized designs that withstand repeated thermal cycling. Liquid-cooled server halls are piloting hybrid tubes carrying both coolant and fiber, an emerging niche for integrated power-over-fiber assemblies certified up to 430 V DC.[3]Panduit Corp., “Fault Managed Power over Optical Network Channels,” PANDUIT.COM
Restraints Impact Analysis of North America Wire and Cable Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High installation costs for underground and submarine cables | -0.8% | North America | Medium term (2-4 years) |
| Copper and aluminium price volatility | -0.6% | North America | Short term (≤ 2 years) |
| Skilled-labour bottlenecks for fibre/HV installations | -0.5% | United States, Canada | Long term (≥ 4 years) |
| Lengthy permitting and ROW approvals for new corridors | -0.4% | United States | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High underground and submarine installation cost
Underground distribution work can cost 4.5 times more than overhead construction, while submarine installation windows hinge on vessel availability and seasonal weather. Limited specialty-contractor fleets inflate day-rates and prolong project timelines, forcing utilities to balance resilience benefits against capital budgets. Cost-optimization now centers on route-engineering software and joint-trench programs that consolidate electrical, telecom, and gas conduits within a single excavation to dilute per-foot expenses.
Copper and aluminum price volatility
Spot prices swung between USD 8,200–11,500 per t for copper and hovered near USD 2,400 per t for aluminum in 2024, pressuring manufacturers to hedge and adopt pass-through pricing. Utilities increasingly accept indexed clauses pegged to COMEX averages, though that practice complicates multi-year capital planning. Composite-core and aluminum-clad designs offer partial mitigation, yet performance trade-offs restrict substitution in high-load centers. Vertical-integration moves, such as cable-makers acquiring rod mills, aim to curb raw-material exposure.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Wire and Cable Market Segment Analysis
By Cable Type:
Fiber Optics Accelerate Digital LinksLow-voltage energy conductors sustained 39.40% revenue in 2025 on the back of resilient residential and commercial construction. Conversely, fiber-optic variants are registering a 6.12% CAGR to 2031, propelled by telco 5G roll-outs and cloud-provider AI clusters. The North America wire and cable market size for fiber segments is projected to add USD 3.28 billion by 2031. Signal-and-control lines also benefit from factory-automation retrofits that embed sensors across production lines.
Composite fiber designs with rollable ribbons enable 2,000-strand vaults in compact footprints, trimming duct-leasing costs for carriers. Low-smoke zero-halogen jackets are gaining code acceptance in data centers, while bend-insensitive single-mode cores improve slack management in tight trays. In power, medium-voltage shielded cables remain the workhorse for distribution upgrades, whereas high-voltage XLPE and HVDC extruded systems service 300 km offshore wind export runs. As utilities converge data and energy networks, hybrid power-fiber cables reinforce synergies within the North America wire and cable market.


By Voltage Rating:
Mid-Range Leads Grid ModernizationThe sub-1 kV bracket accounted for 42.30% shipments in 2025, anchored in residential feeders and building wiring. Yet, the 36–69 kV span exhibits the fastest 6.03% CAGR, mirroring feeder-backbone enhancements and renewable interconnections. This tier often delivers the best cost-capacity trade-off for suburban substations, explaining its outsized traction in planned capital budgets.
Utilities are specifying advanced aluminum-composite and high-temperature low-sag variants within 69–220 kV upgrades to double ampacity without wider rights-of-way. Such specifications lift conductor-per-mile revenues, reinforcing the North America wire and cable market’s profitability. IEEE C57 revisions covering higher continuous-operating temperatures further legitimize adoption. Simultaneously, code cycles in commercial real estate push smart-building LV cabling to support PoE lighting and occupancy analytics, expanding the low-voltage revenue base.
By Installation Type:
Submarine Lines Ride Offshore Wind WaveOverhead networks still dominate at 48.20% in 2025 due to lower CAPEX and rapid build rates. However, submarine segments are projected for a 5.86% CAGR as coastal states approve 30 GW of offshore wind through 2031. Each 2 GW cluster can consume ≥ 1,000 km of 525 kV HVDC export cable, translating into multi-billion-dollar procurement lots.
Underground urban feeders gain relevance where wildfire mitigation or aesthetic mandates override initial cost premiums. Utilities are coupling underground builds with fiber backbones to justify the spend through telecom lease income. Aerial micro-duct systems around metropolitan poles enable carriers to deploy fiber quickly without trenching, a niche but expanding slice within the North America wire and cable market.
By Conductor Material:
Composite Cores Gain MomentumCopper retained 52.70% revenue in 2025 owing to unrivaled conductivity and entrenched standards. Composite-core conductors are forecast for a 5.57% CAGR as transmission owners validate 2× ampacity and lower thermal sag. Aluminum remains favored in sub-transmission spans where tower loading and budget constraints outweigh marginal losses.
Composite adoption is accelerating after successful pilots showed compatibility with existing hardware, easing retrofit risk. Manufacturers are publicizing total-lifecycle economics that combine reduced tower counts and deferred corridor acquisition, strengthening the North America wire and cable market’s value proposition. Meanwhile, copper-clad aluminum finds uptake in branch circuits and EV-charging whips, balancing cost with higher-frequency performance.
By End-User Industry:
Telecom Outpaces Traditional SegmentsConstruction led with a 30.30% share in 2025, but telecommunications and data centers delivered the highest 5.99% CAGR through 2031, fueled by hyperscale expansion and FTTP drives. Power-utility demand remains steady, anchored in regulated rate-base investment. Industrial automation upgrades in discrete manufacturing plants unlock fresh volumes for shielded control lines.
EV-platform assembly lines require high-temperature magnet wire and silicone-jacketed flex cables, bolstering specialty wire revenues. Globally, data-communication links represent 38.76% of 2025 revenue, spanning enterprise Ethernet, USB, and FTTH drop lines that anchor the bulk of the cable assembly market. Renewable facilities integrate 1,500 V DC arrays and battery BESS tie-ins, demanding thicker insulation and temperature-cycling resilience. The wide application mix cushions cyclic slowdowns in any one vertical, supporting resilient growth across the North America wire and cable market.
Geography Analysis
United States Wire and Cable Market
The United States held 82.10% revenue in 2025 on the strength of federal infrastructure outlays and advanced manufacturing bases. Intensive U.S. federal funding paired with Buy America clauses funnels predictable volume into domestic plants, encouraging multinationals to expand Gulf Coast copper-rod casting and Southeast optical-fiber extrusion lines. Data-center developers in Virginia, Ohio, and Texas continue to rank among the world’s largest single-site fiber consumers, often pre-purchasing cable reels 12 months ahead to lock in allocations. Utilities in wildfire-prone California, Oregon, and Washington are pivoting to covered conductors and underground circuits to cut outage risk, a trend that increases copper weight per circuit and reinforces revenue in the North America wire and cable market.
Mexico Wire and Cable Market
Mexico tracks a 5.68% CAGR through 2031 as Comisión Federal de Electricidad accelerates its USD 4.2 billion grid-expansion blueprint that includes 145 transmission and 86 distribution projects. In Mexico, CFE’s expansion program allocates USD 3.6 billion to distribution-level improvements through 2030, driving medium-voltage demand. Offshore Gulf wind prospects and the Santa Catarina solar complex require bespoke HVDC export designs, introducing submarine suppliers to new Latin bids. Government incentives for semiconductor and EV assembly clusters are spurring greenfield industrial park construction, boosting low-voltage building-wire pull-through.
Canada Wire and Cable Market
Canada’s major utilities are reinforcing hydro-powered export corridors to the United States, necessitating high-ampacity composite lines over long northern spans. Remote mining operations in the Yukon and Nunavut employ armored aluminum cables resistant to low-temperature embrittlement. Provincial broadband schemes targeting 50/10 Mbps universal service accelerate rural fiber builds, enlarging the addressable base within the North America wire and cable market.
黑料不打烊 provides coverage of the wire and cable market across other key regional markets, including Europe and South America, each with their regulatory frameworks and demand patterns. Detailed country-level analysis extends to India and Mexico incorporating local coverage and market participation, as required.
Regulatory Landscape
In the United States, wireline and utility cable deployment is shaped by federal siting and access rules as much as by product standards. In June 2026, the FCC advanced a draft Notice of Proposed Rulemaking under its Build America initiative to set national standards for wireline access to public rights-of-way, including a proposed 120-day processing timeframe for state and local access applications, a change aimed at reducing permitting friction for fiber and other wireline builds. The FCC also put in place accelerated pole attachment processes via rules effective September 25, 2025, establishing mandatory timelines for large pole attachment requests and contractor approval, which affects aerial fiber and last-mile construction schedules.
For transmission-scale buildouts, the Federal Energy Regulatory Commission (FERC) has been active on interconnection process reforms, including June 2026 actions focused on large-load interconnection tariffs at regional grid operators, which can influence the timing and specification of grid upgrades that use medium- and high-voltage cables. At the same time, federal transmission siting backstops have been constrained, with FERC backstop siting authority not in effect as of April 2026 due to the absence of Department of Energy (DOE) designated National Interest Electric Transmission Corridors (NIETCs). On the procurement and specification side, federal projects commonly reference Unified Facilities Guide Specifications (UFGS), such as UFGS 33 82 00 for telecommunications outside plant and UFGS 27 13 23.00 40 for optical backbone cabling, while rural broadband and telecom builds also align with Rural Utilities Service requirements under 7 CFR Part 1755.
Value Chain Analysis
The North America wire and cable value chain starts upstream with metals and polymer inputs (copper and aluminum rod, specialty alloys, insulation and jacketing compounds), followed by wire drawing, stranding, extrusion, armoring, and final cable assembly and testing at manufacturers such as Prysmian, Southwire, CommScope, and Nexans. Midstream distribution is typically handled by electrical and telecom channel partners and project-based procurement for utilities, EPCs, and data-center contractors, with logistics and inventory planning tied closely to reel sizes, lead times, and site delivery constraints. Downstream, installation and integration are executed by utility line contractors, telecom construction firms, and specialized underground and submarine installers, followed by commissioning, inspection, and ongoing maintenance.
Compliance with standards and reference specifications affects both product design and qualification timelines across the chain. Cable designs commonly align with industry standards bodies such as ANSI/ICEA for power and control cables and TIA (for example, TIA-492 series) for fiber performance requirements, while government and defense buyers frequently tie procurement to UFGS templates such as UFGS 33 82 00 (Outside Plant) and UFGS 27 13 23.00 40 (Optical Backbone Cabling). On the deployment side, rights-of-way access and pole attachment administration are key enabling steps for wireline projects, and recent FCC actions around pole attachment timelines (effective September 25, 2025) and proposed rights-of-way standards (June 2026 draft NPRM) link permitting and make-ready processes to when cable demand converts into installed activity.
Competitive Landscape
The market reflects moderate concentration: the five largest players contributed about 60% of 2024 shipments as measured by revenue. Prysmian’s USD 950 million buyout of Channell Commercial Corporation signals a pivot toward integrated connectivity kits spanning conduits, cabinets, and high-density cable assemblies. Southwire is automating rod-mill lines to dampen copper-price shocks and claims a 15% unit-cost drop on new AI-aided packaging cells. CommScope is leveraging fiber-jacketing know-how to supply hybrid power-fiber structures for edge micro-data halls.
Material security is driving vertical integration; several incumbents have secured off-take agreements with North American copper-smelter restarts, linking cathode supply to in-house wire-drawing capacity. Technology roadmaps prioritize conductor ampacity and embedded analytics: Far East Cable’s chip-embedded products transmit conductor-core temperature data every five seconds, aiding predictive maintenance. New entrants centered on composite cores face qualification hurdles but can win niche projects through single-circuit uprating proposals.
Strategic partnerships are forming between cable vendors and EPC firms to submit turnkey bids that bundle design, supply, and installation. Patent filings around fault-managed power over optical networks reached record levels in 2025, confirming a convergence pathway between energy and data plumbing. Given the capital intensity of extrusion and stranding assets, incumbents continue to enjoy scale economics, yet differentiated digital add-ons may unlock premium margins and shift share in the North America wire and cable market.
North America Wire and Cable Industry Leaders
-
Prysmian Group USA, Inc.
-
Nexans AmerCable Incorporated
-
Southwire Company, LLC
-
CommScope Holding Company, Inc.
-
Belden Inc.
- *Disclaimer: Major Players sorted in no particular order
North America Wire and Cable Market Companies Covered in this Report
- Prysmian Group USA, Inc.
- Nexans AmerCable Incorporated
- Southwire Company, LLC
- CommScope Holding Company, Inc.
- Belden Inc.
- Corning Incorporated
- TE Connectivity Corporation
- Amphenol Corporation
- LS Cable and System U.S.A., Inc.
- Furukawa Electric Co., Ltd. (OFS Fitel, LLC)
- Leoni Cable Inc.
- Sumitomo Electric Wiring Systems, Inc.
- Encore Wire Corporation
- American Wire Group, LLC
- TPC Wire and Cable Corp.
- General Cable Technologies Corporation
- Superior Essex Inc.
- AFL Telecommunications LLC
- NKT North America Inc.
- KEI Industries North America, Inc.
- Hengtong Cable Americas Inc.
- Tratos USA Inc.

Market Opportunities and Future Outlook
Opportunities are emerging where domestic capacity build-out meets faster wireline deployment processes and large-load grid work. In April 2026, Prysmian highlighted a USD 500 million investment tied to expanding Encore Wire operations, including a 1 million square foot expanded copper building wire plant and service center in McKinney, Texas. This signals that suppliers are adding localized capacity to serve electrification demand, data centers, and grid modernization programs. In parallel, Nexans strengthened its US low-voltage platform through the Republic Wire transaction, announcing a definitive agreement in April 2026 and completing the acquisition in June 2026, a consolidation that broadens manufacturing footprint and product availability for residential, commercial, and data-center oriented wire demand.
On the demand enablement side, policy and process changes create room for vendors to shorten build cycles and reduce total installed cost. The FCCs June 2026 draft NPRM proposing national standards for wireline access to public rights-of-way, including a 120-day processing timeframe, targets permitting drag that can delay fiber and related construction. Separately, FCC pole attachment rules effective September 25, 2025 tighten timelines for large attachment requests and contractor approvals, supporting higher utilization for aerial micro-duct and outside-plant cable systems. For power infrastructure, FERCs June 2026 actions around tailored large-load interconnection tariffs at regional operators highlight the near-term work required to connect data-center scale loads, reinforcing opportunities for medium- and high-voltage cabling, substation wiring, and hybrid power-data solutions as interconnection backlogs push grid upgrades and procedural changes.
Recent Industry Developments in North America Wire and Cable Market
- June 2026: Nexans completed the acquisition of 100% of the share capital of Republic Wire, Inc., integrating it into the Nexans PWR-Connect business segment. The consolidation in the North America wire and cable market strengthens Nexans' US low-voltage wire platform and regional manufacturing footprint. The move expands Nexans' access to Republic Wire's customer base and accelerates its capacity to meet growing demand for data center and grid infrastructure projects.
- April 2026: Nexans signed a definitive agreement to acquire Republic Wire, Inc., to strengthen its U.S. presence. The expansion of its low-voltage wire portfolio in North America supports Nexans' platform-building strategy in the United States. This acquisition aligns with the company’s focus on scaling domestic capabilities to serve high-growth sectors such as data centers and utility modernization.
- April 2026: Prysmian Group USA, Encore Wire (via Prysmian press release) unveiled a 1 million square foot expanded Copper Building Wire Plant and Service Center in McKinney, Texas, to support data center growth and grid modernization. Domestic capacity expansion for copper building wire enhances Prysmian’s footprint for data-center and grid infrastructure demand in North America. The expanded facility positions Prysmian to service rising orders from utilities and hyperscale operators, improving delivery resilience and project readiness.


North America Wire and Cable Market Report Scope and Research Methodology
Market Definition and Coverage
For this methodology, the North America wire and cable market counts revenues from insulated wire and cable products used to transmit power and signals across residential, commercial, industrial, and utility applications in the region.
Scope exclusions: This sizing does not include installation labor, connectors, switchgear, or broader electrical distribution equipment that sits outside wire and cable product revenues.
Segments Covered in This Report
-
By Cable Type
- Low-Voltage Energy Cable
- Medium-Voltage Power Cable
- High / Extra-High-Voltage Cable
- Fiber-Optic Cable
- Signal and Control Cable
- Co-axial and Data Cable
- Specialty Wire (Magnet, Stranded, etc.)
-
By Voltage Rating
- < 1 kV
- 1 – 35 kV
- 36 – 69 kV
- 69 – 220 kV
-
By Installation Type
- Overhead
- Underground
- Submarine
- Indoor/Building
- Aerial Micro-duct
-
By Conductor Material
- Copper
- Aluminium
- Copper-Clad Aluminium
- Composite/High-Strength Core
-
By End-user Industry
- Construction (Residential and Commercial)
- Power Transmission and Distribution Utilities
- Telecommunications and Data Centres
- Industrial Manufacturing
- Automotive and Transportation (EV/Rail)
- Renewable Energy (Solar, Wind)
- Oil, Gas and Mining
- Military and Defence
- Other End-user Industries
-
By Country
- United States
- Canada
- Mexico
Data Sources, Market Sizing, and Validation
Desk Research
To build the initial market picture, we start with public sources that show where cable demand comes from and how it moves with construction and energy spending. Examples include U.S. Census Bureau construction spending series, the U.S. Energy Information Administration (generation, grid, and renewables buildout), and Statistics Canada construction and industrial indicators.
We also reference trade and standards bodies, such as NEMA and ASTM publications, plus customs and trade statistics (including U.S. International Trade Commission data) to understand import dependence, conductor mix, and pricing signals. Company filings, investor presentations, and major project announcements are used to map capacity expansions and end-market exposure. Where needed, we complement this with paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export data to pressure-test volumes and average selling price direction. These sources are not exhaustive, and additional public datasets and documents were used for cross-checks and clarification during the work.
Primary Interviews and Surveys
Primary work was used to validate the scope boundaries and to translate broad activity indicators into realistic cable demand, pricing, and mix assumptions. We spoke with participants across manufacturing, distribution, contracting, and large end users so gaps from desk research (like voltage mix, substitution between copper and aluminum, and lead time impacts) could be addressed and then reflected in the final model for the region.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 26% | CXOs: 15% |
| Mid tier: 59% | Functional/Unit leaders: 29% |
| Smaller Players: 15% | Managers: 56% |
Market-Sizing & Forecasting
The core sizing logic uses a top-down build where construction activity, grid and generation investments, industrial output, and telecom network deployment are translated into cable demand pools for North America, and then converted into value using realistic price and mix assumptions. To keep the totals grounded, we corroborate them with selective bottom-up checks, including manufacturer revenue exposure to wire and cable, channel feedback on shipment trends, and volume times average selling price approximations for a few high-visibility applications.
Key inputs that were used (illustrative) include building starts and construction spend, transmission and distribution capex, renewable interconnection activity, conductor material mix (copper versus aluminum), underground versus overhead installation share, and observed price movements tied to metal and polymer costs. When a variable was not consistently available at the same cut across countries, gaps were handled by using the closest public proxy and validating the direction and magnitude through interviews before applying it.
For forecasting, scenario analysis is used alongside a light multivariate regression, with demand drivers like construction spend, utility investment, and industrial activity acting as explanatory variables. Final growth paths are adjusted after expert feedback on supply constraints, project timing shifts, and how quickly pricing normalizes after commodity swings.
Data Validation & Update Cycle
Outputs are checked against independent signals, including trade flows, major project pipelines, and company revenue direction, so the final numbers do not rely on one dataset. Variance checks are run across countries and end uses, and any outliers are reworked by revisiting assumptions and recontacting sources when needed.
Before sign-off, the model and written logic go through multiple analyst reviews so input choices and calculations stay consistent. Reports are refreshed annually, and interim updates are done when material events occur (for example, a major policy change impacting grid spend or an abnormal raw material shock). Right before delivery, we do a final pass to ensure the latest public data and news are incorporated.
黑料不打烊's North America Wire and Cable Market Size Compared Against Other Published Estimates
Published market values for North America wire and cable can look inconsistent because groups often draw the line differently on what counts as revenue and which years are treated as the true base. The table below illustrates how scope choices, pricing treatment, and update timing can create noticeable spreads even when everyone is discussing the same region.
The table points to a key gap around what gets counted as product revenue versus adjacent services. Under 黑料不打烊's scope, the market is measured as wire and cable product revenues in North America with a 2025 base, and totals are cross-checked using end-use demand signals and trade-based sanity checks, rather than extending the value to installation labor or broader electrical equipment bundles.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 37.71 B (2025) | |
| Industry Publisher A | USD 27.37 B (2022) | Uses an earlier base year and can understate later-cycle grid and construction spend, and the pricing path may be held constant in a way that misses metal-driven ASP changes. |
| Market Tracker B | USD 34.31 B (2023) | May mix in a different product boundary (for example, broader electrical components) or apply simplified end-use splits, with fewer validation checks tied to trade and project activity. |
Taken together, the spread mostly comes from base-year selection, whether pricing is updated in line with commodity movement, and whether services or adjacent equipment are included. Our approach keeps the math traceable to visible demand drivers and repeatable adjustments, which makes it easier to reconcile the final number back to practical market activity.


Key Questions Answered in the Report
How large is the North America wire and cable market in 2026?
It reached USD 39.45 billion in 2026 and is projected to grow at a 4.62% CAGR to 2031.
Which cable type is growing fastest in North America?
Fiber-optic cables are advancing at a 6.12% CAGR due to AI-driven data-center and 5G builds.
Why are submarine cables gaining attention in North America?
Offshore-wind export links require 525 kV HVDC submarine systems, driving a 5.86% CAGR for this installation class.
What drives Mexico’s cable demand?
CFE’s USD 4.2 billion grid-modernization program and near-shoring industrial projects boost medium- and high-voltage needs.
Which materials are utilities adopting for capacity upgrades?
Composite-core conductors that double ampacity without new towers are gaining momentum across 69-220 kV lines.
Page last updated on:


 Your data is secure and never sold or shared.


