
Australia Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.81 Billion |
| Market Size (2026) | USD 0.85 Billion |
| Market Size (2031) | USD 1.09 Billion |
| Growth Rate (2026 - 2031) | 5.03 % |
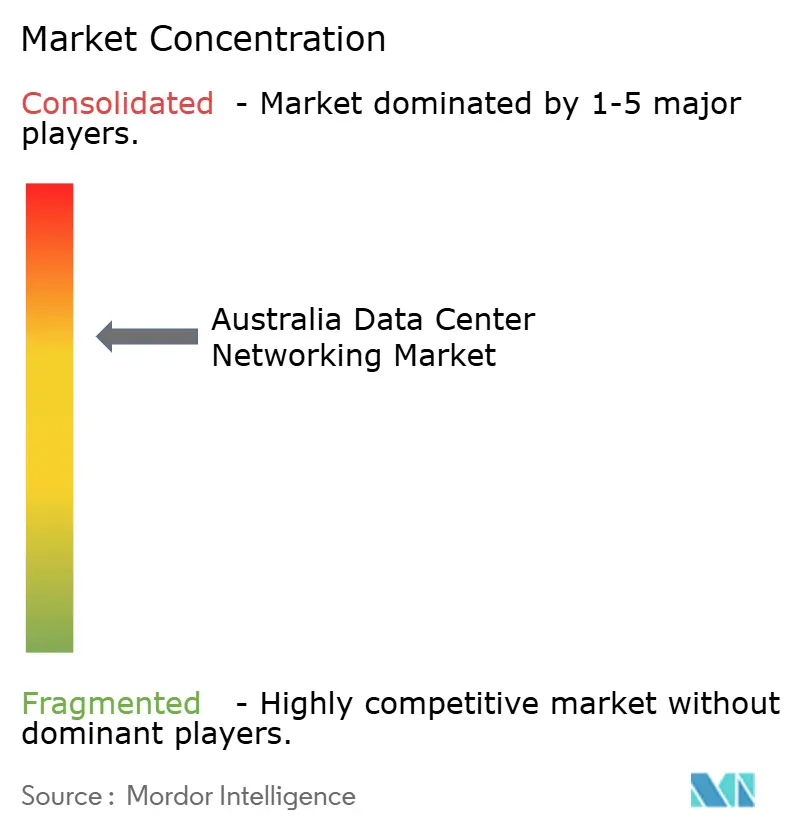
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Australia Data Center Networking Market Analysis by 黑料不打烊
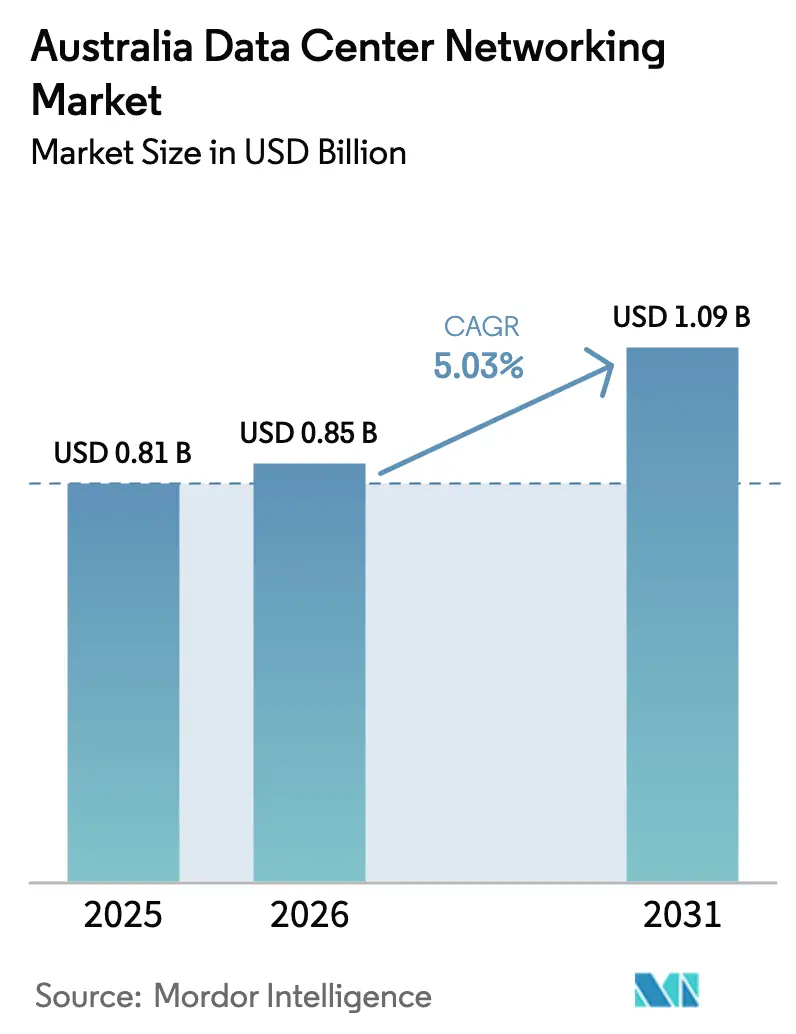
The Australia data center networking market size was valued at USD 0.81 billion in 2025 and estimated to grow from USD 0.85 billion in 2026 to reach USD 1.09 billion by 2031, at a CAGR of 5.03% during the forecast period (2026-2031). Growth now centers on supporting artificial-intelligence training clusters, sovereign-cloud mandates, and ultra-low-latency connectivity for mission-critical workloads rather than on first-wave cloud migration. Government programs such as the USD 2 billion contract for an AWS top-secret cloud underline how national-security objectives steer procurement toward high-bandwidth, heavily segmented fabrics. Hyperscaler build-outs by NEXTDC, Equinix, and Stack Infrastructure, combined with projected household device proliferation, accelerate investment in 400 GbE and 800 GbE switching to pre-empt future east-west traffic surges. Financial-services AI workloads already process hundreds of billions of data points daily, signalling a long-term shift toward non-blocking, leaf-spine architectures.
Key Report Takeaways
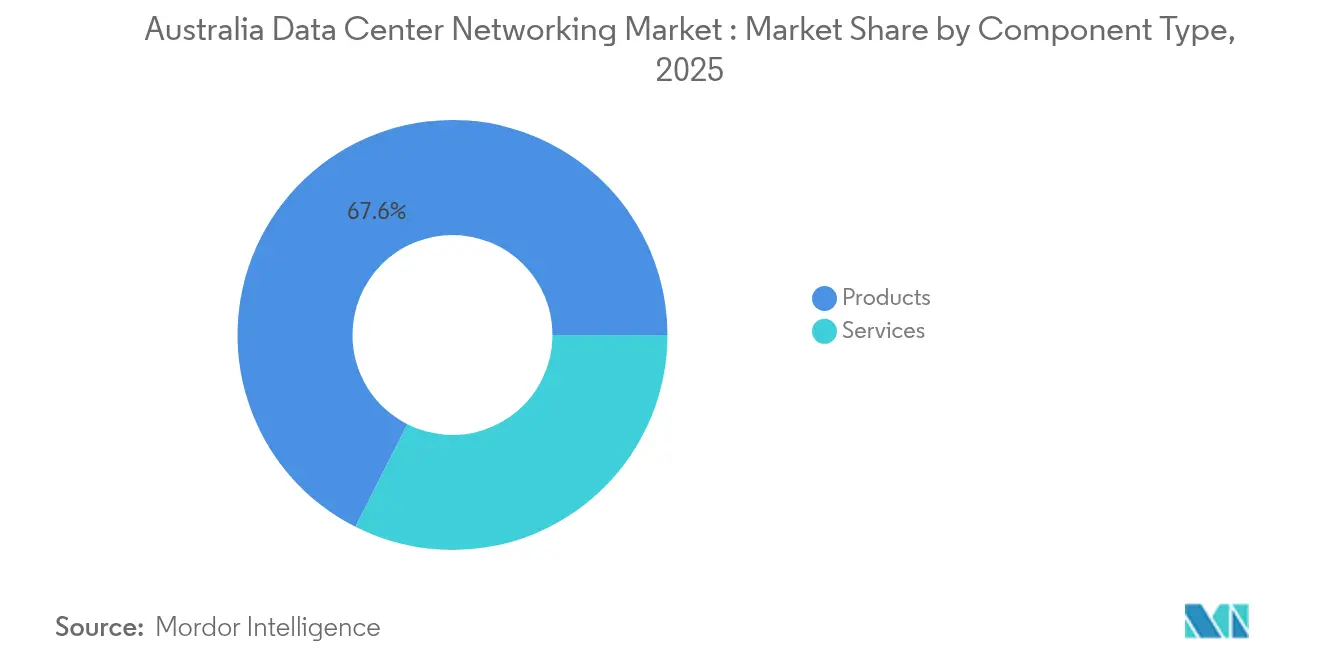
- By component, Products held 67.55% of the Australia data center networking market share in 2025, while Services are projected to rise at a 7.72% CAGR through 2031.
- By end-user, IT & Telecommunications led with 36.12% revenue share in 2025; Healthcare & Life Sciences is forecast to expand at a 6.18% CAGR to 2031.
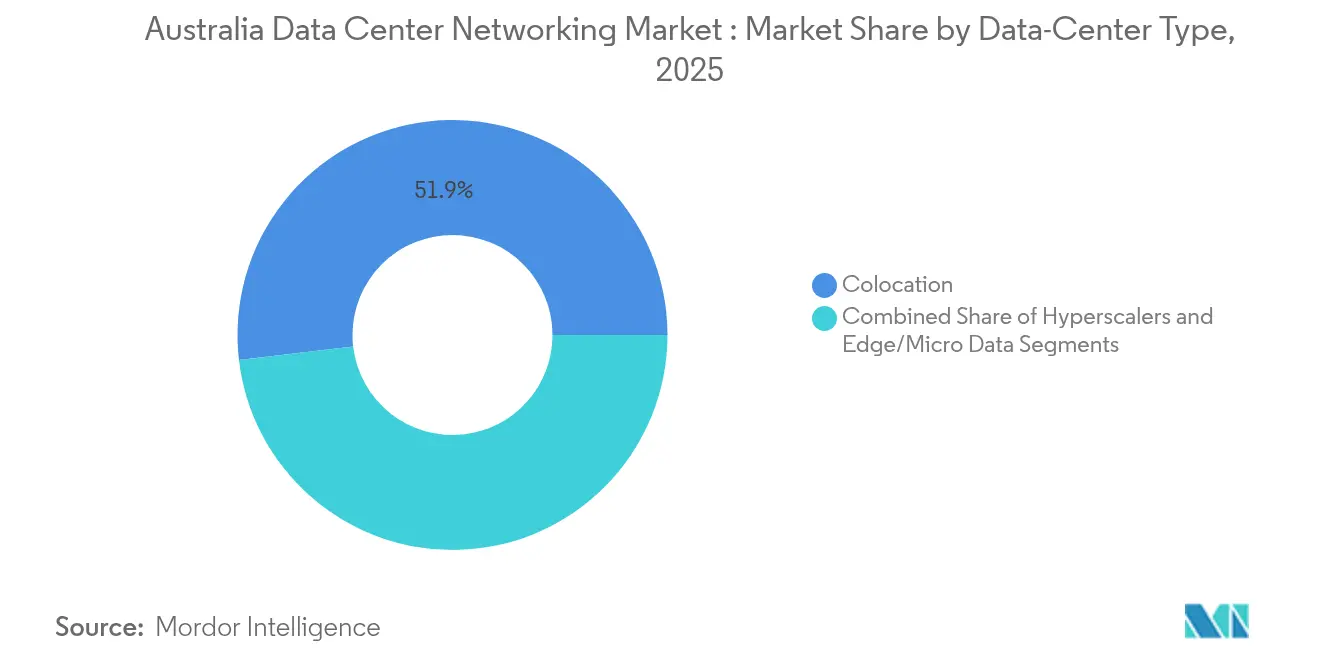
- By data-center type, Colocation facilities accounted for 51.85% of the Australia data center networking market size in 2025, whereas the Hyperscaler/Cloud Service Provider segment is poised for a 8.92% CAGR up to 2031.
- By bandwidth, the 50-100 GbE category retained 35.92% share of the Australia data center networking market size in 2025, while the greater than 100 GbE segment is projected to grow at 9.21% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Australia Data Center Networking Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid rollout of hyperscale and cloud facilities | +1.2% | Australia-wide, concentrated in Sydney, Melbourne | Medium term (2-4 years) |
| Surge in AI/ML-driven East-West traffic inside Australian data centres | +0.9% | Major metros with hyperscale presence | Short term (≤ 2 years) |
| Migration from 10/25 GbE to 100/400 GbE switching fabrics | +0.7% | Tier-1 cities, expanding to regional centers | Medium term (2-4 years) |
| Government incentives for sovereign data-residency and digital-economy targets | +0.6% | National, with concentration in Canberra, Sydney | Long term (≥ 4 years) |
| Growing adoption of software-defined, open networking (SONiC/Net-Ops) | +0.4% | Enterprise and hyperscale deployments nationwide | Medium term (2-4 years) |
| Edge-colocation build-outs around Tier-2 Australian cities | +0.3% | Perth, Adelaide, Brisbane, Darwin | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Rapid rollout of hyperscale and cloud facilities
Operators are shifting from capacity-led builds to capability-driven designs that prioritise interconnection density. NEXTDC’s 550 MW Sydney land bank and Equinix’s AUD 240 million twin-city expansion highlight a push toward leaf-spine topologies optimised for 400 GbE fabric. Stack Infrastructure’s AUD 1.3 billion fund-raising signals global capital’s confidence that Australia data center networking market growth will pivot on these hyperscale builds.
Surge in AI/ML-driven east-west traffic
Cisco’s Nexus HyperFabric AI platforms are arriving in Sydney labs to handle RDMA over Converged Ethernet traffic, where microsecond latency swings stall model training.[1]Cisco, “Nexus HyperFabric AI Solution Brief,” cisco.com Financial giants such as Commonwealth Bank run 2,000 models over 157 billion data points, pushing sustained east-west loads that demand non-blocking 400 GbE switching. Facilities certified under NVIDIA’s DGX-Ready program, including NEXTDC’s, show how purpose-built cold-aisle containment and low-jitter fabrics become competitive differentiators.
Migration from 10/25 GbE to 100/400 GbE fabrics
Wholesale carrier Devoli and Juniper Networks built Australia’s first end-to-end 400 G backbone, a ten-fold capacity uplift positioning the firm for 800 GbE scalability[2]Juniper Networks, “Devoli Launches 400 G Backbone,” juniper.net. Dell Technologies’ Enterprise SONiC Distribution lets operators uncouple network operating systems from merchant-silicon hardware, avoiding refresh traps as Australia data center networking market transitions to 400 GbE.
Government incentives for sovereign data-residency
The Defence Department’s move from Global Switch to locally-owned Canberra Data Centres underscores how policy anchors load in Australian-controlled real estate, demanding micro-segmented 100 GbE fabrics capable of inline inspection. The Digital Transformation Agency’s hosting strategy obliges agencies to split workloads across hybrid clouds while enforcing zero-trust networking.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capex for 400 GbE/800 GbE optics in a small-volume market | -0.8% | Australia-wide, particularly affecting smaller operators | Short term (≤ 2 years) |
| Limited pool of specialised data-centre network engineers | -0.6% | National, acute in regional areas | Medium term (2-4 years) |
| Energy-price volatility impacting TCO models | -0.4% | National, varying by state energy policies | Medium term (2-4 years) |
| Slow standardisation of single-pair Ethernet for DCIM links | -0.2% | Primarily affecting new facility deployments | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High capex for 400 GbE/800 GbE optics
A smaller national procurement base keeps per-port prices high because Australian buyers cannot unlock the scale discounts enjoyed in North America or China. Supply-chain lags still affect 80% of global switch makers, with tariffs adding further price pressure for the Australia data center networking market
Limited pool of specialised network engineers
Infrastructure Australia projects a 93,000-person shortfall across technical trades by 2028, directly constraining deployment velocity for software-defined fabrics. Scarcity is more acute in Tier-2 cities, delaying regional edge-colocation schedules even when capital is available.[3]Infrastructure Australia, “Infrastructure Workforce Forecast 2025-2030,” infrastructureaustralia.gov.au
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Services Accelerate Despite Product Dominance
Products accounted for 67.55% of the Australia data center networking market share in 2025, anchored by high-density leaf-spine switches, routers, and optical interconnects demanded by hyperscale halls. The installed hardware base is expanding as national capacity grows from 1,350 MW in 2024 to 3,100 MW by 2030, underpinning predictable refresh cycles. Services, however, post the fastest 7.72% CAGR to 2031. Tight labour supply and the sophistication of open-networking stacks make integration and lifecycle management a recurring spend priority.
Managed network services providers are bridging Australia data center networking industry skills gaps by offering 24×7 telemetry, intent-based configuration, and automated compliance reporting. Demand for design consulting and training likewise accelerates as organisations grapple with SONiC roll-outs and GPU cluster cabling that deviate from legacy topologies. Thus, expenditure shifts from one-off capital equipment to continual operating outlays attached to multi-year service agreements.


By End-User: Healthcare Velocity Contrasts IT Dominance
IT & Telecommunications retained 36.12% of segment revenue in 2025, driven by operators running both wholesale infrastructure and consumer connectivity products. Telcos leverage their national fibre backbones to market low-latency cross-connect fabrics within carrier-neutral sites, reinforcing their role as anchor tenants for wholesale networking gear.
Healthcare & Life Sciences registers a 6.18% CAGR, the fastest among verticals, as genomic testing and digital pathology create sustained 100 GbE east-west loads. QIAGEN’s Melbourne build for clinical next-generation sequencing mirrors rising sovereign-data expectations in the sector. Financial services retain steady outlays, evidenced by the Commonwealth Bank example above, while government workloads gain momentum under cyber-security mandates that elevate segmentation and encryption needs.
By Data-Center Type: Hyperscaler Momentum Challenges Colocation Leadership
Colocation captured 51.85% of the Australia data center networking market size in 2025, benefiting from network-effect economics around interconnection hubs. Providers like NEXTDC and Equinix distribute the cost of 400 GbE fabrics across dozens of tenants, keeping port pricing competitive and allowing rapid turn-up of cross-connects.
Hyperscaler and cloud-service-provider builds post a 8.92% CAGR through 2031, the fastest of all facility types, propelled by AWS’s USD 2 billion top-secret cloud, Google’s Melbourne cloud region, and Microsoft’s Canberra Azure Government zone. Their designs embrace liquid-cooled GPUs connected via 800 GbE, setting new baselines for port-to-rack density that traditional colocation halls now emulate. Edge/micro-data-center roll-outs in mining towns like Newman broaden geographic dispersion but remain niche in revenue contribution.
By Bandwidth: Migration Patterns Signal Infrastructure Evolution
The 50-100 GbE tier retained 35.92% of 2025 revenue, making it the functional baseline across enterprise and many colocated racks. Operators extend asset life by upgrading optics within the same switch line-cards, delaying wholesale chassis swaps. Yet, the greater than 100 GbE segment is advancing at 9.21% CAGR, reflecting capex front-loading for AI clusters.
Devoli’s 400 G backbone illustrates how wholesale carriers prepare for 800 GbE interfaces by first standardising coherent-optic roadmaps. Meanwhile, ≤10 GbE and 25-40 GbE links shrink rapidly outside of out-of-band management networks and edge appliances. Users therefore plan hybrid fabrics where legacy SAN traffic coexists with 400 GbE east-west flows until full application refactoring completes.
Geography Analysis
Sydney retains primacy as the nation’s digital-traffic core, hosting multiple cable landing stations and the largest contiguous block of hyperscale hall capacity. Equinix extended its SY series sites with 4,175 AI-ready cabinets during 2025, ensuring direct cloud on-ramps and sub-millisecond metro access. Melbourne follows with a projected 45% interconnection bandwidth CAGR to 2026, driven by spill-over demand and state-level incentives for fintech and creative-media workloads.
Tier-2 cities demonstrate sharper percentage growth, albeit off smaller bases. NEXTDC inaugurated Adelaide’s first Tier IV facility in mid-2024 to serve aerospace and defence clients who need five-nines uptime. Perth gains strategic value through Zscaler’s point-of-presence inside Equinix, bolstering cybersecurity posture for mining and LNG operators. Darwin’s AUD 80 million expansion supports northern defence logistics and cross-border traffic into Southeast Asia.
Regional micro-centres arise along supply-chain corridors such as the Pilbara, where edge racks collect IoT telemetry before relaying to Perth 100 GbE aggregation points. However, capital recovery remains challenging because lower rack densities dilute economies of scale. As a result, most high-port-count spine switches still deploy in Sydney and Melbourne, reinforcing their market gravity.
Regulatory Landscape
Australian data center networking procurement is increasingly shaped by sovereign-data and critical-infrastructure obligations, alongside energy and planning expectations for new capacity. In March 2026, the Australian Government published Expectations of data centres and AI infrastructure developers, providing non-binding but actionable guidance for new or expanded developments, including underwriting new renewable power, meeting grid connection costs, and investing in local skills.
For operators and network vendors serving government, telco, and regulated industries, alignment with security and resilience frameworks is a key input into vendor selection and managed-services scope. The Security of Critical Infrastructure (Telecommunications Security and Risk Management Program) Rules 2025 reference recognized security controls, including AS/NZS ISO/IEC 27001:2023 and the Australian Signals Directorate Essential Eight maturity model, tightening requirements around segmentation, monitoring, and incident readiness. APRA CPS 230 also elevates operational resilience expectations for material service providers supporting APRA-regulated entities, reinforcing demand for auditable network change control, business continuity provisions, and contractual flow-downs across colocation and managed network service agreements.
Value Chain Analysis
The value chain covers global hardware and optics OEMs (switching, routing, ADC, and security appliances), merchant-silicon and optics suppliers, and Australian distributors and systems integrators that deliver design, installation, and lifecycle operations. Data center operators and cloud or colocation providers (including hyperscale halls and interconnection-centric facilities) anchor demand, while managed service providers monetize skills shortages through 24x7 monitoring, configuration automation, and compliance reporting around open networking stacks and AI fabrics.
Upstream and adjacent connectivity infrastructure is a key enabler for data center networking outcomes in Australia because it shapes metro and intercity latency, redundancy, and cross-connect density. In June 2026, Subco completed the SMAP submarine cable system linking Sydney, Melbourne, Adelaide, and Perth, adding intra-Australia capacity that supports traffic growth between major data center clusters. In July 2026, Telstra and Google announced a fiber partnership combining capacity leasing on subsea cables with dark-fiber access on Telstra's Aura Network, a national intercity backbone spanning about 14,000 km of new fiber. At the long-haul layer, Vocus is advancing ducted intercapital fiber builds, notably Sydney-Melbourne, designed for upgradeability without repeated civil works, supporting higher-capacity interconnect and backbone scaling as east-west traffic intensifies.
Competitive Landscape
Competition is moderately concentrated, with global switch incumbents deepening AI-centric portfolios while local integrators monetise services gaps. Arista Networks led global data-center switching revenue at USD 7 billion in 2024, up 19.5% year-over-year, and its EOS AI Agent co-engineering with NVIDIA resonates with hyperscalers seeking deterministic micro-burst handling.[4]Arista Networks, “Q1 2025 Results – Data Center Switching,” arista.com Cisco retains a broad account presence through Nexus, ACI, and silicon-one roadmaps but faces pricing pressure where open-networking alternatives gain acceptance.
Juniper Networks’ imminent USD 14 billion merger with HPE promises tighter integration between routing silicon and HPE GreenLake edge-to-cloud services, potentially altering preferred-vendor matrices for government frameworks. Dell Technologies leverages Enterprise SONiC to capture organisations prioritising vendor diversity. Rising service-provider entrants specialise in managed fabrics, using white-box hardware backed by local SLA guarantees to differentiate against multinational OEMs.
Technology alliances shape purchase decisions. Arista and Microsoft optimise 800 GbE line-cards for Azure Canberra, while Cisco teams with NVIDIA on in-switch telemetry for AI congestion avoidance. Meanwhile, domestic fibre operators bundle dark-fibre routes with leaf-spine hardware, offering turnkey latency-bounded links that appeal to high-frequency trading desks.
Australia Data Center Networking Industry Leaders
Cisco Systems Inc.
Arista Networks Inc.
Juniper Networks Inc.
Dell Technologies Inc.
Hewlett Packard Enterprise Company
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A clear whitespace sits in AI-ready, compliance-auditable fabric design and operations for customers with sovereign cloud and resilience requirements, including government and APRA-regulated industries. As procurement shifts toward segmented, inspected, and tightly monitored traffic flows, suppliers that package high-bandwidth leaf-spine architectures with policy-driven automation, telemetry, and documentation (including alignment to AS/NZS ISO/IEC 27001:2023 controls and Essential Eight practices referenced in the critical-infrastructure rules) have a more direct route to attach services revenue to hardware refresh cycles.
Network opportunities also extend to intercity and metro interconnection scaling as AI workloads lift sustained east-west and backbone traffic. Vocus publicized a AUD 500 million, multi-year Australian Digital Infrastructure Platform (ADIP) initiative focused on new ducted fiber, including a Sydney-Melbourne route engineered for future capacity upgrades, which creates room for higher-capacity data center interconnect, optical transport, and router or switch upgrades at landing points and carrier hotels. Additional whitespace is visible in sovereign AI infrastructure build-outs that require tighter compute and networking integration, illustrated by Cisco's launch of an in-country Secure AI Factory deployment hosted in a NEXTDC Sydney facility with NVIDIA and Sharon AI, which raises expectations for low-latency, congestion-managed AI networking across Australian colocation and enterprise environments.
Recent Industry Developments
- June 2026: Vocus announced a $500 million investment in the Australian Digital Infrastructure Platform ADIP, featuring a ducted fibre link between Sydney and Melbourne to support AI data centers. The project provides a high-capacity fibre backbone for AI data centers. Strengthens long-term scalability and resilience of Australian AI workloads infrastructure.
- June 2026: Arista Networks introduced the 7060XE7 Series, a portfolio of 1.6T networking platforms for rack-scale AI infrastructure. The launch delivers rack-scale AI networking capabilities. Enhances Australia’s capacity to support large-scale AI clusters with high bandwidth and density.
- February 2026: Cisco Systems launched the first Cisco Secure AI Factory in Australia, hosted at a NEXTDC data center in Sydney, with Sharon AI and NVIDIA. The onshore AI processing facility aligns with sovereign AI objectives. Supports local AI workloads and onshore data handling, influencing vendor selection in Australian data center networking.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Australia data center networking market is defined as revenue generated from networking products and related services used to connect servers, storage, and users inside a data center and across data centers within Australia.
The scope explicitly excludes general enterprise campus networking that is not deployed for data center use cases, and it also excludes telecom operator access networks outside the data center boundary.
Segmentation Overview
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less than or equals to 10 GbE
- 25–40 GbE
- 50–100 GbE
- Greater than 100 GbE
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts by mapping the Australia demand context and the technical boundary of what is counted as data center networking. We mainly use public sources such as the Australian Bureau of Statistics, the Australian Communications and Media Authority, the Department of Industry, Science and Resources, and energy and infrastructure publications that track build activity and capacity additions.
We then align the market model with supply and procurement signals using company annual reports and investor presentations, data center operator announcements, and reputable press coverage of new halls, expansions, and cloud region deployments. For trade and hardware flow checks, we also refer to import and export statistics and shipment-level trade data from a paid import and export shipment database, followed by cross-checks using a paid company financials and intelligence database and a paid patent database to understand networking technology direction. The desk sources listed here are illustrative, and other public documents and datasets were also used to collect, validate, and clarify inputs.
Primary Interviews and Surveys
Primary work is used to pressure test the scope and the price-volume logic behind networking refresh cycles in Australian data centers. We speak with a mix of data center operators, system integrators, distributors, and large end users. The discussions focus on purchasing triggers (capacity additions, bandwidth upgrades, and resiliency needs) and the typical configuration choices by facility type.
Coverage also includes views across the main demand clusters in Australia, so assumptions on adoption timing, average selling price movement, and services attach rates can be corrected before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 32% | CXOs: 13% |
| Mid tier: 46% | Functional/Unit leaders: 33% |
| Smaller Players: 22% | Managers: 54% |
Market-Sizing & Forecasting
Sizing is built using a mix of top-down and bottom-up checks so the totals remain realistic for Australia. In the top-down approach, data center capacity additions and expansion pipelines are used to reconstruct the likely networking demand pool by linking facility growth to expected switching, routing, security, and interconnect needs over the refresh cycle.
To keep the model grounded, we also run selective bottom-up approximations using sampled project bill of materials, channel checks on shipment momentum, and average selling price ranges for common port speeds and fabrics. We then adjust for coverage gaps where public reporting is limited. Inputs tracked closely include announced megawatt additions, uptake of higher port speeds (such as 100G to 400G migration), east-west traffic intensity linked to AI and cloud workloads, data center type mix (hyperscale, colocation, and enterprise), and the services share tied to design, deployment, and managed operations.
For forecasting, we rely on scenario analysis supported by expert consensus on the pace of new capacity delivery, technology transitions, and price erosion patterns. Where a bottom-up proxy cannot be directly observed, the gap is handled using conservative penetration and replacement assumptions that are reviewed during primary discussions and recalibrated if they conflict with project and trade signals.
Data Validation & Update Cycle
Validation happens in layers so single-source bias is reduced. Model outputs are compared against independent signals such as capacity delivery timing, import trends for relevant hardware categories, and the cadence of large facility announcements. Main variances are reviewed before sign-off.
If a number looks inconsistent with observed build activity or typical refresh behavior, the assumptions behind it are reopened. When needed, experts are re-contacted to confirm what changed in procurement or deployments. Reports are refreshed annually, with interim updates if a material event shifts demand, and a final pre-delivery review pass is completed so clients receive the latest updated view.
黑料不打烊's Australia Data Center Networking Market Size Versus Other Published Estimates
Published market numbers for Australia data center networking often do not align because the boundary can shift from pure data center gear to broader telecom or enterprise networking, and because services are treated differently across studies. Differences also show up when some sources report only switch silicon or only interconnect, which can leave out a large part of actual spend.
Capacity expansion announcements and shipment-direction checks, combined with interview-confirmed refresh cycles, are the evidence points that keep 黑料不打烊's estimate tied to what is actually deployed inside Australian data centers rather than adjacent network spending. Gaps across other figures typically come from mixing in carrier core infrastructure, using aggressive assumptions on 800G timing, applying global price curves without local channel adjustments, or converting currency using different average rates and update dates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 0.81 B (2025) | |
| Trade Journal A | USD 0.62 B (2025) | Often narrows scope to hardware shipped into major facilities and undercounts services and smaller site upgrades, which can reduce the total when refresh activity is spread across many operators. |
| Global Consultancy B | USD 1.15 B (2025) | Commonly folds in adjacent enterprise and carrier networking tied to cloud connectivity and may assume faster high-speed adoption, which can inflate spending versus a data center only definition. |
The spread in the table mainly reflects scope and the way price-volume inputs are applied to upgrades versus new builds. By keeping the model anchored to capacity-driven demand and then checking it against channel and interview signals, the final number stays explainable and practical for planning.


Key Questions Answered in the Report
How big is the Australia Data Center Networking Market?
The Australia Data Center Networking Market size is expected to reach USD 0.85 billion in 2026 and grow at a CAGR of 5.03% to reach USD 1.09 billion by 2031.
What is the current value of the Australia data center networking market?
The market is valued at USD 0.85 billion in 2026 and projects to USD 1.09 billion by 2031 at a 5.03% CAGR.
Which component segment is expanding fastest?
Services grow at an 7.72% CAGR as operators outsource integration, management, and training on AI-centric fabrics.
Why are 100 GbE links gaining traction in Australia?
AI training clusters and hyperscale spine-leaf architectures demand non-blocking 400 GbE and 800 GbE switching before traffic peaks.
Which end-user vertical shows the highest growth rate?
Healthcare & Life Sciences posts a 6.18% CAGR due to genomic analytics and data-sovereignty mandates.
How concentrated is vendor competition?
Five global OEMs together hold roughly 60% share, yielding a moderate concentration score of 6.
What restrains faster market expansion?
High per-port costs for 400 GbE optics and a shortage of specialised data-centre network engineers weigh on near-term growth.
Page last updated on:
- Vietnam Data Center Networking Market
- Indonesia Data Center Networking Market
- United Kingdom Data Center Networking Market
- APAC Data Center Networking Market
- South Korea Data Center Networking Market
- Japan Data Center Networking Market
- China Data Center Networking Market
- Spain Data Center Networking Market
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Australia Data Center Physical Security Market Australia's physical security, split by solution type and service type.
- Data Center Logical Security Market Network security across all regions, split by solution, service and end user.
- North America Data Center Rack Market North America racks, split by rack size and end user.



