
APAC Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 11.44 Billion |
| Market Size (2026) | USD 12.31 Billion |
| Market Size (2031) | USD 17.72 Billion |
| Growth Rate (2026 - 2031) | 7.57 % |
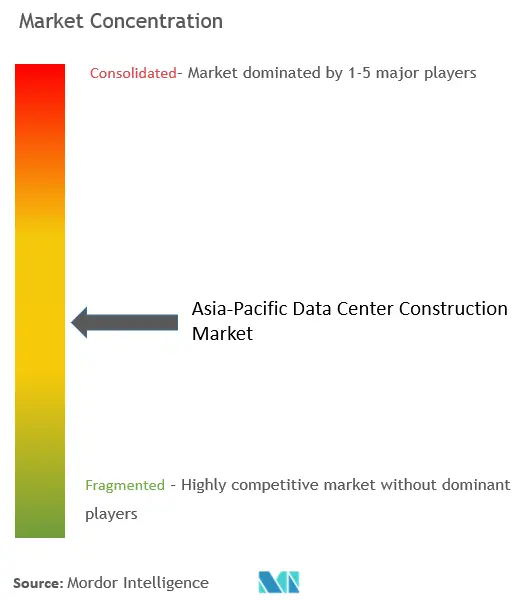
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
APAC Data Center Construction Market Analysis by 黑料不打烊
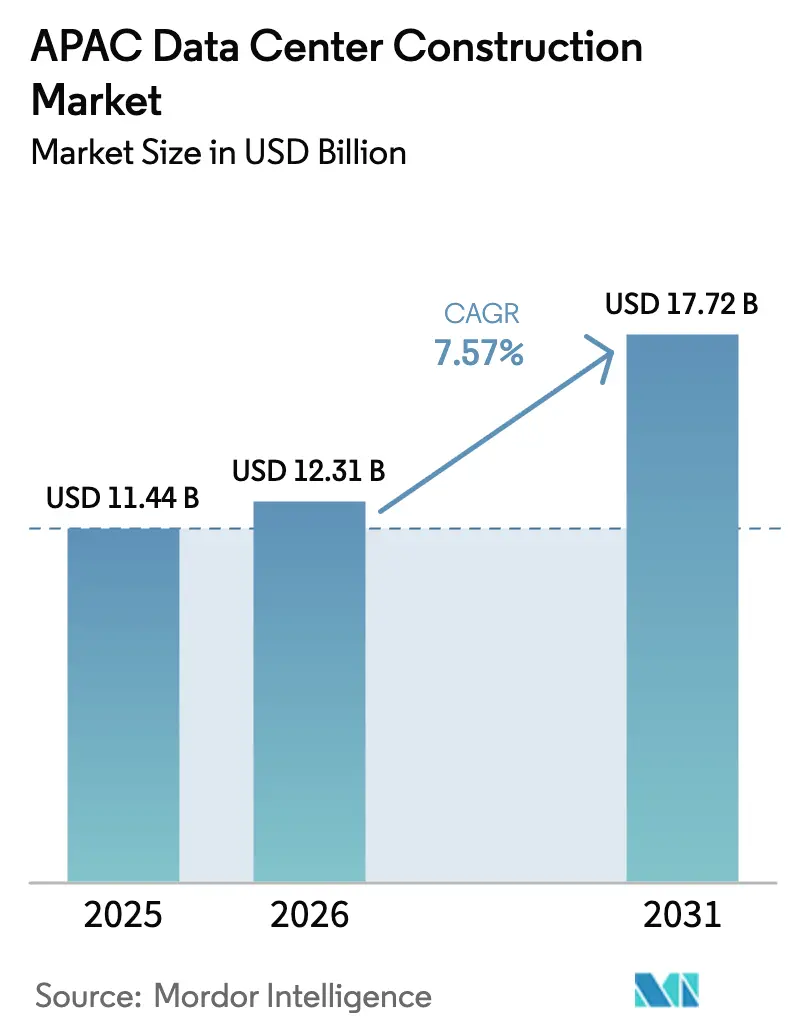
The Asia Pacific data center construction market size in 2026 is estimated at USD 12.31 billion, growing from 2025 value of USD 11.44 billion with 2031 projections showing USD 17.72 billion, growing at 7.57% CAGR over 2026-2031. Growing investment in AI-ready hyperscale campuses, government-backed digital-economy programs, and green-financing instruments are driving sustained growth across every major economy in the region. Operators are re-designing facilities for 40-80 kW rack densities, accelerating demand for liquid-cooled electrical and mechanical systems. Secondary locations such as Johor Bahru and Batam are attracting record commitments as primary hubs face power and land constraints, while sovereign incentives in western China and provincial South Korea keep construction pipelines full. Competitive intensity is rising as cloud platforms shift from colocation leases to self-build projects that guarantee end-to-end control of AI workloads.
Key Report Takeaways
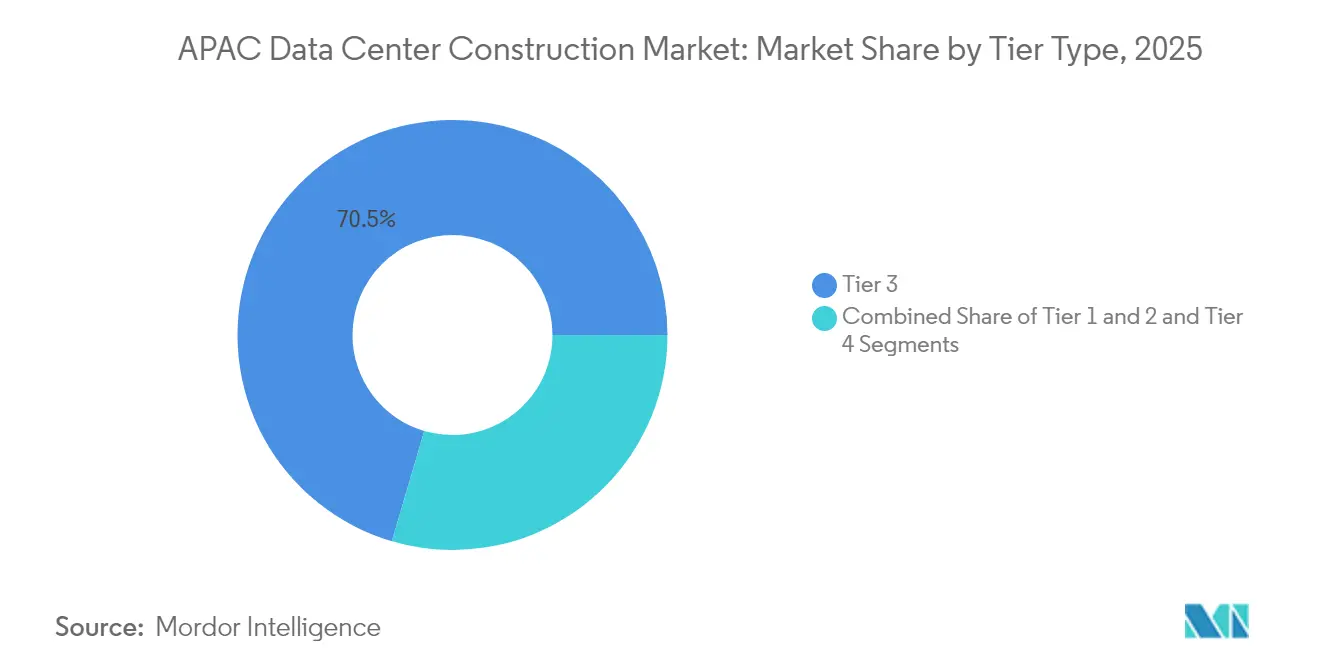
- By tier type, Tier 3 facilities held 70.45% revenue share of the Asia Pacific data center construction market in 2025, whereas Tier 4 builds are forecast to post the fastest 10.67% CAGR through 2031.
- By data center type, colocation retained 54.62% of the Asia Pacific data center construction market share in 2025, while self-build hyperscaler campuses are on track for a 12.05% CAGR to 2031.
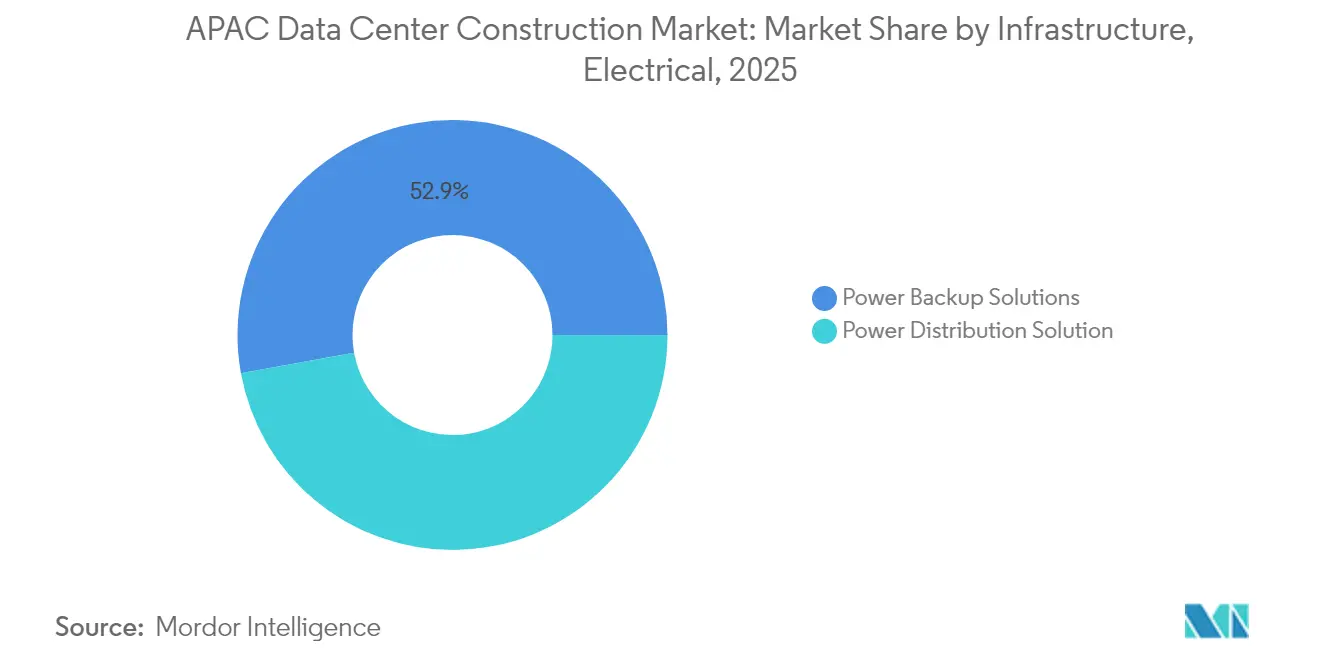
- By electrical infrastructure, power backup solutions commanded 52.85% of the Asia Pacific data center construction market size in 2025; power distribution solutions are projected to expand at 12.68% CAGR.
- By mechanical infrastructure, cooling systems accounted for 44.78% share of the Asia Pacific data center construction market size in 2025, with servers and storage advancing at 10.36% CAGR.
- Regionally, China led spending in 2024; Malaysia is the fastest-growing geography with Johor campuses expected to overtake Singapore capacity by 2028.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
APAC Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale and AI demand for high-density campuses | +2.8% | Global, concentrated in China, Japan, South Korea | Medium term (2-4 years) |
| Government digital-economy and 5G push | +1.9% | APAC core, with spillover to Southeast Asia | Long term (≥ 4 years) |
| Sustainability-linked green financing | +1.2% | Global, early adoption in Singapore, Australia | Short term (≤ 2 years) |
| Spill-over migration from Singapore to Johor and Batam | +0.8% | Southeast Asia, focused on Malaysia and Indonesia | Medium term (2-4 years) |
| Edge DC builds at new submarine-cable landings | +0.6% | APAC coastal regions, submarine cable hubs | Long term (≥ 4 years) |
| Inland-China provincial land-power incentives | +0.5% | Western and Northern China provinces | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Hyperscale and AI demand for high-density campuses
Asia Pacific operators are re-engineering layouts to host 40-80 kW racks, triple traditional thresholds, in order to run generative-AI model training at scale. South Korean and Japanese campus blueprints already stipulate multi-gigawatt utility feeds and direct-to-chip liquid cooling. Hyperscalers view control of power, network, and thermal environments as non-negotiable for latency and security, pushing design-build firms toward modular, prefabricated electrical rooms that slash deployment timelines. Capital flows mirror this shift; SK Telecom has earmarked KRW 3.4 trillion for AI infrastructure through 2028.[1]SK Telecom — “AWS and SKT to Build AI Data Center in Ulsan,” sktelecom.com Equipment vendors are responding with GPU-optimized switchgear and immersion-ready server chassis, tightening collaboration between silicon suppliers and construction contractors.
Government digital-economy and 5G push
Mandates such as China’s Eastern Data Western Compute program and Japan’s semiconductor and digital-industry roadmap are creating explicit build targets tied to sovereign compute capacity. Beijing’s initiative alone is mobilizing 400-500 billion RMB to deploy eight national hubs and ten regional clusters by 2030.[2]Ministry of Economy, Trade and Industry — “Strategy for Semiconductors and the Digital Industry,” meti.go.jp Similar laws in Vietnam require a National Data Centre with integrated risk-assessment functions beginning July 2025, immediately translating into tender activity. Parallel nationwide 5G rollouts elevate edge-node requirements, with telecom carriers leasing or co-developing micro-facilities alongside tower infrastructure to lower user-plane latency.
Sustainability-linked green financing
Loan structures indexed to power-usage effectiveness and renewable-energy coverage are lowering weighted average cost of capital for builders that surpass efficiency benchmarks. AirTrunk’s sustainability-linked facility sets annual targets on megawatt hours of renewable supply and data-center water usage.[3]AirTrunk — “AirTrunk Completes Sustainability-Linked Loan,” airtrunk.com AdaniConneX attracted USD 1.44 billion for ESG-compliant Indian campuses, while Princeton Digital Group closed Southeast Asia’s largest green loan at USD 280 million to fund a 150 MW Johor site. Access to cheaper funding is now a competitive advantage, especially in jurisdictions where utilities impose carbon-pricing mechanisms.
Edge DC builds at new submarine-cable landings
Every new cable landing station effectively seeds an edge-computing cluster because latency-sensitive services gravitate toward the first aggregation point of international traffic. Singapore’s Digital Connectivity Blueprint calls for doubling landing routes while situating “Green Data Hubs” within campus distances of shoreline tie-ins. Batam and Mactan have followed, expediting permits for data-center shells inside their cable-landing parks. Distributed micro-facilities reduce backhaul, improve user experience for streaming and gaming, and set up a logical migration path for autonomous-vehicle data offload.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-sovereignty compliance hurdles | -1.4% | China, Vietnam, with spillover effects globally | Short term (≤ 2 years) |
| Power-grid bottlenecks in tier-1 metros | -0.9% | Singapore, Hong Kong, Tokyo, Seoul | Medium term (2-4 years) |
| High-seismic-zone insurance premiums | -0.6% | Japan, Philippines, Indonesia, New Zealand | Long term (≥ 4 years) |
| Liquid-cooling talent gap | -0.4% | Global, acute in Southeast Asia and emerging markets | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Data-sovereignty compliance hurdles
New cross-border transfer rules in China and Vietnam obligate operators to perform risk assessments and appoint data-security officers, increasing both legal and technical overhead. The absence of a unified definition for “important data” forces multinational cloud platforms to replicate infrastructure country by country. Enterprises are incurring 15-20% incremental operating expense for duplicate archival systems, while construction-stage design must allocate extra white-space for nation-specific cage segregation.
Power-grid bottlenecks in tier-1 metros
Grid moratoria in Singapore and capacity queues in Tokyo and Hong Kong inject timing uncertainty into project schedules. AI-ready blocks that need 50-100 MW continuous loads sometimes wait 24-36 months for permits. As a mitigation, developers are pivoting to Johor, Ulsan, and Western China where industrial estates bundle land with captive generation. LNG and offshore-wind hybrids are emerging as interim sources until regional grids upgrade transmission corridors.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Tier 4 Emerges Despite Tier 3 Dominance
Tier 3 sites accounted for 70.45% of the Asia Pacific data center construction market in 2025, validating their cost-efficiency for most enterprise and cloud use cases. Yet hyperscale AI training demands fail-safe redundancy; therefore Tier 4 capacity is set to register an 10.67% CAGR through 2031. The Asia Pacific data center construction market size for Tier 4 builds is rising fastest in South Korea and Japan where multi-petaflop clusters mandate concurrent maintainability. Operators accept an estimated 40-60% capex premium because contract clauses guarantee 99.995% uptime, a pre-condition for GPU leasing revenue streams. Uptime Institute certifications are becoming competitive differentiators. NEXTDC’s accredited Tier IV Sydney campus illustrates how audit-based credentials secure premium pricing. Simultaneously, some Chinese and Australian contracts specify “Tier 4-plus” add-ons such as dual utility feeds from separate substations. Although Tier 1 and Tier 2 footprints persist for edge or industrial IoT nodes, their relevance is shrinking as enterprise colocation renewals migrate to higher resilience tiers.


By Data Center Type: Hyperscaler Self-Build Disrupts Colocation Model
Colocation still held 54.62% of the Asia Pacific data center construction market share in 2025, buoyed by financial-services and gaming tenants seeking carrier-neutral interconnect. Nevertheless, the self-build trajectory of Amazon, Google, Microsoft, and Alibaba underpins a 12.05% CAGR for owner-operated campuses to 2031. The Asia Pacific data center construction market size for self-build projects has escalated in Australia where AWS alone earmarked AUD 20 billion for new capacity between 2025 and 2029.
As hyperscalers internalize real estate, colocation incumbents respond by clustering in under-served metros and layering managed AI-platform services. ST Telemedia Global Data Centres will inject USD 3.2 billion into 550 MW of India builds, repackaging halls as turnkey GPU-pods. Edge and enterprise micro-sites also grow but at a measured clip, hinging on 5G densification and corporate hybrid-cloud preferences.
By Electrical Infrastructure: Power Distribution Innovation Drives Growth
Power backup solutions captured 52.85% of 2025 spend, reflecting the Asia Pacific data center construction market’s historic focus on generator and UPS resilience. Rising rack densities, however, make intelligent power distribution units the fastest-growing sub-segment, charting 12.68% CAGR through 2031. High-density layouts require busway designs that dynamically re-route amperage, while lithium-ion battery strings displace traditional VRLA cabinets to shave floor loading.
Renewables integration is also changing schematics. Projects such as HiCloud’s offshore wind-powered underwater module near Shanghai showcase battery energy storage systems coupled directly to turbine output. Smart-grid interfaces enable campuses to offer demand-response services and monetize idle capacity during non-peak training cycles, aligning operational savings with green-loan covenants.
By Mechanical Infrastructure: Liquid Cooling Transforms Server Architecture
Cooling systems represented 44.78% of outlays in 2025 but are transitioning from air to liquid modalities. Direct-to-chip loops and immersion tanks now underpin designs exceeding 80 kW per rack. Canon IT Solutions retrofitted its West Tokyo site for 100 kVA racks using DLC manifolds, validating retrofit economics without full shutdown.
Servers and storage investments, expanding at 10.36% CAGR, bundle high-bandwidth fabrics and NVMe arrays tuned for AI inference. Chassis vendors partner with cooling-fluid specialists to certify leak-proof quick-disconnects, while cabinet makers release sealed doors with integrated heat-exchanger panels. Modular edge pods leverage the same architectures at micro-scale, enabling telecom carriers to deploy 5 kW liquid-ready cabinets beside 5G base stations.
Geography Analysis
China retained top position in 2024 construction value on the strength of the Eastern Data Western Compute scheme, which disburses subsidies for land and renewable electricity in Guizhou, Gansu, and Inner Mongolia. Several western provinces now offer power tariffs 20-30% below coastal rates, encouraging cloud majors to shift latency-insensitive loads inland. The Asia Pacific data center construction market size for western Chinese clusters will therefore eclipse coastal additions by the late-2020s, even as national electricity demand from data centers could reach 600 TWh by 2030.
Southeast Asia is the fastest-rising sub-region. Malaysia attracted USD 23.3 billion of commitments in 2024, and Johor campuses are set to overtake Singapore capacity by 2028. Indonesia’s Batam Special Economic Zone is pairing cable-landing licenses with land parcels, drawing hyperscalers that require sub-20 ms latency into Jakarta. Vietnam’s new Law on Data mandates creation of a National Data Centre and drives local build pipelines; simultaneous cross-border rules are influencing network topologies for multinational tenants.
Developed APAC economies emphasise AI speciality builds and sustainability. South Korea has green-lit a 3 GW Jeollanam-do mega-site and AWS-SK Telecom’s 103 MW LNG-cooled campus in Ulsan. Japan’s ministry programs target 2 trillion-yen cumulative market value by 2030, encouraging deployments in Fukushima and Osaka equipped with NVIDIA H100 clusters. Australia follows with record hyperscale capex, alongside NEXTDC’s Sydney S7 land purchase that will support a Tier IV, 300 MW precinct once grid upgrades conclude.
Regulatory Landscape
Regulation in Asia-Pacific increasingly links new data center construction to security, resilience, and sustainability compliance, with permitting and grid-connection processes becoming a direct schedule constraint. Singapore advanced a draft Digital Infrastructure Bill through public consultation, proposing mandatory requirements for data centers meeting a critical IT load threshold (at least 3 MW) around cybersecurity, service continuity, and sustainability reporting, which affects design specifications and documentation from early concept through commissioning.
Across the region, governments are also issuing policy guidance that shapes environmental and community approvals for power-intensive builds. Australia’s Department of Industry, Science and Resources published “Expectations of data centres and AI infrastructure developers” on March 23, 2026, outlining social-license and assessment priorities for developers. At a regional level, the ASEAN Guide for Sustainable Data Centre Development (finalized in Dec 2025) and the ASEAN Plan of Action for Energy Cooperation (2026-2030) reinforce efficiency and renewable-alignment norms, which are increasingly reflected in financing conditions and utility engagement, especially where utilities and regulators require upfront power impact assessments before confirming connections.
Value Chain Analysis
The APAC data center construction value chain typically starts with land acquisition and utility engagement, including power impact studies and connection applications. It then moves through design and engineering (architectural plus specialist MEP), procurement of long-lead electrical and cooling systems, general contracting and fit-out, and finally integrated testing and commissioning prior to handover and ongoing support and maintenance. Delivery models vary by country and customer (colocation versus hyperscaler self-build), but interface management between OEMs, installers, and third-party commissioning agents is a key risk area because equipment such as UPS, generators, and switchgear is often globally sourced and integrated on compressed schedules.
Supply constraints concentrate in specialist execution capacity and long-lead components. Industry assessments cited for APAC point to a shortage of specialized MEP trades and rising delivery risk as build pipelines expand, while construction costs have tracked roughly 7-10% CAGR through 2026. Capacity pressure shows up in supplier utilization, with part of the supply base operating above 80% utilization as of July 2026, creating lead-time and substitution challenges. Fabrication for electrical steel and copper busway is concentrated in China, South Korea, and Japan, while precision cooling equipment supply is dominated by European and Japanese vendors. This supports procurement strategies that favor early ordering, framework agreements, and more prefabricated electrical and mechanical rooms to reduce onsite labor intensity.
Competitive Landscape
Industry structure is moderately fragmented; traditional colocation groups coexist with vertically integrated cloud builders. Blackstone’s USD 16 billion acquisition of AirTrunk and KKR’s USD 1.75 billion injection into ST Telemedia Global Data Centres illustrate private-equity appetite for scale platforms. Partnerships such as Singtel–Hitachi target 200 MW of regional AI-ready capacity, bundling GPU cloud services with construction expertise.
Technology leadership is the key differentiator. Equinix deploys green-bond proceeds to reach 96% renewable-energy coverage across 172 projects, positioning itself for ESG-driven tenant procurement. EdgeConneX expands into Japan to capture submarine-cable edge demand, while domestic Chinese players leverage state incentives to export design services across Belt-and-Road partners.
Supplier ecosystems are also shifting. Electrical OEMs co-develop prefabricated power rooms tailored for GPU voltage stability, and liquid-cooling specialists license patented dielectric fluids to systems integrators. Construction timelines shorten as modular blocks leave factories 90% complete, enabling 20–25 MW go-live targets inside 12 months, a critical capability for AI pipeline launches.
APAC Data Center Construction Industry Leaders
DPR Construction Inc.
Turner Construction Company
Exyte GmbH
Leighton Asia
AECOM
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
White-space creation in secondary and emerging hubs is expanding as power and land constraints, along with stricter approval requirements in tier-1 metros, push developers to diversify locations and delivery formats. Southeast Asia is a key near-term build theater, with industry tracking indicating the sub-region accounted for 31% of data center capacity under construction as of March 2026. That aligns with the broader spill-over migration toward Malaysia (Johor) and Indonesia (Batam) and supports campus-style, multi-phase developments delivered using standardized, repeatable design blocks, especially where utilities and industrial estates can bundle land with clearer power pathways.
There is also an opportunity in faster-deploying formats that fit edge computing and 5G densification timelines. Demand is rising for micro data centers and modular deployments targeting sub-12-month go-live cycles, which expands the addressable scope for prefabricated electrical rooms, containerized cooling, and integrated commissioning services. On the supply side, the regional ecosystem is scaling to serve these needs, including Exyte and JGC’s Nixyte platform aimed at high-tech EPC delivery across Southeast Asian markets. This supports owners that want integrated execution capability rather than multi-vendor contracting, particularly where specialist labor depth is limited.
Recent Industry Developments
- May 2026: Leighton Asia awarded works for a new high-rise data centre project in Hong Kong, including shell and core works with a two-storey basement. The development signals continued expansion of high-density facilities in Hong Kong, strengthening APAC capacity for multi-phase campus deliveries in luxury and high-density markets.
- April 2026: Leighton Asia secured a contract for a large-scale data centre project in Malaysia as part of a multi-phase hyperscale campus. The move broadens the regional hyperscale footprint and validates a multi-phase build approach across Southeast Asia.
- February 2026: Exyte (Nixyte) officially opened a new Nixyte office in Bangkok, Thailand, to support integrated EPC solutions for data centers and other high-tech industries across Southeast Asia. The expansion enhances the Southeast Asia delivery network and enables faster go-lives for AI-ready facilities.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market includes spending tied to building and fitting out data centers across Asia Pacific, covering the civil works and the installed electrical and mechanical packages that make the facility operational.
Scope exclusions: Land purchase, long term IT hardware refresh, and pure operations and maintenance services are excluded unless they are bundled inside a construction or major retrofit contract.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with public indicators that show where capacity is being built, how fast demand is rising, and what it typically costs to deliver a megawatt of new capacity in each key country. We relied on sources such as International Energy Agency power statistics, national energy regulators and grid connection publications, telecom and digital ministry releases, and building permit and construction output data from official statistics agencies.
To convert these signals into a workable sizing model, we also used items like operator and contractor announcements, investor presentations, and audited financial filings where they are available, which helped us map project pipelines and timing. In a few places, subscription databases were used for company financials and intelligence, patent lookups related to power and cooling systems, and selective import and export shipment signals for key equipment categories. These desk sources are illustrative, and many other public and paid references were used to collect data, validate assumptions, and clarify unclear points.
Primary Interviews and Surveys
Primary work was used to pressure test the construction scope, typical cost build up, and delivery timelines for greenfield and retrofit projects, since secondary signals can lag fast moving capacity plans. We spoke with stakeholders across design, engineering, construction, and procurement, and we also covered owners and operators who approve budgets, which helped us confirm how projects are priced and what gets counted as construction in real contracts. Because this is a multi-country market, we balanced inputs across major hubs and emerging build locations in APAC, so local cost and permitting realities were reflected in the final assumptions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 38% | CXOs: 12% |
| Mid tier: 48% | Functional/Unit leaders: 39% |
| Smaller Players: 14% | Managers: 49% |
Market-Sizing & Forecasting
Sizing was built using a top down approach where planned and under-construction IT load (MW) by market was reconstructed from public pipeline signals and then converted into construction value using country-level cost per MW ranges and typical build mixes. To keep the totals grounded, we then checked the result with selective bottom-up approximations such as sample project cost benchmarking, contractor revenue exposure to data center projects, and channel checks for major electrical and mechanical packages.
Key inputs that shaped the model included announced capacity additions and commissioning dates, average construction cost inflation, the split between greenfield builds and major retrofits, the share of higher tier facilities that drive redundancy spend, and changes in rack density that shift cooling and power design needs. Where project disclosure was limited, gaps were handled by applying conservative utilization of announced pipelines and using proxy cost curves from comparable nearby hubs, followed by a review with local experts.
For forecasting, we used scenario analysis with a central case that reflects expected grid connection timing, permitting throughput, and financing conditions, and then adjusted using expert views on hyperscale and colocation expansion plans. The outputs were kept in USD using consistent exchange rate timing assumptions so cross-country aggregation stayed comparable year to year.
Data Validation & Update Cycle
Estimates were validated through a stepwise review that compares model outputs against independent signals such as new capacity brought online, visible construction starts, and cost index movement for labor and materials. When variance appeared, assumptions were re-checked, and follow-up conversations were triggered with relevant respondents to confirm whether the change came from scope, timing, or pricing.
Before sign-off, calculations are reviewed by another analyst to catch unit issues, double counting, and country roll-up errors, and then the narrative is aligned with the final numbers. Reports are refreshed annually, and interim updates are made when material events occur, for example sudden permitting pauses, major new campus awards, or large shifts in build costs. Before delivery, a fresh pass is completed so clients receive the latest updated view.
黑料不打烊's Asia Pacific Data Center Construction Market Size Compared With Other Published Estimates
Published market sizes for APAC data center construction often differ, even when they sound like they cover the same topic, because the counted spend is not always the same. Differences usually come from what is treated as construction, how MW pipelines are converted into dollars, and whether retrofit and fit-out work is included.
The main gap comes from whether only shell-and-core buildings are counted or the full fit-out is included, where 黑料不打烊 counts electrical and mechanical packages as construction only when they are part of a contracted build or major upgrade scope. Estimates also diverge when cost per MW is held flat across countries, when conservative or aggressive pipeline realization is assumed, or when older exchange rate timing is used for USD conversion, which can move the total noticeably in a multi-currency region.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 12.31 B (2026) | |
| Global Real Estate Advisory A | USD 116.18 B (2024) | Uses a multi-year pipeline funding requirement across colocation capacity and treats it as construction need, which can overstate annual market value and mixes timing across 5 to 7 years. |
| Market Data Release B | USD 67.23 B (2022) | Represents an earlier base year and tends to blend broader infrastructure and services around data centers, with limited clarity on whether electrical and mechanical fit-out is measured at installed value or at budgeted CAPEX. |
The spread in values is mainly explained by timing and what is being counted, since pipeline funding totals and broad CAPEX views are not the same as annual construction market value. By keeping the scope tied to contracted build and upgrade activity and validating cost and MW assumptions with cross-checks, the final number stays traceable to repeatable inputs that a buyer can audit.


Key Questions Answered in the Report
What is the current size of the Asia Pacific data center construction market?
The market reached USD 12.31 billion in 2026 and is expected to hit USD 17.72 billion by 2031.
Which tier classification dominates new builds in Asia Pacific?
Tier 3 still leads with 70.45% share, but Tier 4 facilities are growing fastest at 10.67% CAGR.
Why are hyperscalers moving from colocation to self-build campuses?
Direct control over high-density AI workloads, power, cooling, and security drives a 12.05% CAGR for self-build projects through 2031.
How are sustainability goals influencing project financing?
Operators secure lower-cost capital through sustainability-linked loans that reward energy-efficiency and renewable-power milestones.
Which Southeast Asian location is emerging as the next hyperscale hub after Singapore?
Johor Bahru, Malaysia, backed by abundant land and green-loan funding, is projected to surpass Singapore’s installed capacity by 2028.
What technologies enable 40-80 kW rack densities required for AI?
Direct-to-chip and immersion liquid-cooling systems combined with intelligent power distribution units manage the higher thermal and electrical loads.
Page last updated on:
- Data Center Power Market Power systems across all regions, split by component, tier and facility size.
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Asia Pacific Hyperscale Data Center Market Asia-Pacific hyperscale sites, split by data centre type, component and tier.
- APAC Data Center Server Market Asia-Pacific servers, split by facility size and tier.
- Asia-Pacific Data Center Storage Market Storage in Asia-Pacific, split by storage technology, storage type and end user.
- South Korea Data Center Rack Market South Korea racks, split by rack size, rack height and rack type.
- Japan Data Center Server Market Japan's servers, split by tier, facility size and facility type.
- Australia Data Center Power Market Australia's power systems, split by component, facility type and facility size.
- South Korea Data Center Power Market South Korea power systems, split by facility size and tier.
- Asia-Pacific Artificial Intelligence (AI) Optimised Data Center Market AI facilities in Asia-Pacific, split by facility type, component and tier.



