
Australia Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 11.12 Billion |
| Market Size (2026) | USD 11.57 Billion |
| Market Size (2031) | USD 14.72 Billion |
| Growth Rate (2026 - 2031) | 4.93 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Australia Data Center Construction Market Analysis by 黑料不打烊
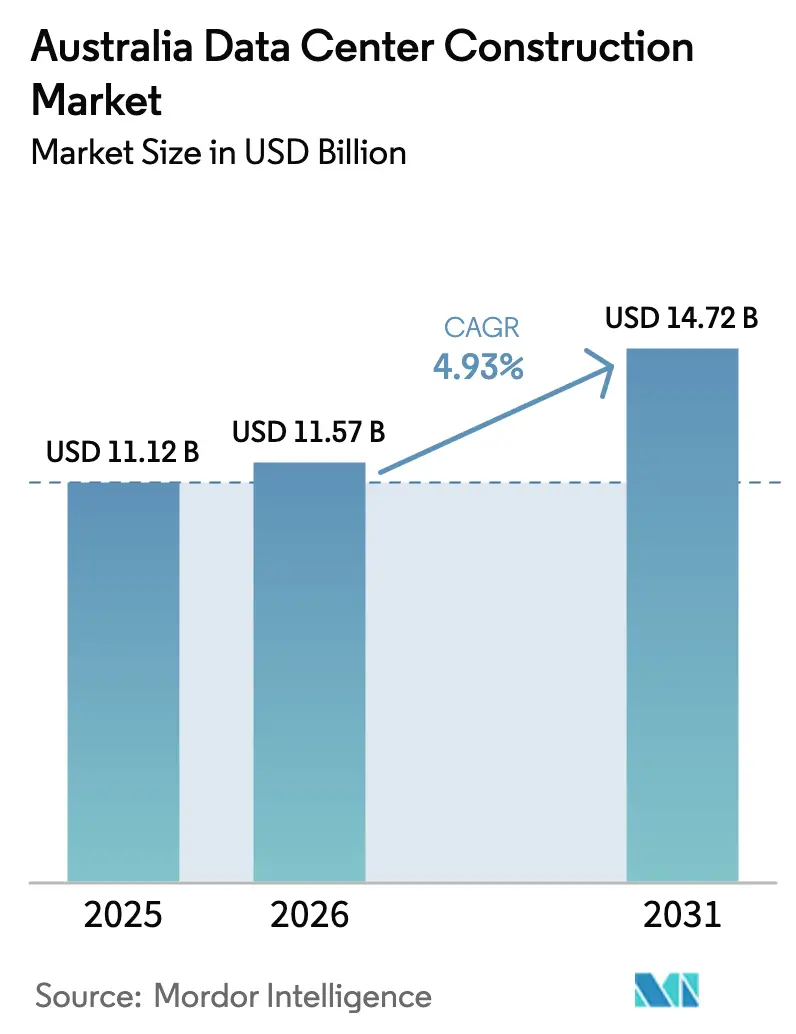
The Australia data center construction market size is projected to be USD 11.12 billion in 2025, USD 11.57 billion in 2026, and reach USD 14.72 billion by 2031, growing at a CAGR of 4.93% from 2026 to 2031. The measured expansion is underpinned by hyperscale capital commitments that tilt spending toward fewer, very large campuses, reinforcing supply-side discipline even as demand for AI-ready capacity accelerates. Government-backed renewable-energy incentives, powered-shell design adoption, and rising rack densities collectively reshape project economics, pushing turnkey contractors to integrate liquid-cooling expertise and modular builds. Competitive strategies now hinge on locking in long-lead electrical equipment, securing grid allocations ahead of rivals, and offering tenants sub-18-month delivery windows. These factors allow well-capitalized developers to preserve margins despite double-digit construction-cost inflation and tightening zoning rules in Sydney and Melbourne. The Australia data center construction market, therefore, evolves from volume-driven enterprise builds to a capital-intensive, hyperscale-first landscape that prizes speed-to-market and energy efficiency.
Key Report Takeaways
- By tier type, tier 3 captured 56.84% of the Australia data center construction market share in 2025, while tier 4 facilities are forecast to post a 5.46% CAGR through 2031.
- By size, hyperscale campuses commanded 60.13% of the Australia data center construction market size in 2025 and are projected to grow at a 5.78% CAGR to 2031.
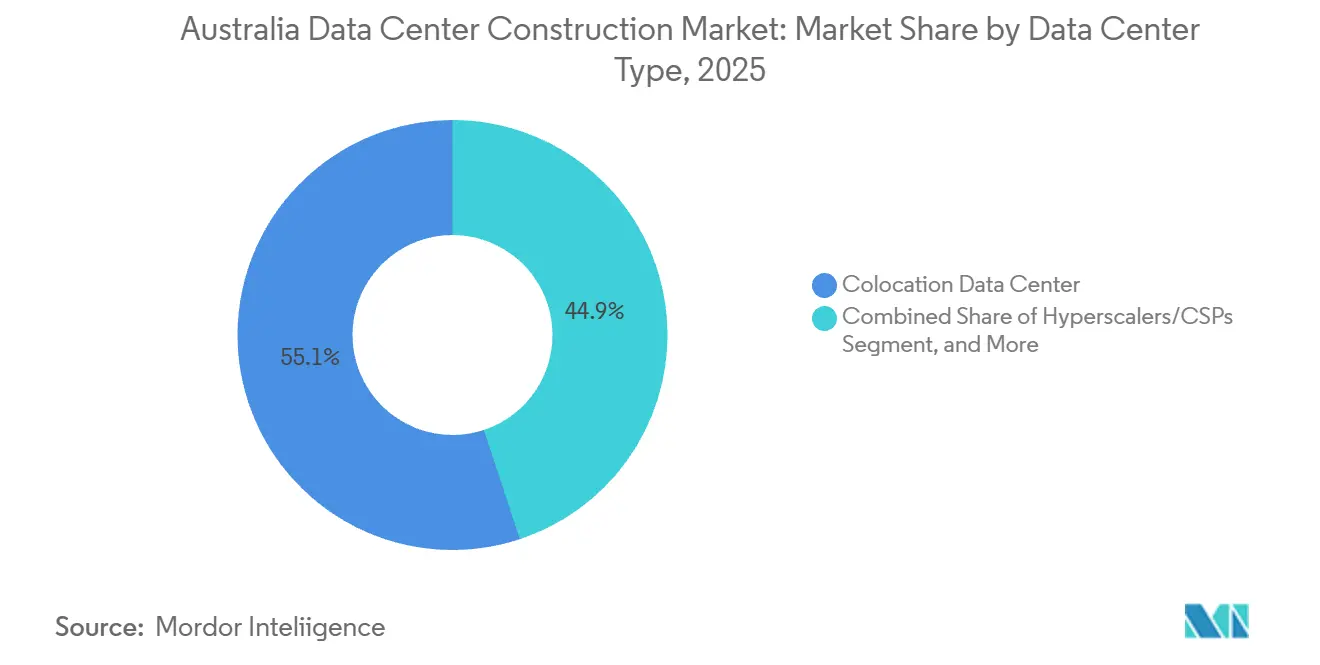
- By data center type, colocation providers held 55.08% of the Australia data center construction market share in 2025; hyperscalers and cloud providers will expand at a 5.82% CAGR during the same period.
- By infrastructure, electrical infrastructure accounted for 39.82% of market share in 2025, while mechanical systems are expected to record a 6.12% CAGR between 2026 and 2031, outpacing other spend categories.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Australia Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in Hyperscale and Cloud Provider Investment | +1.8% | Global, concentrated in Sydney and Melbourne | Medium term (2-4 years) |
| Low-Latency Edge Demand in Sydney and Melbourne | +0.9% | Sydney, Melbourne, with spillover to Brisbane | Short term (≤ 2 years) |
| Government Renewable-Energy Incentives for Green DCs | +0.7% | National, strongest in Victoria and Queensland | Long term (≥ 4 years) |
| AI/HPC Rack-Density Boom Raising New-Build Demand | +1.2% | Global, early adoption in major metros | Medium term (2-4 years) |
| Powered-Shell Leasing Model Shortens Time-To-Market | +0.4% | National, emerging in secondary markets | Short term (≤ 2 years) |
| Repurposing Retired Coal-Plant Sites into DC Campuses | +0.3% | New South Wales, Victoria, Queensland | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Surge in Hyperscale and Cloud Provider Investment
AWS committed AUD 20 billion (USD 13.2 billion) through 2029 for new Sydney and Melbourne availability zones, setting a precedent for multi-year, multi-region builds that absorb grid headroom before rivals can mobilize.[1]AWS to Invest AUD 20 Billion in Australia,” About Amazon, aboutamazon.com.auMicrosoft added a fourth Australian cloud region in 2025 and earmarked capacity increases to 150 MW by 2027, reinforcing the winner-takes-most dynamic. Developers that pre-secure easements and substation upgrades effectively ring-fence metro markets for up to seven years. Colocation operators therefore pivot to powered-shell models, illustrated by Macquarie Data Centers’ 47 MW IC3 Super West project that allows tenant fit-outs during core construction.
AI/HPC Rack-Density Boom Raising New-Build Demand
Rack densities for NVIDIA H100 and AMD MI300 GPU clusters now exceed 100 kW, five times traditional enterprise loads, accelerating demand for chilled-water loops and direct-to-chip cooling. AirTrunk’s 354 MW MEL2 campus integrates rear-door heat exchangers and redundant cooling distribution units that legacy air-cooled halls cannot retrofit cost-effectively.[2]MEL2 Melbourne Campus Development,” AirTrunk, airtrunk.com Upgrading an existing 10 MW facility to liquid cooling costs roughly 60% of a greenfield build while yielding only half the usable density, driving hyperscalers toward purpose-built campuses.
Low-Latency Edge Demand in Sydney and Melbourne
Financial-services, gaming, and AR workloads require sub-5 ms round-trip times, prompting Telstra to deploy micro data centers in 15 retail sites across both cities in 2025.[3]Edge Computing Network Expansion,” Telstra, telstra.com.au Optus extended AWS Local Zones to Brisbane and Perth, lowering latency for regional users. Although individual builds are small at 2-5 MW, premium rents of AUD 300-400 (USD 210-280) per kW monthly create attractive unit economics that complement hyperscale campuses in outer suburbs.
Government Renewable-Energy Incentives for Green DCs
The Commonwealth’s Capacity Investment Scheme underwrites 32 GW of dispatchable renewables, trimming power-purchase costs for data centers willing to locate near renewable-energy zones. New South Wales’ Grid Enhancing Technologies grants further subsidize transmission upgrades for facilities tapping wind and solar farms. Opex savings of AUD 2-3 (USD 1.4-2.1) million annually for a 50 MW site enhance project IRRs, yet the 200-300 km distance from fiber hubs forces developers to weigh latency against energy cost.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Land Scarcity and Zoning Limits in Tier-1 Metros | -1.1% | Sydney, Melbourne primary impact | Medium term (2-4 years) |
| Grid Connection Delays and Limited Power Availability | -0.8% | National, acute in established markets | Long term (≥ 4 years) |
| Shortage of Specialized Trades Inflates Build Costs | -0.6% | National, concentrated in major metros | Short term (≤ 2 years) |
| New Critical-Infrastructure Cyber Rules Escalate Capex | -0.4% | National, all critical infrastructure | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Grid Connection Delays and Limited Power Availability
AEMO’s 2025 Integrated System Plan forecast congestion in Sydney’s western suburbs and Melbourne’s north until at least 2028, delaying connection approvals for 50 MW loads. TransGrid confirmed that 12 queued projects totaling 800 MW await transformer deliveries that will not materialize before 2027. Hyperscalers with balance-sheet heft sidestep the queue by financing dedicated spurs and take-or-pay generation, sidelining mid-tier players that cannot commit to 100 MW uplifts.
Land Scarcity and Zoning Limits in Tier-1 Metros
New South Wales capped individual data center parcels in Macquarie Park and Eastern Creek at 10 hectares to preserve industrial stock for manufacturing. Victoria’s Plan Melbourne policies restrict greenfield approvals, pushing developers toward brownfield conversions that add 6-12 months to timelines. Industrial land in western Sydney traded at AUD 600-800 (USD 420-560) per m? in 2025, a 60% increase over 2023, eroding returns for speculative builds.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Redundancy Premiums Drive Tier 4 Growth
In 2025, Tier 3 facilities dominated the Australia data center construction market, securing a 56.84% share. Meanwhile, Tier 4 facilities are projected to achieve a 5.46% CAGR from 2026 to 2031. Tier 4 capacity is forecast to expand as hyperscalers and financial institutions internalize the cost of downtime. The Australia data center construction market size for Tier 4 deployments will therefore rise faster than the broader market, while Tier 3 continues to dominate on an installed-base basis. NEXTDC’s M3 achieved Tier IV Gold certification in 2024, demonstrating dual utility feeds and N+1 cooling that meet CPS 230 operational resilience mandates. Enterprises willing to accept planned downtime remain in Tier 3, yet regulatory pressure from APRA nudges mission-critical workloads toward fully fault-tolerant designs.
Pricing differentials narrow as liquid-cooling costs compress; a 15-minute outage in a Tier 3 hall could cost a fintech platform up to AUD 1 million (USD 0.7 million) in lost transactions, negating rent savings. Consequently, Tier 3 operators face a strategic choice: retrofit to Tier 4 at roughly USD 20-30 million per 10 MW module or cede high-margin demand to rivals. Over 60% of AirTrunk’s 2025 leasing inquiries already specified Tier IV requirements, signaling a structural upgrade cycle.


By Data Center Size: Hyperscale Economies Marginalize Mid-Tier Builds
Hyperscale campuses captured 60.13% of 2025 revenue and will log a 5.78% CAGR to 2031, reinforcing the Australia data center construction market’s flight to very large projects. CDC’s 504 MW Marsden Park investment achieves USD 4,000 per kW build costs versus USD 5,300 per kW for 20 MW sites, demonstrating scale economies. Medium builds remain viable in Brisbane, Perth, and Adelaide, but lack access to 330 kV transmission and therefore top out at 10-20 MW.
Liquid-cooling-first designs deepen hyperscale moats, as greenfield campuses integrate chilled-water loops into the structural slab and 480-V distribution to minimize copper losses. Retrofitting medium sites trims usable white space by up to 20% and extends upgrade timelines to two years, further tilting economics toward large-scale new builds.
By Data Center Type: Hyperscalers Internalize Capacity
Hyperscalers and cloud providers are projected to grow at 5.82% annually, gradually eroding colocation’s 55.08% share of the Australia data center construction market. AWS’ AUD 20 billion (USD 13.2 billion) Australian investment favors owner-operated facilities, dropping unit cost from AUD 200-250 (USD 140-175) per kW in retail colo to AUD 120-150 (USD 84-105) in self-build scenarios. Microsoft purchased a 15-hectare Melbourne parcel for a 150 MW campus, reinforcing the shift to vertical integration.
Colocation specialists pivot toward hybrid-cloud enterprises needing low-latency interconnection. NEXTDC’s Cloud Connect fabric links more than 30 on-ramps, delivering sub-5 ms access to public clouds for regulated workloads. Edge and enterprise builds remain modest, as few corporate balance sheets can stomach USD 50-100 million for a 5-10 MW self-build.
By Infrastructure: Mechanical Spend Surges on Cooling Upgrades
Electrical infrastructure accounted for 39.82% of market share in 2025, whereas mechanical systems will register a 6.12% CAGR between 2026 and 2031, surpassing electrical growth yet remaining second in absolute spend. Liquid-cooling retrofits comprise up to half of mechanical capex for new hyperscale halls, with AirTrunk allocating AUD 800 million (USD 560 million) of its AUD 5 billion (USD 3.5 billion) MEL2 budget to chiller capacity and chilled-water piping. Standardized electrical designs moderate price escalation, but generator and transformer lead times still stretch beyond 18 months.
The services sub-segment grows in lockstep with mechanical complexity. Schneider Electric noted that 70% of its 2025 Australian projects involved liquid-cooling design services. Prefabricated power rooms and modular white-space kits reduce schedule risk by up to 30%, a compelling proposition for hyperscalers who demand occupied space within 12-18 months.
Geography Analysis
Sydney and Melbourne collectively captured nearly three-quarters of 2025 spend, cementing their status as the gravitational centers of the Australia data center construction market. Western Sydney suburbs such as Macquarie Park and Eastern Creek benefit from existing 330 kV lines and proximity to the Sydney-Singapore cable system, enabling hyperscale builds to tap multi-terabit connectivity. Melbourne’s northern corridor, from Laverton to Derrimut, offers sub-10 ms latency to the CBD, attracting colocation providers that monetize premium interconnect demand.
Second-tier metros, namely Brisbane, Perth, and Adelaide, are expected to grow at roughly 6-7% CAGR. NEXTDC’s B2 Brisbane expansion to 22 MW targets resources and agriculture clients, while Perth hosts edge nodes serving mining analytics workloads. Adelaide’s sovereign requirements sustain demand for Tier 3-plus facilities cleared by the Australian Signals Directorate.
The Australian Capital Territory remains a niche sovereign enclave, with federal workloads requiring strategic-level security, whereas Tasmania’s cool climate and hydroelectric surplus position it for future AI training campuses if Bass Strait transmission upgrades proceed. Latency constraints limit Tasmania to batch-processing, yet 500-MW-plus potential loads could materialize once grid interconnects improve.
Regulatory Landscape
Australia's regulatory environment for data center construction is tightening around energy and critical-infrastructure risk management. A key 2026 anchor is the Australian Government Department of Industry, Science and Resources issuing "Expectations of data centres and AI infrastructure developers" on 23 March 2026, which sets priorities used in Commonwealth regulatory assessments, particularly for new or expanded hyperscale and large-scale AI compute facilities.
Implementation is being coordinated with states and territories via the Energy and Climate Change Ministerial Council, while state planning systems still determine site-specific approvals. In New South Wales, Infrastructure NSW is developing Data Centre Guidelines through a consultation process to manage power and water security risks, adding another planning reference point for large campuses alongside existing local and state planning pathways.
Competitive Landscape
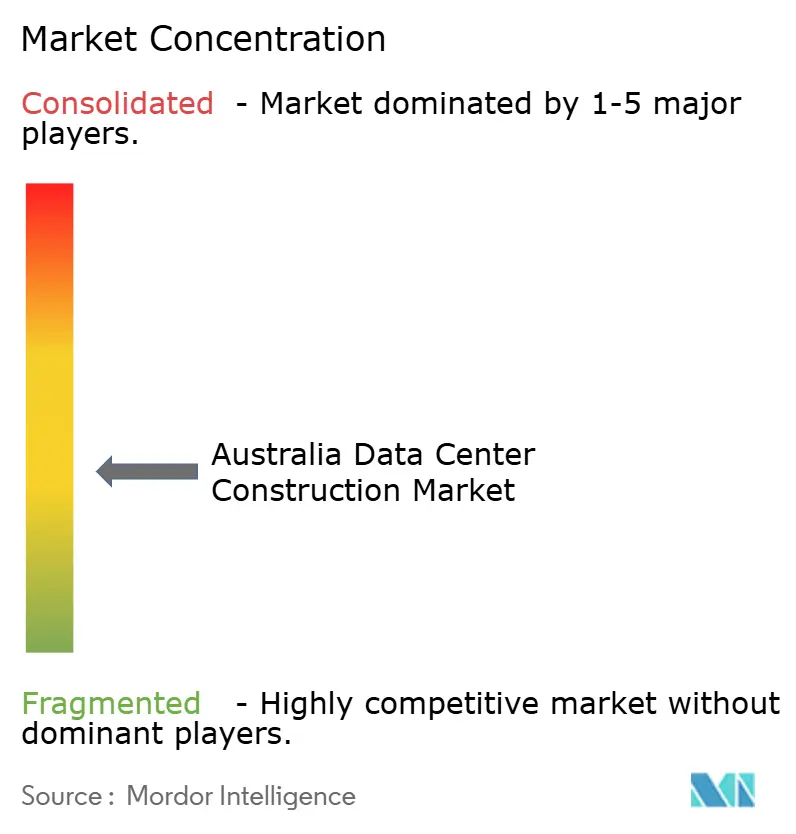
The Australia data center construction market exhibits moderate fragmentation. NEXTDC leverages public-equity access to fund speculative builds, launching a 550 MW S7 Sydney campus in 2025 without anchor tenants. AirTrunk, backed by Macquarie Asset Management, pre-builds powered shells that compress tenant ramp-up cycles, while CDC specializes in wholesale halls of 10-50 MW for single tenants unable to self-build.
Private equity interest intensified after Partners Group’s 2024 purchase of GreenSquareDC and pledge of AUD 1.2 billion (USD 0.84 billion) for expansion. Telstra and Optus dominate micro-edge deployments by leveraging telecom real estate. Equinix and Global Switch focus on interconnection-rich sites inside Sydney and Melbourne, extracting revenue from cross-connects rather than raw capacity. Competitive weapons revolve around construction speed, renewable energy sourcing, and compliance posture, especially in light of the Security of Critical Infrastructure Act’s risk-management mandates.
Technology adoption patterns reveal that operators embracing modular construction and prefabricated mechanical systems trim build schedules by up to 30%, a benefit documented across Schneider Electric’s 2025 Australian project portfolio. Compliance with ISO 27001 information security and ISO 50001 energy management standards is now table stakes for winning enterprise and government tenants, especially after the Security of Critical Infrastructure Act imposed mandatory risk-management programs on facilities above 25 MW. Liquid cooling expertise adds another edge, as Vertiv reports that hyperscale campuses integrating chilled-water rear-door heat exchangers can run 150 kW racks without efficiency penalties. Supply-chain resilience has also become a differentiator, with developers that lock in transformer and generator orders 18 months ahead shielding project timelines from global equipment shortages.
Australia Data Center Construction Industry Leaders
NEXTDC Ltd
AirTrunk Operating Pty Ltd
FDC Construction and Fitout
Multiplex Constructions Pty Ltd
CPB Contractors Pty Ltd
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A near-term whitespace for contractors and developers sits where AI-ready capacity delivery runs up against constrained grid access. This combination increases demand for integrated delivery models that bundle substation works, long-lead electrical procurement, and liquid-cooling mechanical packages, particularly for large campuses.
The build pipeline is being supported by disclosed capital formation. NEXTDC's A$2.2 billion capital plan, disclosed in April 2026, is aimed at accelerating AI-ready infrastructure and progressing large Sydney capacity such as the 350 MW S4 site at Horsley Park. Activity is also supported by a broader investor base behind Australian platforms, with CPPIB's A$76 million investment into NEXTDC reported in May 2026 and industry association Data Centres Australia flagging a $26 billion investment outlook to 2030. Together, these signals point to sustained work for design, civil works, electrical and mechanical integration, and compliance-led upgrades aligned to the March 2026 national expectations on energy and water stewardship.
Recent Industry Developments
- June 2026: AirTrunk announces US$30 billion investment program to develop 5GW of new data center capacity in India by 2030. The launch signals global hyperscale expansion and will affect regional capacity competition, potentially influencing Australian market positioning and supply-chain expectations for large-scale projects.
- April 2026: NEXTDC announces a fully funded A$2.2 billion capital plan to accelerate AI-ready infrastructure, including the 350MW S4 Sydney facility at Horsley Park. The plan directly addresses local demand for AI-ready capacity and reinforces NEXTDC as a dominant Australian campus developer in 2026 - 2029.
- March 2026: NEXTDC and Multiplex commence construction on NEXTDC's 350MW S4 Sydney data center in Horsley Park, NSW. The milestone enables accelerated delivery of large-scale capacity and demonstrates aggressive execution and strong vendor collaboration in high-density builds.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of building and fitting out data centers in Australia, including major construction activity tied to new builds, expansions, and upgrades that create usable technical space.
Scope exclusions: It does not count ongoing operations spending such as colocation service fees, electricity purchases, IT hardware refreshes, or day to day facility management.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small
- Medium
- Large
- Hyperscale
- By Data Center Type
- Colocation Data Center
- Hyperscalers/Cloud Service Provider (CSPs)
- Enterprise and Edge Data Center
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Services - Design and Consulting, Integration, Support and Maintenance
- Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research helped us set the starting structure of the market model and pin down the most repeatable inputs. We reviewed public planning and approvals signals, trade and cost indicators, and Australia level digital infrastructure updates that affect project timing.
Sources used included public data and publications such as the Australian Bureau of Statistics for construction and price series, energy system and grid information from the Australian Energy Regulator and AEMO, national communications updates from the Department of Infrastructure and the ACMA, and building and standards references (including NCC and relevant ISO guidance). We also used company filings, investor presentations, reputable press coverage, and a paid subscription that supports company financials, news checks, and patent lookups where it clarified technology direction and build intensity. This list is not exhaustive, and other sources were used for collection, validation, and clarification.
Primary Interviews and Surveys
Primary work was used to confirm what gets built, how fast it is delivered, and how pricing shifts from one project wave to the next. Interviews and surveys covered developers, contractors, specialist system providers, and large buyers across the main demand hubs in Australia. We then used the input to adjust assumptions for phasing, fit out depth, and typical bill of quantities by facility type.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 36% | CXOs: 13% |
| Mid tier: 49% | Functional/Unit leaders: 43% |
| Smaller Players: 15% | Managers: 44% |
Market-Sizing & Forecasting
Sizing starts with a top-down build of Australia project demand, where planned capacity additions and expansion cycles are converted into construction value using country level cost and fit-out intensity benchmarks. That model is then cross checked with selective bottom-up approximations, such as sampled campus level project values, contractor revenue exposure checks, and a sanity check of typical cost per MW ranges discussed in interviews.
Key inputs used in the model include the number of live projects by stage (planning, under construction, and announced), the share of work split across electrical and mechanical scope, the typical time lag between approvals and ground break, and construction inflation signals that influence equipment and labor budgets. We also monitor changes in power availability and connection lead times, since these often shift when spending shows up in a given year. For forecasting, scenario analysis was used to reflect different build timing outcomes, and the base case was aligned to the most common outlook shared by industry respondents for campus ramp schedules and procurement lead times. Where a project value or schedule was not disclosed, gaps were filled using ranges anchored to comparable Australian facilities with similar tier intent and technical fit out depth, and then reviewed again during validation.
Data Validation & Update Cycle
Outputs are validated through multiple checks so the final numbers stay tied to real construction activity. We compare the model against independent signals, such as known project pipelines, construction cost movements, and the implied spend per unit of delivered capacity, and then investigate outliers before sign off.
A second analyst review is applied to key assumptions, and follow up calls are triggered when we see timing mismatches, sudden price jumps, or pipeline changes that could move the current year value. The report is refreshed annually, and interim updates are made when major builds are delayed, expanded, or canceled. Before delivery, a final refresh pass is completed so clients receive the latest updated view.
黑料不打烊's Australia Data Center Construction Market Size Measured Against Other Published Estimates
Published market sizes for Australia data center construction often differ because groups do not count the same types of spending, and they also place projects into years differently based on their timing rules. The result is that two credible looking numbers can still be far apart, even when both are talking about Australia.
Some estimates only total announced CAPEX for new campuses and leave out expansion works and deeper fit outs, and some others mix construction investment with data center operating revenues. In the approach used by 黑料不打烊, value is counted only when it is tied to construction and fit out scope inside the facility (including electrical and mechanical infrastructure), and projects are timed based on expected execution windows rather than announcement dates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 11.12 B (2025) | |
| Regional Consultancy A | USD 6.81 B (2024) | Often tracks only publicly announced CAPEX for new build projects and can omit expansion phases and non-public fit out depth, which pushes totals lower. |
| Global Consultancy B | USD 3.10 B (2023) | Uses a partial sample of higher tier facilities and applies generalized cost multipliers, which can understate Australia specific electrical and mechanical spend. |
The spread in the table is mainly explained by what is included and how timing is assigned to each build phase. By keeping the counted scope tied to real construction categories and then pressure testing totals against project stages and cost signals, the final estimate becomes easier to trace and repeat year after year using the same steps.


Key Questions Answered in the Report
What is the projected value of the Australia data center construction market by 2031?
It is expected to reach USD 14.72 billion, expanding at a 4.93% CAGR.
Which tier segment is set to grow the fastest in upcoming years?
Tier 4 builds are forecast to grow at a 5.46% CAGR as hyperscalers seek fault-tolerant uptime.
Why are hyperscale projects concentrating in Sydney and Melbourne?
The two metros offer fiber density, subsea cable routes, and 330 kV transmission access, creating network and power synergies that justify large campuses.
How are renewable-energy incentives influencing site selection?
Federal and state programs lower power costs for facilities co-located with wind or solar farms, encouraging developers to evaluate sites outside traditional metro cores.
What strategic shift are colocation providers making to stay competitive?
Many are adopting powered-shell models that allow hyperscale tenants to install equipment in parallel with construction, trimming delivery times to 12 - 18 months.
How does liquid cooling affect construction budgets?
Liquid-cooling infrastructure can account for up to 50% of mechanical capex in new hyperscale halls but is essential for supporting 100 kW-plus GPU racks efficiently.
Page last updated on:
- Data Center Server Market Global servers demand, split by tier, facility size and facility type.
- Data Center Security Market Security across the global market, covering security type, offering and facility type.
- South Korea Data Center Power Market Power systems demand across South Korea, covering facility size and tier.
- Thailand Data Center Power Market Thailand power systems, split by component, facility type and facility size.
- Japan Data Center Rack Market Racks in Japan, split by facility size and tier.
- South Korea Data Center Rack Market South Korea racks, split by rack size, rack height and rack type.
- Australia Data Center Power Market Power systems in Australia, split by component, facility type and facility size.


