
South Korea Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
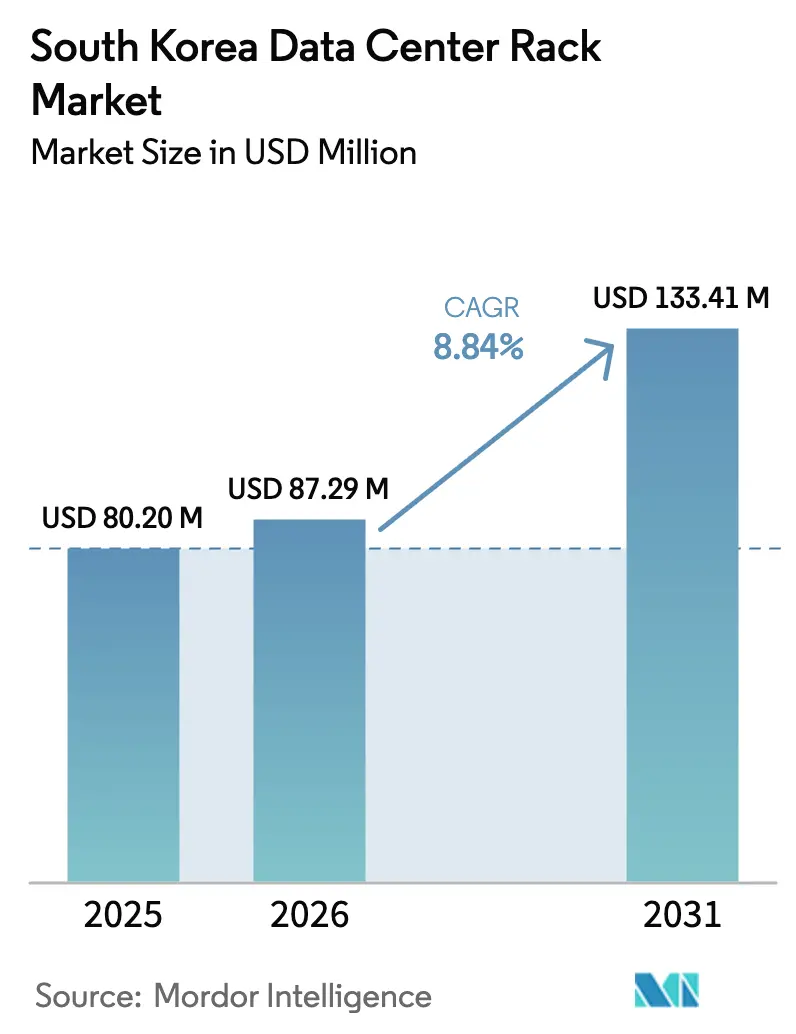
| Base Year Market Size (2025) | USD 80.20 Million |
| Market Size (2026) | USD 87.29 Million |
| Market Size (2031) | USD 133.41 Million |
| Growth Rate (2026 - 2031) | 8.84 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
South Korea Data Center Rack Market Analysis by 黑料不打烊
South Korea Data Center Rack Market size in 2026 is estimated at USD 87.29 million, growing from 2025 value of USD 80.20 million with 2031 projections showing USD 133.41 million, growing at 8.84% CAGR over 2026-2031.
The South Korea data center rack market size stands at USD 62.4 million in 2025 and is projected to advance to USD 128.4 million by 2030, reflecting an 11.24% compound annual growth rate. Investors view the nation as a core Tier 1 location under the AI Diffusion Framework, which grants unrestricted access to advanced AI infrastructure and drives demand for high-density rack solutions csis. Capacity in the Seoul Metropolitan Area alone is forecast to reach 3.2 GW by 2027, a 2.4-fold jump over 2023 and a clear signal that operators need standardized, scalable rack formats.[1]Center for Strategic and International Studies, “Global AI Diffusion Framework,” csis.org Favorable Digital New Deal capital-expenditure incentives, nationwide 5G edge coverage, and strong enterprise adoption of semiconductor and gaming-related AI workloads accelerate rack uptake. Yet headwinds remain from rising industrial power tariffs that range between KRW 97.0 and KRW 234.3 per kWh and from volatility in rack-grade steel prices, both of which compress margins for operators.[2]Korea Electric Power Corporation, “Monthly Electric Tariff Schedule,” kepco.co.kr Competitive intensity is moderate, with Schneider Electric, Rittal, and Delta Electronics battling domestic specialists such as Olabs Technology and Daou Technology for hyperscale, colocation, and emerging edge deployments.
Key Report Takeaways
- By rack size, full racks led with 67.80% of South Korea data center rack market share in 2025, while quarter racks recorded the fastest 14.38% CAGR through 2031.
- By rack height, 42U captured 55.05% share of the South Korea data center rack market size in 2025; 48U is expanding at a 12.55% CAGR to 2031.
- By rack type, cabinet (closed) formats accounted for 71.70% revenue share in 2025; wall-mount racks are projected to grow at a 14.05% CAGR by 2031.
- By material, steel held 73.45% share of the South Korea data center rack market size in 2025, whereas aluminum is advancing at a 13.52% CAGR through 2031.
- By data-center type, colocation facilities commanded 53.90% of South Korea data center rack market share in 2025, yet hyperscale builds are rising at a 14.72% CAGR to the end of the decade.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
South Korea Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale and Colocation Build-outs | +2.8% | National, concentrated in Seoul-Gyeonggi corridor | Medium term (2-4 years) |
| Nationwide 5G–Edge Roll-out | +1.9% | National, with early gains in Seoul, Busan, Incheon | Short term (≤ 2 years) |
| Digital New-Deal CAPEX Incentives | +1.5% | National, government-backed initiatives | Medium term (2-4 years) |
| AI/ML Workload Density Surge | +2.1% | National, semiconductor and gaming hubs | Long term (≥ 4 years) |
| New Submarine Cable Landings | +0.8% | Coastal regions, Busan and Incheon priority | Long term (≥ 4 years) |
| Liquid-cooling-ready rack designs | +1.2% | National, sustainability-focused facilities | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Hyperscale and colocation build-outs
Financial investors back 90% of the planned 1.9 GW of new capacity scheduled for 2024–2027 in Seoul, reshaping rack demand toward units that support liquid cooling up to 132 kW per rack. Large projects such as Koscom’s KRW 1.4 trillion facility in Anyang due in 2026 exemplify the scale and ESG focus of forthcoming campuses. Power-supply constraints imposed by regulators inside the capital region push operators to adopt distributed architectures, boosting demand for edge-ready and modular racks. Bulk procurement lowers per-unit costs yet locks buyers into standardized footprints, sharpening competition among rack vendors that can pre-integrate intelligent power distribution and in-row cooling.
Nationwide 5G–edge roll-out
Since commercial launch in 2019, more than 162,000 5G base stations now blanket the country, creating low-latency use-cases that require compact, ruggedized rack designs for roadside shelters and micro-cells. KT’s demonstration of terabit-speed backhaul between major cities validates the bandwidth assumptions behind ultra-dense edge nodes kdc. Industrial 5G initiatives in smart manufacturing introduce harsh-environment requirements, pushing rack vendors to adopt corrosion-resistant materials and enhanced cable-management. Edge data-center deployments are forecast to grow at 25% annually across Asia-Pacific, with Korea often positioned as the proving ground due to its urban density and early-adopter culture.
Digital New Deal CAPEX incentives
The Digital New Deal program reimburses qualifying data-center investments that meet energy-efficiency thresholds, enabling projects such as KT Cloud’s 10 MW AI cloud site in Gyeongbuk with plans to scale past 320 MW by 2030. Incentives prioritize racks that integrate intelligent PDUs, airflow containment, and sensor-driven thermal management. Procurement guidelines favour suppliers that certify low embodied carbon, which is driving rapid adoption of aluminum and green-steel options. The framework also funds 6G testbeds, stimulating early demand for racks capable of hosting next-generation radios and terabit switching fabrics.
AI/ML workload density surge
Samsung’s USD 55 billion R&D pledge and USD 45 billion infrastructure commitment toward a 7.7-million-wafer mega-cluster intensify the need for AI training capacity. Gaming studios adopting AI-powered graphics generate 26-36% annual rises in server power draw, prompting rack designs that pair liquid cooling plates with front-serviceable manifold blocks. Schneider Electric’s joint reference designs with Nvidia illustrate how 132 kW per rack becomes the new norm in flagship facilities. ESG reporting rules effective 2026 add further pressure to prove measurable gains in power-usage effectiveness, making high-density yet efficient racks a competitive necessity.
Restraints Impact Analysis*
| Restraint | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Electricity Tariffs | -1.8% | National, industrial rate increases | Short term (≤ 2 years) |
| Rack-grade Steel Supply Volatility | -1.2% | National, import dependency | Medium term (2-4 years) |
| Stringent Seismic-Proof Design Codes | -0.9% | National, enhanced safety standards | Long term (≥ 4 years) |
| Limited Availability of RE-100 PPAs | -0.7% | National, renewable energy constraints | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Escalating electricity tariffs
Korea Electric Power Corporation’s debt of KRW 202.5 trillion forces regular tariff hikes, raising industrial rates to as high as KRW 234.3 per kWh. Fossil fuels still produce 58.5% of electricity, leaving operators exposed to LNG volatility. Builders now specify racks with granular branch-circuit monitoring and airflow containment to squeeze every watt from cooling budgets. Examples include Digital Realty’s ICN10 site, which records a PUE of 1.3-1.4 via chilled-water rear-door heat exchangers integrated directly into locked cabinets. The slower progress toward renewable energy targets further tightens margins, making energy-efficient racks a procurement prerequisite.
Rack-grade steel supply volatility
World steel prices remain unstable amid trade tensions, with forecasters warning of 20% spikes in construction inputs under renewed tariffs. Rack builders relying on imported coil must hedge against both currency swings and freight delays. Iron-ore benchmarks are expected to drop in 2025 and 2026, encouraging cautious inventory planning ttiinc. Green-steel offerings commanded 15% of supply in 2023 and carry a premium that many Korean buyers will bear to satisfy ESG mandates. Aluminum and composite frames gain appeal despite higher upfront cost because they insulate buyers from steel volatility while boosting thermal performance.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full rack dominance drives standardization
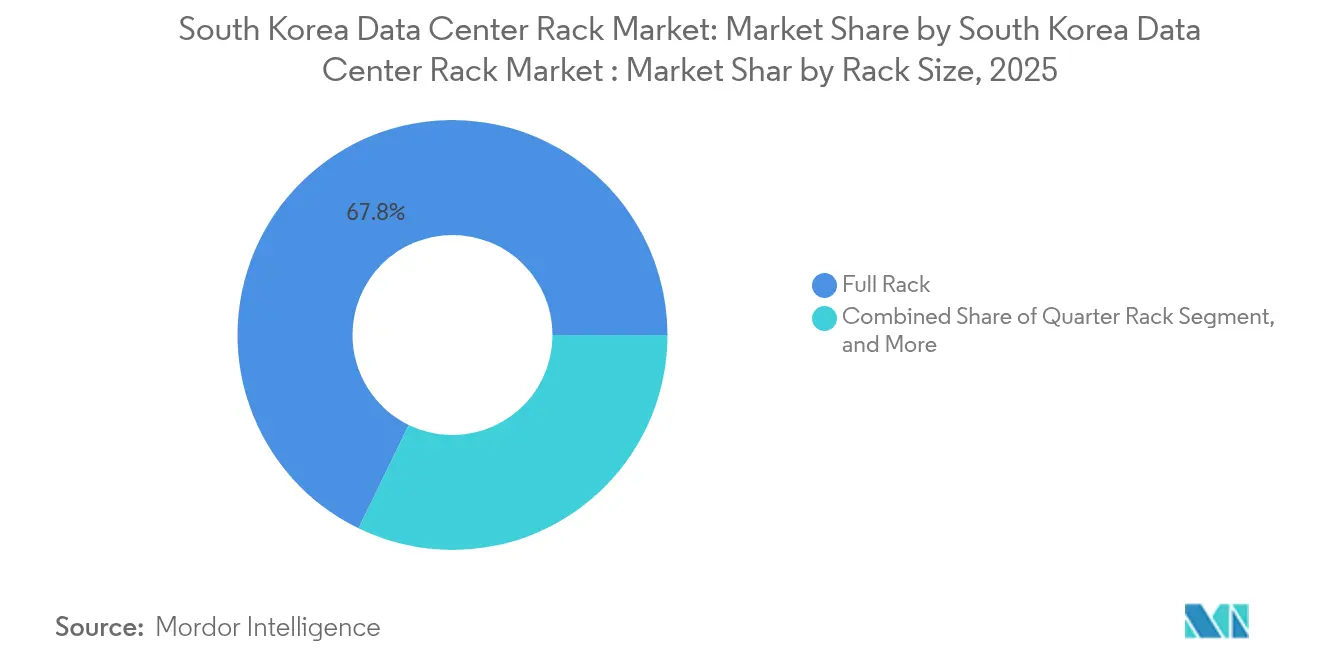
Full racks generated 67.80% of revenue in 2025, a position that underscores hyperscale preferences for uniform, high-density aisles in Seoul’s multistory campuses. This leadership equates to the largest slice of South Korea data center rack market share and reinforces the economies of bulk procurement. Demand accelerates as operators adopt liquid cooling manifolds rated beyond 100 kW. In contrast, quarter racks log the fastest 14.38% CAGR as edge colocation and enterprise branches value modular capacity expansions. Retail colocation suites and distributed telco huts often default to two quarter racks instead of one full unit to optimize power feeds. The South Korea data center rack market continues to split along these form factors, yet vendors increasingly design chassis that let customers bolt quarter racks into unified frames when density demands shift.
Edge growth is particularly evident in Busan and Incheon, where submarine cable landings necessitate micro-data centers within port facilities. Operators there favor quarter racks fitted with side-mounted heat pipes because floor space commands a premium. Meanwhile, bespoke research labs in Gyeonggi retain specialized half-rack footprints that allow rapid hardware swaps during chip-validation cycles. As Korea regulates power additions inside Seoul, many landlords retrofit existing facilities with shorter rows of quarter and half racks to meet electrical quotas without structural upgrades. Such trends embed flexibility into the roadmap of the South Korea data center rack market.


By Rack Height: 42U standard meets emerging 48U demand
The 42U format held 55.05% revenue in 2025, reflecting decades of entrenched compatibility with enterprise gear. Many colocation providers continue to bundle 42U cabinets with fixed cross-connect packages, securing predictable lead times. Yet AI training clusters now require extra vertical space for rear-door heat exchangers and GPU sleds, propelling the 48U category at a 12.55% CAGR. That uplift means the 48U slice of South Korea data center rack market size could challenge 42U dominance by the decade’s end as operators retrofit white space for taller doors and higher cable ducts. Facilities with raised floors taller than one meter are the earliest adopters because they already budget for heavier loads.
Higher racks also offset power-delivery constraints by allowing more SMR batteries and busbars per cabinet, spreading heat across a longer chimney. Vendors therefore reinforce frames with seismic bracing to pass Korea’s upgraded structural codes, which add 50% extra load factors for facilities over 1,000 ㎡. Liquid cooling innovators integrate sliding manifolds that remain serviceable even at 48U heights, ensuring field engineers can replace cold plates without mechanical lifts. These innovations keep the South Korea data center rack market from fragmenting by height, instead encouraging interoperability between 42U and 48U rails and blanking panels.
By Rack Type: Cabinet racks lead security-focused market
Cabinet enclosures captured 71.70% revenue in 2025 because Korean corporate policy prioritizes physical security and acoustic containment in densely populated buildings. Standard cabinets simplify airflow containment solutions such as hot-aisle chimneys mandated by many colocation SLAs. Wall-mount units, however, accelerate at 14.05% CAGR due to rapid edge deployment in retail and transportation hubs. Their shallow depth suits shallow service corridors, while lockable front doors deter vandalism in publicly accessible areas. Open-frame racks persist in test labs and staging zones where technicians value unrestricted access, yet they seldom make it into production halls.
Cabinets increasingly ship with factory-installed high-density busbars and DC rectifiers, enabling brownfield halls to accommodate up to 30 kW without rewiring. Wall-mount designs adopt swing-out hinges for quick fiber management when technicians shoulder cramped equipment closets. Korean telcos specify wall-mounts for 5G edge pods located on building rooftops because enclosed sides resist weather ingress. Those patterns drive steady diversification inside the South Korea data center rack market, though cabinets remain the default solution wherever building codes and landlord insurance clauses demand locked enclosures.
By Data Center Type: Colocation stability versus hyperscale growth
Colocation operators delivered 53.90% of rack demand in 2025 and continue to offer predictable baseline volume. These providers bundle rack, power, and interconnection on multiyear contracts that attract domestic content-delivery, fintech, and gaming tenants. Yet hyperscale investment rises at a 14.72% CAGR as cloud majors and AI start-ups secure entire build-to-suit halls. Hyperscalers prefer pre-certified reference designs, allowing vendors to lock in thousands of identical cabinets before slab pour. Such volume tilts the South Korea data center rack market toward vendors with capital to hold inventory and absorb foreign-exchange swings.
Enterprises constrained by capital budgets still opt for colocation suites, preserving a diversified buyer base. Meanwhile, government decentralization policies encourage regional municipalities to invite midsize colocation builds, which indirectly stimulate local rack assembly plants. Edge data centers attached to 5G macro towers represent a smaller but quickly growing customer tier, typically ordering wall-mount or quarter-rack formats to fit shipping-container envelopes. Each data-center archetype therefore injects varied but complementary demand streams that collectively stabilize revenue for manufacturers.

By Material: Steel dominance faces aluminum challenge
Steel frames remain the bedrock of the South Korea data center rack market, accounting for 73.45% revenue in 2025 thanks to their load-bearing strength and competitive cost. Domestic fabricators source welded sheet and angle profiles from Pohang and Gwangyang mills, keeping lead times short. However, aluminum posts a 13.52% CAGR as buyers value its 205 W m·K thermal conductivity which dissipates heat faster in high-density AI enclosures. Aluminum also reduces per-cabinet weight by up to 40%, easing installation on raised floors with seismic bracing.
Price volatility in steel imports, amplified by trade frictions, nudges some buyers toward aluminum despite its higher sticker price. Green-steel premiums further narrow the cost gap, making lightweight alloys financially viable under ESG procurement mandates. Composite racks that sandwich carbon fiber between aluminum skins appear in semiconductor research labs where electromagnetic cleanliness matters. These shifts diversify the procurement palette but steel’s entrenched supply chains and lower material costs ensure it retains the majority share for the foreseeable future.
Geography Analysis
Seoul and its satellite cities command roughly 60% of operational white space and 70% of data-center power draw, making the capital region the gravitational center of the South Korea data center rack market. Planned additions could lift installed capacity to 3.2 GW by 2027, more than doubling the 2023 baseline. The concentration of campuses allows operators to negotiate bulk rack discounts and rely on established logistics lanes from Incheon port. Yet the government’s moratorium on new heavy-load power permits inside Seoul imposes a hard ceiling, compelling builders to maximize compute per kW through taller and denser cabinets. Seismic building codes force 50% higher structural allowances on white space over 1,000 m, prompting rack makers to reinforce frames and anchor kits for multi-story sites.
Coastal hubs such as Busan and Incheon capitalize on submarine cable landings that shorten round-trip latency to Japan, Singapore, and the United States. Edge-oriented micro-facilities in these ports specify wall-mount or quarter-rack solutions that fit within converted warehouse footprints. Nationwide 5G coverage funnels traffic to these coastal nodes first, making them early beneficiaries of AI-driven content distribution. Aluminum racks gain traction here because lower weight expedites crane lifts during rapid build-outs on pier infrastructure.
Interior provinces like Gyeonggi and Gyeongbuk are emerging beneficiaries of decentralization incentives embedded in the Digital New Deal. KT Cloud’s 10 MW anchor facility in Gyeongbuk, expandable to 320 MW, signals a pivot toward cheaper land and abundant renewable-energy potential. Samsung’s semiconductor mega-cluster in Gyeonggi injects localized demand for AI training labs that favor 48U high-density racks with liquid cooling manifolds. These inland builds diversify revenue streams for rack assemblers and temper geographic concentration risk within the South Korea data center rack market.
Regulatory Landscape
South Korea is tightening the policy framework around AI data center build-outs in ways that affect rack specification, procurement timelines, and regional siting decisions. In June 2026, the Special Act on the Promotion of the Artificial Intelligence Data Center Industry was promulgated, with effectiveness set for February 2027, and it introduces a Ministry of Science and ICT (MSIT) led one-stop permitting process along with a timeout mechanism for approvals. The same framework includes measures such as exemptions from power-grid impact assessments for new or expanded AI data centers located outside the capital region, and it also references tailored building-standard relaxations intended for server-centric facilities, which can change mechanical and spatial assumptions that cascade into cabinet layout, anchoring, and aisle design.
Implementation details are being translated into subordinate statutes, with MSIT forming a research group in June 2026 to draft definitions and the scope of permit exemptions. For rack vendors and integrators, this shifts compliance emphasis toward documenting energy-efficiency features (for example, intelligent power monitoring and airflow containment) and proving structural suitability under stringent seismic-proof design requirements already shaping cabinet reinforcement and anchoring kits in Korean facilities. The interplay between accelerated approvals for non-capital regions and constraints in the Seoul metropolitan area supports greater dispersion of data center projects, which in turn raises demand for standardized rack formats that can be deployed quickly across multiple provinces while still meeting local inspection and safety expectations.
Value Chain Analysis
The South Korea data center rack value chain spans raw materials and fabrication through integrated deployment and facility operations. Upstream inputs include steel and aluminum for frames and panels, along with electronic subcomponents that increasingly sit inside modern cabinets (sensors, metering, and control boards). Domestic industrial and electronics ecosystems support adjacent needs: Samsung Electro-Mechanics supplies MLCCs and substrates used across power and control systems, while Samsung SDI and LG Energy Solution participate in the broader energy-storage battery supply chain that is often specified alongside high-density rack rows for ride-through and resiliency.
Midstream, racks and containerized enclosure systems are supplied and assembled by companies such as Seojin System, while global OEMs (for example, Schneider Electric, Rittal, and Delta Electronics) compete through bundled offers that combine cabinets with power distribution, cooling integration, and monitoring. Downstream delivery is driven by EPCs and builders such as Samsung C&T, Hyundai E&C, DL E&C, and HanmiGlobal that translate operator requirements into purchasable bill-of-materials, often favoring pre-certified, repeatable rack footprints for hyperscale and colocation halls. The ecosystem is also shaped by partnerships that tie rack-adjacent infrastructure to specific projects, including Schneider Electric working with SK Telecom on AI data center infrastructure (covering switchgear, UPS, and ETAP digital twin software) and with HD Korea Shipbuilding & Offshore Engineering on offshore data center technology, both of which influence what rack power and cooling interfaces become standard in new deployments.
Competitive Landscape
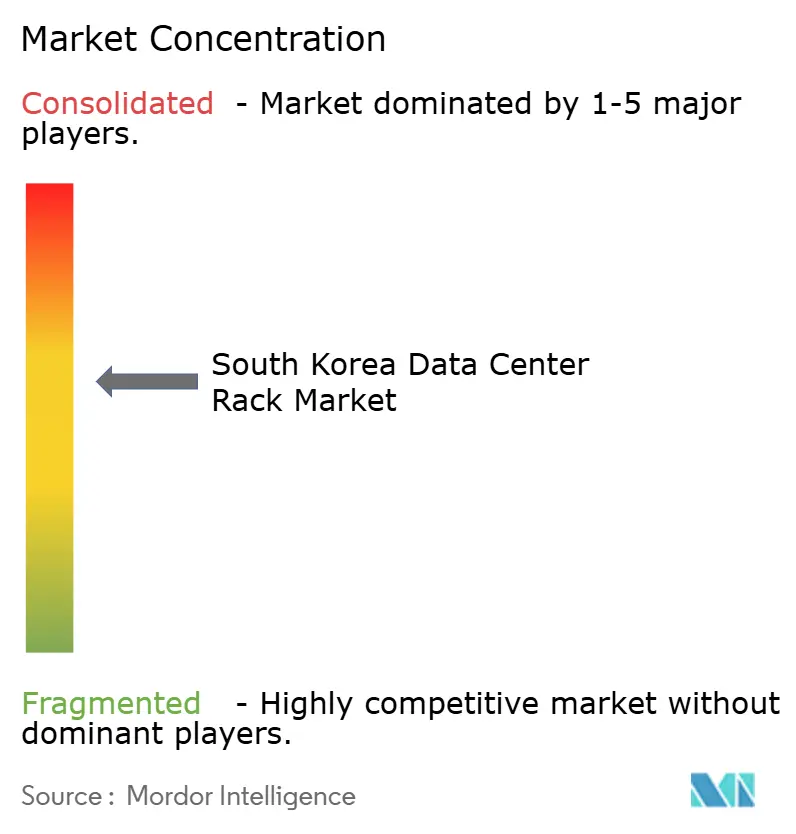
International conglomerates and agile domestic specialists share a moderately concentrated playing field. Schneider Electric deploys global R&D resources to pre-engineer cabinet ecosystems that integrate 132 kW liquid cooling coils, capturing early mindshare among hyperscalers. Rittal tailors its VX series with seismic-grade frames suited to Korean building codes, while Delta Electronics integrates high-efficiency rectifiers that align with tariff-driven energy-savings targets. These brands bundle racks with power and cooling, leveraging economies of scope.
Local manufacturers such as Olabs Technology, Dobe Computing, and Daou Technology exploit short order-to-delivery cycles and fluent understanding of regulatory paperwork. Their proximity to Seoul logistics corridors allows rapid customization, for instance adding Korean-language smart-PDU firmware ahead of factory site acceptance tests. Domestic firms also adapt more quickly to evolving ESG disclosure formats required by the Financial Supervisory Service, offering green-steel or recycled-aluminum options certified by local labs.
Strategic partnerships dominate recent announcements. Schneider Electric and Nvidia produce turnkey rack references that embed AI network fabrics, while Vertiv’s 360AI platform offers modular cooling skids that slot directly into existing aisles datacenterfrontier.[3]Data Center Frontier, “Vertiv 360AI Platform Debuts,” datacenterfrontier.com NTT DATA pairs private-5G service bundles with Schneider’s EcoStruxure modular data centers to capture edge business. Over the next five years, suppliers able to certify racks for liquid cooling, seismic resilience, and energy-usage transparency are expected to gain share inside the South Korea data center rack market.
South Korea Data Center Rack Industry Leaders
Schneider Electric
Rittal
Delta Electronics
Eaton
Huawei
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A central whitespace for rack suppliers is the emerging pipeline of large AI data center projects being promoted outside the Seoul metropolitan area, where permitting and grid-connection treatment is being reshaped. Publicly communicated national targets reference 8.4 GW by 2029 and 18.4 GW by 2035, with Phase 1 projects tied to named sponsors and locations such as SK in Ulsan (5 GW), GS in Donghae (2.4 GW), and Naver in Sejong (1 GW), alongside an articulated private investment ambition of KRW 550 trillion. For the rack market, this type of regional mega-program expands demand for repeatable, high-density cabinet families (including 48U formats) and for configurations that are ready for liquid cooling and granular power visibility, since AI halls tend to lock in rack footprints early and buy at scale.
New form factors also open differentiated demand beyond conventional land-based campuses. The floating data center concept being developed through collaboration between HD Korea Shipbuilding & Offshore Engineering and Schneider Electric highlights an alternative deployment model that can change enclosure requirements around corrosion resistance, vibration and motion tolerance, and compact modular integration of power and cooling at the rack row level. In parallel, MSIT has outlined a plan to localize and export AI infrastructure components starting in 2027, spanning power equipment and cooling systems; this provides a pathway for rack makers and integrators to build local supply chains for rack-level power distribution and monitoring accessories, reducing lead times for colocation and hyperscale customers that are standardizing their cabinet and accessory SKUs across multiple regions.
Recent Industry Developments
- July 2026: Announced a 140 trillion won investment plan to develop AI data centers in the Yeongnam region, with a 100-megawatt hyperscale unit in Ulsan scheduled for operation by Q4 2027. The investment signals a strategic shift to regional hub development and expands demand for high-density rack installations capable of supporting large AI workloads.
- July 2026: Signed a memorandum of understanding to jointly develop floating data center infrastructure technology. The collaboration opens a path to floating data centers that can reduce land and cooling constraints while enabling scalable rack deployments along coastlines.
- February 2026: ABB selected for switchgear supply for its AI data center in Ulsan. The contract secures essential electrical distribution for a greenfield project and underpins growth of the local rack ecosystem.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market is defined as revenue generated from data center rack cabinets and frames sold and installed in South Korea across new builds, expansions, and replacement cycles, covering standard sizes and heights used in commercial and enterprise data centers.
Scope exclusions: We exclude servers, PDUs, cooling systems, general IT services, and broader data center construction spending that is not directly tied to rack hardware revenue.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundary, build the demand context, and avoid overcounting adjacent infrastructure spend. We typically anchor the environment using public sources such as Statistics Korea (KOSIS), the Ministry of Science and ICT releases, Korea Customs Service trade statistics, and Korea Communications Commission publications related to network and digital policy.
To translate demand into rack hardware needs, we also refer to data center focused public disclosures and standards references, such as Uptime Institute content, ASHRAE guidance for thermal ranges, and peer reviewed articles on rack density and airflow practices. On the supply side, we review company filings and investor materials where available, along with reputable press coverage of new capacity announcements and build timelines. We also use select paid subscriptions for company financials, patent lookups, and shipment level trade signals where it helps cross-check directionally. The sources listed above are illustrative, and we also relied on other public documents and datasets to collect, validate, and clarify the inputs.
Primary Interviews and Surveys
Primary work was used to pressure test assumptions that desk sources do not address cleanly, particularly the installed base refresh cadence, typical rack density shifts, and realized pricing by rack type. We spoke with rack suppliers, system integrators, and data center operators across South Korea to close gaps around demand timing, currency effects, and procurement practices before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 16% |
| Mid tier: 48% | Functional/Unit leaders: 25% |
| Smaller Players: 19% | Managers: 59% |
Market-Sizing & Forecasting
Sizing starts from a top-down reconstruction of South Korea rack demand by linking data center build activity and fit-out intensity to rackable white space, then translating that into annual rack shipments and replacement needs. Once the demand pool is formed, we apply price bands by rack type and height so revenue is not overstated when open-frame or wall-mount units are used for specific deployments.
The model is then corroborated with selective bottom-up approximations, such as supplier revenue splits by product line, channel checks on typical order sizes, and sampled ASP times volume checks for common rack configurations. Key inputs that move the numbers include planned data center capacity additions and commissioning timelines, average racks per MW (adjusted for density trends), the share of cabinet versus open-frame builds, steel-driven cost movement that affects pricing, and the replacement cycle for racks in older rooms.
For forecasting, scenario analysis is used because new facility launches can shift by a few quarters due to permitting, power availability, and construction readiness. Variables like pipeline capacity, rack density direction, and pricing progression are stress-tested with interview feedback, and where company-level details are missing, conservative interpolation is applied and rechecked against aggregate import and production signals.
Data Validation & Update Cycle
Outputs are validated through multiple checks so the final totals stay aligned with real-world deployment behavior. We compare modeled rack volumes and revenue against independent signals such as data center pipeline news, trade flow direction, and observed price movement, then investigate any outliers before sign-off.
If a variance is large, follow-up calls are triggered to confirm whether the change is coming from scope (for example, more wall-mount demand), timing (delayed fit-outs), or pricing (FX and material swings). Reports are refreshed annually, with interim updates when major build announcements, policy changes, or sudden pricing shifts materially affect the outlook. Before delivery, an analyst performs a fresh pass so clients receive the latest updated view.
黑料不打烊's South Korea Data Center Rack Market Size Compared With Other Published Estimates
Published market values for South Korea data center racks can look different because researchers may time the currency conversion differently, apply a broad ASP curve across all rack types, or assume a faster replacement cycle than what is observed in real procurement. Differences also appear when some figures blend rack cabinets with nearby fit-out items, which can make the total look larger even if rack unit counts are similar.
In our refresh-led workflow, late-year price checks, KRW to USD timing, and re-validation of cabinet versus open-frame mix are revisited before the number is finalized. This is why the final 2025 value of 黑料不打烊 can land away from estimates that rely on older price points or a fixed mix assumption.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 80.20 M (2025) | |
| Industry Association A | USD 74.60 M (2025) | Uses a unit-based count that emphasizes planned rack additions, applies a single average price across rack types, and typically converts KRW to USD using annual averages that can lag spot movements. |
| Regional Consultancy B | USD 92.10 M (2025) | Often extends scope into broader rack-related fit-out items and assumes higher cabinet adoption in new halls, and the model appears to use a faster ASP escalation without matching it to material and order-cycle checks. |
The spread in the table is mainly explained by how narrowly racks are defined, how pricing is built by configuration, and how current the FX and procurement inputs are when the estimate is locked. By keeping the calculation traceable to rack demand drivers, price bands, and repeatable validation steps, the final output stays practical for planning and can be updated cleanly when the build pipeline or pricing conditions change.


Key Questions Answered in the Report
What is the current size of the South Korea data center rack market?
The market is valued at USD 87.29 million in 2026 and is set to reach USD 133.41 million by 2031 at an 8.84% CAGR.
Which rack format holds the largest share?
Full racks dominate with a 67.80% share in 2025 owing to hyperscale and colocation standardization.
Why are 48U racks gaining popularity?
AI and high-performance workloads need extra space for liquid-cooling hardware and power distribution, driving a 12.55% CAGR for 48U cabinets.
How are rising electricity tariffs affecting rack design?
Higher power costs push operators toward cabinets with intelligent PDUs, airflow containment, and materials that dissipate heat more efficiently.
Page last updated on:
- Data Center Power Market Global power systems demand, split by component, tier and facility size.
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- South Korea Data Center Construction Market Construction in South Korea, split by tier, facility type and infrastructure.
- South Korea Data Center Storage Market South Korea storage, split by storage technology, storage type and facility type.
- South Korea Data Center Server Market Servers demand across South Korea, covering data-center tier, form factor and application / workload.
- Japan Data Center Storage Market Japan's storage, split by facility size and tier.
- Germany Data Center Construction Market Germany's construction, split by tier, facility type and infrastructure.
- Spain Data Center Storage Market Storage in Spain, split by facility size and tier.
- South Korea Hyperscale Data Center Market Hyperscale sites in South Korea, split by facility type, component and tier.
- South America Data Center Construction Market South America construction, split by tier.



