
Germany Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 7.28 Billion |
| Market Size (2026) | USD 7.91 Billion |
| Market Size (2031) | USD 11.94 Billion |
| Growth Rate (2026 - 2031) | 8.62 % |
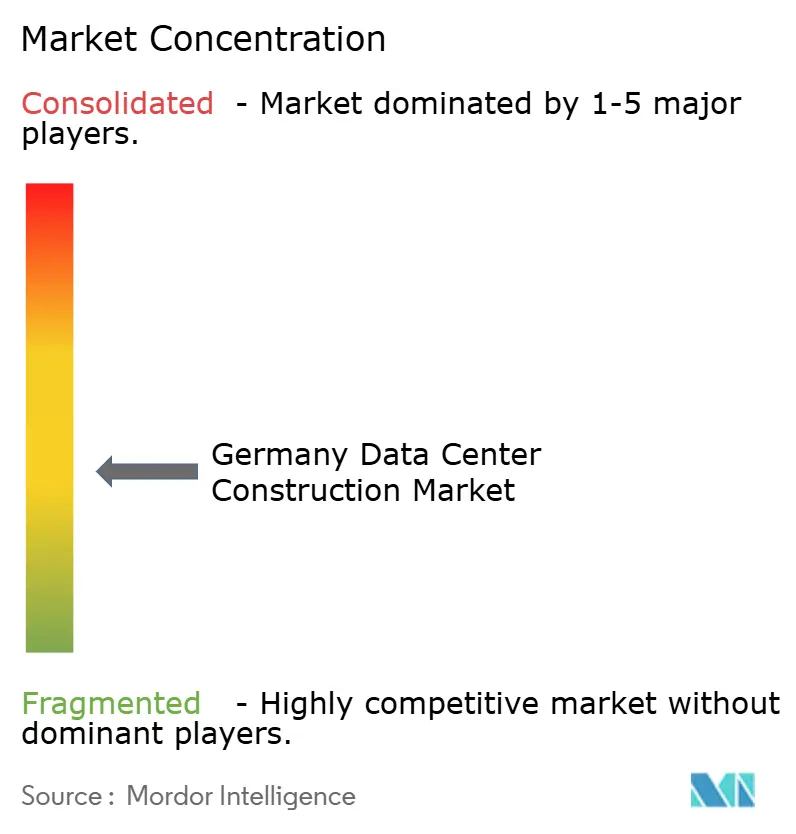
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Germany Data Center Construction Market Analysis by 黑料不打烊
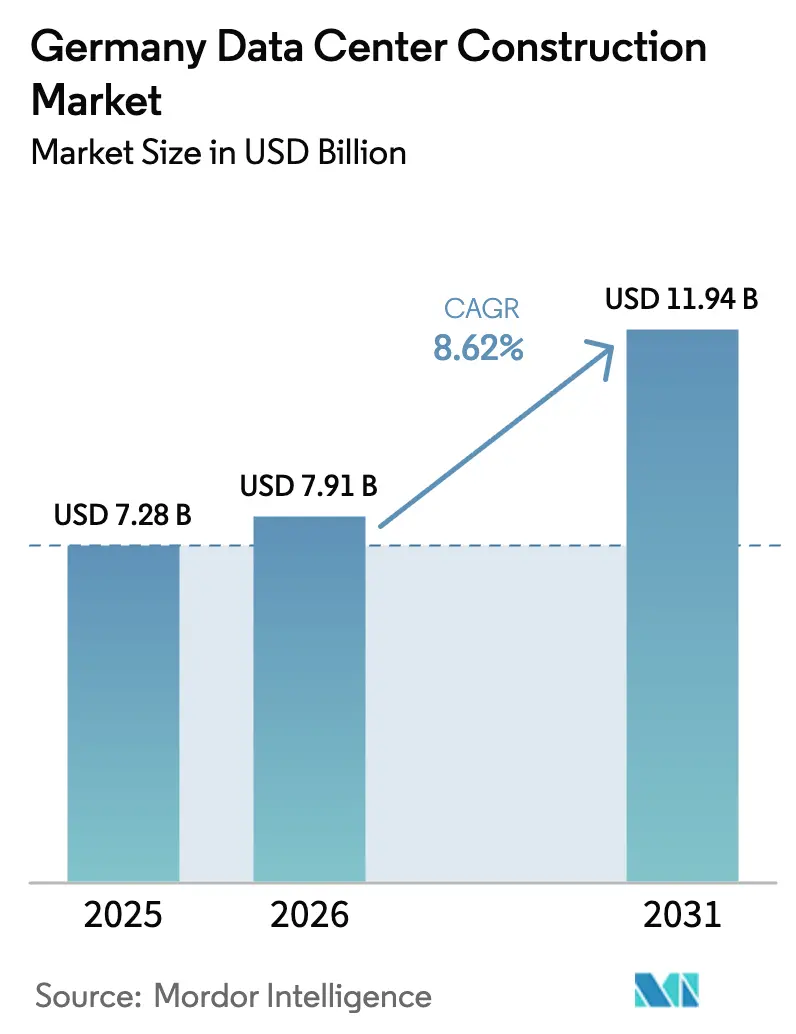
The Germany data center construction market size was valued at USD 7.28 billion in 2025 and estimated to grow from USD 7.91 billion in 2026 to reach USD 11.94 billion by 2031, at a CAGR of 8.62% during the forecast period (2026-2031). Frankfurt anchors most hyperscale projects, yet regulatory pressure to improve energy efficiency and adopt ≥50% renewable power is driving advanced design and retrofit spending. Rising AI rack densities and liquid-cooling adoption are reshaping electrical and mechanical specifications, favoring builders that can standardize high-density modules. Material cost inflation—steel up 40.4% and glass up 49.3% since 2022—adds to project risk but has not slowed multi-billion-euro commitments from AWS, Microsoft, and other hyperscalers. Grid-capacity reallocation policies are opening Berlin, Munich, and Hamburg to large-scale builds as Frankfurt’s 110 kV network reaches saturation
Key Report Takeaways
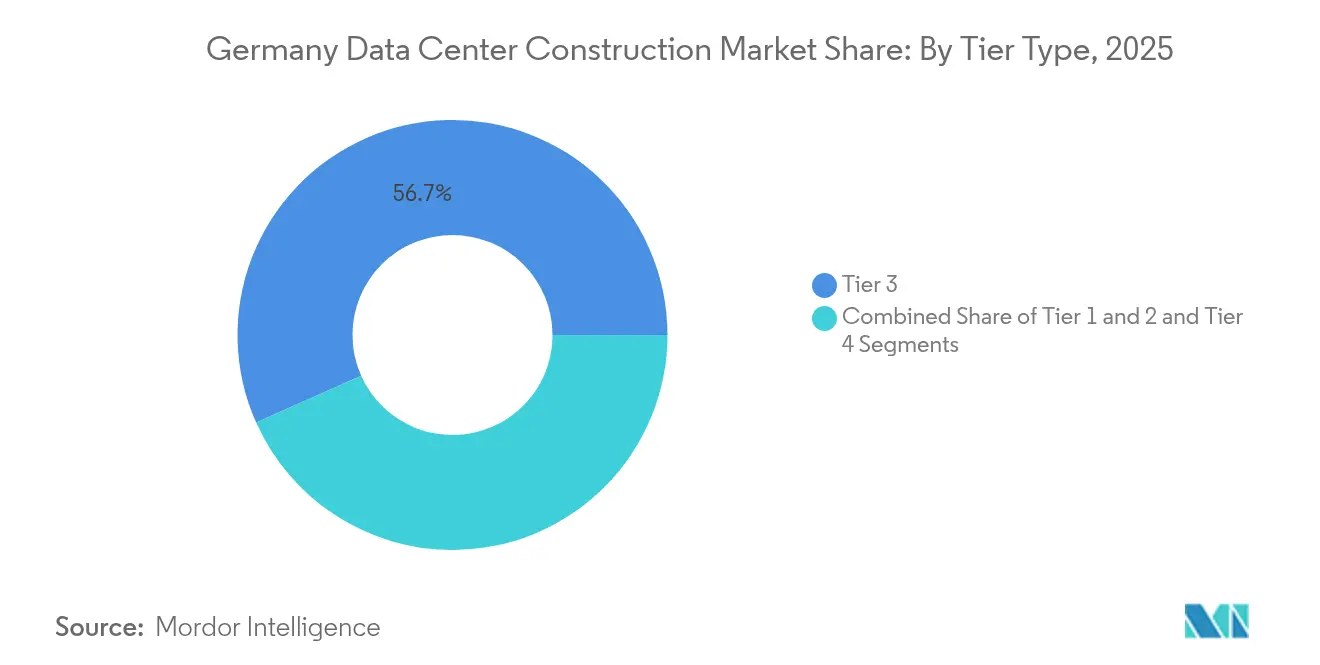
- By tier type, Tier 3 facilities accounted for 56.68% of the Germany data center construction market share in 2025, while Tier 4 projects are advancing at an 10.74% CAGR through 2031 U.S. Department of Commerce.
- By data-center type, colocation sites held 48.65% revenue in 2025; self-build hyperscale campuses are growing fastest at 11.87% CAGR to 2031 Data Center Dynamics.
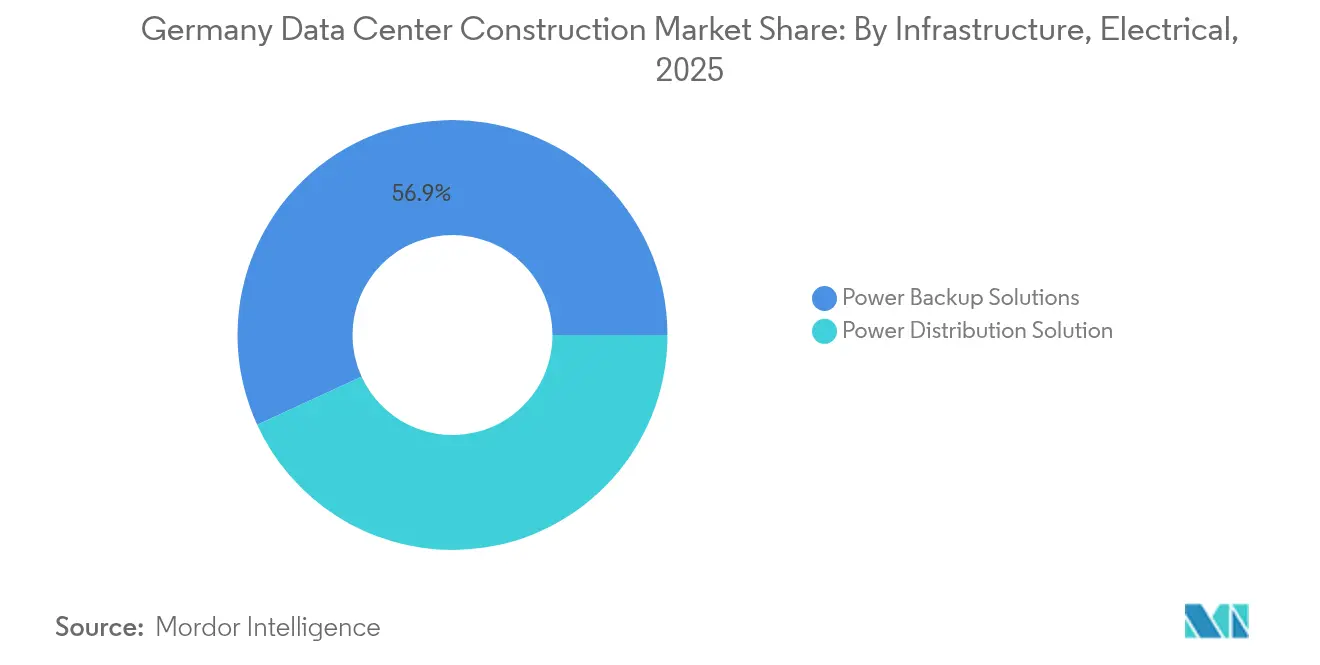
- By electrical infrastructure, power-backup systems commanded 56.85% share in 2025, while power-distribution solutions are forecast to lead growth at 12.71% CAGR Siemens.
- By mechanical infrastructure, cooling systems held 46.92% of the Germany data center construction market size in 2025, yet servers and storage integration is expanding at 12.22% CAGR Supermicro.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Germany Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale cloud capex boom fuels multi-GW build-outs | 2.8% | Frankfurt, Berlin, Munich | Medium term (2-4 years) |
| AI/ML rack-density shift (>80 kW/rack) accelerates liquid-cooling projects | 2.1% | National, concentrated in Frankfurt | Short term (≤ 2 years) |
| Mandatory 50% renewable-power requirement under EnEfG drives retrofit spending | 1.4% | National | Medium term (2-4 years) |
| Grid-capacity re-allocation scheme opens secondary metros | 1.2% | Berlin, Munich, Hamburg, Düsseldorf | Long term (≥ 4 years) |
| Waste-heat purchase incentives (up to EUR 180/MWh) spur heat-re-use infrastructure | 0.8% | Frankfurt, Berlin, Munich | Long term (≥ 4 years) |
| On-site H? fuel-cell pilots cut diesel-backup OPEX in Tier 3/4 builds | 0.4% | National, early adoption in Frankfurt | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Hyperscale Cloud Capex Boom Fuels Multi-GW Build-outs
Hyperscale operators are redefining the Germany data center construction market through record capital deployment. AWS committed USD 9.44 billion to multiple Frankfurt-area campuses designed for gigawatt-scale loads and 18-24 month delivery timetables,[1]AWS Press Office — "AWS to Invest USD 9.44 Billion in Frankfurt Cloud Region," DataCenterDynamicscatalyzing demand for prefabricated modules and concurrent permitting. Microsoft followed with a EUR 3.2 billion (USD 3.6 billion) expansion that doubles national AI capacity and specifies racks above 40 kW. Multi-building scheduling favors firms that can coordinate parallel crews and logistics across dispersed plots, while smaller regional contractors risk displacement. Accelerated timelines intensify competition for skilled labor and specialized switchgear, deepening reliance on global supply chains. The Germany data center construction market therefore rewards builders that scale quickly without compromising PUE performance.
AI/ML Rack-Density Shift Accelerates Liquid-Cooling Projects
AI inference and training clusters now exceed 80 kW per rack, making air cooling impractical and triggering a wave of liquid-cooling retrofits and green-field deployments. Google’s open 1 MW CDU blueprint illustrates a standardized high-voltage, liquid-ready architecture adopted by hyperscalers. Early movers such as GlobalConnect report 90% cuts in cooling energy after submersion projects, setting new efficiency baselines. Supermicro shipped more than 2,000 liquid-cooled racks between 2024 and 2025,[2]Supermicro — "Supermicro shipped more than 2,000 liquid-cooled racks between 2024 and 2025," supermicro.com proving fast hardware uptake and locking in new construction norms. Construction firms now integrate coolant distribution units and heat-recovery loops at slab stage, compressing later trades and altering contractual scopes within the Germany data center construction market.
Mandatory 50% Renewable-Power Requirement Under EnEfG Drives Retrofit Spending
Germany’s 2024 Energy Efficiency Act mandates 50% renewable electricity for data centers immediately and 100% by 2027,[3]Markus Schneider — "Germany Energy Efficiency Act Explained," White & Case LLP sparking a parallel retrofit segment Dentons. Maincubes signed its first solar PPA for Frankfurt operations, coupling data halls with dedicated photovoltaic arrays. Waste-heat reuse targets of 10% by 2026 and 20% by 2028 prompt district-heating tie-ins like TU Dresden’s EUR 1.6 million energy-reuse plant supplying 3,700 homes. Contractors versed in renewable interconnection and heat-export piping win higher-margin scopes. Financing terms increasingly link interest spreads to on-site green generation, embedding sustainability metrics into construction lending. As a result, the Germany data center construction market is seeing ESG compliance transform from a differentiator to entry requirement.
Grid-Capacity Re-allocation Scheme Opens Secondary Metros
The Federal Network Agency shifted from a first-come queue to merit-based allocation, redirecting 110 kV transmission slots toward under-utilized metros. Berlin’s Urban Tech Republic, redeveloping the former Tegel Airport, offers land and grid access for up to 1,000 tech firms, attracting new data center builds. Maincubes already secured a Nauen parcel for its second Berlin campus as operators hedge against Frankfurt constraints. Munich and Hamburg also market available capacity paired with district-heat reuse incentives, diversifying geographic risk. Developers targeting latency to Bavaria’s industrial base and Hamburg’s logistics corridor broaden the Germany data center construction market beyond its traditional Rhine-Main core.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Scarce 110 kV grid connections around Frankfurt delays >200 MW pipeline | -1.8% | Frankfurt metropolitan region | Short term (≤ 2 years) |
| Cap-ex inflation on switchgear and generators (+32% since 2022) | -1.2% | National | Short term (≤ 2 years) |
| Tightened PUE ≤1.2 (new DCs) under EnEfG raises design costs | -0.9% | National | Medium term (2-4 years) |
| Berlin land-use moratorium near TXL airport restricts hyperscale plots | -0.6% | Berlin metropolitan region | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Scarce 110 kV Grid Connections Around Frankfurt Delay Pipeline Projects
Frankfurt’s 110 kV backbone operates near maximum load, extending new interconnection lead times to as long as eight years, well beyond typical hyperscale planning cycles. Digital Realty’s cluster of more than 20 local facilities underlines the demand legacy and the resulting saturation. In response, developers fragment projects below 100 MW or pivot to Brandenburg, Berlin, and North Rhine-Westphalia. Construction scheduling becomes contingent on utility-approved reinforcement works, complicating EPC contracts. The Germany data center construction market therefore prices grid-access scarcity into land valuations and PPA premiums.
Cap-ex Inflation on Switchgear and Generators Raises Construction Costs
Producer-price indices show switchgear and diesel-generator packages rising 32% above general building inflation since 2022, eroding project contingencies. Medium-voltage switchgear demand is projected to climb at 16% CAGR due to hyperscale growth, signaling sustained cost pressure. Siemens notes that a single hyperscale campus can require 1 GW annually, equivalent to the power draw of 750,000 homes, magnifying exposure to price swings. Builders increasingly adopt modular electrics to lock in prices early, but long lead items still extend procurement windows. Rising electrical budgets push clients toward design-build contracts that re-allocate risk inside the Germany data center construction market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Tier 4 Drives Premium Construction
Tier 3 captured 56.68% of the Germany data center construction market share in 2025, confirming its balance of reliability and cost efficiency. Tier 4, however, is expanding at 10.74% CAGR, the swiftest pace within the Germany data center construction market size during 2026-2031. Hyperscale and financial-services buyers justify premium redundancy to achieve 99.995% uptime. Construction mandates include dual active power paths, concurrently maintainable cooling, and fault-tolerant fiber routes. Builders specializing in Tier 4 designs can command higher margins but must manage longer testing cycles and regulatory audits.
Tier 1 and Tier 2 builds now attract limited demand as enterprises shift to cloud and require higher availability. Consolidation around Tier 3 and Tier 4 accelerates a move from enterprise hosting to AI-ready hyperscale estates. Microsoft’s EUR 3.2 billion expansion specifies Tier 4 halls designed for continuous machine-learning workloads. Firms with deep experience in concurrent-maintenance architectures will see sustained pipelines, while contractors focused on lower tiers may need to reskill. The Germany data center construction industry therefore rotates toward premium tiers as table-stake reliability rises.


By Data Center Type: Hyperscalers Reshape Construction
Colocation accounted for 48.65% of 2025 revenue, yet self-build hyperscale projects are forecast to rise 11.87% annually, adding momentum to the Germany data center construction market size trajectory. Sovereign-cloud strategies drive hyperscalers to own facilities outright, bypassing neutral hosts. This ownership model scales multi-gigawatt campuses and demands fast-track permitting, high-voltage substations, and campus-wide liquid cooling.
Edge and enterprise builds remain smaller but strategic, supporting latency-sensitive workloads and regulatory data residency. Amazon’s EUR 7.8 billion Brandenburg sovereign-cloud program underscores how hyperscalers combine national compliance with self-managed infrastructure. For contractors, hyperscale self-builds concentrate scope into fewer, larger clients with stringent vendor audits. Colocation providers counter with district-heat reuse and energy-as-a-service models to stay competitive inside the Germany data center construction market.
By Electrical Infrastructure: Power Distribution Innovation
Power-backup solutions led 2025 electrical spend at 56.85%, reflecting UPS and generator dominance. Yet power-distribution systems will see 12.71% CAGR through 2031, the quickest ascent within the Germany data center construction market. AI clusters drive a shift to higher-voltage busways and direct-current architectures that reduce conversion loss and cable bulk. Builders must integrate bus-ducts capable of 1 MW per rack while meeting EnEfG PUE targets.
Hydrogen fuel-cell pilots by Microsoft (3 MW) and NorthC introduce diesel-free backup paths and new mechanical-electrical interfaces. Prefabricated medium-voltage skids now ship factory-tested, cutting on-site work by weeks. Electrical rooms become smaller yet denser, shifting fire-suppression strategies and access-clearance rules. These innovations raise the technical entry bar for newcomers in the Germany data center construction market.
By Mechanical Infrastructure: Cooling System Evolution
Cooling captured 46.92% of 2025 mechanical budgets, but servers and storage assemblies will post 12.22% CAGR as AI hardware proliferates. The Germany data center construction market faces a rapid pivot from air to direct-to-chip and immersion techniques. Builders must rough-in coolant supply and return manifolds early, coordinate floor loading for tanks, and route waste-heat pipelines to district networks.
Racks and cabinets standardize around 600 mm width but increase depth for rear-door heat exchangers. Fire suppression moves to water-mist and inert-gas blends compatible with liquid setups. Prefabricated white-space modules shorten fit-out schedules, yet require precise factory data to avoid rework. Contractors able to certify new liquid mediums gain a competitive advantage as 80 kW-plus racks become mainstream within the Germany data center construction market.
Geography Analysis
Frankfurt remains the primary hub, hosting more than 20 Digital Realty sites and the DE-CIX exchange, but grid constraints limit single-site expansions above 200 MW. AWS, NTT, and Vantage now distribute builds across multiple parcels to secure utility access, keeping the Germany data center construction market resilient despite bottlenecks.
Berlin is emerging as the leading secondary node. The Urban Tech Republic conversion of Tegel Airport offers sizeable plots with district-heating networks that align with EnEfG reuse targets. Maincubes’ forthcoming Nauen campus and Amazon’s Brandenburg sovereign-cloud zone confirm investor appetite. These projects raise the Germany data center construction market size in the capital region and diversify hyperscale footprints away from the Rhine-Main area.
Munich and Hamburg round out the growth corridor. Equinix’s USD 90 million MU4 site near Munich pairs aquifer thermal energy storage with Tier 3 redundancy. Hamburg leverages port-city renewables to market carbon-neutral edge halls. Together, these metros address regional latency, support automotive and logistics verticals, and absorb demand that Frankfurt’s grid cannot meet, extending the geography reach of the Germany data center construction market.
Regulatory Landscape
Germany's data center construction activity is shaped by the Energy Efficiency Act (EnEfG), which requires data centers to source at least 50% of electricity consumption from renewable sources starting in 2024 and move to 100% renewable electricity by 2027. The law also links efficiency and waste-heat related obligations to MEP design choices. In April 2026, a draft amendment to EnEfG was published with revised and more practicable PUE requirements, including a PUE limit of 1.3 (to be met within two years) for data centers commissioned from 1 July 2026, plus staged PUE thresholds for existing facilities (1.6 from 1 July 2027 and 1.4 from 1 July 2030).
These policy signals also increasingly tie digital infrastructure expansion to energy system constraints and planning practice. The Federal Ministry for Economic Affairs and Climate Action (BMWK) has framed data centers within programs that emphasize site selection and permitting readiness, grid-access coordination, and heat reuse integration with municipal networks, all of which shape early-stage feasibility, interconnection timelines, and local approval pathways for large campuses.
Value Chain Analysis
The Germany data center construction value chain spans land origination and zoning through design, permitting, procurement, build, commissioning, and operations integration. Upstream stakeholders include land developers and municipalities, where planning approvals and land-use constraints determine site availability, as well as grid operators (DSO/TSO) that control 110 kV access and renewable power counterparties that support EnEfG compliance.
Midstream delivery centers on EPCs and specialist contractors that coordinate civil works, substations, switchgear, UPS and generator packages, and high-density cooling (direct-to-chip, immersion, CDU infrastructure). Prefabrication and modular skids are increasingly used to manage lead times and reduce on-site risk. Downstream, colocation and hyperscale self-build operators, along with enterprise and public sector buyers, set technical specifications and audit requirements around tiering, redundancy, and testing, while heat-export offtakers and district heating utilities gain relevance as reuse targets tighten. Industry bodies such as the German Datacenter Association (GDA) engage with the Federal Network Agency (BNetzA) on grid-access topics, reflecting how interconnection feasibility and tariff treatment influence site selection, project phasing, and contract structures across Frankfurt and emerging secondary metros.
Competitive Landscape
International specialists such as DPR Construction, Exyte, and STRABAG combine global data-center know-how with German code compliance, positioning for hyperscale contracts. Domestic players like GOLDBECK and Data Center Group leverage utility relationships and local labor pools to compete on schedule certainty.
Strategic differentiation centers on liquid-cooling integration, waste-heat export, and on-site renewables that match EnEfG thresholds. Siemens moved beyond equipment supply by signing a multi-year modular electrics deal with Compass Datacenters, underlining a trend toward vertical integration.
Private equity interest remains strong. Vantage securitized EUR 720 million of German assets in 2025, the first such issuance in Europe, lowering its cost of capital. Bain Capital and Aquila formed a pan-European platform aimed at secondary metros, signaling confidence that the Germany data center construction market will maintain double-digit demand even outside Frankfurt.
Germany Data Center Construction Industry Leaders
-
Mercury Engineering
-
Michel Bau GmbH & Co. KG
-
Collen Construction Limited
-
DPR Construction
-
Royal HaskoningDHV
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Policy-driven build programs and compliance retrofits are creating demand for high-efficiency, grid-aware campus delivery. The Federal Governments Data Centre Strategy launched on 18 March 2026 sets an explicit capacity ambition, doubling national data center capacity by 2030 and scaling AI/HPC capability, which expands the addressable pipeline for developers, EPCs, and equipment integrators that can package permitting support, grid-connection engineering, and repeatable high-density hall designs. EnEfG requirements for renewable electricity sourcing and PUE performance are also pushing owners toward PPA-backed projects and liquid-cooling readiness, with metered energy reporting extending the scope for design-build teams that can integrate electrical efficiency, cooling innovations, and compliance documentation into the construction program.
A second opportunity cluster sits at the interface of data centers and municipal energy systems. Waste-heat reuse targets and district-heating networks support joint delivery models between data center operators and energy suppliers, including heat-exchanger plants and export piping planned alongside the main build rather than as a later retrofit. Geographic diversification also supports new site-development consortia as grid-capacity constraints in Frankfurt meet visibility around developments such as Berlins Urban Tech Republic (Tegel redevelopment) and Brandenburg sovereign-cloud projects, supporting demand for greenfield campuses, phased substations, and standardized modules in secondary metros.
Recent Industry Developments
- July 2026: Mercury Engineering marks milestone for Equinix MU4.3 data centre delivery in Munich, Germany. The achievement reflects ongoing data center construction activity in the Munich metro and indicates momentum for hyperscale expansion in southern Germany.
- March 2026: Mercury Engineering scaling data centre project delivery in Munich. The expansion supports offsite manufacturing and modular delivery to accelerate German builds and improve project certainty.
- February 2025: Vantage earmarked EUR 1.4 billion for EMEA expansion, including German projects. The announcement points to capital deployment and growing hyperscale activity in Germany beyond Frankfurt.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market tracks spending in Germany for building and expanding data centers, starting from site works and core structure and extending through installed electrical and mechanical infrastructure needed to make the facility operational.
Scope exclusions: It does not count ongoing IT operations, cloud service revenue, or routine post-handover facility management costs that sit outside construction delivery.
Segmentation Overview
-
By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
-
By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
-
By Infrastructure
-
By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
-
By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
-
By Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with establishing the demand and build pipeline for Germany using public signals that stay useful even when project details are limited. We reviewed items such as Federal Network Agency publications, Destatis construction and price indices, Eurostat energy and construction series, and planning and environmental filings available through local portals. For engineering and reliability context, standards and guidance from groups such as Uptime-type certification references and EU energy efficiency direction were also used as boundary checks.
To connect project intent to spending, we cross-checked press releases, investor presentations, and annual reports from developers, utilities, and large construction contractors, and then mapped them to likely delivery timelines. We used selected paid subscriptions only where they add traceable structure, such as company financials and intelligence, patent databases for cooling and power design signals, and an import-export shipment-level database for major electrical equipment flows. The examples listed here are illustrative and not exhaustive, and many other public, official, and corporate sources were also consulted for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and short surveys with stakeholders who touch project scope and pricing, such as contractors, engineering teams, equipment integrators, colocation operators, and enterprise buyers running self-build programs. This step helped confirm what is being built in the near term across Germany, the typical cost ranges by power and cooling intensity, and which cost items are bundled into construction contracts versus procured separately by owners.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 38% | CXOs: 12% |
| Mid tier: 44% | Functional/Unit leaders: 39% |
| Smaller Players: 18% | Managers: 49% |
Market-Sizing & Forecasting
Sizing was built using a combined top-down and bottom-up approach, where the top-down view reconstructs Germany construction spend from the active and planned capacity pipeline, typical build specifications, and construction cost indices. In practice, we start with the build program by metro and site type, convert it into expected deliverable space and IT load, and then apply normalized cost ranges for general construction, electrical systems, and mechanical systems.
To keep the model grounded, several market fingerprints were used as inputs and sense checks, including announced capacity additions and delivery dates, electricity connection constraints and grid upgrade timing, construction materials and labor cost inflation, and the shift to higher rack densities that changes cooling and power architecture. Forecasts were developed using scenario analysis, where near-term committed builds are separated from longer-dated plans, and then assumptions are stress-tested with primary feedback on delays, procurement lead times, and permitting pace. Bottom-up approximations were used selectively, such as sampled project budgets, typical cost per MW for comparable builds, and channel checks on major equipment packages. Where owners procure equipment outside the construction contract, gaps were handled by using conservative ranges and removing overlaps.
Data Validation & Update Cycle
Validation happens in layers so the final numbers do not rely on any single source. We run variance checks across independent signals such as pipeline capacity, timing of grid connections, and whether cost indices imply a realistic spend profile, and then any outliers are reviewed again before sign-off. Where assumptions drive a large share of the total, follow-up outreach is triggered to confirm what is included in contract scope and what is excluded.
Reports are refreshed annually, and interim updates are made when there are material changes such as large project announcements, cancellations, policy shifts, or step-changes in construction costs. Before delivery, the latest public updates are checked again so clients receive the most current view available at that time.
黑料不打烊's Germany Data Center Construction Market Size Measured Against Other Published Estimates
Published estimates for Germany data center construction can look far apart because each publisher draws the boundary differently and then applies its own cost logic to convert builds into dollars. Differences usually show up around whether fit-out is counted, how much owner-furnished equipment is treated as construction spend, and how aggressively future project timelines are assumed.
Permitted project pipelines, grid-connection readiness, and Germany construction cost indices are the checks that keep 黑料不打烊's estimate tied to deliverable builds and updated cost progression for electrical and mechanical packages that are commonly bundled in turnkey contracts. The main gap drivers behind other figures tend to be the inclusion of adjacent IT hardware, the use of fixed cost per MW without updating for power and cooling complexity, and refresh cadence differences that leave older project lists in the model for longer than they should stay.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 7.28 B (2025) | |
| Global Consultancy A | USD 7.20 B (2024) | Uses a prior-year snapshot of the build pipeline and applies a narrower construction scope that can undercount electrical and mechanical packages bundled in turnkey contracts. |
| Industry Publisher B | USD 7.71 B (2024) | Leans on headline project capex and blended cost per MW assumptions that can overstate near-term spend when delivery schedules slip or when owner-procured equipment is included as construction. |
The spread in the table is mainly explained by how each source treats contract scope, timing, and cost escalation for power and cooling heavy builds. By anchoring totals to observable pipeline and cost signals, and then checking them with interview-led scope validation, the outcome stays traceable to repeatable steps when project lists change.


Key Questions Answered in the Report
What is the projected value of the Germany data center construction market by 2031?
The market is expected to reach USD 11.94 billion by 2031, growing at an 8.62% CAGR.
Which German city leads new data center construction?
Frankfurt remains the largest hub, but Berlin, Munich, and Hamburg are gaining share due to grid-capacity reallocation.
How are AI workloads affecting facility design?
AI clusters push rack densities above 80 kW, driving widespread adoption of liquid-cooling infrastructure and higher-voltage power distribution.
What does the Energy Efficiency Act require from new data centers?
The law mandates a PUE of ≤1.2 for new builds and at least 50% renewable electricity immediately, rising to 100% by 2027, plus progressive waste-heat reuse.
Why are Tier 4 facilities growing faster than Tier 3?
Hyperscale and financial-service operators demand 99.995% uptime, justifying the redundancy and higher capital outlay of Tier 4 designs, which are expanding at 10.74% CAGR.
How is construction cost inflation impacting projects?
Switchgear and generator prices have risen 32% since 2022, adding budget pressure and lengthening procurement timelines for large builds.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Japan Data Center Power Market Japan power systems, split by component, facility type and facility size.
- Germany Hyperscale Data Center Market Hyperscale sites in Germany, split by facility type, component and tier.
- South Korea Data Center Rack Market South Korea's racks, split by rack size, rack height and rack type.
- Japan Data Center Server Market Servers demand across Japan, covering tier, facility size and facility type.


