
UK Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 118.75 Million |
| Market Size (2026) | USD 135.46 Million |
| Market Size (2031) | USD 261.77 Million |
| Growth Rate (2026 - 2031) | 14.07 % |
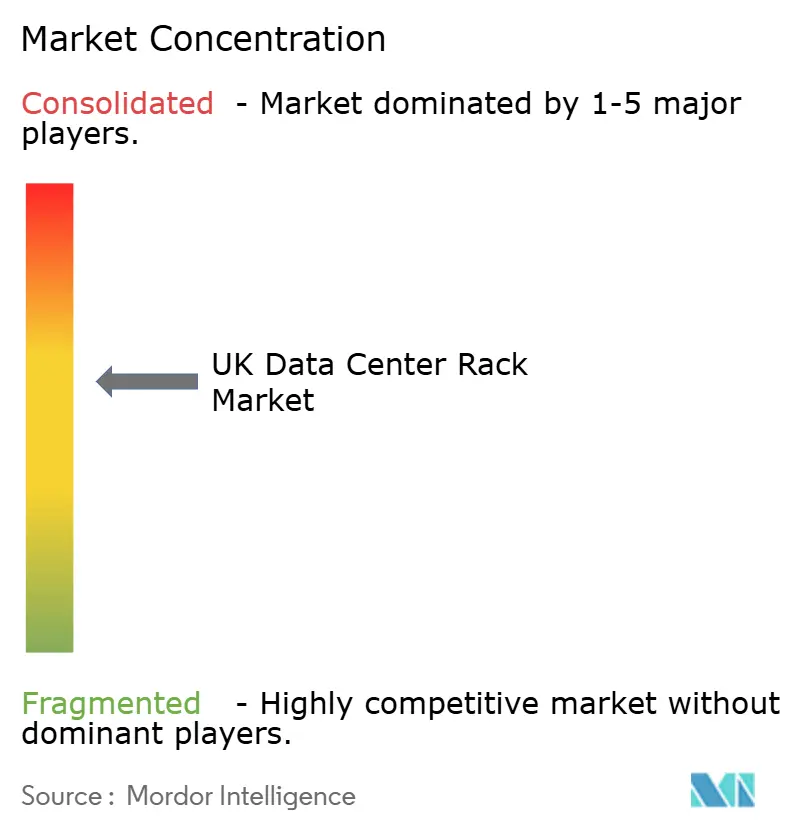
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
UK Data Center Rack Market Analysis by 黑料不打烊
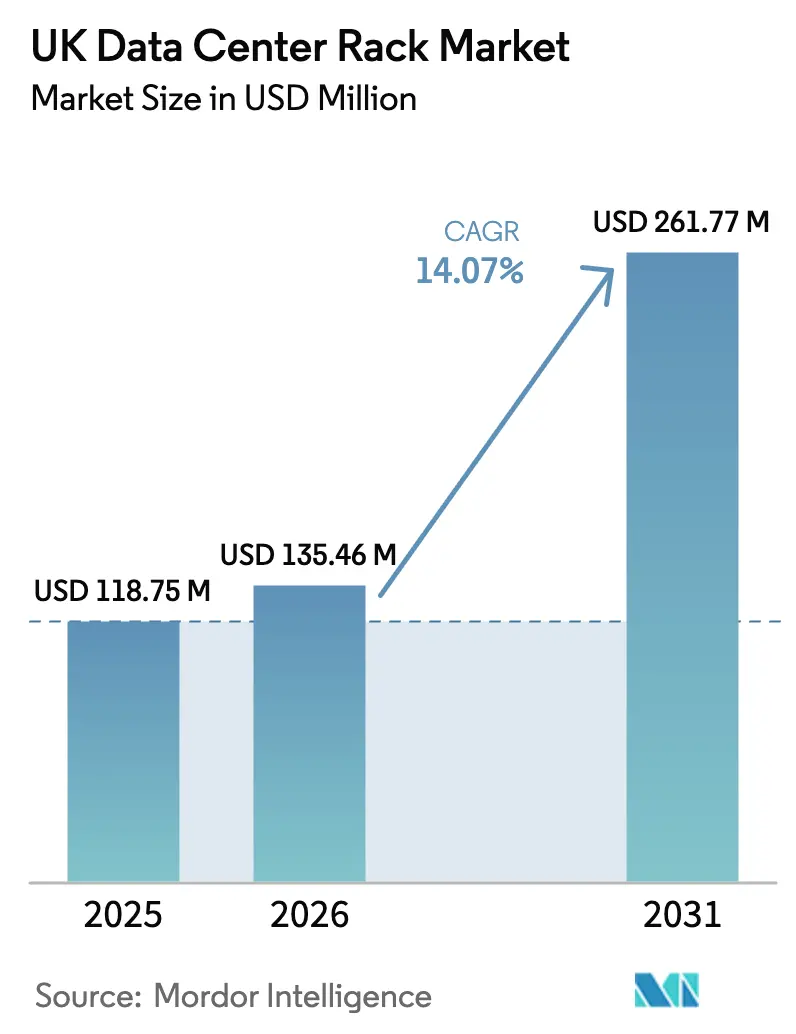
The United Kingdom data center rack market size is expected to grow from USD 118.75 million in 2025 to USD 135.46 million in 2026 and is forecast to reach USD 261.77 million by 2031 at 14.07% CAGR over 2026-2031. Current growth rests on the nation’s AI Opportunities Action Plan, which is unlocking private capital for digital infrastructure while fast-tracking planning approvals. Designation of data centers as Critical National Infrastructure in 2024 tightened cyber-security standards, lifting demand for cabinet-class enclosures that meet stricter physical-security rules. Sovereign-cloud deployments, accelerated by the Competition and Markets Authority’s probe into hyperscale concentration, are steering many enterprises toward domestically run facilities that favor the United Kingdom data center rack market. Meanwhile, AI workloads are driving a shift from 42U to 48U heights, with liquid-cool-ready frames gaining traction as rack power densities surpass 70 kW. Supply-chain pressure from power-grid connection queues is pushing operators into secondary metros and stimulating interest in on-site generation, modular designs, and material innovations such as aluminum alloys.
Key Report Takeaways
- By rack type, cabinet racks captured 64.02% of the United Kingdom data center rack market share in 2025; open-frame racks are projected to grow at 16.05% CAGR through 2031.
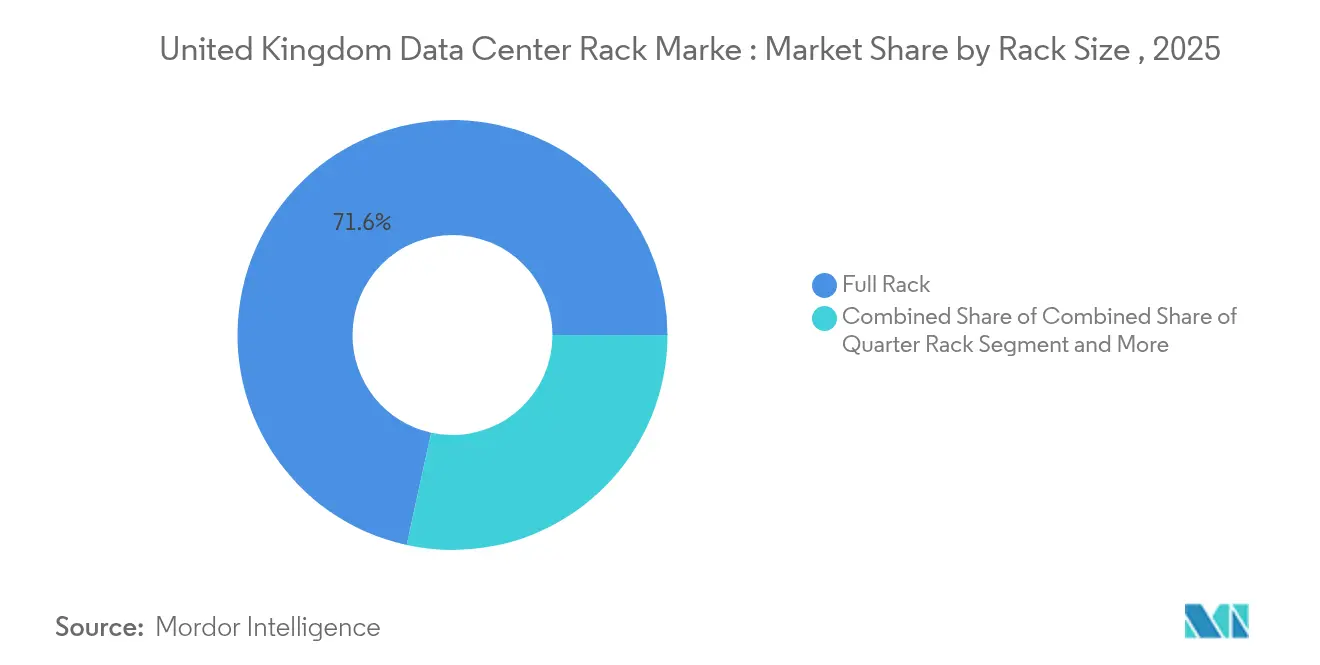
- By rack size, full racks led with 71.58% share of the United Kingdom data center rack market size in 2025, while quarter racks are forecast to advance at 16.12% CAGR to 2031.
- By rack height, 42U configurations accounted for 55.82% share of the United Kingdom data center rack market size in 2025; 48U racks exhibit the highest projected CAGR at 14.92% between 2026-2031.
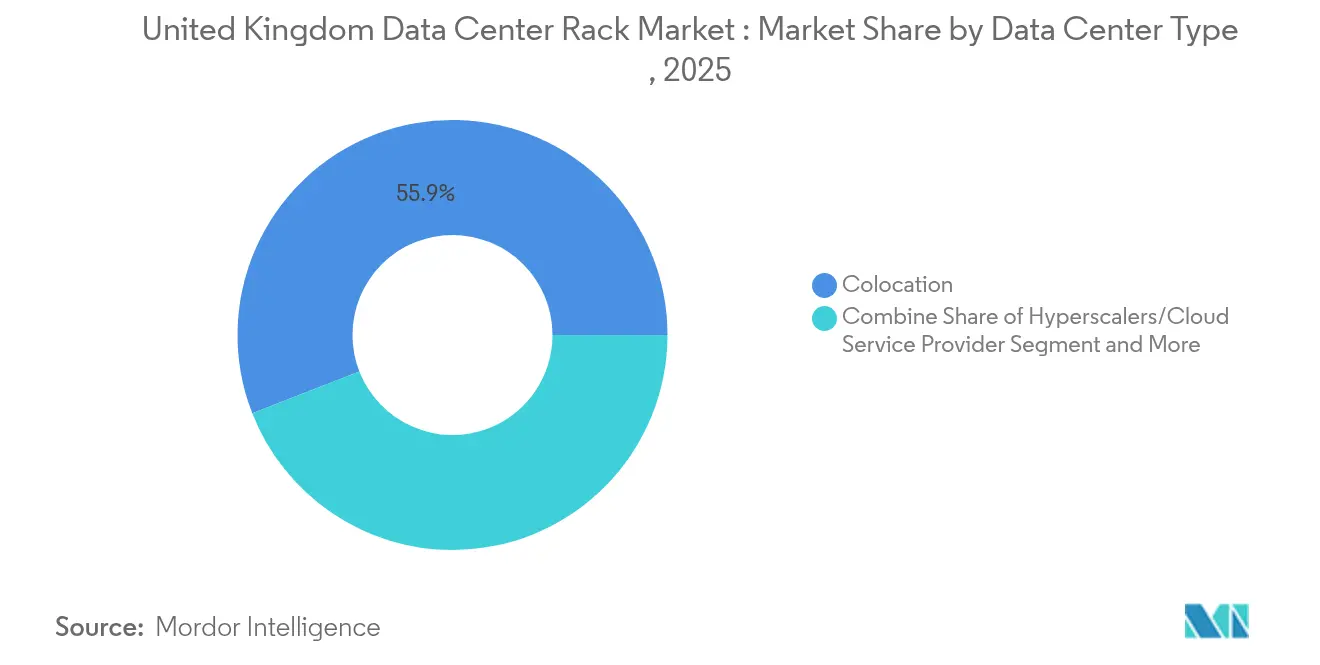
- By data-center type, colocation held 55.93% share of the United Kingdom data center rack market in 2025; hyperscale deployments are expanding at 16.98% CAGR to 2031.
- By material, steel dominated with 81.78% United Kingdom data center rack market share in 2025; aluminum racks are rising at 16.92% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
UK Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid adoption of sovereign and hybrid cloud zones | +3.2% | National, with concentration in London, Manchester, Edinburgh | Medium term (2-4 years) |
| AI/ML rack-density upgrades across hyperscale and colocation | +4.1% | Global, with UK leading in financial services AI adoption | Short term (≤ 2 years) |
| Accelerated 5G edge build-outs needing micro-racks | +1.8% | Urban centers: London, Birmingham, Manchester, Glasgow | Medium term (2-4 years) |
| Government carbon-neutral mandates driving liquid-cool ready racks | +2.3% | National, with early adoption in Scotland and Wales | Long term (≥ 4 years) |
| Surge in fintech and Open-Banking transactions | +1.9% | London financial district, with spillover to Edinburgh | Short term (≤ 2 years) |
| Modular data-hall retrofits in listed U.K. real-estate trusts | +1.0% | Greater London, Manchester, Birmingham metro areas | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Rapid Adoption of Sovereign and Hybrid Cloud Zones
The sovereign-cloud agenda is redrawing rack-deployment patterns as enterprises seek local data-residency compliance. AI Growth Zones streamline approvals, enabling faster cabinet installations with enhanced locking mechanisms that meet financial-sector audit trails. Hybrid architectures also mitigate vendor lock-in risk highlighted by the ongoing cloud-market investigation, spurring demand for racks with integrated cabling and power-distribution units that support multi-cloud switching.[1]Competition and Markets Authority, “CMA launches market investigation into cloud services,” gov.uk Financial institutions further accelerate deployments by specifying British-hosted racks that satisfy open-banking regulations.
AI/ML Rack-Density Upgrades Across Hyperscale and Colocation
AI training clusters are pushing per-rack loads above 90 kW, forcing operators to adopt 48U and custom heights to accommodate immersion trays, rear-door heat exchangers, and high-capacity busbars. Partnerships such as Telehouse’s liquid-cooling laboratory illustrate the convergence of rack, cooling, and monitoring domains, opening opportunities for suppliers able to offer pre-engineered, liquid-ready cabinets. [2]Telehouse, “Telehouse launches London liquid-cooling lab,” telehouse.net Hyperscalers standardize on taller frames to optimize compute-per-square-meter, strengthening volume demand for the United Kingdom data center rack market.
Accelerated 5G Edge Build-Outs Needing Micro-Racks
Nationwide 5G rollout requires edge nodes in shopping centers, stadiums, and roadside cabinets. Operators specify quarter and half-racks with ruggedized casings, vibration dampers, and remote-access sensors so they can manage unmanned sites. Wall-mount formats gain popularity because they fit retail backrooms and cell-tower shelters without structural reinforcements, broadening the customer base for specialized rack vendors.
Government Carbon-Neutral Mandates Driving Liquid-Cool Ready Racks
Net-zero rules and the Energy Efficiency Directive obligate data-center operators to capture waste heat and curtail water usage. Rack manufacturers respond with aluminum skeletons that integrate cold-plate manifolds and quick-disconnect piping, cutting installation labor and leak risk. Recent factory investments in Scarborough will shorten domestic supply chains and reduce embedded-carbon footprints for United Kingdom data center rack market buyers. [3]Schneider Electric, “Schneider Electric invests GBP 42 million in Scarborough facility,” se.com
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Power-grid connection queues (≥24-month delays) | -2.8% | London, Birmingham, Manchester metropolitan areas | Short term (≤ 2 years) |
| Tight labour pool for Tier 3/Tier 4 installers | -1.5% | National, with acute shortages in Scotland and Northern England | Medium term (2-4 years) |
| In-rack thermal hotspots above 70 kW challenging legacy sites | -1.2% | London financial district, established colocation facilities | Short term (≤ 2 years) |
| Rising insurance premiums on high-density halls | -0.8% | Greater London, with spillover to major urban centers | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Power-Grid Connection Queues (≥ 24-Month Delays)
Backlogs totaling 400 GW in the London region force developers to wait two years or more for grid hookups. Many operators redirect capital to Manchester or Cardiff, while others install on-site gas turbines, battery storage, or explore small modular reactors. The AI Energy Council’s formation underscores official urgency; however, long approval cycles still curb near-term rack deployments.
Tight Labour Pool for Tier 3/Tier 4 Installers
Liquid-cool technology demands plumbers, controls technicians, and commissioning engineers schooled in both IT and HVAC disciplines. Post-Brexit immigration constraints have narrowed the talent funnel, lengthening build schedules and inflating wages. Suppliers now ship pre-assembled busways and coolant loops to cut field labor, yet complex retrofits in legacy halls remain schedule-risk factors for United Kingdom data center rack market projects.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full Racks Dominate Enterprise Deployments
Full racks held 71.58% of the United Kingdom data center rack market share in 2025, reflecting the preference for standardized 600 mm × 1,200 mm footprints that streamline airflow and cable management. The segment is projected to expand at 15.86% CAGR as hyperscalers and colocation landlords chase economies of scale. Quarter racks will persist in edge pods, but volume remains modest in the overall United Kingdom data center rack market.
Rising AI compute clusters further cement full-rack popularity because clustered GPU trays consume contiguous vertical and horizontal space, making partial frames inefficient for power and cooling loops. Therefore, suppliers concentrate R&D on strengthening frame rigidity, vibration isolation, and built-in coolant manifolds that serve rack-wide cold-plate grids—features easier to integrate when designing full-height enclosures.


By Rack Height: 42U Standard Faces AI-Driven Evolution
The 42U format still accounts for 55.82% of the United Kingdom data center rack market size, but its dominance is eroding as 48U systems grow 14.92% per year. Taller frames provide an extra 6U that operators allocate to in-rack UPS drawers, top-of-rack switches, or manifold headers for liquid loops. Taller enclosures also raise center-of-gravity considerations, prompting vendors to switch from mild steel to lighter aluminum frames that meet seismic standards without adding floor anchoring.
GPU clusters like NVIDIA DGX SuperPOD occupy multiple rack units per server sled, accelerating the shift to 48U and custom 52U configurations so operators can maximize nodes per kilowatt. Legacy 42U sites in London’s Docklands are therefore retrofitting with rear-door heat exchangers to squeeze incremental capacity until grid upgrades arrive
By Rack Type: Cabinet Security Drives Colocation Preference
Cabinet racks captured 64.02% of the United Kingdom data center rack market share, propelled by financial-services compliance requirements that demand lockable doors, CCTV integration, and differential-pressure containment. Growth remains strongest in cabinet designs because colocation providers rely on them to separate multi-tenant environments, and hyperscalers now adopt sealed racks for internal micro-segmentation of customer clusters.
Open-frame racks survive where cost minimization overrides security, chiefly in dedicated hyperscale halls. Still, even here, operators are adding side-panel kits and RFID-controlled doors, steadily nudging open-frame users toward hybrid or fully enclosed formats. Wall-mount cabinets gain share in roadside and retail deployments that anchor 5G edge applications.
By Data Center Type: Colocation Leads Multi-Tenant Growth
Colocation sites accounted for 55.93% of the United Kingdom data center rack market in 2025, thanks to enterprise outsourcing of non-core infrastructure. Hyperscale cloud operators, expanding at 16.98% CAGR, are building multi-building campuses in Northumberland and Greater Manchester, boosting large-volume rack orders that feature standardized busbar trunking, closed-loop coolant rails, and AI-optimized airflow.
Enterprise self-build facilities shrink as CIOs migrate workloads to OPEX-driven contracts. Edge data centers, though small per site, are proliferating in count, creating a tailwind for micro-rack suppliers that can pre-assemble units in local factories and ship to distributed cell-tower shelters.
By Material: Steel Dominance Faces Aluminum Challenge
Steel remains the default, anchoring 81.78% of the United Kingdom data center rack market size, yet aluminum racks rise 16.92% annually. Weight savings facilitate multi-story builds where floor loading is critical, and aluminum’s superior thermal conductivity improves liquid-cool efficiency. Operators embracing net-zero targets value aluminum’s recyclability, prompting some to stipulate minimum recycled content in procurement tenders.
Composite and copper-lined frames cater to electromagnetic shielding requirements inside classified government pods. Although niche today, these premium racks could expand if post-quantum encryption drives demand for secure enclaves that resist side-channel attacks.
Geography Analysis
Greater London retains the largest share of the United Kingdom data center rack market, fueled by proximity to financial hubs and undersea cables. However, 24-month grid queues and soaring land costs shift fresh investment toward Manchester, Birmingham, and Edinburgh. Scotland’s renewable energy surplus and cooler climate attract hyperscale projects aiming to lower Power Usage Effectiveness, while Wales offers inexpensive sites near the Western Power grid spine.
Northern England is ascending quickly: QTS’s proposal in Northumberland and Kao Data’s Stockport campus illustrate how brownfield industrial land, previously overlooked, is being repurposed for data-center campuses. These locations supply ample power headroom and enjoy improved fiber backhaul via recent rail-corridor conduit projects. As a result, the United Kingdom data center rack market size in northern regions is forecast to grow faster than the national average through 2031.
Edge computing reshapes geographic strategy by dispersing micro-data centers along 5G corridors. Latos Data Centres’ plan for 40 sites underscores the pivot toward regional hubs where latency-sensitive workloads require racks closer to users. Public-sector incentives under the “leveling-up” agenda should further diversify deployment, allowing the United Kingdom data center rack market to avoid over-reliance on the congested South-East.
Regulatory Landscape
The United Kingdom has tightened oversight of data center resilience and security, which is shaping rack specifications and procurement. After data centers were designated Critical National Infrastructure in September 2024, the Cyber Security and Resilience (Network and Information Systems) Bill introduced in November 2025 brings data centers into an essential-services style cyber framework, with Ofcom positioned as the operational regulator. In-scope operators face requirements around registration, resilience controls, and incident reporting, reinforcing demand for lockable cabinet racks and physical-security features that support audit needs.
Planning and energy-policy changes are also affecting where and how capacity is built. The Infrastructure Planning (Business or Commercial Projects) (Amendment) Regulations 2026 (SI 2026/13), made on 8 January 2026, enables certain data center projects to use the Nationally Significant Infrastructure Projects (NSIP) consenting pathway through a Development Consent Order. In parallel, DESNZ and Ofgem-led grid connection reform, alongside the government’s AI Growth Zones program, is prioritizing strategically important demand projects and pushing developers toward designs that compress build schedules, including modular halls and pre-integrated busway and PDU-ready racks, as well as toward locations where power and planning pathways are clearer.
Competitive Landscape
Competition remains moderate, with Schneider Electric, Vertiv, and Eaton facing specialized challengers in liquid-cool integration and edge form factors. Market consolidation accelerated in 2024, tallying 13 strategic transactions as players pursued integrated value chains. Schneider Electric’s USD 850 million Motivair acquisition shores up direct-to-chip cooling know-how, letting it bundle racks, busways, and coolant distribution as a single SKU.
Vertiv partners with immersion-tank makers to deliver hybrid solutions that retrofit legacy halls, while Eaton packages racks with lithium-ion UPS skids to shorten build cycles for colocation operators. Regional specialists such as Cannon Technologies differentiate on rapid lead times and bespoke cable-management accessories favored by telecom edge deployments. New entrants leverage aluminum fabrication and sustainable sourcing to win bids tied to ESG scoring, carving out niches inside the broader United Kingdom data center rack market.
Technology alliances increasingly decide market share: Telehouse coordinates a vendor ecosystem spanning pump-skids, coolant, and sensors to guarantee 90 kW-plus per rack. Similar ecosystems emerge at new Scottish campuses, indicating that rack suppliers able to certify end-to-end performance with cooling and power partners will capture premium segments.
UK Data Center Rack Industry Leaders
Eaton Corporation
Rittal GmbH & Co. KG
Schneider Electric SE
Hewlett Packard Enterprise Co.
Vertiv Group Corp.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Compliance-driven upgrades and planning reform create whitespace for rack suppliers that can combine security, monitoring, and high-density readiness into repeatable designs. With data centers treated as Critical National Infrastructure (September 2024) and cyber requirements formalized through the Cyber Security and Resilience (Network and Information Systems) Bill introduced in November 2025 under Ofcom oversight, operators have stronger incentives to standardize on cabinet-class enclosures with access control, asset tracking, and physical hardening. That, in turn, supports opportunities for vendors offering pre-certified cabinet platforms aligned to multi-tenant colocation and sovereign-cloud audit needs, including integration points for sensors and tamper-evident features.
Siting and power constraints are also changing the mix of rack heights, materials, and integration levels purchased in the United Kingdom, as demand shifts toward regional builds and modular delivery models. Industry commentary points to London accounting for over 80% of UK data center supply, while grid and land constraints are pushing activity toward Greater Manchester, South Wales, and Scotland, which aligns with AI Growth Zones and wider infrastructure development. The 2026 update allowing larger projects to use the NSIP regime (SI 2026/13) supports centralized consenting for select developments and reinforces demand for factory-built, rapidly installed racks and containment systems designed for compressed construction windows. At the same time, grid-connection reform efforts led by DESNZ and Ofgem prioritize strategically important loads, which increases the addressable need for higher-power rack architectures such as liquid-cool-ready frames and busbar-compatible cabinets that help operators convert scarce power allocations into more compute per square meter.
Recent Industry Developments
- April 2026: Vertiv hosted the Secretary of State for Northern Ireland at its Campsie manufacturing site to highlight progress in facility expansion. The expanded capacity for electrical switchgear production strengthens Vertiv's local manufacturing footprint and resilience in UK power for faster data center deployment. This event signals enhanced domestic capability that supports enterprise digital infrastructure expansion in the region.
- January 2026: Eaton collaborated with Flexnode to deliver modular, scalable rack and power infrastructure for data center compute applications. The collaboration shortens deployment schedules and expands Eaton's reach in modular data center solutions. The initiative underscores growing demand for rapid, scalable power and rack architectures in new data center builds.
- November 2025: Schneider Electric and DataCentre UK deployed two modular data centers for the South Warwickshire University NHS Foundation Trust, featuring APC NetShelter racks. The project demonstrates accelerated modular build capability and strengthens NHS digital infrastructure readiness. It also expands market visibility for modular data center enclosures in UK institutional deployments.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers revenues earned from data center racks sold and deployed in the United Kingdom, including common enclosure and frame formats used to mount IT equipment in enterprise, colocation, and hyperscale-style facilities.
Scope exclusions: We exclude IT hardware (servers, storage, and networking), power and cooling infrastructure, and most rack add-ons like standalone power distribution units and monitoring systems.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to assemble the first view of demand and supply signals in the United Kingdom, before we stress-test assumptions through interviews. We relied on public datasets and official references to anchor model inputs, including UK government and regulator publications, trade statistics, and infrastructure planning information.
Examples of sources include Office for National Statistics releases, HM Revenue and Customs trade data, National Grid system updates, and UK planning portals where larger data center builds are tracked, plus standards and technical references from bodies such as ISO or IEC. We also review company filings, investor presentations, trade press, and patent databases, then use paid subscriptions for company financials and news screening, along with shipment-level import and export checks where they help confirm pricing and sourcing. This list is not exhaustive, and we reviewed additional sources to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary work focuses on validating the real buying cycle for racks in the UK, since order timing, lead times, and refresh cycles can move totals meaningfully year to year. We spoke with a mix of rack suppliers, distributors and installers, data center operators, and end users, then tested assumptions on rack height preferences, cabinet versus open-frame mix, and typical pricing steps under different load and compliance needs.
To avoid over-relying on London-only signals, inputs were also cross-checked with respondents familiar with other UK clusters. Follow-ups were conducted when desk indicators and field feedback did not match cleanly.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 26% | CXOs: 18% |
| Mid tier: 54% | Functional/Unit leaders: 35% |
| Smaller Players: 20% | Managers: 47% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs the UK rack demand pool from data center build-outs and refresh activity, then translates that into rack units and value using realistic shipment timing and pricing ladders. Once the structure is in place, totals are corroborated through selective bottom-up checks, such as sampled supplier revenue ranges, distributor channel checks, and an ASP times volume sanity check tied to a few high-visibility facility expansions.
The model uses practical inputs that can be tracked and rechecked, including planned and active data center capacity additions, estimated rack density by facility type, the mix shift from 42U toward taller cabinets (like 45U to 48U), cabinet versus open-frame adoption, and steel-driven cost movement that affects average selling prices. Where public data is not granular enough, gaps are handled using conservative ranges, then narrowed using interview feedback, and applied consistently across the forecast years.
For forecasting, we use scenario analysis because build pipelines and commissioning schedules can shift, then align those scenarios to what operators and integrators expect for installs and replacements. Assumptions are adjusted for timing effects, such as delayed energization, phased fit-outs, and bulk purchasing cycles, so the revenue curve does not get smoothed unrealistically.
Data Validation & Update Cycle
Outputs are validated through multiple checks to keep the numbers traceable to real activity. We compare modeled rack volumes and values against independent signals such as facility pipeline updates, construction milestones, import patterns for rack-like shipments, and stated expansion plans, then review outliers before final sign-off.
If a major variance appears, the related assumptions are revisited, and we re-contact relevant respondents to confirm whether the change is genuine or driven by timing, pricing, or scope mismatch. The report is refreshed annually, with interim updates when material events occur, for example large project delays, new capacity announcements, or sharp pricing changes. Before delivery, an additional pass is completed so clients get the most current view available at that time.
黑料不打烊's United Kingdom Data Center Rack Market Estimate Compared With Other Published Estimates
Published market sizes for UK data center racks can vary even when the topic name looks the same. The main reasons are differences in what gets counted as a rack, which year is used as the base, and how pricing changes are applied across cabinet types and heights.
The table reflects a wide spread that is mostly explained by scope and pricing choices. In 黑料不打烊's model, the value is limited to racks and rack enclosures sold into UK data centers, rather than folding in adjacent items like power distribution add-ons or broader data center infrastructure bundles. Another gap is the use of fixed global average pricing, which can miss UK-specific shifts like taller cabinet adoption and installation-led buying cycles. Currency timing and refresh cadence can also push totals further away when cut-offs differ.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 118.75 M (2025) | |
| Regional Consultancy A | USD 210.00 M (2024) | Often groups racks with wider data center fit-out line items, and may include items like PDUs and accessories, which inflates the addressable value versus rack-only revenue. |
| Industry Journal B | USD 239.20 M (2023) | Uses an older base year and typically applies straight-line growth with limited checks on UK commissioning delays, height mix shift, and year-to-year ASP movement. |
Taken together, the differences come down to what is counted, when it is counted, and how the price per rack is allowed to change. By tying the totals to observable build activity, realistic rack densities, and a clear treatment of cabinet versus frame pricing, we get a market number that is easier to explain and repeat when new project data comes in.


Key Questions Answered in the Report
What factors are driving growth in the United Kingdom data center rack market?
Robust AI investments, sovereign-cloud mandates, and 5G edge deployments combine to lift rack density needs and spur demand for liquid-cool-ready enclosures.
How large is the United Kingdom data center rack market today?
The market generated USD 135.46 million in 2026 and is forecast to reach USD 261.77 million by 2031.
Which rack type leads the market?
Cabinet racks dominate with 64.02% share in 2025 due to stringent physical-security requirements in colocation facilities.
Why are 48U racks gaining popularity?
They provide extra vertical space for AI servers and cooling hardware, enabling power densities above 70 kW per rack and supporting taller liquid-cool manifolds.
Page last updated on:
- Data Center Construction Market Construction worldwide, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Malaysia Data Center Server Market Malaysia's servers, split by data-center tier, form factor and application / workload.
- United States Data Center Server Market The US's servers, split by data-center tier, form factor and application / workload.
- Chile Data Center Water Consumption Market Water use demand across Chile, covering source of water procurement, facility type and facility size.
- Taiwan Hyperscale Data Center Market Taiwan hyperscale sites, split by facility type, component and tier.
- North America Hyperscale Data Center Market North America's hyperscale sites, split by facility type, component and tier.



