
Malaysia Data Center Server Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.22 Billion |
| Market Size (2026) | USD 2.59 Billion |
| Market Size (2031) | USD 5.53 Billion |
| Growth Rate (2026 - 2031) | 16.42 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
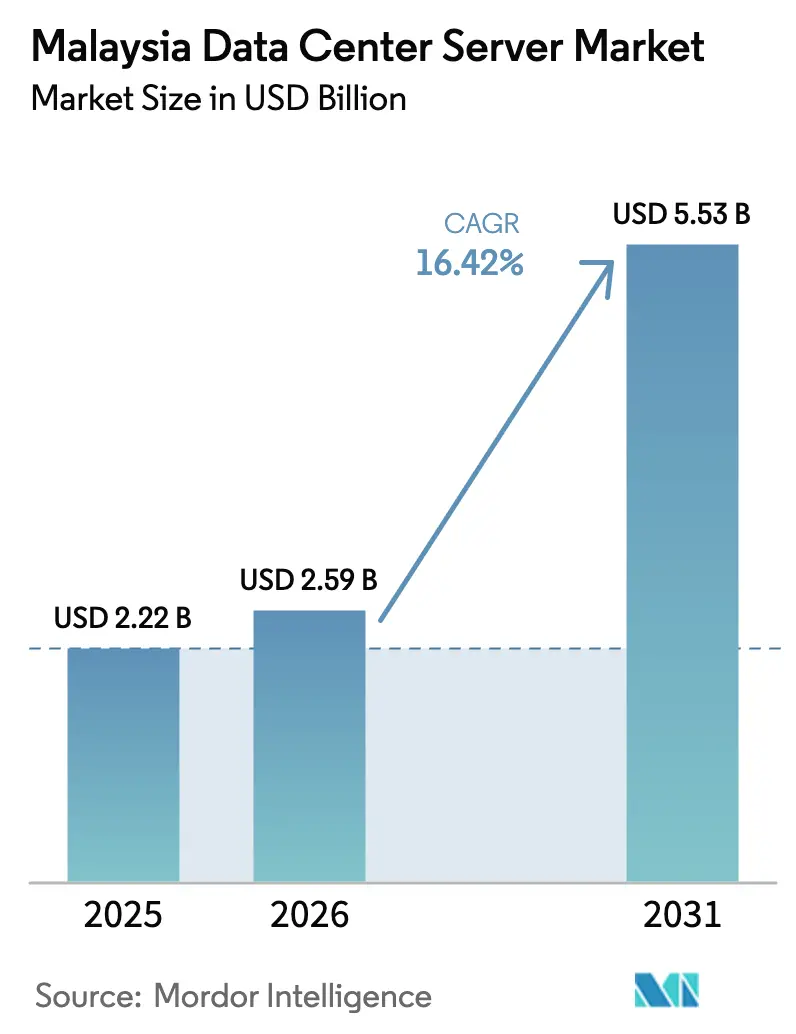
Malaysia Data Center Server Market Analysis by 黑料不打烊
The Malaysia data center server market size was valued at USD 2.22 billion in 2025 and estimated to grow from USD 2.59 billion in 2026 to reach USD 5.53 billion by 2031, at a CAGR of 16.42% during the forecast period (2026-2031). Growing hyperscale footprints, a national cloud-first mandate, and targeted renewable-energy incentives are invigorating server refresh cycles, particularly for high-density AI configurations. Johor’s rapid rise to 1.6 GW of live capacity, favourable land prices, and streamlined permitting make the state the focal point for new server installations. Concurrently, electricity-tariff reforms elevate power-efficiency considerations, sharpening vendor competition around performance-per-watt. Finally, ongoing submarine-cable projects strengthen Malaysia’s role as an interconnection hub, driving incremental server demand for content caching and traffic transit.
Key Report Takeaways
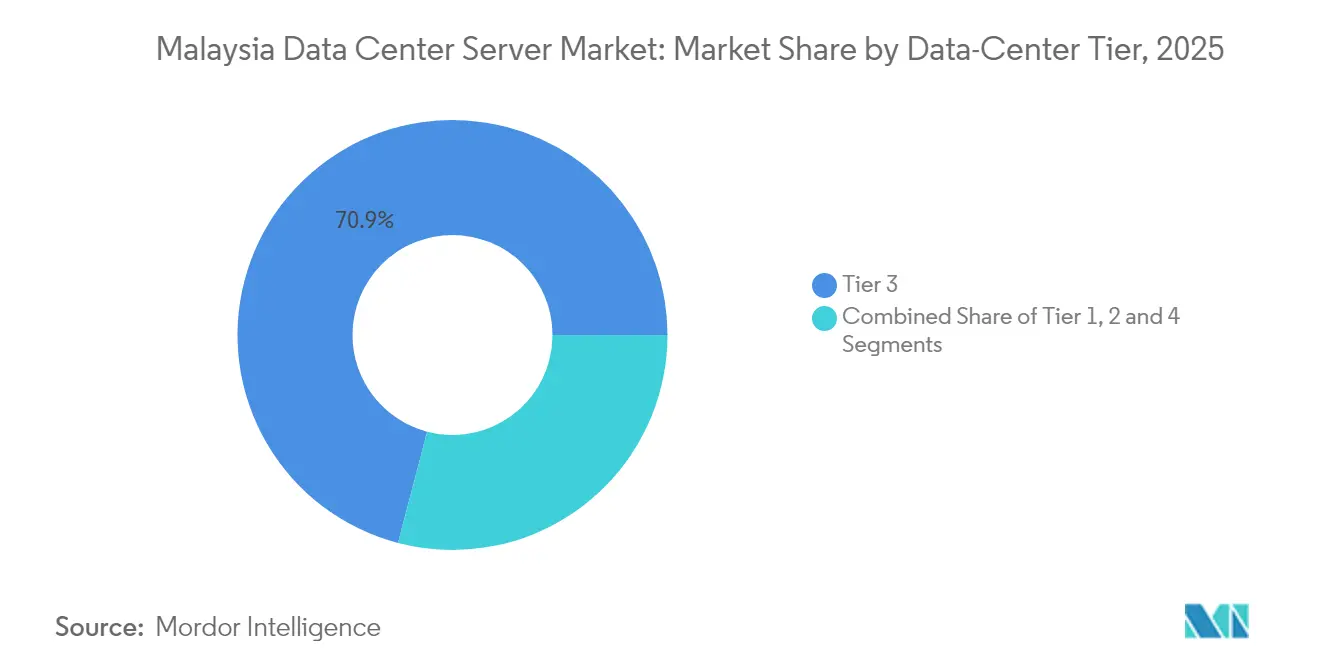
- By data-center tier, Tier 3 facilities held 70.92% of Malaysia's data center server market share in 2025, while Tier 4 is advancing at an 18.33% CAGR through 2031.
- By form factor, half-height blades led with 62.54% revenue share in 2025; quarter-height micro-blades are projected to expand at a 16.61% CAGR to 2031.
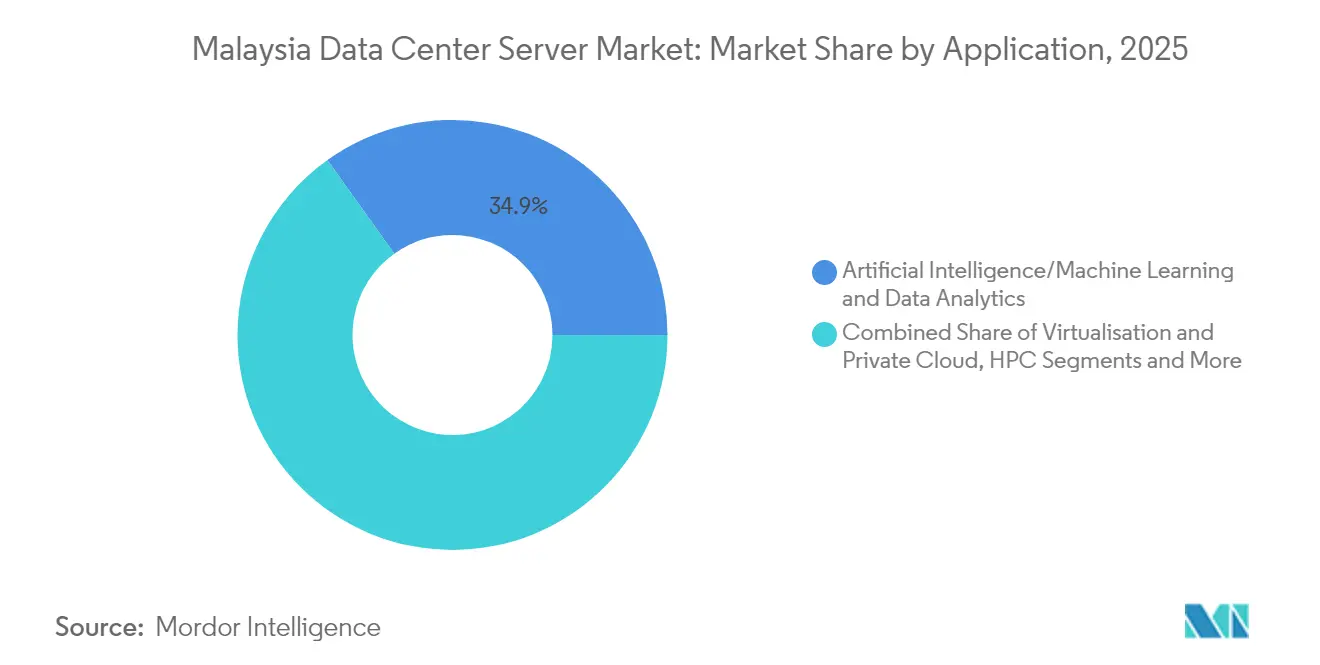
- By application, AI/ML workloads accounted for 34.88% of the Malaysia data center server market size in 2025 and command the highest absolute spending; virtualization and private-cloud workloads are the fastest-growing at 16.94% CAGR to 2031.
- By data-center type, colocation sites captured 56.62% of the Malaysia data center server market size in 2025, whereas hyperscaler deployments are growing at an 18.21% CAGR.
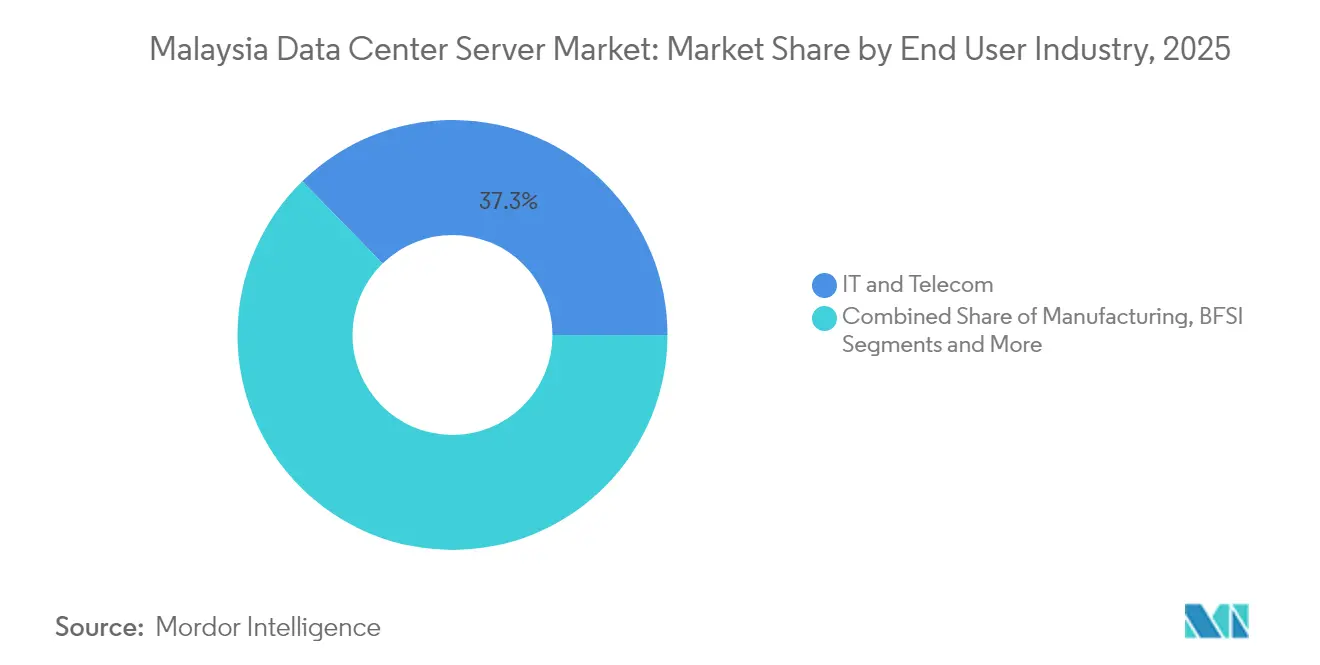
- By end-use industry, IT & telecom led with 37.32% revenue share in 2025; manufacturing and Industry 4.0 workloads are forecast to post a 17.21% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Malaysia Data Center Server Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in hyperscale & colocation data-center investments | +4.2% | National, concentrated in Johor and Selangor | Medium term (2-4 years) |
| Expansion of internet infrastructure and new submarine cables | +2.8% | National, with spillover to ASEAN region | Long term (≥ 4 years) |
| Government cloud-first & Digital Economy incentives | +3.1% | National, early gains in Cyberjaya and Putrajaya | Short term (≤ 2 years) |
| Rising adoption of cloud, AI/ML & IoT-driven workloads | +3.9% | Global demand, localized in Malaysia | Medium term (2-4 years) |
| Entry of sovereign-fund-backed edge micro-hubs in Tier-2 cities | +1.7% | Regional, focusing on Penang, Johor Bahru, Kuching | Long term (≥ 4 years) |
| Introduction of 2026 green-tax credit for high-efficiency servers | +1.3% | National, with early adoption in major facilities | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Surge in Hyperscale & Colocation Data-Center Investments
Major cloud providers pledged more than USD 15 billion in 2024 alone, led by Google’s USD 2 billion first Malaysian region in Greater Kuala Lumpur and Microsoft’s three-site rollout scheduled for Q2 2025.[1]Google Cloud, “Google Announces First Malaysia Cloud Region,” cloud.google.comJohor’s comparative land affordability and close distance to Singapore accelerate campus-scale builds such as Vantage’s 256 MW Cyberjaya complex and Princeton Digital Group’s 150 MW AI-ready JH1 site. The resulting spike in rack demand concentrates orders for liquid-cooled GPU servers optimized for AI inference, reinforcing the Malaysia data center server market.
Government Cloud-First & Digital-Economy Incentives
The MyDIGITAL blueprint targets a 22.6% GDP share from digital activities by 2025 and requires 80% of public-sector workloads to migrate to hybrid cloud environments.[2]The Edge Markets, “TNB Tariff Hike and Data-Center Impact,” theedgemarkets.com Conditional approvals worth RM 12-15 billion allow hyperscalers to build locally, while the Cloud Framework Agreement steers procurement toward domestic partners. Ministries upgrading from legacy three-tier stacks to hyper-converged architectures report faster data access and stronger resiliency, cementing ongoing server refresh cycles.
Rising Adoption of Cloud, AI/ML and IoT-Driven Workloads
AI/ML already consumes 35.3% of server cycles, propelled by Malaysia’s roll-out of a sovereign AI stack based on Huawei Ascend chips and an in-country large-language-model program. Nvidia’s USD 4.3 billion venture with YTL Power adds GPU-dense clusters that draw over 40 kW per rack, making liquid cooling a necessity. Smart-hospital deployments and nationwide MEC pilots further diversify load profiles, encouraging purchases of edge-specific micro-blades designed for low-latency processing.
Expansion of Internet Infrastructure and New Submarine Cables
Malaysia’s participation in SEA-ME-WE 6 and other cable systems strengthens its interconnection profile, creating server demand for transit traffic and CDN nodes.[3]Submarine Networks, “SEA-ME-WE 6 Cable Route Update,” submarinenetworks.comTelekom Malaysia’s fiber expansion and DE-CIX’s peering fabric enhance route diversity and drive purchases of high-throughput network servers needed for traffic aggregation
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High CapEx for facility & server procurement | -2.1% | National, particularly affecting SME adoption | Short term (≤ 2 years) |
| FX-linked cost risk from imported hardware | -1.8% | National, with higher impact on price-sensitive segments | Medium term (2-4 years) |
| 2027 electricity-tariff reform cutting industrial subsidies | -2.3% | National, concentrated in energy-intensive facilities | Medium term (2-4 years) |
| Land scarcity in Greater Kuala Lumpur inflating real-estate costs | -1.4% | Regional, primarily affecting Klang Valley developments | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
2027 Electricity-Tariff Reform Cutting Industrial Subsidies
TNB lifted the base tariff 14.2% to 45.62 sen/kWh from July 2025, while future fuel-cost pass-throughs compound uncertainty. Data-center loads could constitute 38.37% of peak-demand growth by 2030, so operators now prioritise server models with higher performance-per-watt and explore direct renewable-energy contracts under CRESS.[4]U.S. Department of Commerce, “Corporate Renewable Energy Supply Scheme Explained,” trade.gov Vendors offering liquid-cooled, high-efficiency systems stand to benefit.
High CapEx for Facility & Server Procurement
Advanced AI servers such as Nvidia’s GB300 NVL72 can cost between USD 3.7-4 million per node, while liquid-cooling retrofits add up to 30% to build costs. Semiconductor tightness prolongs lead times, pushing some buyers to dual-source from Taiwanese ODMs setting up Johor factories. Green financing—exemplified by Princeton Digital’s USD 280 million sustainability-linked loan—offers partial relief but not enough to offset capital barriers for smaller entrants.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Data-Center Tier: Mission-Critical Tier 4 Drives Growth
Tier 3 facilities dominated the Malaysia data center server market share at 70.92% in 2025, supported by banking, telecom, and public-sector workloads that demand high availability. Parallelly, Tier 4 sites are outpacing overall growth at an 18.33% CAGR, reflecting hyperscaler insistence on five-nines uptime for AI training clusters. Vantage’s Cyberjaya and Princeton Digital’s JH1 campuses exemplify the Tier 4 blueprint, featuring redundant power and chilled-water loops to sustain racks exceeding 70 kW.
The Malaysia data center server market is thus bifurcating: Tier 1-2 footprints meet edge and disaster-recovery needs, whereas Tier 3-4 facilities capture long-term, mission-critical demand. Tier 4’s momentum also aligns with the 2026 green-tax credit that rewards high-efficiency hardware, nudging enterprises toward the latest processor generations and cooling techniques.


By Form Factor: Micro-Blades Gain Edge-Computing Traction
Half-height blades held 62.54% revenue in 2025 courtesy of their familiarity, balanced thermals, and integration ease into legacy racks. Yet quarter-height micro-blades are expanding at a 16.61% CAGR, propelled by 5G backhaul rollouts and regional MEC nodes that require compact, ruggedised servers. Intel’s 5G Digital School venture in Penang showcases micro-blade edge clusters providing AI-enabled educational content with minimal latency.
Within hyperscale halls, full-height blades and GPU trays dominate AI training, but operators simultaneously procure micro-blades for latency-sensitive inference tasks. Consequently, server vendors increasingly market unified chassis able to host mixed-blade heights, lowering spares inventories and accelerating deployment—an advantage in Malaysia data center server market procurement cycles.
By Application/Workload: AI Dominance Reshapes Server Requirements
Artificial-intelligence workloads captured 34.88% of the Malaysia data center server market size in 2025 as sovereign-AI investments converged with private-sector adoption. NVIDIA-Blackwell-based racks slated for late-2025 delivery will intensify GPU attachment ratios, driving power densities past 40 kW per rack. Virtualization and private-cloud stacks nevertheless register the quickest 16.94% CAGR, fuelled by enterprises modernising ERP and productivity suites.
Smart hospitals, industrial IoT, and BFSI analytics join the demand queue, dictating heterogeneous server fleets blending GPU-rich, CPU-dense, and storage-heavy nodes. This workload mix shifts purchasing priorities toward configurable motherboards, higher memory bandwidth, and front-serviceable NVMe drives that enhance uptime in Malaysia data center server market deployments.
By Data-Center Type: Hyperscalers Accelerate Market Transformation
Colocation operators retained 56.62% of the Malaysia data center server market size in 2025, offering enterprises scale minus ownership risks. Hyperscalers, however, are marching at an 18.21% CAGR as Google, Microsoft, Oracle, and Chinese cloud giants secure multibillion-dollar land banks around Johor and Cyberjaya. Dedicated halls outfitted for liquid cooling, single-phase immersion, and 21-inch OCP racks make hyperscaler campuses the bellwether for next-generation server specs.
Edge and enterprise self-builds continue in verticals such as manufacturing where low-latency control loops are mission-critical. The coexistence of colocation and hyperscale footprints creates a layered market structure in which vendors must cater simultaneously to turnkey colocation SKUs and highly customised hyperscale bill-of-materials.
By End-Use Industry: Manufacturing Digitisation Drives Server Demand
IT & telecom remained top buyers with 37.32% share in 2025, investing in NFV, 5G core, and content-delivery nodes. Manufacturing workloads tied to Industry 4.0 and predictive-maintenance initiatives are forecast to climb 17.21% CAGR as semiconductor fabs, E&E clusters, and automotive suppliers adopt AI-powered quality control. Malaysia’s social-security agency PERKESO’s shift to Red Hat platforms illustrates how public services reduce manual processes and increase online interaction for citizens.
Healthcare posts double-digit growth through telehealth and smart-hospital roadmaps, while BFSI continues to refresh servers for real-time fraud analytics and open-banking APIs. Government ministries, under MyDIGITAL, increasingly stipulate domestic data-residency, thereby channeling fresh spend into local server halls.
Geography Analysis
Johor dominates new-build momentum, courtesy of abundant land and a one-stop approval desk that shortens project timelines. Mega-campuses from ByteDance, Microsoft, and Oracle substantiate the region’s transition from manufacturing hub to global digital-infrastructure node. Larger parcels also permit on-site solar arrays and battery-energy storage, aligning with ESG mandates.
Selangor, anchored by Cyberjaya and Greater Kuala Lumpur, remains Malaysia’s flagship data-center corridor. High dark-fiber density and proximity to governmental agencies keep utilisation high, though land scarcity inflates plot prices and nudges expansions toward the fringes of Klang Valley. Sustainability programs aimed at achieving carbon neutrality by 2030 attract operators seeking credible green-power pathways.
Penang, Sarawak, and other Tier-2 cities emerge as edge-centric zones. Penang leverages its semiconductor ecosystem to pilot low-latency education and industrial IoT workloads, while Sarawak’s first wholesale facilities cater to Borneo’s connectivity uplift. Lower real-estate costs and fresh renewable-energy potential open the door for sovereign-fund micro-hubs that feed regional redundancy needs.
Regulatory Landscape
Malaysia is tightening governance for data-center buildouts through a multi-agency approval and sustainability framework that directly affects server procurement and deployment timing. MITI and the Ministry of Digital set up a Data Centre Task Force (DCTF) in February 2025 to evaluate and approve new projects, with approvals tied to demonstrated availability of energy and water resources; in July 2026, MITI reiterated that data-center approvals depend on energy and water supply availability. Complementing the gatekeeping mechanism, the 2024 Final Guidelines for Sustainable Data Centre and related guidance for sustainable development embed performance requirements such as PUE and WUE benchmarks (including a recommended design WUE of 2.2 or lower), pushing operators toward higher-efficiency server platforms and thermal designs.
On incentives, Malaysia uses investment and tax-support mechanisms to steer build quality and local participation. The Digital Ecosystem Acceleration (DESAC) scheme provides tax incentives for eligible digital-infrastructure projects, including data centers, and applications for DESAC tax incentives are open until 31 December 2027. Policy direction also includes restrictions on approvals for non-AI data centers to conserve resources, aligning the regulatory environment with AI-oriented deployments that typically demand higher-density, more power-efficient server configurations and stronger lifecycle energy management.
Competitive Landscape
Competition is moderate. Dell Technologies, Hewlett-Packard Enterprise, and Cisco Systems still command large enterprise refresh cycles. Yet AI workloads grant share gains to Supermicro, Wiwynn, and other ODMs that offer GPU-dense, liquid-ready chassis at aggressive lead times.
Chinese vendors Huawei, Inspur, and Lenovo gain traction through cost-advantaged offers and local assembly commitments, dovetailing with Malaysia’s sovereign-AI agenda. Nvidia’s reference designs influence BOM choices among hyperscalers, pushing x86 CPU vendors toward accelerator-friendly motherboards.
Supply-chain localisation intensifies: Wiwynn’s Johor plant and potential module lines from Inventec lower shipping costs and buffer geopolitical risk for operators sourcing servers in Malaysia data center server market deployments. Energy-efficiency regulations further shape vendor line-ups, rewarding those who meet next-gen performance-per-watt thresholds.
Malaysia Data Center Server Industry Leaders
Dell Technologies
Hewlett Packard Enterprise
Cisco Systems
Huawei Technologies
Lenovo Group
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A visible whitespace area is the shift from pure capacity build to compliance-led, efficiency-led refresh cycles under Malaysia’s sustainability guidelines and approval conditions, which increases demand for higher-efficiency server configurations and liquid-ready platforms. The 2024 sustainable data-center guidelines (PUE/WUE benchmarks, including recommended design WUE of 2.2 or lower) and MITI’s 2026 emphasis that approvals depend on energy and water availability reinforce procurement preference for performance-per-watt improvements, workload consolidation, and accelerator-optimized infrastructure. In parallel, DESAC tax incentives (open until 31 December 2027) create room for vendors and integrators to package compliant server stacks with power, cooling, and monitoring solutions that align with project-approval requirements.
Malaysia is also using investment-led programs to deepen domestic participation, creating openings beyond the server box across supporting infrastructure tied to server deployments. MIDA reported RM34.6 billion of approved investments in data centers and cloud computing in Q1 2026 across 33 projects, and the government has articulated a 40% local participation target in data-center development, which elevates demand for local system integration, electrical and cooling components, and engineering services alongside server rollouts. This supports opportunities for ecosystem players in cooling and facilities systems (for example, local HVAC/cooling suppliers such as Dunham-Bush Industries), structured cabling and network infrastructure partners, and talent development collaborations with universities and technical institutes that can supply data-center operations and IT engineering capabilities needed to run high-density AI and hybrid-cloud server environments.
Recent Industry Developments
- July 2026: AirTrunk secures up to 175 million financing from IFC to expand its data center facilities in Johor, totaling 420 MW. The funding supports large-scale capacity expansion in Johor and reinforces the region as a regional AI and cloud hub. The move aligns with high-density capacity needs and accelerates green, scalable data-center growth in Malaysia.
- July 2026: TM Nxera (Telekom Malaysia & Singtel Nxera JV) tops out a data center facility in Iskandar Puteri, Johor, marking the initial 64 MW phase. The completion adds near-term operational capacity in a key Johor campus. This progress accelerates Malaysia’s hyperscale footprint and AI-ready infrastructure readiness in Iskandar Puteri.
- July 2026: DayOne Data Centers agrees to acquire a 65-acre land parcel in Iskandar Puteri, Johor for RM398 million to support data center development. The land bank strengthens Johor as a major data center hub with expanded development potential. The acquisition broadens the opportunity pipeline for future capacity additions in the region.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers the value of servers purchased and deployed inside data centers located in Malaysia, including new installations and refresh demand linked to capacity expansions and technology upgrades.
Scope exclusions: We exclude enterprise on-premise server rooms that are not operated as data centers, along with networking gear, storage systems, and services such as colocation, cloud subscriptions, and managed hosting.
Segmentation Overview
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- Other End Users
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the Malaysia country context and build the first cut of demand signals that typically move server buying. We relied on public Malaysia-focused sources such as Department of Statistics Malaysia releases, Bank Negara Malaysia macro indicators, the Malaysian Communications and Multimedia Commission updates, and customs trade statistics to sense-check hardware inflows.
To connect demand with supply-side realities, we also reviewed data center permit and infrastructure announcements from public agencies, investor presentations and annual reports, and credible press coverage on new facility launches. When paid subscriptions were available, they were used mainly for company financials and intelligence, news and financials, and patent databases, to validate expansion timing and technology shifts. This desk list is illustrative, and many other public and paid sources were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work was used to pressure-test assumptions that usually do not show up clearly in public data, such as refresh cycles, average selling price movement, and the split between general compute and higher density configurations. We spoke with a mix of data center operators, system integrators, channel partners, and large enterprise buyers across Malaysia, so demand drivers from both hyperscale and colocation sites, as well as enterprise workloads, were reflected in the final model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 28% | CXOs: 18% |
| Mid tier: 53% | Functional/Unit leaders: 33% |
| Smaller Players: 19% | Managers: 49% |
Market-Sizing & Forecasting
Sizing started with a top-down build where Malaysia data center activity was translated into server demand using practical usage ratios and procurement behavior described by interviewees. We then checked those outputs with selective bottom-up approximations, such as sampled price per server by form factor and application, along with channel checks on shipment momentum, before adjusting totals to a consistent scope.
Key inputs used in the model included live and pipeline data center capacity in Malaysia, expected rack density ranges by data center type, typical refresh and replacement timing, workload mix shifts (including virtualization and AI-oriented deployments), and average selling price changes driven by configuration choices and currency timing. Where gaps existed for smaller sites and private builds, assumptions were filled using ranges agreed during primary discussions and then narrowed using import signals and project-level announcements.
Forecasts were produced using scenario analysis. The base case was anchored on committed capacity additions and realistic refresh behavior, and then stress-tested with higher and lower adoption paths based on power availability, permitting pace, and buildout schedules that respondents described from their own build plans.
Data Validation & Update Cycle
Outputs were validated through repeated cross-checks against independent signals, including data center capacity additions, major project timelines, and hardware import direction, followed by internal variance checks across segments and years. When a metric moved outside an expected range, the assumptions were reviewed again, and selected primary contacts were re-engaged to confirm whether it reflected a real market shift or an incorrect input.
Before sign-off, the model and key assumptions go through multi-step analyst review so calculation logic, unit consistency, and currency handling are aligned. Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery pass completed so clients receive the latest view available.
黑料不打烊's Malaysia Data Center Server Market Size Compared With Other Published Estimates
Published market sizes can differ even when the same country and topic are being discussed, mainly because the scope boundary and price logic are not always handled the same way. For data center servers, the biggest spreads usually come from whether adjacent data center IT items are mixed in, and whether the estimate is tied to installed capacity signals or extrapolated from broader IT spending.
The benchmark table shows a clear spread across sources. In 黑料不打烊's model, the value is counted only for server hardware deployed within Malaysia data centers, which avoids blending in storage, networking, or data center construction spend. Differences also arise when some estimates apply aggressive price escalation for high-density configurations without validating refresh timing, or when older exchange rates and older project pipelines are carried forward without a fresh check against new campus announcements and commissioning delays.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 2.22 B (2025) | |
| Industry Research Publisher A | USD 1.40 B (2026) | Uses a later starting year and often relies on broader IT hardware demand signals, which can undercount near-term server refresh tied to new data center capacity coming online. |
| Market Bulletin B | USD 3.00 B (2025) | Likely blends adjacent data center IT categories or applies a high ASP uplift across all deployments, which can overstate value if configuration shifts are not separated by site type and application. |
Taken together, the spread is mainly explained by what gets included around servers and how pricing and refresh cycles are treated in each model. By keeping assumptions tied to capacity additions, realistic rack densities, and interview-led refresh behavior, the approach here stays traceable to clear variables and can be repeated as new builds and upgrades are announced.


Key Questions Answered in the Report
What is the current size and growth outlook for the Malaysia data center server market?
The market stands at USD 2.59 billion in 2026 and is projected to reach USD 5.53 billion by 2031, registering a 16.42% CAGR over the forecast period.
Which workloads are driving the highest demand for servers in Malaysia?
AI and machine-learning workloads lead with 34.88% share in 2025, while virtualization and private-cloud workloads are the fastest-growing at a 16.94% CAGR through 2031.
Why is Johor emerging as Malaysia’s primary data-center hub?
Johor offers lower land costs, streamlined approvals, and proximity to Singapore, helping it reach 1.6 GW live capacity and making it the focal point for hyperscale projects.
What government incentives support continued server investment?
The MyDIGITAL cloud-first policy, green tax credits for high-efficiency servers starting 2026, and the Corporate Renewable Energy Supply Scheme collectively encourage sustained infrastructure upgrades.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Netherlands Data Center Power Market The Netherlands power systems, split by component, facility type and facility size.
- Taiwan Hyperscale Data Center Market Taiwan hyperscale sites, split by facility type, component and tier.
- India Data Center Rack Market India's racks, split by rack size, rack type and cooling compatibility.
- China Data Center Cooling Market China cooling, split by facility type, tier and cooling technology.
- Malaysia Hyperscale Data Center Market Hyperscale sites demand across Malaysia, covering facility type, component and tier.
- Thailand Hyperscale Data Center Market Thailand's hyperscale sites, split by data centre type, component and tier.
- Malaysia Data Center Power Market Power systems in Malaysia, split by component, facility type and facility size.
- Taiwan Data Center Construction Market Construction demand across Taiwan, covering tier.



