
Taiwan Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.94 Billion |
| Market Size (2026) | USD 1.03 Billion |
| Market Size (2031) | USD 1.64 Billion |
| Growth Rate (2026 - 2031) | 9.79 % |
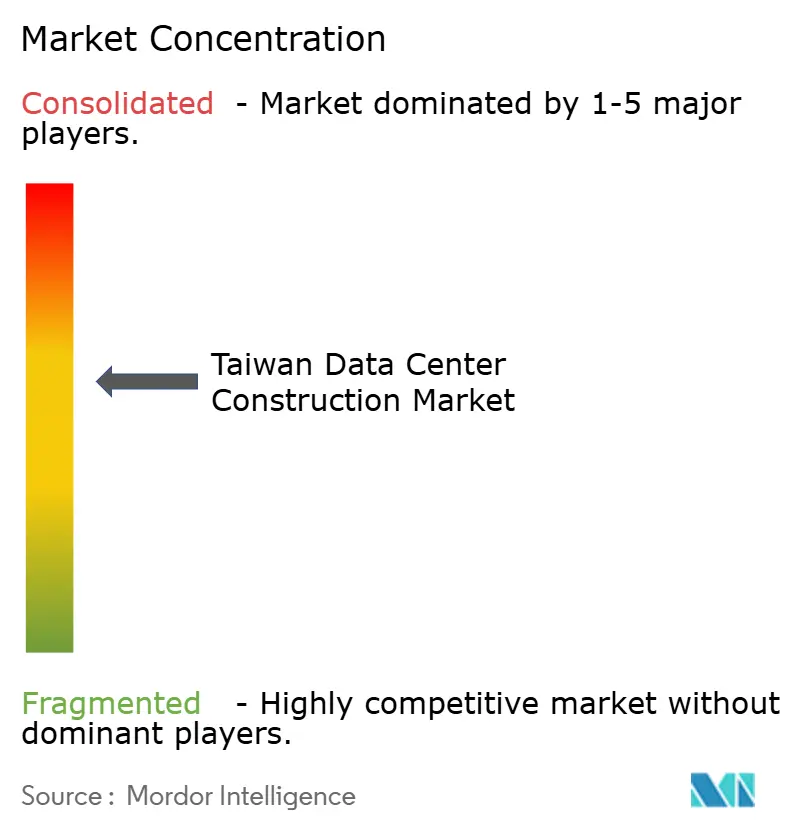
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |

Taiwan Data Center Construction Market Analysis by 黑料不打烊
The Taiwan data center construction market size was valued at USD 0.94 billion in 2025 and estimated to grow from USD 1.03 billion in 2026 to reach USD 1.64 billion by 2031, at a CAGR of 9.79% during the forecast period (2026-2031). This momentum is fueled by Taiwan’s role as a linchpin in the global AI and semiconductor supply chain, its maturing sovereign-AI strategy, and a nationwide shift toward edge computing that is reshaping infrastructure demand. Accelerating cloud-service adoption, dense 5G coverage, and 14 international submarine cables are enabling low-latency connectivity that supports cross-border workloads. Cooling innovation, renewable-energy procurement, and battery energy-storage pilots are addressing power density and sustainability challenges. Meanwhile, geopolitical risk is prompting hyperscalers to prioritize sovereign capacity that can operate independently from external jurisdictions, driving continued private and government capital inflows into the Taiwan data center construction market.
Key Report Takeaways
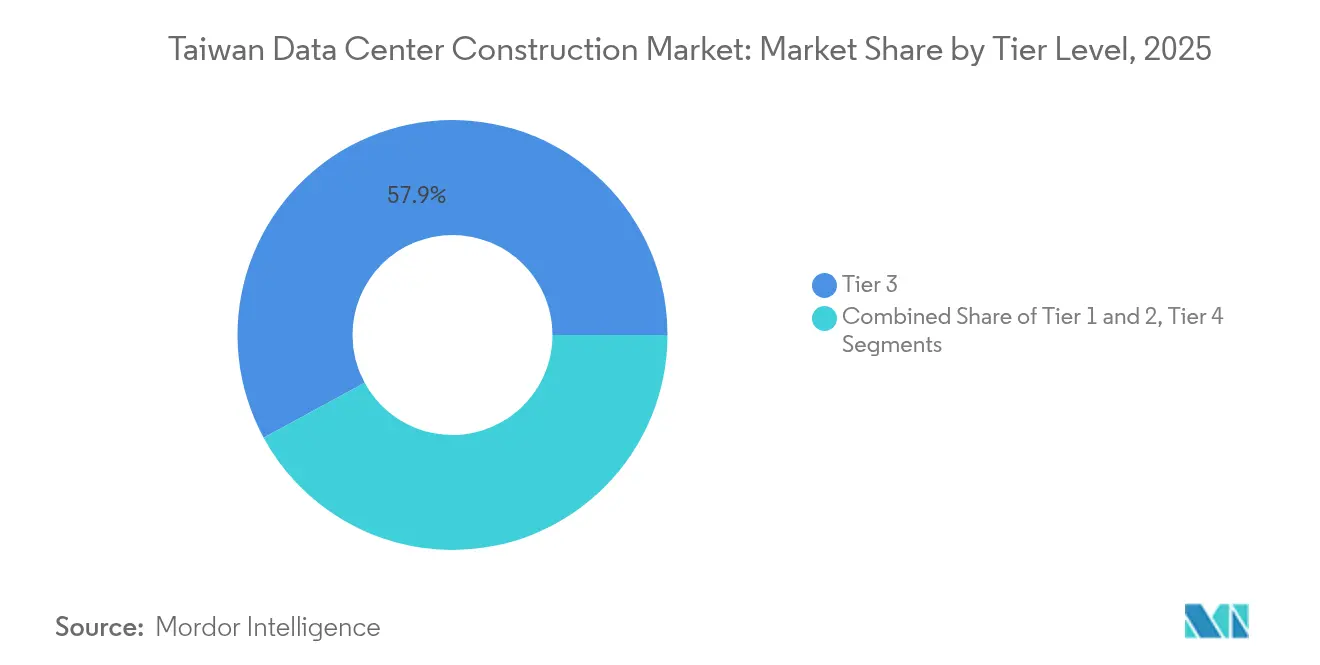
- By tier type, Tier 3 facilities led with 57.92% revenue share in 2025; Tier 4 installations are projected to advance at a 9.86% CAGR through 2031.
- By data center type, colocation held a 53.95% share of the Taiwan data center construction market size in 2025, while self-built hyperscalers are expected to grow at a 10.04% CAGR.
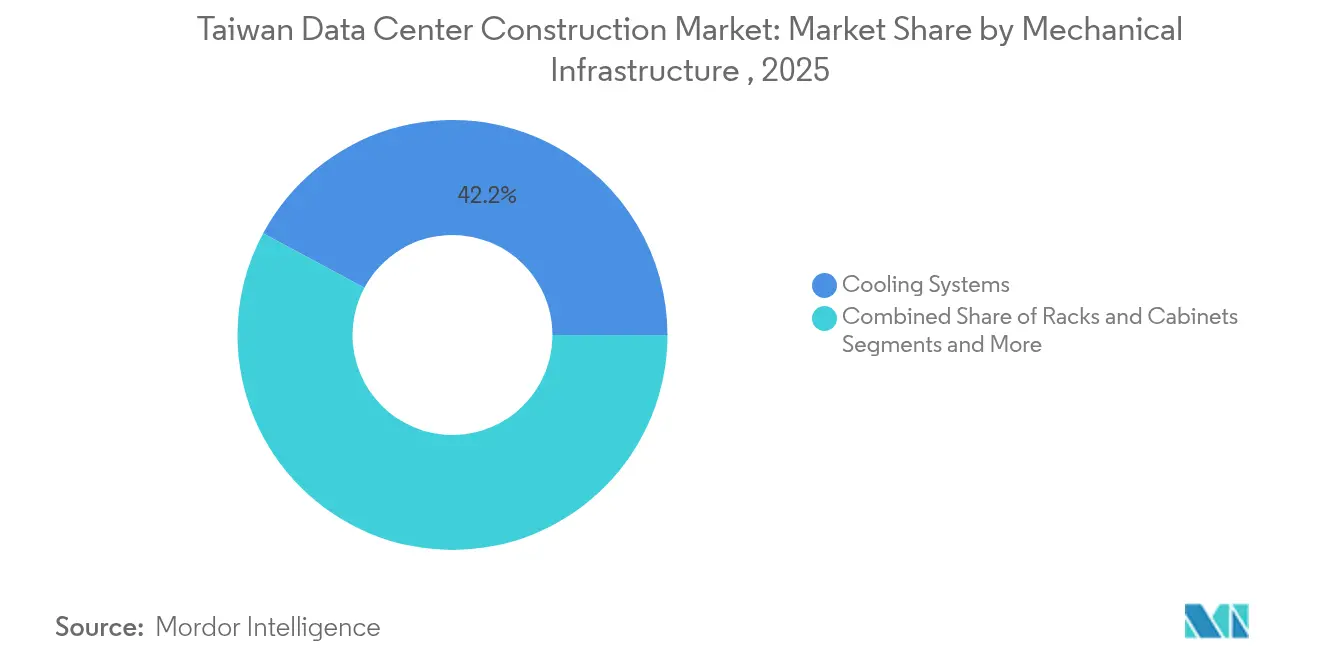
- By mechanical infrastructure, cooling systems accounted for 42.15% share of the Taiwan data center construction market size in 2025; servers and storage components are developing at a 10.34% CAGR.
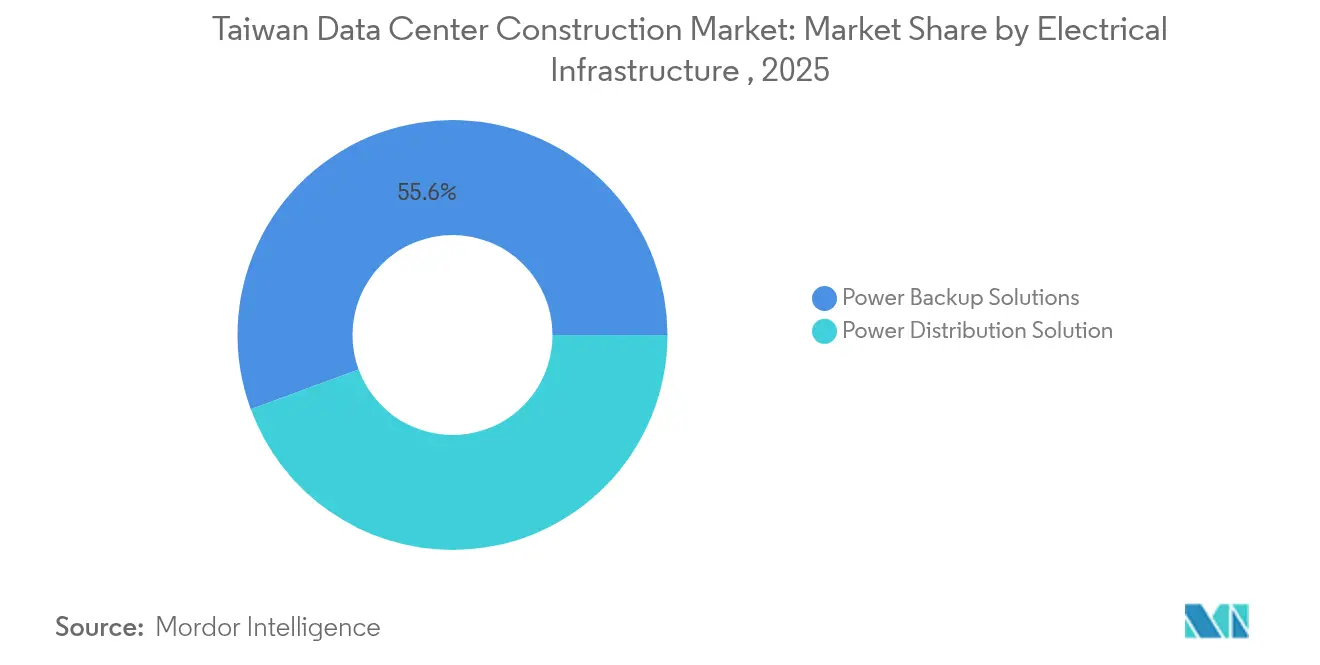
- By electrical infrastructure, power backup solutions captured 55.62% of the Taiwan data center construction market share in 2025, whereas power-distribution solutions are expanding at an 10.98% CAGR.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Taiwan Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing cloud-service adoption | +2.8% | Taipei metro, Hsinchu Science Park | Medium term (2-4 years) |
| 5G rollout and national digitisation initiatives | +2.1% | Taipei, Taichung, Kaohsiung | Short term (≤ 2 years) |
| Government tax-rebate programme for green DC builds | +1.5% | Science parks and industrial zones | Long term (≥ 4 years) |
| Semiconductor-driven edge/AI workload localisation | +3.2% | Hsinchu, Taichung, expanding to Tainan | Medium term (2-4 years) |
| New submarine-cable landings lowering latency | +1.8% | Northern and central coastal regions | Long term (≥ 4 years) |
| Grid-level BESS pilots enabling >50% renewable integration | +1.4% | Yilan, Hsinchu, Taoyuan, Tainan | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Growing Cloud-Service Adoption
Cloud-service penetration is extending beyond conventional enterprise migrations as data-sovereignty policies mandate local processing of sensitive IP and citizen data. Amazon Web Services committed USD 5 billion for its first Taiwanese region with three availability zones, confirming long-term confidence in the Taiwan data center construction market.[1]Tim Culpan, “AWS to invest USD 5 billion in Taiwan region,” aws.amazon.comHybrid and multi-cloud strategies dominate in semiconductor design, where air-gapped networks and low-latency connections to nearby fabs remain essential. Colocation operators are adding direct cloud on-ramp nodes that satisfy both compliance and performance needs. Government programs aiming for 80% uptake of digital lifestyle services further guarantee demand for scalable facilities.
5G Rollout and National Digitization Initiatives
Taiwan achieved 94% 5G coverage in 2024, and more than 16,000 base stations now blanket the island, creating a foundation for edge-computing workloads that must be processed locally within milliseconds. Telecoms such as Chunghwa Telecom have coupled 5G with all-photonics backbone networks and low-earth-orbit satellite backup, reducing latency for critical applications. Smart-manufacturing pilots that rely on 5G edge nodes have already cut traffic-signal wait times by 35%, proving the practical value of micro data centers in urban corridors.
Government Tax-Rebate Programme for Green DC Builds
A tiered incentive grants 5%–20% tax credits on capital and operational expenditure for data centers that achieve stringent PUE and renewable-energy goals.[2]Ministry of Finance R.O.C., “Green data center tax incentives,” mof.gov.tw Google’s 500 MW offshore-wind PPA with Copenhagen Infrastructure Partners underscores how foreign operators leverage the scheme to green their footprints. Facilities meeting Taiwan’s EEWH Gold or Diamond standards can tap accelerated depreciation, which lowers build-out payback periods and propels the Taiwan data center construction market toward more sustainable designs.
Semiconductor-Driven Edge/AI Workload Localization
Taiwan Semiconductor Manufacturing Company is adding 11 wafer-fabrication plants and four advanced-packaging lines that must interface with design verification and AI training clusters on-site. AI inferencing adjacent to fabs reduces design turnaround and IP-leak risk, prompting demand for high-tier facilities equipped with precision cooling and seismic damping. Government-backed sovereign-AI projects plan 1,200 petaflops of public compute by 2029, cementing a long runway for the Taiwan data center construction market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid-power scarcity and volatile electricity pricing | -2.4% | Island-wide, acute in science parks | Short term (≤ 2 years) |
| Scarce land and escalating Taipei metro real-estate costs | -1.8% | Taipei, New Taipei, Taoyuan | Medium term (2-4 years) |
| High seismic-design CAPEX for Tier III/IV facilities | -1.2% | Seismic zones nation-wide | Long term (≥ 4 years) |
| Slow EIA permitting for hyperscale campuses | -0.9% | Projects above 50 MW | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Grid-Power Scarcity and Volatile Electricity Pricing
Electricity demand is expected to climb 12%–13% by 2030, largely from AI compute clusters.[3]Energy Administration, “Electricity demand forecast 2025-2030,” energy.gov.tw Imported fossil fuels still make up 83% of the energy mix, exposing operators to commodity-price swings and supply risks. Battery-energy storage rollouts totaling 160 MW offer limited relief. Repeated summer reserve-margin shortfalls are forcing projects to integrate on-site solar, wind, and liquid-cooling systems that cut facility power envelopes. Those mitigation costs temporarily weigh on the Taiwan data center construction market, yet they also accelerate the adoption of more efficient designs.
Scarce Land and Escalating Taipei Metro Real-Estate Costs
Downtown parcel scarcity is pushing new builds toward Taoyuan, Taichung, and Kaohsiung. Amazon Web Services chose a suburban Taoyuan industrial park for its region, reflecting the pivot to locations that balance cost and fiber proximity. Science parks provide pre-approved zoning, though competition with semiconductor expansions intensifies bidding. Developers respond with multi-story layouts and higher rack densities to maximize limited footprints, a trend that is now standard across the Taiwan data center construction market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Tier 4 Growth Accelerates Despite Tier 3 Dominance
Tier 3 facilities maintained a 57.92% stake of the Taiwan data center construction market in 2025, signaling client preference for balanced uptime and cost. This translates to the largest contribution to the overall Taiwan data center construction market size. Financial institutions, hyperscalers, and government bodies, however, are driving Tier 4 demand with an anticipated 9.86% CAGR. Seismic-resistant engineering that surpasses nuclear-plant standards is mandatory, and builders employ viscous-fluid dampers and dual active-active grids to meet Tier 4 certification.
Seismic retrofits for older Tier 3 shells allow modular upgrades to near-Tier 4 capability, illustrating a shift toward resilient brownfield expansion. Contract-win criteria now emphasize verifiable seismic isolation and in-rack liquid cooling. Builders adding these features position themselves for higher-margin Tier 4 contracts, reinforcing a premium tier that the Taiwan data center construction market will continue to reward as AI workloads intensify.


By Data Center Type: Hyperscaler Self-Build Momentum Challenges Colocation Leadership
Colocation retained 53.95% of 2025 revenue as SMEs and semiconductor suppliers favor shared facilities for cost control. This portion underscores how colocation remains a linchpin in the Taiwan data center construction market. Nevertheless, self-built hyperscaler campuses are set to outpace all other formats at a 10.04% CAGR. Amazon, Google, and Microsoft increasingly favor outright ownership to secure compliance and optimize AI training clusters, bringing bespoke power and cooling.
Enterprise edge deployments are evolving fastest in design. Telecoms are installing micro data centers at 5G base stations to host latency-sensitive workloads. These edge nodes feature prefabricated, two-rack enclosures with integrated liquid cooling, reflecting how diversified architectures extend the physical scope of the Taiwan data center construction market.
By Electrical Infrastructure: Power Distribution Innovation Drives Grid Modernization
Backup generators, UPS strings, and static transfer switches formed 55.62% of the 2025 spend, illustrating the priority placed on availability. Battery-storage pilots are embedding lithium-iron-phosphate chemistries that allow rapid response to grid disturbances. Power-distribution units are on a trajectory to log 10.98% CAGR, lifted by smart-switchgear adoption that mitigates intermittent renewable feeds.
Projects now require busway systems rated above 6,000 A and intelligent power quality monitoring. These specifications are becoming the baseline for any facility seeking long-term power purchase agreements tied to renewables. The electrical segment, therefore, stands at the forefront of technological upgrades that buttress the Taiwan data center construction market.
By Mechanical Infrastructure: Cooling Innovation Responds to AI Density Demands
Cooling represented 42.15% of mechanical spend in 2025, and immersion plus direct-to-chip solutions are gaining ground. Liquid cooling removes thermal limits that once capped rack power at 15 kW; Foxconn’s upcoming 100 MW supercomputing center will run at over 70 kW per rack. Servers and storage sub-systems will exhibit 10.34% CAGR because advanced GPUs and high-bandwidth memory demand bespoke configurations.
Vendors are shipping compact brushless pumps and integrated CDU-plus-rack assemblies that can be field-retrofit, letting legacy sites raise densities without floor-plan increases. Such innovations demonstrate why thermal management continues to define competitive differentiation in the Taiwan data center construction market.
Geography Analysis
Taipei and New Taipei host the highest facility count, leveraging dense fiber backbones and financial-sector proximity. However, land costs and grid constraints encourage a southward migration. Hsinchu Science Park links directly to semiconductor fabs, which fuels the fastest regional facility additions at mid-double-digit megawatt bookings. Taichung offers lower real-estate prices and grid headroom, functioning as a central corridor that bridges northern and southern workloads.
Southern Taiwan Science Park in Tainan benefits from government plans to install a 120-petaflop AI center by 2025 and a sovereign-cloud complex by 2029, both of which anchor forthcoming demand. Offshore-wind zones along the west coast supply up to 500 MW of contracted energy for hyperscale campuses, aligning geography with renewable goals. Coastal cable-landing stations at Toucheng, Fangshan, and Tamsui safeguard latency to North Asia and the United States, ensuring that distributed builds still maintain carrier-neutral reach.
Reclaimed-water programs and desalination plants add 628,100 tons per day of non-potable water, guaranteeing chiller make-up for high-density sites. This resource diversification further stabilizes operational risk across the Taiwan data center construction market. As a result, Taiwan is evolving from a single-hub model into a three-node topology of north, central, and south that balances power, land, and connectivity.
Regulatory Landscape
Taiwan data center construction is increasingly shaped by energy efficiency and power-allocation controls led by the Ministry of Economic Affairs (MOEA) and the Energy Administration. For hyperscale and colocation facilities with energy consumption of 5 MW or above, developers must prepare and submit Energy Utilization Manuals and adopt Best Available Techniques, with PUE benchmarks referenced at 1.3 for hyperscale and 1.4 for colocation. On the supply side, Taipower has constrained new power applications above 5 MW in areas north of Taoyuan since August 2023, which affects site selection and sequencing where approvals and grid access are feasible.
For digital infrastructure linked to public-sector compute, the Ministry of Digital Affairs (MODA) sets additional compliance requirements, including alignment with the Cyber Security Management Act for national AI computing power centers. In July 2026, a draft amendment to the large-load review process broadened evaluation indicators to cover investment output, job creation, supply-chain contribution, AI ecosystem support, and cybersecurity resilience. This updates how large-scale data center projects are reviewed beyond energy use.
Value Chain Analysis
The Taiwan data center construction value chain begins with site origination and feasibility (land, grid access, and permitting), followed by design and engineering, procurement, construction, commissioning, and ongoing operations support. Local and international EPC and engineering firms play a central role in translating client requirements into Tier III and Tier IV-ready builds. CTCI supports end-to-end EPC delivery for data centers, including a referenced 16 MW TPE11 project, while Exyte provides global engineering, construction, and commissioning services backed by local presence for complex, high-spec programs.
On the infrastructure and integration side, TECO contributes MEP scope across electrical and HVAC, along with transformers rated up to 150/161 kV and modular data center solutions that can shorten schedules for edge and campus expansions. Downstream integration combines AI server racks and high-density white-space fit-out with power infrastructure (UPS systems, switchgear, transformers) and cooling systems (closed-loop water and air-cooled chiller architectures). Commissioning, monitoring, and O&M digitization are increasingly embedded into delivery to manage efficiency constraints and uptime requirements.
Competitive Landscape
The Taiwan data center construction market features a mid-level concentration where local EPC firms, international engineering specialists, and equipment vendors converge. United Integrated Services, TECO, and CTCI hold large backlogs linked to semiconductor clients, while global groups such as Exyte bring clean-room pedigrees required for on-fab data halls. Schneider Electric, ABB, and Delta Electronics embed power and cooling gear, bundling design-build packages that shorten project delivery.
Sustainability credentials increasingly decide bid outcomes. Firms demonstrating sub-1.3 PUE designs and renewable-PPA arrangements gain preferred-vendor status under Taiwan’s green-build incentives. Liquid-cooling consortia comprising Foxconn, Nvidia, and CoolIT Systems showcase the synergy between hardware providers and general contractors. Edge-facility specialists like Advantech are partnering with telecoms to deploy containerized units that align with 5G rollouts.
Taiwan Data Center Construction Industry Leaders
TECO Corporation
CTCI Group
M+W Group
Exyte
AECOM
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Policy-linked compute buildouts and tighter energy governance are creating whitespace for developers and contractors that can deliver measurable efficiency and compliance outcomes. MODA BOO procurements for AI computing power centers set a defined entry bar, at least 15 PetaFLOPS (FP32) and investment exceeding NT$300 million (excluding land), which favors turnkey consortia that can combine facility delivery, high-density thermal design, and cybersecurity-ready operations. Alongside this, Energy Administration requirements tied to Energy Utilization Manuals for 5 MW-plus sites, plus PUE benchmarks (1.3 for hyperscale and 1.4 for colocation), are sustaining demand for advanced cooling, power-train optimization, and verifiable commissioning and monitoring packages.
There is also room in modularization and repeatable, AI-ready designs that reduce schedule risk under constrained land and power conditions. A visible signal is TECO's strategic alliance with Foxconn on integrated modular AI data center solutions for hyperscalers, aligning construction methods with higher rack densities and faster deployment. In addition, the July 2026 assessment of large-scale approvals using indicators that include supply-chain benefits and cybersecurity resilience increases the premium on local sourcing, resilient operations design, and partners that can document economic and ecosystem contributions alongside technical performance.
Recent Industry Developments
- July 2026: Secured financing with Nomura for the first phase of an 80MW data center campus in North Taiwan, in partnership with Keppel Data Centre Fund II and contracted to a global hyperscale customer. The financing for large-scale capacity expansion accelerates hyperscale campus development in North Taiwan and underlines private funding for AI/large-scale DL workloads.
- May 2026: TECO Corporation boards approved and signed an acquisition agreement with Malaysia-based Dynaciate Engineering Sdn. Bhd. to accelerate Southeast Asia AI data center infrastructure expansion, expected to close by end-August 2026. The acquisition expands TECO's regional data center capabilities and Southeast Asia pipeline, expanding capabilities beyond Taiwan.
- March 2026: Chief Telecom board of directors approved an investment exceeding NT$3 billion (US$93.5 million) for a fourth AI data center at the Central Taiwan Science Park. The investment strengthens Taiwan’s AI data center capacity at a key park, signaling continued operator-led capacity buildup near semiconductors and AI demand.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers the value of building and fitting out data center sites in Taiwan, including electrical and mechanical systems that make the facility operational, along with construction activity tied to new builds and expansions.
Scope exclusions: It does not count ongoing colocation service revenue after commissioning, routine facilities management, or IT hardware such as servers and storage.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
- Tier 1 and 2
Data Sources, Market Sizing, and Validation
Desk Research
We start by mapping Taiwan data center build activity to measurable public signals, then we use those signals to set reasonable ranges for capacity additions, timing, and cost intensity. Desk research also helps us understand permitting and power constraints, since these can move construction schedules and affect how spending shows up across years.
Sources reviewed include official and non-paywalled references such as Taiwan government energy and power statistics, construction and building-permit releases, and telecom and digital infrastructure updates. We also use company filings and investor presentations, association websites, and reputable press coverage to cross-check project announcements and delivery timelines. Where needed, paid subscriptions are used for company financials, patent lookups for cooling and power equipment direction, and shipment-level trade checks to validate major equipment flow patterns. We also review trade and customs summaries where equipment imports indicate build cycles. These examples are illustrative only, and many additional sources were consulted to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Interviews and surveys with construction providers, infrastructure suppliers, facility operators, and project managers in Taiwan are used to clarify cost, timing, power, and cooling inputs that are missing from public records. Respondents also help test project-stage assumptions and distinguish construction work from bundled equipment or operating spend. Conflicting responses are rechecked before the final analysis.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 20% |
| Mid tier: 45% | Functional/Unit leaders: 30% |
| Smaller Players: 25% | Managers: 50% |
Market-Sizing & Forecasting
Our core build uses a top-down approach in which planned and under-construction capacity additions are reconstructed from project pipelines, expected commissioning windows, and typical cost per MW ranges for Taiwan site conditions. We then stress-test those totals with selective bottom-up checks, including sampled project cost benchmarks, channel checks on major equipment packages, and a limited roll-up of announced builds to confirm the model is not over counting.
Key inputs that shape the sizing include planned IT load additions (MW), the share of spend allocated to electrical versus mechanical infrastructure, construction timelines by project type, and the impact of power connection availability on phasing. We also track shifts in cooling intensity tied to higher rack density, since this changes mechanical spend per MW. Contractor pricing signals are also incorporated to reflect labor availability and materials inflation.
For forecasting, scenario analysis is used to reflect different paths for delivery timing and power readiness, before selecting the most likely case supported by interview consensus. When project data is incomplete, gaps are handled by applying conservative ranges for unknown start dates and standardizing cost assumptions to the same currency timing, then revisiting those choices during validation.
Data Validation & Update Cycle
Model outputs are checked against independent signals such as announced capacity additions, grid and power connection commentary, and visible construction milestones. Variances are then reviewed to determine whether the driver is timing, scope, or cost assumptions. If an outlier is found, the underlying project list and unit-cost ranges are rechecked, and follow-up outreach is triggered to confirm what changed.
Before sign-off, the work is reviewed in steps so calculation logic, unit consistency, and year mapping are verified by another analyst. Reports are refreshed annually, and interim updates are made when material events occur, such as large project announcements, major delays, or policy shifts that can alter build activity. Prior to delivery, a final pass is completed to ensure the latest public updates are reflected in the narrative and sizing.
黑料不打烊's Taiwan Data Center Construction Market Size Compared With Other Published Estimates
Published market values for Taiwan data center construction do not always match because each publisher uses a different boundary for what counts as construction spending and how that spending is recognized. Differences also come from how costs are normalized, since exchange-rate timing and cost inflation treatment can move totals even if the physical build pipeline looks similar.
By tracking commissioning-linked spend phasing and refresh-timing assumptions, 黑料不打烊 keeps the estimate anchored to Taiwan build-outs that translate into electrical and mechanical fit-out value within the forecast window, rather than mixing in operating services or multi-year contracts. Gaps widen when a study counts total investment for broader data center markets, applies global average costs that miss local labor and materials conditions, or assumes aggressive delivery schedules without follow-up checks on power readiness and permitting progress.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 0.94 B (2025) | |
| Industry Report A | USD 1.85 B (2024) | Uses a wider "data center investment" lens that can bundle IT infrastructure and broader facility spend, which inflates totals versus construction-only accounting. |
| Trade Article B | USD 1.47 B (2023) | Relies heavily on announced investment budgets and may not adjust for schedule slippage or spend that shifts outside the stated year, which can overstate realized construction value. |
The spread in the table mainly reflects boundary choices and timing, not just growth expectations. When construction scope is kept specific and spending is aligned to realistic project phasing, the result is easier to trace back to observable build activity and repeatable checks year after year.


Key Questions Answered in the Report
What is the current value of the Taiwan data center construction market?
The market stands at USD 1.03 billion in 2026 and is projected to reach USD 1.64 billion in 2031.
Which tier classification leads the market?
Tier 3 facilities hold 57.92% revenue share, reflecting balanced reliability and cost performance.
How fast is the Hyperscaler self-build segment growing?
Self-build campuses are forecast to expand at a 10.04% CAGR through 2031, outpacing all other data-center types.
Why are liquid-cooling systems gaining traction in Taiwan?
High GPU densities, warm climate, and power constraints make liquid cooling essential for efficient heat removal and lower PUE.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Data Center Cooling Market Global cooling demand, split by cooling technology, cooling component and facility type.
- China Data Center GPU Market GPUs demand across China, covering deployment type, gpu type and interconnect.
- South Korea Data Center GPU Market South Korea's GPUs, split by deployment type, gpu type and interconnect.
- Japan Data Center GPU Market GPUs in Japan, split by deployment type, gpu type and interconnect.
- Europe Data Center Water Consumption Market Europe water use, split by source of water procurement, cooling technology and facility type.
- Taiwan Hyperscale Data Center Market Taiwan hyperscale sites, split by facility type, component and tier.
- Hong Kong Data Center Networking Market Hong Kong's networking, split by component, end-user and data-center type.
- Netherlands Data Center Power Market Power systems demand across the Netherlands, covering component, facility type and facility size.
- Asia-Pacific Data Center Cooling Market Asia-Pacific's cooling, split by cooling technology, cooling component and tier.



