
Spain Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
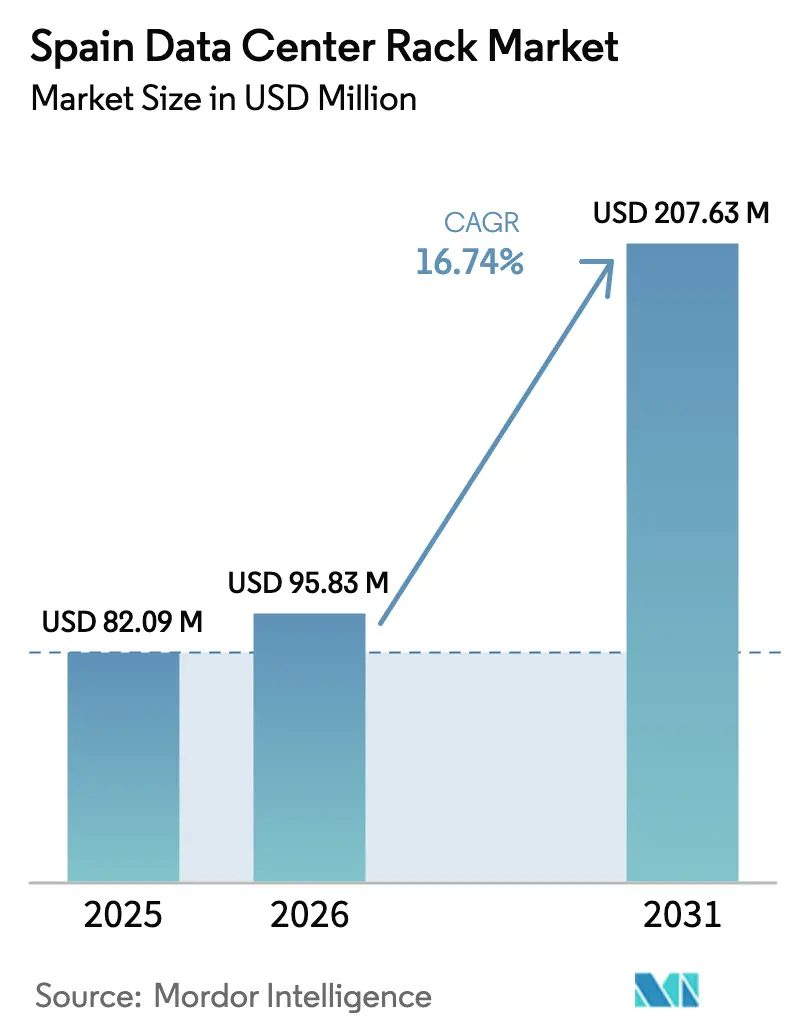
| Base Year Market Size (2025) | USD 82.09 Million |
| Market Size (2026) | USD 95.83 Million |
| Market Size (2031) | USD 207.63 Million |
| Growth Rate (2026 - 2031) | 16.74 % |
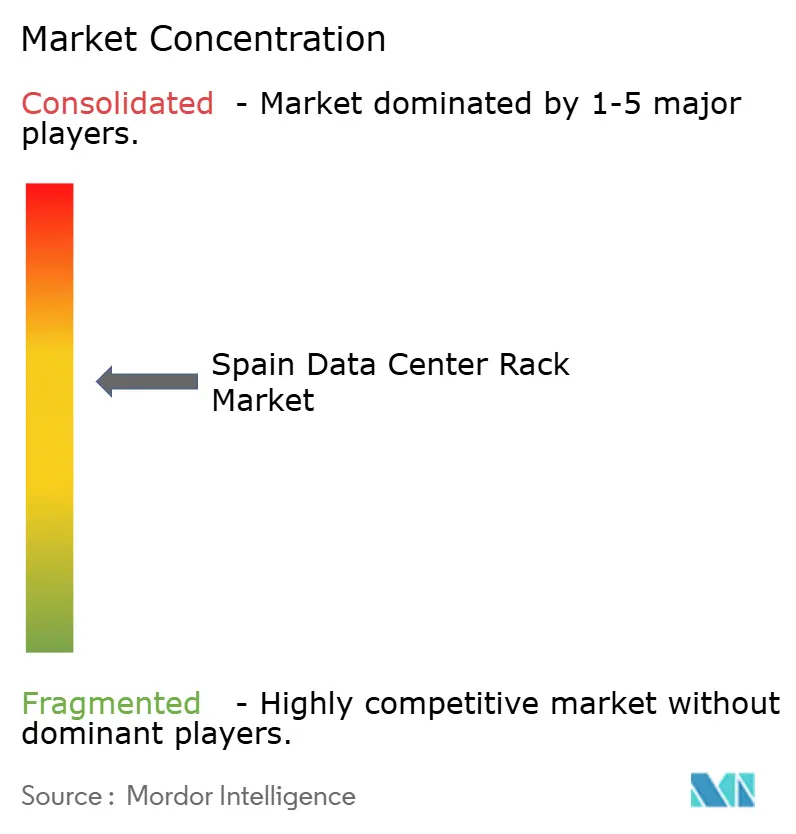
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Spain Data Center Rack Market Analysis by 黑料不打烊
The Spain data center rack market size is expected to grow from USD 82.09 million in 2025 to USD 95.83 million in 2026 and is forecast to reach USD 207.63 million by 2031 at 16.74% CAGR over 2026-2031. Hyperscale capital expenditure topping EUR 8 billion is positioning Spain as Southern Europe’s digital crossroads, while submarine cable landings in Bilbao and Valencia underpin sustained international connectivity. Government-backed Espa?a Digital 2026 funds nationwide fiber and 5G backbones that channel fresh demand into colocation halls, even as AWS, Microsoft and Google pour USD 3 billion into hyperscale campuses designed for AI workloads exceeding 60 kW per rack. Rack densities are climbing to 120 kW in Aragón, prompting operators to favor liquid-ready 52U designs and integrated power distribution. Despite steel retaining 78.3% material share, aluminum’s 19.7% growth rate illustrates a pivot toward lighter, seismically resilient structures that ease installation near coastal cable landings.
Key Report Takeaways
- By rack size, full racks led with 68.32% of Spain data center rack market share in 2025; the same segment is projected to expand at a 18.96% CAGR through 2031.
- By rack height, the standard 42U format held 54.61% share in 2025 in Spain data center rack market, while the 48U segment is forecast to grow fastest at 19.21% CAGR to 2031.
- By rack type, cabinet (closed) racks commanded 71.68% revenue share in 2025 in the Spain data center rack market and are advancing at a 20.62% CAGR on heightened security and airflow demands.
- By data-center type, colocation facilities held 57.12% revenue share in 2025 in the Spain data center rack market ; hyperscale builds are expected to grow at 18.88% CAGR through 2031.
- By material, steel accounted for 77.62% share in 2025 in the Spain data center rack market; aluminum registers the fastest rise at 19.05% CAGR given weight-reduction imperatives.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Spain Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale build-outs by AWS, Microsoft and Google accelerating above 60 kW rack demand | + 4.2% | Madrid, Aragón, Barcelona | Medium term (2-4 years) |
| Edge-cloud roll-outs by Spanish telcos (Telefónica, Cellnex) require micro-racks | + 2.8% | National, with concentration in urban centers | Short term (≤ 2 years) |
| EU-funded "Espa?a Digital 2026" fibre and 5G backbone stimulates colocation growth | + 3.1% | National, priority in underserved regions | Medium term (2-4 years) |
| Corporate cloud migration in BFSI and public sector after Royal Decree-law 14/2019 compliance | + 2.3% | Madrid, Barcelona, regional capitals | Short term (≤ 2 years) |
| AI model training hubs in Aragón driving liquid-cool ready 52U racks | + 3.8% | Aragón, with spillover to Castilla-La Mancha | Long term (≥ 4 years) |
| Sub-sea cable landing in Bilbao (Grace Hopper, Medusa) lifting demand for seismic-rated racks | + 1.5% | Bilbao, Northern Spain coastal regions | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Hyperscale build-outs by AWS, Microsoft and Google accelerating above 60 kW rack demand
Hyperscale operators have re-defined specifications in the Spain data center rack market, standardizing 60 kW-plus designs to run generative-AI training clusters. AWS opened its Aragón region in 2024, Microsoft earmarked USD 2.1 billion for the Spain Central cloud region, and Google boosted Madrid capacity with USD 650 million, collectively stretching national power provisioning thresholds Amazon, Microsoft, Google. Their spending shifts preference toward 52U racks with liquid manifolds, heavier gauge cable ladders and frame tolerances exceeding 1,300 kg. Operators now demand integrated bus-bar power strips and tool-less airflow blanking panels to curb thermal hotspots that throttle GPUs. Procurement teams also insist on vendor stock harmonization across multiple campuses to streamline spares, making standardized full racks the baseline choice.
Edge-cloud roll-outs by Telefónica and Cellnex require micro-racks
Telefónica and Cellnex collectively oversee more than 10,462 tower and rooftop sites that are being upgraded to host edge compute pods supporting 5G slicing, connected-vehicle telemetry and AR streaming Cellnex. Space-limited shelters favor 6U-to-12U micro-racks featuring sealed doors, vibration dampers and DC power shelves compatible with telco battery strings. Vendors are responding with wall-mount enclosures carrying outdoor corrosion ratings and remotely monitored door sensors. Roll-outs concentrate inside Madrid’s M-30 ring and Barcelona’s metropolitan area where densification improves latency below 10 ms for IoT transactions. This distributed architecture widens the Spain data center rack market footprint beyond traditional halls, benefiting local fabricators that can deliver bespoke form factors inside shorter lead times.
EU-funded “Espa?a Digital 2026” backbone stimulates colocation growth
Espa?a Digital 2026 dedicates EUR 4 billion to boost fiber reach and 5G standalone cores, attracting colocation providers that package carrier-neutral cross-connects for enterprises pursuing latency-sensitive SaaS workloads [1] Ministerio de Ciencia e Innovación, “Espa?a Digital 2026 Roadmap,” ciencia.gob.es. Regional fiber loops cut backhaul costs for operators in Valencia, Málaga and Bilbao, inspiring new multi-tenant halls to pre-install 42U cabinet rows with modular roof chimneys ready for liquid retrofit. Government grants covering up to 50% of duct-laying expenses lower build costs, letting colo operators compete aggressively on rack rates while maintaining ISO 27001 and Tier III resilience. The initiative’s digital-sovereignty angle also encourages domestic cloud adoption among public agencies, further inflating demand for high-security cabinet racks.
AI training hubs in Aragón driving liquid-cool ready 52U racks
Aragón’s wind-and-solar mix delivers 68% renewable penetration and average industrial tariffs 18% below Madrid, making the region a magnet for GPU megafarms. Amazon’s three data center permits include annual water draws nearing 755,720 m?, signaling large-scale liquid cooling loops that need taller racks to house pumping manifolds and leak-detection rails . Operators specify 52U frames with 19-inch vertical pitch but deeper footprints to seat duplex CDU sets. Fabricators must reinforce caster load bearing and provide anodized aluminum rails resisting coolant corrosion. The Spain data center rack market sees parallel demand for dripless quick-disconnect fittings and ultrasonic flow meters embedded into the rack doors for live monitoring.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Power-grid congestion in Madrid and Barcelona delaying rack deployments | -2.1% | Madrid, Barcelona metropolitan areas | Short term (≤ 2 years) |
| Escalating steel prices impacting rack cost structure | -1.4% | National, with manufacturing concentration effects | Medium term (2–4 years) |
| Water-use restrictions curbing adoption of high-density chilled-water racks | -1.8% | National, acute in Catalonia and Andalusia | Medium term (2–4 years) |
| Talent shortage for liquid-cool maintenance raising OPEX and slowing adoption | -0.9% | Madrid, Barcelona, emerging data center hubs | Medium term (2–4 years) |
| Permitting delays for edge data center retrofits in heritage zones | -1.2% | Historic urban cores in Spain; notably Seville, Valencia, Granada | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Power-grid congestion in Madrid and Barcelona delaying rack deployments
The April 2025 blackout that knocked out power to 55–60 million residents exposed system inertia gaps in a grid leaning on 59% solar generation. Data-center requests for new 120 kW circuits now face six-to-nine-month queue times at Madrid’s Vicálvaro substation, forcing operators to stagger rack installations in 2 MW tranches . Some hyperscalers are shifting expansion toward Zaragoza where redundant 400 kV feeds exist, but colos tied to urban fiber hubs must absorb diesel genset surcharges that add 6–8 EUR per rack monthly. The constraint dents Spain data center rack market momentum in the capital, amplifying interest in energy-efficient aluminum frames that shave power by improving airflow.
Water-use restrictions curbing chilled-water rack adoption
Spain’s worst drought in six decades leaves 78% of land at desertification risk, triggering municipal caps on industrial withdrawals in Catalonia and Andalusia. Traditional chilled-water CRAH loops consuming 1.5 liters per kWh are under scrutiny as city councils link construction permits to water-reuse ratios. Meta’s planned Talavera campus drawing 665 million liters yearly ignited public pushback, illustrating regulatory headwinds. Operators pivot to direct-to-chip or immersion cooling, yet these alternatives entail thicker door heat exchangers that only fit within custom 48U-plus cabinets, inflating capital outlays by 14–17%. Resultant procurement hesitancy trims forecast volumes for high-density rack SKUs until recyclable coolant ecosystems mature.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full-height frames dominate Spain’s capacity expansion
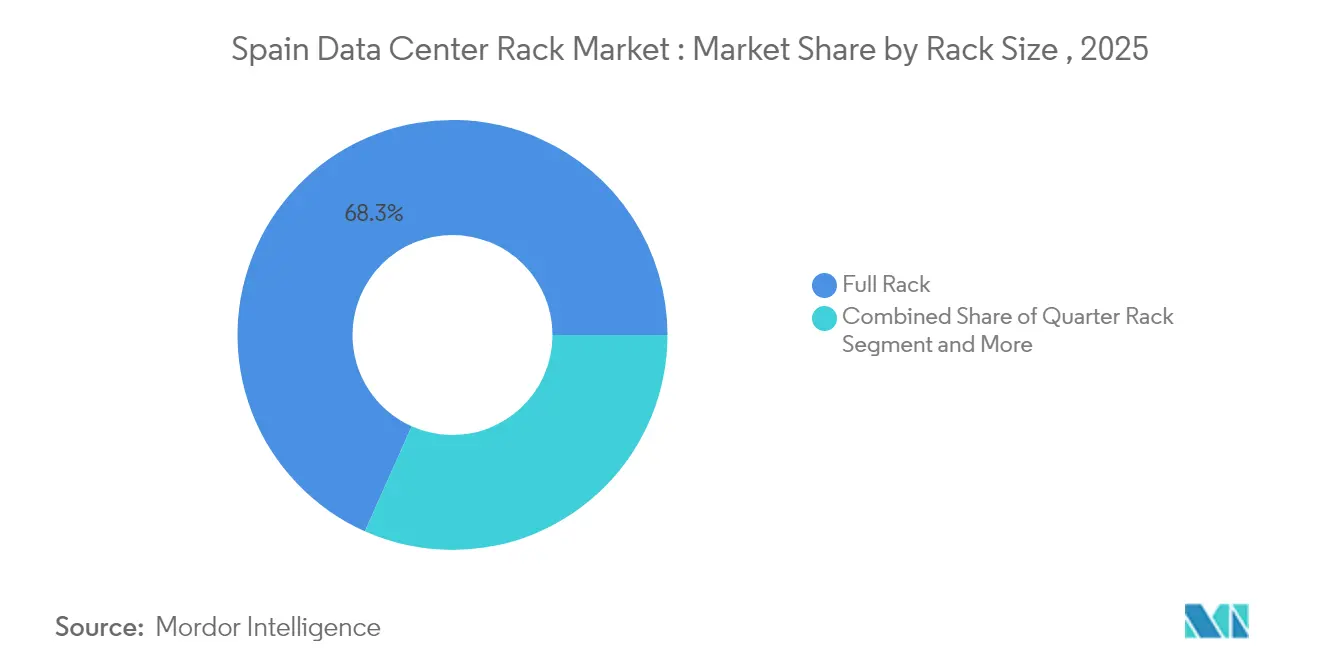
Full racks controlled 68.32% of shipments in 2025 and form the backbone of hyperscale halls ringing Madrid and Huesca. The Spain data center rack market size for the full-rack segment is projected to reach USD 141.86 million by 2031, underpinning the broader market’s 16.74% CAGR path. Standardizing on full frames lets operators maximize servers per square meter and simplify hot-aisle containment retrofits that preserve PUE below 1.3. Quarter and half racks still populate telecom closets and brownfield enterprise labs, yet their combined share is eroding as cloud migration lifts server consolidation ratios.
Adoption accelerates because global operators apply the same specifications used in Dublin, Frankfurt and Paris to Spanish builds, locking in economies of scale on cable trays, PDUs and door swing clearances. Vendors such as Eaton pre-assemble SmartRack bundles, with brush grommets, blanking panels and bus-way tap-off units, that roll directly onto raised floors, cutting site labor by 12 hours per rack. Contract manufacturers in Asturias and Navarre keep lead times under four weeks for custom color, seismic kits and LoRaWAN sensor rails, a differentiator in Spain data center rack market orders placed by fast-growing SaaS tenants.


By Rack Height: 48U adoption overtakes the 42U incumbent
The 42U format retained 54.61% share in 2025, yet operators now specify 48U enclosures to fit rear-door heat exchangers and extra breakers needed for 415 V three-phase feeds. The Spain data center rack market size for 48U designs is forecast to swell at 19.21% CAGR, mirroring AI GPU density curves. Taller frames raise total static load to 1,500 kg, necessitating welded steel corners or extruded aluminum columns with torsional ribs for stability during seismic events near Bilbao’s cable hubs.
Early adopters report that adding six rack units slashes row length by nearly 15%, freeing white-space for battery cabinets. Schneider Electric’s EcoStruxure firmware update in 2024 broadened environmental sensor support, encouraging facility teams to retrofit 48U rows with digital manifold gauges. Although shipping taller cabinets complicates pallet stacking, domestic carriers adapt with telescopic trailers, limiting freight premiums to 3%. This cost-containment bolsters migration from legacy 42U frames, keeping Spain data center rack market acceleration on track even amid steel inflation.
By Rack Type: Cabinet designs outpace open frames on security and airflow
Cabinet racks represented 71.68% revenue in 2025 and display a 20.62% CAGR through 2031 as Spanish banking, healthcare and public-sector tenants adopt stricter data-sovereignty protocols. Spain data center rack market share for cabinet variants is set to exceed 77.00% by 2027, reflecting mandated biometric locks and tamper-evident screws required under Royal Decree-law 14/2019. Closed doors enable differential pressure zones, permitting chilled rear-door coolers to reject 80% of thermal load without aisle containment.
Open-frame racks remain common in low-risk lab zones or HPC labs where technicians need 360-degree access, yet their share drops as cyber-insurance carriers tie premiums to physical intrusion safeguards. Cabinet makers integrate EMP mesh linings for defense-sector deployments near Madrid’s Torrejón base, a feature now requested by multinational banks migrating mainframes. The granular segmentation of rack SKUs lengthens buyers’ RFPs, but integrated bundles shorten installation cycles, elevating Spain data center rack market competitiveness for turnkey suppliers with in-house cooling IP.
By Data Center Type: Hyperscale growth eclipses colocation dominance
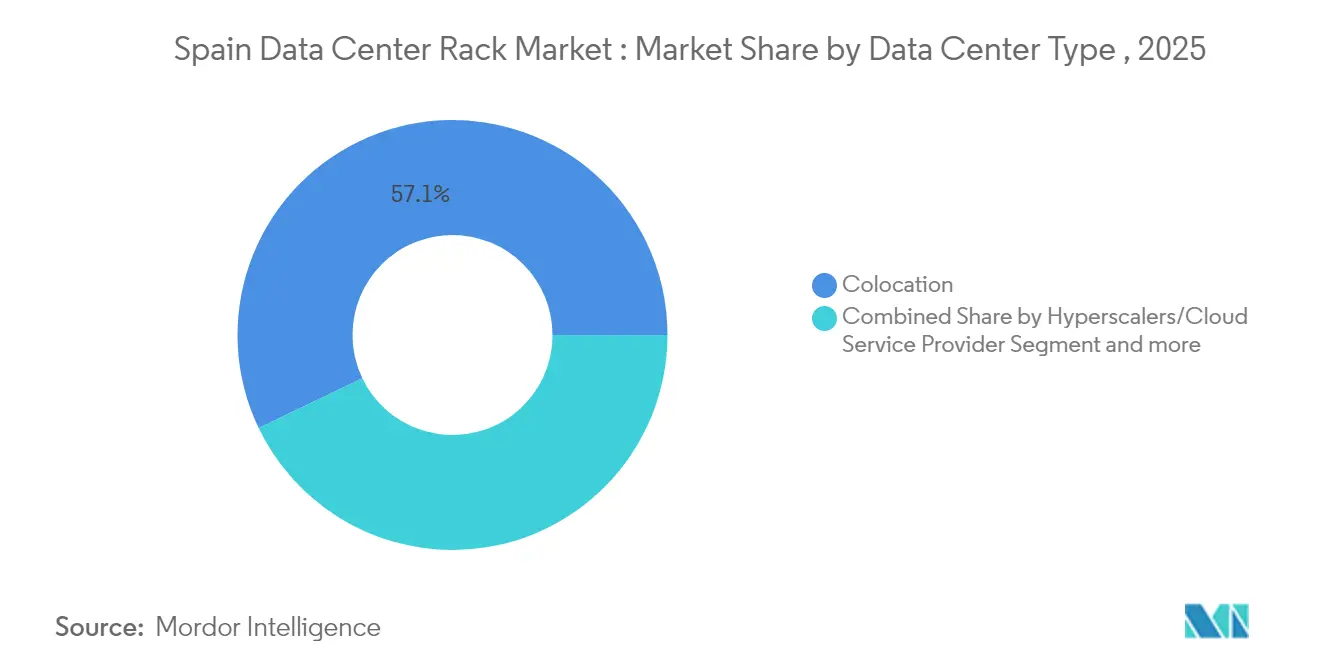
Colocation still accounts for 57.12% of 2025 shipments, sustained by inter-connect density in Madrid’s Las Rozas corridor. Yet hyperscalers show the fastest 18.88% CAGR as Amazon, Microsoft and Google channel capital toward purpose-built campuses in Aragón and Castilla-La Mancha. Correspondingly, the Spain data center rack market size tied to hyperscale facilities should surpass USD 101.6 million by 2031. Vertical integration lets hyperscalers dictate rack specifications, favoring 52U cabinet heights, integrated CDU rails and AI-ready bus-bar harnesses.
Colo operators respond by offering “build-to-suit” suites with 20-year power reservations and vendor-agnostic cage footprints. Smaller enterprise and edge nodes deployed by Telefónica along 5G routes adopt micro-rack arrays slotted into street-level shelters, diversifying revenue streams for Spanish fabricators. Overall, the dual-track deployment model, hyperscale for cloud-native workloads, colocation for latency-sensitive interconnects, enlarges the Spain data center rack market addressable base and buffers cyclicality.
By Material: Aluminum gains traction despite steel’s price edge
Steel held 77.62% of 2025 demand thanks to its low cost and 1,800 kg static-load limits. However, aluminum’s 19.05% CAGR underscores operator appetite for lighter frames that reduce craning loads and improve thermal dispersion. Structural alloys now feature magnesium to heighten tensile strength, letting aluminum racks match 1,200 kg capacities while weighing 35% less. Spain data center rack industry specifiers pair these frames with raised-floor isolation pads that cut seismic sway in Bilbao’s cable-landing halls.
High electricity tariffs hitting European smelters spur cost volatility, yet aluminum’s recyclability aligns with ESG metrics that grant hyperscalers power-usage exemptions. The EU Steel and Metals Action Plan’s 2025 subsidy round may narrow price differentials, but for now steel remains dominant where budget constraints trump weight. Hybrid solutions, steel posts with aluminum side panels, offer compromise options, reflecting continual product innovation driving Spain data center rack market resilience.
Geography Analysis
Madrid retained 60.84% of installed capacity in 2025 and anchors international peering exchanges, yet grid bottlenecks and land scarcity dampen new rack deployments. Aragón houses Spain’s cheapest renewable blend, allowing hyperscalers to secure 500 MW leases and plan rack densities of 120 kW without curtailment penalties. Barcelona remains the second-largest cluster, though Catalonia’s drought-triggered water quotas slow high-density liquid loops, nudging operators to implement airside economizers instead of chilled-water coils.
Northern Spain, led by Bilbao, commands growing interest due to Grace Hopper and Medusa cables, giving carriers sub-50 ms RTT to New York and Tel Aviv. Rack manufacturers court local colocation builds by stocking seismic kits rated to Zone 3 acceleration levels, a niche yet profitable opportunity within the Spain data center rack market. Valencia and Málaga attract edge deployments targeting Mediterranean tourist bandwidth spikes, leveraging municipal tax breaks for green building certifications. Regional governments compete on fast-track permitting and renewable PPAs; Castilla-La Mancha offers 10-year property-tax holidays that shift TCO calculus for hyperscalers weighing Zaragoza against Toledo. Spain’s robust rail network lets integrators stage racks in Madrid and dispatch overnight to satellite cities, mitigating logistics costs for dispersed builds. Consequently, the Spain data center rack market evolves from a Madrid-centric entity into a polycentric fabric optimized for both submarine cable proximity and renewable-energy availability.
Regulatory Landscape
Spain data center rack demand is increasingly shaped by grid-access and sustainability rulemaking alongside core EU and national compliance obligations for facilities handling regulated workloads. Royal Decree-law 14/2019 and related public-sector and critical-infrastructure cybersecurity requirements continue to push buyers in BFSI and government toward lockable cabinet racks with tamper-evident features and auditable physical-access controls.
In March 2026, Royal Decree-law 7/2026 introduced new grid-access conditions relevant to high-load data centers, including capacity reservation charges and milestone-based permitting that can affect build schedules and phased rack rollouts. In parallel, the Ministry for Ecological Transition (MITECO) has advanced a draft Royal Decree focused on data center sustainability, emphasizing renewable-energy correlation, energy efficiency, sustainable water use, and heat reuse for larger facilities (for example, sites above 1 MW), making environmental design choices such as liquid-ready and heat-recovery compatible rack configurations more prominent in procurement and permitting discussions.
Value Chain Analysis
The Spain data center rack value chain runs from global steel and aluminum sourcing and component fabrication (frames, doors, rails, cable management, PDUs, and monitoring) into assembly and configuration, then through distributors and integrators to data center operators and enterprise/telco end users. As densities move beyond 60 kW per rack in hyperscale and AI deployments, specifications pull in adjacent suppliers such as liquid-cooling manifold providers, busway and power-distribution vendors, sensor and access-control providers, and logistics partners capable of handling taller, heavier 48U to 52U cabinets.
Spain combines multinational supply with local and regional fulfillment capacity that supports short lead times for large projects. Schneider Electric operates a manufacturing and logistics footprint in Sant Boi de Llobregat (Barcelona) that supports prefabricated and modular data center solutions, while Rittal S.A. coordinates enclosure and IT infrastructure systems from its Sabadell base, anchoring local availability for cabinet racks and accessories. Vertiv participates through integrated modular and thermal management offerings delivered via project and partner ecosystems, a model that aligns with hyperscale and colocation operators seeking factory-built, repeatable rack-and-power blocks for multi-site rollouts.
Competitive Landscape
The competitive field skews moderately concentrated. Schneider Electric, Vertiv and Rittal collectively shipped 46.5% of 2024 volumes, bundling racks with bus-way, monitoring and cooling. Their Iberian warehouses enable 72-hour dispatch into Madrid’s Alcobendas campus lanes. Local firms such as Esnova Racks and Espaciorack differentiate through bespoke paint schemes and rapid prototype cycles, capturing finance and government contracts where Spanish-language engineering support is mandatory.
Legrand’s 17 data-center-focused acquisitions since 2010 expand its containment and power raceway catalog, allowing cross-selling into hyperscale bids. Dell and HPE deepen presence through factory-integrated rack-scale systems bundled with GPU sleds, aiming to secure AI cluster refreshes. Meanwhile, ODMs from Taiwan infiltrate via distribution partners, offering bare-frame options priced 12% below branded equivalents; however, warranty concerns limit uptake among regulated sectors.
Innovation priorities revolve around immersion-ready frames with polymer coatings, tool-less side panels and native support for DC bus-bar harnesses. Aluminum adoption acts as a product-differentiation lever, yet supply chain discipline is critical when London Metal Exchange premiums fluctuate. Strategic partnerships between rack vendors and cooling specialists, such as Vertiv’s tie-up with GRC for immersion tanks, underline converging value-chains inside the Spain data center rack market.
Spain Data Center Rack Industry Leaders
Eaton Corporation
Rittal GMBH & Co.KG
Schneider Electric SE
Vertiv Group Corp.
nVent Electric plc
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Large, multi-year data center build programs and campus announcements are creating clear whitespace for rack vendors that can deliver standardized, high-density, liquid-ready cabinet platforms and rapid-delivery programs across multiple Spanish regions. Recent examples include Amazon's investment plan totaling EUR 33.7 billion through 2035 to expand data center infrastructure and AI capabilities in Aragon, alongside major campus proposals such as Apto's 240 MW project in Fuenlabrada (Madrid), Ferrovial's 60 MW campus in Madrid, and EdgeMode's 300 MW AI campus proposal in Toledo. These projects favor repeatable rack specifications (for example, 48U to 52U formats, heavier loading tolerances, and integrated power and sensor rails) and increase the value of Iberia-based warehousing, kitting, and configuration services that reduce on-site labor and commissioning time.
A second opportunity area is compliance-led engineering around power and sustainability constraints that increasingly influence permitting and operational acceptance. The March 2026 Royal Decree-law 7/2026 grid-access framework and MITECO's draft sustainability Royal Decree elevate requirements around energy efficiency, renewable alignment, water stewardship, and heat reuse, driving demand for racks that support higher airflow control, liquid cooling interfaces, and monitoring instrumentation. Suppliers that package racks with access control, environmental sensing, and integration-ready mounting for CDUs and rear-door heat exchangers are better positioned for colocation and public-sector deployments where auditability and facility efficiency features are purchased together rather than as standalone components.
Recent Industry Developments
- July 2026: Apto (Madrid data center campus project) announced a 2 billion euro investment for a 240MW data center campus in Fuenlabrada, Madrid. The launch expands Spain's AI oriented capacity, signaling a major push in hyperscale infrastructure. Drives headcount, rack and power demand; strengthens Madrid as a hyperscale hub; accelerates rack density and modular solution adoption.
- July 2026: Submer Group announced a 1 billion euro investment for a sustainable AI data center at the former Ercros site in Flix, Catalonia. The investment underscores Catalonia as a focal point for AI driven data center development. Catalonia site reuse boosts regional rack deployment and cooling solutions; signals focus on immersion-ready, modular racks for AI workloads.
- March 2026: Amazon announced an additional 18 billion euro investment in Spain, totaling 33.7 billion euros, to expand data center infrastructure and AI capabilities in the Aragon region. The expansion reinforces Spain as a major hyperscale hub and expands capacity for AI workloads. Strengthens Spain’s hyperscale footprint; increases rack, cabling, and cooling capacity needs; reinforces Aragon as a key AI data center corridor.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers the revenue generated from data center racks supplied and installed within Spain, across enterprise and colocation facilities. It includes standard rack frames and related structural configurations that house IT equipment, measured in USD at the point of sale.
Scope exclusions: The scope excludes IT servers, storage, network switches, and standalone room infrastructure such as cooling units and UPS systems.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure of the model and to anchor Spain country level demand signals that influence rack shipments and pricing. We referenced public and official sources such as INE (Spain), Eurostat, Red.es publications under national digital plans, CNMC telecom indicators, and International Energy Agency power data to understand investment cycles and facility activity.
We also reviewed company filings, investor presentations, press releases, and reputable industry news to map capacity additions, new data hall launches, and typical rack density ranges seen in Spain. In addition, paid subscriptions for company financials and intelligence, patent databases, and shipment level import and export data were used selectively to validate supplier exposure and hardware flow patterns. The sources listed above are illustrative only, and many other public documents and datasets were also used for data collection, cross checks, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and surveys with rack manufacturers and distributors, colocation operators, engineering teams, and buyers responsible for data hall fit outs. Respondent input was used to confirm typical rack unit mixes, pricing movements, lead times, and demand timing by major Spanish metro areas, and then to align assumptions across the value chain so the final sizing is practical and repeatable.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 31% | CXOs: 16% |
| Mid tier: 49% | Functional/Unit leaders: 39% |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The sizing starts from a top down reconstruction of Spain's rack demand pool by linking data center build activity to rackable footprint and expected rack density ranges, which are then converted into annual unit needs and revenue using locally validated average selling prices. That view is then checked with selective bottom up approximations, including supplier and channel roll ups, sampled price quotes, and spot checks on project pipelines, so the totals stay within what can realistically be shipped and installed.
Key inputs include new and announced data hall capacity additions, colocation take up and pre lease signals, typical rack heights (for example, 42U to 52U) and enclosure preferences, average power density movements that influence rack specifications, and import and distribution patterns that affect availability and pricing. Where direct visibility on smaller projects is limited, gaps are handled by applying conservative install rate assumptions based on installer feedback and observed procurement cycles. For forecasting, scenario analysis is used around hyperscale and colocation build timing, and the yearly path is smoothed with an exponential trend aligned to expert expectations for demand timing and price normalization.
Data Validation & Update Cycle
Before finalizing, model outputs are triangulated against independent signals such as facility announcements, power and connectivity indicators, and observed procurement lead times that often surface earlier than revenue. Variance checks are run at each step to catch outliers, after which assumptions are reviewed internally and adjusted only when the supporting evidence is consistent across sources.
If a major mismatch appears, or if new capacity announcements materially change the demand outlook, respondents are re contacted and the model is re run for the affected years. Reports are refreshed annually, with interim updates when material events occur, and a final analyst pass is completed right before delivery so clients receive the latest updated view.
黑料不打烊's Spain Data Center Rack Market Size Measured Against Other Published Estimates
Published market sizes for Spain data center racks often differ, even when they look close at first glance, because the underlying scope and counting logic are not always the same. Differences usually come from what is treated as a rack sale, the year used as the base, and how pricing and shipment timing are converted into USD.
Open frame racks and cabinets with integrated enclosures are often mixed together in external figures, and edge micro sites are sometimes counted as full data center installations, which can move totals up or down quickly in a country with uneven project sizes. In 黑料不打烊, servers and other IT hardware sit outside the scope, and the model is kept tied to rack specific demand signals like build outs, density shifts, and country level shipment checks that are refreshed with the latest available project updates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 82.09 M (2025) | |
| Regional Consultancy A | USD 74.90 M (2023) | Uses an older base year and applies a narrower product view that only partially counts open-frame racks, which can understate demand during a build cycle. |
| Global Consultancy B | USD 95.00 M (2024) | Combines rack revenue with a broader enclosure definition and applies annual average currency timing, which can lift the USD value versus project-timed pricing. |
The spread across estimates mostly reflects base year timing and what is counted as rack revenue, rather than a disagreement on Spain's data center build momentum. By keeping inputs traceable to installation activity and realistic pricing ranges, the sizing stays easy to follow and can be re checked as new projects move from announcement to deployment.


Key Questions Answered in the Report
What is the current valuation of the Spain data center rack market?
The market is valued at USD 95.83 million in 2026 and is projected to reach USD 207.63 million by 2031.
Which rack type leads demand in Spain
Cabinet (closed) racks dominate with 71.68% revenue share in 2025 and post a 20.62% CAGR through 2031 on heightened security and airflow control needs.
Why are 48U cabinets gaining traction over 42U models?
AI workloads require extra vertical space for liquid cooling manifolds and redundant PDUs, driving 48U designs to a 19.21% CAGR.
How are power-grid constraints affecting data center builds?
Madrid and Barcelona face queue times up to nine months for new circuits, delaying high-density rack roll-outs and shifting some projects to Aragón.
Page last updated on:
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Power Market Power systems worldwide, split by component, tier and facility size.
- Spain Data Center Storage Market Storage demand across Spain, covering facility size and tier.
- France Data Center Cooling Market Cooling in France, split by cooling technology, type and end user vertical.
- Europe Data Center Storage Market Europe's storage, split by storage technology, storage type and end user.
- UK Data Center Storage Market The UK storage, split by facility size and tier.
- Italy Data Center Construction Market Construction demand across Italy, covering tier, facility type and infrastructure.
- France Data Center Storage Market France's storage, split by facility size and tier.
- United States Data Center Server Market The US servers, split by data-center tier, form factor and application / workload.
- United States Data Center Storage Market The US's storage, split by storage technology, storage type and end user.



