
Italy Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
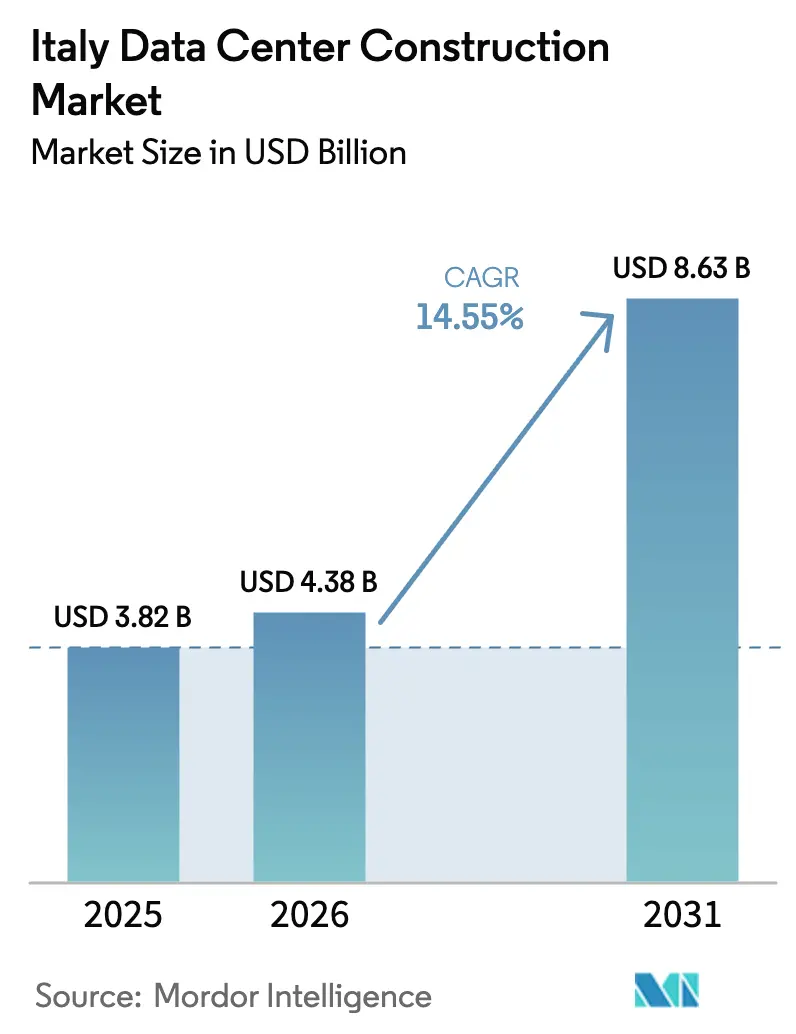
| Base Year Market Size (2025) | USD 3.82 Billion |
| Market Size (2026) | USD 4.38 Billion |
| Market Size (2031) | USD 8.63 Billion |
| Growth Rate (2026 - 2031) | 14.55 % |
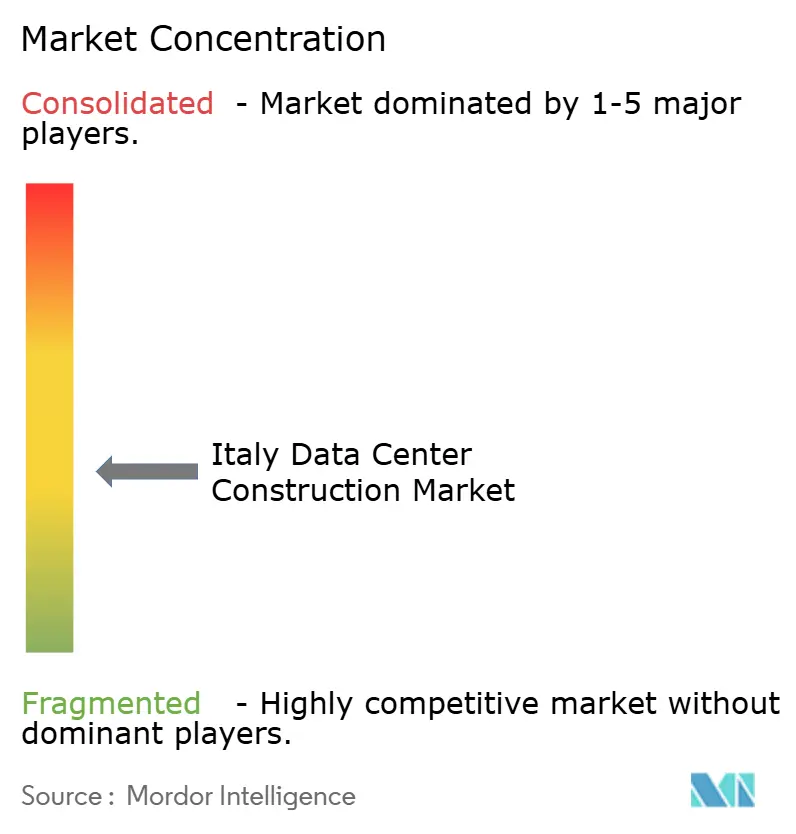
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Italy Data Center Construction Market Analysis by 黑料不打烊
Italy data center construction market size in 2026 is estimated at USD 4.38 billion, growing from 2025 value of USD 3.82 billion with 2031 projections showing USD 8.63 billion, growing at 14.55% CAGR over 2026-2031. Steady capital inflows from hyperscalers, strong government backing, and Italy’s geographic role as a Mediterranean connectivity node form the foundation of this rapid scale-up. Power connection requests have already eclipsed installed grid capacity, yet sustained investment plans by Terna and a wave of new submarine cable landings keep investor sentiment positive. Microsoft, AWS, Google Cloud, and Oracle continue to anchor fresh builds, while domestic operators such as TIM and Aruba blend local expertise with global best practice to accelerate delivery. Rising sustainability mandates, 5G rollout, and the build-to-lease approach embraced by hyperscalers collectively shape the next phase of the Italy data center construction market.
Key Report Takeaways
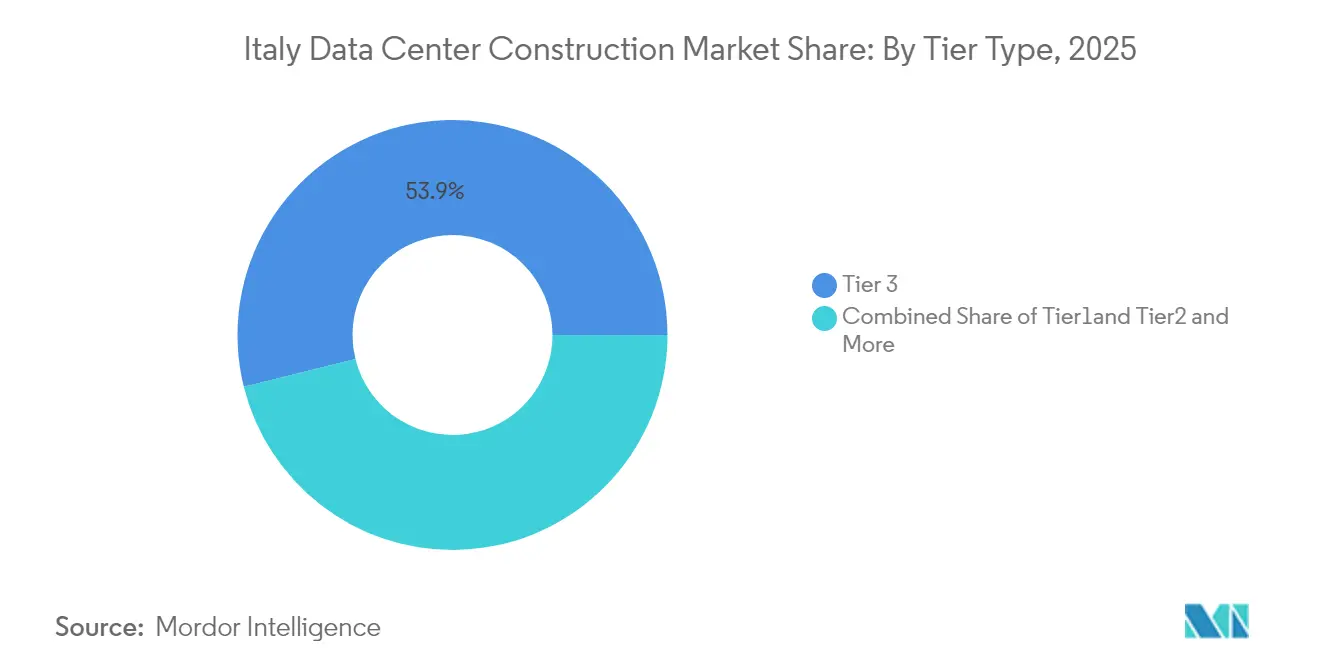
- By tier type, Tier 3 led with a 53.86% share of the Italy data center construction market in 2025, while Tier 4 facilities are expanding at a 17.48% CAGR through 2031.
- By data center type, colocation services held a 55.94% share of the Italy data center construction market size in 2025; self-build hyperscaler sites are growing 18.98% annually to 2031.
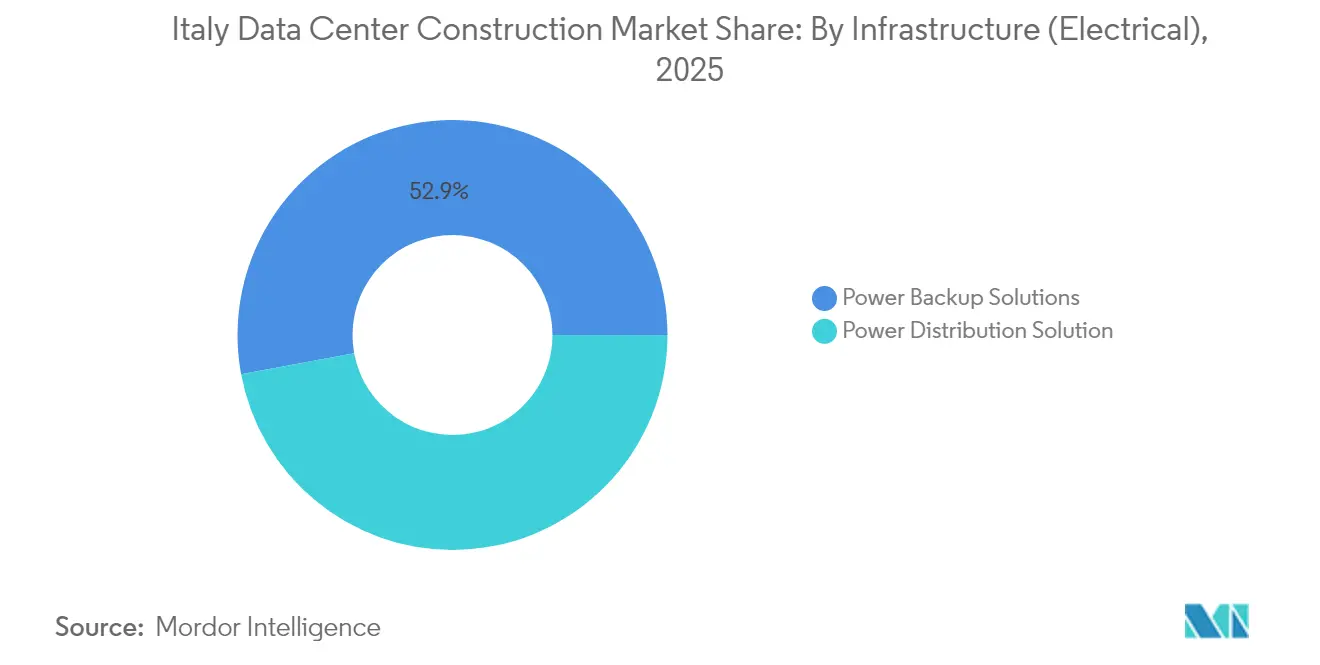
- By electrical infrastructure, power backup solutions accounted for 52.93% of the Italy data center construction market size in 2025, whereas power distribution solutions post the fastest 18.56% CAGR.
- By mechanical infrastructure, cooling systems captured 47.88% share of the Italy data center construction market size in 2025 and remain essential as servers and storage rise at a 16.13% CAGR.
- Regionally, Northern Italy commanded 61.58% of 2025 revenue; Sicily is forecast to post the highest 20.87% CAGR on the back of fresh cable landings.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Italy Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| 5G rollout accelerating edge and core builds | +2.8% | National, focused on Milan, Turin, Rome | Medium term (2-4 years) |
| Surging cloud and hyperscale demand | +3.2% | Northern and Central regions | Short term (≤ 2 years) |
| PNRR digital grants | +2.1% | Nationwide, underserved areas prioritized | Medium term (2-4 years) |
| Sustainability mandates and green energy sourcing | +1.9% | EU-wide, Italy leading Mediterranean uptake | Long term (≥ 4 years) |
| New subsea cable landings | +1.7% | Sicily, Genoa, Mediterranean coast | Long term (≥ 4 years) |
| Build-to-lease model | +1.5% | Northern Italy, moving southward | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
5G rollout accelerating edge and core builds
WindTre’s EUR 485 million purchase of OpNet’s standalone 5G assets unlocked 3,000 base stations serving 75% of Italy’s population, spurring immediate demand for micro-edge sites that reinforce traditional cores. TIM’s 2024-2026 plan maps 16 new data centers that dovetail with this national 5G push,[1]Telecom Italia, “TIM 2024-2026 Plan Accelerates 5G and Cloud,” telecomitalia.com and Phoenix Tower International’s 1,900-site program further underlines the need for low-latency capacity. Because 5G splits workloads between radio, edge, and core, facility planners now prioritize smaller footprints near population clusters, advanced liquid-assisted cooling, and resilient distribution paths to meet stringent latency targets.
Surging cloud and hyperscale demand
Google Cloud, Microsoft, AWS, and Oracle continue to earmark multi-billion-euro budgets for Italian expansion, often in partnership with TIM or other local carriers. The Milan-Turin corridor has become the epicenter, yet secondary cities are quickly absorbing projects as prime sites tighten. Hyperscale investment not only enlarges the Italy data center construction market but also boosts local employment, with University of Turin research projecting 65,000 jobs by 2025 from the Google ecosystem alone.[2]Google Cloud, “Introducing Google Cloud Regions in Milan and Turin,” cloud.google.com Partnerships shorten permitting cycles, ensure compliance with digital-sovereignty rules, and allow carriers to cross-sell edge services.
Government “PNRR” digital grants
Italy’s PNRR allocates EUR 32.5 billion to digital objectives,[3]European Commission, “Recovery and Resilience Facility: Italy Country Factsheet,” europa.eu and cloud-first directives in public administration are creating demand visibility that de-risks private capital. Piano Transizione 5.0 adds EUR 12.7 billion of tax credits to companies that lower energy use by at least 3%, directly supporting efficient builds. Municipal funding envelopes earmark EUR 500 million for cloud enablement in underserved areas, nudging operators to distribute capacity beyond the Milan-Turin core and thereby broadening the Italy data center construction market.
Rising sustainability mandates and green energy sourcing
From September 2024, EU rules require operators to disclose energy KPIs, driving efficiency upgrades and renewable sourcing. Italy’s Energy Decree trims permitting timelines for solar and wind projects that feed data centers, while leaders such as Aruba power entire campuses with hydro and PV. Retelit’s Avalon 3 recovers waste heat for district networks, illustrating how environmental rules spur technical innovation and adjacent revenue streams.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid-power scarcity and volatile prices | -3.1% | Nation-wide, severe in industrial north | Short term (≤ 2 years) |
| Specialised labour shortage | -2.2% | Major metropolitan areas | Medium term (2-4 years) |
| Seismic-zone engineering costs | -1.8% | Central and Southern seismic belts | Long term (≥ 4 years) |
| Limited reclaimed water for cooling | -1.4% | Arid industrial zones | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Grid-power scarcity and volatile energy prices
Connection requests topped 42 GW in March 2025—almost triple available headroom—forcing operators to queue as long as three years for new feeds. Terna’s EUR 23 billion grid plan will ease congestion but not before late decade. Meanwhile, some hyperscalers buy retired Enel power assets to avoid delays. Rising spot prices complicate budgeting, and construction cost indices have risen 20% since the pandemic, squeezing margins for developers across the Italy data center construction market.
Shortage of specialised data-center construction labour
Italy shares a global shortfall of skilled technicians who understand high-density power, advanced cooling, and seismic design. Temporary booms from the Superbonus scheme distorted the labour pool, leaving fewer qualified crews for Tier 4 builds. Training pipelines exist but need two-plus years to flow, placing upward pressure on delivery timelines and wages and restraining the overall Italy data center construction market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Tier 4 Drives Premium Reliability
Tier 3 facilities controlled 53.86% of the Italy data center construction market share in 2025 as enterprises sought balanced uptime and cost. Nevertheless Tier 4 sites, required by finance, government, and AI workloads, expand 17.48% each year to 2031. This segment commands higher CAPEX due to dual power paths, concurrent maintainability, and seismic hardening. Vertiv’s CoolLoop Trim Cooler, compliant with impending EU F-GAS rules, cuts cooling energy 70%, making it attractive to Tier 4 builders seeking compliance and savings. Aruba’s IT4 in Rome exemplifies this trend with five duplicate buildings, 30 MW IT load, and renewable power.
Growth momentum also ripples down to Tier 1 and Tier 2 for edge or cost-sensitive projects. Yet as business continuity rises on boardroom agendas, these lower tiers are yielding share to fault-tolerant designs. The Italy data center construction market therefore shows a clear shift toward premium reliability, with operators positioning modular Tier 4 capacity along seismic lines to minimize disruption risk.


By Data Center Type: Hyperscalers Reshape Construction Patterns
Despite colocation’s 55.94% 2025 base, self-build hyperscaler projects rise 18.98% per year. Microsoft’s EUR 4.3 billion investment in Northern Italy, paired with AI-ready architecture, typifies this pivot. Google Cloud blends self-build and outsource by leasing space from TIM in Milan and Turin, illustrating hybrid forms that optimize speed and compliance. This wave enlarges the Italy data center construction market size for hyperscale to an estimated USD 2.39 billion by 2031, equal to 27.65% of total value.
Edge and enterprise builds grow moderately but still anchor regional diversification. The build-to-lease model lowers capital-heavy lifting for hyperscalers: Oracle’s Turin region runs inside a TIM campus, meeting uptime and sovereignty goals without direct land ownership. Pension and infrastructure funds are eager landlords, turning predictable 20-year hyperscale leases into bond-like returns, and thereby injecting new capital into the Italy data center construction industry.
By Infrastructure, Electrical Type: Power Distribution Innovation Accelerates
Power backup systems own 52.93% of spending today, a testament to uninterruptible uptime needs. Still, power distribution gear posts the quickest 18.56% CAGR as racks climb from 5-10 kW to 40-50 kW. The Italy data center construction market size for distribution is set to double by 2031, propelled by AI clusters like iGenius’s southern campus featuring 80 Nvidia servers. Terna’s smart-grid upgrades dedicate EUR 3.4 billion to data-center-oriented substations, enabling real-time load management.
Advanced busways, solid-state transformers, and on-site battery energy storage now appear in RFPs as standard. Operators are also pre-wiring for future fuel-cell integration. These investments streamline commissioning timelines while satisfying KPIs set by the EU’s forthcoming sustainability scorecard.
By Mechanical Infrastructure: Cooling Systems Face AI Challenge
Cooling ruled 47.88% of spend in 2025, but servers and storage—climbing 16.13% annually—now dictate mechanical design. Liquid immersion, rear-door heat exchangers, and heat-recovery loops shift facility layouts. Leonardo’s DaTEG system delivers 30% better chip performance at lower wattage, proving advanced thermal management’s ROI. The Italy data center construction market must also adapt cabinet structures for heavier liquid lines and denser gear while ensuring seismic integrity.
Operators capture new revenue by selling recovered heat to district utilities, as Retelit’s Avalon 3 does for 1,250 homes. Such innovations not only align with EU climate targets but also mitigate grid strain by offsetting regional heating demand.
Geography Analysis
Northern Italy remains the epicenter, with Lombardy and Piedmont accounting for roughly 61.58% of 2025 spend thanks to dense fibre routes, renewables access, and a seasoned supply chain. Milan hosts major campuses from Aruba, Data4, Microsoft, and AWS, while Turin gained momentum after Oracle and Google Cloud established sovereign cloud zones. This cluster effect accelerates lead-times but risks grid-capacity saturation, prompting operators to scout Central and Southern parcels.
Sicily’s Palermo, bolstered by Sparkle’s Sicily Hub and the 240 Tbps BlueMed cable, positions the island as a tri-continent gateway. Genoa adds a second landing point that slashes latency for North Africa and Middle East traffic, enlarging the Italy data center construction market potential along the Ligurian coast. Bologna’s “Data Valley,” centered on the Leonardo supercomputer, attracts HPC-heavy tenants and research consortia, diversifying demand beyond commercial cloud.
Southern regions leverage abundant solar and wind, lower land costs, and PNRR incentives. iGenius’s USD 1 billion project illustrates this pivot, integrating renewable power and AI supercomputing. Yet seismic engineering inflates CAPEX, triggering use of the Sismabonus tax break to recover up to 50% of reinforcement spend. Despite higher upfront outlays, operators value location diversity for disaster recovery and carbon-free energy procurement, broadening the Italy data center construction market footprint.
Regulatory Landscape
Italy’s data center builds operate under a fast-evolving framework that combines EU sustainability disclosure requirements (effective from September 2024 for energy KPI reporting) with national measures to accelerate permitting and grid access. In 2026, the Energy Decree-Law (Law Decree No. 21/2026) introduced a unified national authorization procedure for data center construction and expansion, plus related grid-connection works, consolidating steps such as environmental assessments into a single process managed by the competent authority for the Integrated Environmental Authorization (AIA), with a standard 10-month timeline (extendable by three months for complex projects).
Oversight spans multiple bodies. AGCom regulates electronic communications, while the National Cybersecurity Agency (ACN) sets certification, resilience, and security expectations that influence design and operational requirements for sensitive workloads. On the industrial and connectivity side, MIMIT steers digital and industrial policy alignment (including public-sector digital transition programs), and energy and infrastructure decisions intersect with MASE and regional authorities, making early stakeholder coordination a key compliance task for developers.
Value Chain Analysis
The Italy data center construction value chain typically starts with land acquisition and grid-capacity planning, followed by feasibility, design, and permitting that increasingly reflect the 2026 unified authorization pathway under Law Decree No. 21/2026. Engineering and design services feed into procurement of electrical (power distribution and backup) and mechanical (cooling) systems, general construction, and then integration, commissioning, and long-term support and maintenance. Grid-connection availability remains a gating input, so developers generally secure utility engagement early and evaluate on-site generation and self-consumption models alongside traditional interconnection.
Demand is shaped by hyperscalers, colocation providers, and public-sector digital programs, with national digital sovereignty priorities and initiatives such as the Polo Strategico Nazionale (PSN) influencing location and compliance choices. Governance and execution involve coordination across ministries (including MIMIT and MASE) and regional authorities, while sustainability requirements reinforce procurement shifts toward renewable supply, high-efficiency cooling, and heat-recovery-ready designs. This tightens the link between energy developers, equipment OEMs, and data center operators during project delivery.
Competitive Landscape
Competition balances between legacy telcos (TIM, WindTre), pure-play providers (Aruba, Retelit), and hyperscalers with voracious capacity needs. TIM commands the largest domestic footprint through 16 data centers and cloud pacts with Google and Oracle. Aruba differentiates via 100% renewable portfolios, Rating 4 certifications, and heat-recovery pilots, drawing sustainability-focused tenants. Microsoft, AWS, and Google underpin the bulk of greenfield work, often through land-lease or powered-shell partnerships that de-risk local execution.
Private equity and infra funds are amplifying firepower: Bain Capital’s 80% stake in AQ Compute and InfraVia’s 50% purchase of Iliad’s OpCore unlock billions for expansion. Strategic moves include Phoenix Tower’s edge-ready mast acquisition, Vantage Data Centers’ EUR 1.4 billion EMEA allocation, and Terna’s escalated capex to safeguard grid resilience. The Italy data center construction market thus sees rising M&A pace, vendor consolidation, and heavier emphasis on ESG compliance as a competitive differentiator.
Italy Data Center Construction Industry Leaders
AECOM
Arup Group Limited
DPR Construction, Inc.
Schneider Electric SE
Fortis Construction, Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Named campus programs and financing structures are expanding the investable pipeline and widening opportunities beyond the established Milan cluster. EdgeConneX’s Campus Italia program (three campuses, 300 MW, EUR 3 billion, Lombardy), Apto’s EUR 3 billion Lacchiarella campus plan, and Rai Way’s approved EUR 400 million hyperscale development in Pomezia (Rome) are adding concrete project scale. Investor-led platforms are also forming to scale renewable-powered capacity, including the Green Arrow Capital and Gruppo Lazzari joint venture (EUR 1 billion) focused on a network of renewable-supplied sites, which reinforces the build-to-lease and powered-shell approaches already used by hyperscalers.
Two near-term opportunity pockets are emerging from observed constraints: (i) power-led design and delivery, including projects that integrate on-site renewables and self-consumption to navigate grid congestion and queue times, and (ii) regional diversification tied to connectivity and public digital migration, including Sicily and other southern and central nodes. Here, subsea landings and PNRR-linked digital infrastructure programs support new demand corridors. With a reported pipeline exceeding 1.2 GW across active projects and 174 active centers cited in industry tracking, developers that can package permitting readiness, grid strategy, and sustainability compliance into bankable delivery schedules gain leverage with both hyperscalers and public-sector-aligned tenants.
Recent Industry Developments
- July 2026: CyrusOne MIL1 data center broke ground in Segrate, Milan (27MW). The launch expands CyrusOne's northern Italy footprint and accelerates hyperscale capacity to serve AI and cloud workloads in the region. The project strengthens the Milan cluster and supports 2031 market scale projections.
- July 2026: Rai Way Planning permission secured for �400 million hyperscale data center campus in Pomezia, Rome. The planning milestone unlocks sizeable new capacity in the Rome region and advances regulatory certainty for large-scale investments. Anchors future capacity in central Italy and reinforces Rome as a hyperscale hub, supporting grid and connectivity plans.
- June 2026: Apto Investment confirmed at �3 billion for 300MW data center campus in Lacchiarella, Milan. This is the largest single-site data center campus announced in 2026 and signals strong demand in Lombardy. Drives scale in Lombardy and influences workforce, supply chain, and regional ESG integration.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the market counts spending to build and fit out data centers in Italy, covering site works, building, and the main technical systems needed to run a facility (power and cooling) up to commissioning.
Scope exclusions: We exclude ongoing facility operations and recurring service contracts, and we also exclude pure telecom network rollout outside the data center boundary.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the hard outer limits of the model, and then to keep the spend logic realistic for Italy. We reviewed public and official sources that help explain construction activity and cost movement, such as national statistics on construction output and price indices, electricity and grid development publications, and permitting or planning releases from local authorities.
To translate activity into market value, we also used materials on data center build practices and efficiency trends from sources such as the European Commission and Eurostat, industry groups that discuss digital infrastructure, and peer reviewed engineering journals that cover cooling, electrical rooms, and energy performance. Company filings, investor presentations, reputable press, and paid company financials, contract and tender records, and patent look ups were used to cross-check timelines and technology choices. These sources are illustrative, and many other references were also consulted for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on confirming what is being built in Italy and how budgets are split across civil works, electrical, and mechanical packages, since these splits can move totals materially. We spoke with a mix of project delivery teams, contractors, consultants, and end users, and we kept coverage balanced across the main hubs and secondary sites so our assumptions could be checked against procurement behavior and project phasing in practice.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 15% |
| Mid tier: 56% | Functional/Unit leaders: 31% |
| Smaller Players: 17% | Managers: 54% |
Market-Sizing & Forecasting
The core sizing starts from a top-down build pipeline for Italy, where announced and permitted capacity additions are converted into annual construction spend using typical cost per MW and cost per square foot logic, and then allocated across electrical, mechanical, and general construction work. To keep the output grounded, we corroborate the totals with selective bottom-up checks, including sampling project budgets from public disclosures, doing channel checks on equipment ordering cycles, and validating a few representative builds against cost benchmarks.
Key inputs in the model include upcoming and live IT load additions (MW), the mix of colocation versus self-build projects, the tier level being targeted, and the timing of grid connections and energization, which often determines when the largest electrical spend occurs. We also track construction cost indices, power pricing signals that influence design choices, and observed shifts toward higher rack density that can change cooling and electrical scope. For forecasting, scenario analysis is applied around capacity delivery timing and cost inflation, and then final year-by-year values are smoothed with an exponential trend path that is reviewed and adjusted using primary feedback on lead times and procurement behavior.
Data Validation & Update Cycle
Validation is done in several passes so the numbers are not driven by one data stream. We check model outputs against independent signals like known capacity additions, construction start announcements, and macro construction cost movement, and then any sharp jumps are reviewed back to the project list and underlying assumptions. Where variance remains high, respondents are re-contacted to confirm whether a change is real, for example a delayed grid connection or a scope shift from shell-only to full fit-out.
Before sign-off, the model and key assumptions are reviewed by another analyst, and outliers are challenged until the drivers are clearly explained. The report is refreshed annually, and interim updates are triggered if there are material events such as large project cancellations, new hyperscale commitments, or major changes in power availability. Right before delivery, a final pass is completed so clients receive the most current view available.
黑料不打烊's Italy Data Center Construction Market Size Versus Other Published Estimates
Published market numbers for Italy data center construction can look far apart because authors do not always count the same build boundary, or they apply different timing rules for when a project becomes spend. Differences also show up when currency conversion methods vary, or when cost inflation is handled with a single flat factor instead of year-by-year adjustments.
Evidence like announced facility investments, stated MW additions, and tiered fit-out plans are the checks used to keep 黑料不打烊's 2025 estimate tied to construction and fit-out spending, rather than mixing in IT hardware value or full operating revenue. Another common gap comes from whether models include only new builds, or whether they also pull in refurbishment and upgrade work, which can lift totals in mature sites even when new capacity is not accelerating.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 3.82 B (2025) | |
| Trade Bulletin A | USD 3.13 B (2024) | Uses an investment lens that can lag construction timing, and it may apply a different split between general construction and technical fit-out, which reduces the counted spend in early project phases. |
| Industry Brief B | USD 4.00 B (2025) | Tends to broaden the boundary by blending adjacent upgrade and retrofit programs into the annual total, and it can overstate value if euro budgets are converted at spot rates without normalizing to a consistent base. |
The table shows that the spread is mainly explained by what gets counted as construction spend in a given year, and whether adjacent categories like refurbishments and currency effects are folded into the total. By keeping the scope tied to build and fit-out packages and then re-checking project timing through multiple signals, the estimate stays transparent and repeatable for decision-making.


Key Questions Answered in the Report
What is the current Italy Data Center Construction Market size?
The Italy Data Center Construction Market is projected to register a CAGR of 14.55% during the forecast period (2026-2031)
Who are the key players in Italy Data Center Construction Market?
AECOM, Arup Group Limited, Legrand, Daikin Applied and STULZ are the major companies operating in the Italy Data Center Construction Market.
What years does this Italy Data Center Construction Market cover?
The report covers the Italy Data Center Construction Market historical market size for years: 2019, 2020, 2021, 2022, 2023, 2024 and 2025. The report also forecasts the Italy Data Center Construction Market size for years: 2026, 2027, 2028, 2029, 2030 and 2031.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Data Center Power Market Power systems worldwide, split by component, tier and facility size.
- Italy Data Center Power Market Power systems demand across Italy, covering component, facility type and facility size.
- France Hyperscale Data Center Market Hyperscale sites demand across France, covering facility type, component and tier.
- Italy Data Center Rack Market Racks demand across Italy, covering rack size, rack height and rack type.
- China Data Center Power Market China power systems, split by component, facility type and facility size.
- Italy Hyperscale Data Center Market Hyperscale sites in Italy, split by facility type, component and tier.
- Italy Data Center Networking Market Networking demand across Italy, covering component, end-user and data-center type.



