
United Kingdom Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Historical Data Period | 2020 - 2024 |
| Market Size (2026) | USD 2.25 Billion |
| Market Size (2031) | USD 4.92 Billion |
| Growth Rate (2026 - 2031) | 16.94 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |

United Kingdom Data Center Construction Market Analysis by 黑料不打烊
The United Kingdom data center construction market size reached USD 2.25 billion in 2026 and is projected to climb to USD 4.92 billion by 2031, reflecting a 16.94% CAGR over the period. Hyperscaler pre-leasing, government designation of data centers as critical national infrastructure, and sovereign ambitions for domestic AI compute are compressing development cycles and lifting funding appetite. A pivot toward GPU-dense designs is forcing higher rack power densities and accelerating the shift from air to liquid cooling. Meanwhile, grid congestion in the South-East and inflation in mechanical-electrical-plumbing (MEP) inputs are nudging capital toward Manchester, Scotland, and other regions where renewable electricity and land remain available. Partnerships between general contractors and specialist MEP firms are becoming the norm as owners demand turnkey delivery within narrower schedules.
Key Report Takeaways
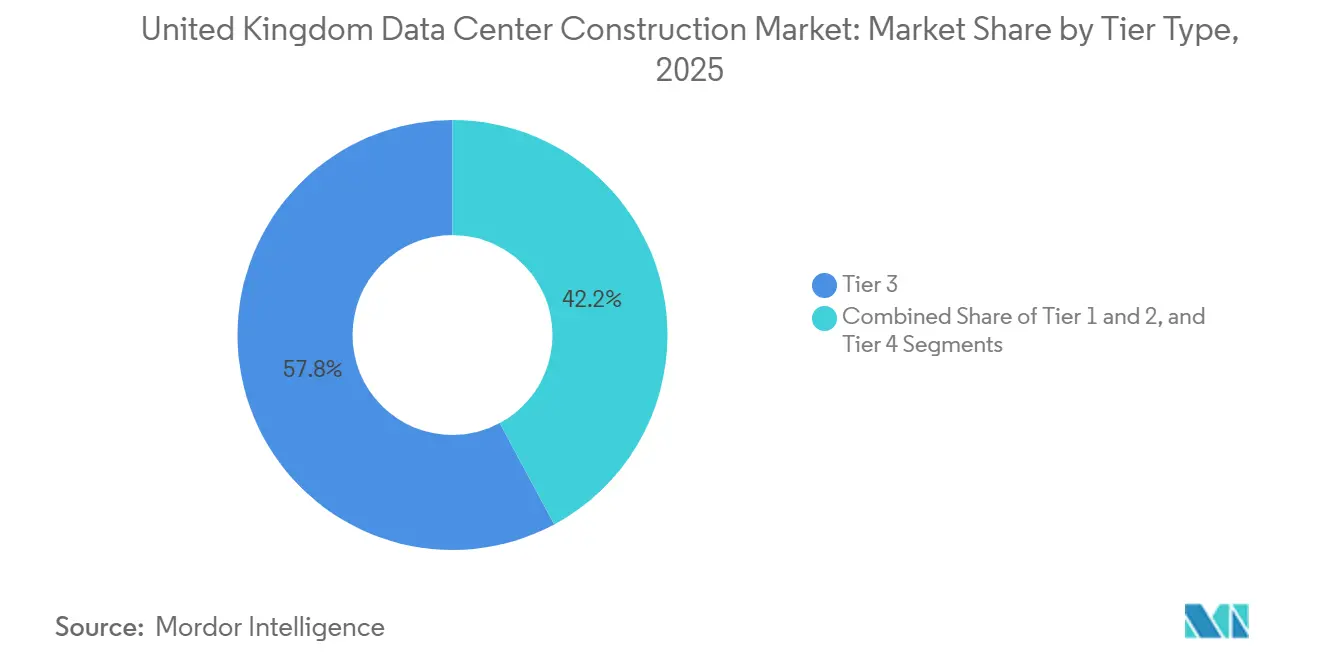
- By Tier Type, Tier 3 facilities led with a 57.84% revenue share in 2025, while Tier 4 is projected to advance at a 17.32% CAGR through 2031.
- By Data Center Size, hyperscale configurations accounted for a 62.65% share of the United Kingdom data center construction market size in 2025 and are poised to expand at a 17.43% CAGR to 2031.
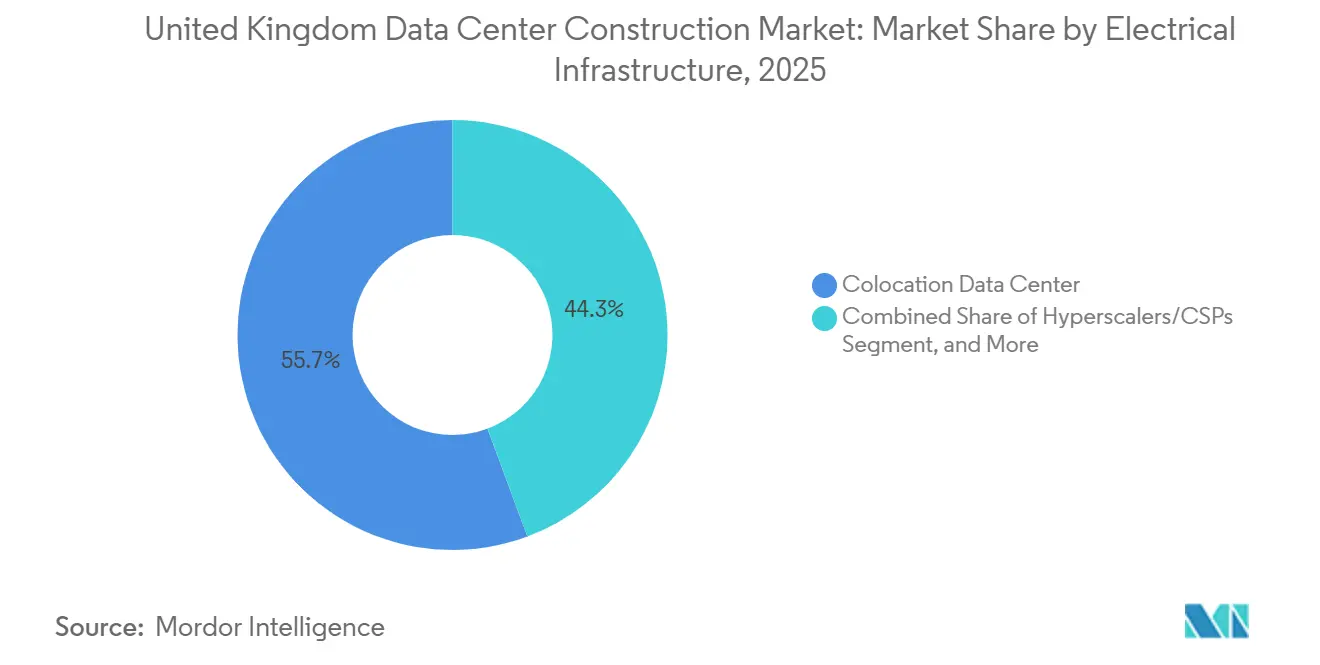
- By Data Center Type, colocation sites captured 55.68% of the United Kingdom data center construction market share in 2025, whereas owned hyperscaler facilities are set to grow at a 17.86% CAGR through 2031.
- By Infrastructure, electrical systems accounted for 40.45% of 2025 spending, yet mechanical infrastructure is forecast to post a 17.66% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
United Kingdom Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscaler Pre-Leasing and AI-GPU Demand Wave | +4.8% | National, concentrated in South-East England and Manchester | Short term (≤ 2 years) |
| 5G/6G Roll-Out Accelerates Edge and Core Build-Outs | +3.2% | National, early gains in London, Manchester, Edinburgh | Medium term (2-4 years) |
| Government AI Growth Zones and ?14 Billion CNI Program | +2.9% | National, priority zones in Manchester, West Midlands, Edinburgh | Medium term (2-4 years) |
| Nationally Significant Infrastructure Fast-Track Permits | +2.1% | National, especially South-East England and Midlands | Short term (≤ 2 years) |
| Data-Center-as-Critical-Infrastructure Tax Incentives | +1.6% | National | Medium term (2-4 years) |
| On-Site Small-Modular-Reactor Pilots for Green Power | +0.9% | Pilot sites in Northern England and Scotland | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Hyperscaler Pre-Leasing and AI-GPU Demand Wave
Microsoft’s GBP 30 billion pledge bundled owned halls with long-term pre-leases that guarantee occupancy as soon as power is switched on?. Google followed with a GBP 5 billion (USD 6.12 billion) program that locks in tenant status for GPU-dense space across multiple campuses. Nvidia then committed GBP 11 billion (USD 13.6 Billion) to inference-optimized capacity, further validating the anchor-tenant model. Developers such as CyrusOne secured 90 MW in Enfield before breaking ground, compressing financing spreads by 150-200 basis points?.[1]UK Department for Science, Innovation and Technology, “AI Growth Zones Announced,” gov.uk The government’s critical-infrastructure designation reinforced investor confidence by signaling regulatory stability.[2]CyrusOne, “CyrusOne Announces LON6 Data Centre in London,” cyrusone.com
5G ? 6G Roll-Out Accelerates Edge and Core Build-Outs
BT and AWS activated Wavelength Zones in London and Manchester, embedding cloud compute inside carrier networks to hit sub-10 millisecond latency for augmented-reality and autonomous-vehicle workloads. Vodafone paired with Google Cloud to deploy edge nodes across 15 cities by 2026, spreading demand beyond traditional hubs. The private 5G grid at Thames Freeport shows industrial clusters bypassing public carriers for dedicated edge infrastructure. A GBP 1 billion diversification fund is subsidizing domestic equipment supply, shortening procurement cycles for new micro-data centers. These initiatives fragment capacity additions into dozens of 1-5 MW sites, extending the construction opportunity set nationwide.
Government AI Growth Zones and ?14 Billion CNI Program
Data-center designation as critical national infrastructure unlocked accelerated consultations and tied the sector to a GBP 14 billion (USD 17.36 billion) public-private upgrade plan for grid, fiber, and roads. AI Growth Zones in Greater Manchester, the West Midlands, and Edinburgh received GBP 500 million (USD 620 Million) to cut connection fees and shave months from project timelines. National Grid awarded a GBP 9 billion (USD 11.2 billion) reinforcement framework that allocates 15 GW of South-East capacity by 2030, assuring developers that power will be available when sites go live. Collectively, the grants and grid upgrades add almost three percentage points to mid-term build velocity.
Nationally Significant Infrastructure Fast-Track Permits
The Planning and Infrastructure Act 2025 moved data center projects above 50 MW into the Nationally Significant Infrastructure Project regime, cutting approval windows from 18 months to about 6 months. Updated National Policy Statements EN-1, EN-3, and EN-5, published in January 2026, put data centers on the same policy footing as power plants. The Abbots Langley case, which lingered 14 months in local appeals before winning permission, illustrates the delays the new regime eliminates. While developers must now submit net-zero pathways and secured grid offers up front, the streamlined path materially derisks large campuses.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid Congestion in South-East, 132 kV Moratoriums | -3.1% | South-East England, notably Greater London and Thames Valley | Short term (≤ 2 years) |
| Construction-Grade Labor and MEP Cost Inflation | -2.4% | National | Medium term (2-4 years) |
| Local Opposition over Water and Visual Footprint | -1.2% | Water-stressed South-East and select rural sites | Medium term (2-4 years) |
| Tight EU/UK Scope-3 Carbon-Reporting Compliance | -0.8% | National | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Grid Congestion in South-East, 132 kV Connection Moratoriums
National Grid ESO paused new 132 kV offers in parts of Greater London and surrounding counties, creating seven-to-ten-year delays unless developers bankroll costly upstream upgrades. Project budgets can rise by GBP 150 million (USD 186 million) for a 100 MW campus under such self-funded reinforcement. Equinix chose a bespoke 400 kV feed for its GBP 3.9 billion (USD 4.84 billion) Hertfordshire campus, but the workaround added 18 months to the pre-construction timeline. Developers are therefore pivoting to Manchester and Scotland, where SP Energy Networks and SSE Networks still offer three-year energization slots.
Construction-Grade Labor and MEP Cost Inflation
RICS recorded a 12% year-on-year jump in MEP wages in 2025, reflecting post-Brexit skill shortages and competition from residential megaprojects.[3]Royal Institution of Chartered Surveyors, “UK Construction Market Survey,” rics.org Schneider Electric noted that transformer lead times extended to 42 weeks, up from 26 weeks two years earlier. Copper prices climbed 18% in 2025, inflating busbar and cabling costs. Builders that deploy factory-fabricated skids have cut on-site labor by up to 40% and trimmed schedules by eight months, yet Balfour Beatty reports adoption below 20% of new build value.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Redundancy Premium Drives Tier 4 Uptake
Tier 3 sites captured 57.84% of revenue in 2025, underscoring their suitability for general enterprise workloads that tolerate planned maintenance windows. The Financial Conduct Authority’s operational-resilience mandate, effective March 2025, requires banks to withstand infrastructure failures, nudging critical applications toward Tier 4 halls that duplicate every power and cooling path. Although Tier 4 designs demand 30-40% more capital, they remove downtime risk, appealing to financial services and healthcare operators. Over 2026-2031, Tier 4 is forecast to register a 17.32% CAGR, outpacing the broader United Kingdom data center construction market.
Demand for Tier 3 remains healthy among price-sensitive colocation customers. Operators such as Digital Realty recently expanded London campuses with Tier 3, N+1 redundancy to balance uptime guarantees against competitive rent. Tier 1 and Tier 2 footprints continue to shrink as legacy enterprise sites are decommissioned. The net effect is a gradual migration toward higher redundancy, aligning with government rhetoric on critical infrastructure and supporting the United Kingdom data center construction market’s premium-driven growth profile.


By Data Center Size: Hyperscale Supremacy
Hyperscale campuses exceeded 50 MW and accounted for 62.65% of revenue in 2025. Power-purchase leverage, cooling economies, and labor utilization drive power usage effectiveness (PUE) below 1.15, compared with 1.4-1.6 for smaller builds. Equinix’s Hertfordshire expansion and QTS’s GBP 10 billion (USD 12.4 billion) Blyth plan exemplify modular phasing, allowing supply to track tenant ramps. Over the forecast period, hyperscale is expected to record a 17.43% CAGR, reinforcing its dominance in the United Kingdom data center construction market.
Large (10-50 MW) and medium (5-10 MW) facilities together attract regional enterprises that need proximate compute but lack hyperscale budgets. Kao Data’s 30 MW Manchester campus typifies this cohort. Small edge sites under 5 MW are declining as compute shifts into telecom street furniture. Overall, scale remains the single-largest predictor of capital efficiency, ensuring hyperscale’s structural advantage persists.
By Data Center Type: The Colocation-Hyperscaler Hybrid
Colocation operators held a 55.68% stake in 2025, driven by enterprise lift-and-shift migrations and tight capital budgets. Yet owned hyperscaler sites are projected to expand at a 17.86% CAGR as Microsoft, Google, and AWS internalize GPU clusters to fine-tune cooling, network, and security parameters. Anchor leases are still common: Equinix pre-leased entire Hertfordshire phases to multiple hyperscalers, locking in 15-year revenue streams while retaining ownership of the buildings.
Enterprises lacking hyperscale balance sheets gravitate toward colocation, drawn by renewable energy procurement and carbon-tracking services. Edge data centers account for a shrinking 15% slice because mobile operators now co-locate compute at tower sites. Consequently, a hybrid model, developer-owned real estate tailored to hyperscaler specifications, defines the future profile of the United Kingdom data center construction market.
By Infrastructure: Liquid Cooling Reconfigures CapEx Mix
Electrical systems accounted for 40.45% of 2025 spending, reflecting the capital-intensive nature of substations, switchgear, and uninterruptible power supplies. However, mechanical infrastructure is set to rise at a 17.66% CAGR as racks transition from 8 kW air-cooled to 60 kW liquid-cooled configurations. Direct-to-chip solutions and immersion tanks are proliferating; Mitsubishi Electric’s rear-door heat exchangers enable 40 kW racks without overhauling legacy mechanical rooms. Stellium’s Slough retrofit cut PUE from 1.4 to 1.05, confirming the operational upside.
General construction and professional services together account for roughly 35% of spend, but their shares will decline as prefabricated modules push more value into factory settings. The cooling revolution, therefore, reshapes the bill of materials and sustains double-digit expansion within the United Kingdom data center construction market.
Geography Analysis
The South-East commanded roughly 65% of 2025 investment, thanks to proximity to London’s financial core, subsea cable landings, and dense dark-fiber routes. Equinix, Colt DCS, and Ark Data Centres each broke ground on multi-billion-pound expansions, but grid connection freezes and outspoken water utilities have tempered enthusiasm. Developers are responding by adopting closed-loop or adiabatic systems that curb water draw by up to 80%, mitigating community opposition.
Manchester captured 15% of new build value in 2025, buoyed by AI Growth Zone grants and SP Energy Networks’ three-year connection offers. BT-AWS Wavelength Zones underline the city’s edge-compute credentials, while Kao Data’s campus demonstrates the appetite for mid-scale capacity. The West Midlands and Edinburgh are gaining traction on similar policy and connectivity logic.
Scotland attracted 8% of 2025 spend, led by QTS’s Blyth megaproject and abundant wind power that yields power purchase agreements at below-market rates. Lower land prices and cool ambient temperatures provide additional incentives, even though fiber backhaul to London incurs longer routes. Wales and the Midlands shared the remaining 12%, with Thames Freeport’s private 5G initiative showcasing industrial-edge potential.
Grid relief frameworks, renewable surpluses, and infrastructure grants are nudging capital beyond the M25. As a result, regional diversification lessens the South-East bottleneck and broadens opportunity across the United Kingdom data center construction market.
Regulatory Landscape
The UK has moved data centers into a more centralized, infrastructure-style consenting and policy framework. Data centers were designated as Critical National Infrastructure in September 2024, elevating expectations around resilience, security, and continuity planning across design and operations. Building on that shift, the Nationally Significant Infrastructure Project (NSIP) pathway was extended to qualifying data center schemes via the Infrastructure Planning (Business or Commercial Projects) (Amendment) Regulations 2026, effective 8 January 2026, complementing the Planning and Infrastructure Act 2025 changes referenced in the report and tightening the link between large campuses and national permitting processes.
Policy support is also being operationalized through DSIT programs and guidance intended to reduce bottlenecks in planning and power access. DSIT has positioned AI Growth Zones to accelerate delivery of large-scale AI-capable capacity and is developing a National Policy Statement for data centers to set clearer decision criteria, while a GBP 4.5 million national expert team supports local planning authorities handling data center applications. Alongside updated National Policy Statements (EN-1, EN-3, EN-5) published in January 2026, these steps raise the importance of front-loaded evidence on grid offers, net-zero pathways, and environmental impacts (notably water use) within UK data center construction permitting.
Competitive Landscape
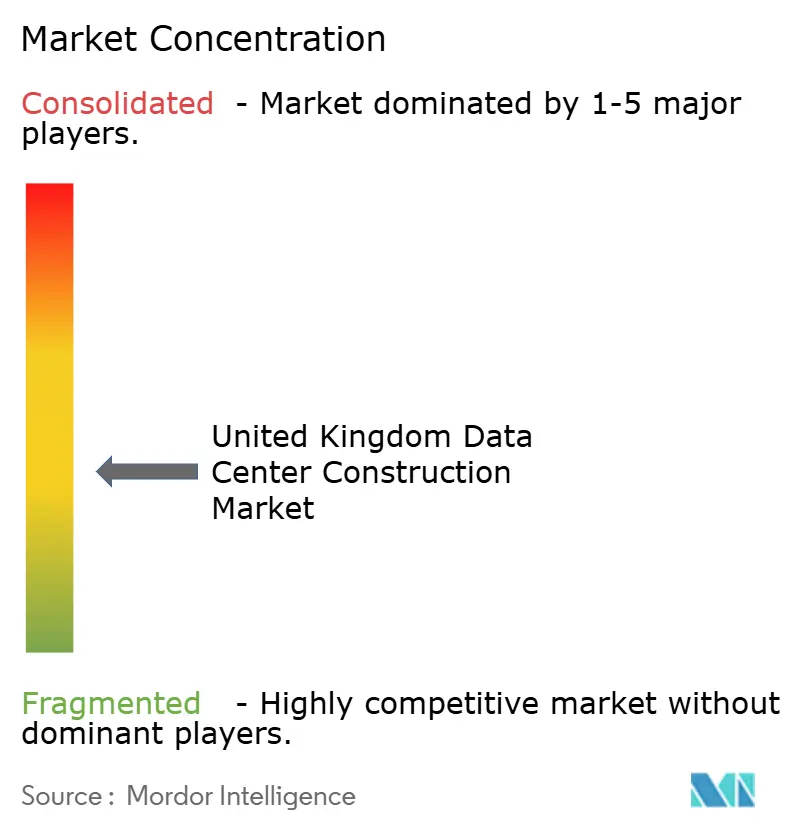
The market is moderately fragmented. Skanska, ISG, and AECOM dominate shell-and-core scopes, while Mercury Engineering, Mace, and Laing O’Rourke lead MEP packages. Equinix’s choice of a Skanska-Mercury joint venture on Hertfordshire signals a trend toward integrated project delivery, where design, procurement, and build risk sit with a single consortium.
Modular construction remains a white-space opportunity: fewer than one-in-five new builds use factory-fabricated skids, yet those that do report 30-40% reductions in on-site manpower and eight-month schedule savings. Equipment vendors such as Schneider Electric are climbing the value stack by bundling software that monetizes battery arrays in frequency-response markets.
Emerging specialists in liquid cooling, notably Submer and LiquidStack, bypass traditional mechanical contractors by offering turnkey immersion solutions, carving out a profitable niche as AI workloads proliferate. Sustainability regulations further tilt the playing field toward firms that can quantify embodied carbon, an area where Mace and Arup invested heavily in digital toolsets during 2025. Overall, the competitive narrative remains dynamic but tilts toward integrated, sustainability-literate providers within the United Kingdom data center construction industry.
United Kingdom Data Center Construction Industry Leaders
ISG Ltd
AECOM
Rider Levett Bucknall
Mercury Engineering
Skanska UK plc
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Government-backed AI capacity programs and permitting changes are creating identifiable whitespace for large, power-intensive builds outside traditional London clusters, where grid congestion and 132 kV constraints have slowed timelines. DSIT's AI Growth Zones initiative explicitly targets large-scale AI data center capacity, with a stated ambition around 500 MW sites by 2030 and potential scaling beyond 1 GW, and the program design highlights tangible levers such as faster access to power and lower electricity costs for very large facilities. This reinforces opportunities for developers, EPCs, and MEP specialists to package end-to-end delivery propositions that combine high-voltage connection strategy (including 400 kV workarounds where needed), GPU-dense mechanical design (liquid cooling readiness), and planning documentation suitable for NSIP-style scrutiny.
A second opportunity set sits in the build-out of public and quasi-public compute and supply-chain localization tied to the UK's compute policy agenda. The UK government has committed up to GBP 2 billion (2025-2030) for a public compute ecosystem, including GBP 1 billion for AI Research Resource expansion, which can translate into projects with stricter requirements on security, operational resilience, and carbon reporting. In parallel, the UK AI Hardware Plan and Compute Roadmap point to procurement pathways and export-finance-enabled supply development, supporting demand for UK-based systems integration, prefabrication, and compliance tooling (for embodied carbon and Scope 3 reporting) within data center construction programs.
Recent Industry Developments
- July 2026: Ark Data Centres announced a ?807m investment at its Longcross Park campus in Surrey, including development of a new 36MW facility (LP02) for Nebius. The move expands UK sovereign and AI compute capacity; strengthens long-term demand for local build-out services.
- July 2026: John F Hunt was awarded a ?20m enabling works contract for a new hyperscale data center campus near the M25/M40 interchange. The award accelerates delivery timelines and boosts near-term on-site activity at the hub location.
- May 2026: Glencar secured a contract to construct the LON1B2 facility, a 70MW, 23,000 sq m data center at the Brent Cross campus in North London, valued at over ?100m. The project adds significant capacity in the London area, influencing regional market dynamics and bidding landscape.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, we define the market as the value of construction work delivered to build data centers in the United Kingdom, including core building works and the main fit-out systems needed to make the site operational.
Scope exclusions: We exclude routine facility maintenance, IT hardware purchases, and stand-alone network services that are not part of a construction or expansion project.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small
- Medium
- Large
- Hyperscale
- By Data Center Type
- Colocation Data Center
- Hyperscalers/Cloud Service Provider (CSPs)
- Enterprise and Edge Data Center
- By Infrastructure
- Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Services - Design and Consulting, Integration, Support and Maintenance
- Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts with building a clear picture of the UK data center build pipeline and the cost items that usually move the total project value. We rely on public sources such as the UK Office for National Statistics construction output series, UK Department for Energy Security and Net Zero publications on electricity supply and networks, and National Grid and Ofgem updates on connections and constraints, since power availability tends to dictate where and when projects can be delivered.
We also review permitting and planning signals through local authority portals, industry bodies such as Uptime Institute publications and Data Centre Alliance materials, and technical references from ASHRAE guidance plus peer-reviewed papers on cooling and energy efficiency (useful for checking design shifts like higher rack density). This is complemented with company filings, investor presentations, and reputable press coverage of campus announcements and expansions, followed by consistency checks using paid subscriptions that aggregate company financials, contract awards, and patent activity when we need comparable inputs across many projects. These desk sources are not exhaustive, and we used additional public references for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary work is used to confirm what the desk research cannot fully settle, mainly what is actually under construction now versus what is still in concept. We spoke with a mix of project owners, engineering and construction specialists, and key component contractors across the United Kingdom so schedule risk, MEP cost moves, and typical build specs could be checked and then applied consistently in the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 37% | CXOs: 16% |
| Mid tier: 43% | Functional/Unit leaders: 28% |
| Smaller Players: 20% | Managers: 56% |
Market-Sizing & Forecasting
Sizing is built using a top-down approach where construction demand is reconstructed from the UK project pipeline, typical capex per MW ranges, and the split of spend across civil works and MEP packages, before totals are mapped to the study years. Once that structure is stable, we cross-check it with selective bottom-up approximations, including sampled project-by-project roll-ups from public announcements and channel checks on average pricing, which are then used to adjust outliers.
A few inputs matter more than others in this market, so we keep them explicit in the model. These include planned and under-construction IT load additions (MW), average build cost per MW by build type, shifts in power density that change cooling design, grid connection timelines by region, and inflation trends in steel, concrete, and key electrical equipment. Where project values are not disclosed, gaps are handled using benchmark cost curves and confirmed ranges from interviews, and then the assumptions are applied consistently across similar builds.
For forecasting, scenario analysis is used because timing is strongly influenced by grid access, permitting, and financing cycles. The base case combines our view of the deliverable pipeline with expert consensus on cost escalation and design changes, and then sensitivities are run for delayed energization, faster AI-driven density upgrades, and normalization in MEP lead times.
Data Validation & Update Cycle
Validation is done in layers so the final numbers are not driven by one single data set. We compare model outputs against independent signals such as MW additions implied by public capacity announcements, construction output indicators, and reported capex programs, and then review variances until the drivers are clearly explained.
Anomaly checks are performed at the project and regional levels, followed by an internal review step where assumptions, conversions, and year mapping are rechecked before sign-off. Reports are refreshed annually, and interim updates are completed when material events happen, such as major campus approvals, large delays in grid connections, or step changes in equipment pricing. Before delivery, we complete a final analyst pass so clients receive the latest updated view.
黑料不打烊's United Kingdom Data Center Construction Market Sizing Compared With Other Published Estimates
Published market sizes for UK data center construction can look far apart, even when they appear to be measuring the same underlying construction scope. The main reasons are usually which spend categories are counted, what year is used as the base, and whether values reflect committed builds only or also include early stage plans.
In practice, the biggest gaps come from whether shell plus core and MEP fit-out are both included, how cost per MW is escalated over time, and how projects are filtered when grid connection dates are uncertain. Another common difference is currency timing and inflation treatment, since using a single fixed exchange rate or a flat cost index can shift totals quickly in a construction-led market.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 2.25 B (2026) | |
| Industry Report A | USD 2.18 B (2026) | Uses a narrower definition that focuses on core building and selected electrical works, and it applies more conservative escalation for MEP packages during the forecast window. |
| Advisory Brief B | USD 5.10 B (2026) | Often blends construction with broader data center investment budgets, which can pull in land, financing, and some non-construction program costs that sit outside delivered build value. |
The table indicates that much of the spread ties back to what is counted as construction value and how uncertain projects are handled when energization timing is not locked in. For that reason, filtering the pipeline to grid-secured and contract-ready phases helps keep the estimate grounded, which is an approach used in 黑料不打烊's analysis.


Key Questions Answered in the Report
What is the current value of the United Kingdom data center construction market?
The market was valued at USD 2.25 billion in 2026 and is on track to reach USD 4.92 billion by 2031.
Which segment is growing fastest within new builds?
Tier 4 facilities, favored by financial services and healthcare firms, are projected to post a 17.32% CAGR through 2031.
Why are hyperscale projects moving north of London?
Grid connection moratoriums, lower land costs, and renewable power availability in Manchester and Scotland are drawing capital away from the congested South-East.
How is liquid cooling changing construction budgets?
Direct-to-chip and immersion solutions are shifting more capital into mechanical systems, which are forecast to grow at a 17.66% CAGR through 2031.
What regulatory reforms have had the biggest impact recently?
The Planning and Infrastructure Act 2025 and updated National Policy Statements in 2026 reclassified large data centers as nationally significant, trimming approval timelines and de-risking projects.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Server Market Global servers demand, split by tier, facility size and facility type.
- Italy Data Center Power Market Power systems demand across Italy, covering component, facility type and facility size.
- Canada Data Center Power Market Power systems in Canada, split by component, tier and facility size.
- Germany Data Center Processor Market Processors demand across Germany, covering processor type, application and architecture.
- United Kingdom Hyperscale Data Center Market The UK's hyperscale sites, split by facility type, component and tier.


