
Canada Data Center Construction Market Size and Share
Market Overview
| Study Period | 2025 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.34 Billion |
| Market Size (2026) | USD 3.71 Billion |
| Market Size (2031) | USD 6.27 Billion |
| Growth Rate (2026 - 2031) | 11.05 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Canada Data Center Construction Market Analysis by 黑料不打烊
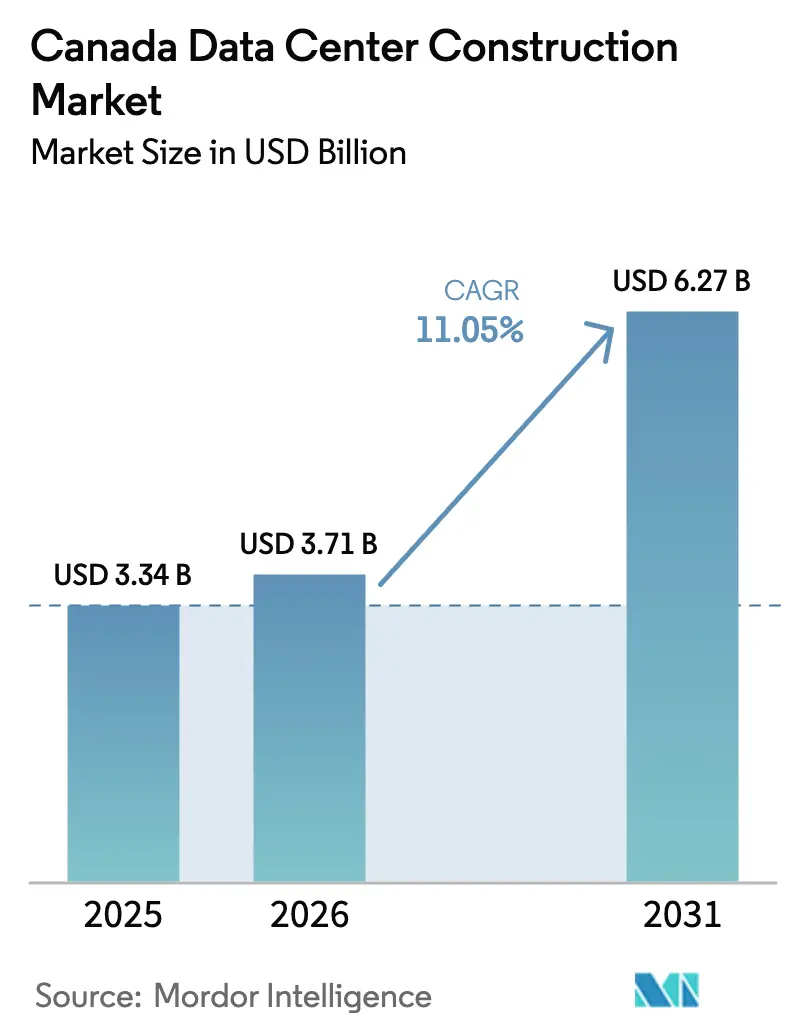
The Canada data center construction market size was valued at USD 3.34 billion in 2025 and estimated to grow from USD 3.71 billion in 2026 to reach USD 6.27 billion by 2031, at a CAGR of 11.05% during the forecast period (2026-2031). This growth is powered by Ottawa’s CAD 2.4 billion (USD 1.75 billion) sovereign AI compute package, hyperscale capital-expenditure programs, and abundant low-carbon hydroelectric capacity. Hyperscalers are pivoting from leased colocation halls to purpose-built campuses, spurring a rapid shift in design norms toward high-density racks, liquid cooling, and on-site generation. Alberta’s 1.2 GW phased grid-connection framework is accelerating self-build projects, while Quebec and British Columbia attract investment with renewable baseloads despite tighter water-use rules. Skilled-labor shortages and 4.3% year-over-year inflation in non-residential construction costs are lifting capital intensity, but bulk-procurement tactics and joint ventures with power developers are easing some pressure.
Key Report Takeaways
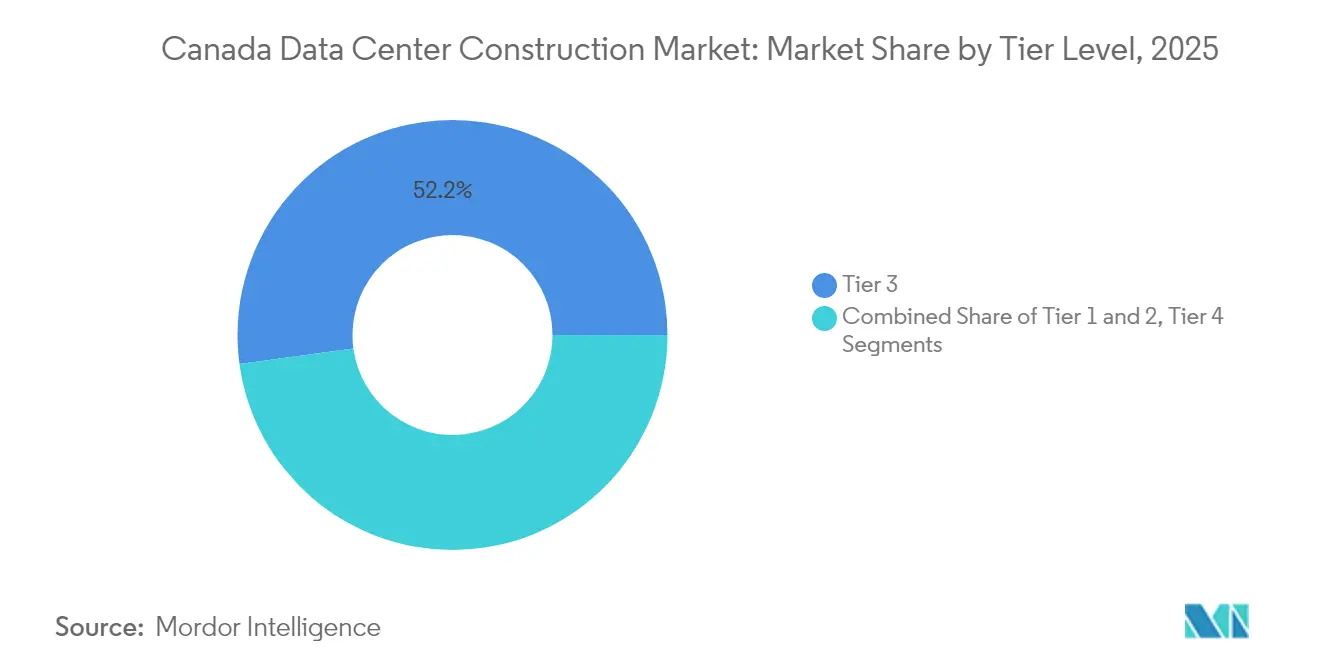
- By tier type, Tier 3 installations commanded 52.15% of the Canada data center construction market share in 2025, while Tier 4 projects are projected to post the fastest 12.95% CAGR to 2031.
- By data-center type, colocation facilities held 53.95% revenue share of the Canada data center construction market size in 2025; self-build hyperscalers are forecast to expand at 11.88% CAGR through 2031.
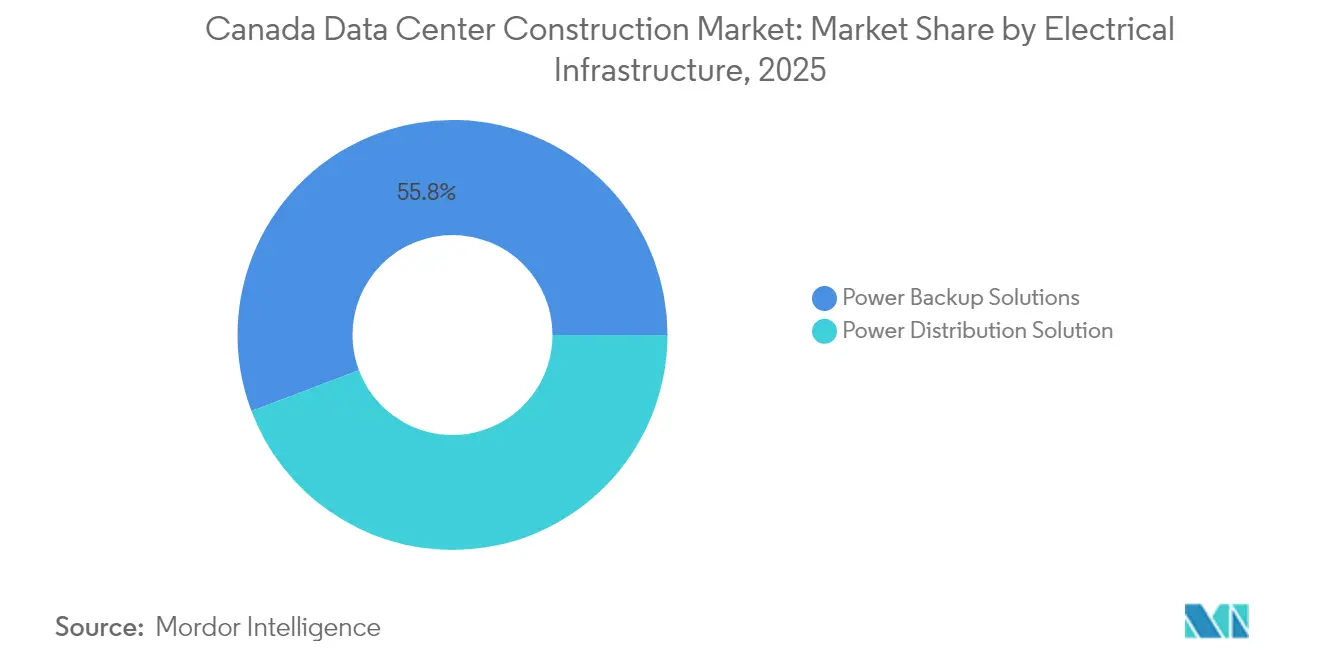
- By electrical infrastructure, power-backup systems accounted for 55.75% spending in 2025; power-distribution solutions lead growth at 13.02% CAGR to 2031.
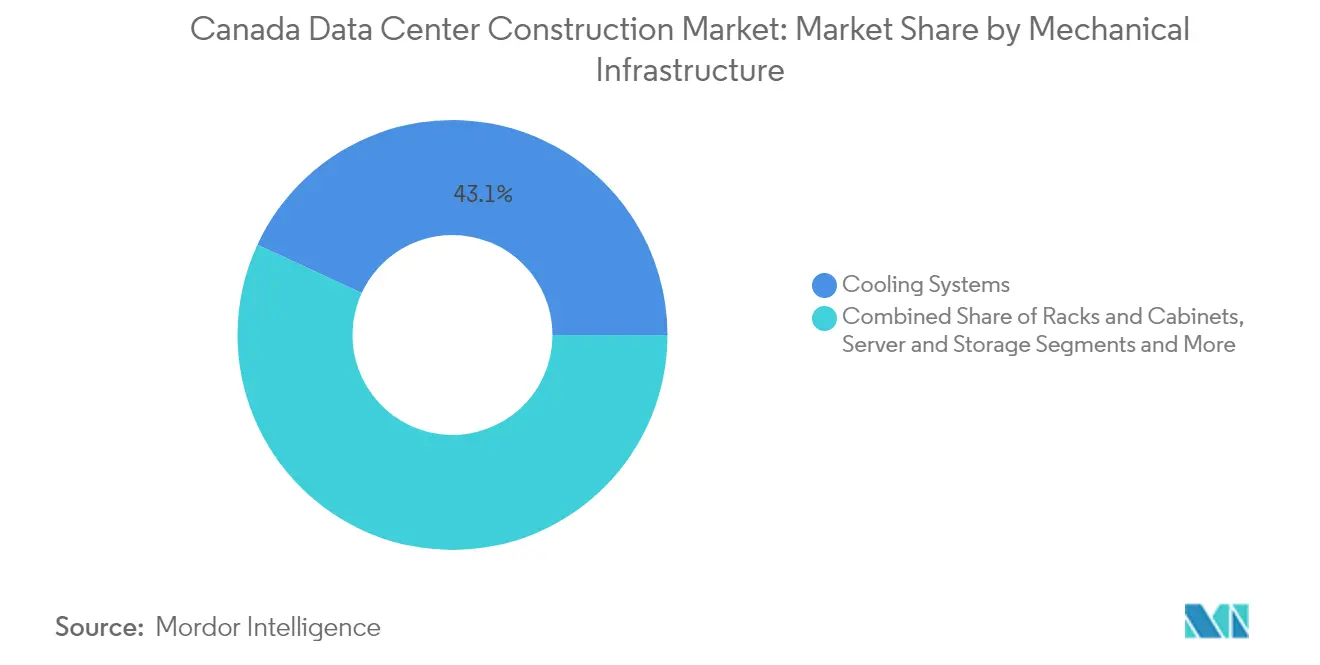
- By mechanical infrastructure, cooling systems captured 43.10% share of the Canada data center construction market size in 2025; servers and storage register the highest 12.29% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Canada Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Soaring cloud and AI workload demand | +2.8% | Global, with concentration in Toronto, Montreal, Calgary | Medium term (2-4 years) |
| Accelerating hyperscale CAPEX commitments | +2.1% | Alberta, Ontario, British Columbia | Short term (≤ 2 years) |
| Federal CAD 2.4 billion (USD 1.74 billion) Sovereign AI Compute Strategy | +1.9% | National, with early gains in Toronto, Calgary, Montreal | Medium term (2-4 years) |
| Abundant low-carbon hydro-power capacity | +1.6% | Quebec, British Columbia, Ontario | Long term (≥ 4 years) |
| Alberta's 1.2 GW phased grid-connection program | +1.4% | Alberta, with spillover to Saskatchewan | Short term (≤ 2 years) |
| Adaptive-reuse of vacant industrial assets | +0.8% | Toronto, Montreal, Vancouver metropolitan areas | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Soaring Cloud and AI Workload Demand
AI inference and training jobs consume 160% more energy than conventional workloads, prompting builders to specify liquid cooling, reinforced flooring, and surge-ready electrical topologies.[1]Canada Energy Regulator, “Energy Demand Outlook for AI Workloads,” cer-rec.gc.caBell Canada’s 500 MW AI supercluster in British Columbia illustrates how AI demand is dictating province selection, cooling modality, and megawatt scale. Developers now design for rack power densities that routinely exceed 50 kW. Grid interconnection studies incorporate transient peak-load modelling, and contracts with hydro utilities embed priority-service clauses that reduce downtime risk. The Canada data center construction market, therefore, sees growing bids for modular chillers, immersion cooling vats, and high-amp busways that minimize stranded capacity.
Accelerating Hyperscale CAPEX Commitments
AWS, Microsoft, and Google are redirecting multi-tenant budgets toward single-tenant Canadian campuses aligned with AI compute roadmaps. eStruxture’s 90 MW CAL-3 project in Calgary shows how hyperscalers value greenfield parcels that allow 100 acre layouts and tax-advantaged power-purchase agreements.[2]eStruxture Data Centers, “CAL-3 Hyperscale Campus Announcement,” estruxture.comCapital intensity exceeds USD 11 million per MW because facilities integrate on-site switchyards and three-stage liquid-cool loops. Longer lead times for transformers and generators are prompting design-build contracts with fixed-price escalation clauses. The Canada data center construction market is therefore experiencing a shift in tender criteria, rewarding contractors with pre-secured power-equipment supply chains
Federal CAD 2.4 Billion (USD 1.74 billion) Sovereign AI Compute Strategy
Ottawa’s program mandates that datasets and compute remain on Canadian soil, pushing builders to deliver Tier 4-equivalent redundancy plus isolated meet-me rooms. Cohere’s federally backed campus will include electromagnetic shielding and multi-factor security perimeters, boosting per-square-foot spend. Domestic ownership clauses favour Canadian REITs and pension funds, tightening local capital pools. Consequently, the Canada data center construction market is pivoting toward alliances that blend civil-works firms with cybersecurity specialists to satisfy bespoke bid specifications.
Abundant Low-Carbon Hydro-Power Capacity
Hydro-Québec’s CAD 50 billion (USD 36.42 billion) grid-expansion plan underwrites long-term renewable capacity, yet 2023 drought-induced export cuts remind planners to provision dual-fuel backup. Wonder Valley’s 1.4 GW off-grid campus pairs gas turbines with geothermal wells, reducing grid-interconnect delays.[3]Government of Alberta, “Wonder Valley Off-Grid Power Project Details,” alberta.caContractors must therefore integrate medium-voltage switchgear, black-start turbines, and heat-recovery chillers during initial pours. These hybrid designs lift mechanical-electrical-plumbing complexity and keep the Canada data center construction market on a steep learning curve for power-system integration.
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Grid-level power-availability bottlenecks | -1.8% | Alberta, Ontario, with emerging constraints in Quebec | Short term (≤ 2 years) |
| Escalating construction & MEP equipment costs | -1.2% | National, with highest impact in Toronto, Vancouver | Medium term (2-4 years) |
| Shortage of Uptime-tier-certified labour | -0.9% | National, particularly acute in specialized MEP trades | Long term (≥ 4 years) |
| Municipal water-use limits on liquid cooling | -0.6% | British Columbia, select Ontario municipalities | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Grid-Level Power-Availability Bottlenecks
Alberta’s system operator now caps new load at 1.2 GW, compelling developers to commission on-site generation before permitting. Pembina and Kineticor’s 1.8 GW gas plant, dedicated to data-center clients, extends build cycles by up to 18 months. Land negotiations must now coordinate pipeline easements and emissions-offset plans alongside traditional zoning. These factors lengthen critical-path schedules, constraining near-term capacity additions across the Canada data center construction market.
Escalating Construction and MEP Equipment Costs
Non-residential building costs rose 4.3% year over year in Q2 2024, outpacing headline inflation . UPS, chiller, and switchgear manufacturers report lead times stretching beyond 60 weeks, driving bulk-purchase consortiums among builders. Pipe, valve, and fitting spend is forecast at CAD 42.5 billion (USD 30.89 billion) for 2025, squeezing subcontractor cash flows. Contractors are passing through indexed material clauses and adopting prefab modular skids to reduce site labor. The Canada data center construction market therefore faces margin compression that could deter smaller entrants lacking scale.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Tier Type: Tier 4 Drives Premium Construction
The Canada data center construction market size allocated to Tier 3 facilities stood at USD 1.74 billion in 2025, yet Tier 4 projects post the leading 12.95% CAGR. Tier 4 specifications mandate dual power trains, isolated switchboards, and concurrently maintainable paths, lifting capex by more than 40% per MW. Borden’s CAD 322 million (USD 234.51 million) expansion that achieved Tier III certification showcases federal appetite for fault-tolerant assets. Contractors with Uptime Institute credentials command pricing premiums, and training pipelines lag demand, limiting bid competition across the Canada data center construction market. Standards Council of Canada’s immersion-cooling fluid code advances specialist fluid-handling skills that further differentiate Tier 4 builders.
Second-generation operators still refurbish legacy Tier 2 halls, but new enterprise workloads push procurement teams toward Tier 3 minimums. Insurance underwriters are tightening uptime covenants, prompting risk-sharing clauses that embed performance penalties. These trends sustain the Tier 4 momentum, underscoring rising technical-barrier moats in the Canada data center construction industry.


By Data Center Type: Hyperscaler Self-Build Momentum
Colocation still dominates with 53.95% revenue share of the Canada data center construction market size in 2025, but self-built hyperscale campuses race ahead at 11.88% CAGR. Bell Canada’s six-site AI Fabric demonstrates how telecom incumbents spin up vertically integrated builds to guarantee GPU access. CoreWeave’s tie-up with Cohere illustrates collaboration between AI model developers and infrastructure financiers. Builders respond by pre-leasing adjacent parcels to enable 100-MW add-on phases. Edge and enterprise footprints grow incrementally, favoring 5–15 MW standardized shells that can be deployed in 9–12 months, a cadence well-suited to metropolitan retail bandwidth demand.
Contractors therefore diversify product lines, offering both hyperscale mega-campus frameworks and prefabricated edge pods. The Canada data center construction market consequently exhibits a bimodal project-size distribution, with few mid-tier builds outside adaptively reused industrial stock.
By Electrical Infrastructure: Power Backup Solutions Lead
Power-backup assets represented 55.75% of electrical-infrastructure spend in 2025 as AI workloads heighten risk tolerance thresholds. The Canada data center construction market share for power-distribution systems is climbing on a 13.02% CAGR, driven by bus-duct retrofits that handle growing rack amperage. Wonder Valley’s 1.4 GW hybrid station demonstrates scale requirements when public grids lag. Natural Resources Canada’s revised energy-efficiency rules spur adoption of high-efficiency UPS blocks that cut PUE but raise capital cost.
Demand for intelligent switchgear that dynamically routes power between utility feeds, gas turbines, and battery farms is surging. Electrical contractors with in-house SCADA teams gain competitive edge as real-time energy management becomes a procurement criterion in the Canada data center construction market.
By Mechanical Infrastructure: Cooling Systems Evolution
Cooling systems captured 43.10% spend in 2025, yet servers and storage assemblies grow fastest at 12.29% CAGR as GPU-rich nodes proliferate. British Columbia’s ban on once-through potable-water cooling after 2028 is pushing designs toward closed-loop adiabatic and immersion systems. CSA B52:23 refrigerant code revisions add installation checkpoints for low-GWP blends, lengthening inspection timelines.
Immersion-cool tanks enable 100 kW-plus rack densities, but they require dielectric-fluid handling and vapor-recovery gear, enlarging mechanical-room footprints. Contractors invest in fluid-technician certification programs to stay bid-eligible. The Canada data center construction industry therefore intersects with chemical-safety regulation, forcing firms to master multi-disciplinary compliance.
Geography Analysis
Alberta leads near-term capacity additions due to CAD 100 billion( USD 72.83 billion) policy backing and competitively priced gas. Its 1.2 GW phased grid-connection pathway lowers queue uncertainty, catalyzing eStruxture’s 90 MW CAL-3 build, Beacon AI’s 400 MW blueprint, and Wonder Valley’s off-grid 1.4 GW park. Provincial regulators fast-track brownfield wellsites for substation placement, compressing locality approval cycles within the Canada data center construction market.
Ontario retains the largest installed base with 93 sites across 291 MW, anchored in Toronto’s financial hub. Adaptive reuse of industrial shells is prevalent; DuPont Fabros converted a printing plant in Vaughan into a 46 MW hall at CAD 41.6 million (USD 30.30 million), evidencing the viability of repurposing to overcome scarce greenfield plots. Construction costs run CAD 280–350 sq ft (USD 203.93- 254.91), challenging project economics, but offset by fiber richness and talent access.
Quebec and British Columbia appeal to operators seeking renewable baseloads. Hydro-Québec’s CAD 50 billion(USD 36.42 billion) transmission plan enables 5,000 km of new lines through 2035, supporting QScale’s GPU-ready campus backed by Aligned Data Centers and Desjardins Capital. British Columbia hosts Bell Canada’s 500 MW AI supercluster, leveraging cool ambient temperatures for free-air cooling nine months per year
Regulatory Landscape
Canada data center construction permitting and grid access are increasingly shaped by province-level power-allocation rules and utility interconnection requirements, along with building, electrical, and refrigerant codes that come into play during design review and inspection. In Alberta, the Data Centre Regulation (June 9, 2026, under the Electric Utilities Act) created a framework for large facilities (75 MW or more) and explicitly prioritizes projects that bring their own generation, aligning with the province's broader approach to managing large-load interconnection queues. Ontario has moved in parallel on grid governance, with Bill 40 amendments to the Electricity Act, 1998, and the IESO drafting technical requirements on May 14, 2026 for large computational loads to protect system reliability, adding another layer of technical due diligence for transmission-connected builds.
Environmental and resource constraints are also tightening project conditions. British Columbia implemented the Data Centre Facility and Hydrogen Production Facility Power Supply Regulation (B.C. Reg. 8/2026), limiting new electricity capacity for conventional data centres to 100 MW over two years starting January 2026, which elevates the importance of project sequencing and power procurement strategy for new campuses. Across multiple provinces, Indigenous consultation is becoming more central to approval pathways, especially where new transmission, substations, or large greenfield sites are involved, extending pre-construction timelines and raising the value of early stakeholder engagement in site selection and design.
Competitive Landscape
Industry structure is tightening as pension funds and infrastructure investors consolidate construction platforms. Fengate’s CAD 1.8 billion outlay for eStruxture exemplifies capital pooling that accelerates multi-province rollout. EllisDon deepens its technology depth with Palantir and Scale AI partnerships to forecast cost overruns and schedule slippage. H5 and Novacap’s joint venture adds private-equity dry powder, enabling rapid site acquisition aligned with hyperscale pre-leases.
Traditional contractors such as Bird Construction pivot into data-center-adjacent works, winning CAD 575 million(USD 418.78 billion) in industrial foundations that overlap power-station scopes. Specialist players holding Uptime Institute and CSA B52 credentials command premiums, creating a two-tier vendor pool in the Canada data center construction market. Technology adoption—digital twins, drone progress scans, and AI-driven quality checking—emerges as a win factor.
Emerging disruptors target niche pain points. Start-ups focusing on immersion-cool deployment, modular substation kits, and rapid-erect steel frames compress schedules by 30%. Off-grid power integrators bundle gas turbines, heat-recovery generators, and carbon-capture add-ons, appealing to hyperscalers under emissions scrutiny. Competitive intensity therefore stems from capability breadth rather than sheer contractor count in the Canada data center construction industry.
Canada Data Center Construction Industry Leaders
Black & Veatch Holding Company
PCL Construction
Bird Construction
EllisDon
DPR Construction
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Large, power-intensive AI campuses and the associated power infrastructure are expanding the addressable scope for EPC, general contractors, and specialty MEP packages, particularly in Alberta and the Prairies where new-build announcements are landing. In July 2026, Meta broke ground on a C$13 billion data centre in Sturgeon County, Alberta, described as a 1 GW facility with scalability, which draws in major civil works, high-voltage interconnects, and multi-stage cooling and backup systems. The project structure, including a Clark Builders and PCL Construction joint venture on construction and a dedicated power consortium involving Pembina Pipeline, Morgan Stanley Infrastructure Partners, and Kineticor, points to whitespace for contractors that can connect campus delivery with utility-scale generation and grid-interface execution.
A second opportunity pocket is repeatable, multi-site delivery programs tied to sovereign AI and telecom-led compute rollouts, where procurement favors partners that can secure long-lead electrical gear and standardize designs for faster phase builds. Bell Canada's 300 MW AI data centre in Sherwood, Saskatchewan (announced as a $1.7 billion project) and its long-term construction partnership with Bird Construction reflect a shift toward framework-style contracting and national build pipelines, supporting consistent specifications for high-density halls, liquid cooling, and on-site power solutions. At the same time, province-level power allocation caps and reliability requirements (for example, Alberta's large-load framework and British Columbia's two-year capacity limit) create room for behind-the-meter generation, modular substations, and hybrid energy designs that reduce interconnection risk and compress schedules for committed sites.
Recent Industry Developments
- July 2026: PCL Construction was chosen as lead industrial general contractor for the 2.9 million square foot Sturgeon Data Centre in Sturgeon County, Alberta, designed for Meta and with capacity scalable to 1.8 gigawatts. The project advances large-scale hyperscale deployment and strengthens schedule discipline for Canada data-centre expansion.
- July 2026: Bird Construction formalized a long-term strategic partnership with Bell Canada to act as its preferred construction partner for a multi-year, Canada-wide AI data center buildout, beginning with the 300 MW AI Fabric facility in Saskatchewan. The partnership improves capacity, supply chain readiness, and multi-site delivery for national AI infrastructure.
- May 2026: Bird Construction advances the Sherwood, Saskatchewan AI Fabric facility project with Bell Canada, a CAD 1.7 billion commitment with approximately CAD 1.3 billion expected to be incurred in 2026. Near-term capital intensity and progress toward 2027 online phases for AI compute capacity.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of building and upgrading data center sites in Canada, including core construction work and the major on-site infrastructure installed to make facilities power-ready and temperature-controlled.
Scope exclusions: Land purchases, ongoing colocation operating services, and off-site utility transmission upgrades are excluded from this market sizing.
Segmentation Overview
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
- By Infrastructure
- By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
- By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service - Design and Consulting, Integration, Support and Maintenance
- By Electrical Infrastructure
- Tier 1 and 2
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to map the demand pool and validate the physical build pipeline before any numbers are finalized. We rely on public infrastructure and construction indicators to explain when projects move from announcements into actual construction starts and when equipment orders are placed.
Typical sources include official statistics and technical references such as Statistics Canada (non-residential construction and price indexes), Natural Resources Canada (energy and emissions context), the Canada Energy Regulator (power system updates), provincial utility and regulator filings, and building code and standards publications that influence design choices. We also review company filings and investor decks, reputable press coverage of new campuses, and procurement signals, then cross-check with paid databases for company financials and intelligence, patent look-ups, and shipment-level import and export data tied to critical equipment categories. This desk research list is illustrative and not exhaustive, and additional public and paid sources are used to collect data, validate assumptions, and resolve open questions.
Primary Interviews and Surveys
Primary work is used to verify what is truly being built and paid for, especially when project timelines slip or when designs shift toward higher density and different cooling needs. Interviews and surveys were completed with contractors, engineering teams, equipment providers, and data center operators, with coverage spread across the main build provinces and the national supply chain so that pricing, lead times, and typical bill-of-material splits could be checked and refined.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 36% | CXOs: 13% |
| Mid tier: 50% | Functional/Unit leaders: 27% |
| Smaller Players: 14% | Managers: 60% |
Market-Sizing & Forecasting
Market sizing is built using a top-down and bottom-up combination so the totals stay realistic even when project disclosures are limited. From the top down, construction value is reconstructed by linking Canada's active and planned data center capacity additions to typical cost-per-MW and cost-per-square-foot ranges, which are then adjusted for local labor and materials inflation.
To keep the model grounded, results are corroborated with selective bottom-up checks, such as sampled project budgets from public announcements, contractor workload signals, and equipment categories that move in step with new halls (for example, generators, switchgear, UPS, and cooling plant). Inputs that mattered most include announced IT load additions, tier-related redundancy requirements, power availability and connection timelines, construction cost indices, and typical mechanical and electrical share of total build value. When bottom-up checks show gaps, they are filled using province-level cost multipliers and conservative use of publicly visible project counts, before totals are rebalanced.
For forecasting, scenario analysis is used so the outlook reflects different build pacing outcomes, and then the final path is anchored to expert consensus on permitting speed, grid connection lead times, and procurement cycles for long-lead electrical gear. A short sensitivity pass is also run on cost-per-MW and schedule slippage so the forecast does not swing on one-off price moves.
Data Validation & Update Cycle
Validation is completed in steps so outliers are caught early and corrected with evidence. Model outputs are checked against independent signals such as new capacity announcements, construction starts reported in credible news, and changes in construction cost indices, and then any large variance is reviewed again by another analyst before sign-off.
If a material discrepancy is observed, the related assumptions are reopened and primary contacts are re-engaged to confirm what changed, such as lead times, pricing, or a project moving from planned to paused. Reports are refreshed annually, with interim updates for material events, and a final pre-delivery review is performed so clients receive the latest market view.
黑料不打烊's Canada States Data Center Construction Market Estimate Compared With Other Published Estimates
Published market sizes for Canada data center construction can look far apart, even when each estimate is trying to describe the same build cycle. The differences usually come from what cost items are counted, how project timing is treated, and whether pricing is updated for recent construction inflation.
IT hardware purchases sit outside 黑料不打烊's scope, so figures that bundle servers and storage into facility build totals can land higher even if the underlying pipeline is similar. Another driver is how cost-per-MW is progressed, since some estimates keep one national average that does not reflect province-level labor rates, power availability constraints, or the shift toward higher density designs that can lift mechanical costs.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 3.34 B (2025) | |
| Trade Journal A | USD 5.44 B (2024) | Often presented as total data center investment, which can bundle IT equipment and broader fit-out categories, and it may use facility lists that do not separate construction value from overall program spend. |
| Industry Portal B | USD 17.31 B (2024) | Can reflect a wider data center revenue or investment definition, with limited transparency on what is counted as construction versus operations, and country-level scaling that may not align with on-the-ground build timelines. |
The spread in the table mainly comes from what is included in the spending basket and how consistently timing and pricing are refreshed. By keeping the model tied to build activity and construction-relevant inputs, the final number stays easier to trace back to repeatable steps and clear cost drivers.


Key Questions Answered in the Report
What is the current value of the Canada data center construction market?
The market stands at USD 3.71 billion in 2026 and is projected to reach USD 6.27 billion by 2031.
Which province is adding capacity fastest?
Alberta leads near-term expansion with a 1.2 GW phased grid-connection program and CAD 100 billion policy incentives.
Why are Tier 4 facilities gaining traction?
Mission-critical AI workloads require fault-tolerant power and cooling redundancies, driving a 12.95% CAGR in Tier 4 builds.
How are power constraints influencing construction timelines?
Limited grid headroom forces developers to integrate on-site generation, extending schedules by up to 18 months in some provinces.
Page last updated on:
- Data Center Construction Market
- United Kingdom Data Center Construction Market
- Malaysia Data Center Construction Market
- Vietnam Data Center Construction Market
- China Data Center Construction Market
- Middle East Data Center Construction Market
- Italy Data Center Construction Market
- Saudi Arabia Data Center Construction Market
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Data Center Power Market Power systems across all regions, split by component, tier and facility size.
- Canada Data Center Power Market Power systems in Canada, split by component, tier and facility size.
- Canada Hyperscale Data Center Market Hyperscale sites demand across Canada, covering facility type, component and tier.
- Middle East Data Center Rack Market Racks in the Middle East, split by rack size, rack type and tier.


