
Middle East Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Historical Data Period | 2020 - 2024 |
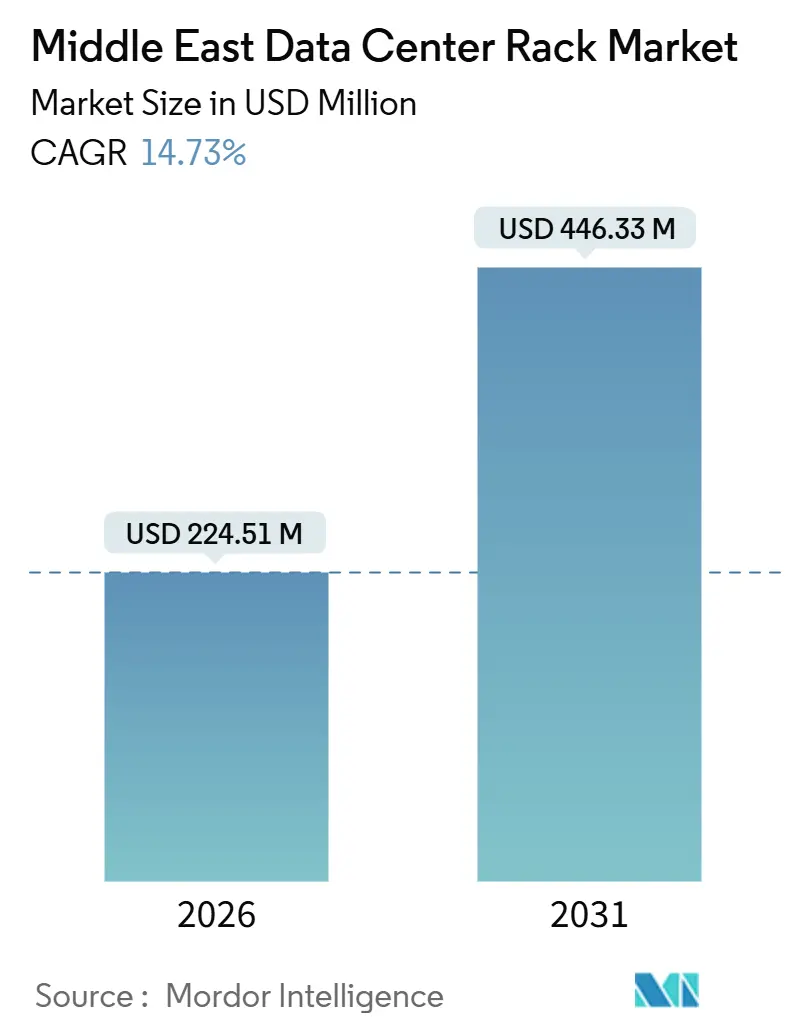
| Market Size (2026) | USD 224.51 Million |
| Market Size (2031) | USD 446.33 Million |
| Growth Rate (2026 - 2031) | 14.73 % |
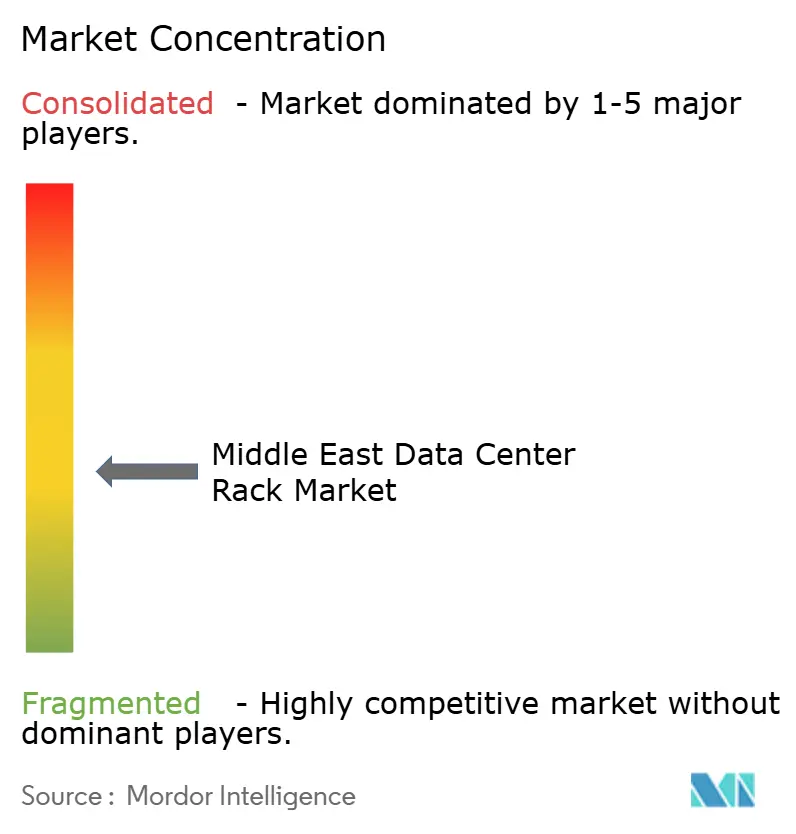
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Middle East Data Center Rack Market Analysis by 黑料不打烊
The Middle East Data Center Rack Market size is estimated at USD 224.51 million in 2026, and is expected to reach USD 446.33 million by 2031, at a CAGR of 14.73% during the forecast period (2026-2031). Demand is accelerating because hyperscale clouds are localizing capacity, sovereign-AI mandates require on-shore computing, and operators are standardizing on high-density, enclosed cabinets that support liquid or rear-door cooling. Full-length 42U racks remain dominant, yet edge rollouts tied to 5G and micro-modules are lifting shipments of half-height enclosures. Saudi Arabia and the United Arab Emirates account for the bulk of new deployments, but Oman and Jordan are emerging with specialized edge and colocation projects. Supply chains are in flux as local-content rules reward knock-down kits and regional fabrication, while heat-intensive GPU clusters are pushing designers toward liquid cooling.
Key Report Takeaways
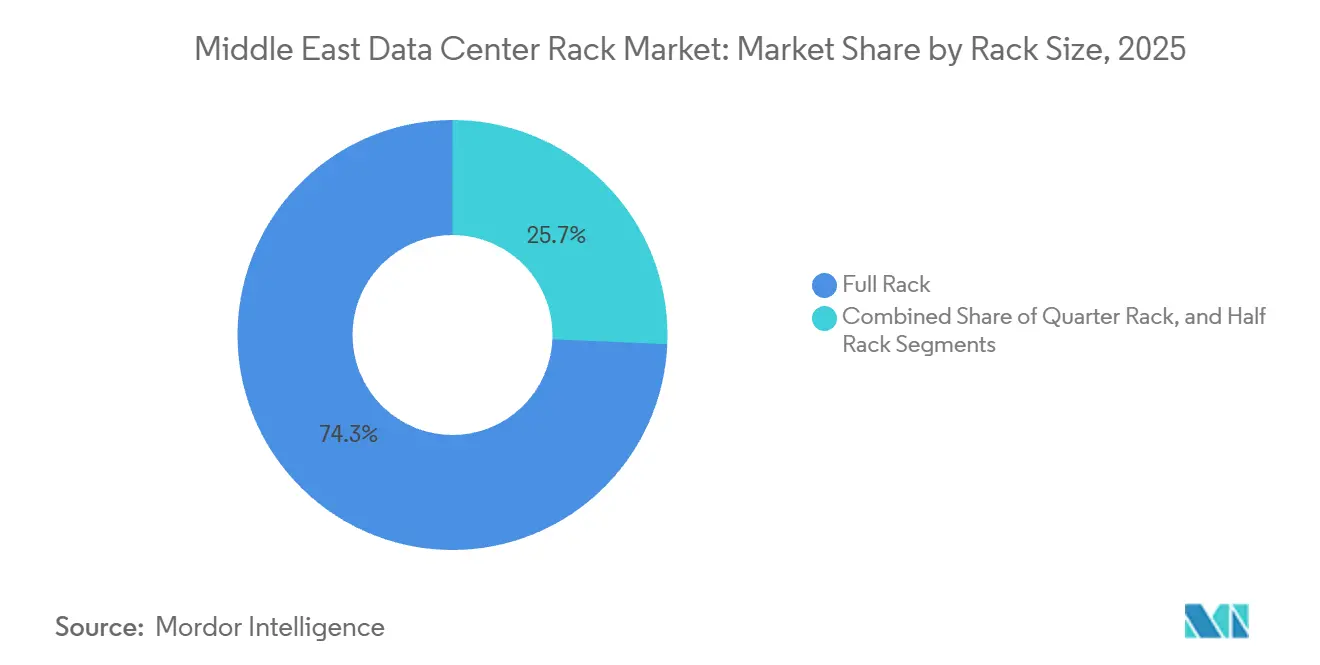
- By rack size, full racks held 74.32% of Middle East data center rack market share in 2025, while half racks are projected to expand at 15.53% CAGR through 2031.
- By rack type, enclosed cabinets captured 79.33% revenue share in 2025, and this format is forecast to grow at 15.67% CAGR to 2031.
- By tier classification, Tier 3 led with 56.21% share in 2025, whereas Tier 4 racks show the highest projected CAGR at 16.12% over 2026-2031.
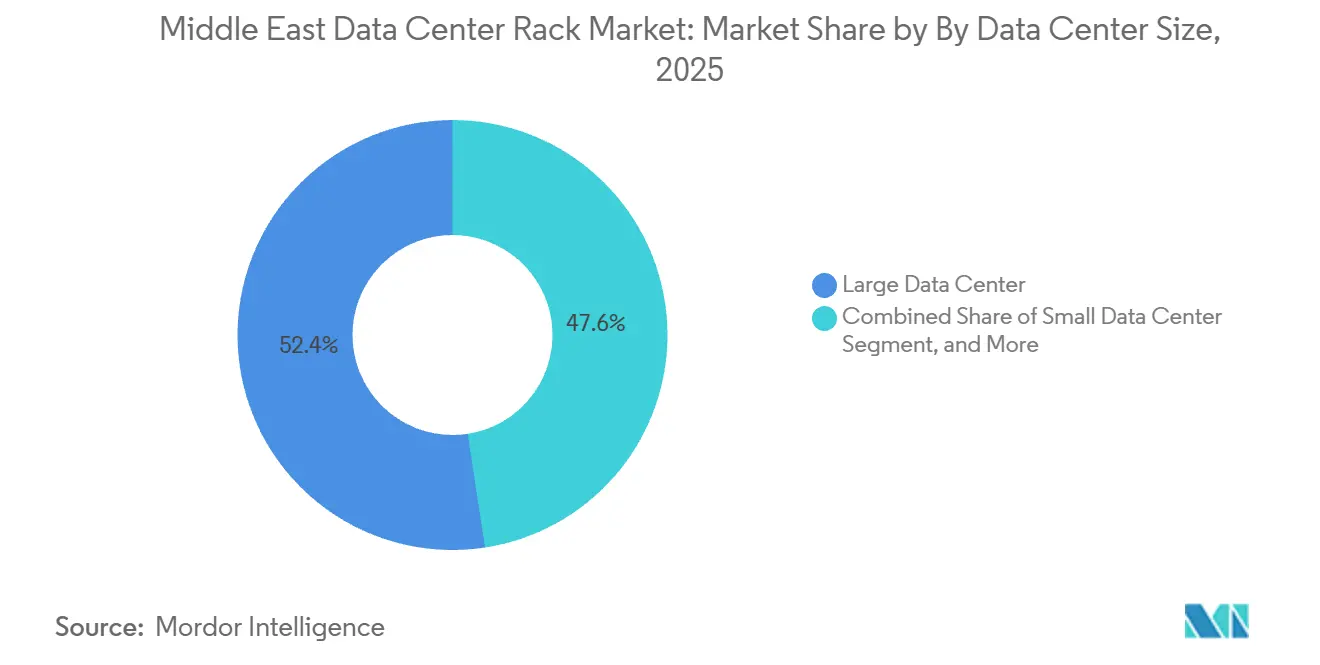
- By data center size, large facilities represented 52.42% of shipments in 2025, yet hyperscale sites are expected to rise at 15.71% CAGR during the outlook.
- By data center ownership, colocation providers commanded 51.53% share in 2025, while hyperscalers and cloud service operators are set to advance at 15.82% CAGR over the forecast window.
- By country, Saudi Arabia led with 39.35% revenue share in 2025, while the United Arab Emirates is forecast to expand at 16.08% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Middle East Data Center Rack Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale Build-Outs by Cloud Majors in Saudi Arabia and UAE | +3.8% | Saudi Arabia, UAE, spillover to Oman | Medium term (2-4 years) |
| Accelerated Local-Content Requirements Driving On-Shore Colocation Demand | +2.9% | Saudi Arabia, UAE, Jordan | Short term (≤ 2 years) |
| 5G-Led Edge Sites Requiring Micro-Module Racks | +2.4% | UAE, Saudi Arabia, Oman | Medium term (2-4 years) |
| Sovereign-AI and HPC Investments in Gulf States | +3.2% | Saudi Arabia, UAE | Long term (≥ 4 years) |
| Renewable-Energy PPA Incentives Lowering Opex for Rack Densification | +1.6% | UAE, Saudi Arabia | Long term (≥ 4 years) |
| Micro-Climate Resistant Enclosures for Desert Environments | +1.4% | GCC-wide with focus on Saudi Arabia and UAE | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Hyperscale Build-Outs by Cloud Majors in Saudi Arabia and UAE
Cloud platforms are rolling out multi-region footprints inside the Gulf to satisfy data-sovereignty rules, and every new availability zone translates into thousands of high-density, enclosed cabinets engineered for 20 kilowatt or higher loads. Racks must integrate cable-routing, rear-door heat exchangers, and sensor-driven airflow because AI training clusters intensify thermal output. Modular pod layouts that scale from 5 megawatts to 50 megawatts are shortening construction schedules, giving rack vendors that deliver pre-assembled kits an edge.
Accelerated Local-Content Requirements Driving On-Shore Colocation Demand
Saudi Arabia’s IKTVA and the UAE’s ICV frameworks impose 30%-40% domestic-value thresholds on technology projects, so global vendors now ship knock-down racks for final assembly in-country or partner with regional steel fabricators.[1]Saudi Arabian Government, “In-Kingdom Total Value Add (IKTVA) Program,” my.gov.sa Certification under these schemes commands price premiums yet ensures priority in bid evaluations. As local compliance expands to Jordan, the supply chain is moving from import-centric to hybrid models that split fabrication, powder coating, and final integration across multiple Gulf plants.
5G-Led Edge Sites Requiring Micro-Module Racks
Standalone 5G cores and network slicing push compute toward radio sites, retail branches, and industrial yards, and each node needs a half rack or wall-mount enclosure that tolerates temperature swings while dissipating 5-10 kilowatts. Half-height cabinets embed power distribution, closed-loop cooling, and fire suppression inside a single form factor, slashing on-site labor. Telecom operators now standardize on sealed, IP55-rated steel to protect baseband units from dust, and this requirement accelerates demand for compact racks.
Sovereign-AI and HPC Investments in Gulf States
National AI blueprints in Saudi Arabia and the UAE allocate hundreds of megawatts for large language model training, and these GPU clusters need liquid-cooled racks that handle 50 kilowatt loads or higher.[2]Qualcomm, “Qualcomm and Saudi SDAIA Partner on 200MW AI Compute Infrastructure,” qualcomm.com Vendors that integrate manifold distribution units, leak detection, and redundant pumps inside the cabinet capture premium pricing even as overall volumes stay modest. This development splits the Middle East data center rack market into a commodity air-cooled tier and a high-margin liquid-cooled tier aimed at HPC workloads.
Restraints Impact Analysis of Middle East Data Center Rack Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Import Tariffs on Steel Enclosures in Non-FTA Countries | -1.8% | Jordan, Oman | Short term (≤ 2 years) |
| Limited Availability of Tier-IV Colocation Floor Space Outside GCC | -1.2% | Jordan, Rest of Middle East | Medium term (2-4 years) |
| Growing Preference for Blade and Sled Servers Reduces Rack Count | -1.4% | GCC-wide with early adoption in UAE and Saudi Arabia | Medium term (2-4 years) |
| Water-Scarcity Regulations Limiting Liquid-Cooling Retrofits | -1.1% | UAE, Saudi Arabia, Oman | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High Import Tariffs on Steel Enclosures in Non-FTA Countries
Jordan and some secondary Gulf states levy 5%-15% duties on finished steel products, and fully assembled racks often fall into higher tariff bands, raising landed costs. Buyers respond by sourcing local fabrication or importing flat-pack kits for final assembly, which splinters quality assurance and prolongs project timelines. To preserve margins, multinational suppliers are opening bonded warehouses in Dubai free zones, but this adds logistics complexity.
Water-Scarcity Regulations Limiting Liquid-Cooling Retrofits
Freshwater conservation policies in the UAE and Saudi Arabia limit evaporative cooling, discouraging retrofit liquid-cooling loops that rely on chilled water. Closed-loop immersion and direct-to-chip systems avoid water draw yet raise rack costs by 20%-30%, slowing adoption in legacy halls. Consequently, older data centers stay on air-cooled racks, while new hyperscale builds integrate liquid designs from day one, deepening the technology gap between facilities.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Middle East Data Center Rack Market Segment Analysis
By Rack Size:
Edge Proliferation Drives Compact FormatsFull racks command 74.32% of Middle East data center rack market share in 2025, underscoring the historical dominance of 42U footprints for colocation and enterprise halls. Yet half racks expand at a 15.53% CAGR through 2031, propelled by 5G edge rollouts that install compute in small shelters. Nokia’s 2025 Cloud RAN build in Abu Dhabi used 12U and 18U weatherized enclosures, proving how radio access networks shift away from centralized halls toward distributed nodes. Quarter racks see niche uptake for remote offices, but bulk demand will continue to cluster around the two leading sizes.
Operators favor dual portfolios, one for hyperscale halls that absorb thousands of identical 42U cabinets and another for half-height enclosures that ship fully integrated with power, cooling, and security. The approach simplifies procurement while meeting divergent thermals, with GPU clusters leaning on full racks that support 20 kilowatt power and half racks targeting edge applications running at 5 kilowatt or lower. Vendors that span both ends capture the widest wallet share, but must juggle distinct supply chains and pricing models.


By Rack Type:
Enclosed Cabinets Dominate Desert DeploymentsEnclosed cabinets held 79.33% of Middle East data center rack market share in 2025 and are projected to grow 15.67% through 2031. Dust ingress protection drives the preference, as IP54-rated doors shield servers from desert particulates while positive-pressure airflow improves reliability.[3]IEC, “IEC 60529 IP Rating Standards for Enclosures,” iec.ch Open-frame racks linger in test labs or Tier 1 halls, yet their share is eroding because operators pair uptime targets with stricter environmental controls.
Thermal strategies also tilt the field. Rear-door heat exchangers and in-row chillers retrofit smoothly onto sealed cabinets, letting facilities step up power density without replacing chilled-water plants. The Moro Hub solar data center in Dubai completed in 2025 and adopted sealed enclosures with rear-door exchangers to manage daytime heat using passive energy.[4]Moro Hub, “Moro Hub Completes Phase 2 of Solar-Powered Data Center,” morohub.com As AI drives 30-50 kilowatt loads, the enclosed format cements its edge, sustaining premium ASPs despite hyperscaler price pressure.
By Tier Type:
Tier 4 Gains as Sovereign-AI Demands Five-Nines UptimeTier 3 halls accounted for 56.21% of racks in 2025, a legacy from enterprise colocation contracts that permit planned downtime for maintenance. Yet Tier 4 deployments expand at 16.12% CAGR because sovereign-AI projects and financial workloads require uninterrupted runtime. Saudi Arabia’s 200 megawatt AI compute estate, announced in 2026, mandates 2N+1 redundancy in power and cooling, pushing rack orders toward cabinets with dual PDUs and intelligent monitoring.
Higher tiering raises capital cost per rack by about 25%, but downtime costs for GPU clusters exceed USD 100,000 per hour, making Tier 4 cost-effective. Vendors that embed environmental sensors and predictive analytics into their frames help operators hit service-level objectives, creating a feature race that differentiates premium suppliers from commodity-only brands.
By Data Center Size:
Hyperscale Facilities Outpace Legacy SegmentsLarge data centers formed 52.42% of shipments in 2025, yet hyperscale campuses will grow at 15.71% CAGR through 2031 as cloud majors deploy multi-region capacity. A single hyperscale hall can house 20,000 racks, dwarfing the 500-rack footprint typical of a large colocation site. Microsoft’s three Saudi availability zones adopted standardized 42U cabinets with 20 kilowatt thresholds, revealing the scale effect that hyperscale deals have on volume.
Standardization compresses margins because price negotiations hinge on massive unit counts, but vendors gain predictability and longer forecast horizons. Conversely, medium sites from 100-500 racks and small sites under 100 racks retain higher margins through customization. Suppliers must balance portfolio mix, channel policy, and production scheduling to optimize profitability during the hyperscale build wave.
By Data Center Type:
Hyperscalers Gain Share from Colocation ProvidersColocation operators held 51.53% share in 2025, but hyperscalers and cloud service providers will pick up speed with a 15.82% CAGR, reflecting a pivot toward owned-and-operated estates. AWS and Oracle both chose captive facilities for their 2025-2026 expansions, bypassing third-party halls and negotiating directly with manufacturers. Direct procurement rewards vendors that can offer just-in-time logistics and global spares programs, but payment terms lengthen to 90 days.
Colocation providers retain a role because enterprises prefer opex renting over capex builds. They order smaller batches and require flexible rack widths, deeper cable trays, and variable PDU configurations to support mixed tenants. The divergent needs keep both segments relevant, yet growth momentum clearly favors hyperscaler footprints.
Geography Analysis
Saudi Arabia Data Center Rack Market
Saudi Arabia held 39.35% of Middle East data center rack market share in 2025. Vision 2030 digital policy, on-shore data mandates, and a USD 5.3 billion hyperscale commitment by AWS collectively drive demand. The Saudi Data and Artificial Intelligence Authority joined Qualcomm in 2026 for a 200 megawatt AI estate requiring liquid-cooled, 50 kilowatt racks. Local-content clauses under IKTVA incentivize assembly plants inside the Kingdom, welcoming regional manufacturers that partner with domestic steel mills.
United Arab Emirates Data Center Rack Market
The United Arab Emirates is forecast to grow at 16.08% CAGR from 2026 to 2031, the fastest in the region. Dubai’s role as a submarine-cable crossroads and Abu Dhabi’s sovereign-AI investments spur rack orders. Khazna’s planned 5 gigawatt AI campus and the Stargate UAE project target 1 gigawatt of GPU capacity, both specifying enclosed, liquid-ready cabinets. The UAE’s ICV scorecard pushes suppliers to localize, and the DEWA D33 efficiency mandate makes high-density racks critical to reduce cooling energy per megawatt.
Middle East Data Center Rack Market
Oman, Jordan, and other Middle East states represent emerging opportunities. Oman focuses on 5G edge shelters and rust-resistant enclosures for coastal humidity. Jordan courts colocation deals by offering lower power tariffs, but higher import duties on finished steel reduce competitiveness. Iraq, Lebanon, and Yemen remain hampered by infrastructure gaps, limiting rack deployments to opportunistic contracts with international agencies or telcos. Vendors must tailor go-to-market models, pairing direct sales in core Gulf markets with channel distribution and project-based bids in frontier states.
Regulatory Landscape
Saudi Arabia is tightening formal oversight for data center operations and data residency, which is shaping rack specifications around monitoring, redundancy, and physical security. The Communications, Space and Technology Commission (CST) Data Centers Services Regulations (DCSR), effective since January 2024, define service tiers and raise compliance expectations for operators, while SDAIA administers the Saudi Personal Data Protection Law (PDPL) with limits on cross-border transfers that reinforce in-Kingdom hosting. Power availability and connection standards are also a gating item, with the Ministry of Energy and the Saudi Electricity and Regulatory Authority (SERA) influencing grid connection and reliability requirements, which in turn feed higher-density rack and power-distribution designs.
In the UAE, operators work through a layered rule set that includes federal requirements and free-zone regimes such as DIFC and ADGM, affecting where workloads are placed and how colocation contracts are structured. On procurement, local-content frameworks, including Saudi IKTVA and the UAE ICV scorecard, are steering sourcing decisions toward in-country assembly and regional fabrication, pushing manufacturers to align bills of materials and supplier footprints with qualification requirements rather than relying only on imported, fully assembled cabinets.
Value Chain Analysis
The Middle East data center rack value chain begins with sourcing steel, fasteners, coatings, doors, cable-management components, and accessory subassemblies, then progresses through fabrication (sheet-metal forming and welding), finishing (powder coating and corrosion protection), and final assembly and kitting. Local-content policies in Saudi Arabia and the UAE are accelerating a shift away from importing fully assembled racks toward hybrid models that use knock-down kits and in-country assembly. Dubai free zones also function as logistics hubs for inventory positioning and quicker fulfillment for Gulf projects.
Downstream, racks are increasingly bundled into integrated physical infrastructure stacks that pair cabinets with power distribution, cooling interfaces (rear-door systems and liquid-ready manifolds), and monitoring software. Delivery typically runs through EPCs, hyperscalers, and colocation operators, with coordination often extending across infrastructure vendors such as Schneider Electric and Vertiv, developers and integrators, and grid-aligned delivery partners. Industry groups including the Gulf Data Centre Association (GDCA) support coordination across the GCC through sector alignment and knowledge sharing.
Competitive Landscape
The Middle East data center rack market is moderately concentrated, with global vendors like Schneider Electric, Vertiv, and Rittal maintaining strong positions through partnerships with colocation providers and hyperscale operators. Local-content mandates in Saudi Arabia and the UAE are creating opportunities for regional manufacturers offering faster, customized solutions. Competitive strategies focus on liquid-cooling, intelligent rack systems, localization, and vertical integration. Chinese manufacturers are entering the Gulf with cost advantages but face quality concerns and longer customization lead times.
Technology adoption is driving change, with pre-integrated rack solutions reducing installation time and winning hyperscale contracts. Schneider Electric’s EcoStruxure platform uses IoT and analytics to differentiate. Opportunities lie in liquid-cooled AI racks, micro-modules for 5G, and modular systems that meet IEC 60529 standards. The market is splitting into low-margin air-cooled racks and premium liquid-cooled enclosures, pressuring mid-tier suppliers to localize or integrate.
Private equity-backed manufacturers are partnering with global brands to ensure cost efficiency, while Gulf sovereign funds invest to meet localization quotas. Vertiv’s 2025 joint venture in King Abdullah Economic City highlights a shift to local assembly. Abu Dhabi’s AIQ is integrating anomaly detection into rack controllers, and Dubai partnerships are cutting replenishment cycles to ten days. Startups like Submer and Iceotope are licensing designs to vendors, accelerating market entry. Consolidation is expected as global firms acquire smaller assemblers to scale and meet warranty demands.
Middle East Data Center Rack Industry Leaders
Schneider Electric SE
Vertiv Group Corp.
Rittal GmbH & Co. KG
Eaton Corporation plc
Legrand SA
- *Disclaimer: Major Players sorted in no particular order
Middle East Data Center Rack Market Companies Covered in this Report
- Schneider Electric SE
- Vertiv Group Corp.
- Rittal GmbH & Co. KG
- Eaton Corporation plc
- Legrand SA
- nVent Electric plc
- Panduit Corp.
- Huawei Technologies Co., Ltd.
- Black Box Corporation
- Chatsworth Products, Inc.
- Middle East Fiber Cable Manufacturing Co.
- Great Lakes Data Racks & Cabinets Inc.
- Delta Electronics, Inc.
- ABB Ltd.
- Belden Inc.
- Canovate Group

Market Opportunities and Future Outlook
A key whitespace is in-country, compliant supply of high-density enclosed cabinets and liquid-ready rack ecosystems that align with Gulf localization thresholds while supporting AI-driven power densities. Evidence includes Schneider Electric stating a commitment to nearly triple its Saudi manufacturing capacity by 2030, which signals a broader local supply base for data center infrastructure components and creates more room for rack vendors and sub-suppliers to qualify under IKTVA and ICV-aligned sourcing. The UAE is also adding AI-ready capacity anchors, including the April 2026 Dubai Integrated Economic Zones Authority (DIEZ) and the VOLT UAE initiative for an AI-ready data center in Dubai Silicon Oasis, which supports demand for standardized, enclosed cabinets and faster-to-deploy modular rack lineups.
Another opportunity is framework-based, multi-site delivery for converged AI-ready infrastructure, which tends to favor vendors that can provide standardized racks alongside integration services, spares, and commissioning across multiple GCC countries. Vertiv's June 2026 framework agreement with Edge-Serve, IRCL, and Saudi Electricity Project Development Company (PDC) shows how buyers are packaging power, cooling, and physical infrastructure requirements into repeatable rollouts, creating openings for rack platforms designed for rapid kitting, local assembly, and higher-tier resiliency. Beyond core hyperscale metros, edge and specialized builds in Oman and Jordan still support demand for compact, ruggedized enclosures and channel-led delivery models, particularly where import duties on finished steel and project-by-project procurement increase the value of local finishing and final assembly.
Recent Industry Developments in Middle East Data Center Rack Market
- June 2026: Vertiv: Announced framework agreement with Edge-Serve, IRCL, and Saudi Electricity Project Development Company (PDC) to deploy converged AI-ready data center infrastructure in the GCC. The arrangement enables rapid AI-ready data center deployments and strengthens regional partnerships and supply chains.
- May 2026: Schneider Electric: Committed to tripling Saudi manufacturing capacity to 32 production lines by 2030 to support data center and digital infrastructure local supply chains. The expansion enhances local manufacturing resilience and supply security for ME data-center rack market.
- April 2026: Schneider Electric (with Volt UAE and DIEZ): Collaborated on a 29 MW initial, 100 MW total power project at Dubai Silicon Oasis, delivering power, distribution, and smart data center infrastructure. The project accelerates UAE edge and hyperscale rack deployments; strengthens regional footprint and reference sites.


Middle East Data Center Rack Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market means revenues generated from supplying data center racks used to mount IT and network equipment across colocation, hyperscale, and enterprise facilities in the Middle East, covering new builds and replacement demand where rack units are procured.
Scope exclusions: Excludes servers, storage, networking gear, power and cooling equipment, and general data center construction services.
Segments Covered in This Report
- By Rack Size
- Quarter Rack (Below 11U)
- Half Rack (12 to 22U)
- Full Rack (Above 42U)
- By Rack Type
- Enclosed Cabinet
- Open-Frame
- Wall-Mount and Micro-Edge Enclosure
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Data Center Size
- Small Data Center
- Medium Data Center
- Large Data Center
- Hyperscale Data Center
- By Data Center Type
- Colocation Data Center
- Hyperscalers Data Center/CSPs
- Enterprise and Edge Data Center
- By Country
- Saudi Arabia
- United Arab Emirates
- Oman
- Jordan
- Rest of Middle East
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market frame and build a country-level demand map before any field assumptions were tested. We referenced public infrastructure and ICT indicators, along with policy and investment signals, to identify where rack deployments are actually happening and how quickly capacity is being added.
Typical sources included official statistics and releases such as national telecom regulators and ICT ministries, central bank and national statistics offices, customs and trade statistics portals, and energy authorities for power availability and pricing context. We also reviewed company filings and investor presentations from facility operators and integrators, plus reputable press coverage of new data center announcements. Where helpful for consistency checks, paid subscriptions were used for company financials and intelligence, patent databases, and shipment-level import and export screening for relevant rack and enclosure categories. This list is illustrative only, and other public sources were used as well to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary interviews and surveys were used to pressure-test desk assumptions on rack demand timing, pricing bands, and specification mix, since those shift as new build pipelines advance. Interviews covered a mix of rack suppliers, system integrators, data center operators, and large buyers, and we ensured the view set was balanced across the Gulf and the wider Middle East so country-level differences were not averaged out too early.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 15% |
| Mid tier: 55% | Functional/Unit leaders: 28% |
| Smaller Players: 18% | Managers: 57% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs the rack demand pool from data center capacity additions and expansion plans by country, then translates those volumes into rack counts and value using practical deployment ratios. To keep totals realistic, we added selective bottom-up checks, including sampled pricing by rack class, channel checks on delivery lead times, and supplier and integrator revenue splits where those were observable.
Key inputs that shaped the model included announced and active data center projects, the mix between colocation and self-built facilities, typical rack unit heights used in new deployments (for example 42U patterns versus compact options), average rack power density direction (linked to AI and high-performance compute buildouts), and price differences driven by enclosed versus open frame designs and cable management needs. When data was incomplete for smaller countries or for edge rollouts, gaps were handled using comparable-country adoption ratios, then the direction was validated with interview feedback.
For forecasting, scenario analysis was used so project timing changes and procurement delays could be reflected cleanly, and then the preferred case was carried forward once it aligned with expert expectations. Assumptions were kept simple and traceable so the model can be rerun when new builds are announced or when pricing shifts with steel and logistics costs.
Data Validation & Update Cycle
Validation is done through multiple checks so outliers do not slip into the final numbers. We compare outputs against independent signals such as data center build announcements, import patterns for relevant equipment classes, and the pace of expansion activity in key hub countries, before totals are finalized.
If a country result looks too high or too low versus its pipeline, the assumptions are reviewed, and follow-up calls are triggered to confirm what changed, for example delayed commissioning or a shift to higher density. Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery review is completed so clients receive the latest view available at the time of purchase.
黑料不打烊's Middle East Data Center Rack Market Size Compared With Other Published Estimates
Published market values for Middle East data center racks can vary even when they sound like they describe the same thing, because the scope and the conversion from capacity plans into rack value are not handled in the same way. Differences usually come from what gets counted as a rack sale, which countries are included, and how older installed bases versus new build-outs are treated in the starting year.
Some estimates bundle adjacent infrastructure like cabinets with integrated power distribution, containment, or services, which inflates the rack value, while others undercount by relying on broad data center spending shares that do not reflect local procurement patterns. The spread in the table is mainly explained by whether replacement cycles are assumed to be short and uniform across the region, how rack ASPs are adjusted for material cost swings, and whether the model is refreshed when large Saudi Arabia and UAE project timelines shift, a step that is handled explicitly in the demand-pool build used by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 224.51 M (2026) | |
| Regional Consultancy A | USD 221.57 M (2024) | Uses an earlier base year and folds in ancillary cabinet hardware and installation add-ons, and then applies a faster upgrade-cycle assumption that does not match observed retrofit timing in several countries. |
| Trade Journal B | USD 93.41 M (2025) | Applies a narrower rack definition closer to basic frames, and relies on conservative adoption ratios from a limited set of mature sites, which can miss newer high-density deployments linked to hyperscale and sovereign projects. |
Across these three figures, timing and scope choices can shift the result as much as underlying demand does. By keeping rack revenue tied to clear procurement triggers, and by stress-testing ASP and replacement assumptions against project and buyer feedback, the final estimate stays easier to replicate and update when the regional build pipeline changes.


Key Questions Answered in the Report
How large is the Middle East data center rack market in 2026 and what growth is expected?
The market is valued at USD 224.51 million in 2026 and is projected to reach USD 446.33 million by 2031, registering a 14.73% CAGR.
Which rack size is growing fastest in the region?
Half-height racks from 12U to 22U show the fastest expansion at 15.53% CAGR, driven by 5G edge deployments.
Why are enclosed cabinets preferred over open-frame racks in Gulf data centers?
Desert dust, temperature extremes, and the need for rear-door or liquid cooling make sealed, IP-rated cabinets more reliable and more efficient.
What role do local-content programs play in rack procurement?
Saudi IKTVA and UAE ICV requirements favor suppliers that assemble or source components domestically, impacting vendor selection and pricing.
How is liquid cooling affecting rack design in the Gulf?
AI and HPC clusters demand 50 kilowatt heat removal per rack, prompting designs that integrate manifolds, pumps, and sensors for immersion or direct-to-chip cooling.
Which countries contribute most to regional rack demand?
Saudi Arabia leads with 39.35% share, while the United Arab Emirates is the fastest growing at 16.08% CAGR through 2031.
Page last updated on:
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Middle East Data Center Construction Market Construction in the Middle East, split by infrastructure, tier and facility type.
- Middle East Data Center Physical Security Market Physical security demand across the Middle East, covering solution type and service type.
- Middle East And Africa Artificial Intelligence (AI) Data Center Market The Middle East and Africa AI facilities, split by facility type, component and tier.



