
Saudi Arabia Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
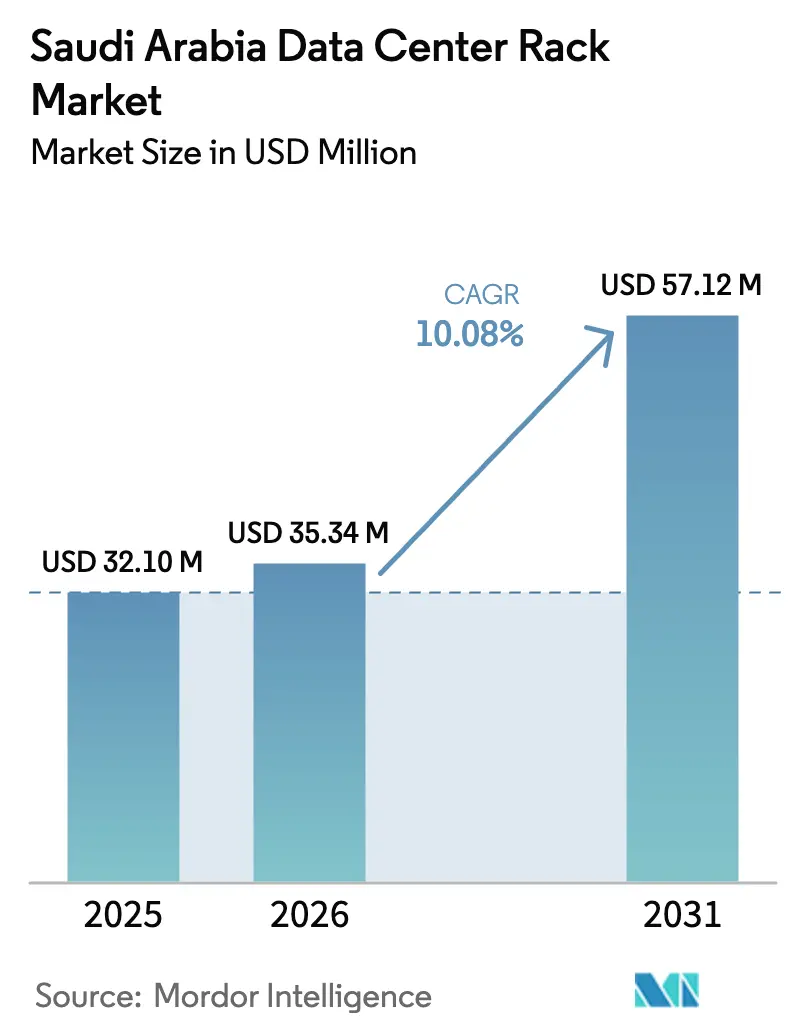
| Base Year Market Size (2025) | USD 32.1 Million |
| Market Size (2026) | USD 35.34 Million |
| Market Size (2031) | USD 57.12 Million |
| Growth Rate (2026 - 2031) | 10.08 % |
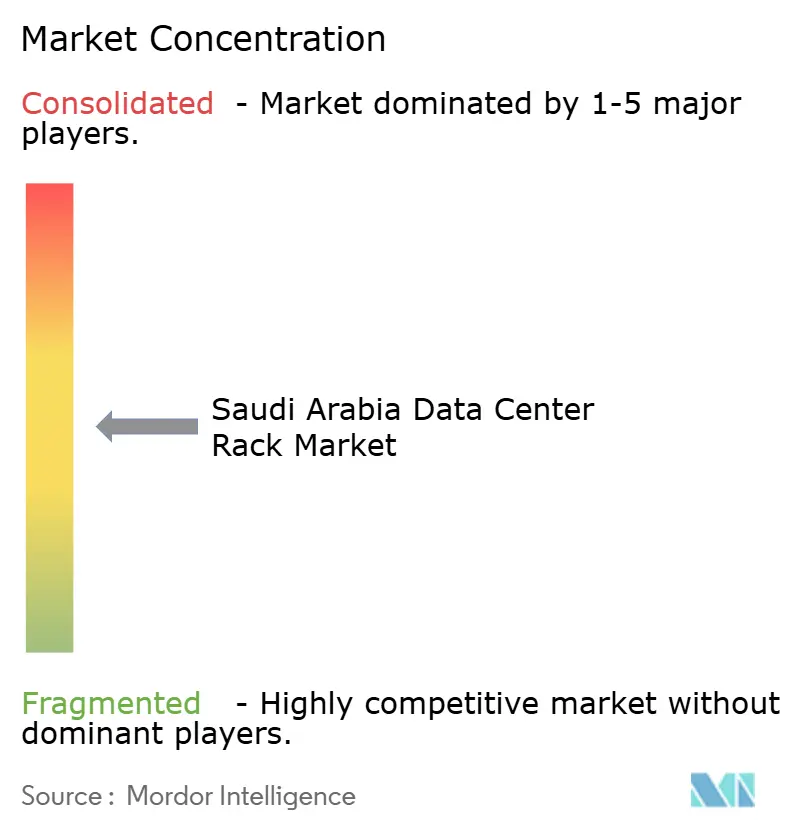
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Saudi Arabia Data Center Rack Market Analysis by 黑料不打烊
The Saudi Arabia data center rack market size is expected to grow from USD 32.1 million in 2025 to USD 35.34 million in 2026 and is forecast to reach USD 57.12 million by 2031 at 10.08% CAGR over 2026-2031. Near-term momentum reflects a surge of hyperscale projects backed by Vision 2030, a USD 18 billion national data-center program, and aggressive 5G rollouts that push IT equipment closer to end users. Expanding cloud adoption by public agencies is accelerating demand for secure, high-load racks, while AI workloads are raising average rack power densities and driving liquid-cooling readiness. At the same time, operators seek lighter and corrosion-resistant materials to deal with coastal humidity and to simplify edge deployments in remote zones. Continuous localization of content, coupled with a widening skills base, reinforces the overall growth trajectory of the Saudi Arabia data center rack market.
Key Report Takeaways
- By rack size, full racks held 61.62% of the Saudi Arabia data center rack market share in 2025, while quarter racks are projected to grow at 14.03% CAGR to 2031.
- By rack height, 42U racks led with 51.90% revenue share in 2025; the 48U segment is expanding at 12.95% through 2031.
- By rack type, cabinet enclosures commanded 71.35% share of the Saudi Arabia data center rack market size in 2025; wall-mount racks post the fastest 14.62% CAGR to 2031.
- By data-center type, colocation sites held 55.78% of the Saudi Arabia data center rack market size in 2025, whereas hyperscalers record a 15.02% CAGR through 2031.
- By material, steel accounted for 71.22% of the Saudi Arabia data center rack market share in 2025, while aluminum solutions register an 11.07% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Saudi Arabia Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing penetration of FTTH and 5G backhaul | 3.5% | National, with concentration in Riyadh, Jeddah, and Dammam | Medium term (2-4 years) |
| Hyperscale DC build-outs by STC / AWS / Google | 2.7% | Major urban centers (Riyadh, Jeddah, Dammam) | Short term (≤ 2 years) |
| Vision 2030 digital-government push | 1.8% | National | Long term (≥ 4 years) |
| Colocation demand surge from OTT and BFSI (data-localization) | 1.3% | Riyadh and Jeddah | Medium term (2-4 years) |
| AI-dedicated GPU campuses needing high-density racks | 0.9% | Riyadh and NEOM | Medium term (2-4 years) |
| Solar + battery PPAs enabling low-OPEX remote DCs | 0.8% | Secondary cities and remote locations | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Increasing penetration of FTTH and 5G backhaul
Rapid fiber and 5G deployment has reached 77% of the population, forcing the creation of edge sites that place compute within one hop of mobile users.[1]U.S. Department of Commerce, “Saudi Arabia – Digital Economy,” trade.gov These micro-facilities need compact quarter and wall-mount racks that fit telecom closets and rooftop shelters. Operators now specify integrated battery backups and dust-proof door seals to cope with power fluctuations and desert particulates. Suppliers are therefore releasing shallow-depth enclosures with rear-cable swing frames and filtered side panels. Over the next three years, rack demand is projected to rise sharply in secondary towns where 5G small-cell clusters outnumber traditional central offices.
Hyperscale DC build-outs by STC, AWS, Google
Center3, Pure Data Centres, and DataVolt anchor more than 300 MW of new hyperscale capacity scheduled before 2027. Build contracts specify 48U racks supporting >3,000 lb static loads, hot-aisle containment, and liquid-cooling manifolds. Modular rail kits and tool-less airflow blanking panels shorten installation windows that hyperscalers cap at 14 weeks. Vendors answer with factory-integrated rack-and-power pods that ship fully wired. Standardization around identical footprints gives suppliers predictable volume, lowering per-unit cost and reinforcing the Saudi Arabia data center rack market.
Vision 2030 digital-government push
The Cloud-First Policy seeks 50% public-sector cloud adoption by 2025, doubling current consumption. [2]World Bank, “The Cloud Imperative: Strategy and Practices from the Kingdom of Saudi Arabia,” worldbank.org Ministries now demand biometric doors, tamper seals, and electromagnetic shielding on every rack. Central procurement guidelines require that new enclosures pass seismic and thermal-shock tests, raising the average bill of materials. Manufacturers have introduced government-grade lines with bonded-steel frames and audit-ready smart locks. Long-term demand looks resilient because refresh cycles align with multiyear e-services rollouts that underpin Vision 2030 milestones.
Colocation demand surge from OTT and BFSI
Data-localization rules obligate OTT video platforms and banks to host traffic within the Kingdom . Colocation operators reply with micro-segmented cages equipped with electronic rack locks, per-door sensors, and dual PDUs. AI-native tenants seek 30 kW cabinets featuring rear-door heat exchangers, incentivizing facility owners to upgrade entire rows. Rising tenancy levels improve utilization, allowing landlords to negotiate multi-year rack frame contracts that stabilize supply and reduce lead-time volatility.
Restraints Impact Analysis*
| Restraint | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High CapEx and energy-intensive OPEX for Tier III/IV builds | -1.5% | National | Medium term (2-4 years) |
| Global supply-chain lead times for high-density racks | -1.2% | National, with greater impact in secondary cities | Short term (≤ 2 years) |
| Limited redundant grid capacity in key metros | -0.9% | Riyadh, Jeddah, Dammam | Medium term (2-4 years) |
| Shortage of certified liquid-cooling integration talent | -0.7% | National | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
High CapEx and energy-intensive OPEX for Tier III/IV builds
Data Centers Services Regulations introduced in 2024 elevate redundancy and testing thresholds, driving per-rack costs 30% above baseline. Cooling in peak summer conditions pushes PUE penalties that leave operators cautious on new halls. To soften the burden, facility designers adopt perforated doors delivering up to 70% open area and chimney-based containment that channels exhaust directly to ceiling plenums. Suppliers also promote in-row evaporative coolers that lower compressor runtime. Still, sticker shock postpones non-essential expansions and trims the CAGR contribution of smaller enterprises.
Global supply-chain lead times for high-density racks
Liquid-cooling-ready frames rely on valves, gaskets, and manifolds sourced from a narrow supplier base. Port congestion in Asia and extended factory backlogs stretch delivery to 18–22 weeks, slowing GPU cluster projects. Supermicro’s USD 20 billion partnership with DataVolt vividly illustrates demand that currently outpaces capacity.[3]Super Micro Computer Inc., “Supermicro Announces Strategic Partnership with DataVolt,” ir.supermicro.com Regional fabricators respond by tooling local plants for 48U skeletons and front-door heat exchangers, aiming to cut lead time by half. Some operators hedge risk through frame-agnostic layouts enabling phased integration of cooling skids once parts arrive.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Quarter Racks Gain Momentum
Full racks dominate the Saudi Arabia data center rack market with 61.62% share in 2025. They remain the default choice for hyperscalers because standardized footprints simplify hot-aisle containment and bulk cabling. The segment benefits from AI clusters that regularly exceed 30 kW, levels that full-height frames handle without structural compromise. Demand also stems from colocation corridors in Riyadh, where common hall designs are pre-engineered around 600 mm x 1,200 mm footprints. Rollout of GPU cloud zones by STC continues to reinforce volume ordering of full racks, sustaining price competitiveness and high availability in distributor stock.
Quarter racks, however, exhibit the speediest rise at a 14.03% CAGR. Edge computing units in 5G base-station huts, shopping malls, and university campuses favor these compact enclosures. Micro data–center vendors package a pair of quarter racks with fire suppression and battery strings inside shipping-container shells, allowing turnkey deployment within six weeks. Logistics convenience—two technicians can hand-carry an empty quarter rack upstairs—further widens addressable markets. Converter kits that merge two quarter racks into a half rack add flexibility for capacity upgrades, enhancing life-cycle value and minimizing stranded capital.


By Rack Height: Vertical Optimization Drives Adoption
Traditional 42U frames hold 51.90% of revenue yet face share dilution as operators pursue denser floors. The 42U standard carries a reputation for easy reachability and abundant accessory options, a heritage that keeps it entrenched in colocation meet-me rooms and enterprise server halls. Techniques such as top-of-rack switching and side-cable troughs help maintain airflow clarity even at 15 kW. Meanwhile, server OEMs certify new AI chassis within 42U envelopes, ensuring backward compatibility.
The 48U cohort is projected to expand 12.95% through 2031, supported by hyperscalers that prioritize compute density over walk-in clearance. Taller cabinets often pair with motorized lifts to streamline maintenance. EAE Elektrik delivers KabinPLUS 48U frames rated at 1,500 kg, offering high static strength that accommodates eight-GPU blades per 1U slot. Operators that replace every sixth 42U row with 48U gain roughly 15% extra rack count without extending the white space envelope, an important advantage where land prices continue to climb around Riyadh Tech Valley.
By Rack Type: Wall-Mount Solutions Address Edge Requirements
Cabinet enclosures account for 71.35% of the Saudi Arabia data center rack market size. Their closed design supports ducted exhaust and front-door filtration, essential for minimizing particulate ingress in desert climates. Most models integrate side panels with quick-release locks, allowing rapid extraction for cable upgrades. Security features such as swing-handle keypads and centralized monitoring via Modbus complement compliance requirements under the Personal Data Protection Law.
Wall-mount racks grow quickest at 14.62% CAGR as rail-side deployments for 5G edge nodes multiply. Tripp Lite’s 12U hinged model illustrates this demand by offering 200-lb capacity and reversible doors in only 18 inches depth tripplite.eaton.com. Telecommunications operators value fold-out brackets that enable single-person maintenance on street-level cabinets. Hybrid “swing-mount” concepts further extend usability, letting customers deploy small UPS units behind access switches while preserving frontal airflow pathways.
By Data Center Type: Hyperscalers Drive Innovation
Colocation facilities held 55.78% share of the Saudi Arabia data center rack market size in 2025. They attract enterprises pursuing data-sovereignty compliance without heavy CapEx. These providers outfit cages with modular busbars that snap into rack roofs and support mixed power feeds, making them appealing to BFSI tenants with complex redundancy needs. Continuous power-density upgrades keep colocation halls competitive when courting AI research projects.
Hyperscale operators deliver the fastest 15.02% CAGR. DataVolt has signed multi-gigawatt PPA commitments to secure renewable electricity, enabling GPU campuses that each consume up to 120 MW. Within such facilities, every rack is ordered factory-fitted with front-to-back airflow baffles, dual busbars, and immersion-ready bays. Fixed-spec procurement unlocks manufacturing scale, compressing per-unit costs and elevating the Saudi Arabia data center rack market.

By Material: Aluminum Gains Traction in Specialized Applications
Steel frames remain entrenched at 71.22% market share because they carry heavy point loads economically. Vendors supply welded or bolted variants; both satisfy 3,000 lb static targets required for dense blade arrays. Yet weight constraints in rooftop micro-sites drive interest in aluminum frames that are 35% lighter yet still meet 1,100 lb benchmarks. Aluminum naturally resists saline corrosion, a benefit for Jeddah’s coastal data centers where sea air accelerates galvanic wear.
Composite and hybrid materials surface in special-purpose enclosures for EMI-sensitive workloads. Legrand’s latest lineup applies powder-coated steel uprights with die-cast aluminum doors to optimize stiffness and thermal exchange legrand.us. Engineers can attach copper mesh grounding straps directly onto internal aluminum members, ensuring a continuous earth path across mixed materials. Adoption remains niche but grows as military and aerospace tenants request high-shielding cabinets to house satellite-uplink control systems.
Geography Analysis
Riyadh commands the largest cluster of commercial and governmental data centers, with six active sites from five providers baxtel.com. Capital city facilities favor high-density racks engineered for AI inference nodes and rely on chilled-water rear-door heat exchangers to manage 40 kW loads. The Saudi Arabia data center rack market size in Riyadh is expected to nearly double by 2030 as DataVolt and Alfanar inject more than USD 1.4 billion into new halls.
Jeddah follows as the second-largest hub, benefitting from submarine-cable landings that attract international content platforms. Zoom’s freshly launched facility in the city underscores rising demand for corrosion-resistant aluminum cabinets that withstand humid coastal air. Operators here install desiccant dehumidifiers directly within row-level containment to keep internal RH below 50%. Dammam and the Eastern Province are emerging zones where oil-and-gas digital twins generate compute loads requiring ruggedized racks sealed against airborne hydrocarbons. Nokia and stc Group’s 1 Tbps optical link trial in the region paves the way for hybrid cloud analytics that demand low-latency edge sites. Further north, NEOM’s ZeroPoint DC pioneers renewable-powered infrastructure in a desert setting, relying on double-walled cabinets with reflective paint and roof solar shade to reduce inlet-air temperatures. Rack suppliers must therefore tailor corrosion protection, thermal coatings, and seismic anchoring based on each region’s micro-climate and regulatory stipulations.
Regulatory Landscape
Saudi Arabia regulates data center services primarily through the Communications, Space and Technology Commission (CST), which publishes the Data Center Services Regulations and maintains a provider framework that links registration to development stage and capability (including tier level and security management practices such as ISO 27001). Compliance also ties into broader national requirements for data governance, cloud services, AI, and cybersecurity, including controls issued by the National Cybersecurity Authority for critical systems. This framework supports physical-security and auditability needs, particularly for racks designed around Tier III/IV facility expectations.
On the infrastructure side, power availability and reliability standards overseen by the Saudi Electricity Regulatory Authority and the Ministry of Energy shape data hall specifications. That, in turn, drives rack requirements for higher density power distribution, as well as integration with containment and cooling. The National Data Center Strategy unveiled in June 2025 by MCIT and SDAIA adds a further policy anchor for scaling domestic data center capacity, supporting the case for more standardized rack specifications across hyperscale, colocation, and public-sector deployments.
Value Chain Analysis
The value chain begins with raw materials and fabricated components, including steel and aluminum frames, doors, rails, fasteners, gaskets, and increasingly liquid-cooling-ready manifolds and sealing elements. Global rack and critical-infrastructure OEMs such as Schneider Electric, Vertiv, and Rittal supply engineered racks alongside integrated physical infrastructure elements, while regional channels handle stocking, configuration, and onsite modifications that can reduce lead times for edge and retrofit deployments.
Downstream, EPC and construction firms deliver shell-and-core and fit-out work for hyperscale and colocation projects, coordinating mechanical and electrical integration such as containment, busways, and chilled-water interfaces. IT and networking layers pull through rack demand via OEM and platform procurement, spanning servers from Dell, HPE, and Supermicro and accelerators from NVIDIA and AMD, alongside networking ecosystems led by Cisco. Final delivery typically bundles racks with PDUs, cable management, access control, and monitoring, then moves into installation, commissioning, and lifecycle services such as moves/adds/changes, spares, and compliance audits, where local capability and certified integration talent increasingly influence differentiation.
Competitive Landscape
The Saudi Arabia data center rack market features a blend of international giants—Schneider Electric, Vertiv, Rittal—and agile regional specialists such as Norden Communication. Global brands supply pre-engineered SKUs validated under international standards, securing large block orders from hyperscalers who prefer multi-country harmonization. Local vendors use geographic proximity to offer swift onsite modification, a trait prized by edge-site owners that need custom wall-mount brackets within days.
Strategic alliances broaden solution scope. Schneider Electric pairs its Easy Rack line with chilled-water distribution panels from local HVAC partners to deliver turnkey rows for high-density AI labs. Norden Communication promotes dual-rack systems whose vertical cable troughs align with third-party busbar trunks, simplifying power reticulation across multitenant cages.
Technology differentiation deepens as racks become sensor platforms. Top vendors embed environmental probes, firmware-based access logs, and API hooks for predictive maintenance analytics. Combined with server telemetry, these racks let operators fine-tune airflow and adapt fan curves, yielding energy savings of 6–8% in test deployments. Competitive intensity is expected to rise once local fabrication capacity scales up, narrowing cost gaps between imported and domestic frames and increasing buyer leverage in large procurement cycles.
Saudi Arabia Data Center Rack Industry Leaders
Schneider Electric SE
Vertiv Group Corp.
Rittal GmbH and Co. KG
Dell Technologies Inc.
Eaton Corporation plc
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A clear white space is emerging around standardized, AI-ready rack ecosystems that reduce deployment time across hyperscale programs and large colocation expansions. Saudi Arabia has active capacity build initiatives tied to MCIT and SDAIA, including an official target of 1.5 GW of data center capacity by 2030, and new large-scale facilities that provide near-term demand signals for high static-load cabinets, integrated power distribution, and liquid-cooling readiness. The launch of the 480 MW Hexagon Data Center in Riyadh (Tier IV, LEED Gold) and STC Group's Riyadh 5 data center at SPARK (40 MW initial capacity, expandable to 80 MW) both expand the installed base that needs repeatable rack footprints, secure enclosures, and row-level containment compatibility.
Another opportunity involves localization and shorter lead times for high-density racks and accessories as GPU and liquid-cooling projects strain global supply for specialized valves, manifolds, and sealing components. Continued hyperscale activity and procurement discipline from major developers, including Center3's plan targeting 300 MW by 2027 and the 250 MW AirTrunk-Humain hyperscale project moving through bidding in April-May 2026, creates room for local assembly, kitting, and compliance-ready configurations aligned with CST operational requirements. For rack vendors, the most actionable differentiation remains repeatable 48U high-load cabinets, corrosion-mitigating options for coastal sites, and factory-integrated features such as blanking, cable segregation, smart locking, and power-ready frames that reduce onsite labor and commissioning complexity.
Recent Industry Developments
- March 2026: The partnership builds standardized power distribution solutions and power racks for AI driven data centers in Saudi Arabia. It strengthens data-center infrastructure capabilities and supports large-scale AI deployments with common rack and power standards.
- March 2026: The partnership builds standardized power distribution solutions and power racks for AI driven data centers in Saudi Arabia. It strengthens data-center infrastructure capabilities and supports large-scale AI deployments with common rack and power standards.
- February 2026: Schneider Electric participated in Datacenter Nation Riyadh 2026 to discuss power and cooling innovations for high-density AI workloads. The engagement supports localization and scalability of AI inspired data-center infrastructure in Saudi Arabia.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers revenue generated from data center racks supplied and installed within Saudi Arabia, including cabinets and frames used to mount IT and network equipment in commercial and enterprise facilities.
Scope exclusions: Excludes servers, storage, network switches, power and cooling equipment, and ongoing facility services that are not sold as part of the rack hardware itself.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to set the baseline demand for racks in Saudi Arabia and to keep assumptions consistent across time. We review public capacity signals and policy targets that influence data center buildouts, and then translate those signals into rackable floor area and deployment patterns.
Common reference points include official ICT and digital infrastructure publications (for example, from the national communications regulator), Saudi statistical releases on construction and investment activity, and trade and customs statistics for metal products where relevant. We also use data center and telecom association publications, peer reviewed papers on rack density and thermal design, and publicly available project announcements and press coverage. Company filings and investor presentations are used to cross-check typical product mix, pricing direction, and channel structure, and paid subscriptions are used selectively for company financials, patent checks, and shipment level trade visibility. The sources listed here are illustrative only, and many other public documents and datasets were also consulted for cross checks and clarification.
Primary Interviews and Surveys
Primary work focuses on confirming how racks are specified and purchased in Saudi projects, and which buyer groups are driving volume in the near term. We speak with rack suppliers, local integrators, colocation operators, and enterprise facility teams, then cross check with consultants who track new builds across Riyadh, the Eastern Province, and emerging zones.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 37% | CXOs: 15% |
| Mid tier: 47% | Functional/Unit leaders: 28% |
| Smaller Players: 16% | Managers: 57% |
Market-Sizing & Forecasting
Market sizing is built using a top down demand reconstruction that starts from Saudi data center expansion signals and then translates them into rack requirements. The model uses indicators such as planned and commissioned white space additions, typical rack density ranges by facility type, adoption of enclosed cabinets versus open frames, average rack height mix (for example 42U and 45U preferences), and the share of high density deployments that require stronger load ratings.
Once the demand pool is formed, revenue is derived by applying practical price ranges by rack type and material (steel versus aluminum), with adjustments for import share and local assembly where seen in the channel. To keep totals realistic, we corroborate with selective bottom up checks, such as sampled project bill of materials, distributor channel feedback on unit volumes, and a limited roll up of supplier revenue exposure to Saudi deliveries. Where direct volume visibility is incomplete, gaps are handled using build pipeline timing, typical order lead times, and conservative adoption assumptions that were validated in interviews.
For forecasting, scenario analysis is used with a base case tied to build schedules, cloud region rollouts, and enterprise digitalization programs, and then stress tested for delays in power availability and project permitting. The final time series is smoothed using simple trend logic so short term spikes in procurement do not overstate the long run path.
Data Validation & Update Cycle
Validation is done through repeated triangulation across independent signals, and we do not rely on one data line to carry the full estimate. Model outputs are checked against observed procurement behavior, import movement direction when applicable, and publicly visible commissioning milestones, and then variances are reviewed by another analyst before sign off.
If large shifts appear, we re contact relevant respondents to confirm whether the change is driven by pricing, project timing, or a real mix shift toward higher value cabinets. Reports refresh annually, and interim updates are made when material events occur, such as major project awards or sudden changes in capacity plans. Before delivery, a fresh review pass is completed so clients receive the most current view that can be supported by documented assumptions.
黑料不打烊's Saudi Arabia Data Center Rack Market Size Compared With Other Published Estimates
Published market sizes can vary even when they talk about the same country, because not everyone counts the same products, uses the same timing for projects, or updates pricing in the same way. Differences also come from whether an estimate treats racks as a hardware line item only, or bundles adjacent infrastructure that is procured in the same fit out cycle.
Cooling doors, aisle containment, and integrated power strips are common add ons in deployments, but they sit outside 黑料不打烊's scope for this rack market, which keeps the total tied to cabinet and frame revenue and then cross checked against Saudi capacity additions and typical rack density.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 32.10 M (2025) | |
| Regional Consultancy A | USD 41.80 M (2025) | Often bundles containment, rack PDUs, and deployment services with rack hardware, and uses higher blended pricing that fits turnkey fit outs rather than rack only revenue. |
| Trade Journal B | USD 26.50 M (2026) | Typically relies on a narrow set of import and distributor signals, which can miss locally assembled units and timing shifts from large project batch orders. |
The spread in the table is mainly explained by what gets counted with the rack and how project timing is recognized across years. By keeping inclusions explicit and then validating totals with build pipeline signals plus channel checks, the estimate remains easy to trace and practical to update when Saudi deployment schedules change.


Key Questions Answered in the Report
What is driving double-digit growth in the Saudi Arabia data center rack market?
Vision 2030 investments, hyperscale cloud build-outs, nationwide 5G coverage, and stringent data-localization laws collectively lift rack demand across hyperscale, colocation, and edge segments.
Which rack sizes are gaining popularity for edge deployments?
Quarter racks and wall-mount enclosures are preferred for edge sites because their compact footprint fits telecom closets and remote shelters while still supporting integrated power backup.
Why are aluminum racks becoming more common in Saudi data centers?
Aluminum frames weigh less, resist coastal corrosion, and dissipate heat effectively, attributes valued in humid coastal cities such as Jeddah and in rooftop edge locations.
How are hyperscalers influencing rack specifications?
Operators such as DataVolt and center3 standardize on 48U racks with >3,000 lb load capacity, liquid-cooling compatibility, and integrated cable ducts, pushing vendors to scale identical SKUs.
Page last updated on:
- Africa Data Center Rack Market
- Australia Data Center Rack Market
- Belgium Data Center Rack Market
- Brazil Data Center Rack Market
- Canada Data Center Rack Market
- Chile Data Center Rack Market
- China Data Center Rack Market
- Data Center Rack Market
- Denmark Data Center Rack Market
- Europe Data Center Rack Market
- France Data Center Rack Market
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Data Center Server Market Servers worldwide, split by tier, facility size and facility type.



