
Chile Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
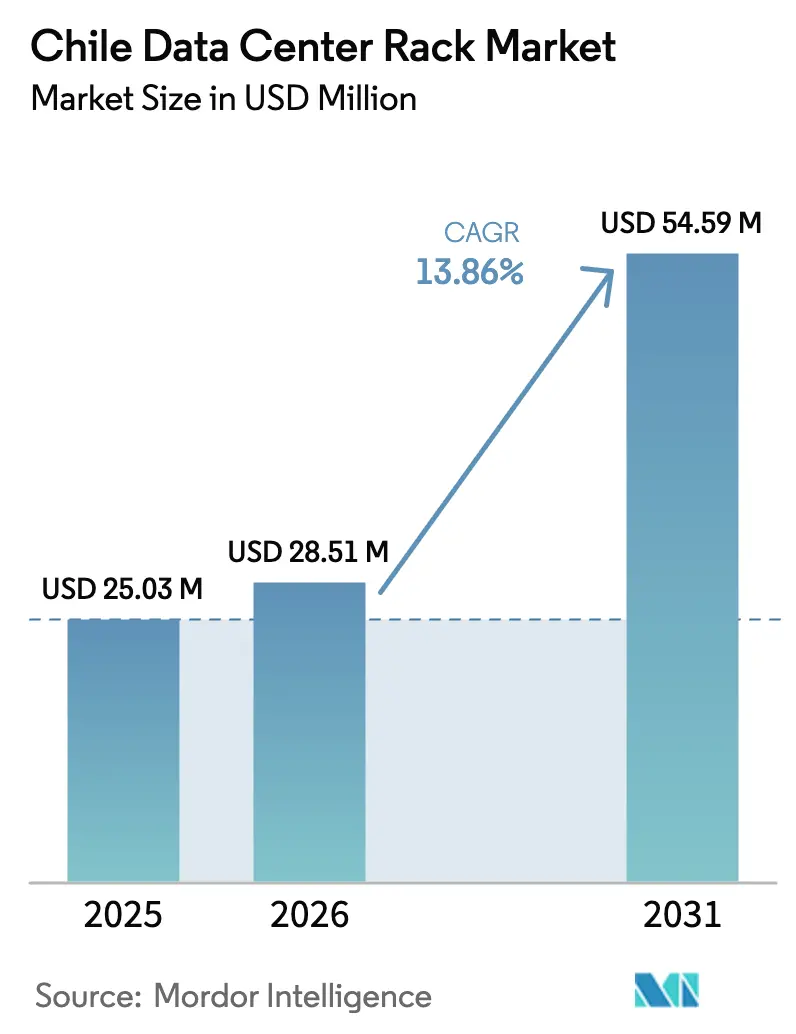
| Base Year Market Size (2025) | USD 25.03 Million |
| Market Size (2026) | USD 28.51 Million |
| Market Size (2031) | USD 54.59 Million |
| Growth Rate (2026 - 2031) | 13.86 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Chile Data Center Rack Market Analysis by 黑料不打烊
The Chile data center rack market size is expected to grow from USD 25.03 million in 2025 to USD 28.51 million in 2026 and is forecast to reach USD 54.59 million by 2031 at 13.86% CAGR over 2026-2031. Sustained hyperscale commitments—most notably Amazon’s USD 4 billion AWS build-out—anchor fresh capacity pipelines and underpin robust cabinet demand in Santiago, Valparaíso, and emerging edge locations .[1]Amazon Web Services, “AWS Announces USD 4 Billion Investment in Chile,” aws.amazon.com Operators continue to standardize around 42U and full-rack footprints to speed fit-outs, reduce procurement complexity, and support 20–40 kW densities demanded by AI and cloud workloads.[2]Schneider Electric, “2024 Full-Year Results,” se.com Government incentives that link tax credits to renewable-power sourcing further strengthen the Chile data center rack market’s value proposition as global firms pursue net-zero targets. Taken together, submarine cable landings, 5G rollouts, and AI-focused research programs reinforce Chile’s status as Latin America’s fastest-scaling digital-infrastructure node, driving supplier competition across steel and aluminum form factors.
Key Report Takeaways
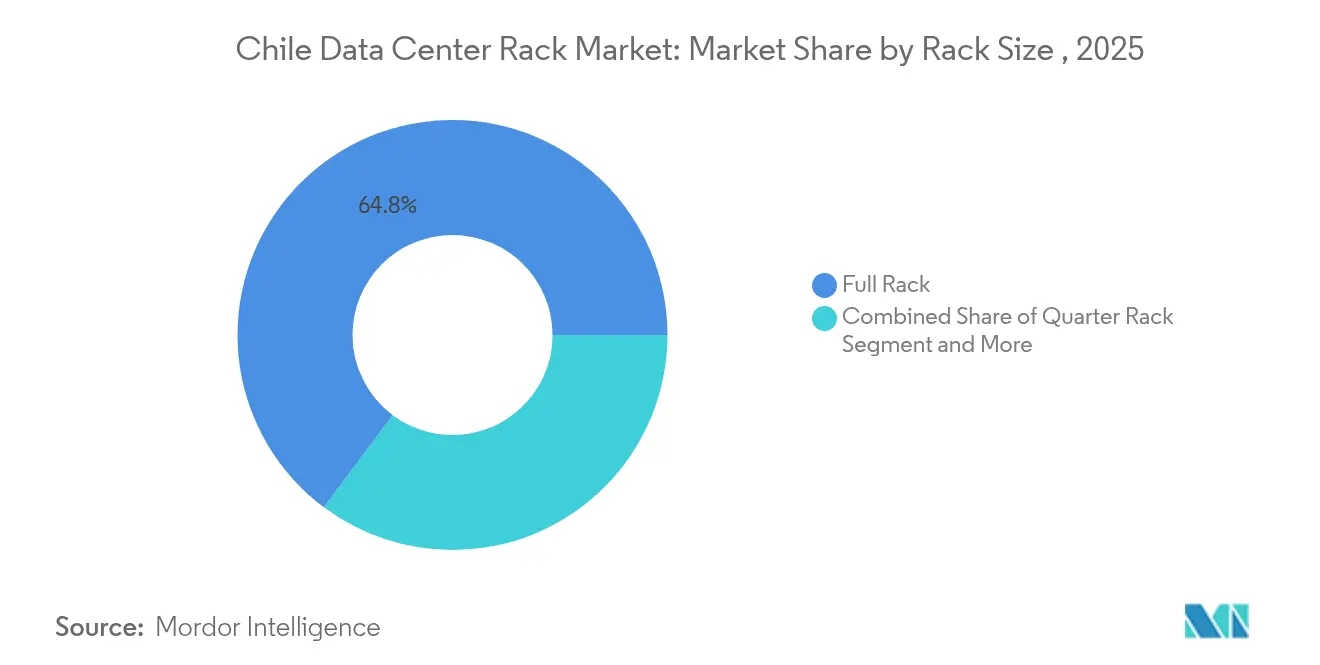
- By rack size, full-rack configurations led with 64.80% of Chile data center rack market share in 2025.
- By rack height, 42U systems held 55.90% share of the Chile data center rack market size in 2025, while 48U is projected to post a 14.84% CAGR through 2031.
- By rack type, cabinet solutions accounted for 71.60% share of the Chile data center rack market size in 2025 and are set to grow at a 15.25% CAGR to 2031.
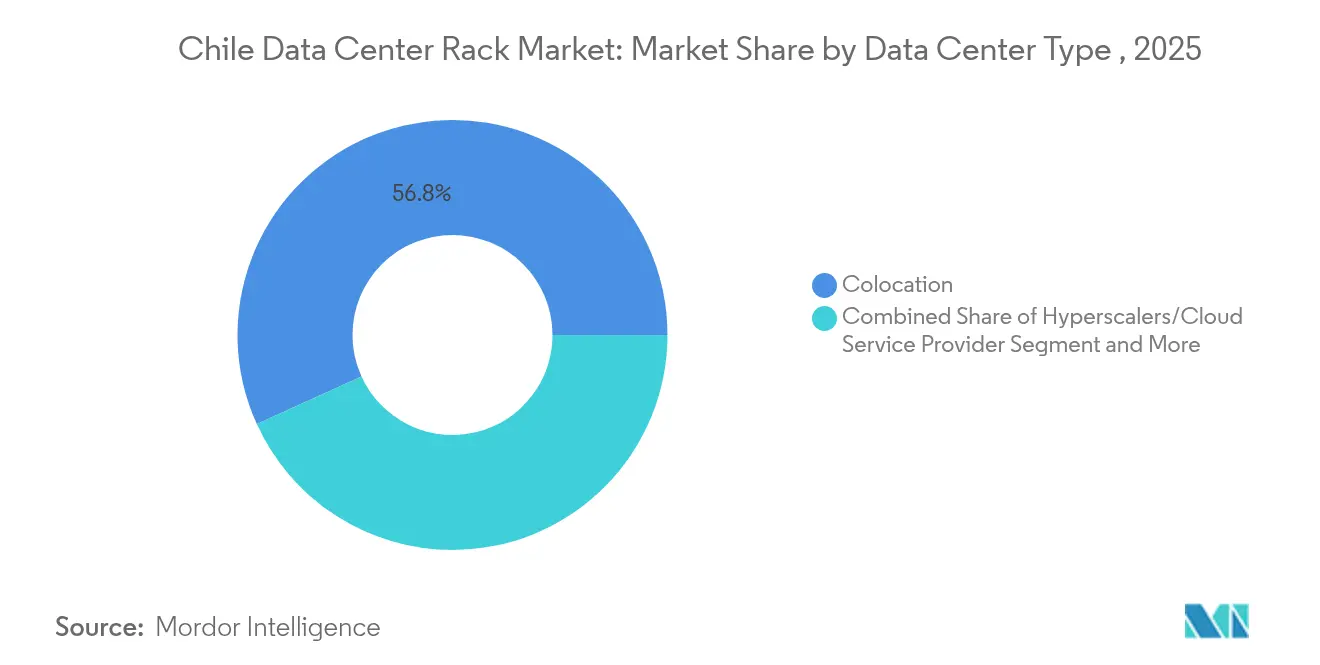
- By data-center type, colocation operators captured 56.80% revenue in 2025; hyperscale and cloud facilities are forecast to expand at 15.75% CAGR through 2031.
- By material, steel dominated with 77.50% share in 2025, while aluminum is the fastest-growing material at a 16.55% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Chile Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising cloud-first digital strategy among Chilean enterprises | +2.8% | National, with early gains in Santiago, Valparaíso, Concepción | Medium term (2-4 years) |
| 5G-led edge-data-center build-outs | +2.1% | National, concentrated in Santiago metro and port cities | Short term (≤ 2 years) |
| Government incentives for renewable-powered data centers | +1.9% | National, with focus on northern solar regions | Long term (≥ 4 years) |
| Hyperscale investments linked to new submarine cables | +3.2% | Coastal regions, particularly Valparaíso and Santiago metro | Medium term (2-4 years) |
| Shift to high-density (20-40 kW) racks | +2.4% | Santiago metro and hyperscale facilities | Short term (≤ 2 years) |
| Emergence of Santiago as a regional AI model-training hub | +1.8% | Santiago metro, with spillover to Valparaíso | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Rising Cloud-First Digital Strategy Among Chilean Enterprises
Chilean companies accelerate cloud adoption to modernize public-service platforms and core business workloads, pushing steady cabinet uptake across the Chile data center rack market. Internet penetration stands at 91% and mobile connections at 147%, giving enterprises the bandwidth foundation for hybrid migrations. The Chile Digital 2035 program mandates 100% digital public services, prompting agencies to replace legacy hardware with standardized 42U racks that ease multi-colocation interoperability. Financial-services and mining firms further favor cabinet enclosures for compliance and dust mitigation. Consequently, demand for full racks capable of 20–40 kW densities rises in line with enterprise AI pilots.
5G-Led Edge-Data-Center Build-Outs
Entel’s national 5G coverage, extended even to Antarctica’s Presidente Eduardo Frei base, accelerates micro-data-center rollouts that prefer quarter-rack and wall-mount solutions.[3]Ericsson, “Entel Brings 5G to All Chilean Regions,” ericsson.com Low-latency use cases—such as remotely piloted salmon-farm equipment and automated port cranes—need resilient racks that fit small footprints and withstand coastal humidity. As operators chase Chile’s 90% 5G-coverage target for 2025, suppliers able to deliver ruggedized form factors register faster order cycles, strengthening regional distribution channels outside Santiago.
Government Incentives for Renewable-Powered Data Centers
Chile aims for 70% renewable electricity by 2030—a policy that fuels global cloud entrants seeking carbon-neutral sites and energizes aluminum rack adoption because of weight and cooling advantages. Microsoft’s pledge to source 100% renewable power for its local campuses by 2025 spotlights high-efficiency rack designs with minimized airflow obstruction. Tax credits and streamlined permits under the National Data Centers Plan reward operators that certify low power-usage effectiveness, prompting upgrades to liquid-ready cabinets compatible with direct-to-chip cooling.
Hyperscale Investments Linked to New Submarine Cables
The Humboldt cable’s Valparaíso landing will add 144 Tbps of transpacific capacity by 2027, inducing hyperscale players to pre-lease megawatt blocks and specify taller 48U racks that house extensive fiber-cross-connect gear. Scala Data Centers already built a 30 MW site in Curauma to exploit this route, filling its halls before project completion. Tall racks consolidate switching, optics, and compute inside a single footprint, optimizing space economics where land prices rise sharply.
Restraints Impact Analysis*
| Restraint | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Severe water-stress regulations on cooling systems | -1.8% | National, particularly acute in Santiago metro | Short term (≤ 2 years) |
| High land-acquisition costs in Santiago metro | -1.2% | Santiago metropolitan region | Medium term (2-4 years) |
| Slow power-grid permitting for >20 MW campuses | -0.9% | National, with delays concentrated in Santiago | Medium term (2-4 years) |
| Peso volatility impacting imported rack prices | -1.1% | National | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Severe Water-Stress Regulations on Cooling Systems
Court challenges over aquifer use halted Google’s USD 200 million Santiago build, underscoring how strict water rules can derail large projects. Developers pivot toward immersion and direct-to-chip cooling that cut evaporative loss by design, requiring racks pre-configured for coolant manifolds. AI training clusters, often exceeding 10.2 kW per rack with NVIDIA DGX H100 systems, intensify this shift. Consequently, open-frame architectures gain traction where airflow is unhindered, while sealed cabinets must integrate rear-door heat exchangers to stay viable in water-scarce districts.
High Land-Acquisition Costs in Santiago Metro
Scarce seismic-qualified plots and premium power feeds push land prices above regional norms, encouraging operators to secure suburban campuses like TECfusions’ 100 MW Puente Alto site. Larger parcels lower unit land cost but add logistical hurdles, from longer delivery routes for steel frames to extended permitting timelines. Smaller rack vendors lacking volume leverage face margin pressure when serving dispersed builds, prompting strategic alliances with local assemblers to offset haulage and currency risks.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full-Rack Dominance Drives Hyperscale Adoption
Full racks captured 64.80% of Chile data center rack market share in 2025 as global operators standardized on uniform footprints across multiregion campuses. The Chile data center rack market size for full racks is forecast to rise at 15.68% CAGR, propelled by Amazon’s USD 4 billion expansion program that replicates AWS’s global cabinet blueprint. Enterprise colocation tenants favor the same format to simplify capacity upgrades and maintain SLA consistency. Quarter and half racks remain relevant for telecom edge nodes and mid-market migrations but see slower uptake as cloud-first strategies mature.
Schneider Electric’s acquisition of Motivair aligns with this trend—liquid-ready full racks allow 20–40 kW loads without costly room-level retrofits. NVIDIA DGX H100 clusters, already deployed in local AI pilots, require the depth and cable-management clearances available only in full-size cabinets. Consequently, supply chains favor bulk orders of identical SKUs, trimming lead times and reducing per-rack cost for Chilean hyperscale sites.


By Rack Height: 42U Standard Meets AI Density Requirements
The 42U profile held 55.90% share of the Chile data center rack market size in 2025 due to its ergonomic serviceability and compatibility with mainstream PDUs. However, taller 48U frames are growing at 14.84% CAGR as submarine-cable operators and AI clusters add network spines and rear-door exchangers that need extra vertical space. 45U and custom heights serve telecom and research use cases where unique airflow or seismic bracing is specified.
Chile’s AI research community, spearheaded by the Franco-Chilean Binational Center launched in 2025, often demands unconventional rack heights to host experimental liquid tanks and sidecar GPUs . Operators balance this flexibility with maintenance safety: keeping heavy switch gear below eye level to meet local labor standards. Ongoing seismic-code updates also influence height choices, nudging facilities toward braced 42U designs for production workloads while relegating taller frames to isolated high-density halls.
By Rack Type: Cabinet Security Drives Enterprise Adoption
Cabinets represented 71.60% revenue in 2025 because enclosed designs safeguard mission-critical workloads from dust and unauthorized access, priorities for Chile’s banking and mining verticals. The Chile data center rack market is expected to see cabinet demand increase at a 15.25% CAGR as data-sovereignty rules mandate in-country retention of sensitive records iticolombia. Open-frame racks gain adoption where airflow is paramount, especially in immersion-cooling rooms that eliminate need for solid side panels.
Financial regulators enforce strict audit trails, prompting operators to integrate electronic locks and environmental sensors within cabinet doors for real-time compliance reporting. Earthquake-risk mitigation also favors cabinets because factory-welded structures outperform bolt-together open frames during lateral shocks. Equipment vendors respond by shipping pre-populated, vibration-tested cabinets, enabling enterprises to deploy rack-level mini-clouds in remote mining sites with minimal onsite assembly.
By Data Center Type: Colocation Leadership Reflects Market Maturity
Colocation providers held 56.80% share in 2025, signifying corporate preference for turnkey data halls operated by seasoned specialists. However, hyperscale campuses, buoyed by Amazon and Microsoft projects, will register a 15.75% CAGR to 2031, gradually shifting the center of gravity of the Chile data center rack market. Enterprise on-premise facilities persist for latency-sensitive SCADA and government workloads but account for declining volume as cloud economics improve.
Vertiv’s 2024 revenue mix illustrates this shift: stronger growth came from colocation orders where racks, PDUs, UPS, and monitoring ship as bundles. Hyperscale operators insist on rack SKUs matched to global data-center design kits, driving bulk orders multiple quarters in advance. Edge installations, linked chiefly to 5G nodes, favor rugged wall-mount enclosures engineered for constrained telecom shelters, expanding vendor portfolios beyond traditional IT cabinets.
By Material: Steel Dominance Faces Aluminum Challenge
Steel framed 77.50% of racks installed during 2025 because it combines affordability with seismic-grade rigidity, critical in a country lying on the Pacific Ring of Fire. Aluminum, though only a modest base, is projected to grow 16.55% annually through 2031 as weight savings enable higher floor loads without reinforcement, especially in retrofit buildings. Hybrid composites find niche adoption in electromagnetic-shielded military and healthcare sites.
Lighter alloys also shorten installation time; two technicians can position an empty aluminum cabinet without forklifts, a key advantage in edge sites lacking loading docks. Cost parity remains a hurdle, yet currency swings favor locally extruded aluminum when imported steel prices spike on peso volatility. Suppliers hedge by offering dual-material portfolios—steel for cost-sensitive enterprise halls and aluminum for AI clusters where power and cooling density offset higher upfront rack spend.
Geography Analysis
Santiago’s metro area concentrates the bulk of Chile data center rack market deployments thanks to mature fiber rings, multiple neutral IXPs, and proximity to financial customers. The capital’s racks increasingly serve AI training workloads initiated by the Binational Center on Artificial Intelligence, pushing power densities beyond historical norms and necessitating liquid-ready 42U and 48U format. Yet severe water-stress regulations and escalating land costs prompt operators to scout peripheral communes and neighboring regions to mitigate permitting delays.
Valparaíso has emerged as a strategic alternative built around submarine-cable landings, most notably the Humboldt route scheduled to activate in 2027 with 144 Tbps capacity dw. Scala Data Centers pre-leased its 30 MW Curauma build on the cable’s doorstep, stacking 48U cabinets to integrate dense fiber cross-connect panels. Coastal climate benefits free-air cooling days, lowering PUE for operators that certify renewable energy mixes to meet tax-credit thresholds.
Secondary cities such as Concepción and Antofagasta serve mining, logistics, and telecom edge applications. Entel’s 5G footprint in every Chilean region opens demand for compact quarter-racks and wall-mount enclosures inside rugged shelters serving automated salmon farms and remote dredging operations. Grid-expansion plans—adding 4,000 km of new transmission by 2031—will widen viable sites, though seismic zoning continues to dictate structural rack material choices. Suppliers with regional inventory hubs gain competitive lead times when serving these dispersed projects, reinforcing domestic assembly value chains.
Regulatory Landscape
Chile is formalizing a dedicated policy framework for data centers through the Ministry of Science (Ministerio de Ciencia, Tecnologia, Conocimiento e Innovacion) under the National Data Centers Plan (PDATA), which focuses on regulatory streamlining, sustainability, and geographic decentralization. On February 25, 2026, the Environmental Evaluation Service (SEA) issued updated criteria for when data center projects enter the Environmental Impact Assessment System (SEIA), increasing the importance of earlier environmental scoping for campus design and, indirectly, for rack-level density and cooling choices in water-stressed areas.
Permitting digitization is also progressing through the System for the Unified Processing of Permits (SUPER), a centralized platform used to manage state-required permits. In parallel, the Humboldt submarine cable advanced through public approvals, including a regional coastal use approval in June 2026 for the Santo Domingo landing, supporting long-haul connectivity buildouts that typically lift demand for standardized cabinet footprints and higher-capacity cross-connect zones.
Value Chain Analysis
The Chile data center rack value chain begins with raw materials (steel and aluminum) and component subassemblies (frames, panels, rails, fasteners, doors, and cable management). This is followed by OEM manufacturing and configuration, including seismic bracing, lock systems, airflow accessories, and liquid-cooling readiness.
Distribution and integration are handled through a mix of vendor-direct channels and regional partners that stage inventory and perform pre-assembly, labeling, and kitting for faster site installation. That model matters as operators standardize on 42U and full-rack deployments and request rack-plus-power or rack-plus-cooling bundles. Downstream demand comes primarily from hyperscalers, cloud providers, and colocation operators active in Chile, including Google, Amazon Web Services, Microsoft, Scala, Equinix, and Ascenty, plus telecom edge deployments linked to 5G expansion. Network and subsea connectivity projects also shape rack requirements through cross-connect density and fiber management needs, with Google listed as the lead investor in the 14,800 km Humboldt submarine cable in partnership with state-owned Desarrollo Pais and SubCom contracted for marine survey and manufacturing. Government-industry collaboration mechanisms such as Clean Production Agreements (CPAs) also influence procurement specifications for materials, packaging, and energy-aware rack accessories.
Competitive Landscape
Global vendors and regional specialists share a moderately concentrated field as hyperscale builds scale sharply. Schneider Electric posted EUR 38 billion 2024 revenue, citing double-digit growth in South American data-center projects, with Chile contributing strongly across mining and cloud builds. The Motivair acquisition equips the firm with in-house liquid-cooling know-how, letting it package racks, CDUs, and containment under a single SKU—an appealing proposition in water-stressed jurisdictions.
Vertiv recorded USD 8.0 billion 2024 sales, rising 17% year-on-year on heavy Americas colocation orders, and now bundles cabinet power-train kits tailored to Chilean seismic code Zone 3 requirements. Eaton’s USD 24.9 billion 2024 topline underscores its diversification into modular plants; local distributors offer fast-ship steel frames to bridge peso-driven price spikes. Regional player Scala, though primarily a landlord, influences rack standards through design-build partnerships with OEMs for its 100+ MW Latin assets.
Strategic themes emphasize integrated rack-plus-cooling stacks, earthquake resilience, and renewable-aligned efficiency. Vendors localize manufacturing where feasible to hedge currency swings and meet rapid delivery windows demanded by hyperscale contracts. Alliances with construction firms familiar with Chilean seismic and environmental codes accelerate campus commissioning. As hyperscale share grows, purchasing power consolidates; yet diverse edge and enterprise niches maintain entry points for smaller fabricators offering bespoke or ruggedized enclosures.
Chile Data Center Rack Industry Leaders
Schneider Electric SE
Vertiv Group Corporation
Eaton Corporation plc
Legrand SA
Delta Electronics, Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
One clear whitespace in Chile is demand for racks and cabinets designed for high-density, low-water cooling architectures. As environmental scrutiny tightens and water-stress constraints affect project planning, operators are pushing toward direct-to-chip and other liquid-ready approaches. The SEA criteria update for SEIA entry in February 2026, alongside PDATA's sustainability emphasis, raises the value of rack platforms that simplify compliance documentation, including sensor-ready cabinets, leak-detection routing, and standardized containment interfaces, while supporting 20-40 kW densities referenced for hyperscale and AI workloads in Santiago and emerging nodes.
Demand is also expanding beyond Santiago, creating additional pull for ruggedized and logistics-friendly rack SKUs. PDATA targets regulatory streamlining and decentralization, while activity in the northern region is being shaped by supplier and stakeholder references to modular infrastructure demand in Antofagasta and Atacama and by Desarrollo Pais work on an AI campus concept in Antofagasta (targeting up to 1 GW). Connectivity-led capacity supports taller, more cable-dense rack configurations near coastal routes as well. Humboldt received regional coastal use approval in June 2026 for a Santo Domingo landing, and Scala has positioned capacity near Valparaiso, supporting ongoing requirements for standardized cabinets, structured cabling integration, and faster-delivery rack programs linked to cable activation and cross-connect buildouts.
Recent Industry Developments
- May 2026: Vertiv announced a strategic distribution alliance with MAXID to improve inventory positioning and delivery logistics for critical data center infrastructure solutions across Chile and other South American markets. The agreement strengthens local availability and lead-time performance for bundled deployments where racks are procured alongside power and thermal equipment, supporting faster hall fit-outs.
- August 2025: Vertiv inaugurated a new regional office in Santiago with capacity for around 60 staff to support customer coverage in Chile as data center projects scale. A larger in-country footprint supports pre-sales engineering, after-sales service, and coordination with integrators, which can reduce deployment friction for standardized cabinet and accessory rollouts.
- October 2024: Schneider Electric completed its acquisition of Motivair, adding liquid-cooling capabilities that complement rack and enclosure portfolios used in high-density data halls. This expands the ability to supply integrated rack-plus-cooling architectures, which is increasingly relevant in Chile where operators are designing for higher rack power densities and tighter resource constraints.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Chile data center rack market is defined as the revenue earned from racks and rack enclosures installed in Chilean data centers, covering cabinet and open-frame designs used to mount IT and network equipment.
Scope exclusions: This sizing excludes active IT hardware inside the rack (servers, storage, switches), standalone power and cooling equipment, and building construction services.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundaries, map demand drivers, and build a clean starting dataset before assumptions were tested in interviews. The study relied on public and official sources such as Chilean customs trade statistics for relevant rack and enclosure imports, the National Institute of Statistics (INE) for macro indicators and business activity, and energy system publications from Chilean authorities (including grid and generation updates) to understand where new data center capacity can realistically come online.
We also referenced materials from telecom and digital infrastructure associations, along with public regulator publications that help interpret connectivity rollout progress and permitting signals. Company filings, investor presentations, and reputable press were reviewed to capture facility announcements and expansion timing, and these inputs were cross-checked using paid subscriptions for company financials and intelligence, an import and export shipment-level database, and a patent database to check product and feature direction. The sources listed here are illustrative only, and additional public references were also consulted to clarify data points and validate assumptions.
Primary Interviews and Surveys
Primary work focused on confirming what is being installed in Chile and how rack demand is changing with densification and new builds. Interviews included rack manufacturers and distributors, system integrators, colocation operators, and large enterprise buyers to verify rack type preferences, typical order sizes, lead times, and pricing behavior.
Coverage was kept Chile-specific. Respondents were selected to reflect the full buying chain from specification to procurement, so desk research gaps could be closed and key assumptions could be checked more than once.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 25% | CXOs: 13% |
| Mid tier: 61% | Functional/Unit leaders: 37% |
| Smaller Players: 14% | Managers: 50% |
Market-Sizing & Forecasting
Sizing was built using a combined top-down and bottom-up approach. On the top-down side, we reconstructed the rack demand pool by linking Chile data center capacity additions and fit-out cycles to rack deployment intensity (racks per IT area and refresh rates), and then converting unit demand into value through realistic average selling prices.
To keep the model grounded, the totals were corroborated with selective bottom-up approximations, including supplier and channel roll-ups, sampled project bills of materials, and ASP checks for common configurations. Inputs that mattered most included planned data center build-outs, typical rack heights used in new halls (for example 42U, 45U, and 48U), the split between cabinet closed and open-frame installations, the pace of rack density shifts (kW per rack), and import timing signals that indicate procurement cycles.
For forecasting, we used scenario analysis tied to build-out schedules and power availability, then aligned the pace of growth with what interviewees expect for expansions and refresh projects over the next five years. Where bottom-up visibility was thin, gaps were handled through conservative adoption assumptions and then re-tested through follow-up checks on pricing and lead times.
Data Validation & Update Cycle
Outputs were validated through triangulation across independent signals, followed by step-by-step variance checks at the assumption level. When the model produced unusual jumps, we revisited the underlying drivers, such as a single large facility phase, a pricing swing, or a timing shift in imports, and then rechecked those points with another source or respondent.
Before sign-off, a second analyst reviews the key calculations, and any large deltas versus external indicators trigger a re-contact cycle with industry participants. The report is refreshed annually, and interim updates are made when material events occur, such as major new data center announcements, policy changes that affect power access, or sharp currency moves. Right before delivery, we run a final pass so clients receive the latest updated view.
黑料不打烊's Chile Data Center Rack Market Size Measured Against Other Published Estimates
It is normal to see different market sizes for data center racks because publishers do not always count the same products, time period, or buyer set. The largest differences usually come from whether open-frame racks and wall-mount racks are included, how imported racks are treated versus locally assembled units, and whether pricing is taken from list prices or project-based realized ASPs.
Import shipment patterns, announced data center capacity additions, and a second-pass check on installed rack density are signals that keep 黑料不打烊 tied to actual rack deployments in Chile by counting racks only when they are part of data center fit-outs, rather than bundling adjacent IT hardware spending into the same total.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 25.03 M (2025) | |
| Industry Association A | USD 22.60 M (2025) | Often emphasizes member-reported cabinet shipments, which can undercount open-frame and wall-mount racks bought through integrators, and it may apply a narrow set of standard rack heights. |
| Global Consultancy B | USD 31.20 M (2026) | May infer rack value using broad equipment-to-capacity ratios and blended price inflation, which can overstate racks per expansion phase and smooth out Chile-specific pricing and mix shifts. |
The spread across the table is mainly explained by scope boundaries and price and mix handling, rather than a disagreement on Chile data center growth itself. When unit demand is tied back to build-out timing and then translated into value with configuration-level ASP checks, the result is easier to reconcile to procurement behavior and to repeat during updates.


Key Questions Answered in the Report
What is the current size of the Chile data center rack market?
The Chile data center rack market size reached USD 28.51 million in 2026 and is projected to hit USD 54.59 million by 2031.
Which rack configuration leads the market in Chile?
Full racks dominate with 64.80% share, favored by hyperscale and colocation operators for standardized, high-density deployments.
How are water-stress regulations affecting data-center design?
Strict oversight is pushing operators toward liquid cooling systems, driving demand for racks compatible with immersion and direct-to-chip cooling technologies.
Why is Valparaíso attracting hyperscale investments?
The city hosts submarine-cable landings, including the Humboldt route, providing low-latency links to Asia-Pacific markets and easing coastal cooling requirements.
Page last updated on:
- Africa Data Center Rack Market
- Australia Data Center Rack Market
- Belgium Data Center Rack Market
- Brazil Data Center Rack Market
- Canada Data Center Rack Market
- China Data Center Rack Market
- Data Center Rack Market
- Denmark Data Center Rack Market
- Europe Data Center Rack Market
- France Data Center Rack Market
- Germany Data Center Rack Market
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Construction Market Construction worldwide, split by tier, facility size and facility type.
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.


 Your data is secure and never sold or shared.


