
Denmark Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
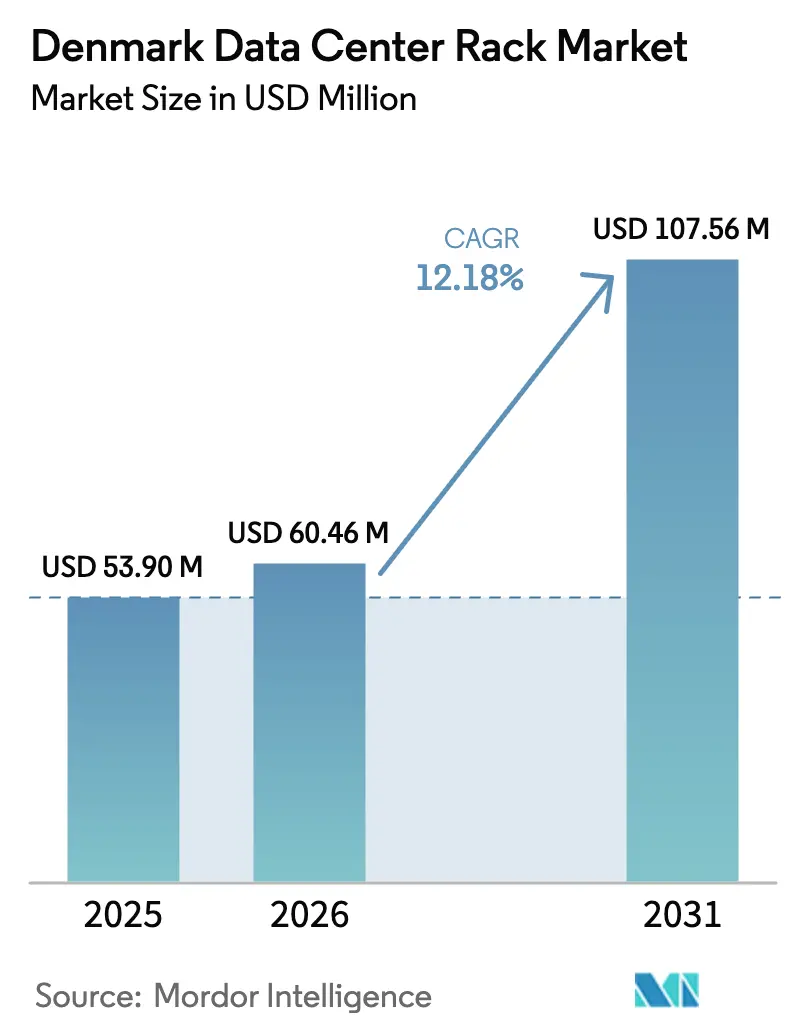
| Base Year Market Size (2025) | USD 53.9 Million |
| Market Size (2026) | USD 60.46 Million |
| Market Size (2031) | USD 107.56 Million |
| Growth Rate (2026 - 2031) | 12.18 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Denmark Data Center Rack Market Analysis by 黑料不打烊
Denmark data center rack market size in 2026 is estimated at USD 60.46 million, growing from 2025 value of USD 53.9 million with 2031 projections showing USD 107.56 million, growing at 12.18% CAGR over 2026-2031. Expansion mirrors Denmark’s role as a Nordic digital hub where 81% of the national power mix comes from renewable sources, giving operators a cost-stable, low-carbon energy base that supports premium rack investments. Continuous infrastructure spending, such as Microsoft’s multiyear build program that has required 4.1 million work hours and created 1,005 construction jobs, bolsters local demand.[1]Microsoft Corp., “Microsoft Expands Sustainable Danish Data Centers,” news.microsoft.com District-heating buy-back schemes allow data centers to monetize waste heat, offsetting 10–15% of operating costs and accelerating adoption of closed-cabinet racks engineered for efficient thermal capture. The full-rack form factor remains dominant, but AI workloads pushing 60–120 kW per rack are steering buyers toward taller 48U frames and liquid-cooling-ready designs. Material innovation, especially the move from steel toward lighter aluminum, is gaining traction as operators confront floor-loading limits for GPU-dense deployments.
Key Report Takeaways
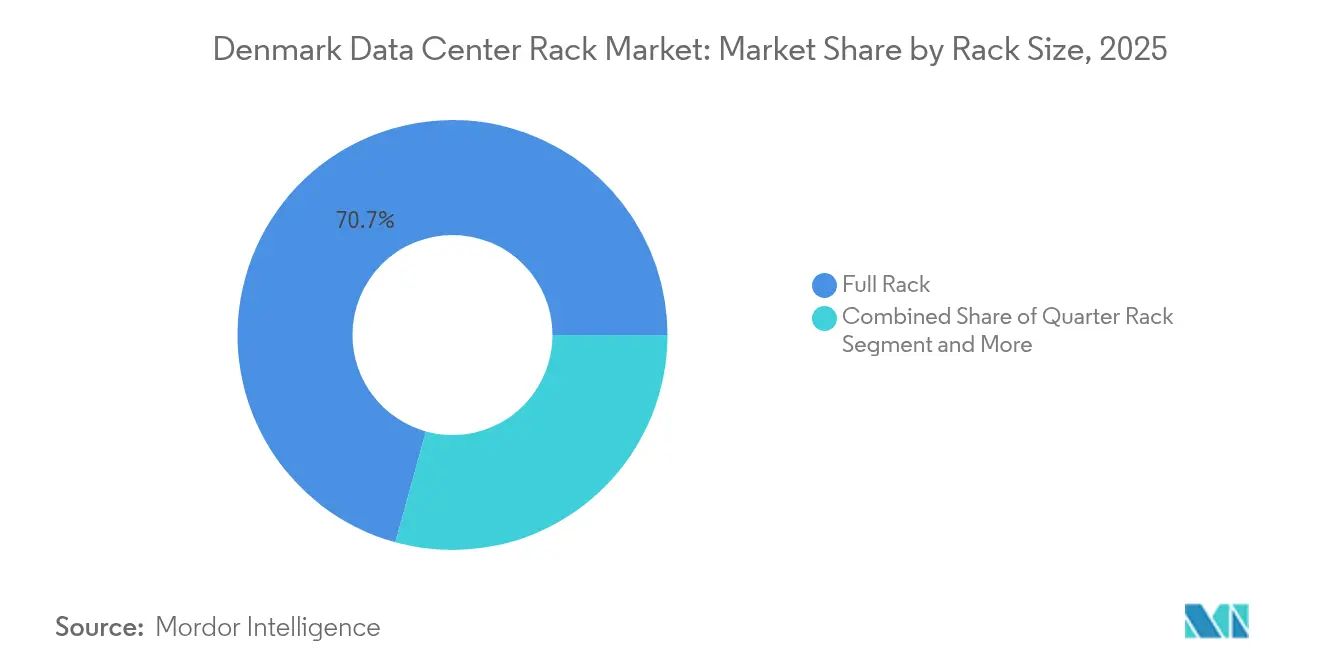
- By rack size, full racks led with 70.72% of Denmark data center rack market share in 2025; quarter racks are projected to post the fastest 18.87% CAGR through 2031.
- By rack height, 42U cabinets held 54.63% share of the Denmark data center rack market size in 2025, while 48U is advancing at an 18.16% CAGR to 2031.
- By rack type, closed-cabinet solutions captured 75.58% share in 2025 and are expanding at 19.02% CAGR to 2031.
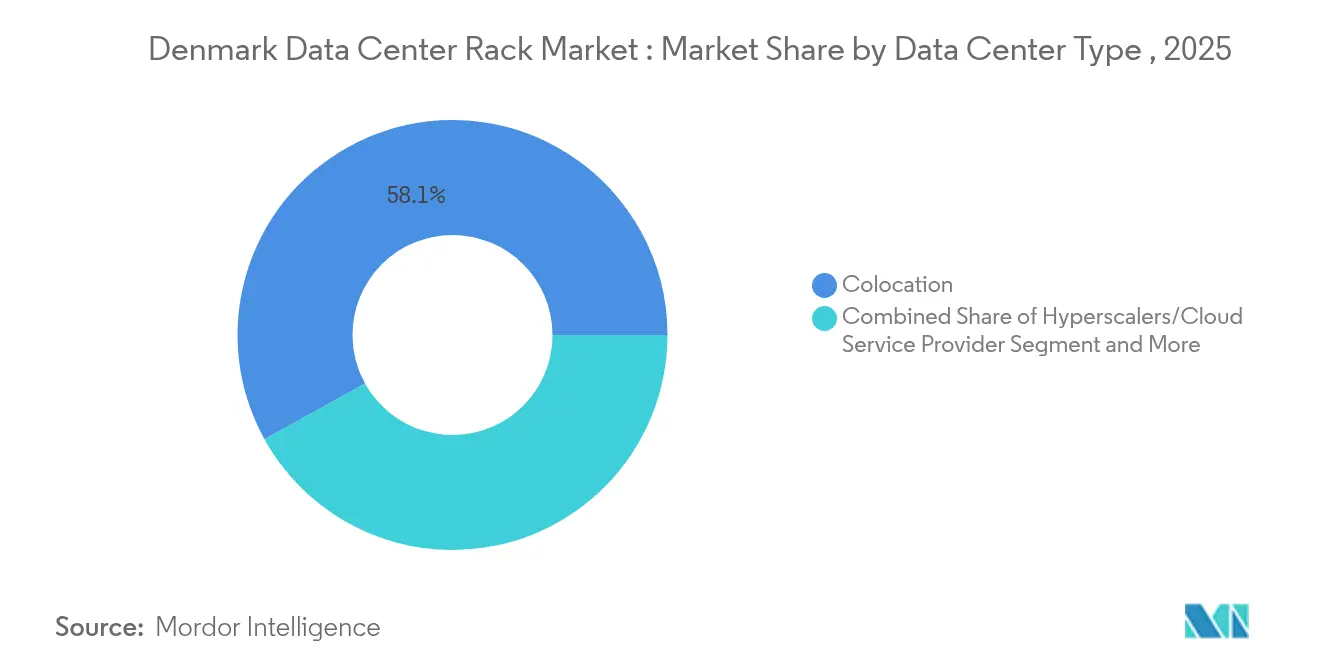
- By data-center type, colocation facilities accounted for 58.05% of Denmark data center rack market share in 2025; hyperscale deployments show the highest 20.14% CAGR through 2031.
- By material, steel held 74.62% share of the Denmark data center rack market size in 2025, while aluminum is forecast to grow 19.11% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Denmark Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in cloud-based business operations | +2.1% | Global, with Nordic emphasis on sustainability | Medium term (2-4 years) |
| Internet adoption & IT-services expansion | +1.8% | Denmark national, spillover to Nordics | Short term (≤ 2 years) |
| Hyperscale & colocation build-outs near renewable-rich grids | +2.7% | Denmark core, expansion to renewable corridors | Long term (≥ 4 years) |
| Rise in AI-driven high-density racks | +3.2% | Global with Denmark early adoption | Medium term (2-4 years) |
| District-heating buy-back incentives for waste-heat racks | +1.6% | Denmark national, Nordic regional interest | Long term (≥ 4 years) |
| Power-to-X pilot racks with on-site hydrogen fuel cells | +0.9% | Denmark core, EU regulatory alignment | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Hyperscale & Colocation Build-outs Near Renewable-Rich Grids
Denmark’s offshore-wind corridor delivers stable, low-volatility power that lets hyperscale firms such as Google run operations on 100% renewables.[2]Google LLC, “Fredericia Data Center Powered by 100% Renewables,” blog.google atNorth’s planned 250 MW ?lgod campus exemplifies how proximity to generation assets cuts transmission losses by 15–20%, lowering opex and supporting high-density rack clusters. Carbon-neutral credentials attract enterprise tenants that must meet ESG targets, reinforcing the Denmark data center rack market as a preferred destination.
Internet Adoption & IT-Services Expansion
With 99.997% grid uptime, Denmark ranks among Europe’s most reliable power markets, encouraging mission-critical SaaS providers to colocate locally. Fiber-optic upgrades and 5G rollout spur edge deployments that rely on standardized rack kits for rapid activation.
District-Heating Buy-Back Incentives for Waste-Heat Racks
Two-thirds of Danish households tap district heating. Tax changes in 2022 removed barriers for data-center hookups, and Meta’s Odense campus now warms 6,900 homes annually using recycled rack heat. [3]Meta Platforms Inc., “Odense Data Center Heat Recycling,” about.facebook.com Heat revenue boosts IRR enough to warrant premium enclosures tailored for hot-water capture, lifting the Denmark data center rack market.
Rise in AI-Driven High-Density Racks
Training clusters for generative-AI workloads need 60–120 kW per rack—up to eight times traditional loads. Denmark’s cool climate and district-heating network reduce liquid-cooling costs. Penta Infra’s CPH-1 site hit 100% heat-reuse efficiency in 2024, proving that AI-grade racks can deliver parallel revenue from heat sales PentaInfra. The capability accelerates turnover from 42U to 48U racks, boosting the Denmark data center rack market.
Restraints Impact Analysis*
| Restraint | % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Low availability of skilled resources | -1.4% | Denmark national, Nordic regional | Short term (≤ 2 years) |
| Limited industrial land near 132 kV grid nodes | -0.8% | Denmark core urban areas | Medium term (2-4 years) |
| Escalating copper prices inflating cabling costs | -1.2% | Global with Denmark import dependency | Short term (≤ 2 years) |
| Prospective carbon-based server tax | -0.6% | EU regulatory framework, Denmark early adoption | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Low Availability of Skilled Resources
Microsoft’s build program alone needed 1,005 specialized workers, stretching Denmark’s limited technical labor pool. Wage inflation of 20–25% adds cost pressure, delaying rack rollouts vital to hyperscale capacity growth.
Escalating Copper Prices Inflating Cabling Costs
Copper cost spiked 15–20% in 2024, adding budget risk for GPU-dense racks that use triple the copper per cabinet. Although operators trial aluminum conductors for low-current paths, critical feeds still depend on copper, slowing Denmark data center rack market adoption when metal prices swing sharply.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full Racks Dominate Enterprise Deployments
Full racks captured 70.72% of Denmark data center rack market share in 2025, highlighting the sector’s preference for standardized 42U and 48U footprints that simplify airflow modeling. The Denmark data center rack market size tied to full racks is forecast to expand at 18.64% CAGR as hyperscalers pack more GPUs per cabinet. Enterprises migrating from server rooms gravitate to half- and quarter-racks for branch offices, yet volume remains niche.
A second factor underpinning full-rack dominance is supply-chain efficiency: vendors concentrate production on high-volume SKUs, shortening lead times and reducing unit pricing. atNorth’s DEN02 colocation design standardizes on full racks to streamline project delivery atNorth. This strategy aids Denmark data center rack market penetration among multinational tenants needing predictable specifications across regions.


By Rack Height: 42U Standard Faces 48U Challenge
The 42U format held 54.63% share of the Denmark data center rack market size in 2025. However, 48U cabinets—offering 14% extra vertical capacity—are set to register 18.16% CAGR, driven by AI servers stacked with accelerator cards. Denmark’s robust floor-loading codes and effective liquid-cooling infrastructure mitigate risks linked to taller racks.
Manufacturers like Lenovo now qualify 48U frames for 4,000-pound loads, ensuring compatibility with GPU clusters. Operators adopting 48U gain better space economics on expensive Danish real estate, positioning this form factor as the next standard for the Denmark data center rack market.
By Rack Type: Enclosed Cabinets Lead Cooling Optimization
Closed cabinets own 75.58% of Denmark data center rack market share thanks to built-in airflow management essential for heat-reuse schemes. Chatsworth Products’ ZetaFrame system with hot-aisle containment exemplifies the shift toward enclosure-integrated cooling. Open-frame models remain in edge sites where ambient conditions are less controlled.
Closed designs help operators maintain inlet temperatures optimal for district-heating recovery, translating into additional revenue. Their higher upfront price becomes marginal once heat-buy-back income is modeled over a 15-year rack lifecycle, reinforcing adoption throughout the Denmark data center rack market.
By Data Center Type: Colocation Leads, Hyperscale Accelerates
Colocation centres delivered 58.05% of cabinet purchases in 2025, reflecting outsourcing trends among enterprises attracted by green power and permit simplicity. Hyperscale builds, though smaller in absolute numbers, will log a 20.14% CAGR to 2031 as cloud giants consolidate European AI clusters in Denmark.
Digital Realty’s Copenhagen campus offers turnkey connections to offshore-wind PPAs, encouraging tenants to deploy high-density cabinets without negotiating individual energy contracts. This value proposition sustains colocation leadership even as hyperscale growth inflates total Denmark data center rack market volume.
By Material: Steel Dominance Faces Aluminum Innovation
Steel remained the default, holding 74.62% share in 2025. Yet aluminum’s 19.11% projected CAGR signals a shift toward lighter alloys suitable for 4,000-pound GPU racks where floor-loading limits apply. nVent HOFFMAN’s move to aluminum frames for select SKUs highlights evolving customer requirements.
Aluminum’s embodied-carbon advantage also dovetails with Danish sustainability metrics. Recycling loops in the EU secure local feedstock, lowering scope-3 emissions for operators and giving aluminum an edge in future Denmark data center rack market tenders.
Geography Analysis
Copenhagen anchors the Denmark data center rack market with 25 facilities operated by 11 providers, reinforcing its status as EMEA’s 18th-largest hub. Grid reliability of 99.997% and proximity to trans-Nordic fiber routes make the capital an ideal landing zone for international workloads.
West Jutland is emerging as the next growth pole. Google’s Fredericia site leverages abundant offshore-wind capacity for carbon-free power, while atNorth selected ?lgod for a 250 MW campus that will export surplus heat to local greenhouses. Esbjerg’s first fully Danish-owned hyperscale project, scheduled for 2026, aims to scale from 10 MW to 200 MW and underscores regional decentralization.
Denmark’s integration into the Nordic power pool lets operators arbitrage surplus hydro or wind from Norway and Sweden, cushioning market participants against price spikes. At the same time, a nationwide district-heating grid covering 64.5% of homes drives selection of racks engineered for controlled heat exhaust, a unique requirement compared with other EU states. These intertwined energy and thermal networks differentiate the Denmark data center rack market from broader European peers.
Regulatory Landscape
Denmark has tightened oversight around how large power users, including data centers, connect to and operate on the grid, which affects project timelines and the mix of rack solutions deployed. From February 1, 2026, Energinet changed the rules for large grid connections by abolishing the first-come-first-served principle and moving to a maturity-based scoring approach that rewards projects with higher readiness and grid friendliness.
On the operational side, data centers with an IT load of 500 kW or above must report sustainability performance metrics (including energy-efficiency related data) into a national scheme that feeds a European database. Surplus-heat recovery is also embedded in permitting and operating considerations, with operators required to conduct cost-benefit analyses overseen by the Danish Energy Agency (Energistyrelsen) to evaluate the technical and economic feasibility of heat reuse, reinforcing demand for closed-cabinet racks and thermal-containment designs aligned with district-heating integration.
Value Chain Analysis
The Denmark data center rack value chain begins with global rack and enclosure OEMs and adjacent power and thermal infrastructure suppliers, then moves through Danish and Nordic distributors, system integrators, and installation contractors who adapt standard SKUs to local requirements such as heat-reuse interfaces and high-density power distribution. Global vendors including Schneider Electric SE, Vertiv Group Corp., Rittal GmbH & Co. KG, and Eaton Corporation plc supply racks, containment, PDUs, and integrated cabinet systems, while Danish players such as Cabinet System A/S address local demand for configurable enclosures and accessories.
Downstream, colocation and hyperscale operators are the primary buyers. Delivery depends on a network of local engineering services, fiber and network providers, and specialized construction and commissioning firms that support campus builds and retrofits. The Danish Data Center Industry (DDI) functions as a key industry body connecting operators, vendors, and municipalities, helping coordinate practical issues such as permitting workflows and site selection constraints near grid nodes, alongside operational requirements for district-heating connections that shape rack specifications.
Competitive Landscape
Competition is moderately fragmented. Global conglomerates such as Eaton and Schneider Electric command strong positions in power management and turnkey enclosures yet must localize solutions to interface with district-heating loops and hydrogen-ready backup systems. Nordic specialists, including Rittal’s regional integrators and emerging Danish fabricators, leverage intimate knowledge of permit protocols and energy-reuse standards to win niche contracts.
Strategic moves skew toward sustainability. Schneider Electric’s 2024 purchase of Motivair added direct-to-chip liquid-cooling capability, essential for GPU racks exceeding 80 kW . Vertiv’s reference designs codified with NVIDIA simplify AI cluster deployment and align with Danish operators’ density targets. These initiatives elevate solution stickiness and expand service deals around lifecycle thermal management.
Market entrants targeting hydrogen fuel-cell backup leverage Denmark’s Power-to-X roadmap, which aims for 4–6 GW of electrolysis by 2030. Vendors able to integrate rack power distribution with fuel-cell stacks may carve out a premium segment, reshaping the Denmark data center rack market over the long term.
Denmark Data Center Rack Industry Leaders
Rittal GMBH & Co.KG
Schneider Electric SE
Vertiv Group Corp.
Eaton Corporation plc
Cabinet System A/S
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Grid-access constraints and policy changes are creating whitespace for rack suppliers that can help operators qualify projects and reduce grid impact. Energinet's February 2026 shift from first-come-first-served to a maturity-based scoring model increases the value of integrated, deployment-ready rack packages such as preconfigured cabinets, containment, and power distribution. This approach can shorten commissioning cycles and support smoother handling of efficiency and readiness requirements in connection and permitting processes.
Denmark's heat-reuse and sustainability operating requirements continue to pull the market toward premium closed-cabinet and thermal-management-ready rack designs. With district heating covering a large share of households and data centers required to assess surplus-heat recovery feasibility under Danish Energy Agency oversight, demand concentrates on racks designed for controlled exhaust capture, hot-aisle containment, and compatibility with liquid-cooling retrofits. In parallel, high-density AI build-outs in Denmark are reinforcing demand for taller, heavier-duty frames such as 48U, along with power-dense cabinet architectures, expanding the addressable market for reinforced, liquid-cooling-ready, and energy-optimized rack solutions bought through colocation and hyperscale procurement channels.
Recent Industry Developments
- July 2026: Microsoft launched the Denmark East cloud region with facilities in H?je Taastrup, K?ge, and Roskilde. The expansion broadens Denmark's cloud and AI capacity and increases demand for data center capacity, including scope for greater district heating integration.
- July 2026: Schneider Electric + Aeven confirmed collaboration to implement Galaxy VX UPS and EcoStruxure Microgrid Advisor for grid-assisted power to Danish data centers. The partnership delivers a combined power and microgrid solution for high-density AI racks, reinforcing resilience and grid interaction.
- June 2026: Caverion Denmark commenced a technical installation project for an operational data center expansion valued at 111 MDKK. The on-site expansion activity indicates continued capacity growth and sustains local service demand.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the Denmark data center rack market covers revenue from rack cabinets and related rack enclosures used to mount IT and network equipment inside data centers located in Denmark.
Scope exclusions: We exclude full data center construction spend, power and cooling infrastructure, and ongoing installation labor that is billed as a separate service.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (?52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to map the Denmark data center footprint and to anchor the model with public, repeatable signals. We rely on official and non-paywalled sources such as Statistics Denmark for business and trade context, Eurostat for harmonized macro and industry series, and the International Energy Agency for electricity and demand trends that influence buildouts.
To connect infrastructure growth to rack needs, we also review sources such as ENTSO-E for grid and supply indicators, the Danish Energy Agency for national energy planning signals, and public procurement portals for tender language that can indicate rack specifications and delivery timelines. Alongside this, we use company filings, investor presentations, customs-style import-export views where available, and paid company financials and news subscriptions to cross-check pricing moves and shipment commentary. These sources are illustrative, and we use additional references during data collection, validation, and clarification.
Primary Interviews and Surveys
We speak with Denmark-based data center operators, colocation specialists, rack and infrastructure suppliers, consultants, and facility managers. Their input helps clarify rack densities, product preferences, selling prices, project commissioning, and gaps in public capacity data before these assumptions are triangulated.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 15% |
| Mid tier: 50% | Functional/Unit leaders: 30% |
| Smaller Players: 20% | Managers: 55% |
Market-Sizing & Forecasting
Sizing starts from a top-down build that reconstructs Denmark rack demand from the active and planned data center footprint, then translates rack volumes into expected rack counts by site type and typical deployment patterns. Those rack volumes are priced using observed Denmark and Northern Europe selling price bands, adjusted for mix shifts between cabinet types, heights, and materials.
We then corroborate the totals with selective bottom-up checks, such as sampling distributor throughput, comparing vendor-reported capacity signals, and using a simple ASP x volume view for commonly purchased rack formats, and we adjust when the gap is persistent. Inputs that matter in this market include planned rack additions tied to capacity expansion, site commissioning timelines, average rack height preferences, density and cooling-related design changes that affect cabinet choice, and freight and metal-linked price movements that can shift ASPs.
For the forecast, scenario analysis is used so demand can be flexed based on how quickly announced projects move from planning to live operations and how refresh cycles change for existing facilities. Where bottom-up detail is thin for smaller channels, gaps are handled with conservative range estimates anchored to observed procurement patterns, then re-validated in primary check-ins.
Data Validation & Update Cycle
Validation is done through several checks so the final numbers stay aligned with real market signals. We compare modeled revenue with independent indicators such as build-pipeline timing, import and supply signals, and public announcements that point to changes in rack deployment rates.
Outliers are reviewed by a second analyst, and assumptions are revisited if the model creates step changes that cannot be explained by pricing, mix, or project timing. Reports are refreshed annually, with interim updates when material events occur, such as major project delays, large capacity announcements, or sharp currency and input-cost swings. Before delivery, a fresh review pass is completed so clients receive an updated view that matches the latest available information.
黑料不打烊's Denmark Data Center Rack Market Size Versus Other Published Estimates
Published market sizes for Denmark data center racks can vary widely, even when they look like they cover the same topic. The differences usually come from what gets counted as rack revenue, the year used for pricing and currency conversion, and how project timing is treated when sites are still under construction.
A refresh-led gap also shows up in the way ASPs are moved forward from older price points, since recent steel, freight, and supplier lead-time shifts can change cabinet pricing quickly. When the model is re-run with current quarter currency timing and a re-checked Denmark price band by rack type, the total aligns better with what buyers are actually paying, which is the approach applied in 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 53.9 M (2025) | |
| Global Consultancy A | USD 70 M (2024) | Often bundled scope where rack cabinets are combined with installation and fit-out line items, and pricing is not consistently re-based to Denmark transaction timing for the stated year. |
| Industry Tracker B | USD 45 M (2025) | Uses conservative rack-addition assumptions based on a limited pipeline view, and applies a flat ASP progression that underweights recent mix shifts toward higher specification cabinets. |
The table shows that most of the spread can be explained by scope boundaries and the timing of price and currency inputs, rather than a true disagreement on demand direction. By keeping the model tied to rack units added and refreshed in Denmark, and then pricing those units with year-specific assumptions that can be rechecked, we deliver a market size that is easier to trace and repeat.


Key Questions Answered in the Report
What is the current value of the Denmark data center rack market?
The market is valued at USD 60.46 million in 2026 and is forecast to reach USD 107.56 million by 2031.
Which rack size is most popular in Denmark?
Full-rack configurations, particularly 42U and 48U, held 70.72% market share in 2025.
Why are 48U cabinets gaining traction?
AI workloads requiring 60-120 kW per rack drive demand for the extra 6U of vertical space, supporting an 18.16% CAGR for 48U units.
How does Denmark’s district heating influence rack choices?
Data centers can sell waste heat, so operators prefer closed-cabinet designs optimized for thermal capture to monetize up to 15% of operating costs.
Page last updated on:
- Africa Data Center Rack Market
- Australia Data Center Rack Market
- Belgium Data Center Rack Market
- Brazil Data Center Rack Market
- Canada Data Center Rack Market
- Chile Data Center Rack Market
- China Data Center Rack Market
- Data Center Rack Market
- Europe Data Center Rack Market
- France Data Center Rack Market
- Germany Data Center Rack Market
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.


 Your data is secure and never sold or shared.


