
North America Data Center Networking Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 9.8 Billion |
| Market Size (2026) | USD 10.42 Billion |
| Market Size (2031) | USD 14.17 Billion |
| Growth Rate (2026 - 2031) | 6.35 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
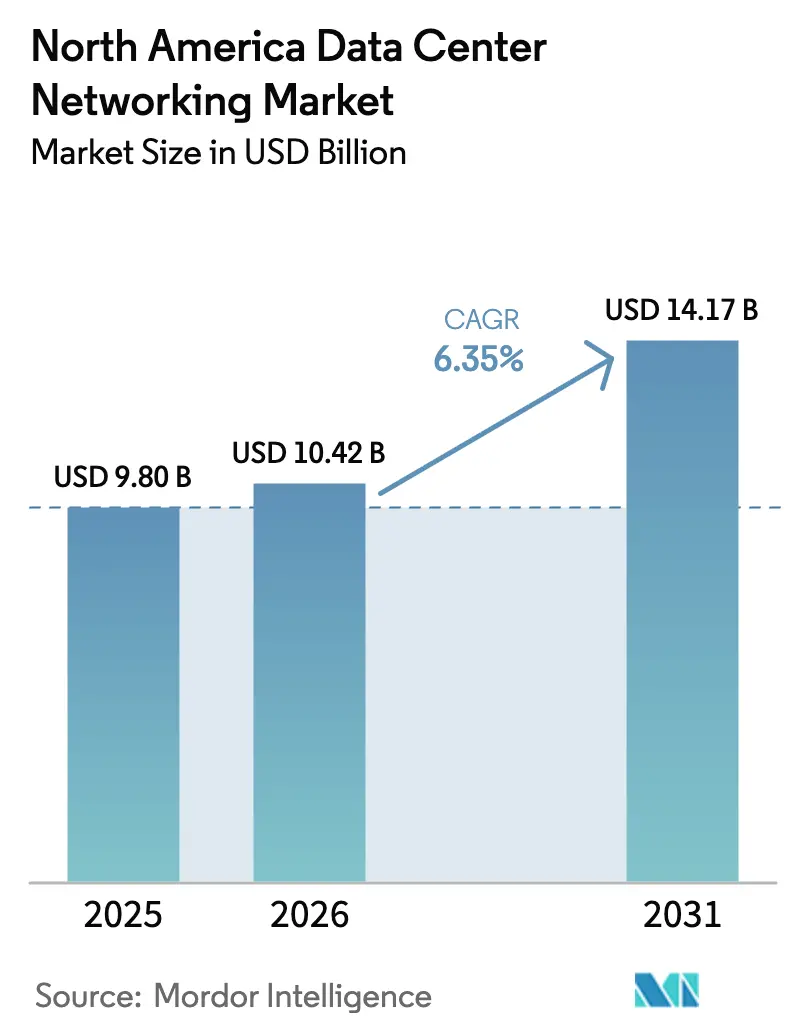
North America Data Center Networking Market Analysis by 黑料不打烊
North America data center networking market size in 2026 is estimated at USD 10.42 billion, growing from 2025 value of USD 9.8 billion with 2031 projections showing USD 14.17 billion, growing at 6.35% CAGR over 2026-2031. Strong hyperscale investments, a rapid shift to AI-centric workloads, and the push for ultra-low-latency connectivity keep the region at the global forefront of data-center build-outs. Power-hungry AI training clusters, heightened cybersecurity demands, and the mainstreaming of 400 G/800 G Ethernet are reshaping spending priorities. Colocation remains the dominant deployment model, yet hyperscalers lead absolute capacity additions, while edge sites scale quickly to support 5G and IoT services. Vendors differentiate through silicon advances, open-network operating systems, and managed-service offerings that ease multicloud complexity for enterprises.
Key Report Takeaways
- By component, products commanded 71.25% of the North America data center networking market share in 2025; services are projected to expand at an 10.85% CAGR through 2031.
- By data-center type, colocation facilities led with 52.85% revenue share in 2025, while hyperscalers are set to advance at a 14.9% CAGR to 2031.
- By bandwidth, 50-100 GbE configurations accounted for 37.65% of the North America data center networking market size in 2025; links above 100 GbE are rising at a 12.7% CAGR.
- By end-user, IT & telecommunications held 36.90% share of the North America data center networking market size in 2025; healthcare is the fastest-growing segment at 8.85% CAGR.
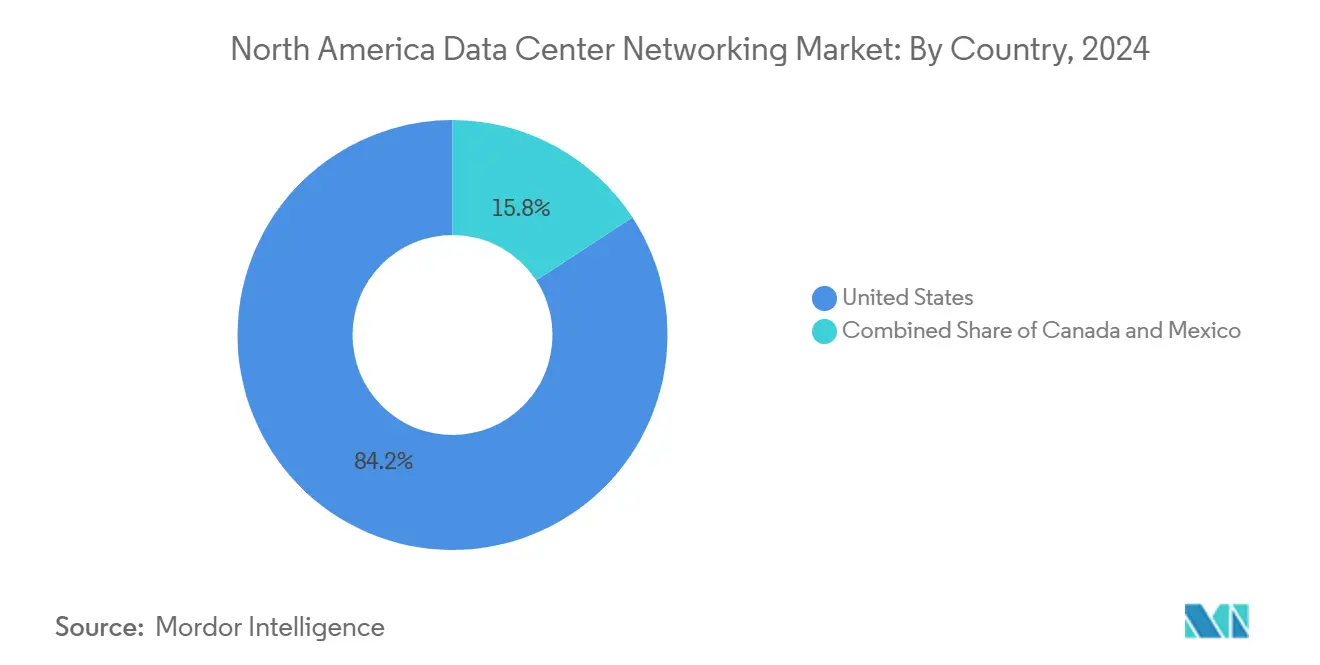
- By geography, the United States contributed 83.75% of the North America data center networking market share in 2025, whereas Mexico is forecast to accelerate at a 9.95% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Data Center Networking Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing need for cloud storage and low-latency performance | +1.8% | US hyperscale corridors | Medium term (2-4 years) |
| Rising cybersecurity threats and network refresh | +1.2% | North America, EU enterprise cores | Short term (≤ 2 years) |
| AI/ML workloads demanding 400/800 GbE | +2.1% | US West Coast, expanding to Canada and Mexico | Medium term (2-4 years) |
| Edge data-center rollout alongside 5G | +0.9% | Metro areas across North America | Long term (≥ 4 years) |
| Utility-scale on-site generation | +0.7% | US Southwest and Texas renewables clusters | Long term (≥ 4 years) |
| State-level tax incentives | +0.5% | Washington, Georgia, Texas, select Canadian provinces | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
AI/ML Workloads Driving Adoption of 400 G/800 G Switching
Demand for model training on thousands of GPUs has doubled the addressable network spend for AI fabric, pushing operators to jump from 100 G to 400 G and 800 G leaf-spine designs. Arista expects its AI-center networking revenue to reach USD 1.5 billion in 2025 as customers deploy ultra-low-latency Ethernet fabrics optimised for distributed learning. Broadcom’s 102.4 Tbps Tomahawk 6 silicon underpins next-generation switches that interconnect more than 1 million accelerators per cluster.[1]Broadcom Inc., “Introducing Tomahawk 6: 102 Tbps Ethernet Switching,” broadcom.com The Ultra Ethernet Consortium is finalising congestion-aware protocols that streamline all-reduce, all-gather, and collective ops typical in deep learning. Silicon photonics further narrows latency and power envelopes, with Taiwan’s foundry network emerging as a critical scale-out supply base.
Rising Cybersecurity Threats Prompting Network Upgrades
Zero-trust adoption has accelerated after CISA reported coordinated attacks on managed service providers that ripple through downstream tenants.[2]Cybersecurity and Infrastructure Security Agency, “Protecting Managed Service Providers,” cisa.gov Financial majors such as J.P. Morgan have rebuilt inter-data-center encrypted channels and refreshed firewalls to satisfy evolving compliance requirements. AI-based threat-detection engines now sit inline on core switches, allowing sub-second anomaly isolation. Healthcare operators extend these controls to edge pods carrying protected health information, incorporating chip-level secure boot and telemetry to meet HIPAA mandates.
Increasing Need for Cloud Storage and Low-Latency Application Performance
Global data creation is on pace to surpass 200 zettabytes by 2025, forcing enterprises to embrace latency below 1 ms for workloads such as trading, autonomous driving, and AR overlays. Storage fabrics are evolving toward 64 G Fibre Channel and NVMe-over-TCP, while spine-and-leaf layouts minimise hop counts and avert head-of-line blocking. Hybrid-cloud strategies amplify these requirements, demanding seamless performance between on-prem and public zones without sacrificing observability.
Edge Data-Center Proliferation Alongside 5G Roll-outs
American Tower has opened micro-sites delivering 1 MW of IT load inside macro-tower compounds, shaving last-mile latency for content caching and private-5G slices. Nokia’s alliance with Andorix shows telco-neutral real estate converging with edge compute for smart-building analytics. Typical edge halls span 500 kW–2 MW, use modular chillers, and tap carrier-hotel cross-connects to interlock with hyperscale regions.
Restraints Impact Analysis of North America Data Center Networking Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Network complexity and multi-vendor integration | -0.8% | Global hybrid clouds | Medium term (2-4 years) |
| High capex for 800 GbE optics and switches | -1.1% | North American hyperscalers | Short term (≤ 2 years) |
| Power-grid interconnection delays | -1.4% | US high-demand zones, extending into Canada | Long term (≥ 4 years) |
| Optical-transceiver supply shortages | -0.9% | Global fab networks, North American assembly lines | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Power-Grid Interconnection Delays Lengthening Build Cycles
More than 2,600 GW of generation await grid interconnection in the United States, slowing data-center energisation by up to seven years in congested locales such as Northern Virginia.[3]Lawrence Berkeley National Laboratory, “Queued in: Interconnection Backlogs,” lbl.gov The backlog threatens 20% of planned facilities and could double Virginia’s electricity consumption by 2033. Operators respond by co-locating on-site renewables or adopting micro-grids; Google’s USD 20 billion programme pairs campuses with solar and wind parks that bypass transmission bottlenecks.
High Capex for Next-Gen Optics and 800 GbE Switches
A single 1U 16-port 800 G switch now lists north of USD 30,000, reflecting costly co-packaged optics and high-density ASICs. Lumentum warns that tight EML supply could persist into 2026 even as the firm targets USD 500 million quarterly optical revenue. Celestica’s DS4100 800 G top-of-rack platform underscores the premium paid to unlock 12.8 Tbps non-blocking bandwidth.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Data Center Networking Market Segment Analysis
By Component:
Services Accelerate Despite Product DominanceProducts still account for 71.25% of the North America data center networking market, anchored by Ethernet switches, routers and optical interconnects that underpin hyperscale fabrics. Services, however, are forecast to climb at an 10.85% CAGR as firms outsource design, monitoring and lifecycle support to managed providers. Installation and integration tasks balloon with 400 G/800 G rollouts, while managed network services absorb operational complexity for enterprises lacking in-house skillsets. This pivot toward services echoes the rise of consumption-based models across IT infrastructure.
A maturing installed base amplifies demand for proactive maintenance and AIOps-driven troubleshooting. Training and consulting revenues also rise because AI fabric tuning and silicon-photonic deployments require specialised expertise. The North America data center networking market size for services is set to outpace products in incremental growth even though hardware will continue to dominate absolute spend.


By End-User:
Healthcare Emerges as Growth LeaderIT and telecommunications dominate with 36.90% share of the North America data center networking market, reflecting constant backbone upgrades by cloud and content providers. Healthcare and life sciences record the fastest 8.85% CAGR owing to telehealth expansion, genomics data spikes and strict compliance mandates. Hospital groups now ingest petabyte-scale imaging datasets and rely on encrypted, ultra-reliable interconnects for remote surgery support.
Banking, financial services and insurance remain sizeable, modernising with all-photonic backbones that allow live core-system migrations under one-second downtime nttdata. Media & entertainment budgets climb with high-bit-rate streaming, while industrial firms upgrade to enable Industry 4.0 analytics at the edge. The North America data center networking industry thus touches every vertical seeking competitive differentiation through low-latency data flows.
By Data-Center Type:
Hyperscalers Drive Future GrowthColocation sites delivered 52.85% of 2025 revenue, catering to enterprises seeking pay-as-you-go footprints and carrier neutrality. Yet hyperscalers are scaling fastest at 14.9% CAGR, highlighted by AWS’s USD 11 billion Georgia build and Microsoft’s USD 80 billion multiyear campus plan. Operators are also deploying modular edge pods to support 5G densification, with capacities between 500 kW and 2 MW.
Hyperscalers’ dominance reflects the pivot to cloud-native architectures and AI platform launches requiring exascale bandwidth. Colocation keeps relevance through interconnection-rich campuses linking multiple clouds, while edge and micro-data-center models thrive near population clusters where milliseconds matter.

By Bandwidth:
Ultra-High-Speed Transition AcceleratesLinks in the 50-100 GbE range still comprise 37.65% of the North America data center networking market size, serving mainstream enterprise applications. Ports above 100 GbE exhibit a 12.7% CAGR as operators leapfrog directly to 400 G and 800 G fabrics. Arista’s 51.2 Tbps 7060X6 leaf and 460 Tbps 7800R4 spine exemplify this shift. Broadcom’s Tomahawk 6 further pushes bandwidth ceilings beyond 100 Tbps per chassis.
Legacy ≤ 10 GbE deployments continue to taper, while 25-40 GbE rolls forward as a midway refresh for mid-market operators reluctant to absorb the full capex of 400 G optics. Nonetheless, AI cluster economics increasingly make 400 G the new floor for greenfield builds.
Geography Analysis
United States Data Center Networking Market
The United States retains 83.75% of the North America data center networking market, underpinned by unrivalled hyperscale campus density, leading silicon ecosystems, and a deep talent pool. Northern Virginia added 391.1 MW in Q1 2024 capacity yet faces grid constraints extending energisation timelines to seven years. Federal and state incentives such as revived Washington sales-tax exemptions and Georgia’s equipment credits steer deployment patterns, while the Department of Energy highlights 16 prospective eco-efficient campus zones.
Mexico Data Center Networking Market
Mexico, while smaller in absolute spend, records the briskest 9.95% CAGR and is emerging as a Latin American interconnection hub. Querétaro hosts 65% of national capacity with 26 active builds, drawing USD 7 billion of new investment for 2023-2027. Cloud majors view the corridor as a nearshoring back-plane to US workloads and a stepping-stone to Spanish-speaking markets. Edgenet’s plan for 30 micro-facilities highlights the push toward nationwide low-latency coverage.
Canada Data Center Networking Market
Canada leverages hydroelectric abundance to attract sustainable builds in Quebec and British Columbia. Provincial incentives and proximity to US demand pools position Canadian halls as disaster-recovery and AI inference spill-over sites. Partnerships such as Nokia-Andorix for private-5G edge mesh show the country aligning telco and data-center agendas.
Regulatory Landscape
The US regulatory environment is increasingly tying data center networking upgrades to grid readiness and cyber compliance. In June 2026, the Federal Energy Regulatory Commission (FERC) issued multiple show-cause orders to accelerate large-load interconnection reforms at RTOs/ISOs, and directed the North American Electric Reliability Corporation (NERC) to develop mandatory reliability standards for computational loads by December 31, 2026. These steps directly affect the timelines and siting feasibility of the high-density AI clusters that underpin 400G/800G network refresh cycles.
On the public-sector IT side, OMB Memorandum M-25-03 (implementation guidance for the Federal Data Center Enhancement Act) reinforces centralized investment governance and adds cybersecurity and resilience requirements for federal data center modernization. FedRAMP security baselines also continue to shape cloud-connected networking architectures used for government workloads. NIST programs such as USGv6, along with federal network initiatives such as Trusted Internet Connection (TIC), further influence enterprise-grade design choices for IPv6 and perimeter/egress controls.
Value Chain Analysis
North America data center networking value creation starts with high-performance switching silicon and optics, and then moves through system vendors, integrators, and operators that assemble, deploy, and run large-scale fabrics. Silicon and platform roadmaps from companies such as Broadcom and NVIDIA influence switch and NIC capabilities, while OEMs and networking specialists (Cisco, Arista, Juniper, Dell, and HPE) package ASICs, optics, and NOS stacks into leaf-spine systems, security appliances, and SDN controllers for hyperscalers, colocation providers, and large enterprises.
Deployment and operations are handled through resellers and systems integrators (for example, Presidio), as well as managed service providers that cover design, integration, observability, and lifecycle support. This services component is expanding as AI fabrics and multi-vendor environments increase operational burden. Across the chain, standards and frameworks steer specifications and procurement, including NIST USGv6 for IPv6 alignment, the federal Trusted Internet Connection (TIC) program for government networking controls, and data center infrastructure standards such as ANSI/TIA-942-B, which formalizes facility and connectivity requirements.
Competitive Landscape
Cisco holds a commanding but gradually eroding 76.13% share of core networking revenue, facing stiff AI-fabric competition from Arista (10.03%) and Juniper (7.27%). Arista’s CloudVision telemetry and super-spine leaf architecture appeal to hyperscalers, while Juniper’s AI-Native Portfolio claims 90% trouble-ticket reductions and 85% opex cuts through self-driving operations. Broadcom remains the silent king-maker, embedding Tomahawk silicon across multiple OEM lines.
M&A reshapes the field: Hewlett-Packard Enterprise is contesting a DOJ suit to seal its USD 14 billion bid for Juniper, aiming to fuse servers, storage, and networking into an open AI stack. White-box integrators such as Celestica and FS attack niche AI clusters with price-performance-optimised 800 G switches. Meanwhile, American Tower, Digital Realty, and Equinix attempt to blur lines between carrier hotels, edge colo, and regional cloud on-ramps, heightening the importance of neutral connectivity fabrics.
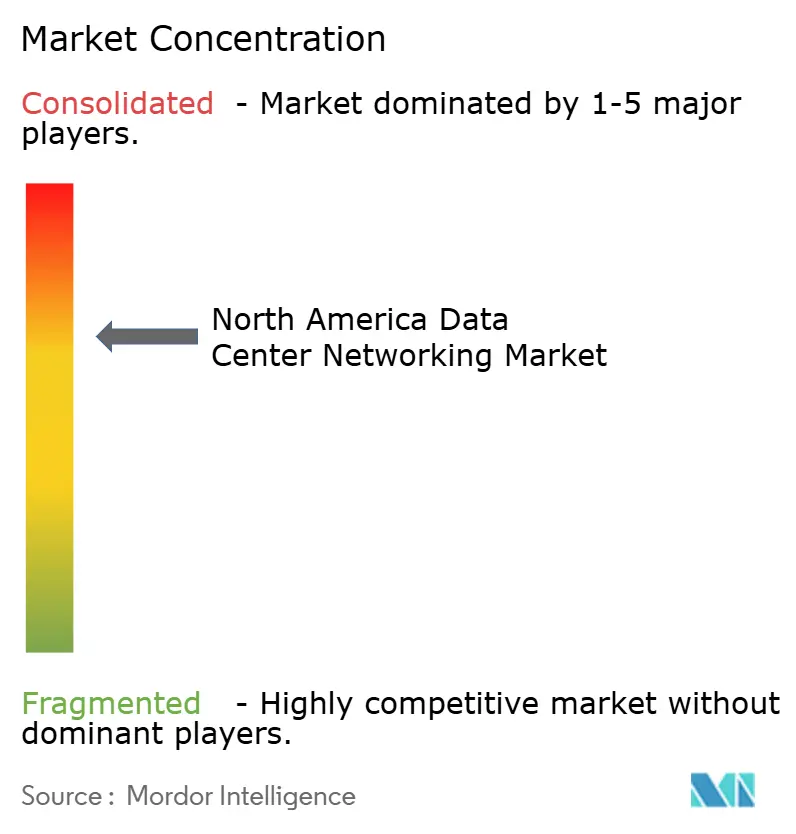
Despite moderate consolidation, innovation cycles run brisk: Broadcom’s 102.4 Tbps switch, Dell’s partner rebates for Z-Series, and Google’s renewables-coupled campuses all signal aggressive capex linked to AI economics and sustainability imperatives.
North America Data Center Networking Industry Leaders
Cisco Systems, Inc.
Juniper Networks, Inc.
Arista Networks, Inc.
Dell Technologies Inc.
Hewlett Packard Enterprise Company
- *Disclaimer: Major Players sorted in no particular order
North America Data Center Networking Market Companies Covered in this Report
- Cisco Systems, Inc.
- Broadcom Inc.
- Juniper Networks, Inc.
- Arista Networks, Inc.
- Dell Technologies Inc.
- Hewlett Packard Enterprise Company
- Extreme Networks, Inc.
- NVIDIA Corporation (incl. Cumulus Networks)
- VMware, Inc.
- Fortinet, Inc.
- F5, Inc.
- Radware Ltd.
- A10 Networks, Inc.
- NEC Corporation
- Lenovo Group Limited
- Ciena Corporation
- IBM Corporation
- Oracle Corporation
- Array Networks, Inc.
- Infinera Corporation
Read Analysis of North America Data Center Networking Companies

Market Opportunities and Future Outlook
AI-optimized fabrics create actionable whitespace for higher-speed switching, liquid-cooled architectures, and operational software that reduces deployment friction. In June 2026, Arista introduced a next-generation 1.6 Tbps portfolio for AI fabrics, reflecting a shift toward 1.6T lanes and denser spine-leaf designs. Vendors and integrators can capture value through migration services, fabric validation, and telemetry-driven assurance as customers move beyond 100 GbE to 400/800 GbE and newer form factors.
Standardized reference architectures and ecosystem programs are also widening the addressable customer base beyond hyperscalers by reducing integration risk for enterprises and colocation tenants. Equinix, Cisco, and NVIDIA announced Secure AI Factory deployments in June 2026, providing operators and customers a repeatable blueprint spanning switching, optics, security controls, and managed operations. At the same time, grid and siting constraints are raising demand for network designs that maximize throughput per watt and simplify scaling, which aligns with liquid-cooled switching and optics approaches and compliance-driven upgrades tied to OMB M-25-03, FedRAMP requirements, and zero-trust adoption.
Recent Industry Developments in North America Data Center Networking Market
- June 2026: Juniper Networks ships QFX5250-64OE-L, a 102.4 Tbps fixed switch with 64 ports of 1.6 Tbps each and 100% liquid cooling. The high density switch supports AI workloads by enabling cooling-enabled data-center fabrics for core and aggregation layers.
- March 2026: Arista Networks forms the XPO multi-source agreement for 12.8 Tbps liquid-cooled optics modules. The initiative advances liquid-cooled optics for AI ready networks and fosters an interoperable ecosystem to scale deployments.
- February 2026: Cisco Systems introduces Silicon One G300 102.4 Tbps switching silicon for AI data centers with liquid cooling. The silicon strengthens Cisco's AI dedicated data-center portfolio, reinforcing thermal management and scalability in next-gen spine-leaf fabrics.


North America Data Center Networking Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market includes spending on networking products and related services used to connect servers, storage, and racks inside data centers, and to link data centers to each other across North America.
Scope exclusions: We exclude general-purpose enterprise campus LAN equipment that is not procured for data center use cases, and we do not count building power and cooling infrastructure.
Segments Covered in This Report
- By Component
- Products
- Ethernet Switches
- Routers
- Storage Area Network (SAN)
- Application Delivery Controllers (ADC)
- Network Security Appliances
- Software-Defined Networking (SDN) Controllers
- Optical Interconnects
- Services
- Installation and Integration
- Training and Consulting
- Support and Maintenance
- Managed Network Services
- Products
- By End-User
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Government and Defense
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing and Industrial
- Other End-Users
- By Data-Center Type
- Colocation
- Hyperscalers/Cloud Service Providers
- Edge/Micro Data Centers
- By Bandwidth
- Less Than equals to 10 GbE
- 25–40 GbE
- 50–100 GbE
- Greater than 100 GbE
- By Country
- United States
- Canada
- Mexico
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts by building a fact base on data center build activity and network technology direction, then turning it into a practical demand map by country. Sources we relied on include public datasets and references such as U.S. Census Bureau trade statistics, USITC tariff and import data, Statistics Canada releases, and FCC publications on broadband and connectivity trends. We also reviewed standards and technical adoption signals from organizations such as IEEE and IETF, since speeds like 25-40 GbE and 50-100 GbE tend to roll out in recognizable waves.
To translate these signals into value, we used public company filings and investor presentations to understand product mix, revenue splits, and the timing of large refresh cycles. Where coverage needed more structure, we supplemented with paid subscriptions used for company financials and intelligence, patent landscape checks, and shipment-level import and export records to sense-check major supply flows. This list is not exhaustive, and we also used other public and paid sources for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary work was used to confirm how buyers and operators in the region prioritize switching, routing, and optical interconnect upgrades, and to verify what is treated as products versus services in real contract language. We spoke with a mix of data center operators, system integrators, and network specialists across the US, Canada, and Mexico, so the model captures both hyperscale build-outs and colocation-driven expansions, followed by cross-checks on bandwidth transition timing and service attach rates.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 25% | CXOs: 16% |
| Mid tier: 56% | Functional/Unit leaders: 38% |
| Smaller Players: 19% | Managers: 46% |
Market-Sizing & Forecasting
Sizing starts with a top-down reconstruction of the North America spend pool by linking data center capacity additions and refresh cycles to the share of budgets typically directed toward networking. Those totals are then corroborated with selective bottom-up approximations, where sampled vendor revenue exposure, channel checks, and average selling price assumptions are multiplied by estimated volumes for key equipment classes, then adjusted when the two views diverge.
Key inputs in the model include colocation and hyperscaler build activity, measured bandwidth migration (for example, 25-40 GbE moving into 50-100 GbE, followed by links above 100 GbE), the mix shift between products and services, and country-level demand weightings within North America. Service intensity is also tracked since design, integration, monitoring, and lifecycle support can expand faster than hardware during upgrade-heavy years. Forecasting is run using scenario analysis supported by trend smoothing on the historical series, and the scenarios are anchored to interview-based expectations on upgrade timing and supply constraints. Where bottom-up details are missing for smaller buyer groups, gaps are handled through share-based allocation tied to observable indicators like data center type mix and bandwidth adoption pace.
Data Validation & Update Cycle
Outputs are checked in three steps so the final numbers stay practical and explainable. First, we compare results against independent signals such as trade flows for relevant networking equipment categories, disclosed capex direction from major operators, and observed shifts in port-speed adoption. Next, anomalies are reviewed, and if an unexpected jump is found, the assumptions behind pricing, service attachment, or country mix are re-tested, and when needed a follow-up call is triggered.
Before sign-off, the work is reviewed by another analyst to confirm that calculations, currency handling, and time-series logic are consistent across the model. Reports are refreshed annually, with interim updates when material events change demand or pricing, and a final pre-delivery pass is done so clients receive the latest updated view.
黑料不打烊's North America Data Center Networking Market Sizing Compared With Other Published Estimates
Published market values for North America data center networking can look far apart because the scope is not handled the same way, and because pricing and refresh timing are treated differently across models. Differences usually show up when one estimate blends adjacent IT networking spend into the total, or when services are either fully included or mostly ignored.
In our checks, the biggest spread came from whether managed network services and lifecycle support are counted together with Ethernet switching, routing, and optical interconnect revenue, and from how quickly the model steps up average selling prices as links move beyond 100 GbE. That is why the 2025 value of USD 9.8 B is best read with those inclusions made explicit, as done by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 9.8 B (2025) | |
| Regional Consultancy A | USD 26.45 B (2025) | This figure appears to include a wider bundle of data center networking spend by folding in network virtualization and broader software layers, which can lift totals beyond equipment plus directly tied services. |
| Industry Portal B | USD 14.71 B (2025) | This estimate is consistent with a scope that leans toward products and a narrower service definition, and it may also use a more aggressive price curve for high-speed links without the same contract-level service attach checks. |
Taken together, the table suggests that most gaps are caused by scope boundaries around services and software, and by different assumptions on when higher-speed ports become the dominant spend line. By keeping the model tied to observable build activity, bandwidth transitions, and realistic service attachment, we can explain each step and still keep the total repeatable year to year.


Key Questions Answered in the Report
What is the current size of the North America data center networking market?
The market stands at USD 10.42 billion in 2026 and is forecast to climb to USD 14.17 billion by 2031 at a 6.35% CAGR.
Which component segment is growing fastest?
Services, spanning managed, integration and consulting offerings, expand at 10.85% CAGR as enterprises outsource complex AI-era network operations.
Why are 400 G and 800 G Ethernet ports gaining traction?
AI/ML training clusters need massive east-west bandwidth; 400 G/800 G fabrics cut training time and slash congestion, driving broad adoption.
How do power-grid delays affect new data-center builds?
Interconnection queues can prolong energisation to seven years in high-demand US regions, forcing operators to invest in on-site renewables and micro-grids.
Which country is the fastest-growing geography in North America?
Mexico leads with a projected 9.95% CAGR through 2031, driven by nearshoring, cloud investments and strategic locations like Querétaro.
Who are the leading networking vendors?
Cisco retains the largest share, but Arista, Juniper and white-box suppliers such as Celestica are capturing momentum through AI-optimised platforms.
Page last updated on:
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Data Center Security Market Security across all regions, split by security type, offering and facility type.
- Data Center Cooling Market Cooling across the global market, covering cooling technology, cooling component and facility type.
- Mexico Data Center Cooling Market Mexico's cooling, split by cooling technology, type and end-user industry.
- South America Data Center SSD Market SSDs in South America, split by form factor, interface and nand technology.
- Data Center RFID Market Asset tracking across all regions, split by component, tag type and data-center type.



