
New Zealand Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 36.75 Million |
| Market Size (2026) | USD 40.81 Million |
| Market Size (2031) | USD 68.93 Million |
| Growth Rate (2026 - 2031) | 11.05 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
New Zealand Data Center Rack Market Analysis by 黑料不打烊
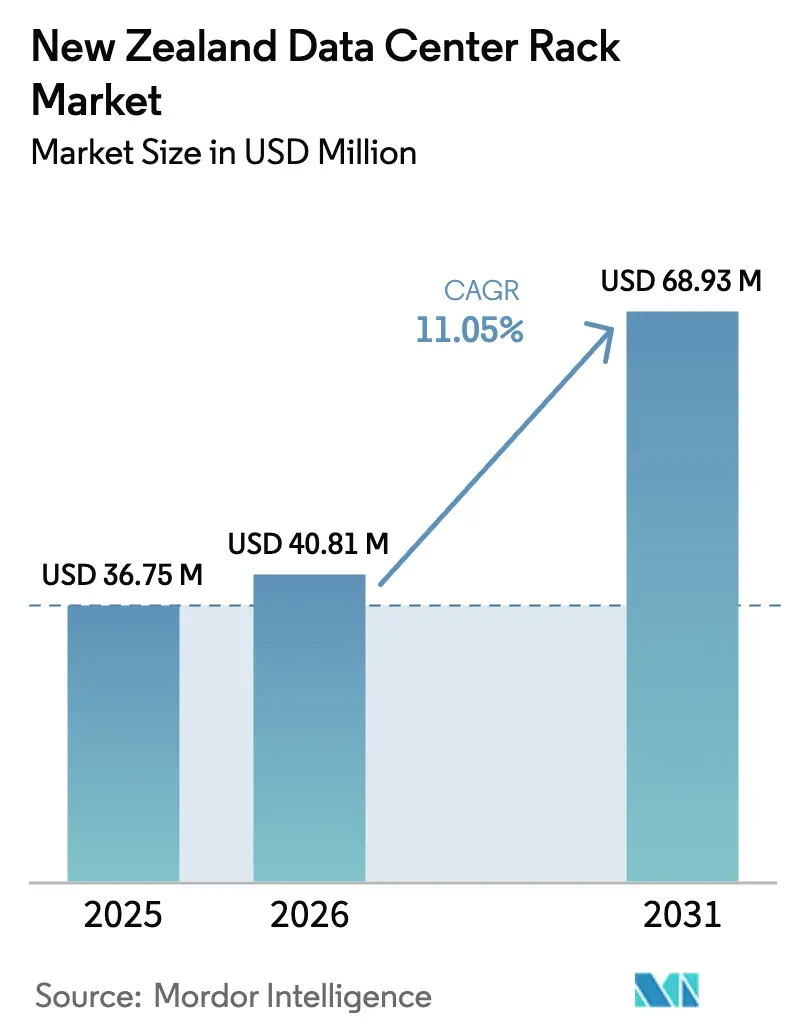
The New Zealand data center rack market size is expected to grow from USD 36.75 million in 2025 to USD 40.81 million in 2026 and is forecast to reach USD 68.93 million by 2031 at 11.05% CAGR over 2026-2031. Heightened hyperscale commitments from Microsoft and AWS, sustained submarine-cable investments, and expanding 5G coverage collectively elevate rack demand. Growth also stems from public-sector projects such as the Government Communications Security Bureau’s sovereign facility, which strengthens data-sovereignty compliance and stimulates procurement of seismic-compliant racks. Meanwhile, nationwide carbon-neutral mandates propel the adoption of energy-efficient cabinet solutions, and renewable power availability enhances the country’s attraction for sustainable data center deployments. Racks that accommodate AI-ready power densities and liquid-cooling loops are becoming mainstream, and operators increasingly specify ruggedized form factors for edge sites serving 5G and remote renewables.
Key Report Takeaways
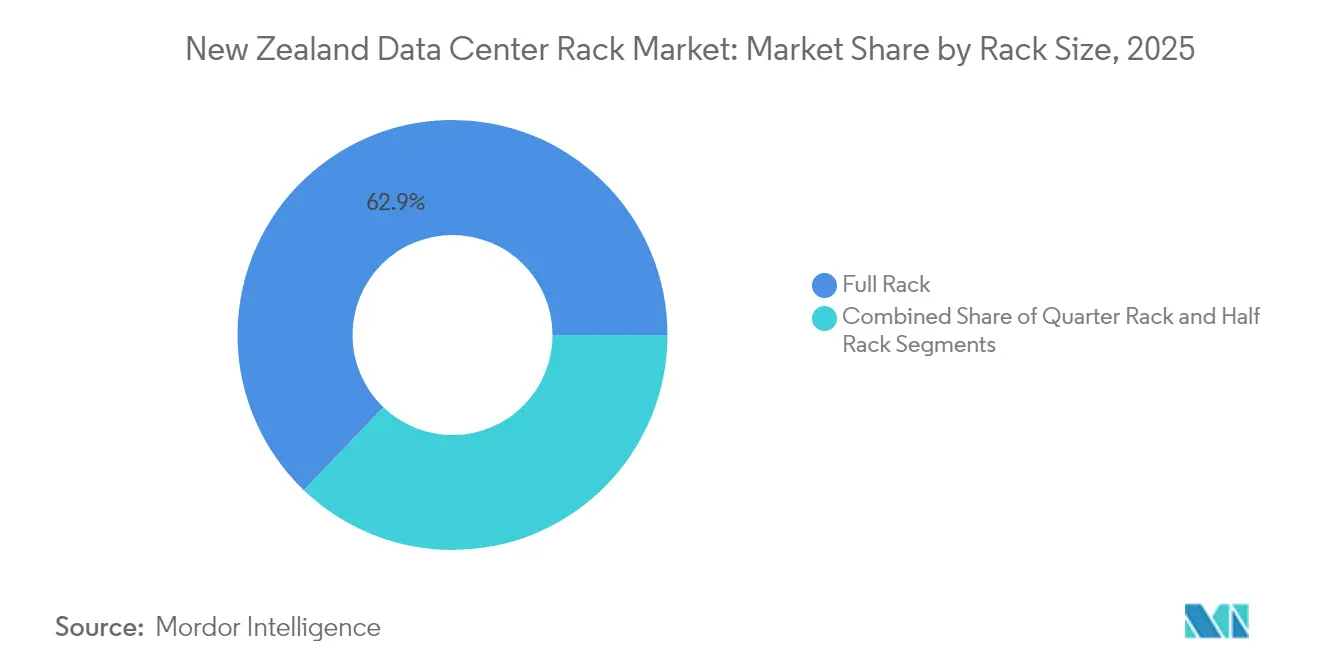
- By rack size, Full Rack solutions commanded 62.85% of New Zealand data center rack market share in 2025, while Quarter Rack deployments trailed but address edge use cases.
- By rack height, 42U maintained 50.65% share of New Zealand data center rack market size in 2025; 48U units are growing fastest at a 12.1% CAGR to 2031.
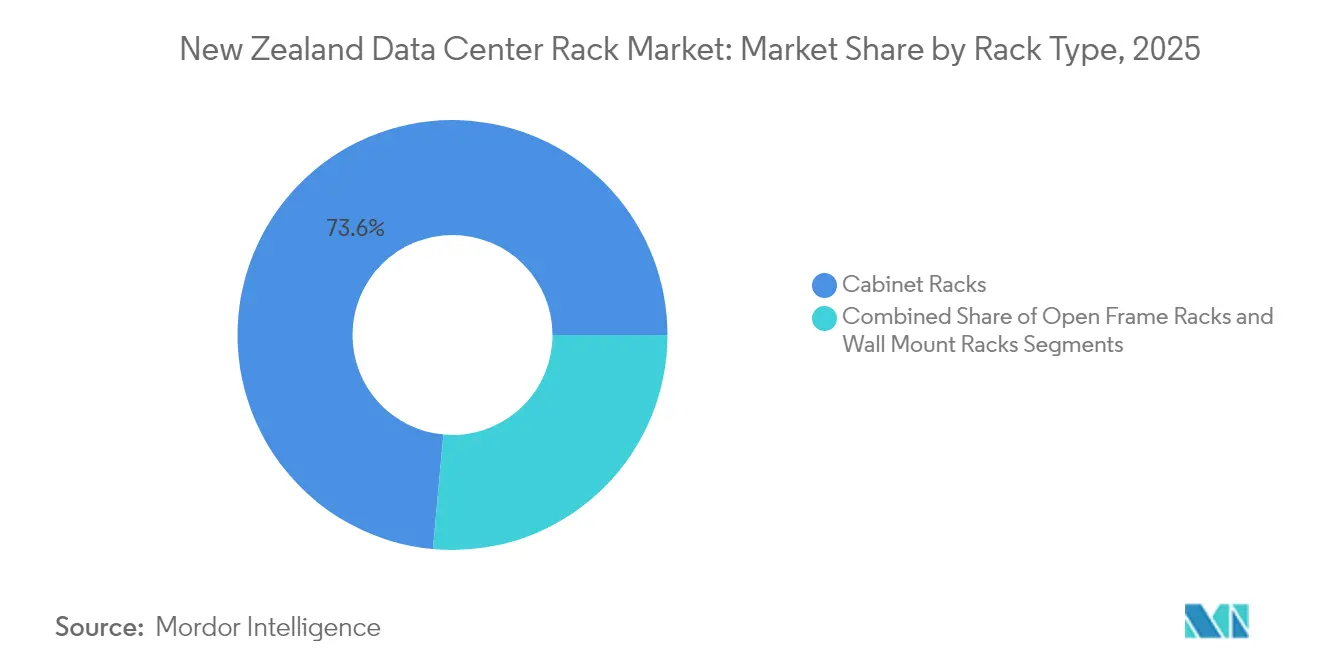
- By rack type, Cabinet formats led with a 73.55% revenue share in 2025, and their category is forecast to expand at 12.84% CAGR through 2031.
- By data-center type, Colocation facilities held 53.85% of New Zealand data center rack market size in 2025, but Hyperscale and CSP sites post the highest 13.02% CAGR to 2031.
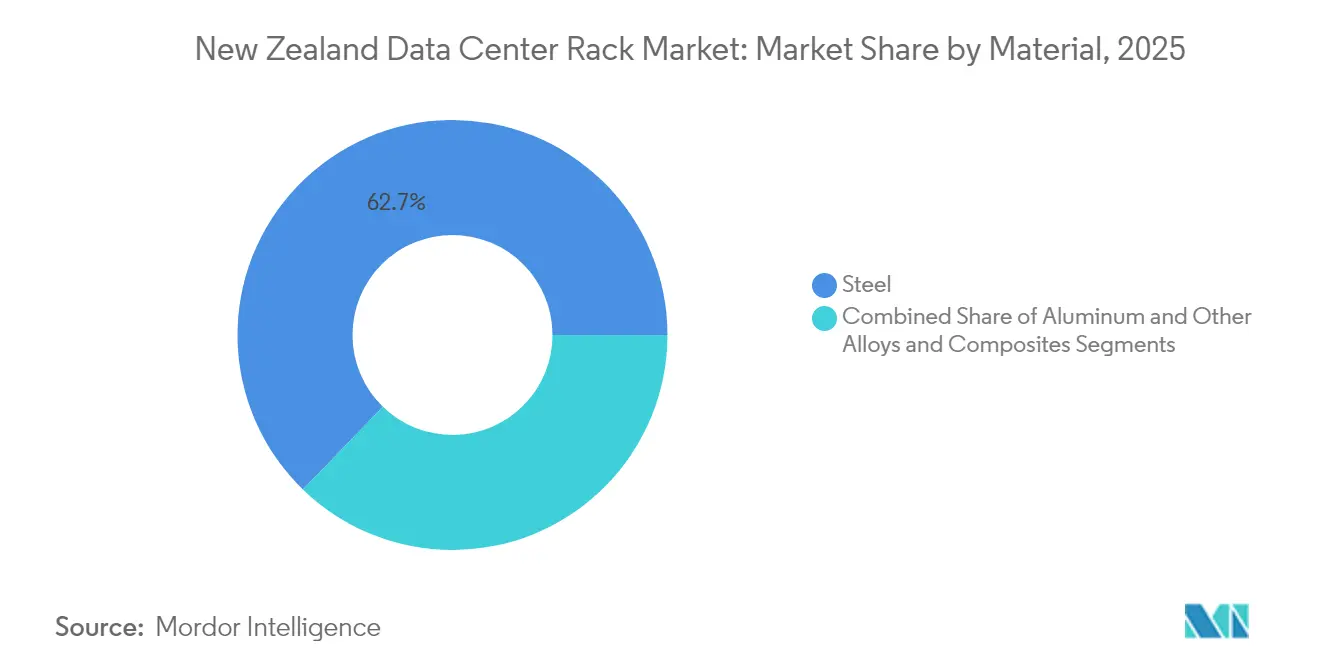
- By material, Steel accounted for 62.75% share in 2025, whereas Aluminum racks exhibit an 11.06% CAGR due to weight and thermal benefits through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
New Zealand Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising dominance of 5G networks | +2.1% | National, with early gains in Auckland, Wellington, Christchurch | Medium term (2-4 years) |
| Expansion of fibre-optic backbone connectivity | +1.8% | National, concentrated in urban centers and submarine landing points | Long term (≥ 4 years) |
| Accelerating cloud & hyperscale investments | +2.7% | Auckland-centric, expanding to regional centers | Short term (≤ 2 years) |
| Government "Zero-Carbon 2050" push for energy-efficient racks | +1.4% | National, with South Island renewable energy advantages | Long term (≥ 4 years) |
| Edge-computing demand from remote renewables and IoT sites | +1.6% | Rural and remote areas, renewable energy sites | Medium term (2-4 years) |
| New international submarine-cable landings spurring DC build-outs | +2.2% | Coastal landing points, Auckland, Wellington | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Rising Dominance of 5G Networks
Nationwide 5G rollout accelerates distributed computing, requiring compact racks for cell-site edge nodes. Spark’s Nokia partnership across 700 towers exemplifies this shift, while Auckland Airport’s private 5G showcases ultra-low-latency use cases.[1]Reseller News Editors, “Spark selects Nokia for 5G network expansion,” reseller.co.nzSpectrum allocations in the 3.5 GHz and upcoming 24-30 GHz bands extend coverage into rural zones, prompting demand for weather-resistant enclosures. Operators now prefer factory-sealed cabinet designs that support redundant power feeds and filtered ventilation to withstand remote environments. This evolution differentiates the New Zealand data center rack market from traditional centralized models and sustains a premium for ruggedized solutions.
Expansion of Fibre-Optic Backbone Connectivity
The Southern Cross NEXT and forthcoming Te Waipounamu cables amplify international capacity and lower latency, spurring rack upgrades in coastal data centers. Direct South Island–Australia connectivity fosters regional hosting, encouraging taller racks that pack more servers per square meter to monetize new bandwidth paths. Enhanced redundancy positions New Zealand as an Asia-Pacific interconnect node, bolstering investor confidence in high-density deployments. Data center operators respond with 48U cabinets that handle hotter exhaust temperatures yet maintain seismic compliance, securing a scalable footprint for emerging AI workloads.
Accelerating Cloud and Hyperscale Investments
Microsoft’s hyperscale region and AWS’s USD 7.5 billion programme compress build timelines, pushing standardization on 42U and 48U cabinets with pre-installed busbars and liquid-ready manifolds.[2]National Cyber Security Centre, “Annual Cyber Threat Report 2023,” ncsc.govt.nzLocal telco Spark counters with a NZD 15 million edge facility, signalling multicloud ecosystems that blend centralized and regional capacity. Intensifying competition lifts order volumes for full-depth steel racks able to house multi-node GPU clusters. Deloitte estimates that data centers could consume 7% of national electricity by 2030, reinforcing the preference for racks that integrate granular power monitoring and containment accessories to sustain PUE targets.
Government “Zero-Carbon 2050” Push for Energy-Efficient Racks
The Carbon-Neutral Government Programme forces agencies to cut emissions, driving procurement of cabinets compatible with liquid cooling and renewable integrations.[3] Operators now specify aluminum or low-carbon steel frames to reduce embodied emissions. Vendors differentiate through in-rack heat-recovery coils and sensor arrays that feed ESG dashboards, a capability prized by hyperscalers under 24×7 carbon-free energy commitments. South Island sites leveraging 100% hydro and wind supply gain visibility among international investors, amplifying regional diversification.
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating cybersecurity & ransomware risks | -1.8% | National, with higher impact on government and financial sectors | Short term (≤ 2 years) |
| Shortage of local data-center skillsets | -1.4% | National, acute in Auckland and Wellington | Medium term (2-4 years) |
| High national electricity tariffs | -1.1% | National, with regional variations | Long term (≥ 4 years) |
| Seismic-compliance cost for rack installations in quake zones | -0.9% | High and medium seismic risk areas, primarily North Island | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Escalating Cybersecurity & Ransomware Risks
Three hundred-plus critical incidents in 2022/23 highlight rising cyber exposure. Higher security expectations translate into closed-cabinet preferences with locking side panels, tamper sensors and segmented cable troughs.Colocation tenants demand multi-factor cage access and camera-ready enclosures, elevating specification costs. While new tools like the Malware Free Networks service mitigate threats, insurance underwriters now scrutinize physical security ratings, discouraging open-frame rack adoption in sensitive workloads and moderating market expansion.
Shortage of Local Data-Center Skillsets
New Zealand needs 4,000-5,000 additional technology professionals annually, but graduations lag requirements. Scarce expertise in liquid cooling, high-density power wiring and seismic anchoring forces operators to import labour or prolong deployment cycles. Smaller enterprises hesitate to refresh legacy racks, slowing addressable demand. Training schemes such as Mission Ready help, yet upskilling timelines extend beyond immediate project horizons, constraining near-term shipment growth in the New Zealand data center rack market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Hyperscale Standardization Anchors Full-Rack Supremacy
Full Rack cabinets dominated at 62.85% New Zealand data center rack market share in 2025, reflecting hyperscalers’ preference for 600 mm×1,200 mm 42U footprints that streamline supply chains. Quarter and Half Racks cater to edge and enterprise niches where space, power, or budget restrict full-height units. Over 2026-2031, Full Rack demand scales in tandem with the overall New Zealand data center rack market, projected at an 11.34% clip as cloud tenants consolidate workloads into denser cabinets.
Operators also explore nine-foot (48U) variants when ceiling height permits. These units improve kW-per-footprint metrics, reduce white-space leasing costs, and align with AI training cluster designs. Quarter Rack deployments remain pivotal for 5G micro-edge sites and IoT gateways situated at base stations or renewable plants, though their aggregate contribution to the New Zealand data center rack market size stays modest. Vendors position modular accessories—busway extensions, blanking panels, cable lacing bars—to offer growth paths within the same footprint.


By Rack Height: 48U Configurations Lead Density Drive
The 42U format held 50.65% of New Zealand data center rack market size in 2025 due to entrenched telecom standards. Yet 48U units deliver the highest 12.1% CAGR through 2031, feeding appetites for GPU-dense nodes requiring vertically stacked servers. Taller frames also amortize floor costs as land values in Auckland rise.
Engineering consultancies adapt anchoring kits to meet NZS 4219 seismic guidelines, ensuring stability without footprint penalties. Meanwhile, custom ≥52U racks target experimental liquid-immersion pods or extra-high OCP sleds. Such formats introduce new thermal gradients, prompting active rear-door heat exchangers and chilled-water loop integration that elevate procurement value per rack in the New Zealand data center rack market.
By Rack Type: Cabinets Strengthen Security and Thermal Control
Cabinet solutions captured a 73.55% share in 2025 and are forecast for 12.84% CAGR, buoyed by surge in multi-tenant footprints where airflow containment and access control are vital. Closed designs enable cold-aisle isolation, door-mounted sensors and side-panel locks that satisfy PSA and ISO 27001 audits. Open-frame racks persist in non-production labs and high-airflow HPC pods but face security caveats.
Wall-mount racks underpin rural edge nodes and telco roadside huts, integrating shallow depths and convection vents. Cabinet vendors now embed brush strips, high-CFM top fans and micro-PDU rails that support AI-grade loads. Immersion-ready versions arrive pre-coated for dielectric fluid tolerance, preserving structural rigidity across temperature swings crucial to New Zealand’s seismic zones.
By Data Center Type: Colocation Holds Ground While Hyperscale Surges
Colocation operators maintained 53.85% of New Zealand data center rack market size in 2025, supplying compliance-ready floorspace to banks and government agencies. Hyperscalers lead future growth at 13.02% CAGR as Microsoft and AWS complete Auckland campuses that each exceed 30 MW phases. Their reference designs specify uniform full-rack rows, centralized busway channels, and liquid-ready manifolds that elevate dollar-value per unit sold.
Edge and enterprise sites address latency-sensitive workloads in agriculture, utilities and aviation. Telcos deploy micro-edge huts using 12-42U hybrid racks close to 5G antennas. This diversity broadens total addressable shipments yet amplifies customization needs across the New Zealand data center rack market.
By Material: Steel Remains Mainstay as Aluminum Gains Momentum
Structural steel frames dominated at 62.75% share in 2025, valued for load capacity and familiar seismic behavior. Yet aluminum units chart an 11.06% CAGR, propelled by South Island operators that prize low weight and corrosion resistance. Fabricators introduce hybrid SM45 steels with Eco-PZ coatings, cutting embodied CO?, aligning with Zero-Carbon targets without sacrificing tensile strength.
Innovations such as Tate’s low-carbon alloy tray reduce rack mass by 30%, easing installation in retrofitted floors. TimberMod concepts integrate cross-laminated timber containment skeletons around steel cores, marrying sustainability with rigidity. Composite FRP enclosures emerge for coastal stations exposed to salt spray, illustrating expanding material palettes in the New Zealand data center rack industry.
Geography Analysis
The Auckland metropolitan area commands the majority of deployments owing to its concentration of submarine cables and hyperscale campuses, securing more than half of New Zealand data center rack market size in 2025 . Dense cloud footprints stimulate demand for 42U and 48U cabinets rated above 10 kW per rack. International interconnect exchanges anchored in Auckland further incentivize premium power-per-footprint solutions that maximize return on constrained downtown plots.
Wellington’s government agencies generate steady cabinet orders emphasizing security accreditation and seismic anchoring, although some public-sector workloads are migrating north to the new GCSB complex in Whenuapai, sustaining cabinet refresh cycles. Christchurch and Hamilton support regional enterprise nodes and research institutes, favoring modest-density racks outfitted with redundant PDUs for high availability.
South Island regions such as Invercargill present emerging clusters powered by 100% hydro and wind. The Te Waipounamu cable’s 120 Tbps capacity will unlock direct Australia routes, attracting operators pursuing carbon-free SLAs. Cooler ambient temperatures permit free-air cooling for nine months of the year, trimming OPEX and heightening appeal of taller 48U frames. Queenstown and Dunedin telecom shelters add low-touch rugged racks tied to renewable micro-grids, broadening geographic diversification within the New Zealand data center rack market.
Regulatory Landscape
New Zealand public-sector hosting and security requirements shape rack specifications through controls linked to the New Zealand Information Security Manual (NZISM), maintained by the Government Communications Security Bureau (GCSB), and the Protective Security Requirements (PSR). Under the government Cloud First policy, agencies are directed toward public cloud unless exceptions apply, which concentrates demand for compliant colocation and cloud-adjacent halls that prioritize closed cabinets, physical access controls, and auditable layouts.
The Department of Internal Affairs (via the Government Chief Digital Officer) also runs the Public Cloud Data Centre Certification (PCDCC), an optional certification for onshore facilities assessed against PSR and NZISM expectations. Guidance on offshore storage jurisdictional risk and the handling of higher-sensitivity classifications reinforce data-sovereignty and assurance-led procurement, which increases the need for secure, standardized cabinet deployments and site designs that can pass government assurance reviews.
Competitive Landscape
Global infrastructure majors front-load the supply chain, but local integrators tune solutions for seismic and regulatory nuances. Schneider Electric’s Galaxy VXL UPS delivering 1.25 MW per frame complements its EcoStruxure-ready cabinets and positions the firm for AI data halls . Vertiv’s power and cooling portfolio addresses 10-140 kW per rack scenarios, mirroring rack power densities forecast to reach 1,000 kW in niche HPC pods. Eaton’s Fibrebond acquisition bolsters prefabricated modular data halls that embed steel or aluminum racks pre-wired with PV-ready switchboards.
nVent’s edgeNRG range services telco roadside shelters and offshore renewables, featuring NEMA 4-rated enclosures capable of remote DCIM. Rittal expands colocation-optimized TS IT variants with automatic airflow shutters and security bars. Dell, HPE and Supermicro cooperate with rack vendors on turnkey AI clusters, embedding NVIDIA Blackwell and GB200 GPU nodes that draw up to 80 kW per cabinet.
New Zealand Data Center Rack Industry Leaders
Schneider Electric SE
Eaton Corporation
Rittal GmbH & Co.KG
Hewlett Packard Enterprise
Vertiv Group Corp.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Rack demand has visible whitespace in build-outs and retrofits tied to new capacity coming online and facilities moving from concept to construction. DataCentres New Zealand cited 56 operational data centers nationwide as of May 2026, with a further 20 planned or under construction, supporting opportunities for suppliers that can provide repeatable cabinet lines and accessories aligned to colocation and cloud operator standards.
Government cloud adoption mechanisms also create room for rack vendors and integrators that can map physical infrastructure to assurance expectations. The Cloud First policy, the PCDCC (onshore) certification pathway, and jurisdictional risk assessments collectively favor solutions that simplify PSR/NZISM-aligned deployments, including lockable cabinets, segmentation options for multi-tenant floors, and structured cable and power distribution that improves auditability. Geographic diversification is another angle, with industry focus extending beyond Auckland toward South Island development corridors such as around Invercargill, where renewable generation availability supports sustainability-led facility positioning and related rack orders for energy-aware, liquid-cooling-ready rows.
Recent Industry Developments
- July 2026: TenPeaks (formerly Spark NZ data center unit) completed the sale of its data center business to Pacific Equity Partners, with TenPeaks planning an NZ$3 billion investment to expand its portfolio of 11 existing facilities. The deal signals market consolidation in the New Zealand data center sector as capital reshapes asset ownership. The planned investment broadens TenPeaks' footprint, enabling scale expansion to support growing demand from hyperscale and enterprise customers.
- July 2026: Datacom acquired a 5,200 sqm, 8MW data center in East Tamaki, Auckland from T4. The acquisition expands Datacom’s footprint in Auckland and increases capacity for high-density workloads. This move strengthens Datacom’s ability to serve hyperscale and enterprise customers across the region.
- May 2026: Chorus completed a 23-rack capacity expansion at its Mount Eden colocation data center in Auckland. The capacity addition supports rising demand at a key NZ site and enhances edge and urban-colocation deployment potential. The expansion aligns with scale-up needs for local workloads and proximity-based services.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market covers revenue generated from selling data center racks installed in New Zealand, including cabinets and frames used to house IT and network equipment in commercial, enterprise, and edge sites.
Scope exclusions: Rack-related services (such as installation labor, maintenance contracts, and facility operations) are not counted as market revenue.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
We start by mapping how many racks are being installed and refreshed across New Zealand, and then we tie that to realistic price levels for common rack formats. Public sources help us build the base demand signals, such as national statistics releases, customs trade summaries for relevant metal products, and electricity and energy outlooks that indicate data center expansion pressure.
We also refer to sources such as Stats NZ, New Zealand Customs Service publications, the Ministry of Business, Innovation and Employment (MBIE), the Electricity Authority, and standards guidance used in data center design (for example, cabinet dimensions and safety-related practices). These are then complemented with company filings, investor presentations, industry association updates, and a paid subscription that supports company financials and patent lookups to confirm product positioning and shipment directionality. The sources listed here are illustrative only, and many other public references were checked to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Primary work is used to convert the desk signals into usable inputs, especially around what share of projects are new builds versus expansions, what rack types are actually being specified, and how pricing moves with power density and customization. We speak with a mix of operators, contractors, distributors, and rack-focused product specialists, and we cover demand across the main data center hubs plus smaller regional deployments so the model does not overfit to one city.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 16% |
| Mid tier: 54% | Functional/Unit leaders: 29% |
| Smaller Players: 19% | Managers: 55% |
Market-Sizing & Forecasting
A top-down approach is used first, where data center build activity and expansion signals are translated into a rack demand pool, which is then valued using typical rack pricing bands observed in New Zealand. To keep it practical, we rely on a small set of traceable inputs, such as planned white space additions, proxy indicators for rack density by facility type, typical refresh cycles for cabinets, the mix of enclosed versus open frame racks, and pricing differences tied to height, material choice, and seismic requirements.
Once the first pass is built, results are checked using selective bottom-up approximations, such as sampled average selling price times estimated unit shipments from channel feedback, and sanity checks against the scale of known data center projects. Where the bottom-up view is incomplete, gaps are handled by applying conservative penetration factors by facility type, and then rechecking the totals with interview feedback.
For forecasting, we apply scenario analysis supported by short time-series smoothing, since project pipelines can be lumpy in a smaller country market. Assumptions on new capacity additions, timing of builds, and price drift are refreshed using what participants share about procurement cycles and what tends to change first when timelines slip.
Data Validation & Update Cycle
Before sign-off, we triangulate the modeled outcome against independent signals, such as construction pipeline cues, import movement directionality, and operator commentary on capacity utilization and expansion intent. When a value looks off, it is traced back to one of the drivers (like rack density, pricing, or the new build share), and then the assumption is revisited and corrected in the model.
A second analyst review is completed to check calculations, year alignment, and currency handling, followed by targeted re-contacts if a key assumption is still uncertain. Reports are refreshed annually, and interim updates are made when material events occur, such as major project announcements or a step-change in procurement patterns. Right before delivery, we perform a final update pass so clients receive the most current view possible.
黑料不打烊's New Zealand Data Center Rack Market Estimate Compared With Other Published Estimates
Published market values for data center racks in New Zealand can differ because authors do not always count the same products, they may mix services with hardware, or they may apply different build-timing assumptions for a small set of large projects.
Key gaps usually come from whether estimates are built from racks as a physical unit demand pool versus being inferred from broader data center spending, and from how average selling prices are treated when rack specifications shift toward higher density. By tracking project pipeline timing, rack density assumptions, and price bands, 黑料不打烊 keeps the estimate centered on rack hardware demand and avoids pulling in adjacent facility items that can inflate totals.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 36.75 M (2025) | |
| Trade Journal A | USD 91.00 M (2023) | Often reports colocation revenue and then converts it into implied rack value, which can blend services and occupancy effects into what should be a hardware-only number. |
| Industry Blog B | USD 5.83 B (2025) | Likely uses a broad data center investment lens and labels it as a rack market, which pulls in construction and electrical infrastructure spending that is not rack revenue. |
The spread in the table mainly reflects scope boundaries and what the number is trying to represent, whether it is rack hardware sales, colocation revenue, or total facility investment. Our approach stays traceable to install and refresh activity and to realistic rack pricing, which makes it easier for buyers to reuse the steps and adjust inputs when project timing changes.


Key Questions Answered in the Report
What is the current value of the New Zealand data center rack market?
The market stands at USD 40.81 million in 2026 and is on track to reach USD 68.93 million by 2031.
Which rack height is growing fastest in New Zealand?
48U cabinets register the highest 12.1% CAGR through 2031 as operators seek higher server density.
Why is Auckland the primary hub for rack demand?
Auckland hosts most submarine cable landings and hyperscale campuses, driving concentration of high-density cabinet deployments.
What role does sustainability play in rack purchasing decisions?
Government Zero-Carbon 2050 goals and abundant renewable power spur demand for low-carbon materials and energy-efficient, liquid-cooling-ready racks.
Page last updated on:
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- New Zealand Data Center Cooling Market New Zealand's cooling, split by facility type, tier and cooling technology.
- Chile Hyperscale Data Center Market Hyperscale sites in Chile, split by facility type, service type and end user.
- Austria Data Center Networking Market Networking in Austria, split by component.
- New Zealand Data Center Physical Security Market New Zealand physical security, split by solution type, service type and end user.
- Vietnam Data Center Server Market Servers demand across Vietnam, covering data-center tier, form factor and application / workload.
- Vietnam Data Center Storage Market Storage in Vietnam, split by storage technology, storage type and facility type.
- Canada Hyperscale Data Center Market Hyperscale sites demand across Canada, covering facility type, component and tier.
- Saudi Arabia Hyperscale Data Center Market Hyperscale sites demand across Saudi Arabia, covering facility type, component and tier.



