
Nigeria Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
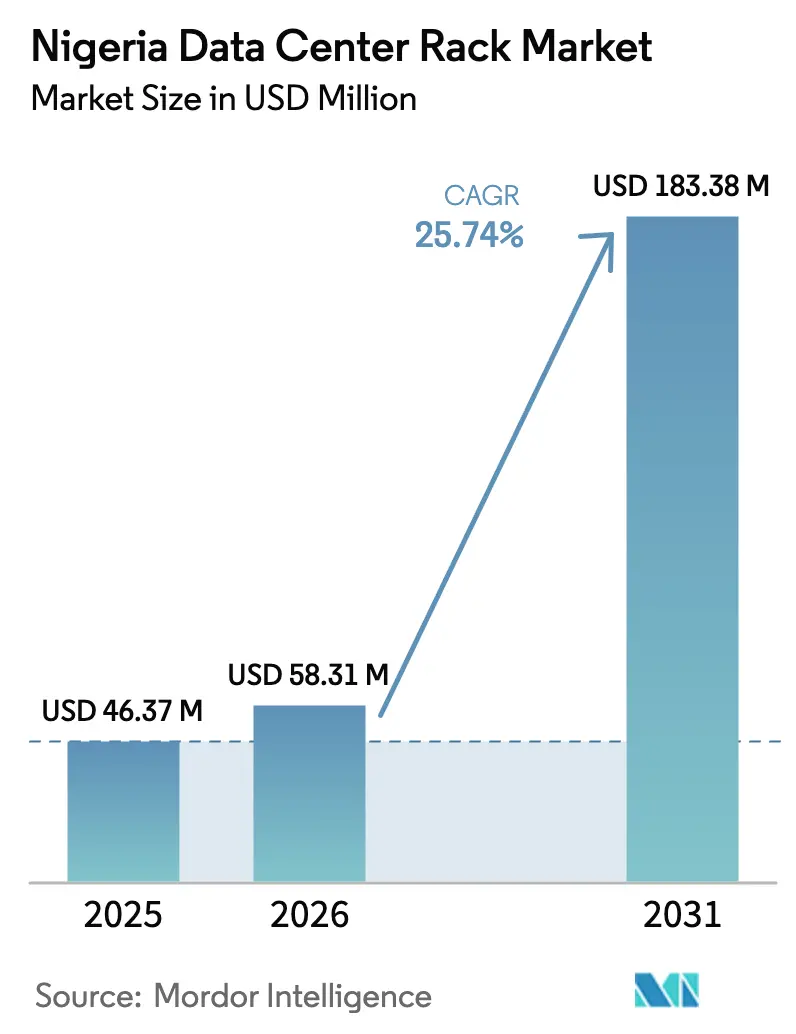
| Base Year Market Size (2025) | USD 46.37 Million |
| Market Size (2026) | USD 58.31 Million |
| Market Size (2031) | USD 183.38 Million |
| Growth Rate (2026 - 2031) | 25.74 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Nigeria Data Center Rack Market Analysis by 黑料不打烊
The Nigeria data center rack market size is expected to grow from USD 46.37 million in 2025 to USD 58.31 million in 2026 and is forecast to reach USD 183.38 million by 2031 at 25.74% CAGR over 2026-2031. Momentum comes from government–mandated data-localization rules, explosive fintech adoption, and more than USD 20 billion of subsea-cable investment that has transformed Lagos into West Africa’s primary interconnection hub. Rapid hyperscale build-outs, a shift toward taller 48U racks, and rising use of aluminum frames to reduce floor-loading are reshaping capital-spending priorities. Currency depreciation is pushing operators toward naira-denominated cloud services, while diesel-to-solar micro-grids are gaining favor as a hedge against persistent grid failures. International entrants such as Equinix, Vantage, and Huawei Cloud are scaling local footprints to comply with data-sovereignty rules, but indigenous suppliers benefit from NITDA’s local-content thresholds and tax incentives that favor domestically assembled rack systems.
Key Report Takeaways
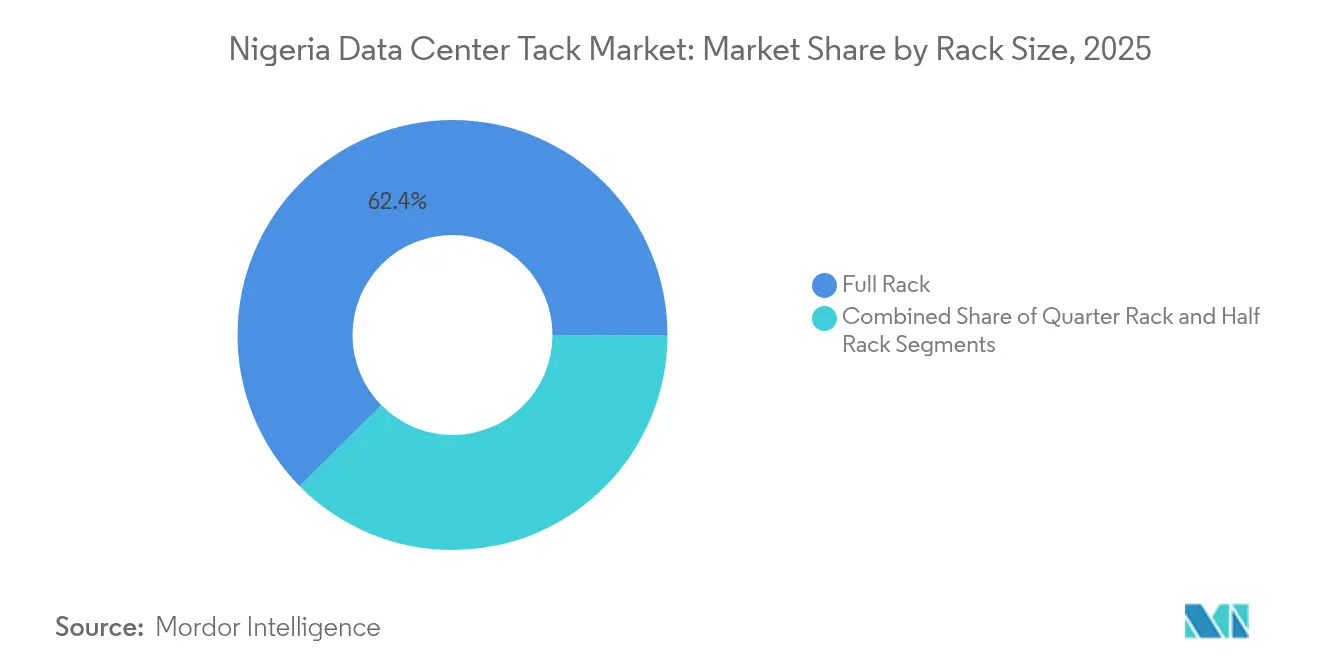
- By rack size, full racks captured 62.42% of Nigeria data center rack market share in 2025; quarter and half racks trail far behind while full racks are expanding at a 27.26% CAGR through 2031.
- By rack height, 42U units held 50.55% share of the Nigeria data center rack market in 2025; 48U formats deliver the fastest 26.88% CAGR to 2031.
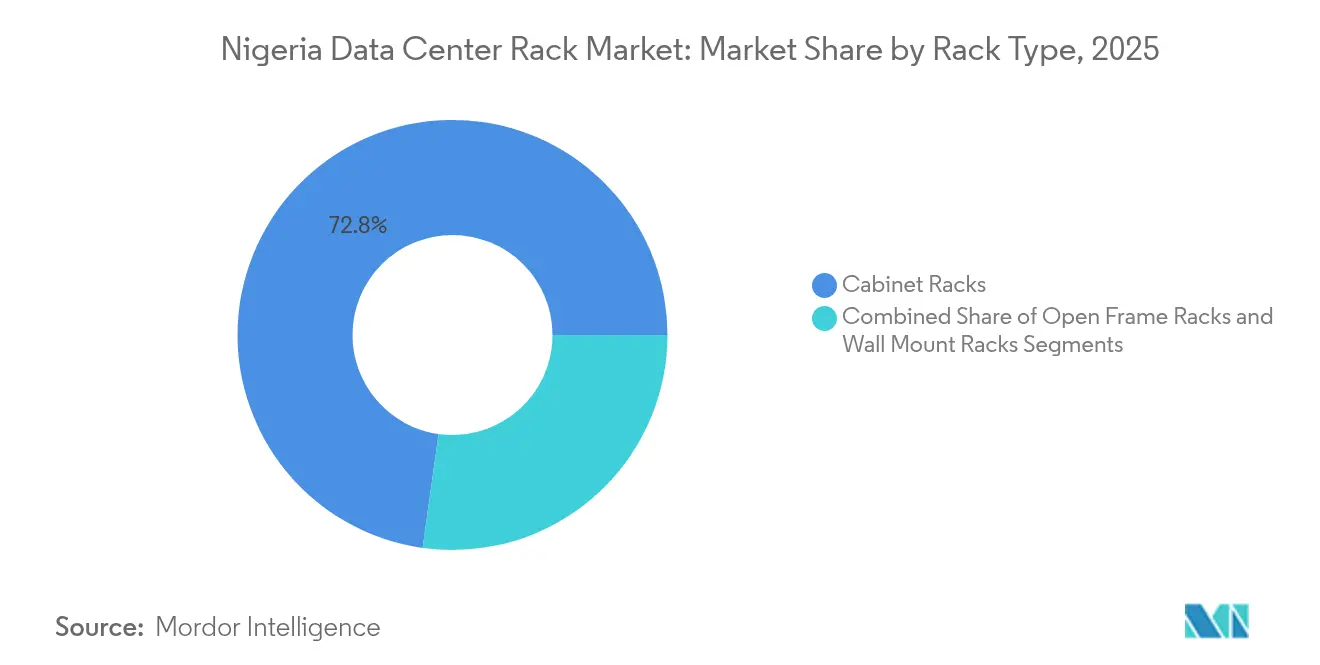
- By rack type, cabinet systems controlled 72.78% share of the Nigeria data center rack market in 2025, with enclosed solutions growing at 26.21% CAGR as security standards tighten.
- By data-center type, colocation providers led with 51.64% Nigeria data center rack market size in 2025, while hyperscale deployments post the strongest 27.44% CAGR.
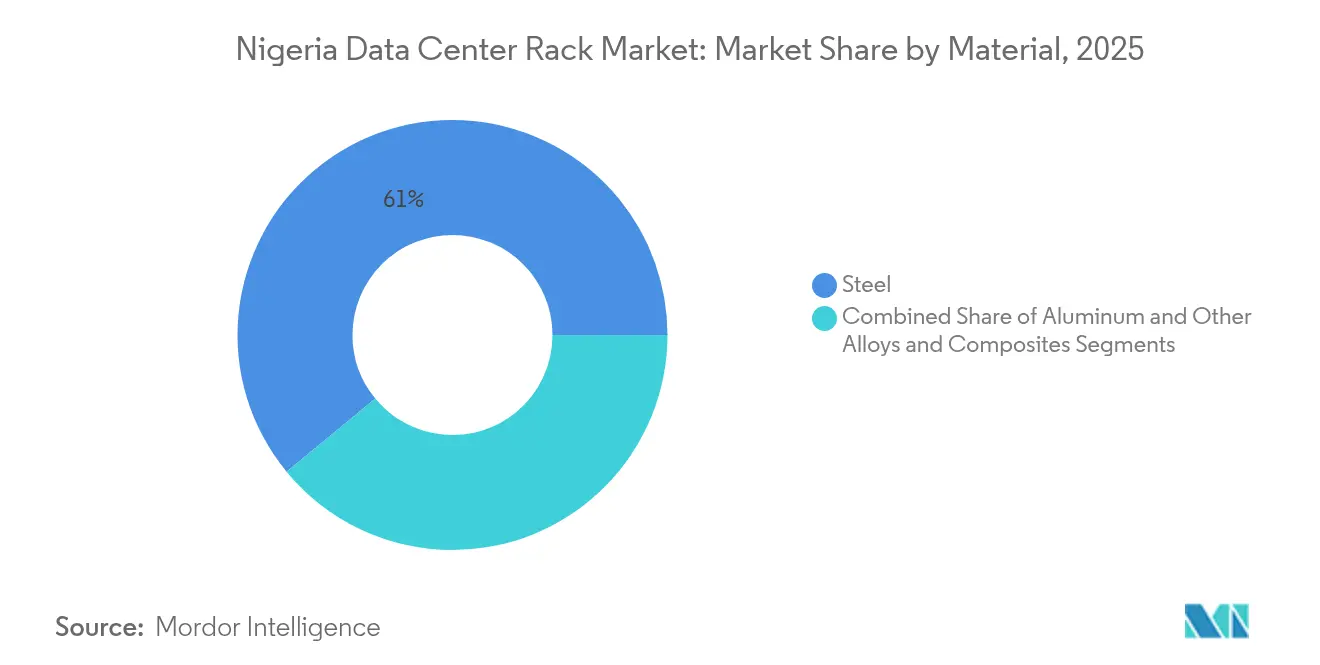
- By material, steel frames dominated 60.96% of Nigeria data center rack market size in 2025; aluminum alternatives are accelerating at 26.39% CAGR on weight-optimization economics.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Nigeria Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Accelerated cloud-migration by BFSI & telcos | +6.8% | Lagos and Abuja | Medium term (2-4 years) |
| Local-content hosting mandates | +5.2% | National (NITDA-enforced) | Long term (≥ 4 years) |
| Surge in subsea-cable landings | +4.1% | Lagos, spillover South-South | Short term (≤ 2 years) |
| Hyperscale rack demand from fintech/AI start-ups | +3.9% | Lagos, Abuja, Port Harcourt | Medium term (2-4 years) |
| Diesel-to-solar micro-grid retrofits | +2.8% | Northern states, national rollout | Long term (≥ 4 years) |
| Naira-denominated local-cloud pricing | +2.1% | National (SME focus) | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Accelerated cloud-migration by BFSI & telcos
Banks and mobile-money operators are lifting compute density as they pivot to cloud-native platforms for real-time payments, fraud analytics, and 5G-enabled edge services. The Central Bank of Nigeria has endorsed cloud adoption for Tier-1 banks, prompting United Bank for Africa to sign a USD 3 million infrastructure contract with Huawei Cloud.[1]Central Bank of Nigeria, “Circular on Cloud Services for Banking,” cbn.gov.ngTelecom groups upgrading to standalone 5G also require high-capacity racks to support network-slicing cores hosted in carrier-neutral sites. Full-rack demand rises accordingly, pushing the Nigeria data center rack market toward hyperscale-grade floor designs that can host 15 kW per cabinet on average.
Local-content hosting mandates
NITDA’s Guidelines for Nigerian Content in ICT and the 2023 Data Protection Act oblige public-sector bodies and regulated industries to process data onshore, fueling captive demand for domestic floor space. Foreign cloud providers must partner, acquire, or build local facilities, often procuring indigenously assembled steel racks to satisfy sourcing rules. This framework insulates the Nigeria data center rack market from offshore competition and lengthens equipment replacement cycles, increasing the addressable base for local manufacturers.
Surge in subsea-cable landings boosting Lagos connectivity
The landings of the 2Africa and Equiano systems have quadrupled international bandwidth, slicing latency between Lagos and Europe to under 60 ms. Improved backhaul economics attract hyperscale cloud nodes, which prefer taller 48U racks to maximize compute per square foot. While Lagos enjoys a connectivity dividend, worries persist that roadworks on the coastal highway could jeopardize cable routes, incentivizing operators to diversify inter-city fiber loops and invest in redundant cabinet-level power isolation.
Hyperscale-ready rack demand from fintech/AI start-ups
Flutterwave’s daily 500,000-transaction load and Opay’s latency-reduction deal with Huawei Cloud exemplify a surge in AI-augmented fintech services that demand GPU-optimized cabinets.[2]Flutterwave Corp., “Processing Milestones and Infrastructure Footprint,” flutterwave.comDomestic cloud providers respond with naira-priced offerings that shelter customers from foreign-exchange swings. GPU clusters require 7 kW–20 kW per rack, accelerating aluminum adoption for thermal performance and weight savings inside the Nigeria data center rack market.
Restraints Impact Analysis*
| Restraint | (~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Chronic grid unreliability & diesel costs | -8.2% | National; acute in Northern states | Short term (≤ 2 years) |
| Shortage of rack-qualified engineers | -4.7% | Lagos and Abuja | Medium term (2-4 years) |
| Currency-linked spike in rack import prices | -3.1% | Nationwide | Short term (≤ 2 years) |
| Rising fire-safety insurance premiums | -1.8% | Primarily Lagos, spreading to other metros | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Chronic grid unreliability and soaring diesel costs
Nigeria suffered multiple nationwide blackouts during 2024 and early 2025, forcing operators to run diesel gensets for as much as 14 hours daily. Fuel prices rose sharply after subsidy removal, lifting OPEX for 1 MW sites by up to USD 1 million annually. Operators now deploy solar-hybrid micro-grids and lithium-ion storage, trimming diesel runtime by 26% on pilot projects led by Daystar Power.[3]Daystar Power, “Hybrid Solar Solutions Reduce Diesel Use by 26%,” daystar-power.comYet intermittent renewables complicate rack cooling, reinforcing demand for fully enclosed cabinets with aisle containment to maintain ASHRAE Class A1 conditions.
Shortage of rack-qualified data-center engineers
The rapid acceleration of the Nigeria data center rack market has outstripped the pipeline of Uptime-certified technicians. Microsoft’s 2024 closure of a small Lagos facility, partly blamed on staffing constraints, underscores the gap. Government initiatives such as the 3MTT program aim to certify 3 million technologists by 2027, but rack installation, thermal-mapping, and busbar trunking skills remain in short supply, lengthening commissioning lead times and capping expansion velocity.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full rack adoption anchors hyperscale builds
Full racks secured 62.42% Nigeria data center rack market share in 2025 and are expanding at a 27.26% CAGR as hyperscale tenants standardize on 42U-48U, 15 kW cabinets to consolidate compute floors. Equinix’s Lagos campus exemplifies this preference, leasing only full cabinets to multinational clients in order to enforce uniform power-delivery strips and structured cabling. Quarter and half racks remain options for SMEs, but strict local-content laws that anchor enterprise data onshore create incentives for banks and e-commerce platforms to migrate whole workload clusters, elevating average rack utilization above 80%.
The efficiency edge comes from economies of scale in cooling and PDUs: operators can deploy shared CRAH units across contiguous rows while retaining customer segregation via smart-lock doors. Large cabinets also allow weight even-loading, reducing tile stress in older data rooms upgraded from Tier II to Tier III. As datacenter corridors migrate to hot-aisle containment, bigger racks improve air-velocity patterns and facilitate rear-door heat exchangers, making full cabinets a long-term staple in the Nigeria data center rack market.


By Rack Height: 48U towers maximize density under power caps
While 42U remains the dominant form factor with 50.55% share, 48U units are climbing at a 26.88% CAGR as operators stretch vertical real estate without enlarging white-space footprints. The Nigeria data center rack market size for 48U units is forecast to pass USD 36.2 million by 2031, capturing workloads that demand GPU accelerators and high-port top-of-rack switches.
Operators are, however, balancing increased height against floor loading limits; aluminum rails lighten gross cabinet mass by up to 25%, easing static-load pressures on raised floors. Cable-management complexity rises with additional RU slots, spurring stronger adoption of vertical busbars and overhead fiber troughs. Environmental sensors mounted at 4 RU intervals help maintain inlet temperatures within ASHRAE limits, minimizing thermal stratification that can plague high-rise cabinets, a priority for mission-critical tenants dominating the Nigeria data center rack market.
By Rack Type: Cabinet solutions meet security and compliance needs
Cabinet enclosures owned 72.78% market share in 2025 and will grow 26.21% CAGR as enterprises tighten physical-security policies. Insurance underwriters now require fully sealed racks with biometric doors in sites exceeding 1 MW following two minor fires in Lagos labs during 2024. Closed cabinets isolate tenant equipment, enabling tiered containment zones that align with ISO 27001 and PCI-DSS audits, both common among Nigerian fintechs.
Open-frame racks persist in network-distribution rooms where airflow is paramount, but urban humidity and dust favoured by Harmattan winds complicate such deployments. Wall-mount units serve remote BTS shelters supporting 5G edge, yet volumes remain marginal relative to cabinet shipments. Integration of electronic-swing handles, thermal probes, and DCIM gateways is standard within premium cabinets, anchoring their continued dominance in the Nigeria data center rack market.
By Data Center Type: Hyperscale nodes on verge of overtaking colocation
Colocation providers controlled 51.64% Nigeria data center rack market size in 2025, but hyperscalers are advancing 27.44% CAGR as global clouds position for West African traffic. Airtel Africa’s 38 MW site and Kasi Cloud’s twin-hall build each allocate more than 3,000 racks spread across 48U layouts. Local-content mandates encourage clouds to co-locate with accredited indigenous partners instead of long-haul peering from South Africa.
Edge micro-data centers, often containerized, support 5G backhaul and video-stream-caching across secondary cities. Yet limited backhaul redundancy outside Lagos and Abuja keeps their rack counts modest. Over the forecast horizon, a tipping point looms in which hyperscale nodes eclipse colocation white space, reshaping demand curves and entrenching vertically integrated rack-and-power procurement strategies inside the Nigeria data center rack market.
By Material: Aluminum makes strides as densification accelerates
Steel frames retained 60.96% share in 2025 thanks to local fabrication networks that shorten import lead times. Currency swings inflate the cost of imported stainless steel, yet local mills keep mild-steel prices relatively steady, protecting domestic cabinet assemblers. Meanwhile, aluminum racks notch a 26.39% CAGR because lighter alloys simplify floor retrofits where static load is capped below 1,500 kg per tile. Corrosion resistance is another driver: salt-laden Atlantic air affects coastal facilities, prompting operators like Africa Data Centres to specify powder-coated aluminum for new halls.
Composite and hybrid materials remain niche, earmarked for specialized environments such as oil-servicing rigs near Port Harcourt where electromagnetic shielding is required. Over time, total cost-of-ownership models that add fuel savings from easier transport and faster installation may push aluminum toward parity in the Nigeria data center rack market, especially as high-density AI clusters proliferate.
Geography Analysis
The Nigeria data center rack market concentrates 77.35% of installed cabinets in metropolitan Lagos, leveraging five subsea-cable landing stations that cut transit latency to Europe and the US. The city’s rack footprint expanded by 24% during 2024, driven by Equinix’s LG2.3 extension and Africa Data Centres’ 10 MW hall, both pre-leased by banks and global SaaS firms. Lagos offers abundant dark-fiber routes and proximity to Africa’s busiest fintech cluster, making fully enclosed 48U racks the default specification for new builds.
Abuja forms the nation’s second-largest cluster, hosting Galaxy Backbone’s Tier IV campus and multiple federal-agency pods migrating from on-premises server rooms. Lower humidity and fewer salt-laden winds extend hardware life, yet intermittent grid supply compels operators to size diesel reserves for 48-hour blackout scenarios
Regulatory Landscape
Nigeria's data center rack demand is shaped by data-sovereignty requirements and public-sector cloud procurement expectations enforced through multiple bodies. The Nigerian Data Protection Commission (NDPC) administers compliance under the Nigeria Data Protection Act 2023, while NITDA's Nigerian Content in ICT guidance reinforces onshore processing and local participation in ICT supply chains, which can extend to locally assembled rack systems for regulated and government-linked deployments.
In October 2025, NITDA issued the National Cloud Policy 2025, introducing a data classification approach that tightens local residency requirements for higher-sensitivity datasets and formalizes a Cloud First posture for Federal Public Institutions. Data centers also sit within the Critical National Information Infrastructure (CNII) protection framework overseen by the Office of the National Security Adviser (ONSA), and facilities that deliver connectivity services intersect with Nigerian Communications Commission (NCC) licensing expectations for telecom and internet infrastructure. These controls tend to favor compliance-led cabinet racks, auditable physical access, and more standardized deployment practices across Lagos and emerging secondary hubs.
Competitive Landscape
The Nigeria data center rack market is moderately fragmented. Equinix, having completed its USD 320 million MainOne acquisition, wields the largest single footprint and upstream control of the MDXi cable-landing white space. Africa Data Centres and Rack Centre follow, each scaling beyond 10 MW with modular design templates that standardize 42U and 48U racks for rapid hall replication.
Equipment vendors Schneider Electric, Vertiv, and Eaton compete on integrated rack-power-cooling bundles. Schneider’s 2024 pact with NVIDIA delivers turnkey AI pods rated up to 80 kW per cabinet, targeting fintech risk-analytics workloads. Vertiv’s lithium-ion UPS line targets hyperscale nodes seeking to trim PUE below 1.4, crucial in diesel-heavy Nigeria. Eaton differentiates through local-assembly partnerships in Ogun State that shorten order cycles and satisfy NITDA sourcing quotas.
Nigeria Data Center Rack Industry Leaders
Equinix (MainOne)
Schneider Electric SE
Vertiv Group Corp.
Eaton Corporation
Rittal GmbH & Co. KG
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
One opportunity is the geographic broadening of Nigeria's interconnection and colocation footprint beyond Lagos, which supports incremental rack demand in new metros and along alternative fiber and subsea routes. Equinix's launch of the PR1 carrier-neutral data center in Port Harcourt provides a second anchor for carrier-neutral capacity, and the company also communicated a USD 140 million investment plan (announced April 2025) tied to expanding internet and digital infrastructure in the south. Rack suppliers that can standardize configurations across multiple sites may benefit, including 42U to 48U cabinet options aligned with higher compute density.
Another opportunity is compliance-driven workload repatriation tied to government cloud procurement rules, which can translate into onshore capacity build and refresh cycles. NITDA's National Cloud Policy 2025, along with its Cloud Service Provider (CSP) certification and government marketplace approach, tightens the bar for in-country cloud delivery. That tends to shift spending toward new halls and retrofit activity in certified environments, with procurement often favoring secure, enclosed cabinets that are ready for integrated monitoring and power distribution, while also expanding room for local assembly and services (installation, containment, and retrofit) that help operators meet Nigerian content expectations and reduce import exposure.
Recent Industry Developments
- July 2026: Central Bank of Nigeria (CBN) issued a directive mandating that banks, fintechs, and payment companies must migrate transactional data from overseas cloud servers to domestic data centers by January 1, 2027. The mandate accelerates data localization and expands demand for domestic data center capacity and related services in Nigeria.
- February 2026: Equinix inaugurated its PR1 carrier-neutral data center in Port Harcourt, serving as a landing point for the 2Africa submarine cable and functioning as a second digital anchor for Nigeria outside Lagos. The development broadens regional interconnection and strengthens Nigeria's data hosting options.
- November 2025: Equinix - The company announced a $22 million investment for its LG3 data center project in Lagos, designed to provide 610 square meters of colocation space. The investment expands Equinix's Lagos footprint and reinforces Nigeria as an interconnection hub for fintech and digital services.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the Nigeria data center rack market covers revenue earned from racks used to house IT equipment inside data center rooms in Nigeria, across new installations and replacements, as purchased by operators and enterprises.
Scope exclusions: It does not count servers, power and cooling equipment, building construction, rack-level installation labor, or ongoing managed services.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research helped us map the demand environment and the supply chain realities that shape rack buying in Nigeria. We leaned on public indicators such as data center project announcements, public-sector digitization signals, and trade and cost factors that impact imported rack bills.
Sources reviewed included Nigeria Customs and port trade statistics, NBS macro series, NITDA and NCC publications, ITU connectivity indicators, and standards references such as TIA-942 and ISO/IEC data center guidance. We also reviewed company filings, investor presentations, and credible industry news. In a few cases, paid subscriptions for company financials and intelligence, patent databases, and shipment-level import-export records were used to cross-check directionally important inputs. The sources listed here are illustrative, and many other public and paid references were also consulted for data collection, validation, and clarification.
Primary Interviews and Surveys
We interview data center operators, rack distributors, contractors, and enterprise IT buyers in Nigeria through expert interviews and surveys. Their responses clarify rack counts, occupancy, replacement cycles, local pricing, import exposure, and planned capacity, helping resolve gaps between project evidence and supplier or buyer estimates.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 18% |
| Mid tier: 45% | Functional/Unit leaders: 32% |
| Smaller Players: 25% | Managers: 50% |
Market-Sizing & Forecasting
Sizing was built using a top-down approach where planned and active data center capacity in Nigeria was translated into rack demand, and then converted into value using locally tested average selling prices by rack type and height. The totals were then corroborated with selective bottom-up approximations, such as channel checks with distributors and integrators and sampled ASP multiplied by estimated unit volumes in key builds, which helped us correct for gaps where public project data is limited.
Inputs used in the model included announced versus under-construction capacity timelines, average rack density ranges by data center type, the split of cabinet closed versus open-frame racks, mix shifts toward 45U and above, and import duty and FX pass-through trends that influence price realization. For forecasting, scenario analysis was used around project commissioning timing and pricing, with a base case informed by what operators and suppliers expect for the next build cycle. Where unit visibility was weak for smaller sites, assumptions were bounded using floor-space proxies and typical rack spacing rules, and then validated again through interviews.
Data Validation & Update Cycle
Outputs were checked in several ways so the final number stays realistic for Nigeria. We compared implied rack counts and pricing against independent signals like known site expansions, public capacity references, and trade-linked cost movements, and then investigated any unusual jumps before sign-off.
A second analyst review was completed to re-check calculations, scope alignment, and currency conversions. Re-contact triggers were used when an assumption looked out of line with what respondents described. Reports are refreshed annually, and interim updates are made when material events occur, such as major facility launches, project delays, or sharp FX shifts. Before delivery, a fresh pass is done so clients receive the latest updated view.
黑料不打烊's Nigeria Data Center Rack Market Size Measured Against Other Published Estimates
Published market sizes for racks in Nigeria can look far apart because firms do not always count the same thing, and their timing assumptions on projects and prices can differ. Differences also show up when one estimate treats racks as a hardware-only revenue pool and another blends in adjacent costs.
The table shows a noticeable spread around the 2025 value, and in 黑料不打烊's model the count is limited to rack hardware revenue inside Nigerian data centers. Pricing is built from cabinet versus open-frame mixes and local import and FX timing, rather than bundled fit-out or services.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 46.37 M (2025) | |
| Regional Consultancy A | USD 60.00 M (2025) | Includes rack installation and containment fit-out, and applies a faster shift to 48U deployments across most sites, which lifts the implied ASP versus a hardware-only view. |
| Trade Journal B | USD 38.00 M (2025) | Counts only commissioned sites in the year and uses older exchange-rate assumptions, which reduces the value attributed to imported cabinets and delays recognition of under-construction demand. |
Taken together, the gaps mostly come from what gets bundled with racks, plus how quickly new capacity is assumed to turn into installed cabinets and at what local price. By keeping the scope and input variables explicit and then cross-checking with channel feedback, our estimate stays traceable to repeatable steps that buyers can follow and stress-test.


Key Questions Answered in the Report
What is the current value of the Nigeria data center rack market?
The market is worth USD 58.31 million in 2026 and is projected to hit USD 183.38 million by 2031.
Which rack size dominates Nigerian data centers?
Full cabinets hold 62.42% share and are rising 27.26% CAGR as hyperscale tenants standardize on 42U–48U footprints.
Why are 48U racks gaining popularity?
Operators adopt 48U formats to maximize compute density without expanding floor space, a crucial efficiency step amid high energy costs.
How do local-content rules affect foreign cloud providers?
NITDA regulations require on-shore data hosting, compelling international clouds to partner with or acquire Nigerian facilities to remain compliant.
Page last updated on:
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Data Center Server Market Global servers demand, split by tier, facility size and facility type.
- Nigeria Data Center Server Market Nigeria's servers, split by facility size and tier.
- United States Data Center GPU Market GPUs demand across the US, covering deployment type, gpu type and interconnect.
- North America Containerized Data Center Market North America modular builds, split by container size, component module and tier.
- Middle East And Africa Artificial Intelligence (AI) Data Center Market AI facilities in the Middle East and Africa, split by facility type, component and tier.
- Nigeria Data Center Physical Security Market Nigeria physical security, split by solution type and service type.
- Saudi Arabia Hyperscale Data Center Market Saudi Arabia's hyperscale sites, split by facility type, component and tier.



