
India Carbon Black Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
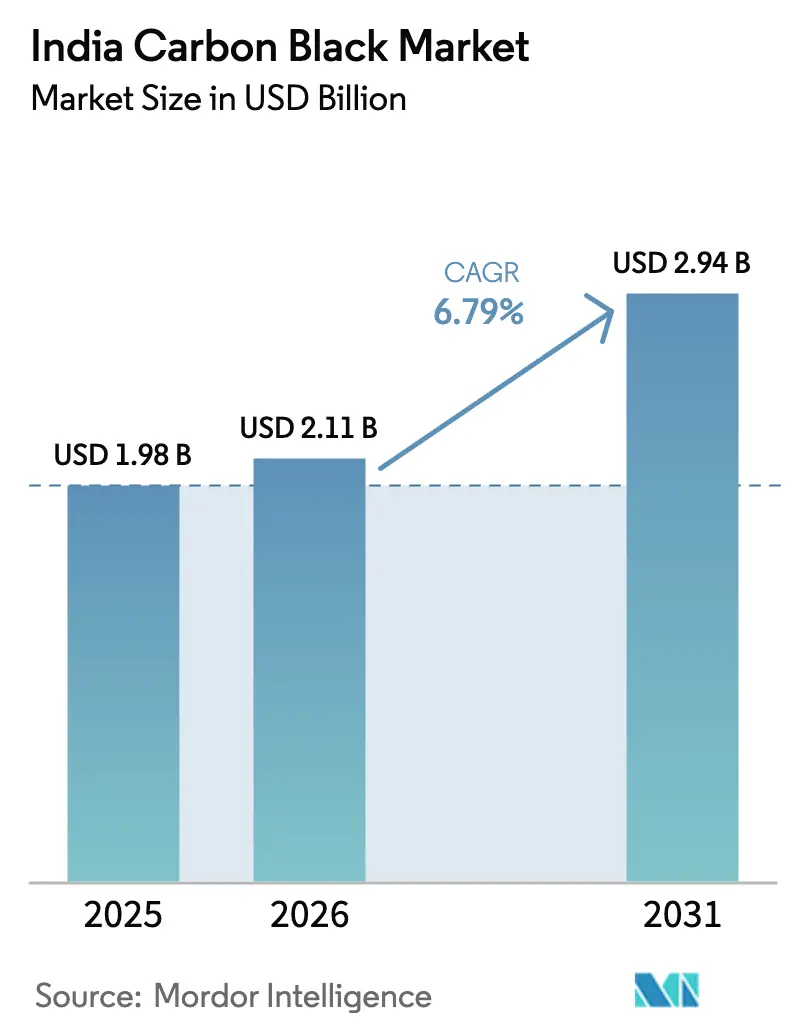
| Base Year Market Size (2025) | USD 1.98 Billion |
| Market Size (2026) | USD 2.11 Billion |
| Market Size (2031) | USD 2.94 Billion |
| Growth Rate (2026 - 2031) | 6.79 % |
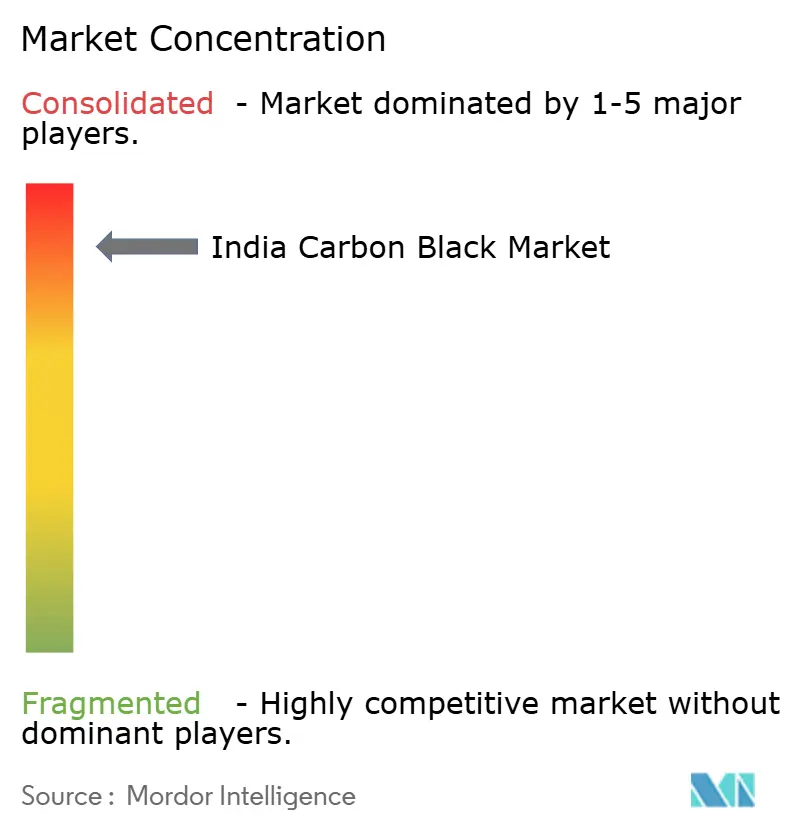
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
India Carbon Black Market Analysis by 黑料不打烊
India Carbon Black market size in 2026 is estimated at USD 2.11 billion, growing from 2025 value of USD 1.98 billion with 2031 projections showing USD 2.94 billion, growing at 6.79% CAGR over 2026-2031. Strong tire production, accelerating battery manufacturing programs and expanding polymer demand in infrastructure underpin this outlook, while domestic capacity additions improve supply resilience. Growth is further supported by a shift toward radial tires, an uptick in conductive grades for lithium-ion cells and steady government spending on road, rail and renewable-power corridors. Major producers continue to leverage feedstock integration and waste-heat recovery to contain costs amid volatile petroleum-coke prices. Meanwhile, specialty carbon black development offers margin lift as OEMs seek darker, UV-stable plastics for premium applications.
Key Report Takeaways
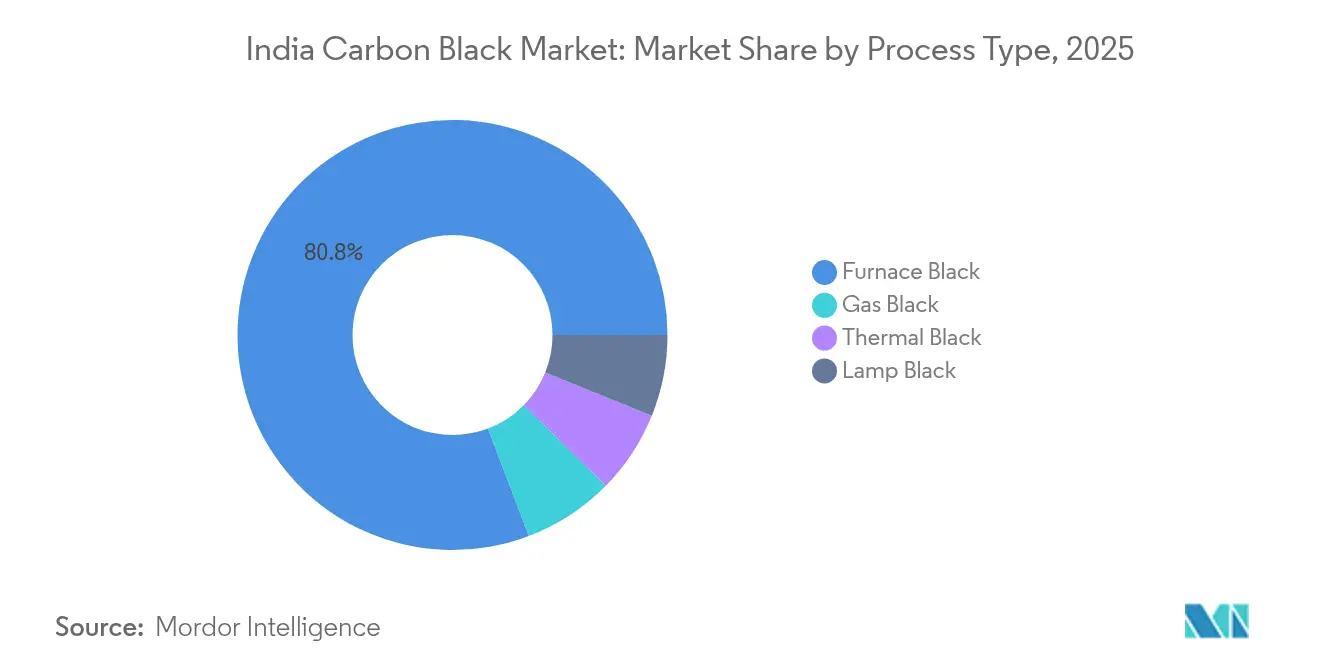
- By process type, furnace black led with 80.78% of the India carbon black market share in 2025, whereas gas black is advancing at an 8.12% CAGR through 2031.
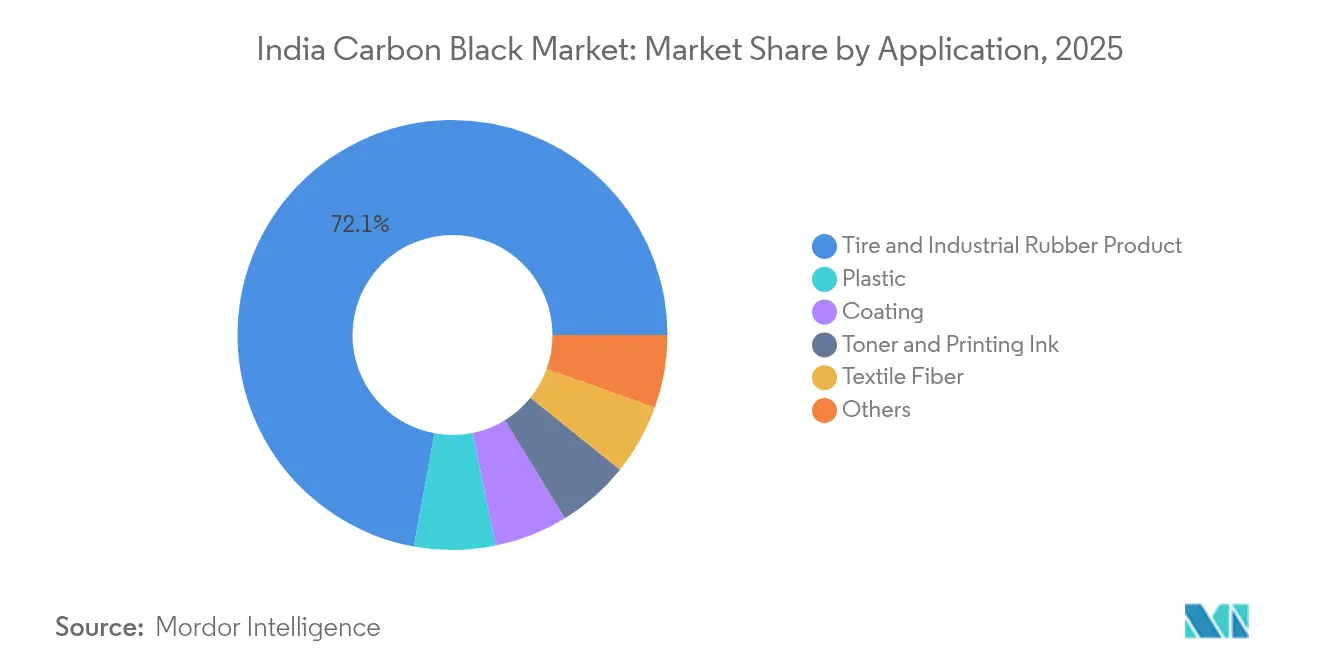
- By application, tire and industrial rubber captured 72.12% of 2025 revenue, while plastic compounds are projected to expand at a 7.65% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Carbon Black Market Trends and Insights
Drivers Impact Analysis*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging radial-tire production | +2.1% | National – Tamil Nadu, Maharashtra, Gujarat | Medium term (2-4 years) |
| Growing penetration of specialty grades | +1.8% | National – Karnataka, Gujarat, Maharashtra | Long term (≥ 4 years) |
| Ramp-up of lithium-ion cell manufacturing | +1.5% | National – Gujarat, Tamil Nadu, Haryana | Medium term (2-4 years) |
| Infrastructure boom in pipe and cable lines | +1.2% | National infrastructure corridors | Long term (≥ 4 years) |
| OEM push for darker, UV-stable plastics | +0.9% | National automotive clusters | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Surging Radial-Tire Production for Passenger and Commercial Vehicles
Vehicle makers continue to convert truck and bus platforms from bias-ply to radial construction, which requires more reinforcing filler per unit. Replacement cycles remain steady because freight utilization is rising, and highways under Bharatmala have shortened delivery times. Tire plants in Tamil Nadu and Gujarat run high-utilization shifts, sustaining offtake commitments with domestic carbon black suppliers. Higher belt-reinforcement needs raise average carbon black loading by up to 20% over legacy designs. As a result, carbon black demand grows faster than tire unit output, providing volume visibility irrespective of new-vehicle sales variation.
Growing Penetration of Specialty and Conductive Carbon Blacks
Premium conductive and UV-stable grades command two-to-three-times the price of commodity furnace blacks. Birla Carbon’s Continua material and PCBL’s surface-modified lines illustrate the technical shift toward low-ash, narrow-distribution products for battery electrodes and high-gloss polymers[1]Aditya Birla Group, “Birla Carbon – Our Businesses,” adityabirla.com. Indian producers investing in research and development and application labs secure long-term supply contracts because downstream users require formulation support. These grades raise margins and buffer earnings against feedstock swings. The trend encourages capacity earmarked specifically for batteries, cables, and high-performance plastics, diversifying revenue beyond tires.
Rapid Ramp-up of Lithium-ion Battery Cell Manufacturing
India’s Production-Linked Incentive scheme catalyzes multiple gigawatt-hour cell plants in Gujarat and Tamil Nadu. Cathode and anode formulas rely on ultra-pure conductive carbon black with controlled surface area to maintain cycle life. Local sourcing lowers logistics risk and enables just-in-time deliveries that cell makers demand for quality consistency. Producers with battery-grade certification gain an early-mover advantage, and forward contracts lock in pricing premiums that are less exposed to tire industry swings. These volumes sit atop the conventional rubber base, lifting overall domestic consumption.
Domestic Infrastructure Boom Boosting Pipe and Cable Applications
Pipe extruders and power-cable jacketers need 2-4% carbon black loading to meet 20-year outdoor durability targets. Smart-city projects, high-speed rail corridors, and utility upgrades bring steady polymer compound demand across regions. Carbon black’s dual role as colorant and UV stabilizer is hard to replace, ensuring a continuous pull even when automotive cycles cool down. Plants near ports in Gujarat and Maharashtra capitalize on lower freight costs for polyethylene and PVC producers, aligning logistics with national infrastructure rollout schedules.
Restraints Impact Analysis*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile petroleum-coke and coal-tar prices | -1.4% | Nationwide production clusters | Short term (≤ 2 years) |
| Stringent furnace-emission regulations | -0.8% | Maharashtra and Gujarat enforcement hubs | Medium term (2-4 years) |
| Rising silica-based green-tire adoption | -0.6% | Automotive clusters | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Volatile Petroleum-Coke and Coal-Tar Pitch Prices
Feedstock accounts for roughly two-thirds of cash cost, so refinery shutdowns and freight spikes compress margins quickly. Oriental Carbon & Chemicals operated near 70% utilization in FY 2024 because price pass-through lagged cost inflation. Hedging is limited, pushing producers to seek long-term supply agreements with refiners such as ONGC. Integrated waste-heat recovery partly cushions energy swings, yet smaller plants lacking scale remain vulnerable.
Stringent Regulatory Norms for Carbon-Black Furnaces
Tightening particulate-emission rules oblige continuous monitoring and high-efficiency scrubbing. PCBL’s historical Kochi shutdown underscores the risk of non-compliance. New projects budget significant capex for flue-gas desulfurization and bag-filter systems, raising entry barriers. Larger players absorb these costs across higher volumes, whereas regional independents may exit or sell capacity, accelerating consolidation.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Process Type: Furnace Black Retains Scale Advantage
Furnace black held 80.78% of the India carbon black market share in 2025 because it offers the lowest unit cost for large-run production. While niche, gas black posts the fastest 8.12% CAGR because of superior conductivity sought in battery electrodes and antistatic polymers. The India carbon black market size contribution from furnace lines is set to expand in absolute terms as PCBL and Epsilon Carbon commission additional reactors in Gujarat and Karnataka. Environmental investments make new furnace capacity capital-intensive, yet scale economies maintain competitiveness over lamp or thermal processes.
Gas black’s growth is rooted in specialty demand rather than volume leadership. Producers target modest capacities co-located with downstream compounders to offset higher conversion costs. Thermal black remains a micro-segment for ultra-pure applications, while lamp black serves legacy ink markets. As OEMs tighten conductivity and purity specs, suppliers upgrading process control capture premium pricing, lifting average realization per ton across the India carbon black market.


By Application: Tire Rubber Dominance Faces Polymer Upswing
Tire and industrial rubber end-uses represented 72.12% of revenue in 2025, reinforcing the historic link between vehicle build rates and the India carbon black market. The plastic segment, however, is projected to deliver a 7.65% CAGR, supported by pipes, cables, and automotive interior trims that need UV resilience. India's carbon black market size gains from plastic applications will offset any moderation in tire growth as electric vehicles adopt extended tread-wear compounds that reduce per-tire filler load.
Printing inks, toners, and coatings offer stable but smaller volumes driven by packaging and construction. Continuous growth in e-commerce boosts inkjet toners, where small-particle carbon black enables dense optical density. Coating formulators in the building sector specify high-purity grades for fa?ade durability, expanding non-rubber consumption. These diversified outlets improve capacity utilization and decrease dependence on automotive cycles in the India carbon black industry.
Geography Analysis
Western and southern corridors dominate consumption because they host tire plants, chemical parks, and major ports. Maharashtra and Gujarat account for the largest share owing to integrated refinery feedstock and export infrastructure. PCBL’s Mundra and Palej units supply both domestic customers and overseas buyers via deep-draft berths, enhancing the India carbon black market’s logistics efficiency. Tamil Nadu benefits from proximity to commercial-vehicle OEMs and emerging battery manufacturers, pushing regional demand ahead of national averages.
In Karnataka and Andhra Pradesh, capacity additions aim to serve new electrical-cable and pipe plants linked to renewable-energy corridors. The India carbon black market size allocated to southern states is projected to grow through 2031 as solar and wind installations require UV-stable polymer components. Northern regions sustain modest growth tied to off-the-road tire and agricultural machinery hubs around Haryana and Uttar Pradesh.
Export performance complements domestic sales. Currency competitiveness and India’s reputation for quality reinforce these lanes. However, freight volatility and trade-remedy duties in destination markets influence margin realization, motivating producers to balance international exposure with the reliable pull from domestic tire makers.
Regulatory Landscape
In India, carbon black production and recovered carbon black (rCB) activity are facing tighter environmental compliance expectations alongside efforts to standardize waste-derived feedstocks. Decisions published in January 2024 by the Ministry of Environment, Forest and Climate Change (MoEFCC) Technical Review Committee (TRC) set conditions for importing used tire scrap for rCB projects, including eligibility-type requirements and Central Pollution Control Board (CPCB) verification. For operators working with the tire-waste stream, this reinforces the need for detailed documentation and strict compliance.
Product quality standardization is increasingly shaping market access and downstream qualification. In May 2026, NITI Aayog proposed national standards for Tyre Pyrolysis Oil and recovered carbon black to improve quality and reliability. Together with ongoing emissions controls on furnace operations, the proposal raises expectations for traceability and consistent specifications. In July 2026, Epsilon Carbon reported that it became the first company in India to receive Bureau of Indian Standards (BIS) certification for carbon black, underscoring the growing role of formal certification in supplier qualification, particularly for specialty, battery-adjacent, and performance polymer applications.
Value Chain Analysis
The India carbon black value chain begins with hydrocarbon feedstocks, with producers drawing Carbon Black Feedstock (CBFS) from crude oil and other refinery-linked streams, alongside energy inputs and consumables for furnace operations. Large producers often benefit from co-location near refineries and ports in Gujarat and Maharashtra. Investments in waste-heat recovery and emission-control systems are increasingly integrated into new and upgraded lines, which raises conversion capital intensity but also supports cost control through energy recovery.
Manufacturing outputs then flow to tire and industrial rubber customers as well as to non-rubber processors, including plastics, cables, inks, and coatings, typically via bulk logistics and regional warehousing near major industrial corridors. In March 2026, PCBL commissioned 30,000 MT of additional brownfield capacity in Tamil Nadu, showing how debottlenecking and brownfield additions can strengthen domestic supply resilience and shorten lead times to southern demand centers. At the same time, international logistics disruptions have affected input and export flows, with May 2026 commentary noting rerouting around the Cape of Good Hope that increases transit times and freight costs. This reinforces the advantage of domestically sourced feedstocks and port-adjacent inventory hubs for supply continuity.
Competitive Landscape
The India carbon black market is highly consolidated. Capacity expansion is often paired with waste-heat recovery turbines that lower Scope 2 emissions, meeting tightening ESG criteria from tire majors. Technology differentiation centers on surface-modified and low-PAH grades aimed at EV batteries and food-contact polymers. Patent filings from PCBL and collaborative projects between Birla Carbon and downstream compounders illustrate a shift toward application co-development. Smaller regional players cater to inks and coatings but face compliance-cost pressure, opening the door for acquisitions by larger firms seeking footprint diversification in the India carbon black industry. Pricing power remains linked to feedstock swings. Integrated players with long-term petroleum-coke contracts hedge exposure better than standalone units. Strategic sourcing from ONGC’s OPaL complex offers domestic supply security and cost stability OPALINDIA.IN. As customers prioritize reliable delivery, producers with port-adjacent inventory hubs and robust quality systems gain preferred-supplier status, reinforcing incumbency advantages across the India carbon black market.
India Carbon Black Industry Leaders
PCBL Limited
Birla Carbon (Aditya Birla Group)
Himadri Speciality Chemical Ltd
Epsilon Carbon Pvt Ltd
Continental Carbon India Ltd (Continental Carbon Asia)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
White space is opening around higher-value specialty grades that target batteries and advanced polymers, where qualification, purity, and conductivity requirements narrow supplier shortlists beyond commodity furnace black. Himadri Speciality Chemical Ltd provides a clear example of this shift, as it commissioned an anode materials facility in April 2026 and has disclosed investments to expand into adjacent advanced carbon materials, including a carbon nanotube project and a plan to convert part of existing carbon black capacity into super speciality carbon black. This mix of downstream battery-material capability and specialty carbon black upgrading supports application-led product development, such as conductive, low-ash, and narrow-distribution grades, along with long-term offtake structures with cell, compound, and polymer customers.
A second opportunity area is emerging through exportable capacity and trade flows, where external supply constraints and policy changes can redirect demand toward India. Credit-rating commentary has pointed to export demand into the European Union following restrictions on Russian material, and port-accessible producers with consistent quality systems can use this window to balance domestic, tire-linked volumes with export programs. Alongside this, the May 2026 NITI Aayog proposal to standardize recovered carbon black and pyrolysis oil signals a pathway for more reliable rCB integration into rubber and plastics formulations. That can create a clearer channel for compliant rCB producers, while conventional carbon black manufacturers can participate through blending, qualification support, and circularity-linked product lines.
Recent Industry Developments
- July 2026: Himadri Speciality Chemical Ltd Commencement of entry into Super Speciality Carbon Black (SSCB) via a project converting ~6,000 MTPA of existing capacity. The expansion into high-margin SSCB strengthens the company's portfolio and taps EV and battery related plastics and specialty polymers markets. The move diversifies product mix beyond standard carbon black and may support higher-margin applications.
- May 2026: Birla Carbon (Aditya Birla Group) Global restructuring to a three-business-unit model (Asia, Americas & EMEA, Specialty Materials) with a dedicated President for Specialty Materials. The realignment tailors carbon black supply for specialty markets, improving execution speed and focus on specialty-grade carbon blacks and nanotubes. Potentially enhances customer service for non rubber applications.
- February 2026: Himadri Speciality Chemical Ltd Commenced commercial operations of a 70,000 MTPA speciality carbon black line at Mahistikry, Hooghly, West Bengal, bringing total capacity to 250,000 MTPA. Strengthens India’s specialty carbon black capacity and positions for higher-margin grades and non rubber applications. Enhances domestic supply resilience.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the India carbon black market is defined as the value of carbon black sold for rubber and non-rubber applications within India, with revenues captured at the point of sale and expressed in USD for a consistent comparison over time.
Scope exclusions: This sizing excludes downstream finished goods value (such as tires, plastics products, and inks) and excludes unrelated black pigments that are not carbon black.
Segmentation Overview
- By Process Type
- Furnace Black
- Gas Black
- Lamp Black
- Thermal Black
- By Application
- Tire and Industrial Rubber Product
- Plastic
- Toner and Printing Ink
- Coating
- Textile Fiber
- Others
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundary and to build the first set of demand signals for carbon black in India. We referenced public datasets and documents such as Department for Promotion of Industry and Internal Trade (DPIIT) releases, Department of Chemicals and Petrochemicals publications, Directorate General of Commercial Intelligence and Statistics (DGCIS) trade notes, and UN Comtrade-aligned HS code trade series where available. Sector context was also checked through sources such as the Society of Indian Automobile Manufacturers (SIAM) and Rubber Board of India updates, since tire and industrial rubber remain the largest consumption pool.
On the supply side, capacity additions and utilization commentary were compiled from company annual reports, investor presentations, and stock exchange filings, which helps map realistic shipment potential by year. To avoid relying on a single lens, we also used paid subscriptions for company financials and intelligence, patent databases, and shipment-level import and export signals, which filled gaps where public data lagged. This desk research list is illustrative and not exhaustive, and multiple other public and paid sources were referenced for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary inputs were collected through expert interviews and structured surveys across producers, distributors, tire and rubber compounders, plastics and masterbatch participants, and selected downstream buyers that influence specifications and procurement cycles. We used these discussions to confirm how grade mix typically shifts, how feedstock links to price movement, and how quickly specialty volumes get qualified. Those details were then used to align the desk indicators with purchase behavior across India.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 15% |
| Mid tier: 50% | Functional/Unit leaders: 39% |
| Smaller Players: 17% | Managers: 46% |
Market-Sizing & Forecasting
Market sizing starts with a top-down build where production and trade data are used to reconstruct India-available supply, which is then translated into value using price ranges by major end-use and grade. To keep the model grounded in real demand, the totals are checked against a bottom-up approximation using sampled volumes from key application pools and typical consumption intensity, and then adjusted when the two views do not align.
The main inputs used in the model include carbon black capacity additions and expected ramp ups, import and export trends under HS 280300, tire production directionality as the biggest demand anchor, the split between tire versus non-tire applications, and feedstock and realized price movement that affects revenue even when volumes are steady. Where data is not available for a smaller application, the gap is handled through conservative proxy ratios derived from expert inputs and then reviewed again during validation. For forecasting, scenario analysis is used so the outlook can flex with realistic assumptions on tire growth, exports, and operating rates, while price paths are kept consistent with what industry respondents expect under normal feedstock cycles.
Data Validation & Update Cycle
Validation is done through triangulation across three angles, which are supply availability, trade flows, and end-use pull signals, and then the remaining variance is explained before final sign-off. Outliers are flagged when implied consumption per tire, implied netbacks, or utilization levels move outside what primary respondents consider workable, and those cases are rechecked with follow-up calls. Before publication, the model and written conclusions go through multi-step analyst review so assumptions, units, and currency treatment stay consistent across the time series.
Reports are refreshed annually, and interim updates are made when material events change the outlook, such as a large capacity commissioning, a sharp shift in exports, or a policy move impacting trade. Right before delivery, an analyst performs a fresh pass on key variables so clients receive the latest updated view.
黑料不打烊's India Carbon Black Market Sizing Compared With Other Published Estimates
Published market sizes for India carbon black can look far apart because the underlying scope is not always the same, and the pricing logic can be applied at different points in the value chain. Differences also come from which year is treated as the base, how imports and exports are netted out, and whether specialty grades are priced with a separate uplift or blended into an average.
By tracking capacity ramp ups, trade-linked availability under HS 280300, and application-led pricing bands, 黑料不打烊 keeps the estimate tied to carbon black sales in India rather than mixing in unrelated black materials or downstream product values. A second gap driver is the update cycle, since some publishers keep older feedstock and currency assumptions in place for longer, which can inflate or depress USD values when real prices have already moved.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 1.98 B (2025) | |
| Regional Consultancy A | USD 0.93 B (2024) | Uses an earlier base year and tends to apply a blended ASP without clearly separating tire-led commodity volumes from higher-priced specialty grades, which can understate revenue when mix upgrades accelerate. |
| Trade Journal B | USD 84.18 B (2024) | The stated value is not consistent with a carbon black raw material market and likely includes a much wider chemicals or rubber value chain definition, which makes it not directly comparable to carbon black sales revenues. |
The spread in the table mainly comes down to scope boundaries and how price is mapped to volumes, not just forecasting optimism. When the market is defined at the carbon black sales level, and when trade signals and capacity additions are used as hard checks, the final number stays traceable to repeatable steps and is easier to update as conditions change.


Key Questions Answered in the Report
What is the current value of the India carbon black market?
It is valued at USD 2.11 billion in 2026 and is projected to reach USD 2.94 billion by 2031.
How fast is demand for carbon black in plastic applications growing?
Plastic compounds are expanding at a 7.65% CAGR through 2031 on the back of infrastructure and automotive needs.
Which process segment dominates the Indian supply?
Furnace black leads with 80.78% share owing to cost-efficient, large-scale production economics.
Why are specialty carbon blacks gaining traction?
Conductive and UV-stable grades fetch premium pricing and support lithium-ion batteries, cables, and high-gloss auto parts.
How are feedstock price swings affecting producers?
Volatile petroleum-coke and coal-tar costs squeeze margins, encouraging long-term supply contracts and vertical integration.
What regions account for the highest consumption?
Maharashtra and Gujarat lead due to tire, chemical, and port infrastructure, while Tamil Nadu and Karnataka are rising on EV and polymer growth.
Page last updated on:



