
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 8.25 Billion |
| Market Size (2026) | USD 8.64 Billion |
| Market Size (2031) | USD 10.59 Billion |
| Growth Rate (2026 - 2031) | 4.17 % |
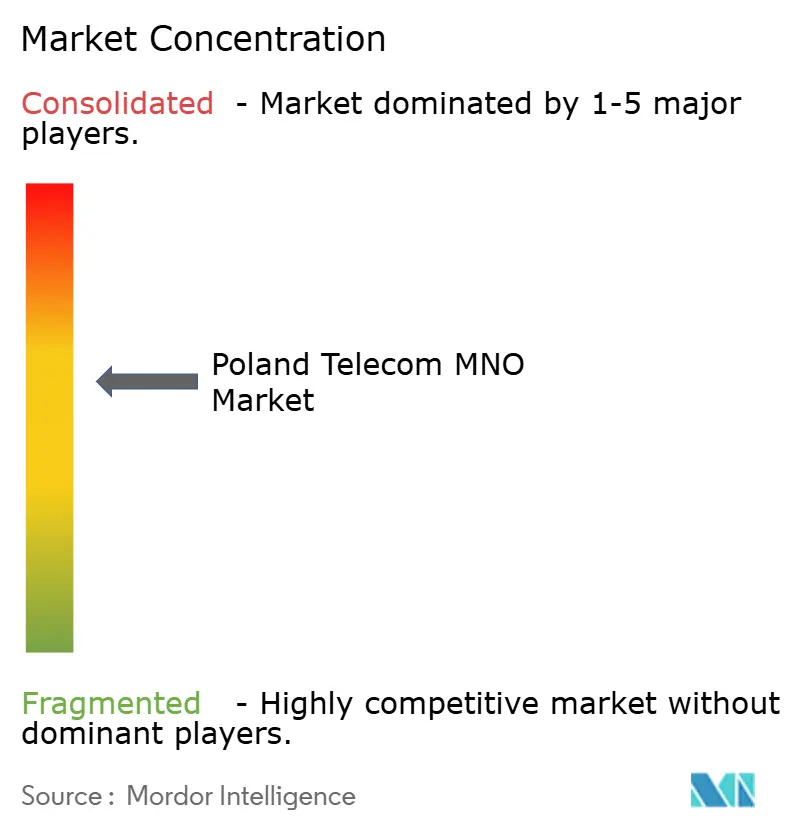
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Poland Telecom MNO Market Analysis by 黑料不打烊
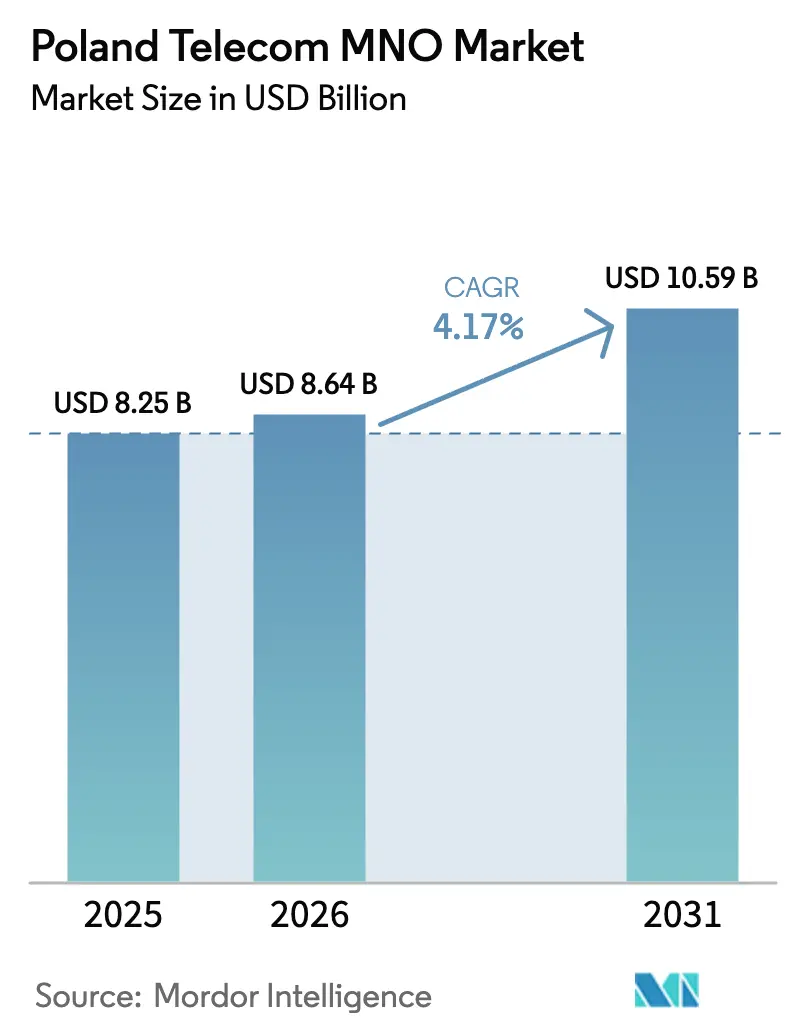
The Poland Telecom MNO Market size is projected to expand from USD 8.25 billion in 2025 and USD 8.64 billion in 2026 to USD 10.59 billion by 2031, registering a CAGR of 4.17% between 2026 to 2031. In terms of subscriber volume, the market was valued at 48.38 million subscribers in 2025 and is expected to grow from 50.22 million in 2026 to 59.56 million by 2031, at a CAGR of 3.47% over the forecast period (2026-2031). This expansion is unfolding in a mature environment where subscriber volumes have peaked, and operators now monetize value-added services, especially 5G data, fiber convergence, and enterprise IoT solutions. A four-player structure keeps competition intense, yet the March 2025 low-band spectrum auction obliges every licensee to deliver 120 Mbps to 99% of households by 2030, sparking fresh rural investment while dense urban areas shift toward millimeter-wave capacity. Bundled quad-play offers, particularly those combining mobile with fiber speeds of 300 Mbps to 900 Mbps, are raising average revenue per offering and reducing churn even as pure mobile ARPU inches upward. Enterprise adoption of private 5G, unified communications, and machine-to-machine links is opening a new, higher-margin layer of demand that cushions the drag from wholesale termination cuts and roaming-cap declines. EU Digital Decade grants, lower policy rates and rising real wages provide macro tailwinds that sustain device upgrades and broadband migration despite fiscal consolidation.
Key Report Takeaways
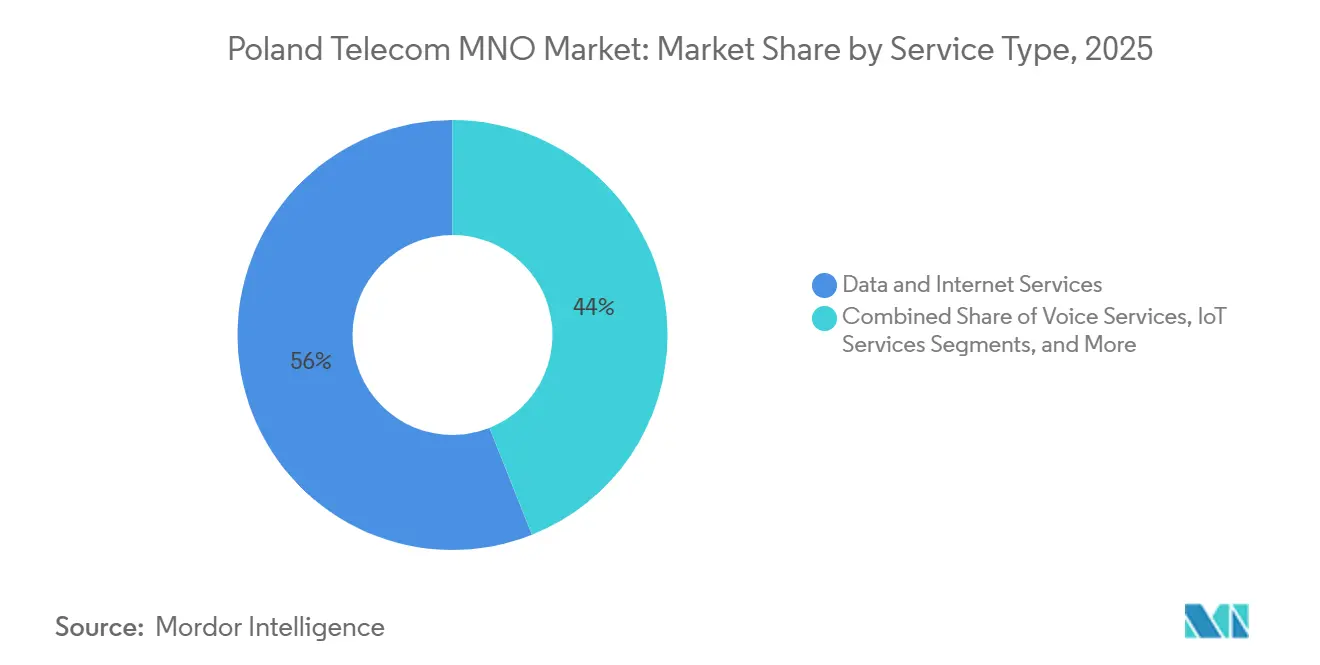
- By service type, Data and Internet Services captured 56.02% of the Poland telecom MNO market share in 2025, while IoT and M2M Services are forecast to accelerate at a 5.43% CAGR through 2031.
- By end-user, consumers generated 72.32% of revenue in 2025, whereas the enterprises segment is projected to expand at a 3.86% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Poland Telecom MNO Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| 5G Spectrum Auction and Rollout Accelerates Mobile Data Monetisation | +1.2% | National, Warsaw, Krakow, Gdansk, Wroclaw | Medium term (2-4 years) |
| Convergent Quad-Play Bundles Driving ARPU Uplift and Churn Reduction | +0.9% | National, strongest in fiber-ready cities | Short term (≤ 2 years) |
| EU-Funded FTTH Expansion Widens Addressable Fixed-Broadband Base | +0.7% | Eleven underserved provinces | Long term (≥ 4 years) |
| Video-Rich Traffic Surge from Streaming, Gaming and Remote Work | +0.6% | Metropolitan areas | Medium term (2-4 years) |
| Private-5G Pilots in Katowice SEZ and Ports Unlock Enterprise Revenue | +0.3% | Katowice SEZ, Gdansk, Gdynia | Long term (≥ 4 years) |
| mObywatel e-ID Push Boosts Demand for Secure Connectivity Services | +0.2% | National | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
5G Spectrum Auction and Rollout Accelerates Mobile Data Monetisation
The March 2025 auction allocated 700 MHz and 800 MHz licenses that run until 2040, raising PLN 2.5 billion for the state and imposing strict obligations on Orange, Play, T-Mobile, and Polkomtel to reach 99% of households at 120 Mbps. Those low-band blocks complement the mid-band 3.6 GHz grids already in place, creating a coverage-capacity-hotspot triad that mirrors Western European playbooks. Operators are now packaging 5G fixed-wireless access at PLN 80 per month to households beyond fiber, giving them a fresh revenue path while refarming 2G and 3G airwaves to meet soaring data loads. Longer term, open-API programs such as GSMA Open Gateway allow Polish MNOs to commercialize fraud-prevention, latency, and quality-on-demand features.[1]GSMA, “Mobile Economy Europe 2025,” gsma.com
Convergent Quad-Play Bundles Driving ARPU Uplift and Churn Reduction
Orange grew convergent customers 4.9% year on year to 1.79 million in Q1 2025, each generating PLN 126.2 in average monthly revenue, quadruple the handset figure. Polkomtel counts over 2.5 million multi-play subscribers whose annual churn is several hundred basis points lower than mobile-only peers. T-Mobile added 98,000 broadband lines in nine months thanks to its MagentaOne pack, proving that single-invoice simplicity trumps the gigabyte race. The national regulator tallied 14.1 million bundle users in 2024, giving all four operators headroom to convert legacy cable and satellite customers to IPTV-over-fiber offerings.
EU-Funded FTTH Expansion Widens Addressable Fixed-Broadband Base
L22: A EUR 450 million Digital Poland package and a EUR 131 million InvestEU facility are underwriting neutral-host fiber rolls that aim to reach 1.1 million additional homes, mostly in east and southeast Poland. Orange already passes 9.16 million homes, and Play’s InfraVia venture targets another 6 million at lower construction cost than dense Warsaw ducts. Deregulation proposals that would lift local-loop mandates from the incumbent could further pivot the market toward facilities-based rivalry. For MNOs, the upside spans wholesale rentals, gigabit broadband sales and, critically, higher-margin quad-play conversions.
Video-Rich Traffic Surge from Streaming, Gaming and Remote Work
L23: Arthur D. Little expects average European mobile data usage to soar from 16 GB per month in 2023 to 76 GB by 2030.[2]Arthur D. Little, “Mobile and Fixed Data Traffic Projections,” adlittle.com Orange’s subs already pull 11.7 GB monthly and VoLTE now carries 80% of calls on T-Mobile, freeing spectral blocks for pure data. Tele-medicine, e-prescriptions and remote work are entrenching video reliance, while smartphone adoption among seniors pushes subscription penetration closer to Western levels. Operators respond with densification; Play built 805 new 5G sites in 2024, and tiered fiber upgrades that sell 900 Mbps boosts for PLN 20.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| EU-Mandated MTR and Roaming Caps Squeeze Operator Margins | -0.8% | National, EU-aligned | Short term (≤ 2 years) |
| Fierce Price Competition Keeps Retail ARPUs under Pressure | -0.6% | National, prepaid and entry postpaid | Short term (≤ 2 years) |
| Energy-Price Volatility Raises Network Opex for 5G Densification | -0.3% | National | Medium term (2-4 years) |
| Slow 700 MHz Clearance Delays Rural Coverage Obligations | -0.2% | Rural and semi-rural | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
EU-Mandated MTR and Roaming Caps Squeeze Operator Margins
Wholesale roaming ceilings will fall from EUR 1.30 per GB in 2025 to EUR 1.00 in 2027, while symmetrical mobile-termination rates keep sliding under EU rulings. Deutsche Telekom flags these cuts as a direct drag on Poland service revenue.[3]Deutsche Telekom, “Annual Report 2024,” telekom.com Lower inbound roaming income particularly hurts a market traversed by German, Czech and Baltic travelers, and cost-oriented scrutiny on national roaming deals trims wholesale spreads for infrastructure-heavy incumbents. Operators answer by chasing higher-margin enterprise slices, as Polkomtel’s PLN 1,504 B2B ARPU exemplifies.
Fierce Price Competition Keeps Retail ARPUs under Pressure
T-Mobile’s June 2025 move to a PLN 75 unlimited plan with free 300 Mbps fiber upended tiered pricing overnight and forced rivals to simplify offers or cede port-out flows. Play led portability for ten straight quarters but still posted only PLN 32.7 mobile ARPU in Q4 2024. Orange’s handset ARPO sits below PLN 30, and SIM-only propositions cap the upside even as data usage explodes. With headline inflation easing to 2.6% in 2026, consumers remain price-sensitive, making data-driven upsell rather than tariff hikes the main lever.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Service Type: Data Dominates While IoT Gains Enterprise Traction
Data and Internet Services held 56.02% of Poland telecom MNO market share in 2025, underscoring the pivot from voice-centric revenue to pure broadband. The Poland telecom MNO market size attributed to this category is on track to widen in lockstep with mid-band 5G densification, fixed-wireless substitution and widespread VoLTE adoption. Operators continue to repurpose 2G and 3G spectrum for next-generation data, while fiber backhaul further boosts mobile throughput. Over-the-top messaging has hollowed out SMS income, rendering Messaging Services a minor slice whose relevance now lies in two-factor authentication for e-government and banking.
IoT and M2M Services post the fastest 5.43% CAGR through 2031, driven by private 5G networks in Katowice SEZ, Baltic ports and national rail corridors. The Poland telecom MNO market size for IoT remains modest today, yet the enterprise deals command premium SLAs that far exceed consumer ARPU. Deployment of 5G RedCap chips opens mid-tier wearables and video surveillance opportunities, bridging the gap between narrowband IoT and full-fledged URLLC use cases. Meanwhile, OTT and PayTV remains relevant because bundled IPTV stabilizes churn even as standalone streaming erodes linear channels. Commodity Voice Services keep shrinking as minutes migrate to data-borne apps, freeing low-band airwaves for capacity expansion.


By End-User: Consumers Lead, Enterprises Lift Margins
Consumers produced 72.32% of Poland telecom MNO market revenue in 2025, reflecting near-universal handset ownership and growing smartphone data appetites. Unlimited-data offers, handset installment plans and fiber-linked TV packages keep volumes high, but price rivalry restrains average returns. Operators thus push quad-play bundles that raise switching costs and elevate average revenue per offering almost fourfold versus mobile-only.
Enterprises, government bodies and large institutions are the fastest-growing cohort at a 3.86% annual clip. Although their slice of Poland telecom MNO market size is smaller, the margin differential is substantial, with Polkomtel reporting PLN 1,504 per-account revenue, nearly 20 times consumer handset ARPU. Demand concentrates on private 5G, edge compute, secure identity APIs and unified communications. Public-sector digital-ID programs and railway FRMCS trials add a B2G dimension that is relatively immune to price-led churn. As fixed-mobile convergence and spectrum-based service-level guarantees mature, the enterprise line of business will shape network-slicing strategies and influence where incremental capex lands.

Geography Analysis
The Poland telecom MNO market shows stark urban-rural differences. Warsaw, Krakow, Wroclaw, Gdansk and Poznan host roughly 30% of the population yet receive most mid-band 5G nodes and fiber strands. Orange’s C-band grid covers 40% of citizens primarily in these cities, while Play’s 805 new sites in 2024 lifted its 5G reach to 77% of inhabitants. EU funds totalling EUR 450 million steer wholesale fiber into eleven underserved provinces such as Lubelskie and Podkarpackie, narrowing the divide but stretching operator payback timelines.
L33: Industrial clusters bolster regional demand. Katowice SEZ, the Gdansk-Gdynia port axis and Silesian auto corridors anchor private 5G pilots that bundle connectivity with low-latency edge compute. The PKP FRMCS pilot validates public 5G SA for mission-critical rail signaling over Warsaw-Krakow and Warsaw-Gdansk tracks, giving MNOs a template to pursue other transport authorities.[4]Ericsson, “Private 5G and FRMCS Trials in Poland,” ericsson.com UKE’s spectrum set-asides for 3.8-4.2 GHz local use empower enterprises such as Comarch to self-deploy, forcing national operators to pitch managed-service overlays rather than raw bandwidth.
Mid-sized cities between 100,000 and 500,000 residents provide the sweetest economics for fiber. Play’s Elsat pickup adds 700,000 passings mainly in such locales, while Orange leverages pre-existing ducts to hit 54% broadband penetration on fiber. OECD data highlight a three-fold GDP per capita spread across voivodeships, which echoes in broadband adoption and premium-tier take-up. National plans to reach 100 Mbps everywhere by 2025 and gigabit service by 2030 place coverage obligations on low-band holdings and motivate operators to spread costs through wholesale and subsidy channels.
Regulatory Landscape
Poland’s telecom sector is governed primarily by the Electronic Communications Law and overseen by the Office of Electronic Communications (UKE). Spectrum policy remains a central lever: following the March 2025 low-band auction, licensees (Orange, Play/P4, T-Mobile, and Polkomtel) are subject to coverage and quality obligations that rise from 98% of households at 50 Mbps by end-2026 to 99% at 120 Mbps by 2030, shaping rural deployment priorities and the timing of 700 MHz utilization.
In 2026, UKE advanced a more deregulatory stance in fixed wholesale. Workstreams were initiated to lift obligations around BSA/LLU for Orange Polska and to deregulate elements of fixed call termination markets, signaling a shift toward facilities-based competition where fiber footprint and backhaul ownership matter more than mandated access. Cybersecurity compliance also tightened in April 2026, when UKE started registration of electronic communications entities into the list of essential and important entities in line with NIS2 implementation, increasing governance and reporting requirements for operators and key ecosystem participants. Separately, UKE indicated in February 2026 that it would not rush a 26 GHz assignment, aligning the timeline with later-stage 5G densification economics rather than forcing immediate mmWave capex.
Competitive Landscape
Orange Polska, Play Communications, T-Mobile Polska and Polkomtel share a mature arena where SIM penetration already exceeds 127%. Orange commands 18.6 million SIMs plus the largest fiber footprint, yet its 2024 revenue slipped 1.8%, showing that efficiency gains only partly offset legacy erosion. Play leads portability and invests heavily in 5G, adding 12,426 base stations and financing rollout via PLN 700 million green bonds. T-Mobile grows convergence fastest, with broadband lines up 41.1% year on year, aided by Deutsche Telekom capital and a strategic one-tariff play. Polkomtel leverages Netia fiber and targets enterprise private 5G to claw higher ARPU, already serving 44% of its B2C base with bundles.
White-space opportunities cluster around EU-funded rural fiber, industrial private 5G contracts and monetized network APIs. Early 5G standalone rollouts could secure a lead, given that only 15% of European peers had gone SA by Q3 2024, according to GSMA. UKE’s intent to lift wholesale duties from Orange may tilt the field toward facilities-based competition, nudging rivals to accelerate their own fiber and tower builds.
Retail price wars are unlikely to abate after T-Mobile’s PLN 75 plan, so operators depend on service differentiation. Orange trials Real Time Text for accessibility compliance, Play pushes sustainability-linked bonds, and Polkomtel courts logistics and manufacturing clients with Ericsson-backed standalone slices. The market remains moderately concentrated, yet none of the four exceeds a third of subscribers, creating persistent incentive to undercut or bundle rather than collude.
Poland Telecom MNO Industry Leaders
Orange Polska SA
Play Communications S.A
T-Mobile Polska S.A.
Polkomtel Sp. z o.o.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Convergence and infrastructure monetization form the clearest whitespace in Poland’s mature MNO market, where growth levers are shifting from new SIM additions toward higher-value multi-service relationships and enterprise-grade connectivity. 2025 investment rose 32.3% year-on-year to PLN 12.7 billion, and the broader electronic communications market was reported at PLN 46.0 billion. This scale of committed spend on networks, fiber extension, and modernization can feed quad-play, wholesale access, and managed-service revenue streams.
Several near-term opportunity lanes are anchored in active programs and policy actions rather than new customer acquisition. EU-backed rural FTTH expansion, including the Digital Poland and InvestEU facilities referenced in the report context, creates addressable pockets for fixed-mobile bundles and FWA where fiber remains uneconomic. UKE’s 2026 deregulatory trajectory around BSA/LLU changes the competitive calculus for Orange and pushes rivals to deepen their own infrastructure positions. On the enterprise side, private 5G deployments in industrial zones and ports, together with transport-sector FRMCS trials highlighted in the report context, create room for premium SLAs, managed edge connectivity, and security-oriented services. These services align with NIS2-driven governance demands and the mObywatel e-ID push for secure connectivity features.
Recent Industry Developments
- July 2026: Netia: UOKiK approved Netia acquisition of TK Telekom, finalizing May 2026 agreement. Regulatory clearance for consolidation in fixed/mobile infra. Strengthens Netia’s fixed-mobile convergence and enterprise fiber footprint, impacting market structure.
- July 2026: Orange Polska & APG: EU regulatory filing for joint acquisition of Nexera fiber operator. Flagship fiber acquisition in Poland’s regulatory review. Expands Orange/APG fiber reach and wholesale capabilities, accelerating converged services strategy.
- July 2026: Polkomtel Sp. z o.o.: Term Sheet signed with Towerlink Poland and Cellnex Poland to manage telecoms infrastructure for 5G rollout. Infrastructure-sharing and fiber/5G deployment initiative. Enables accelerated 5G rollout via shared access and potential capex optimization.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the Poland telecom market is defined as operator revenue earned from providing connectivity and related communication services to consumers and businesses in Poland across mobile and fixed networks, including service add-ons where they are billed as part of telecom offers.
Scope exclusions: Hardware device sales, unrelated IT services, and pure media content revenue that is not packaged and billed through telecom service plans are excluded.
Segmentation Overview
- Overall Telecom Revenue and ARPU
- Service Type
- Voice Services
- Data and Internet Services
- Messaging Services
- IoT and M2M Services
- OTT and PayTV Services
- Other Services (VAS, Roaming and International Services, Enterprise and Wholesale Services, etc.)
- End-User
- Enterprises
- Consumer
Data Sources, Market Sizing, and Validation
Desk Research
Desk research builds the base picture of how the telecom market is performing in Poland, and it helps us keep definitions consistent across years. We rely on public market totals and operational indicators from sources such as Poland's telecom regulator publications, Eurostat, the OECD telecom data series, and the International Telecommunication Union, which help cross-check subscriber trends and network adoption.
We also review operator annual reports and investor presentations, plus official spectrum and licensing announcements, to align timing of 5G rollouts and coverage goals with revenue impacts. When needed, subscription based datasets for company financials, news and financials, and import and export shipments are used to sanity-check reported revenue lines and major capex cycles. The sources listed here are illustrative only, and many other public documents and datasets are reviewed to collect, validate, and clarify the final analysis.
Primary Interviews and Surveys
We interview and survey CXOs, functional leaders, and managers from telecom operators, infrastructure providers, distributors, and enterprise users in Poland. Their input helps test ARPU, 5G migration, M2M demand, pricing, and rollout assumptions. It also clarifies gaps in public totals and supports reconciliation of the model before sign-off.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 15% |
| Mid tier: 48% | Functional/Unit leaders: 30% |
| Smaller Players: 25% | Managers: 55% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where national service revenue pools are reconstructed from operator reporting and regulator style market totals, and then split into service lines based on observed mix and billing structure. To avoid overcounting, bundled plans are treated carefully so that only the telecom service value is captured, followed by consistent allocation across voice, data and internet, messaging, IoT and M2M, and operator sold OTT and PayTV.
Once the totals are formed, we corroborate them with selective bottom-up approximations, such as sampled tariff checks, ARPU times subscriber counts, and enterprise contract value ranges where available. The market model uses practical inputs like mobile and fixed subscriber bases, ARPU movement, 5G coverage and adoption timing, fiber household coverage and take-up, and IoT SIM connections, which together explain why revenue shifts even when population growth is limited. For forecasting, scenario analysis is applied around price intensity, migration to higher data plans, and the timing of network investments translating into paid upgrades, and then the scenarios are aligned to expert expectations gathered in interviews. When data is missing for smaller sub-categories, the gap is handled through ratio-based estimates tied back to verified service mix so the final totals remain consistent and traceable.
Data Validation & Update Cycle
Outputs are validated through multiple checks, where modeled revenue totals are compared against independent indicators like subscriber counts, ARPU direction, and reported service mix, and then mismatches are investigated before sign-off. If a variance is driven by a one-time event such as a price reset, a major promo wave, or a regulatory change, we re-contact relevant respondents to confirm timing and impact.
A second analyst reviews the assumptions, formulas, and year-over-year movement so that unit logic stays consistent across the time series. The report is refreshed annually, and interim updates are done when material events occur, such as spectrum awards, large pricing moves, or notable network coverage changes. Before delivery, a final pass is completed to ensure the latest public releases and verified interview signals are reflected.
黑料不打烊's Poland Telecom Market Size Compared With Other Published Estimates
Published market values for Poland telecom often differ because sources do not treat bundled services, wholesale activity, and operator sold add-ons in the same way, and they also pick different base years and currencies. Differences also show up when one estimate follows nominal local currency totals and another converts to USD with a different exchange timing.
Another common gap driver is whether the value is counted for the full electronic communications sector or only for mobile network operator service revenue, which changes the addressable pool before forecasting even begins. It also matters if OTT and PayTV are included only when billed by operators, or if all standalone media spending is folded in, and how ARPU progression is assumed during heavy promotion periods.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 8.25 B (2025) | |
| Industry Regulator Bulletin A | USD 11.50 B (2025) | Uses the broader electronic communications market in nominal local currency, which can include additional fixed, infrastructure, and wholesale related revenue pools that are not limited to MNO service scope, and USD conversion timing can shift the headline. |
| Trade Journal B | USD 9.10 B (2025) | Applies simplified service mix splits and forward ARPU uplift assumptions that can overstate monetization in years with heavy discounts, and it may treat operator sold OTT and PayTV as full media spend rather than only the billed telecom-linked portion. |
The spread in the table is mainly explained by whether the number represents a broad sector total or an operator service revenue view, plus how bundles and add-ons are counted. By keeping OTT and PayTV inside the model only when it is packaged and invoiced through telecom offers and by aligning year and currency timing, the estimate stays more reproducible, which is the approach applied by 黑料不打烊.


Key Questions Answered in the Report
What is the current value of the Poland telecom MNO market?
The sector generated USD 8.64 billion in 2026.
How fast will the market grow through 2031?
L41: Revenue is projected to rise at a 4.17% CAGR to USD 10.59 billion by 2031.
Which service type earns the largest revenue share?
Data and Internet Services supplied 56.02% of 2025 turnover.
Why are enterprises critical to operator strategy?
B2B accounts pay ARPU levels up to 20 times higher than consumer handset plans.
How does spectrum policy influence rural coverage?
700 MHz licenses compel all four MNOs to deliver 120 Mbps to 99% of households by 2030.
What new pricing model disrupted competition in 2025?
T-Mobile launched a single PLN 75 unlimited mobile plan bundled with 300 Mbps fiber at no extra fee.
Page last updated on:



