
Hypermarket Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 804.88 Billion |
| Market Size (2031) | USD 908.47 Billion |
| Growth Rate (2026 - 2031) | 2.45 % |
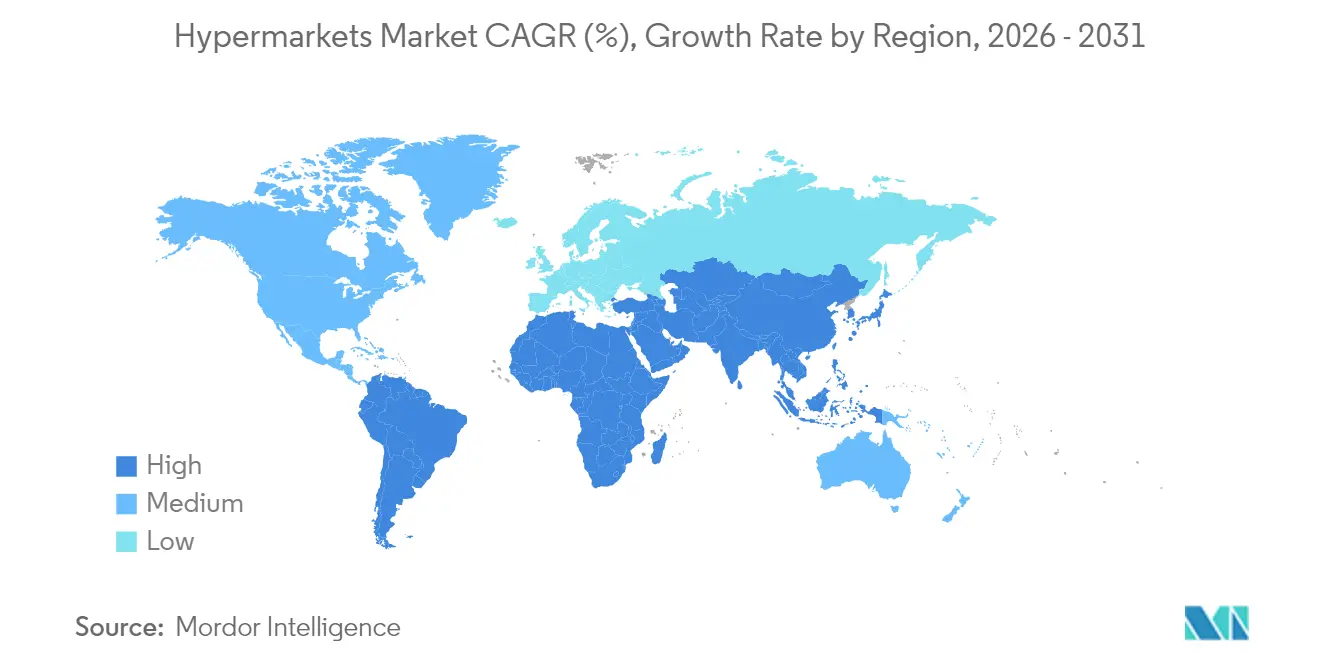
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Europe |
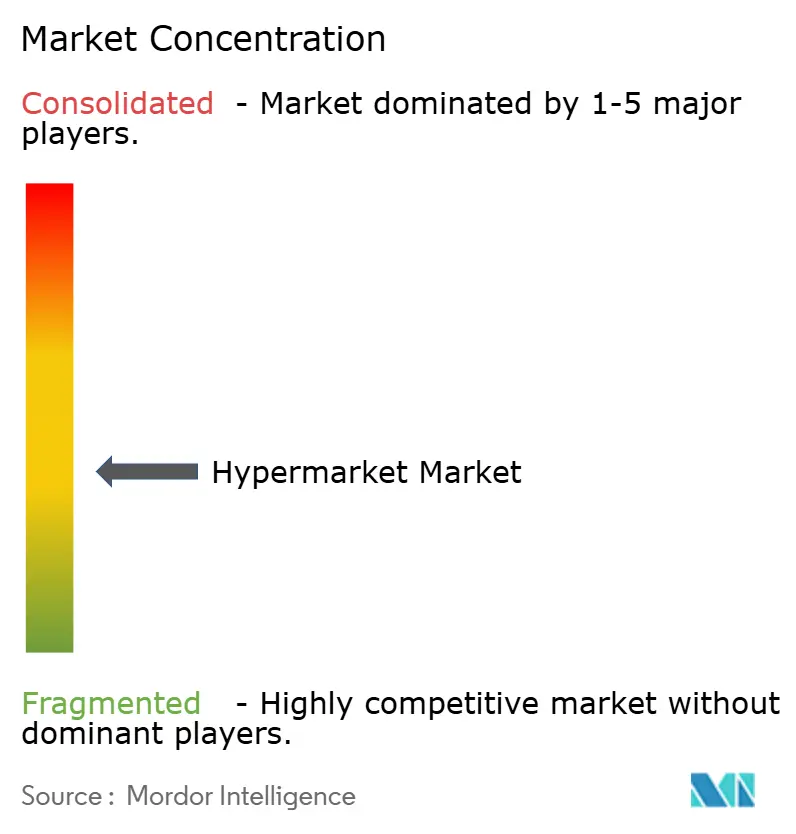
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Hypermarket Market Analysis by 黑料不打烊
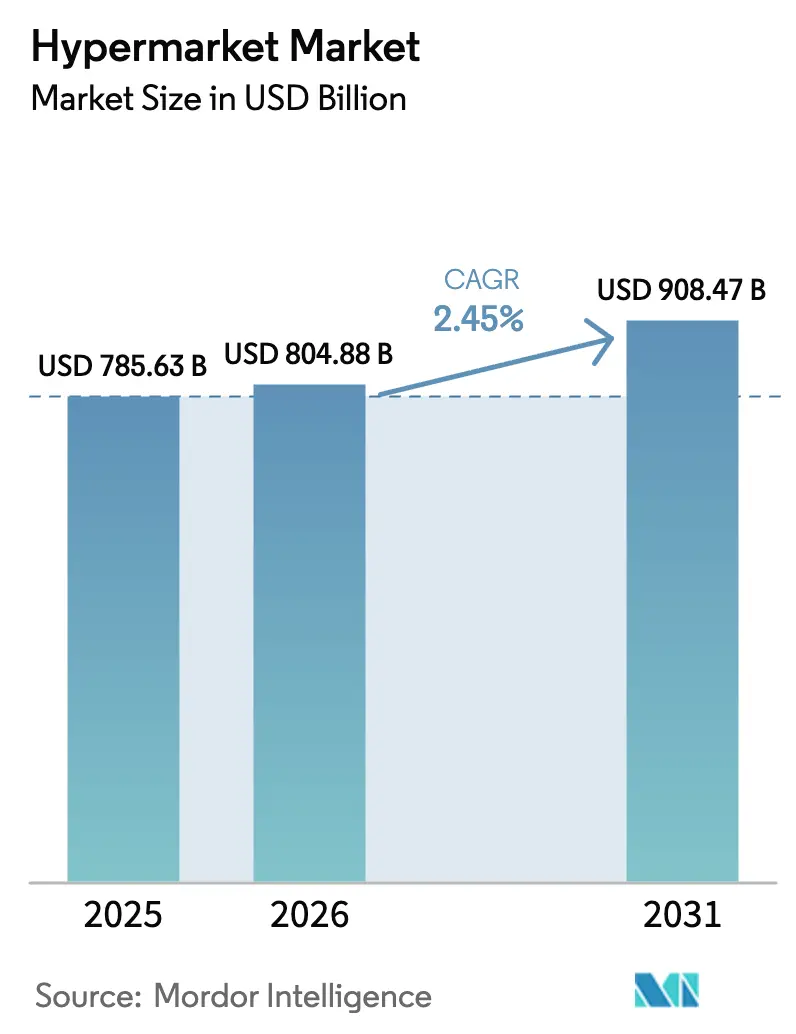
hypermarket market size in 2026 is estimated at USD 804.88 billion, growing from 2025 value of USD 785.63 billion with 2031 projections showing USD 908.47 billion, growing at 2.45% CAGR over 2026-2031. Sustained demand for one-stop shopping, investments in micro-fulfilment, and format optimisation offset competitive pressure from discount banners and pure-play e-commerce. Continuous urban migration, highlighted by the United Nations identifying Asia–Pacific as the principal contributor to global city-dweller growth, underpins new store openings [1]Source: United Nations Department of Economic and Social Affairs, “World Urbanization Prospects 2024 Revision,” un.org. . Operators also align with consumer expectations for sustainable sourcing, lower prices, and seamless omnichannel journeys that blend click-and-collect with in-store experiences. Competitive intensity nonetheless heightens as discounters enlarge footprints and zoning rules raise hurdles for new large-box projects.
Key Report Takeaways
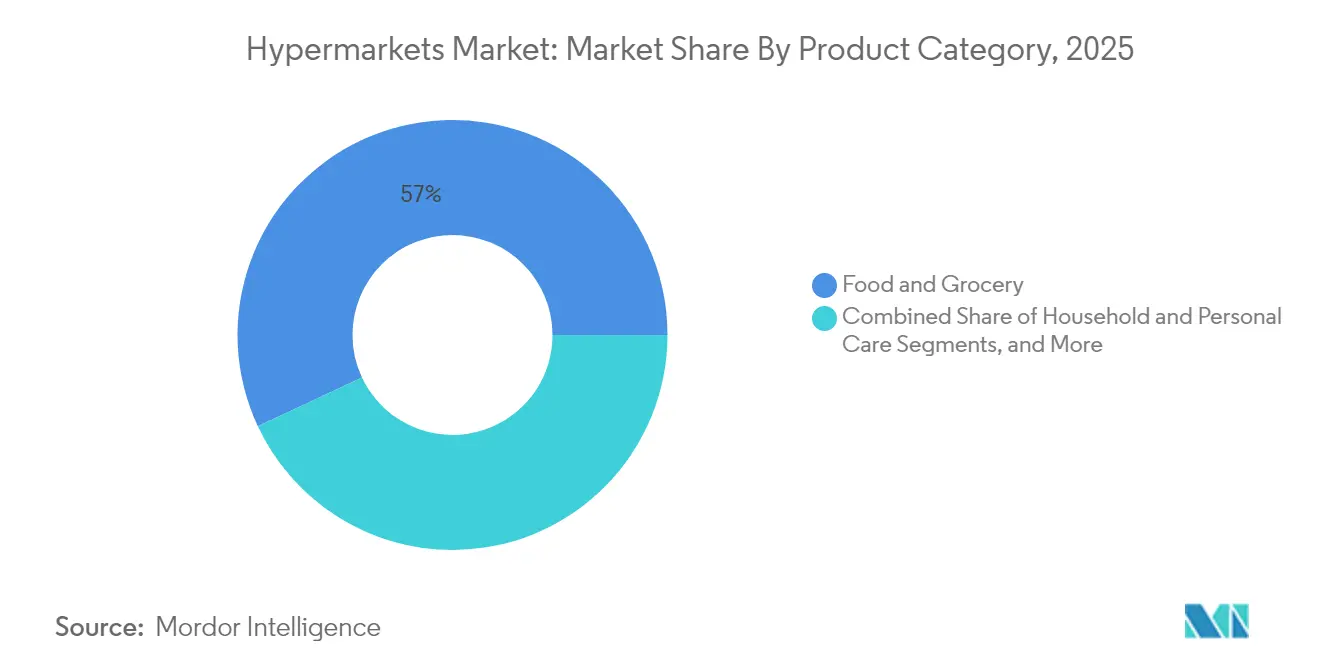
- By product category, food and grocery led with 56.98% of hypermarket market share in 2025; Consumer Electronics is projected to advance at a 6.18% CAGR through 2031.
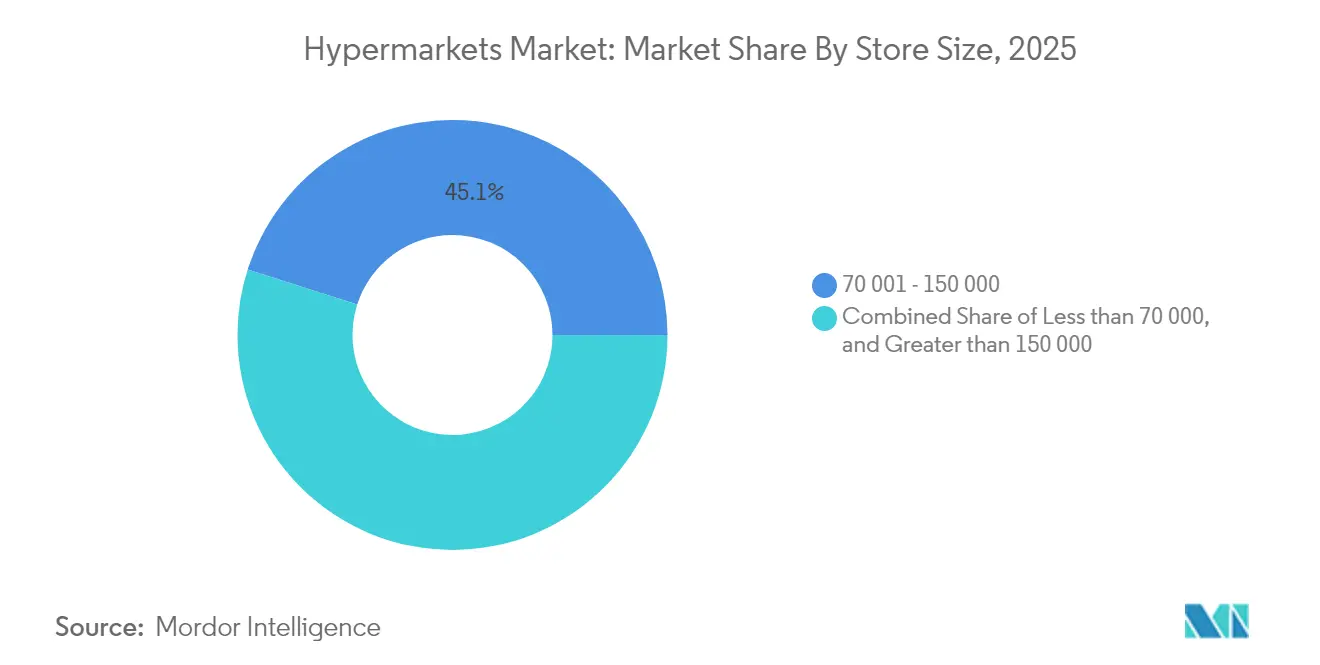
- By store size, the 70,001–150,000 sq ft format held 45.08% of the hypermarket market size in 2025, while ≤70,000 sq ft stores are poised for a 6.82% CAGR to 2031.
- By ownership model, publicly listed chains accounted for 62.56% of the hypermarket market size in 2025; franchise-operated outlets exhibit the strongest 7.34% CAGR outlook.
- By geography, Asia–Pacific captured 33.88% of the hypermarket market share in 2025, whereas the Middle East and Africa region is expected to post a 8.82% CAGR to 2031.
- Top 5 companies such as Walmart Inc., Carrefour SA, Costco Wholesale Corp., Tesco PLC, Kroger Co. hold significant market share in 2024.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Hypermarket Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Urbanization and rising disposable income | +0.8% | APAC core, spill-over to MEA | Long term (≥ 4 years) |
| Expansion of private-label FMCG ranges | +0.5% | Global, with EU leadership | Medium term (2-4 years) |
| Omnichannel and click-and-collect adoption | +0.4% | North America and EU, expanding to APAC | Short term (≤ 2 years) |
| Supply-chain digitization and automation | +0.3% | Global, led by developed markets | Medium term (2-4 years) |
| Micro-fulfilment hubs inside hypermarkets | +0.2% | Urban centers globally | Medium term (2-4 years) |
| Experiential in-store retail formats | +0.1% | Premium markets in NA, EU, APAC | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Expansion of Private-Label FMCG Ranges
Private label penetration reached 39.1% of European grocery sales in 2024, with projections indicating 40-42% by 2030, fundamentally altering hypermarket economics through improved margins and customer loyalty. Private labels boost gross margins and build loyalty, prompting hypermarket operators to dedicate shelf space and R&D budgets to store brands. High brand control lets retailers tailor pack sizes for value seekers and trial sustainable packaging that meets ESG mandates. Success hinges on robust auditing and supplier development programs, competencies that favor well-capitalized chains over smaller rivals.
Omnichannel and Click-and-Collect Adoption
In 2024, more than 80% of grocery transactions still occurred in physical stores, yet the majority of purchasing decisions were digitally influenced. Click-and-collect leverages existing store networks, trimming last-mile delivery expense while keeping margins healthier than pure delivery models. Carrefour’s online GMV reached EUR 5.9 billion in 2024, illustrating how the hypermarket market meshes physical assets with digital convenience. The approach also helps cushion footfall erosion as shoppers alternate between online baskets for bulky items and quick trips for fresh foods. The model also aligns with U.S. Department of Agriculture findings that consumers increasingly value time-saving collection services in food retail.[2]Source: U.S. Food and Drug Administration, “FSMA Section 204: Food Traceability Final Rule,” fda.gov
Micro-Fulfilment Hubs Inside Hypermarket
Carving out 10,000 sq ft for micro-fulfilment robots allows a 70,000 sq ft store to service a 15-minute delivery radius without new real estate. This re-purpose taps existing utilities, mitigates zoning hurdles, and increases inventory turns. Retailers simultaneously shorten pick times for click-and-collect orders, strengthening omnichannel propositions. However, dense automation demands stable power and advanced inventory orchestration that some legacy buildings need retrofits to support.
E-commerce Cannibalization of Footfall
Online grocery penetration has retreated from pandemic highs yet remains structurally higher than pre-2020, locking in lower footfall for hypermarket in electronics, apparel, and health-beauty aisles. Consumer surveys by industry association FMI show half of shoppers now rely on digital coupons, signaling an entrenched omnichannel mindset. Operators that fail to unify inventory visibility and pricing across channels risk losing share. Nevertheless, fresh categories still benefit from tactile inspection, providing a traffic anchor that digital-first rivals struggle to replicate.
Restraints Impact Analysis of Hypermarket Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| E-commerce cannibalization of footfall | -0.6% | Global, most acute in developed markets | Short term (≤ 2 years) |
| Discount and convenience format competition | -0.4% | Europe and North America primarily | Medium term (2-4 years) |
| Zoning shifts curbing large box builds | -0.3% | Urban centers globally, strongest in EU | Long term (≥ 4 years) |
| Sustainability-linked finance constraints | -0.2% | Global, led by ESG-focused markets | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Zoning Shifts Curbing Large-Box Builds
Municipalities increasingly favour mixed-use projects over standalone big-box venues to advance urban densification goals. For example, the European Commission’s Urban Agenda encourages compact development that can constrain hypermarket blueprints [3]Source: European Commission, “Urban Agenda for the EU – Retail in Cities,” ec.europa.eu. . Securing permits for more than 150,000 sq ft footprints thus takes longer and may impose green-building mandates that lift capex. These trends nudge expansion toward mid-format or multi-level concepts integrated with residential towers. Retailers must master space-efficient planograms and vertical logistics to preserve assortment breadth within tighter shelves.
Sustainability-Linked Finance Constraints
Green bonds and sustainability-linked loans often stipulate caps on energy intensity and food-waste ratios. Operators falling short may face higher interest spreads or reduced credit access. Capital-intensive refrigeration upgrades and renewable-energy investments become prerequisites to unlock favorable terms. Chains that already embed science-based targets enjoy financing advantages, while laggards encounter a rising cost of capital that slows refurbishment cycles and network growth.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Hypermarket Market Segment Analysis
By Product Category:
Food Dominance Amid Electronics GrowthFood and Grocery commanded 56.98% hypermarket market share in 2025 and remains the traffic linchpin that anchors weekly shopping missions. High-turnover staples secure supplier funding for promotions and guarantee footfall, although margins stay thin. Consumer Electronics recorded the swiftest 6.18% CAGR and lifts basket value when shoppers refresh smartphones, gaming consoles, or small appliances. Household and Personal Care perform steadily, buoyed by private-label rollouts that widen choice and price points. Apparel and Accessories under-index amid fashion-forward competition, while Home Appliances benefit from urban renovations and energy-efficient upgrades.
The hypermarket market calibrates space to balance frequency and profitability. Fresh produce sections occupy the front-of-store to capture immediate needs, whereas electronics and appliances reside deeper to encourage longer journeys. Vendor partnerships finance demo areas that transform stores into discovery hubs, reducing online comparison shopping. Still, original-equipment manufacturers selling direct and specialty electronics chains compress hypermarket margins, compelling chains to bolster after-sales services and bundle offers to retain share.


By Store Size:
Mid-Format Optimization Drives EfficiencyThe 70,001–150,000 sq ft bracket represented 45.08% of the hypermarket market size in 2025, reflecting a sweet spot that preserves assortment while containing utilities and labor overheads. Operators retrofit legacy giants into this range by sub-leasing unused wings or inserting micro-fulfilment pods. Smaller ≤70,000 sq ft concepts, predicted to grow 6.82% annually, capture dense urban micro-markets where real-estate premiums deter expansive builds. They rely on high inventory turnover, shrinkage controls, and digital shelf labelling to maintain economics.
Hypermarket market share for super-large boxes above 150,000 sq ft is slipping as zoning hurdles rise and shoppers favor quick missions. Yet these giants still work in commuter belts with ample parking and family clientele seeking full-basket stock-ups. Chains therefore orchestrate a hub-and-spoke model where large suburban stores act as fulfilment hubs feeding smaller urban satellites, spreading logistics costs and elevating service levels.
By Ownership Model:
Franchise Expansion Accelerates GrowthPublicly listed chains retained 62.56% hypermarket market size in 2025, debt market access and sophisticated supply chains. Franchise-operated outlets, projected to expand 7.34% annually, offer capital-light acceleration into new catchments and tap local market savvy. Cooperative banners remain relevant where community ownership underpins loyalty, while privately owned networks feel funding strain for IT and ESG retrofits.
Franchising lifts brand presence but risks execution variance. Leading chains mitigate this through centralized procurement, shared training academies, and real-time performance dashboards. Hypermarket market share gains accrue to franchisors that scale these systems effectively, converting local entrepreneurs into allies rather than competitors.
Geography Analysis
APAC Hypermarket Market
Asia–Pacific accounted for 33.88% hypermarket market share in 2025, underpinned by rapid urban migration and expanding middle-class wallets. Organized retail continues to replace informal wet markets, and governments channel infrastructure spending toward suburban ring roads that improve hypermarket accessibility. Retail property research shows that Chinese retail transaction volumes held firm even as other commercial sectors softened, an indicator of sector resilience. Operators must still navigate provincial regulations and fragmented supplier bases, spurring partnerships with local distributors to ensure consistent product flow.
MEA Hypermarket Market
The Middle East and Africa region is set to deliver a 8.82% CAGR by 2031, the fastest globally. Economic diversification programs in Gulf Cooperation Council states nurture modern trade, while young demographics gravitate to international grocery standards. The UAE commands a USD 40 billion grocery sector, and Saudi Arabia stands at USD 62 billion, providing scale for hypermarket entrants. Franchise structures and joint ventures ease regulatory entry, as illustrated by regional players listing domestically to fund expansions. Yet import dependency exposes margins to currency volatility and global supply disruptions, making resilient procurement strategies essential.
North America and Europe Hypermarket Market
North America and Europe register modest growth as markets mature. Private-label penetration deepens and sustainability regulations tighten, pushing chains toward energy-saving refrigeration and food-waste analytics. Discounter presence is entrenched in Germany, the Netherlands, and increasingly the United States where Aldi surpassed 2,400 stores in 2024. Hypermarkets respond with store refurbishments, fresh-food theatre, and loyalty app upgrades to preserve share. While hypermarket market growth is slower, the regions remain profitable due to higher basket values and established supply chains.

Regulatory Landscape
Hypermarkets face a patchwork of competition, consumer-protection, and trade-compliance rules that affects assortment, pricing, and consolidation options. In the United States, heightened antitrust scrutiny has increased review intensity for large grocery combinations, which affects how national chains structure deals and divestitures and raises execution risk for scale-driven strategies.
Cross-border and supply-chain compliance requirements are tightening for low-value and fast-moving retail flows. This is reinforcing the need for stronger import filing, documentation, and supplier-data governance. In the European Union, Import Control System 2 (ICS2) Phase 3 enforcement from June 1, 2026 expanded Entry Summary Declaration requirements for low-value postal shipments, while Canada updated its Supply Chains Act reporting guidance in late December 2025 ahead of the May 31, 2026 filing deadline, increasing the compliance workload for large retailers and their private-label supplier networks.
Value Chain Analysis
The hypermarket value chain starts with branded and private-label manufacturers and runs through global and regional importers, wholesalers, and direct-to-retailer sourcing, ending at retailer distribution centers and stores that function as both shopping destinations and omnichannel nodes. Upstream, private-label programs depend on supplier qualification, auditing, packaging development, and demand planning, while fresh categories add cold-chain handling and rapid replenishment requirements; downstream, store execution (replenishment, shrink control, checkout, and labor scheduling) remains a key profit lever.
Digitization is increasingly the link across procurement, logistics, and store execution, with retailers adopting interoperable data standards to align with customs processes and e-invoicing requirements and improve end-to-end traceability. On the execution side, electronic shelf labels, AI-assisted forecasting, and self-checkout shorten the cycle time from price changes to shelf availability, while micro-fulfilment or micro-picking shifts parts of distribution into the store, linking last-mile performance to in-store inventory accuracy and planogram discipline.
Competitive Landscape
The hypermarket market is moderately concentrated. Walmart leads with USD 676 billion revenue and 10,692 outlets across 27 nations, wielding data-driven replenishment and a rapidly scaling marketplace for third-party sellers. Carrefour ranks among the top European players, blending hypermarkets, convenience stores, and an expanding digital ecosystem. In Asia–Pacific, Aeon, Reliance Retail, and CP-All harness local logistics to defend domestic turf.
Strategic focus gravitates to technology and sustainability. Chains plan quadruple jumps in AI spending to unlock USD 113 billion in efficiencies, covering areas from predictive ordering to dynamic staffing. Discounters Aldi and Lidl captured 38% of German grocery sales in 2024, proving that streamlined ranges and aggressive pricing resonate with value-driven shoppers. Hypermarkets counter with tiered private-label architectures, self-checkout expansion, and renewable energy rollouts that cut operating costs.
White-space growth lies in urban micro-formats paired with same-day fulfilment. Operators retrofit underused parking lots for drive-thru pick-up lanes or solar canopies that lower utility bills. Acquisitions also shape the landscape: Auchan Retail and Groupement Les Mousquetaires acquired 313 French stores from Casino Group in March 2025 for EUR 1.35 billion, cementing national scale. Competitive success therefore hinges on capital access, digital agility, and the capacity to embed ESG into day-to-day operations.
Hypermarket Industry Leaders
Walmart Inc.
Carrefour SA
Costco Wholesale Corp
Tesco PLC
Kroger Co.
- *Disclaimer: Major Players sorted in no particular order
Hypermarket Market Companies Covered in this Report
- Walmart Inc.
- Carrefour SA
- Costco Wholesale Corp.
- Tesco PLC
- Kroger Co.
- Auchan Retail
- Aldi Sud & Aldi Nord
- Target Corp.
- E.Leclerc
- Lidl (Schwarz Gruppe)
- Intermarche (Les Mousquetaires)
- Coop Schweiz
- Woolworths Group (AU)
- Coles Group
- Mercadona SA
- J Sainsbury PLC
- Migros-Genossenschafts-Bund
- Grupo Cencosud
- Falabella (Tottus)
- SMU SA (Unimarc)
- X5 Retail Group
- Lotte Mart
- Lulu Hypermarket
- Soriana*

Market Opportunities and Future Outlook
Capital reallocation toward store modernization and digital operating models is creating whitespace for vendors and partners focused on automation, pricing, and omnichannel execution. Carrefour's February 2026 2030 Strategic Plan set a higher annual investment budget by 2030 (from EUR 1.8 billion to EUR 2.0 billion), with priorities spanning AI, data, and store modernization, and the group committed more than EUR 150 million with Vusion to deploy electronic shelf labels and related connected in-store infrastructure in France. This supports demand for at-scale rollout capabilities and the integration services needed to operationalize those systems.
Omnichannel economics are increasingly shaped by the need to make stores more productive fulfilment nodes, not just shopping floors. Walmart reaching profitability in its US e-commerce business in 2025 is a concrete signal that store-linked picking, click-and-collect, and tighter inventory visibility across channels remain central. At the same time, footprint rationalization in select non-core European markets, alongside franchised entry into new countries, points to an opportunity set around capital-light expansion models, localized assortments, and compliant cross-border sourcing for private label and general merchandise.
Recent Industry Developments in Hypermarket Market
- July 2026: The Kroger Co. announced a definitive agreement to acquire Giant Eagle for USD 1.65 billion, covering 197 supermarkets and 11 standalone pharmacies. The deal expands Kroger's regional scale and adds pharmacy assets that strengthen traffic drivers and basket-building categories. Larger combined procurement and distribution density can improve private-label economics and omnichannel service levels where the banners overlap.
- February 2026: Carrefour announced the start of exclusive negotiations with Paval Holding Group for the disposal of Carrefour Romania. This reflects portfolio rationalization and a focus on allocating capital to priority markets and formats. It also signals continued reshaping of large-box networks in Europe as operators balance returns, capex needs, and competitive intensity.
- July 2024: Carrefour finalized the acquisition of Cora and Match in France. This transaction expanded Carrefour's store base and reinforced national scale in a core European market. Integration of stores and supply chains can lift purchasing leverage and accelerate modernization programs across the enlarged network.


Hypermarket Market Report Scope and Research Methodology
Market Definition and Coverage
For this methodology, the hypermarkets market is defined as the yearly value of retail sales generated by large-format stores that combine full grocery with a broad non-food assortment, sold through physical stores and their linked order-fulfillment options.
Scope exclusions: Pure-play e-commerce retailers without a hypermarket store base, and traditional small-format convenience outlets, are not counted as hypermarkets.
Segments Covered in This Report
- By Product Category
- Food and Grocery
- Household and Personal Care
- Apparel and Accessories
- Consumer Electronics
- Home Appliances
- Other General Merchandise
- By Store Size
- Less than 70 000
- 70 001 - 150 000
- Greater than 150 000
- By Ownership Model
- Publicly-Listed Chains
- Cooperative Chains
- Privately-Owned Chains
- Franchise-Operated
- Joint-Ventures
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the model structure and keep assumptions grounded in public signals. We relied on widely available references such as national statistics offices and central banks, plus World Bank materials, UN DESA urbanization releases, and OECD consumer indicators to understand demand conditions and inflation effects that feed into retail spending.
On the industry side, we reviewed public filings and investor presentations of listed retailers, along with retail and grocery association publications and trade press coverage, to track format expansion, shifts in assortment, and omnichannel adoption. For cross-checks, we also used paid subscriptions for company financials and intelligence, plus news and financials coverage, and an import-export shipment-level database to sense-check non-food category momentum in selected markets. The desk research sources cited are illustrative only, and multiple other public and paid references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and structured surveys with retail executives, category managers, and store operations leaders, plus logistics and real estate stakeholders who track store expansion and footfall patterns. We used these discussions to confirm spend splits between food and non-food, typical category-level price moves, and the pace of services like click-and-collect, where the fulfillment flow still originates from hypermarket store networks across APAC, EMEA, and the Americas.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 14% | APAC: 43% |
| Mid tier: 51% | Functional/Unit leaders: 26% | EMEA: 36% |
| Smaller Players: 14% | Managers: 60% | Americas: 21% |
Market-Sizing & Forecasting
Market sizing was built using a top-down and bottom-up blend, so the totals remain anchored to realistic demand pools. The top-down path starts from country-level retail and grocery spending series, then adjusts for the share of large-format hypermarket activity using store footprint indicators, urbanization patterns, and format penetration inputs that were discussed in interviews.
To corroborate the totals, we added selective bottom-up checks from sampled retailer revenues, store counts, and a price times volume view for a few high-weight categories where public data is easier to track. Inputs that carried the most weight included consumer price inflation, changes in food versus non-food mix, store opening and closure activity, average selling price movement in key baskets, and the share of sales supported by store-linked fulfillment (such as click-and-collect). Where bottom-up inputs were limited for private retailers or in smaller countries, we used peer market proxies that were reviewed with local experts before being applied.
Forecasting was done using scenario analysis supported by a light multivariate regression, linking growth to drivers such as disposable income trends, inflation easing or persistence, and the expected pace of store network optimization. Assumptions were tightened after rechecking with primary respondents, especially where macro conditions shift quickly and can change discretionary non-food spending.
Data Validation & Update Cycle
Validation is handled through step-by-step cross-checks rather than a single pass. We compare model outputs with independent signals such as retail sales indices, consumer sentiment, and observed format expansion plans, and then investigate variances before final sign-off.
When anomalies appear, such as a sudden jump that does not align with macro indicators or store network moves, we re-open the assumption sheet and re-contact selected interviewees to confirm whether a one-off factor is in play. Reports are refreshed annually, with interim updates when material events occur, including sharp inflation changes, major regulatory shifts affecting large-box stores, or meaningful changes in retailer expansion activity. Before delivery, an analyst performs a fresh review of the latest releases so clients receive an updated and consistent view.
黑料不打烊's Hypermarkets Market Size Compared Against Other Published Estimates
Published market sizes for hypermarkets can look far apart because the term "hypermarket" is used differently across studies, and because some models blend in nearby retail formats. Variations also come from how inflation is treated, which year is used for currency conversion, and whether online fulfillment linked to physical stores is counted in a consistent way.
The main gap comes from format scope, where 黑料不打烊 counts only hypermarket-format retail sales and keeps warehouse clubs and broader supermarket totals outside the number, even when a retailer operates these under the same parent group. Another spread driver is pricing logic, since some estimates apply a single global inflation uplift, while our model uses country-level inflation and category mix checks so food-heavy baskets do not overstate non-food growth during high-inflation periods.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 804.88 B (2026) | |
| Trade Journal A | USD 776.56 B (2024) | Uses an earlier base year and is distributed as a paid announcement, with limited visibility on how store-linked fulfillment, inflation, and exchange-rate timing are applied across countries. |
| Global Consultancy B | USD 790.00 B (2024) | Broadens the format set by including warehouse clubs under the same label, which can lift totals, and the approach appears more format-blended than a hypermarket-only revenue view. |
The comparison shows that scope choices and the treatment of inflation and currency timing can shift the result by tens of billions. By keeping the sizing steps traceable to observable retail spending signals and to store-format definitions checked with industry participants, the final number is easier to explain and to reproduce when new data is released.


Key Questions Answered in the Report
What is the current size of the hypermarket market?
The hypermarket market generated USD 804.88 billion in 2026 and is forecast to rise to USD 908.47 billion by 2031.
Which region leads the hypermarket market?
Asia–Pacific holds the largest regional position with 33.88% market share, driven by urbanization and rising disposable incomes.
Which product category dominates hypermarket sales?
Food and Grocery command 56.98% of sales, acting as the primary traffic driver for weekly shopping trips.
What store format is growing the fastest?
Smaller hypermarkets of ≤70,000 sq ft are projected to expand at a 6.82% CAGR, benefiting from urban real-estate constraints and convenience demand.
How are hypermarkets responding to e-commerce competition?
Chains are integrating click-and-collect, investing in micro-fulfilment, and expanding private-label offerings to retain shoppers and protect margins.
Why is franchising gaining importance in the hypermarket market?
Franchise structures allow rapid geographic growth with lower capital outlays, translating into a 7.34% CAGR forecast for franchise-operated stores by 2031.
Page last updated on:



