
United States Hardware Stores Retail Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
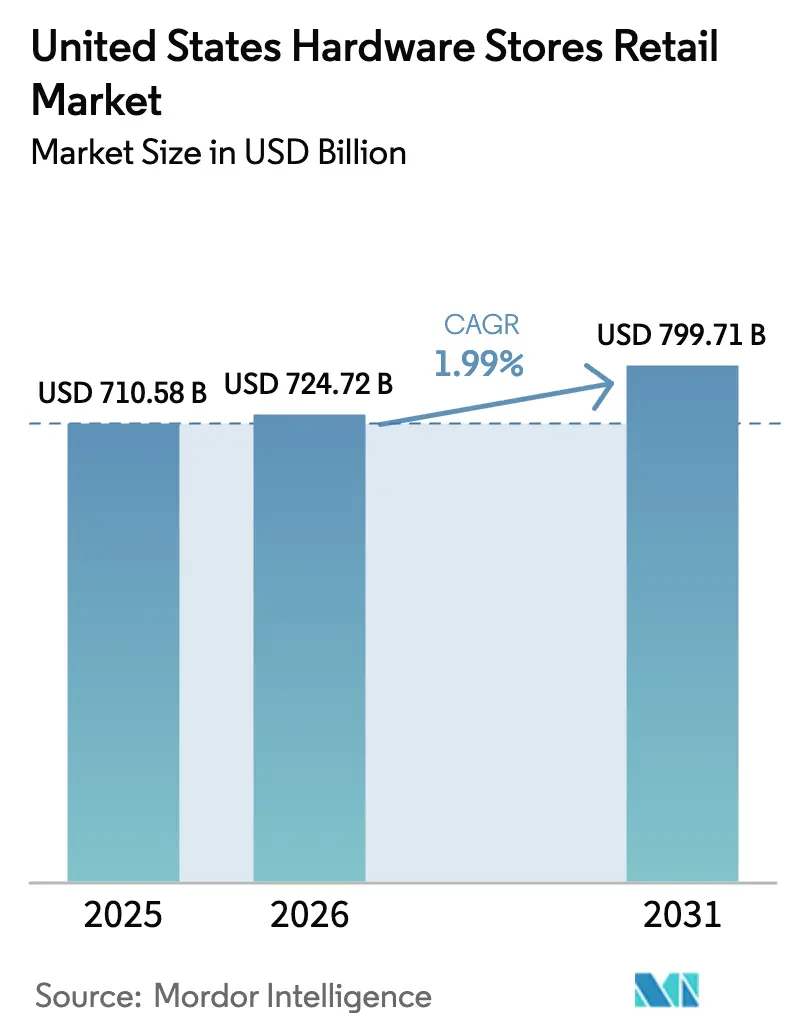
| Base Year Market Size (2025) | USD 710.58 Billion |
| Market Size (2026) | USD 724.72 Billion |
| Market Size (2031) | USD 799.71 Billion |
| Growth Rate (2026 - 2031) | 1.99 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
United States Hardware Stores Retail Market Analysis by 黑料不打烊
The United States hardware stores retail market size in 2026 is estimated at USD 724.72 billion, growing from 2025 value of USD 710.58 billion with 2031 projections showing USD 799.71 billion, growing at 1.99% CAGR over 2026-2031. Renovation spending outpaces new‐build activity as elevated mortgage rates convince many homeowners to remodel rather than relocate, channelling discretionary dollars toward big-ticket kitchen, bathroom, and energy-efficiency upgrades. Population gains in the South, wildfire-resilience mandates in the West, and expanding energy codes nationwide keep baseline demand intact even when broader construction indicators soften[1]“Home Building Geography Index,” National Association of Home Builders, nahb.org. . Large retailers leverage scale to lock in commodity supply and pass along price fluctuations more effectively than independents, while social-media-fueled DIY trends support weekend traffic and higher-margin impulse purchases. The United States hardware stores retail market benefits from a dual engine of professional contractor demand and consumer-driven projects that together mute cyclical volatility.
Key Report Takeaways
- By product type, building materials led with 36.05% of the United States hardware stores retail market share in 2025; Smart-Home Hardware is projected to expand at a 10.03% CAGR through 2031.
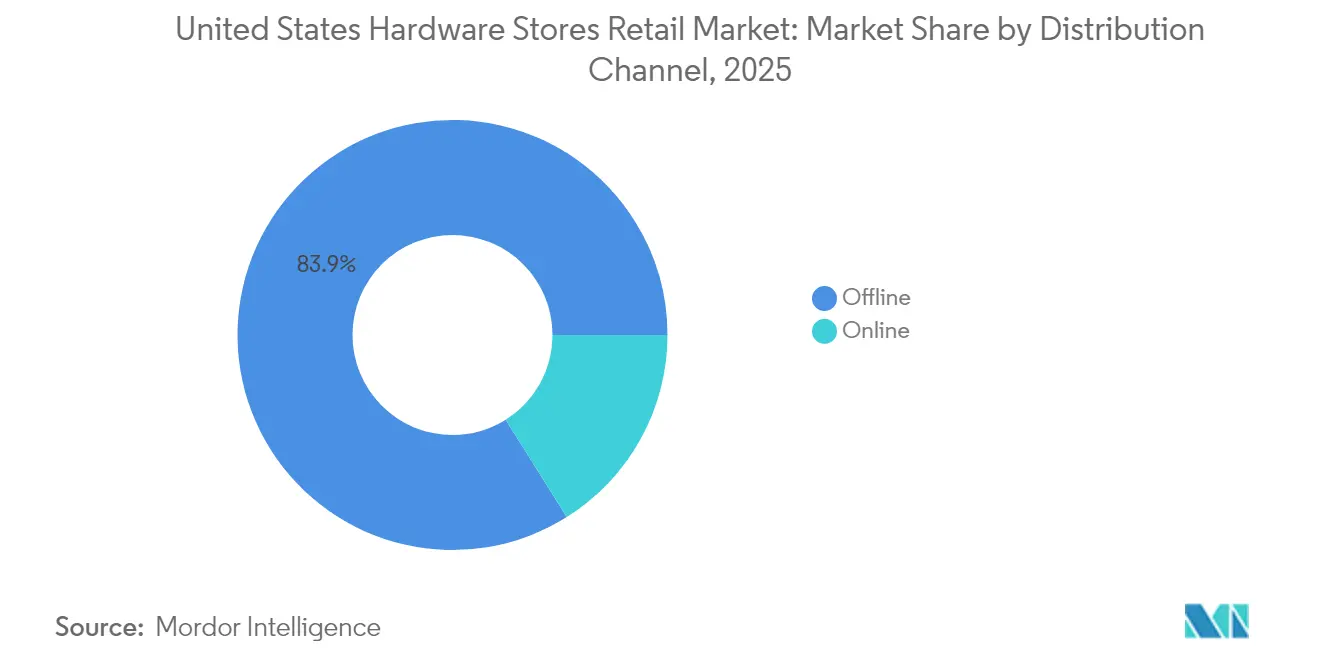
- By distribution channel, offline outlets accounted for 83.92% of the United States hardware stores retail market size in 2025, while online sales are rising at a 13.42% CAGR to 2031.
- By store format, big-box home centers captured 58.88% share of the United States hardware stores retail market size in 2025; online-only platforms recorded the quickest growth at an 11.05% CAGR.
- By region, the South commanded 34.12% of the United States hardware stores retail market share in 2025, whereas the West is advancing at a 6.9% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
United States Hardware Stores Retail Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Big-ticket home-renovation boom post-2024 | +0.8% | National, concentrated in high home-equity markets | Medium term (2-4 years) |
| DIY culture amplified by social-media tutorials | +0.4% | National, stronger in younger demographics | Short term (≤ 2 years) |
| Energy-efficient building code updates | +0.3% | National, led by California and Northeast states | Long term (≥ 4 years) |
| Rapid wildfire-resilient construction mandates | +0.2% | West Coast, expanding to Mountain states | Medium term (2-4 years) |
| Aging-in-place retrofits for seniors | +0.2% | National, concentrated in established suburbs | Long term (≥ 4 years) |
| Insurance-driven demand for fortified roofs | +0.1% | Gulf Coast, Southeast, expanding nationally | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Big-Ticket Home-Renovation Boom Post-2024
Elevated mortgage rates averaging 6.5% through 2024 have fundamentally altered homeowner behaviour, creating a captive audience for renovation projects as moving becomes financially prohibitive[2]“U.S. Economic, Housing and Mortgage Outlook,” Freddie Mac, freddiemac.com. . This rate environment has generated what industry analysts term "mortgage rate lock-in," where homeowners with sub-4% rates from 2020-2021 defer selling, redirecting discretionary spending toward home improvements instead. The Joint Center for Housing Studies projects renovation spending will reach USD 509 billion in 2025, representing a 6.4% upward revision from earlier forecasts. Kitchen and bathroom upgrades dominate this spending surge, with homeowners increasingly viewing these projects as long-term investments rather than discretionary expenses. The trend particularly benefits hardware retailers through higher average transaction values and increased frequency of professional-grade product purchases.
DIY Culture Amplified by Social-Media Tutorials
Social media platforms have democratized home improvement knowledge, with YouTube and TikTok tutorials generating unprecedented confidence among novice DIY enthusiasts, particularly millennials and Gen Z homeowners. This cultural shift represents more than entertainment it translates directly into retail sales as tutorial viewers purchase materials and tools to replicate projects they observe online. The phenomenon has created viral trends around specific techniques and products, driving sudden demand spikes that challenge traditional inventory planning. Hardware retailers report increased sales of specialty tools and materials previously reserved for professional contractors, as social media content normalizes complex projects. The trend extends beyond individual projects to encompass broader lifestyle aspirations, where DIY capability signals personal competence and financial savvy. Retailers increasingly partner with social media influencers and create their own content to capture this audience, recognizing that digital engagement often precedes physical store visits.
Energy-Efficient Building Code Updates
The 2024 International Energy Conservation Code (IECC) implementation across multiple states has created mandatory demand for energy-efficient building materials, insulation systems, and HVAC components that meet stricter performance standards. These regulatory changes operate differently from market-driven trends they create non-negotiable compliance requirements that sustain demand regardless of economic conditions. California's Title 24 updates and similar state-level initiatives have established precedents that other jurisdictions follow, creating predictable waves of regulatory adoption. The codes particularly benefit hardware retailers through increased sales of high-performance insulation, energy-efficient windows, and smart building controls that command premium pricing. Professional contractors increasingly rely on retail channels to source compliant materials quickly, as project timelines compress under regulatory deadlines. The trend accelerates as federal tax credits align with state building codes, creating dual incentives for energy-efficient upgrades that hardware retailers are positioned to fulfil.
Rapid Wildfire-Resilient Construction Mandates
Western states have implemented increasingly stringent wildfire-resistant construction requirements, creating specialized demand for fire-rated roofing materials, ember-resistant vents, and defensible space landscaping products [3]“ISO Wildfire-Mitigation Rules,” Verisk Analytics, verisk.com. . California's Chapter 7A requirements and similar Oregon mandates represent regulatory responses to escalating wildfire losses that now exceed USD 57 billion annually in insured damages. These regulations create captive markets for specialized products that traditional hardware stores previously stocked minimally, forcing rapid assortment expansion and supplier relationship development. The mandates extend beyond new construction to encompass retrofits in high-risk zones, generating recurring revenue streams as existing structures require compliance upgrades. Insurance companies increasingly require wildfire-resistant features for policy renewals, creating additional market pressure beyond regulatory compliance.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Pro-contractor consolidation bypassing retail | -0.4% | National, strongest in commercial construction markets | Long term (≥ 4 years) |
| Volatile lumber & steel pricing | -0.3% | National, acute in import-dependent regions | Short term (≤ 2 years) |
| Skilled-labor shortages slowing DIY completions (under-the-radar) | -0.2% | Tier-2/3 cities and suburban areas | Medium term (2–4 years) |
| Rising retail crime/shrink rates on small hardware items (under-the-radar) | -0.2% | Urban centers and high-footfall retail zones | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Pro-Contractor Consolidation Bypassing Retail
Large-scale professional contractors increasingly establish direct relationships with manufacturers and distributors, circumventing traditional retail channels to secure volume pricing and guaranteed supply allocation. This trend accelerates as contractor consolidation creates entities with sufficient scale to negotiate manufacturer-direct terms previously reserved for major retailers. The shift particularly impacts high-volume, low-margin products where contractors can achieve 15-25% cost savings through direct sourcing arrangements. Regional contractor networks and buying cooperatives further amplify this trend, pooling smaller operators' purchasing power to access wholesale pricing. Hardware retailers respond by emphasizing value-added services, specialized products, and emergency availability that direct channels cannot replicate, but the structural shift toward disintermediation remains a persistent headwind for traditional retail models.
Volatile Lumber & Steel Pricing
Commodity price volatility, exacerbated by tariff policies and supply chain disruptions, creates planning challenges that compress retailer margins and deter large project commitments from price-sensitive customers. Steel prices increased 15-25% and lumber rose 17.2% year-over-year through early 2025, driven by tariff implementations and retaliatory trade measures. These price swings create inventory valuation challenges for retailers, who must balance carrying costs against stockout risks while maintaining competitive pricing. Professional contractors increasingly demand fixed-price quotes with extended validity periods, transferring price risk to retailers who lack manufacturers' hedging capabilities. The volatility particularly impacts project-based sales, where material cost uncertainty can delay or cancel large renovations, reducing both immediate revenue and future maintenance-related purchases.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Building Materials Drive Core Demand
Building Materials commanded 36.05% market share in 2025, reflecting their fundamental role in both new construction and renovation projects across residential and commercial applications. This segment's dominance stems from recurring replacement cycles and regulatory compliance requirements that sustain baseline demand regardless of economic conditions. Smart-Home Hardware emerges as the fastest-growing segment at 10.03% CAGR through 2031, driven by consumer adoption of connected devices and integration with home automation systems. Door Hardware maintains steady demand through security upgrade cycles and aesthetic renovation trends, while Kitchen and Toilet Products benefit from bathroom and kitchen remodeling projects that represent the highest-value home improvement categories.
The segment's evolution reflects broader technological integration, where traditional hardware increasingly incorporates smart features and connectivity options that command premium pricing. Lowe's partnership with OpenAI for its "Mylow" AI advisor demonstrates how retailers leverage technology to guide product selection and cross-selling within this category. Other Product Types capture specialized applications and emerging categories that don't fit traditional classifications, representing innovation opportunities for retailers willing to experiment with new product lines and supplier relationships.


By Distribution Channel: Offline Dominance Faces Digital Disruption
Offline channels maintained 83.92% market share in 2025, demonstrating the enduring importance of physical touchpoints for product evaluation, immediate availability, and professional contractor relationships. This dominance reflects hardware retail's tactile nature, where customers need to assess product quality, compatibility, and specifications before making purchase decisions. However, Online channels accelerate at a 13.42% CAGR through 2031, driven by convenience, expanded product assortments, and improved logistics capabilities that reduce delivery times for urgent projects. The online growth particularly benefits specialized products and hard-to-find items that physical stores cannot economically stock. Successful retailers increasingly adopt omnichannel strategies that blur traditional distribution boundaries, offering services like buy-online-pickup-in-store, curbside delivery, and virtual consultations that combine digital convenience with physical fulfillment. Home Depot's investment in supply chain automation and Lowe's Total Home Strategy exemplify how major players integrate digital and physical capabilities to capture growth across both channels while defending against pure-play online competitors.
By Store Format: Big-Box Efficiency Versus Specialized Service
Big-Box Home Centers captured 58.88% market share in 2025, leveraging their vast product assortments, competitive pricing, and integrated professional services to dominate both DIY and contractor segments. These formats benefit from economies of scale in purchasing, logistics, and marketing that smaller competitors cannot match, while their size enables comprehensive one-stop shopping experiences that reduce customer acquisition costs. Online-Only Platforms represent the fastest-growing format at 11.05% CAGR through 2031, targeting specialized needs and niche products that physical stores cannot economically serve. Traditional Hardware Stores and Lumber & Building-Material Yards maintain relevance through personalized service, local market knowledge, and specialized expertise that big-box formats struggle to replicate consistently. The format evolution reflects changing customer expectations, where convenience and expertise matter more than pure price competition. Farm & Ranch Supply Stores and Warehouse Clubs serve distinct customer segments with tailored assortments and service models, while the recent consolidation of True Value and Do it Best demonstrates how smaller formats must achieve scale to remain competitive.
Geography Analysis
The South's market leadership at 34.12% share in 2025 reflects sustained demographic and economic advantages that create durable demand for hardware retail across both residential and commercial applications. Population growth in states like Texas, Florida, and North Carolina drives new construction activity that generates contractor purchases and subsequent homeowner maintenance needs. The region's business-friendly regulatory environment and lower construction costs attract both residents and businesses, creating multiplier effects that sustain hardware demand across economic cycles. Hurricane preparedness requirements increasingly drive specialized product demand, with insurance companies offering 20-55% premium discounts for FORTIFIED construction standards that require specific materials and installation techniques.
The West's 6.9% CAGR through 2031 reflects unique regulatory and demographic drivers that create premium product opportunities despite slower construction activity. California's stringent building codes and wildfire regulations mandate specialized materials that command higher margins, while high home values justify expensive retrofit projects that generate substantial per-transaction revenue. The region's technology adoption leadership creates early-mover advantages for smart home products and connected building systems that eventually expand to other markets. Aging-in-place demographics particularly impact Western markets, where high housing costs encourage seniors to retrofit existing homes rather than relocate, driving demand for accessibility modifications and safety equipment.
The Northeast and Midwest maintain steady demand through renovation cycles and infrastructure replacement needs, with older housing stock requiring more frequent maintenance interventions than newer construction in growth regions. These markets emphasize energy efficiency upgrades and weatherization projects that align with state-level climate initiatives and utility rebate programs. Regional construction activity data shows the Middle Atlantic division recording 22% year-over-year growth in single-family starts during 2024, indicating pockets of strength that support localized hardware demand despite broader market maturity.
Regulatory Landscape
Regulation shaping the United States hardware stores retail market cuts across building-energy and resilience codes, product safety requirements, and new compliance expectations for connected and electronic products sold through both stores and e-commerce. Adoption of the 2024 International Energy Conservation Code (IECC) across states, alongside California Title 24, increases baseline requirements for insulation, windows, HVAC-related components, and smart controls that retailers stock for DIY and Pro customers. In the West, wildfire-resilient construction rules (for example, California Chapter 7A) also influence assortment decisions for fire-rated and ember-resistant products.
On the product and digital side, the Consumer Product Safety Act framework and OSHA-recognized Nationally Recognized Testing Laboratories (NRTLs) such as UL, ETL, and CSA affect retailer gatekeeping for electrical and jobsite products, shaping vendor qualification and private-label programs. For smart-home and IoT-adjacent hardware, NIST IR 8259 Rev. 1 (April 2026) provides a widely referenced baseline for IoT cybersecurity capabilities, and the FCC Cyber Trust Mark program (with ioXt Alliance named Lead Administrator in July 2026) establishes a recognized labeling pathway that can influence how connected devices are selected, merchandised, and verified across online and offline channels. In parallel, industry bodies such as the National Retail Federation (NRF) and NLBMDA have elevated organized retail crime and policy topics in 2026 agendas, increasing compliance attention on loss prevention and supply-chain integrity for high-shrink categories common in hardware retail.
Value Chain Analysis
The value chain begins with manufacturers and brand owners, covering tools, fasteners, electrical categories, building materials, and connected devices. It then extends through importers and distributors, including cooperatives and specialty building-products distributors, before reaching retailer-controlled distribution networks that support store operations, job sites, and direct-to-consumer delivery. Large chains increasingly route volume through company-operated fulfillment and flatbed networks for bulky building materials, while independents more often depend on cooperative distribution and regional wholesalers to broaden assortment and manage replenishment cadence.
Retail execution is increasingly shaped by data, compliance, and service-layer logistics. AI-supported inventory and replenishment systems and ship-from-location decisions are being adopted to balance in-stock performance with delivery speed, reflecting a shift from vendor-to-store shipping toward retailer-orchestrated fulfillment. On the demand side, Pro workflows, including material list building, scheduling, and repeat ordering based on historical purchases, strengthen ties between contractors and retailers. At the same time, product safety and certification requirements, including NRTL listings for electrical and certain jobsite products, create formal checkpoints that affect onboarding, merchandising, and returns management for regulated categories sold through both stores and online listings.
Competitive Landscape
The United States hardware retail market is deeply consolidated, with a small number of dominant players controlling the majority of industry revenue. This concentrated structure creates significant barriers to entry, making it difficult for smaller or new entrants to compete effectively. Larger retailers benefit from economies of scale in areas such as procurement, logistics, and digital investments, giving them a sustained competitive edge. These advantages are hard for independent or regional players to replicate. As a result, market leaders are shifting focus toward serving professional contractors and B2B customers, who typically generate higher-value transactions and more consistent demand than the DIY segment.
Strategic consolidation is gaining momentum as companies opt for acquisitions over organic growth to expand their capabilities and market presence. A notable example is Home Depot’s USD 18.25 billion acquisition of SRS Distribution, which strengthens its position in the professional contractor supply chain. This move supports vertical integration by linking wholesale distribution with retail operations. At the same time, technology adoption is becoming a major differentiator among top players. Lowe’s partnerships with OpenAI and NVIDIA are helping it deliver tailored shopping experiences and proactive maintenance solutions, increasing customer loyalty and operational efficiency.
New growth opportunities are also emerging in specialized niches that are less dependent on scale and more on localized expertise. Segments such as aging-in-place home modifications, smart home installation services, and regional contractor marketplaces offer room for innovation. These areas require service depth and customization, playing to the strengths of firms that can adapt to specific customer needs. Unlike the traditional big-box model, success here relies on a blend of service capabilities and local market knowledge. As consumer expectations evolve, these white-space areas are expected to become key growth drivers in the next phase of the market.
United States Hardware Stores Retail Industry Leaders
The Home Depot
Lowe’s Companies, Inc.
Menards
Ace Hardware Corp.
True Value Co.
- *Disclaimer: Major Players sorted in no particular order


Market Opportunities and Future Outlook
Service-led differentiation for Pro customers is a key whitespace, particularly where retailers connect quoting, scheduling, and delivery execution into a single workflow. In 2026, named initiatives show this direction: Lowe's launched an AI-driven Material Lists capability for Pro customers to turn project notes and files into product quotes, and The Home Depot rolled out real-time delivery tracking for big and bulky orders through its driver handheld app. Together, these moves support paid service expansion, including takeoff support, jobsite delivery windows, will-call staging, and returns pickup, and they can also monetize higher-frequency Pro replenishment orders that are less dependent on weekend DIY traffic.
A second opportunity sits in compliance-forward assortments and merchandising for smart-home and connected hardware, as cybersecurity and labeling guidance becomes more operational. NIST IR 8259 Rev. 1 (April 2026) and the FCC Cyber Trust Mark program (with ioXt Alliance named Lead Administrator in July 2026) increase the practicality of building curated, verified smart-home sets and installation bundles, especially where energy-efficiency code adoption is already boosting demand for smart controls and higher-performance materials. Retailers that align supplier qualification, online product data, and in-store support can reduce returns and improve conversion in fast-growing connected categories, while meeting buyer expectations around safety and device trust.
Recent Industry Developments
- July 2026: The Home Depot expanded partnership with Military Exchanges for delivery to APO, FPO, and DPO addresses across more than 80 countries. The cross-border logistics expansion extends delivery reach to pro and DIY customers, enhancing international service capabilities. This strengthens pro contractor access and military-family supply chains, expanding international service reach.
- July 2026: Finalized purchase of a 22-acre site in Ocala, Florida, for a new 134,000-square-foot store for $4.6 million. The domestic store footprint expansion adds capacity to serve growing Florida demand from professionals and homeowners. It enhances regional market coverage and professional contractor servicing in the Florida market.
- June 2026: Opened a new store in Buckeye, Arizona. The regional store addition boosts proximity to professional contractors and DIY customers in a growth corridor. It drives higher pro-channel sales by expanding local access.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market is defined as revenue generated from retail sales made by US hardware and home improvement store formats, across in-store and online channels, for common DIY and contractor-led repair, remodel, and maintenance needs.
Scope exclusions: Excludes pure wholesale distribution and direct-to-jobsite sales that do not transact through a retail store or retail e-commerce checkout.
Segmentation Overview
- By Product Type
- Door Hardware
- Building Materials
- Kitchen and Toilet Products
- Other Product Types
- By Distribution Channel
- Offline
- Online
- By Store Format
- Big-Box Home Centers
- Traditional Hardware Stores
- Lumber & Building-Material Yards
- Farm & Ranch Supply Stores
- Warehouse Clubs
- By Region (U.S.)
- Northeast
- Midwest
- South
- West
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the market boundaries and to anchor the model to repeatable public data points. We started with official retail and construction signals, including US Census Bureau retail sales tables, Bureau of Labor Statistics industry productivity series aligned to NAICS 44413, and BEA price and personal consumption data where relevant to home improvement spend.
To keep the trend work practical, we also reviewed NAHB housing indicators, FRED time series used to cross-check turning points, and Federal Reserve releases that influence big-ticket project timing through interest rates. Company annual reports, investor presentations, and reputable business press were used to understand channel mix and category emphasis, and then we pressure-tested assumptions using paid subscriptions for company financial intelligence and news and financials. For select product groups, we also ran shipment-level import and export checks to confirm direction. The sources listed above are indicative and not exhaustive, and many other public and paid references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work centered on interviews and short surveys with retail executives, merchandising and sourcing leaders, store operations heads, and downstream users such as contractors and serious DIY buyers. We covered the major US regions so the model reflects different weather-driven seasonality, housing turnover patterns, and pro versus DIY mix. We then used these inputs to confirm price movements, category shifts, and realistic growth ranges by channel and store format.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 13% |
| Mid tier: 53% | Functional/Unit leaders: 40% |
| Smaller Players: 20% | Managers: 47% |
Market-Sizing & Forecasting
Sizing started with a top-down build that reconstructs the retail demand pool from category-level home improvement spend signals, retail sales direction, and housing and repair activity indicators, and then it is mapped into hardware store retail based on channel and store-format relevance. To keep the output grounded, we corroborated the total with selective bottom-up checks such as sampled average ticket and transaction counts, store network expansion or contraction, and revenue roll-ups from public filings for the larger chains.
Key model inputs included existing home sales and housing starts as demand triggers, remodeling and repair activity proxies, commodity-linked price movement that changes average selling prices, online share changes that move revenue between channels, and weather and disaster repair cycles that create regional demand spikes. Forecasting used scenario analysis supported by light time-series smoothing, where the ranges were set using what interviewees shared on traffic, basket size, and promotional intensity. When a bottom-up check lacked coverage for smaller independents, the gap was handled through store-count and sales-per-store ranges validated by primary responses.
Data Validation & Update Cycle
Model outputs were cross-checked against independent signals, including official retail series, category spending direction, and store-network trends, and then variances were reviewed before final sign-off. We also ran sanity checks on implied growth by channel and by store format so that sharp shifts were supported by a clear driver, not just the math.
If an outlier appeared, assumptions were revisited and respondents were re-contacted to confirm whether it was a one-time event or a real change in buyer behavior. Reports are refreshed annually, with interim updates triggered by material events like large pricing swings or meaningful demand shocks. Before delivery, an analyst performs a fresh pass so clients receive the latest updated view.
黑料不打烊's United States Hardware Stores Retail Market Sizing Compared With Other Published Estimates
Published market sizes for US hardware stores retail can differ by a wide margin, and it usually comes down to what is being counted and how the boundary is drawn. Even when the same wording appears in a title, the underlying scope can shift between hardware-only retail, broader home improvement retail, or measures closer to economic output than retail receipts.
Government series on NAICS-defined hardware stores and trade-association sales outlooks are the two checks that keep 黑料不打烊's estimate tied to retail revenue captured through hardware and home-center store formats, instead of blending in wider home improvement categories or non-retail flows. Differences also come from how online sales are attributed, how average selling price inflation is carried forward, and whether the publisher refreshes assumptions after major rate and housing-cycle changes.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 710.58 B (2025) | |
| Industry Association A | USD 544.60 B (2023) | Uses a broader home improvement industry sales lens and an earlier base year, which can exclude some store formats counted in this scope and can also understate post-2023 price and mix shifts. |
| Government Series B | USD 43.56 B (2025) | Tracks NAICS 44413 hardware stores sectoral output in economic accounts, which is not a full retail-market definition and does not capture home-center retail formats and wider category baskets. |
Taken together, the spread is mainly explained by scope boundaries and the choice of measurement unit, not just forecasting technique. When store formats, channels, and what qualifies as a retail transaction are stated clearly, the final number becomes easier to trace back to a repeatable set of demand and pricing inputs.


Key Questions Answered in the Report
Which product category generates the most revenue?
Building Materials lead with 36.05% share, reflecting core demand for structural staples.
What channel is growing fastest?
Online sales are expanding at a 13.42% CAGR, outpacing the mature offline base.
Why are renovations supporting sales despite high rates?
Elevated mortgage rates discourage relocation, so homeowners invest in upgrades, boosting large-ticket transactions.
Which region shows the quickest growth through 2031?
The West is forecast to grow at 6.9% CAGR, driven by wildfire-resilience mandates and smart-home adoption.
Who dominates the competitive landscape?
Home Depot and Lowe’s together hold roughly 77% of revenue, giving them significant pricing and supply-chain leverage.
Page last updated on:



