
Supermarkets Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 1.04 Trillion |
| Market Size (2031) | USD 1.22 Trillion |
| Growth Rate (2026 - 2031) | 3.16 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
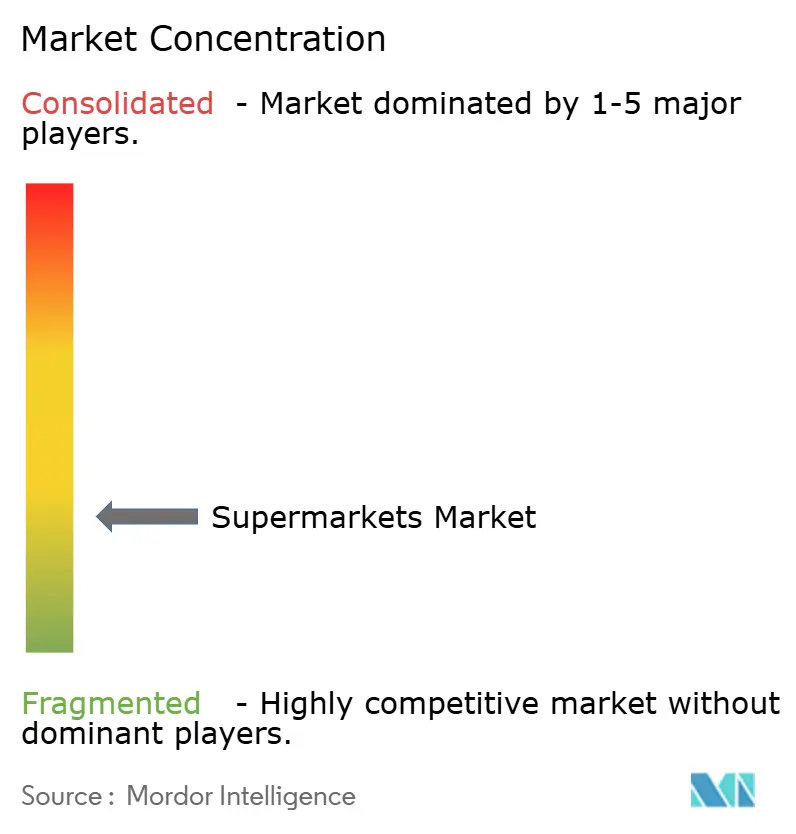
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Supermarkets Market Analysis by 黑料不打烊
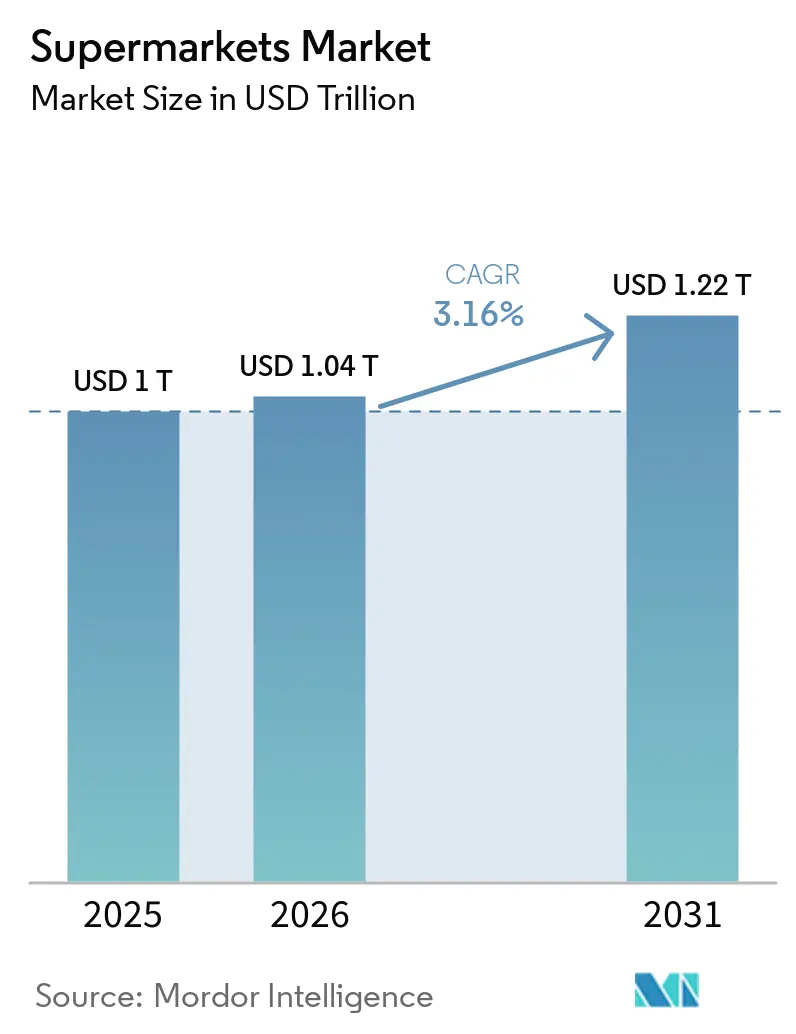
The Supermarkets Market size is projected to expand from USD 1 trillion in 2025 and USD 1.04 trillion in 2026 to USD 1.22 trillion by 2031, registering a CAGR of 3.16% between 2026 to 2031.
Growth reflects steady grocery demand while operators respond to tight margins, format shifts, and digital habits that pull more shopping journeys across channels. Scale remains a clear advantage as large groups deploy private labels, optimize supply chains, and integrate stores with online to defend traffic and share. Walmart’s FY2025 revenues underscore the scale of integrated models that use retail media and membership to strengthen economics[1]Walmart Inc., “Fiscal 2025 Results,” Walmart Corporate, corporate.walmart.com. European leaders also reinforce the Supermarket market through disciplined pricing, logistics density, and deeper banner portfolios that target different value tiers.
Key Report Takeaways
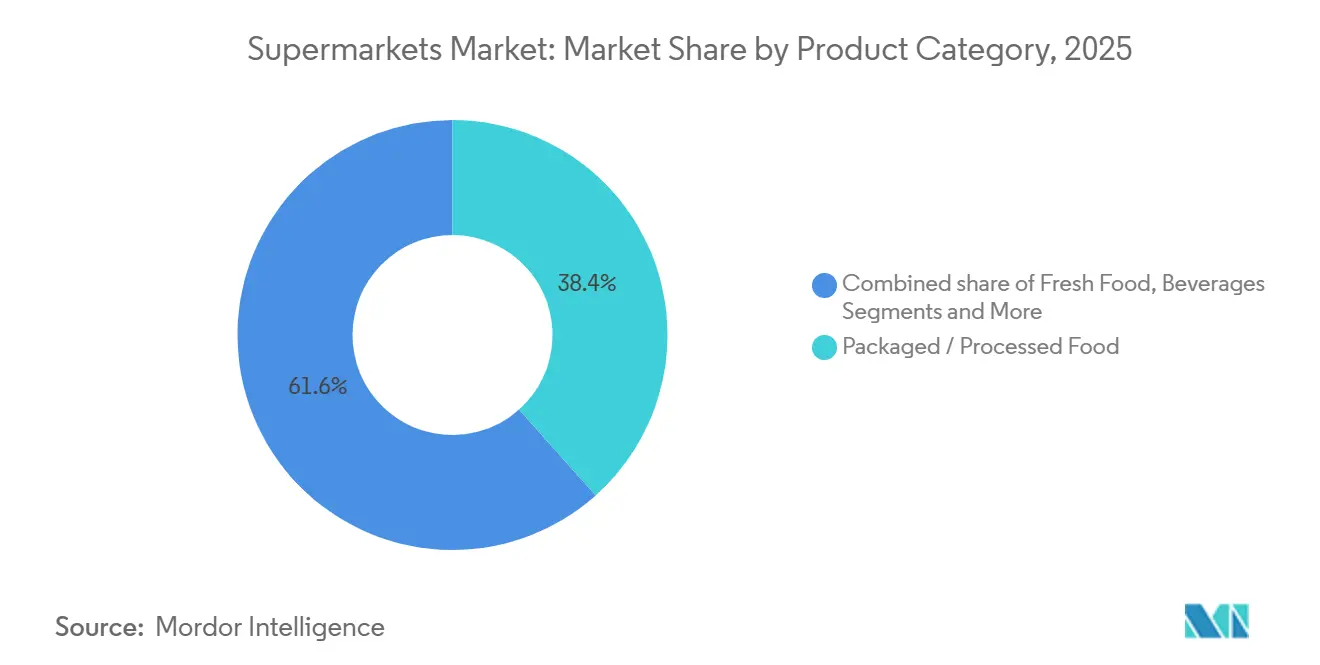
- By product category, packaged and processed food led with 38.37% revenue share in 2025, while ready-to-eat and prepared foods are forecast to expand at a 7.74% CAGR to 2031.
- By sales channel, the offline format held 65.54% share in 2025, while online and e-commerce are projected to grow at an 8.33% CAGR through 2031.
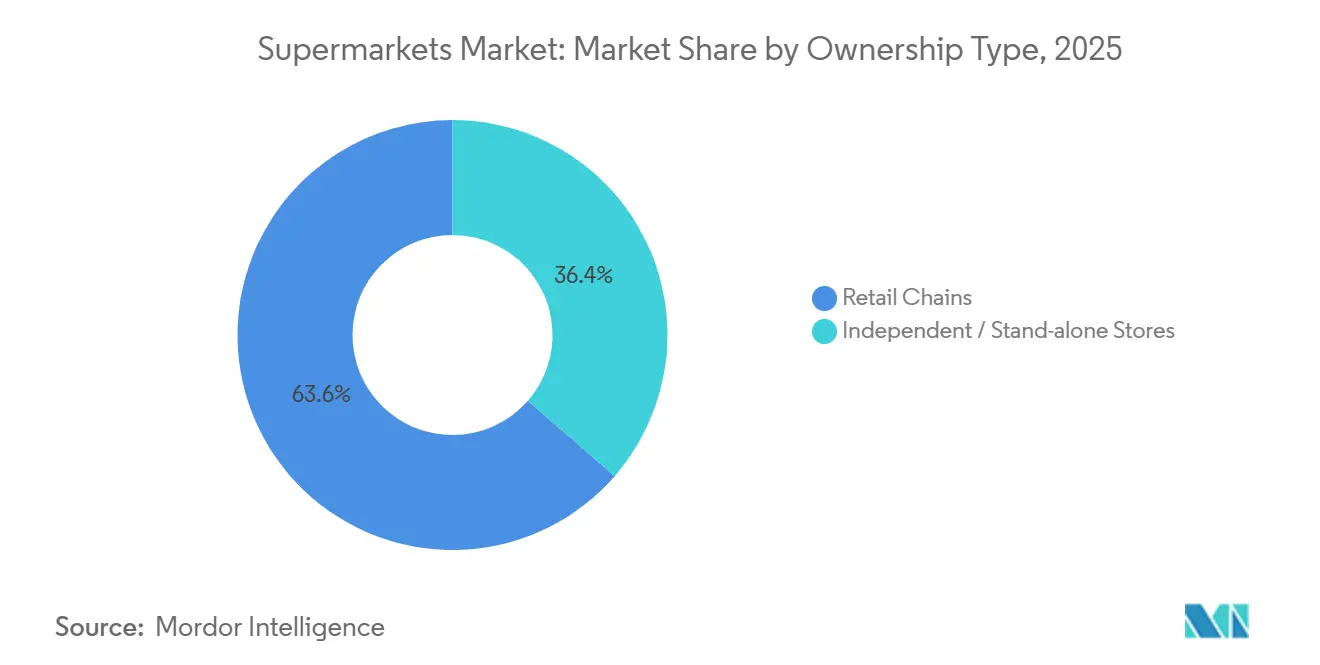
- By ownership type, retail chains accounted for 63.65% of 2025 sales and are projected to advance at a 6.98% CAGR to 2031.
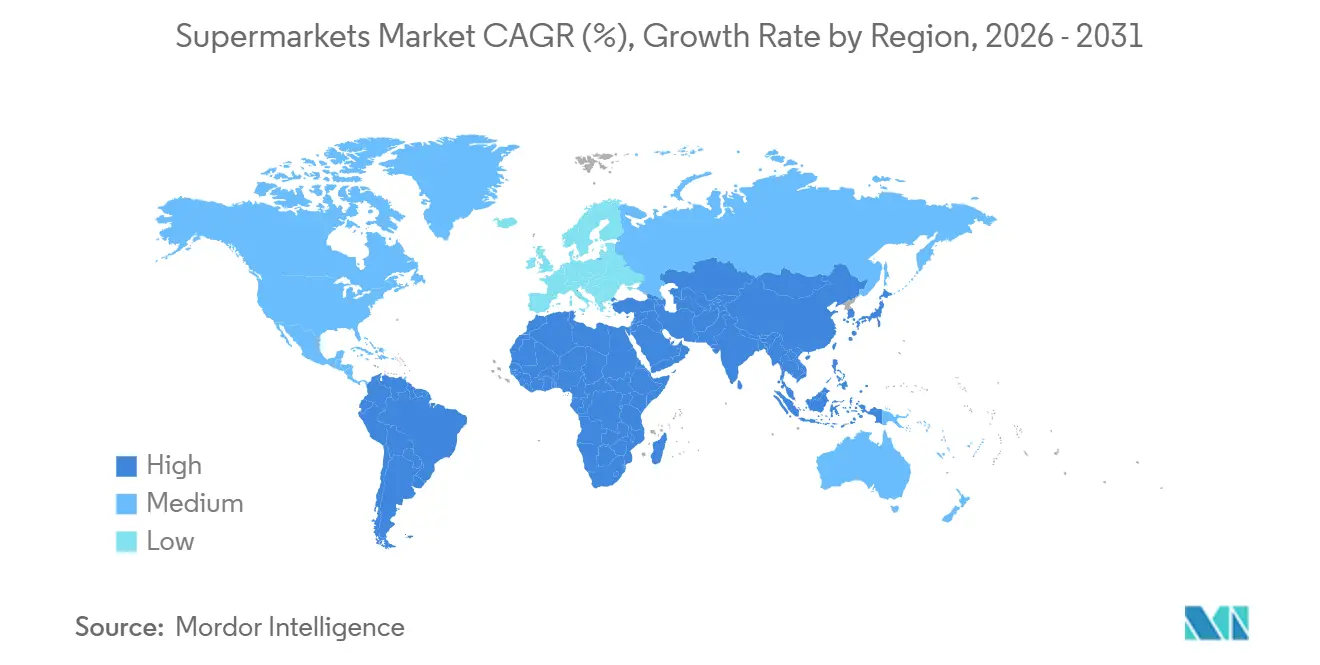
- By geography, North America captured 40.66% in 2025, and Asia-Pacific is the fastest-growing region at a 7.87% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Supermarkets Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid urbanization fueling demand for one-stop grocery shopping in Asia-Pacific megacities | +0.9% | Asia-Pacific core, spill-over to MENA | Medium term (2-4 years) |
| Rise of private-label penetration increasing basket margin in European discount supermarkets | +0.7% | Europe, North America secondary | Long term (≥ 4 years) |
| Digital loyalty apps driving higher visit frequency in North American chains | +0.5% | North America, early adoption in Asia-Pacific urban hubs | Short term (≤ 2 years) |
| AI-powered shelf optimization reducing stock-outs in high-throughput stores | +0.4% | Global, led by North America and Europe | Medium term (2-4 years) |
| Expansion of fresh convenience zones capturing time-starved consumers | +0.3% | Global, strongest in Europe and Asia-Pacific | Short term (≤ 2 years) |
| Government food-subsidy vouchers channeling spend through supermarkets, for example, Brazil | +0.2% | Brazil national, pilots in select South American cities | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Rapid Urbanization Fueling Demand for One-Stop Grocery Shopping in Asia-Pacific Megacities
Urban population growth and rising household incomes in Asia-Pacific continue to reshape grocery habits toward modern formats and one-stop stock-up trips that favor the Supermarket market[2]Australian Government, “Economic and Trade Insights,” Department of Foreign Affairs and Trade, dfat.gov.au. Operators are clustering stores in dense corridors and layering membership and fresh counters to draw larger baskets and recurring visits, which strengthens the Supermarket market in urban nodes. Sam’s Club China has scaled its warehouse grocery base and expanded assortments that fit apartment-living constraints while appealing to family needs. AEON plans to triple its Vietnamese footprint by 2030 with a mix of large-format stores and supermarkets, supported by ongoing investment and format localization. Vietnam’s Ministry of Industry and Trade has eased retail licensing processes and supported cold-chain upgrades that improve food safety and reduce losses, which further supports modern trade expansion.
Rise of Private-Label Penetration Increasing Basket Margin in European Discount Supermarkets
Private label has gained scale and depth in Europe, lifting the Supermarket market through better price-value and broader coverage of consumer needs across tiers. PLMA reported private-label sales reached USD 369.23 billion (EUR 354.5 billion) in the 52 weeks to July 2024, with a market share of nearly 39% across tracked markets, indicating continued consumer acceptance in core categories. Carrefour lifted private-label mix to 37% of food sales in 2025 and reiterated targets to grow the share further to reinforce price competitiveness and shopper loyalty. Tesco continued to scale its Finest premium range and broaden everyday value tiers, consistent with a portfolio strategy that anchors the Supermarket market across income bands. AEON’s TOPVALU reported solid growth in 2025, underscoring how large retailers use private label to strengthen margin structure and improve bargaining leverage with suppliers within the Supermarket market. EU food-safety frameworks and national certifications support trust in store brands and help narrow any perceived gap with multinational labels, improving conversion at the shelf.
Digital Loyalty Apps Driving Higher Visit Frequency in North American Chains
Membership and loyalty programs continue to shape purchase frequency and basket mix, providing retailers with data that increases the precision of offers and improves the economics of the Supermarket market. Walmart reported growth in its membership-related income in FY2025, and Sam’s Club expanded its Plus-tier adoption, reinforcing the value of benefits and savings for households that consolidate trips. Tesco Clubcard now reaches most United Kingdom households with high sales penetration, and the app user base continues to scale, which enhances the capacity to deliver targeted promotions and dynamic pricing. Target expanded its program reach and improved personalized in-app journeys that support convenient replenishment and value recognition in grocery. Retailers are unifying data platforms with point-of-sale and online carts to identify switching risk and to nudge shoppers with rewards that convert within the Supermarket market. The result is higher visit frequency among active members and greater share-of-wallet within banners that combine fuel rewards, subscriptions, and free pickup.
AI-Powered Shelf Optimization Reducing Stock-outs in High-Throughput Stores
Retailers are deploying AI to improve inventory accuracy, reduce waste, and enhance on-shelf availability across the Supermarket market. Walmart scaled AI tools that assist in inventory planning and routing and has developed models that power more relevant search and recommendations in digital grocery journeys. Target rolled out a generative-AI assistant to store teams across thousands of locations to speed inventory inquiries and support replenishment tasks that improve shelf readiness. Ahold Delhaize introduced an AI assistant within Albert Heijn’s app to support meal planning and discovery, which increases conversion and improves the experience in omnichannel grocery. Standards bodies and regulators are shaping responsible AI, which informs how retailers manage model transparency and bias controls in-store and online. The evolving EU AI Act provides a risk-based framework that guides deployment in high-volume retail contexts without undermining consumer protection in the Supermarket market.
Restraints Impact Analysis of Supermarkets Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High operating and infrastructure costs | -0.8% | Global, acute in Europe and mature North American metros | Long term (≥ 4 years) |
| Intensifying competition from quick-commerce dark stores in urban hubs | -0.6% | India core, spreading to Southeast Asia and South America | Medium term (2-4 years) |
| Supply-chain volatility for fresh produce due to climate disruptions | -0.4% | North America, Europe, Asia-Pacific | Short term (≤ 2 years) |
| Thin profit margins | -0.3% | Global | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High Operating and Infrastructure Costs
Operating expenses in food retail remain elevated, pressuring profits and limiting the pace of reinvestment even as operators modernize supply chains in the Supermarket market. Tesco reported lower free cash flow in FY2024/25 as working capital normalized after prior input inflation, and investment priorities focused on pricing and renewal programs. Kroger recognized a USD 2.6 billion impairment related to automated fulfillment, highlighting execution risk in large-scale automation projects in grocery. Walmart reiterated that mix shifts into lower-margin categories can offset parts of gross profit gains in some quarters within the Supermarket market. Costco announced hourly pay increases for frontline roles in March 2026, which lifts wage costs while improving retention in tight labor markets. These dynamics push retailers to sharpen productivity and reallocate capital toward programs that raise availability, reduce shrink, and differentiate value.
Supply-Chain Volatility for Fresh Produce Due to Climate Disruptions
Weather-linked disruptions continue to influence farm output and pricing for key perishables, creating volatility that retailers must buffer in the Supermarket market. USDA ERS projected a 24.8% rise in egg prices for 2025, tied to avian influenza impacts on flocks, and forecast higher beef and veal prices in 2025 due to tight supplies. The agency also noted that food-at-home inflation reached 2.7% year-on-year in August 2025, which affects household budgets and trade-down behavior in grocery stores. Retailers respond by diversifying sourcing, expanding private-label alternatives, and scaling cold-chain investments to stabilize availability within the Supermarket market. Environmental standards and emissions programs are further nudging value chains toward measurement and mitigation practices that can improve long-run resilience. That transition takes time and capital, so near-term price and supply swings will remain a constraint for fresh ranges.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Supermarkets Market Segment Analysis
By Product Category:
Packaged Foods Anchor Sales, Ready-to-Eat Surges on Lifestyle ShiftsPackaged and processed food held 38.37% of the Supermarket market share in 2025, reflecting the broad availability, long shelf-life, and efficient distribution that center-store categories provide. Ready-to-eat and prepared foods are the fastest-growing category at a 7.74% CAGR through 2031 as time-pressed households shift to fresh convenience at the perimeter. Supermarket market operators are investing in in-store kitchens and daily-prepared assortments to increase meal occasions and lunch trips, while maintaining staples that anchor weekly baskets. Mercadona’s “Listo para Comer” program demonstrates how a prepared-foods zone pulls incremental demand within a full-basket destination. AEON Vietnam reports prepared and bakery ranges now represent a sizable portion of food sales in newer stores, which supports growth in urban markets.
The global ready-to-eat category has healthy momentum, and supermarkets capture a significant share of that channel flow, which reinforces category breadth that supports the Supermarket market. Cold-chain uplift and automated facilities improve service levels and freshness, helping retailers expand perimeter categories at scale. Health and personal care ranges continue to benefit from co-location strategies and pharmacy adjacencies that drive cross-shopping, which broadens trip missions in the Supermarket market. Household and cleaning products remain steady with private-label penetration, particularly as vertically integrated programs improve cost control and speed to shelf. Food labeling rules such as the United States Nutrition Facts panel update and EU front-of-pack guidance continue to shape product development and shelf presentation across formats.


By Sales Channel:
Offline Retains Majority, Online Gains Share via Delivery InnovationOffline and brick-and-mortar formats held 65.54% of 2025 sales, signaling the ongoing preference for hands-on produce selection and immediate fulfillment in the Supermarket market. Retailers are improving store missions with fresh convenience zones and services that keep trips productive while maintaining sharp pricing to protect core baskets. The Global Supermarket market size for online and e-commerce is projected to expand at an 8.33% CAGR through 2031 as last-mile economics, subscriptions, and pickup options become more efficient. Retailers are integrating loyalty programs with e-commerce carts and pickup windows, which support add-on items and targeted promotions at checkout. Regulatory guardrails such as GDPR and CCPA shape how retailers personalize digital offers, reinforcing a privacy-by-design approach in grocery apps.
Operators are balancing automation and store-based picking to improve unit economics on delivery and click-and-collect. Kroger adjusted its automation footprint and reweighted toward in-store fulfillment while continuing to scale e-commerce capabilities within the Supermarket market. Several retailers have increased on-demand coverage by partnering with third-party delivery platforms to expand reach without diluting service quality. Retail media and digital coupons now tie directly to basket-building in mobile channels, reinforcing the link between loyalty and online reorder behavior in the Supermarket market. These elements support a stable offline base and a growing digital layer that together strengthen omnichannel outcomes.
By Ownership Type:
Chains Leverage Scale, Independents Hold Niche AppealRetail chains accounted for 63.65% of 2025 sales and are projected to grow at a 6.98% CAGR through 2031 as scale programs, procurement alliances, and private-label depth reinforce the Supermarket market. Chains deploy significant capital toward technology and logistics upgrades that improve service levels and inventory turns, which benefits trip missions and margins. The Supermarket industry also benefits from procurement alliances and joint buying that extract funding for price investment and innovation at the shelf, supporting competitiveness across banners. Large automated distribution centers and customer-fulfillment facilities are scaling in several countries to support daily replenishment and fresh availability. Mergers and portfolio moves in 2025 increased density and enabled tighter loops for last-mile delivery and regional supply.
Independent grocers remain important for local assortment, community engagement, and fresh service lines that build loyal followings in neighborhoods. Co-op models offer shared services that reduce the cost of digital tools and supplier negotiations, which support store modernization in the Supermarket market. At the same time, compliance with food-safety codes and labeling rules places a heavier administrative load on single-store operators that do not have central teams. The Supermarket industry continues to evolve as independents emphasize differentiation, local sourcing, and service experiences while chains scale a broad promise on value and availability. Both models will remain present, with chains growing faster due to capital intensity and digital infrastructure advantages.
Geography Analysis
North America Supermarkets Market
North America captured 40.66% of the Supermarket market share in 2025, supported by the scale of national operators and active expansion programs. Walmart’s results highlight consistent comparable growth and stronger digital adoption that feeds a larger ecosystem around grocery. Loblaw accelerated store openings, pharmacy clinics, and a major new automated distribution center, which supports availability and convenience in Canada. Kroger continues to expand e-commerce and remodels, and expects digital profitability as it optimizes fulfillment and pickup operations. Costco plans dozens of new warehouses, including large projects in North America and Mexico, that expand fresh and essentials reach within the Supermarket market. Publix grew sales and continued its remodel cadence in the Southeast, which supports larger baskets and stronger fresh presentation. Food-safety oversight, organic standards, and federal nutrition programs shape assortments and promotions, while state-level waivers guide specific product eligibility under benefits.
Europe Supermarkets Market
Europe’s leaders sustained pricing discipline, private-label growth, and selective consolidation that reinforce the Supermarket market. Schwarz Gruppe reported revenue growth supported by Lidl and Kaufland, showing how a dual-banner approach enables reach across price points. Carrefour completed the Cora and Match acquisition and expanded its purchasing alliance, targeting efficiencies and a higher private-label share across food. Spain’s Mercadona increased sales and profitability and continued to expand in Portugal, supported by prepared foods and store modernization. European environmental goals and labeling pilots are shaping procurement and shelf signals as retailers move toward lower-impact products and transparent nutrition indicators. Frameworks that standardize sustainability disclosures are broadening, aiding suppliers and brands in reporting progress to stakeholders.
APAC Supermarkets Market
Asia-Pacific is the fastest-growing region at a 7.87% CAGR through 2031, anchored by large markets that continue to formalize food retail. Hema and Sam’s Club China expanded quickly in 2025 and raised the bar on membership value and convenience formats in major cities. Reliance Retail added thousands of stores in India and expanded gross revenue, reflecting momentum in organized grocery. AEON increased private-brand penetration and detailed plans to scale convenience banners and supermarkets in Japan and Southeast Asia. Australia’s Woolworths and Coles invested in large automated facilities that improve service levels and order accuracy for fresh categories across the Supermarket market. Food-safety compliance across the region remains strict, with agencies in China, India, and Japan governing labeling and hygiene protocols for retail. These regulatory and infrastructure shifts support a rapid shift toward organized retail and omnichannel grocery in fast-growing cities.

Regulatory Landscape
Supermarkets operate under overlapping regimes covering food safety, labeling, competition policy, and consumer data protection, with compliance requirements increasingly built into store and e-commerce operating models. In the United States, the USDA Food and Nutrition Service updated the SNAP staple food stocking standards with an effective date of July 7, 2026, and a full compliance deadline of November 4, 2026, which raises execution requirements for retailers that accept benefits (assortment planning, shelf availability, and audit readiness).
In Europe, merger control remains a key constraint on consolidation, with the European Commission issuing draft merger guidelines on April 30, 2026, while national competition bodies continue to scrutinize buyer power and supplier terms in food retail. Beyond competition and benefits-program rules, retailers are also adapting to tighter product and sustainability substantiation and to cross-border sanitary rules that affect sourcing. The United Kingdom and the EU have been preparing businesses for a mid-2027 Sanitary and Phytosanitary (SPS) agreement, which elevates the importance of traceability and compositional controls for grocery supply chains that move goods across borders. In parallel, new EU compliance direction around digital product records (including Digital Product Passport-related requirements and registry timing referenced for July 2026) and the movement of the Green Claims Directive toward enforcement in 2026 increase the cost of poor data quality and unverified claims on-pack and online.
Value Chain Analysis
The supermarket value chain spans branded and private-label manufacturers, agricultural producers and processors, importers, national and regional distributors, and retailer-controlled distribution networks that feed stores and online fulfillment. Large chains increasingly centralize procurement and expand private-label programs to improve margin control and negotiating leverage, while regulators and policy bodies heighten scrutiny of bargaining power and pricing practices, as reflected in the German Monopolkommission’s 2025 work on food supply chains and ongoing antitrust attention to consolidation in grocery retail. On the operating side, the chain depends on temperature-controlled logistics, category management, and high-frequency replenishment for fresh, supported by data-driven forecasting and shrink controls.
Downstream, fulfillment splits across in-store picking, micro-fulfillment or automated facilities, and third-party last-mile partners, with profitability shaped by labor, route density, and substitution rates. Compliance and documentation are becoming structural parts of the chain: traceability is moving beyond shipment visibility toward verifiable composition and sustainability attributes, linked to EU ecodesign-oriented requirements and other product-rule regimes cited in supply-chain compliance discussions. Interoperable data exchange and standardized digital documentation (including eFTI-type frameworks referenced in logistics compliance discourse) strengthen the role of supply chain software, master data, and supplier onboarding as gating steps for assortment expansion and cross-border sourcing.
Competitive Landscape
The global supermarket sector exhibits low concentration, with the top 10 players (Walmart, Schwarz Gruppe, Carrefour, Aldi, Kroger, Tesco, Costco, Ahold Delhaize, Edeka, and REWE) collectively holding a significant share, leaving substantial room for regional champions (Reliance Retail, Woolworths, Mercadona) and independent operators. The Supermarket market shows low concentration at the global level, with leading operators present in most regions and strong national champions in key countries. Walmart continues to scale retail media and membership programs that monetize traffic and improve loyalty economics around grocery[3]Walmart Inc., “Advertising and Membership Updates,” Walmart Corporate, corporate.walmart.com. Schwarz Gruppe balances Lidl’s discount proposition with Kaufland’s broader assortment to capture distinct customer missions within a consolidated network. Carrefour’s portfolio simplification and alliance growth aim to sharpen price competitiveness and expand private label across categories[4]Carrefour, “Portfolio Simplification and Alliances,” Carrefour, carrefour.com. Tesco continues to refine its focus with disposals outside core retail banking, a program to upgrade stores, and an expanded marketplace that adds long-tail items.
Operators are deploying omnichannel strategies, automation, and purchasing alliances to protect pricing and improve service levels within the Supermarket market. Coles and others increased automation investment while ramping AI tools for planning and customer service across merchandising and supply chain. Ahold Delhaize executed bolt-on M&A in Central and Eastern Europe to add density and raise private-label scale, improving logistics efficiency. Canadian retailers such as Loblaw partnered with autonomous trucking firms to reduce logistics costs and emissions in large metropolitan areas. Several grocers expanded rapid delivery coverage and unified retail media platforms to drive vendor funding and incremental ad income in the Supermarket market.
Standards and compliance frameworks help reduce complexity across borders and improve trust for food products and data-driven programs. Quality and safety systems supported by global benchmarks and national regulators continue to shape the core practices that protect consumers in grocery. Data protection rules in key markets guide how banners deploy personalized pricing and loyalty features, which supports sustainable adoption of digital tools in the Supermarket market. The long-run competition pattern rests on a base of strong private-label programs, expanded fresh and prepared foods, and omnichannel convenience tied to resilient logistics. Execution will favor banners that blend value, availability, and easy digital journeys as traffic migrates across channels.
Supermarkets Industry Leaders
Walmart Inc.
Schwarz Gruppe
Carrefour SA
Aldi Süd & Nord
The Kroger Co.
- *Disclaimer: Major Players sorted in no particular order
Supermarkets Market Companies Covered in this Report
- Walmart Inc.
- Schwarz Gruppe (Lidl & Kaufland)
- Carrefour SA
- Aldi Süd & Nord
- The Kroger Co.
- Tesco PLC
- Costco Wholesale Corp.
- Ahold Delhaize
- Edeka-Zentrale
- Rewe Group
- Auchan Holding
- Publix Super Markets Inc.
- Mercadona SA
- Migros-Genossenschafts-Bund
- Loblaw Companies Ltd.
- Woolworths Group (Australia)
- Coles Group
- Reliance Retail (Smart Bazaar)
- Avenue Supermarts (DMart)
- Seven & i Holdings (Ito Yokado)
- AEON Co. Ltd.
- Casino Guichard-Perrachon
- CP ALL Public Co.
- Sainsbury’s PLC
- Waitrose Ltd.

Market Opportunities and Future Outlook
Compliance-led digitization is creating whitespace for supermarkets to differentiate on supplier qualification speed, audit readiness, and product information quality across both shelves and digital carts. The shift toward digital product records in Europe, including Digital Product Passport-related requirements and registry timing referenced for July 2026, increases the value of retailers that can collect, validate, and operationalize supplier data at scale, especially for private-label programs where the banner controls specifications. This supports investment in traceability platforms, interoperable documentation, and tighter master-data governance to reduce delist risk, improve recall execution, and strengthen substantiated sustainability messaging as EU green-claims enforcement activity advances.
In the United States, updated SNAP staple food stocking standards (effective July 7, 2026, with full compliance required by November 4, 2026) create a clear operational opportunity for participating retailers to tighten on-shelf availability and assortment governance in eligible categories, supported by improved inventory accuracy and store execution tools. Separately, ongoing merger scrutiny by the FTC and evolving merger-control guidance in Europe keeps consolidation outcomes uncertain, which strengthens the case for non-M&A scale levers such as procurement alliances, private-label expansion, and supply-chain automation. Investments highlighted by leading groups (for example, Schwarz Gruppe’s plan to invest more than EUR 10 billion in fiscal year 2026, including store expansion and digital capability) also reinforce the competitive premium placed on logistics capacity and digital independence.
Recent Industry Developments in Supermarkets Market
- June 2026: Schwarz Gruppe announces investment increase to more than �10 billion for fiscal year 2026 focused on core business, brick-and-mortar expansion, digital independence, and supply sovereignty. The initiative expands physical footprint and digital capabilities. The expanded capex strengthens market scale, private-label penetration, and omnichannel competitiveness, and may pressure peers to accelerate capex and digitization.
- April 2026: Carrefour SA confirms launch of the Carrefour 2030 strategic plan and integration of services into the ChatGPT interface for French users. This affects digital customer engagement and service platforms. It supports AI assisted shopping experiences and data-enabled loyalty, and could serve as a reference for other banners to integrate AI copilots in stores and online channels.
- March 2026: The Kroger Co. reports FY2025 results and announces 2026 capex guidance of $3.8 - $4.0 billion and $2 billion share repurchase authorization. The investment program shapes fiscal 2026 expansion and capital allocation. It signals aggressive network modernization and growth investments with potential uplift to store density and online fulfillment capabilities, with potential pricing and margin implications for the sector.


Supermarkets Market Report Scope and Research Methodology
Market Definition and Coverage
In this methodology, the supermarket market is the value of sales generated by stores that mainly sell food and household essentials through a self-service format, with a broad product mix and regular replenishment cycles. We treat this as a retail revenue market measured in USD across major countries.
Scope exclusions: We exclude pure-play online marketplaces, convenience stores, and wholesale club formats when they are not operating a supermarket-style assortment and store model.
Segments Covered in This Report
- By Product Category
- Fresh Food
- Packaged / Processed Food
- Beverages
- Household & Cleaning Products
- Health & Personal Care Products
- Ready-to-Eat / Prepared Foods
- Others
- By Sales Channel
- Offline / Brick-and-Mortar
- Online / E-commerce
- By Ownership Type
- Retail Chains
- Independent / Stand-alone Stores
- By Geography
- North America
- Canada
- United States
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia Pacific
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the outside boundaries of demand and to keep assumptions realistic by country and by retail format. We relied on public statistical series and industry measurement sources, such as national accounts and consumer price inflation series from the World Bank and the International Monetary Fund, population and urbanization indicators from the United Nations, and household expenditure splits from the OECD.
To translate these signals into a retailable demand pool, we also reviewed food retail and store-format references from sources such as the Food Industry Association (FMI), the US Census Bureau retail trade releases, Eurostat retail turnover series, and customs trade data where it helps explain packaged-food supply availability. Company annual reports, investor presentations, and reputable business press were used to validate revenue mix statements and store footprint changes, and a paid company financials and intelligence subscription was used selectively to normalize private-company coverage. This list is illustrative, and many other public and proprietary sources were also consulted for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating how supermarkets are defined in practice across regions, and then stress-testing the value build with operators, retail consultants, distributors, and category specialists. These discussions were also used to confirm pricing behavior, including private label, and to clarify how much of online-to-offline fulfillment is handled by supermarket operators versus other channels. We used this input to set realistic same-store sales expectations by region so the model does not lean too heavily on a single secondary data series.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 19% | APAC: 37% |
| Mid tier: 49% | Functional/Unit leaders: 23% | EMEA: 37% |
| Smaller Players: 21% | Managers: 58% | Americas: 26% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where national consumption and retail spend indicators are reconstructed into supermarket-addressable sales, and then rolled up to regional and global totals. We then corroborate the outputs with selective bottom-up approximations, such as sampled country roll-ups of leading retailers, store-count and selling-area checks, and simple ASP x volume logic for high-throughput grocery baskets. Those bottom-up signals are then used to tune outliers.
We prioritized practical inputs tied to supermarket demand, including food-at-home expenditure trends, retail food inflation and exchange-rate timing, supermarket penetration versus alternative formats, modern trade expansion pace in emerging markets, and the online share that is fulfilled by supermarket operators rather than marketplace-only players. Forecasting was mainly driven through scenario analysis, where baseline, conservative, and expansion cases are built around macro consumption outlook, inflation normalization, and store-network execution, then aligned to what interviewees considered achievable in their regions. When bottom-up signals were incomplete for smaller countries, gaps were filled using proxy ratios (such as spend per capita and format penetration), and the results were rechecked at the regional total level.
Data Validation & Update Cycle
Validation is handled through multi-step checks so one noisy input does not steer the final number. We compare final market totals against independent signals such as retail turnover trends, food CPI movement, and published supermarket sales snapshots where available, and then investigate large variances before sign-off.
Each model pass is peer reviewed, and we re-contact experts when a key assumption shifts, such as an abrupt currency move, sharp inflation change, or a major format reclassification in a country. Reports are refreshed annually, with interim updates when material events affect demand or pricing, and a final pre-delivery review is completed so clients receive the most current view.
黑料不打烊's Global Supermarket Market Size Compared Against Other Published Estimates
Published market values for supermarkets can look far apart because groups often draw the line differently between supermarket retail, broader grocery retail, and mixed formats that blend wholesale or convenience traits. We also see divergence when inflation and currency are handled with different timing, or when online grocery is counted even if it is not fulfilled by supermarket operators.
By tracking store-format boundaries, refreshing exchange-rate and inflation inputs, and then checking the roll-up with country retail turnover signals, 黑料不打烊 keeps the value tied to supermarket-led sales rather than a wider grocery umbrella. In practice, the spread usually comes from whether convenience and club formats are included, whether marketplace-only online grocery is treated as part of the same market, and whether assumptions are validated with operator feedback or left as desk-based ratios.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 1.04 T (2026) | |
| Industry Association A | USD 1.00 T (2025) | Uses a sales snapshot style total and does not clearly separate supermarket-format revenue from broader grocery channels across countries, which can compress or shift the global value by year. |
| Global Consultancy B | USD 1.30 T (2026) | Applies a wider grocery retail scope that can fold in adjacent formats and online-only grocery, and often relies on single-step macro ratios without consistent country-level format validation. |
The table shows that most gaps are created by format scope and timing choices, more than by small math differences. With clear inclusion rules, practical country checks, and a repeatable set of demand and price inputs, our estimate stays easier to reconcile back to real-world supermarket activity and to update when conditions change.


Key Questions Answered in the Report
What is the global Supermarket market size and forecast growth to 2031?
The global Supermarket market size is USD 1.04 trillion in 2026 and is projected to reach USD 1.22 trillion by 2031 at a 3.16% CAGR.
Which product categories are leading and which are growing the fastest in the Supermarket market?
Packaged and processed food leads by share in 2025, while ready-to-eat and prepared foods is the fastest-growing category through 2031 at a 7.74% CAGR.
How is the sales channel mix evolving in the Supermarket market?
Offline kept 65.54% of 2025 sales, while the online and e-commerce channel is projected to grow at an 8.33% CAGR through 2031.
Which regions hold the largest share and the fastest growth within the Supermarket market?
North America captured 40.66% in 2025, while Asia-Pacific is set to expand at a 7.87% CAGR through 2031.
How are private labels changing competition in the Supermarket market?
Private labels are lifting price-value and margins, with leading retailers growing their private-brand mix to deepen loyalty and fund sharp everyday pricing.
What digital and AI capabilities matter most for the Supermarket market today?
Loyalty ecosystems, retail media, and AI for inventory and recommendations are central, improving availability, relevance, and omnichannel economics across banners.
Page last updated on:


