
France Data Center Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 5.20 Billion |
| Market Size (2026) | USD 5.59 Billion |
| Market Size (2031) | USD 8.01 Billion |
| Growth Rate (2026 - 2031) | 7.49 % |
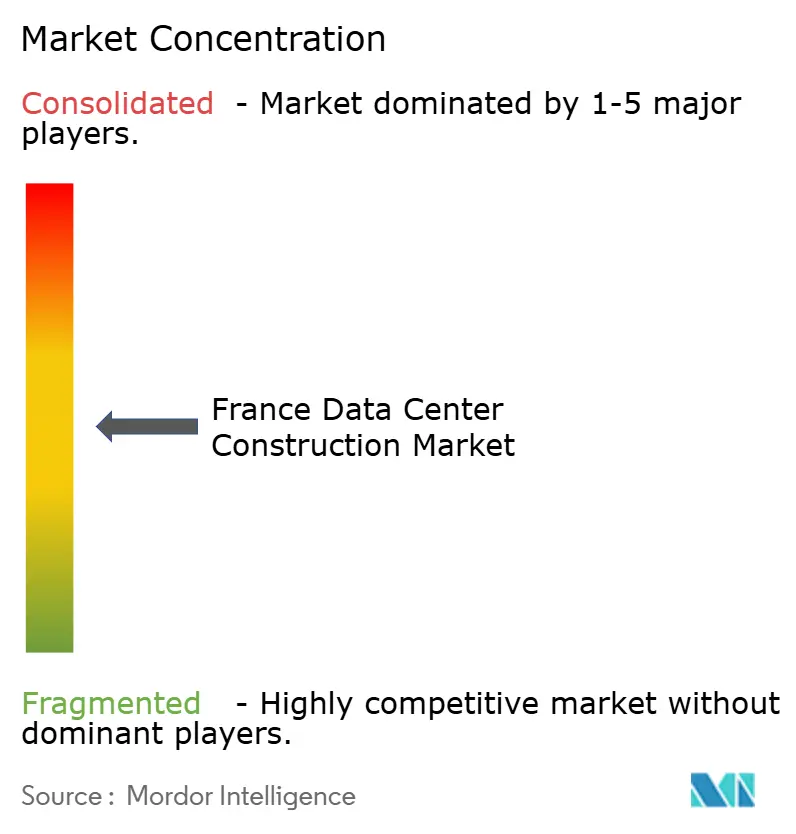
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
France Data Center Construction Market Analysis by 黑料不打烊
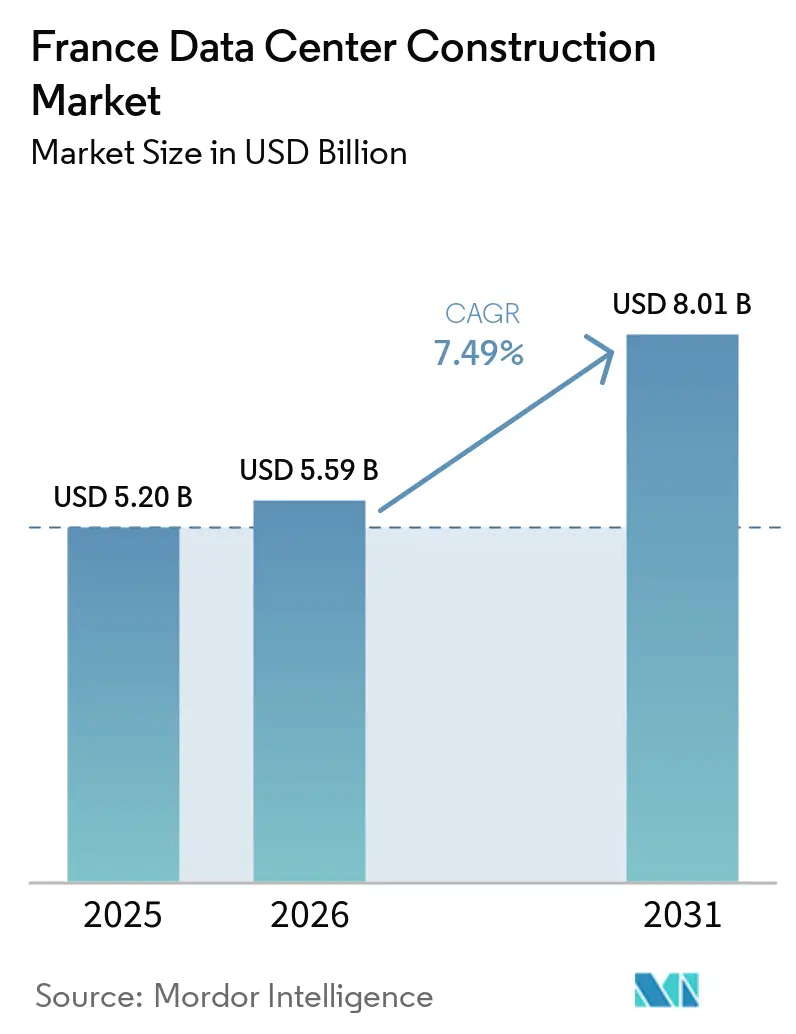
The France data center construction market size is expected to grow from USD 5.20 billion in 2025 to USD 5.59 billion in 2026 and is forecast to reach USD 8.01 billion by 2031 at 7.49% CAGR over 2026-2031. Ready-to-use land parcels, an extensive nuclear-powered grid, and strategic submarine-cable links are accelerating project pipelines. Replacement demand is robust because as much as 80% of installed capacity cannot support high-density AI loads. Competitive intensity is increasing as domestic builders partner with international operators to combine local permitting expertise with global scale. Nevertheless, rising labor and material costs are trimming project margins and shifting activity toward secondary metros.
Key Report Takeaways
- By tier classification, Tier 3 facilities led with 52.15% of France data center construction market share in 2025, while Tier 4 is projected to post an 7.87% CAGR through 2031.
- By data-center type, the colocation category captured 56.60% revenue share in 2025; hyperscaler self-builds are set to expand at a 9.65% CAGR to 2031.
- By electrical infrastructure, power-backup systems accounted for a 51.35% share of the France data center construction market size in 2025, whereas power-distribution solutions are forecast to grow at a 8.92% CAGR.
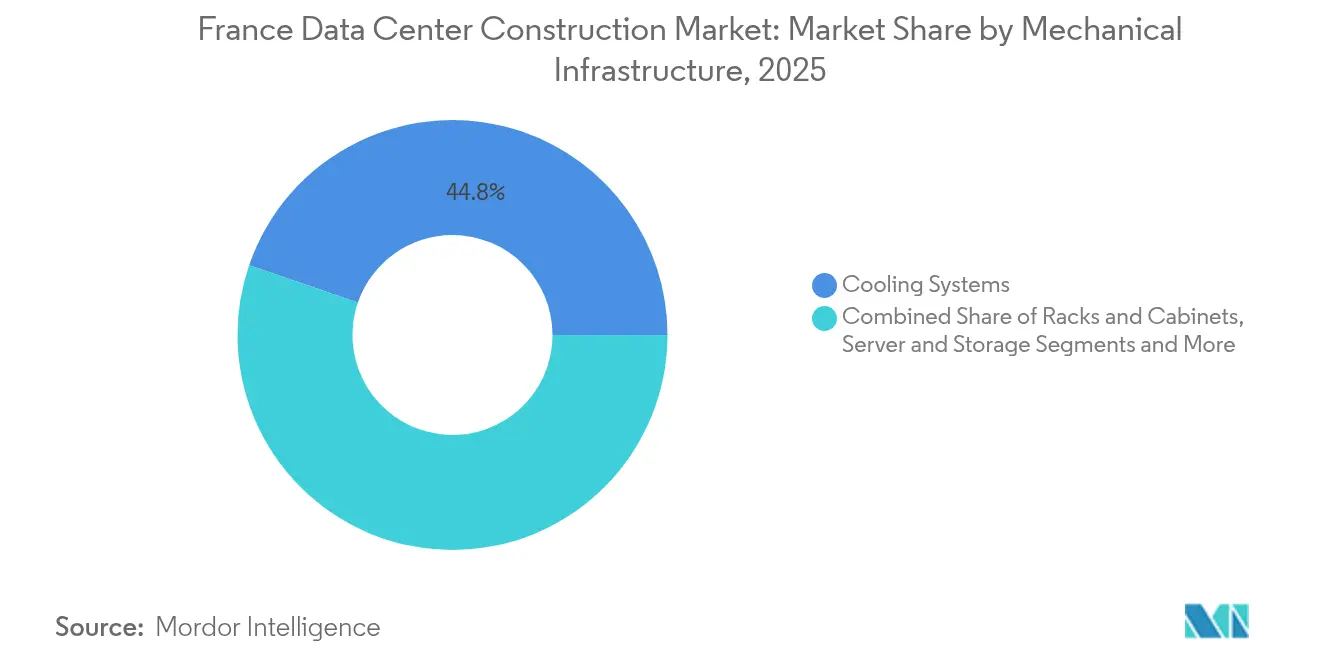
- By mechanical infrastructure, cooling systems dominated with a 44.75% share in 2025, while servers and storage are expected to advance at an 8.25% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
France Data Center Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Digital transformation and managed-cloud demand | +1.2% | National, concentrated in Paris-Lyon-Marseille corridor | Medium term (2-4 years) |
| 5G roll-out and edge-computing densification | +0.8% | Urban centers, expanding to secondary cities | Short term (≤ 2 years) |
| Government AI and digital-sovereignty investment surge | +1.5% | National, with focus on strategic sites | Long term (≥ 4 years) |
| Availability of low-carbon nuclear-backed electricity | +0.9% | National, particularly attractive for hyperscale facilities | Long term (≥ 4 years) |
| Fast-track "national-interest" permit regime | +0.6% | National, streamlining major projects | Medium term (2-4 years) |
| Edge data-center growth for AI/IoT low-latency workloads | +0.7% | Metropolitan areas, industrial zones | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Digital Transformation and Managed-Cloud Demand
Enterprises are replacing on-premises hardware with hybrid-cloud architectures that need low-latency links to public-cloud regions and specialised colocation halls. Sector-specific compliance is reshaping specifications; healthcare operators seek ISO 13485 halls, while gaming and lottery operators commission multi-site audits before moving workloads. The managed-services layer compels builders to integrate staging space for edge appliances and AI inference clusters. Demand for sovereign-hosted environments is anchoring capacity inside national borders to meet European data-protection rules.
5G Roll-Out and Edge-Computing Densification
Widespread 5G coverage is pushing computing clusters closer to streets and factory floors. Municipal projects, such as the Istres private 5G rollout, embed micro-data centers into civic infrastructure to support real-time video analytics, creating opportunities for contractors versed in high-density electrical layouts that fit inside refurbished utility rooms. Manufacturers deploying 5G on production lines are requesting ruggedised edge enclosures paired with liquid cooling that withstand industrial heat and vibration.[1]Ericsson, "Istres launches Private 5G Network for enhanced urban connectivity,"ericsson.com
Government AI and Digital-Sovereignty Investment Surge
Paris has packaged land banks, pre-approved data center power licences, and accelerated permits into a single policy toolkit. The offer has lured cross-border capital, exemplified by a EUR 30–50 billion (USD 34.54-57.57 billion) UAE partnership to build a 1-gigawatt AI campus and by Brookfield’s EUR 20 billion(USD 23.03 billion) allocation that will triple Data4’s national footprint. Public-sector orders are steady; the City of Paris is funding its own cloud facility to safeguard confidential datasets, while sovereign-cloud ventures such as Orange-Capgemini Bleu mandate hardened halls with intrusion-detection zoning.[2]Jean-Paul Legendre, “France Readies 35 Plots for Data Center Megaprojects,” Bat info, batinfo.com
Availability of Low-Carbon Nuclear-Backed Electricity
Roughly 70% of French electricity is nuclear-generated, giving operators predictable energy prices and a low-carbon marketing edge. EDF has earmarked four grid-connected plots for hyperscale parks and offers direct-to-reactor power agreements that shorten energisation schedules. Fluidstack’s planned EUR 10 billion (USD 11.51 billion) AI supercomputer will tap this baseload to run power-hungry model-training clusters around the clock without renewable-intermittency constraints.
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Paris-region land and build-cost inflation | -0.8% | Paris metropolitan area, spillover to surrounding regions | Short term (≤ 2 years) |
| Stringent 2025 energy-efficiency disclosure law (ICPE) | -0.4% | National, affecting all facilities above 500kW | Medium term (2-4 years) |
| Localised grid-capacity bottlenecks in FLAP sub-markets | -0.5% | Paris, Lyon, Amsterdam, Frankfurt connectivity corridors | Medium term (2-4 years) |
| Tightening water-usage regulations for cooling systems | -0.3% | Water-stressed regions, particularly southern France | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Escalating Paris-Region Land and Build-Cost Inflation
Limited industrial plots inside the A86 ring road have pushed average site prices beyond EUR 300(USD 345.51) per square meter, while steel and switchgear costs continue to rise at 5–7% annually. Hourly labour rates advanced from EUR 112.80 (USD 129.88) to EUR 121.02 (USD 139.34) during 2025, squeezing contractor margins. Developers are diverting pipelines to Lyon, Bordeaux and Marseille, where land is cheaper and municipal incentives are available. To offset cost pressures, builders are adopting factory-prefabricated modules that cut on-site labour hours and reduce exposure to price-volatile commodities.
Stringent 2025 Energy-Efficiency Disclosure Law (ICPE)
From 2025, facilities above 500 kW must report actual PUE, water consumption and recovery of waste heat. Operators are incorporating indirect-evaporative or liquid cooling to meet mandated thresholds and future-proof designs. Compliance adds metering, telemetry and data-visualisation systems during construction, raising upfront capex but lowering operating expenses. Projects unable to implement heat-reuse loops risk permitting delays, driving investment toward campuses with adjacent district-heating schemes.[3]Kevin Dalton, “Interxion Implements River Cooling at Marseille Site,” interxion.com
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
Segment 1
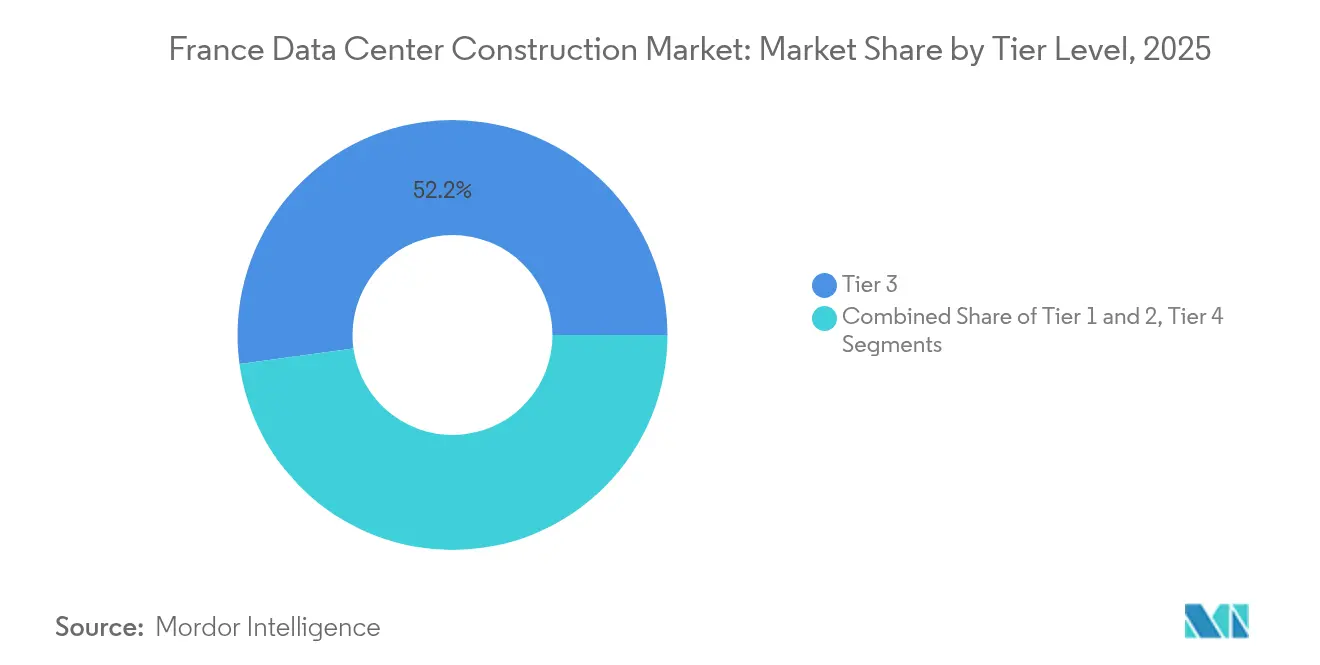
Tier 3 halls retained 52.15% of France data center construction market share in 2025 because most enterprise applications require high but not fault-tolerant uptime. The France data center construction market size for Tier 3 builds is forecast to continue expanding steadily yet below the overall industry CAGR. Tier 4, by contrast, is projected to grow 7.87% annually through 2031 as AI model training, fintech clearing and critical national infrastructure workloads need 99.995% availability.
Tier 4 projects entail 2N power trains, dual fibre paths and concurrent maintainability across mechanical subsystems, prompting larger electrical rooms and more sophisticated building-management software. The Thésée DataCenter campus, recognised as the nation’s first Uptime Tier IV colocation site, integrates AI-based cooling optimisation that trims energy consumption without compromising redundancy. Suppliers are therefore seeing heightened demand for AI-driven environmental controls, arc-flash-resistant switchgear and predictive-maintenance sensors that feed reliability dashboards.


By Data Center Type: Hyperscaler Self-Build Accelerates Market Transformation
Colocation operators commanded 56.60% of France data center construction market share in 2025, since enterprises prefer an opex-based capacity that can be contracted flexibly. Self-built hyperscaler halls, however, will record a 9.65% CAGR to 2031 as public-cloud providers seek cost control and guaranteed rack availability.
Hyperscaler campuses employ template-based designs with 54–60 MW blocks that replicate across regions, letting constructors gain repeatability benefits on materials and timelines. Microsoft’s EUR 4 billion (USD 4.61 billion) pledge is channelled into such cookie-cutter shells that accelerate commissioning. Enterprise and edge projects remain relevant where data-sovereignty rules or millisecond latency targets override economies of scale, prompting construction of micro-facilities inside factories, hospitals, and smart-city districts.
By Electrical Infrastructure: Power Distribution Innovation Leads Growth
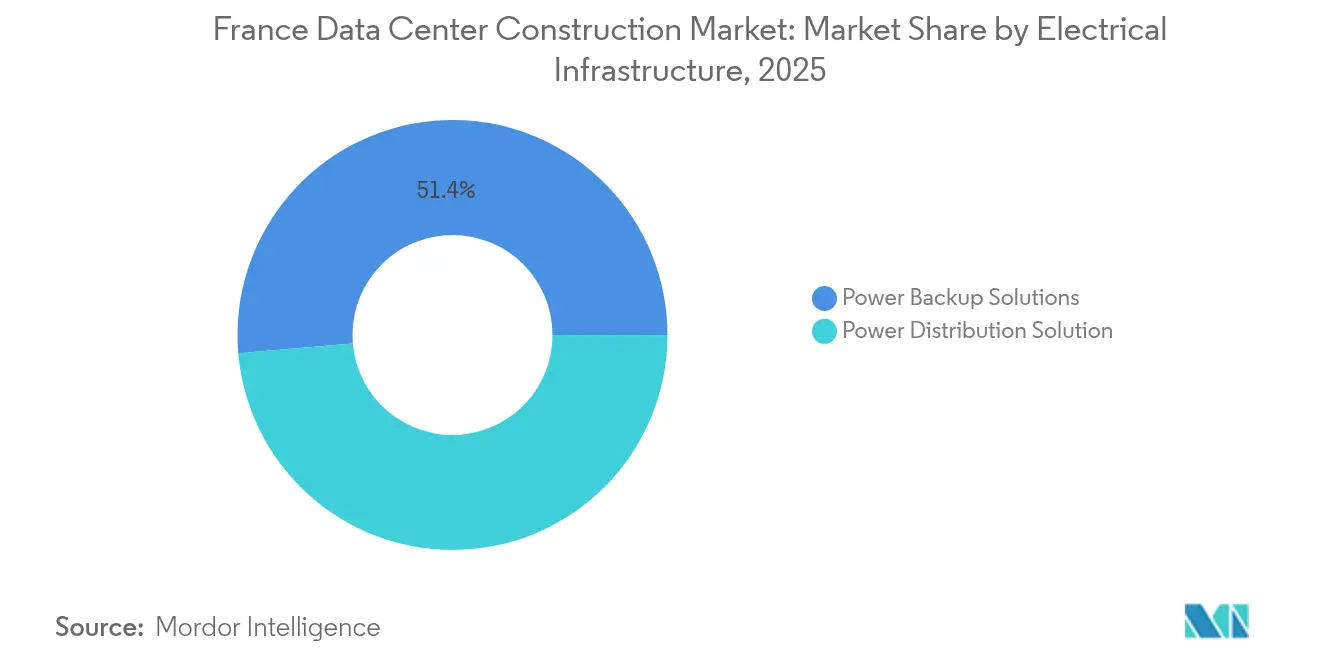
Power-backup systems, including static UPS and diesel generators, held 51.35% of segment revenue in 2025 because uptime contracts still stipulate no-break transfer. Power-distribution units and busways are forecast to expand 8.92% annually, reflecting the shift to rack densities exceeding 40 kW for AI accelerators. The France data center construction market size allocated to advanced distribution gear will approach USD 1.63 billion in 2031.
Next-generation switchboards embed real-time analytics that balance phase loads and predict breaker wear. Socomec’s sensor-rich UPS topology supports edge sites by combining lithium-ion batteries with remote-management APIs, reducing truck-roll visits. Builders increasingly integrate grid-interactive battery energy-storage systems that provide both backup and frequency-regulation revenues, helping owners defray capex while meeting sustainability reporting obligations.
By Mechanical Infrastructure: Servers Drive Density Revolution
Cooling systems remained the largest mechanical slice with 44.75% share in 2025 because every new watt of compute demands roughly equal thermal removal. Servers and storage are poised for the fastest 8.25% CAGR as AI nodes drive exponential growth in GPU trays and NVMe arrays. High-density racks can exceed 100 kW, making direct-to-chip liquid cooling mainstream.
Immersion cooling loops deliver up to 20% longer hardware life and 39% carbon-emission cuts versus raised-floor air, attracting clients with net-zero commitments. 2CRSi’s USD 610 million hardware contract illustrates how server vendors package bespoke chassis, cold-plates and monitoring firmware as a single deal, compelling constructors to coordinate tightly with OEMs during design. Mechanical rooms likewise evolve, housing fluid loop pumps, heat exchangers and redundant dry coolers sized for hotter summer peaks.
Geography Analysis
Paris remains the core location for the France data center construction market because it hosts the bulk of financial trading, government clouds, and internet exchanges. Digital Realty operates 13 interconnected halls offering 932,500 ft? and dark-fibre links that guarantee sub-millisecond latency to La Défense financial district. Land scarcity and tightening acoustic regulations, however, are pushing expansions outward along express rail corridors.
Marseille is emerging as Europe’s southern gateway thanks to 14 submarine-cable terminations delivering 660 Tbps of capacity. Digital Realty’s recent EUR 280 million (USD 322.38 million) MRS5 build adds 22 MW on reclaimed industrial land, while Interxion converted a WWII submarine dock into a chilled-water-cooled facility that funnels waste heat into a district-heating grid.
Lyon, Bordeaux, and Strasbourg form a second-ring constellation that balances cost, power, and seismic resilience. Lyon leverages its position at the confluence of national fibre backbones and hosts SFR’s carrier-neutral Netcenter with Tier III certification. Bordeaux has welcomed Equinix’s BX1, signalling hyperscaler interest in the Atlantic coast. Rural municipalities are also courting projects; Sisteron’s planned green data center will recycle mountain-water cooling and infuse jobs into Provence. This geographic dispersion diversifies risk for clients and cushions the France data center construction market against localised policy changes.
Regulatory Landscape
France data center construction is shaped by environmental permitting (ICPE) and local urban-planning rules (PLU), alongside energy-connection and performance obligations under the Energy Code. Law No. 2025-391 (DDADUE), effective 30 April 2025, introduced dedicated Energy Code provisions for data center energy performance (Articles L236-1 to L236-3) and ties large facilities to formalized energy and environmental reporting requirements.
From 1 October 2025, data centers above 500 kW must report environmental and energy performance data annually to the European Commission through a digital platform. This raises compliance needs around metering, PUE, water-use monitoring, and heat-recovery documentation during build and commissioning. Grid-connection planning and capacity reservations also influence project sequencing, with the Commission de regulation de l energie (CRE) overseeing methodologies linked to financial contributions for reserving grid capacity for projects under national-interest type procedures. In July 2026, a Senate-adopted proposal (Senate bill 348) signaled potential tightening around siting control by local authorities, water-use charging, and mandatory waste-heat recovery, increasing diligence for developers when selecting locations and cooling strategies.
Competitive Landscape
Domestic engineering conglomerates such as Bouygues Energies and Services, Eiffage ?nergie Systèmes, and Vinci Energies capitalise on long-standing relationships with French utilities and regulators. Bouygues recently delivered a 28 MW UK facility that demonstrated agile phased hand-overs, while Eiffage modernised Telehouse Paris hubs without downtime, showcasing retrofit skill. These credentials help local firms secure state-sponsored and enterprise contracts that emphasise compliance documentation and union labour agreements.
International operators introduce capital depth and global best practice to the France data center construction market. Digital Realty and Equinix pursue campus-based expansion that pre-positions substations and liquid-cooling loops for AI tenants. They often employ design-build subsidiaries, tightening feedback loops between operations and construction. Data4, majority-owned by Brookfield, is scaling modular 6 MW blocks across its campuses, ordering identical electrical rooms to shave procurement lead times.
France Data Center Construction Industry Leaders
-
Bouygues Construction
-
Eiffage
-
Vinci Energies
-
Equans (formerly Engie Solutions)
-
CAP INGELEC
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
The market opportunity set is concentrating around AI-ready, high-power campuses and the enabling infrastructure that sits adjacent to the data hall. Governments are fast-tracking very large power requests, and published pipelines of shovel-ready plots are opening whitespace for contractors and equipment suppliers to deliver high-voltage works, including substations and grid-interface and distribution upgrades, while building in compliance-grade instrumentation for the 500 kW-plus reporting regime that became effective from October 2025.
Named, funded campus initiatives are translating into construction scope beyond standard shells, particularly for shared site infrastructure and electrical systems sized for multi-hundred-megawatt developments. In 2026, Campus AI moved into implementation with a major shared-infrastructure award to Eiffage, and Data4 advanced a large northern France campus plan. Together, these developments reinforce demand for repeatable modular build programs, mechanical designs that support liquid cooling, and heat-reuse integration that fits disclosure and permitting expectations. Geography also continues to support additions in Marseille, where submarine cable landings anchor demand for capacity, while secondary metros benefit as land and build-cost pressure pushes expansions beyond the Paris core.
Recent Industry Developments
- July 2026: Ardian and Verne announced plans to develop a 500MW digital infrastructure campus in the Ile-de-France region with investment up to �5 billion. The project creates a major AI/digital campus hub and expands France's capacity to attract large-scale workloads. The move signals a multi-site campus strategy that could reshape bidding dynamics for French data center workloads.
- June 2026: Data4 launched a 700MW data center campus in Escaudain with a �5 billion investment. The scale strengthens northern France's data center footprint and accelerates capacity for AI workloads. It demonstrates aggressive deployment by a leading operator and expands regional supply-chain capabilities.
- June 2026: Eiffage was selected by Campus AI for shared infrastructure and a 400/33 kV electrical substation at Fouju campus with a contract exceeding �120 million. The arrangement provides high voltage grid and shared infra for AI campuses, enabling rapid development timelines. It validates an integrated civil and electrical delivery approach among French builders.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of construction work delivered to build or expand data centers in France. It includes site preparation and the core facility build and fit-out activities that make space ready for IT load and operations.
Scope exclusions: IT servers, storage, network hardware, and ongoing operations and maintenance spend once the facility is commissioned are excluded.
Segmentation Overview
-
By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
-
By Data Center Type
- Colocation
- Self-build Hyperscalers (CSPs)
- Enterprise and Edge
-
By Infrastructure
-
By Electrical Infrastructure
- Power Distribution Solution
- Power Backup Solutions
-
By Mechanical Infrastructure
- Cooling Systems
- Racks and Cabinets
- Servers and Storage
- Other Mechanical Infrastructure
- General Construction
- Service (Design and Consulting, Integration, Support and Maintenance)
-
By Electrical Infrastructure
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to map the build pipeline, cost drivers, and the policy context that shapes where and how projects move ahead. We rely on public sources such as the French energy regulator (CRE), RTE grid connection and adequacy publications, INSEE construction and price indices, Eurostat energy and construction statistics, and ADEME efficiency guidance to understand constraints that feed directly into construction activity.
We also review permitting and environmental rules, including ICPE disclosures for higher-power sites, along with publicly available trade and infrastructure updates from cable-landing and interconnection ecosystems. To cross-check project timelines and contractor exposure, we use company filings, investor presentations, and reputable press coverage, then confirm specific financial and contract signals using subscriptions for company financials and intelligence, patents, and global contracts and tenders where relevant. The desk sources listed above are illustrative, and additional public and paid references are used to collect, validate, and clarify data points.
Primary Interviews and Surveys
Primary work is used to confirm what is actually getting built and paid for in the market, particularly when announcements run ahead of execution. Interviews are conducted with contractors, design and engineering teams, equipment integrators, colocation and hyperscale owner-representatives, and permitting and utility-facing specialists across France so that cost and schedule assumptions can be stress-tested.
Respondent inputs are used to refine typical cost per MW by build type, the split between new builds and expansions, the share of projects delayed by power availability, and how cooling and efficiency requirements are changing scope, for example higher-density halls and water constraints.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 28% | CXOs: 14% |
| Mid tier: 58% | Functional/Unit leaders: 30% |
| Smaller Players: 14% | Managers: 56% |
Market-Sizing & Forecasting
Sizing starts from a top-down build-out of France data center capacity additions and expansion activity. The demand pool is reconstructed using planned MW, build phasing, and likely construction intensity by site type. These totals are then corroborated with selective bottom-up checks, including sampled project cost ranges, supplier and contractor revenue exposure checks, and channel feedback on equipment-led portions that are typically booked under construction budgets.
The model uses practical inputs that can be updated each year, including MW under construction versus early-stage pipeline, average construction cost per MW for different site formats, electrical and mechanical scope mix, regional labor and materials inflation, and time-to-permit and grid-connection lead times. Where project-level data is incomplete, we apply conservative gap handling by using ranges from confirmed similar builds in France and then adjusting for site size and efficiency requirements.
Forecasting is run using scenario analysis supported by trend smoothing, since project schedules can shift when power availability or permitting slows. Growth paths are anchored to what primary experts expect for committed capacity, price movement in key construction packages, and the pace of retrofits needed to support higher-density AI loads.
Data Validation & Update Cycle
Outputs are checked against independent signals so the market stays tied to what is happening on the ground, not only to project announcements. We compare implied spend to MW delivery cadence, to construction cost indices, and to known constraints such as grid connection timing and ICPE-driven design changes, then review outliers before final totals are signed off.
A second analyst review is used to challenge assumptions, rerun sensitivity checks, and confirm that currency handling and inflation treatment are consistent across the time series. Reports refresh annually, with interim updates triggered when a material policy change, major project cancellation, or step-change in construction pricing is confirmed. A final pre-delivery pass is done so clients receive the latest updated view.
黑料不打烊's France Data Center Construction Market Size Compared With Other Published Estimates
Published market values for France data center construction can vary widely because each publisher draws the line around what counts as construction spend, and because project timing is treated differently. Some estimates are built around announcements, while others emphasize executed work and paid construction milestones, which can change the size in any single year.
Key gaps usually come from whether IT hardware and refurbishment-only upgrades are included, how cost per MW is updated for current labor and materials inflation, and whether the model counts only core facility scope or also adds adjacent items such as multi-year operations budgets. The spread is also influenced by currency conversion timing and how quickly regulatory requirements, such as ICPE disclosures for higher-power sites, are reflected in design and cost assumptions, a consistency check kept in the France build model used by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 5.20 B (2025) | |
| Global Consultancy A | USD 6.23 B (2024) | Uses a broader spend definition that folds in IT hardware and some fit-out upgrade programs, which inflates the number versus construction-only scope. |
| Industry Analytics B | USD 5.63 B (2025) | Built from announced budgets and planned campus capex, which can overstate near-term value when grid-connection and permitting delays push real spend into later years. |
Overall, the comparison shows that the biggest drivers are scope boundary choices and how project timing is recognized across years. By keeping inputs tied to MW-based build activity, updated construction cost indices, and execution checks from primary feedback, the resulting market value stays easier to explain and repeat when assumptions change.


Key Questions Answered in the Report
What is the market size of the France data center construction market in 2026?
The industry is valued at USD 5.59 billion in 2026.
How fast is the market expected to grow?
It is forecast to expand at a 7.49% CAGR, reaching USD 8.01 billion by 2031.
Which tier classification is growing the quickest?
Tier 4 builds are projected to grow at 7.87% annually because AI and fintech workloads demand fault-tolerant designs.
Why are hyperscalers increasing self-build activity in France?
Low-carbon nuclear power, shovel-ready plots and strict data-sovereignty rules encourage cloud providers to own facilities and secure long-term capacity.
Page last updated on:
- Data Center Server Market Global servers demand, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- France Hyperscale Data Center Market France's hyperscale sites, split by facility type, component and tier.
- Germany Hyperscale Data Center Market Hyperscale sites demand across Germany, covering facility type, component and tier.
- Brazil Data Center Server Market Servers in Brazil, split by tier, facility size and facility type.
- Japan Data Center Server Market Servers in Japan, split by tier, facility size and facility type.



