
Europe Powder Coatings Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.75 Billion |
| Market Size (2026) | USD 3.86 Billion |
| Market Size (2031) | USD 4.49 Billion |
| Growth Rate (2026 - 2031) | 3.05 % |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Europe Powder Coatings Market Analysis by 黑料不打烊
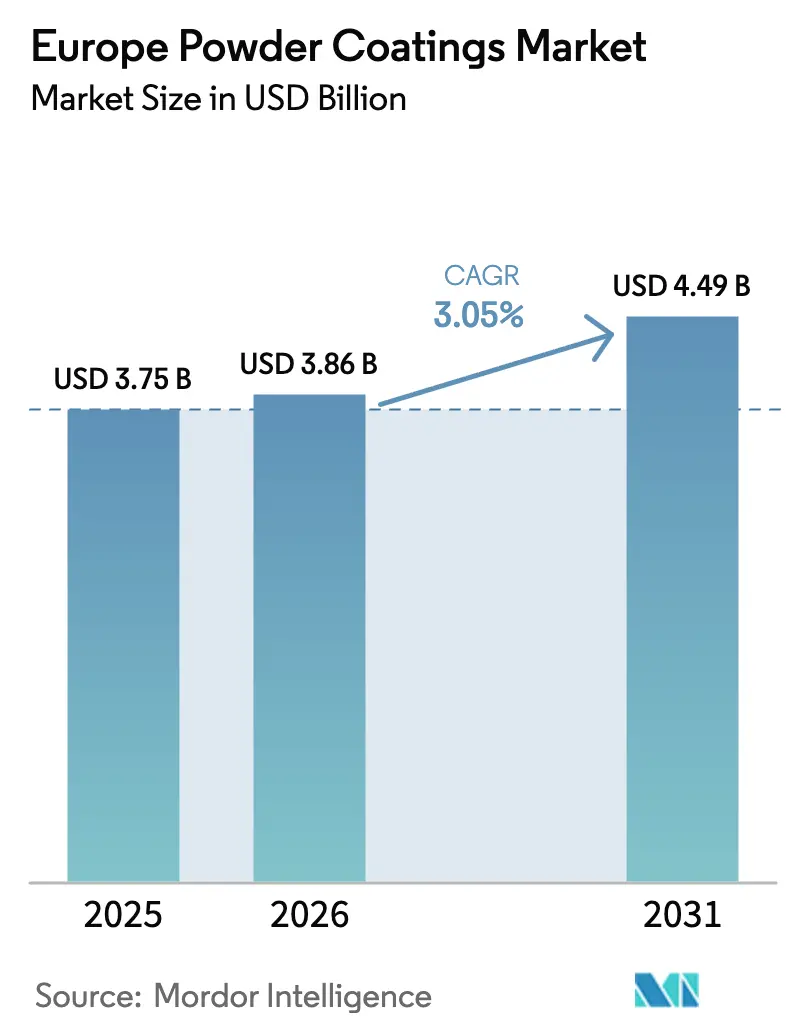
The Europe Powder Coatings Market size was valued at USD 3.75 billion in 2025 and estimated to grow from USD 3.86 billion in 2026 to reach USD 4.49 billion by 2031, at a CAGR of 3.05% during the forecast period (2026-2031). Consistent regulatory tightening on volatile organic compound (VOC) emissions, rapid advances in low-temperature curing chemistries, and the modernization of European industrial assets underpin this growth trajectory. Demand expansion remains broad-based: architecture and infrastructure projects adopt durable polyester powders, automotive producers specify new polyurethane grades for battery housings, and machinery builders shift toward energy-efficient finishing lines. Competitive positioning hinges on sustainable formulations that exclude per- and polyfluoroalkyl substances (PFAS), automation-ready application equipment, and the ability to localize raw-material sourcing amid ongoing anti-dumping duties. The drive toward carbon-neutral manufacturing further solidifies powder technologies as the preferred choice for original equipment manufacturers (OEMs) seeking to reduce embodied emissions throughout product lifecycles. Meanwhile, supply-side challenges, ranging from titanium dioxide duty surcharges to epoxy resin price spikes, continue to prompt capacity rationalizations, regional sourcing strategies, and hedging mechanisms to protect profitability.
Key Report Takeaways
- By resin type, polyester captured 42.01% of the Europe Powder Coatings market share in 2025, while polyurethane is projected to expand at a 3.62% CAGR through 2031.
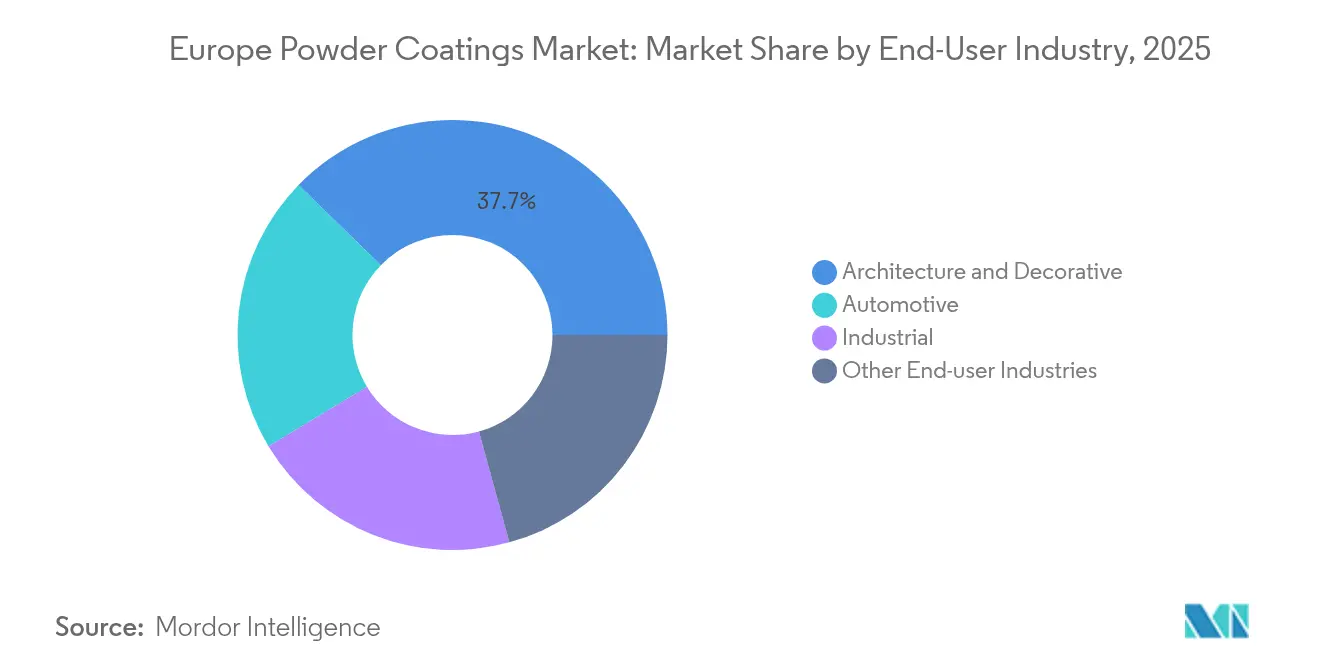
- By end-user industry, architecture and decorative held 37.70% revenue share of the Europe Powder Coatings market size in 2025, whereas automotive is advancing at a 3.4% CAGR over the forecast horizon.
- By geography, Germany led with 21.08% of the Europe Powder Coatings market share in 2025; Rest of Europe is set to post the highest 3.22% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Europe contributes to a system defined not by any single geography but by the interaction of many. The global powder coatings market data by 黑料不打烊 represents that combined structure.
Europe Powder Coatings Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent EU VOC and carbon-neutrality regulations | +0.8% | EU-wide, strongest in Germany, France, Nordic countries | Medium term (2-4 years) |
| Rising automotive OEM and aftermarket powder usage | +0.6% | Germany, Czech Republic, Slovakia, Poland | Short term (≤ 2 years) |
| Growth of architectural aluminium extrusion demand | +0.5% | Central and Eastern Europe, Italy, Spain | Medium term (2-4 years) |
| Superior recyclability and first-pass transfer efficiency | +0.4% | Global, early adoption in Nordic countries | Long term (≥ 4 years) |
| Low-temperature cure powders enable MDF and plastics | +0.3% | Germany, Italy, Poland, furniture manufacturing hubs | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Stringent EU VOC and carbon-neutrality regulations
The Industrial Emissions Directive and the EU Green Deal combine to cap VOC stack emissions at 20 mg/m? for several surface-treatment categories, effectively prioritizing solvent-free powder processes. Facilities emitting more than 200 tonnes of solvent annually must achieve compliance within four years, accelerating capital deployment toward closed-loop powder booths and energy-efficient curing ovens[1]European Commission, “Industrial Emissions Directive: Best Available Techniques Conclusions for Surface Treatment of Metals,” eur-lex.europa.eu. New PFAS thresholds for food-contact coatings and revised REACH Annex XVII restrictions reinforce the transition by penalizing fluorinated chemistries typical in many liquid systems. Automotive refinish markets now require VOC labeling, with Denmark limiting cleaners to 200 g/L and specialty finishes to 840 g/L, a policy stance that has been quickly mirrored in other Nordic states. ISO 14001 audits are increasingly mandating the use of powder as the “best available technique,” thereby embedding conversion objectives into corporate environmental roadmaps.
Rising automotive OEM and aftermarket powder usage
Electrification reshapes finishing requirements: battery enclosures, cooling plates, and high-voltage casings demand electrically insulative yet thermally conductive coatings. Automakers are therefore adopting low-bake powders that cure at 80 °C—down from legacy 140 °C cycles—cutting paint-shop energy consumption by 11-13% and improving mixed-substrate processing flexibility. Supplier qualification hinges on meeting AAMA standards for weatherability and OEM Class A finish criteria, eroding the competitive position of incumbent liquid suppliers. Wheel refurbishers, commercial-vehicle upfitters, and agricultural equipment remanufacturers likewise migrate toward powders for their abrasion resistance and long service life.
Growth of architectural aluminum extrusion demand
EU transport and energy corridors—backed by more than EUR 7 billion in approved projects—continue to lift demand for coated extrusions in rail stations, port terminals, and photovoltaic mounting systems. AkzoNobel’s Interpon D Stone Effect line demonstrates the segment’s emphasis on lightweight, realistic stone finishes that comply with Qualicoat Class 1 regulations while meeting Leadership in Energy and Environmental Design (LEED) scoring requirements. Southeast European extrusion giant Alumil operates eight powder lines with an annual capacity of 57,500 tonnes, underscoring the region’s architectural appeal. Performance specifications such as AAMA 2605 (10,000-hour Florida exposure) drive demand for super-durable polyester formulations.
Superior recyclability and first-pass transfer efficiency
Closed-loop reclaim systems enable powder booths to achieve more than 95% transfer efficiency, significantly reducing hazardous waste volumes compared to solvent-borne facilities[2]AkzoNobel, “Interpon Powder Coatings Sustainability Whitepaper,” akzonobel.com . Sherwin-Williams’ Powdura ECO line embodies the circular economy promise by incorporating 25% post-consumer PET, equivalent to 16 recycled water bottles per pound of coating. PPG’s Enviroluxe Plus eliminates intentionally added PFAS and incorporates 18% post-industrial plastic, shrinking its cradle-to-gate carbon footprint by 30%. Reclaimable overspray and simplified end-of-life disassembly strengthen OEM take-back initiatives across appliances and mobility equipment.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Difficulty in achieving <30 ?m smooth films | -0.4% | Germany, Italy, precision manufacturing regions | Short term (≤ 2 years) |
| High retrofit CAPEX for liquid-to-powder conversion | -0.6% | Southern Europe, SME-concentrated regions | Medium term (2-4 years) |
| EU anti-dumping duties inflating epoxy resin prices | -0.3% | EU-wide, strongest impact on price-sensitive segments | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Difficulty in achieving less than 30 ?m smooth films
Premium automotive interiors and consumer electronics housings require near-perfect surface topography at film builds of less than 30 ?m. Current powder formulations rely on narrow particle-size distributions and specialty flow modifiers, yet maintaining uniformity on complex geometries remains challenging. Allnex’s ultra-low-temperature hybrids cure at 125 °C and improve leveling, but they necessitate tighter humidity control and advanced application hardware. Evonik’s spherical SPHERILEX AC 45 pigments enhance dispersion but require reformulation work across the value chain. Until turnkey solutions reach market maturity, liquid systems retain a technical edge in select high-gloss sectors.
High retrofit CAPEX for liquid-to-powder conversion
Swapping a solvent line for powder typically demands new booths, cyclone separators, infrared or convection ovens, and compressed-air upgrades, with basic installations costing upward of EUR 500,000; fully automated lines run into the multimillion-euro range. European Investment Bank data show that 25% energy-price inflation between 2023 and 2024 eroded discretionary budgets, particularly for SMEs in Southern Europe. Although EU climate grants cover approximately 36% of eligible capital expenditure, application complexity and co-financing requirements deter smaller operators. Leasing constraints and uncertain production volumes further dampen retrofit appetite despite the long-run operational savings.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Resin Type: Polyester Dominance Faces Polyurethane Innovation
Polyester maintained 42.01% of the Europe Powder Coatings market share in 2025, translating to the largest slice of the Europe Powder Coatings market size. Its popularity stems from favorable economics, broad color latitude, and established supply chains that serve both fa?ade panels and general industrial machinery. Formulators have extended performance envelopes by introducing super-durable grades that meet AAMA 2604 and Qualicoat Class 2 specifications. Conversely, polyurethane grades are projected to grow at a 3.62% CAGR, as automotive manufacturers pursue lighter structures and extended corrosion warranties. Low-temperature urethane chemistries also enable coating of medium-density fiberboard (MDF) fixtures, opening incremental opportunities in European furniture hubs.
Technological advancements now center on curing efficiency. AkzoNobel’s Interpon D2525 Low-E polyester requires just 150°C, cutting booth dwell times by 20% and widening applicability to heat-sensitive alloys. Allnex’s CRYLCOAT 4488-0 offers decade-long Florida exposure resistance, while TGIC-free systems dominate new capacity due to impending toxicological re-classifications. Epoxy resins continue to underpin pipeline valves and chemical reactors; hybrids bridge decorative and functional needs; acrylics target ultra-weatherable signage; and niche thermoplastics serve household-appliance and anti-graffiti segments. Across these chemistries, powder suppliers increasingly tout Environmental Product Declarations (EPDs), aligning formulations with customer carbon audits.


By End-User Industry: Architecture Leadership Meets Automotive Acceleration
The architecture and decorative segment accounted for 37.70% of the Europe Powder Coatings market in 2025, buoyed by public-sector building retrofits that specify 15-year warranties and chromium-free pre-treatments. Aluminum curtain-wall systems, metal roofing, and street furniture drive tonnage, while color-stable matte finishes gain popularity among specifiers. Compliance with EN 13523 accelerated conversion from liquid polyesters as municipalities require near-zero VOC construction materials.
Automotive applications are forecast to post the fastest 3.4% CAGR through 2031, as electric vehicle output multiplies. Battery pack enclosures, brake calipers, and alloy wheels feature two-coat powder builds that combine epoxy primers with polyurethane topcoats. Magna notes that switching to 80 °C cure cycles reduced annual paint-shop energy by 20 GWh at its Graz facility. Elsewhere, general industry, including agricultural equipment, compressors, and machine tools, embraces powders to meet enhanced salt-spray benchmarks. Appliance OEMs exploit single-coat systems that eliminate primer stages and enhance factory throughput, while European furniture producers specify soft-touch polyurethane powders on MDF to bypass solvented lacquers.
Geography Analysis
Germany commanded 21.08% of the Europe Powder Coatings market in 2025, supported by a EUR 263 billion machinery sector employing 955,000 people and exporting 81% of output. Fully automated robotic lines, such as those at Hans Stork Oberfl?chentechnik, utilize dense-phase spray guns and closed-loop reclaim systems to meet Federal Emission Control mandates. The nation’s vocational training landscape supplies skilled coaters, enabling high first-run yields and reduced color change downtime. Energy-efficiency subsidies further encourage upgrades to variable-frequency drive ovens and advanced air-handling units.
Rest of Europe represents the fastest-growing sub-region, set to advance at a 3.22% CAGR through 2031. EU-backed infrastructure outlays, EUR 7 billion for rail corridors and EUR 850 million for grid interconnectors, drive aluminum extrusion and structural-steel demand. Investment rates reached 78% among Central and Eastern Europe manufacturing firms in 2024, with 33% of capital expenditures directed to machinery replacement, which often includes powder-coating lines. Automation adoption is brisk, with 45% of surveyed plants implementing IoT sensors and robotic sprayers to improve coating consistency.
Western Europe, encompassing the United Kingdom, France, Italy, and Spain, shows stable replacement demand. The UK ban on hexavalent chromium in 2024 accelerated adoption of titanium-zirconium and silane pre-treatments compatible with powders; Powdertech Corby reports full chrome-free processing across fa?ade contracts. Italy’s Emilia-Romagna furniture cluster increasingly specifies low-cure powders for MDF to bolster export competitiveness. Nordic markets pioneer PFAS-free formulations, incentivized by stringent environmental labeling schemes and consumer preference for circular products. Benelux benefits from Antwerp-Rotterdam chem-port proximity, ensuring secure feedstock supply for formulators and toll coaters.
The powder coatings market is analyzed by 黑料不打烊 across multiple other geographies, with in-depth regional assessments available for North America.
Regulatory Landscape
EU chemical and product rules are continuing to steer formulators toward powder systems, with tighter control of hazardous substances and more rigorous documentation requirements. In May 2026, REACH Annex XVII was amended to restrict substances including NMP, DMF, and certain benzotriazoles relevant to industrial coatings, and ECHA set an import-related limit for NMP in industrial coatings of 0.1% by weight effective August 1, 2026, increasing compliance pressure on cross-border supply into the EU. In parallel, the Industrial Emissions Directive framework and Best Available Techniques for surface treatment reinforce low-VOC finishing choices used by metal processors and OEM coat shops.
Packaging requirements add additional compliance touchpoints for coatings used within packaging value chains. The Packaging and Packaging Waste Regulation (EU) 2025/40 applies from August 12, 2026 and, in defined cases, frames coatings firms as packaging manufacturers, increasing the need for material disclosure, conformity evidence, and traceable formulations. Separately, ECHA opened a public consultation in June 2026 on a draft REACH Annex XVII amendment targeting very low total PFAS limits in industrial coatings, keeping PFAS-free formulation roadmaps and supplier declarations central for powder producers serving sensitive end uses.
Value Chain Analysis
The European powder coatings value chain begins with upstream petrochemical and mineral inputs, including resins such as polyester, epoxy, and polyurethane systems, curing agents, pigments, and additives. Compounding and manufacturing then follow through steps such as premixing, melt extrusion, cooling and flaking, milling/classification, and quality control. Finished powders are distributed through direct-to-OEM channels and regional distributors to job coaters and captive coating lines serving architecture (aluminum extrusions and fa?ade panels), industrial equipment, appliances, and automotive components. Application and integration providers, including booths, guns, reclaim systems, and ovens, remain key enablers, since line design, transfer efficiency, and curing energy shape total applied cost and influence whether customers can convert from liquid systems.
Midstream differentiation increasingly centers on compliance and sustainability documentation tied to customer procurement rather than coating chemistry alone. Europe has a high concentration of Environmental Product Declarations (EPDs) for paints and coatings, and a renewal wave in late 2026 is expected to raise demand for updated lifecycle data from resin, pigment, and additive suppliers through to powder manufacturers. Technology co-development is also becoming more visible across the chain, including partnerships that link coatings producers, appliance OEMs, and laser-technology providers to reduce curing energy and line footprint. Those changes feed back into formulation requirements, including powder response to alternative curing profiles, and into qualification cycles at OEM finishing lines.
Competitive Landscape
The Europe Powder Coatings market features moderate concentration. AkzoNobel, PPG Industries, Sherwin-Williams, Axalta, and BASF command brand loyalty through extensive distributor networks, a broad range of color libraries, and localized technical service centers. Their R&D pipelines prioritize low-bake chemistries, recycled-content binders, and PFAS-free additives. Raw-material inflation remains a shared headwind: January 2025 titanium dioxide duties of EUR 0.25–0.74/kg inflated the cost of goods sold by 4–6%, prompting formulators to consider alternative pigments, such as Venator’s TMP- and TME-free TIOXIDE TR81. Epoxy anti-dumping tariffs reaching 40.8% accelerate a pivot to polyester-dominant portfolios and regional resin suppliers. Energy price volatility incentivizes the adoption of infrared boost zones and recuperative burners to mitigate exposure to natural gas.
Europe Powder Coatings Industry Leaders
-
Akzo Nobel N.V.
-
Jotun
-
PPG Industries, Inc
-
The Sherwin-Williams Company
-
Axalta Coating Systems, LLC
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Reformulation and compliance-led substitution create whitespace for suppliers that can offer PFAS-free, lower-hazard portfolios while maintaining finish quality and weatherability across architectural and industrial applications. The tighter REACH-related focus on substances used in industrial coatings, alongside continued PFAS scrutiny, increases the value of verified raw-material declarations and product documentation. This aligns with expanding EPD use in European coatings procurement and the late-2026 EPD renewal cycle, supporting opportunities in premium architectural powders that meet Qualicoat and AAMA classes and carry stronger environmental documentation for public and commercial projects.
Process innovation and capacity alignment around OEM manufacturing needs are also tangible opportunity areas. AkzoNobel’s expansion of powder coatings capacity at Como (Italy) and Arnsberg (Germany) reflects investment tied to automotive-facing and specialty powder demand in Europe. PPG’s work with IPG Photonics and Whirlpool to commercialize laser-based powder curing points to a pathway to reduce curing energy and cycle time constraints that can limit powder adoption. On inputs, recycled-content and lower-carbon feedstocks are moving from pilot work to broader commercialization, and collaborations such as AkzoNobel with Arkema and BASF on bio-attributed raw materials provide a reference model for differentiation in architecture and general industrial segments where embodied-carbon reporting is increasingly requested by customers.
Recent Industry Developments
- March 2026: PPG collaborated with IPG Photonics and Whirlpool to accelerate the commercialization of laser curing systems for powder coatings, featuring a pilot finishing line at its Strongsville, Ohio facility. The collaboration strengthens PPG's position in advanced powder coating solutions and could shorten time-to-market for laser cured products.
- January 2026: Jotun announced a 113 million euro investment for a new paint and coatings manufacturing facility in Abu Dhabi, UAE, via a 50-year lease with KEZAD Group. The investment expands Jotun's regional production capacity and supports supply security for high-performance coatings in the Middle East.
- September 2025: AkzoNobel partnered with Arkema and BASF to utilize bio-attributed raw materials for lower-carbon architectural powder coatings in Europe. The alliance advances sustainable formulations and could bolster demand for eco friendly finishes in European construction markets.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market is the value of powder coating materials sold for use across Europe, measured at the point where coating producers sell into channels or directly to end users, and reported in USD.
Scope exclusions: This sizing does not count powder coating application equipment, curing ovens, booths, or third party coating service revenue.
Segmentation Overview
-
By Resin Type
- Epoxy
- Polyester
- Epoxy-Polyester (Hybrid)
- Polyurethane
- Acrylic
- Other Resin Type (Thermoplastic (Polyvinyl Chloride, Polyolefins,etc.)
-
By End-user Industry
- Architecture and Decorative
- Automotive
- Industrial
- Other End-user Industries (Furniture, Appliances, etc.)
-
By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- NORDIC Countries
- Rest of Europe
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the basic demand picture for powder coatings in Europe and to keep country-level assumptions realistic before we spoke to the market. We relied on public, repeatable data sets such as Eurostat industrial production series, UN Comtrade trade statistics for related chemicals and resins, and European Chemicals Agency (ECHA) pages on restrictions that affect coating formulations and solvent substitution.
To connect coatings demand with end use activity, we also referenced sources such as ACEA for vehicle production signals, EU construction and renovation indicators available through official statistics, and technical papers in peer reviewed journals that discuss powder coating transfer efficiency and curing trends. Company annual reports, investor decks, and reputable industry press were reviewed as well, and a paid subscription for company financials, patent lookups, and shipment level trade checks was used selectively where needed. The sources listed here are illustrative only, and additional public and paid references were used to collect, validate, and clarify inputs.
Primary Interviews and Surveys
Primary work centered on interviews and surveys with formulators, distributors, applicators, and procurement teams in key end user industries, followed by country level checks across major European manufacturing hubs. These discussions helped confirm mix shifts (for example, thermoset use in general industrial parts), typical pricing movement by resin family, and which end markets were recovering or slowing. We then tightened our assumptions based on what respondents consistently reported at the country and application level.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 35% | CXOs: 18% |
| Mid tier: 47% | Functional/Unit leaders: 30% |
| Smaller Players: 18% | Managers: 52% |
Market-Sizing & Forecasting
The sizing model starts with a top-down reconstruction of the Europe demand pool, where industrial output and end use build rates are translated into coating consumption using typical coating weights, adoption share for powder versus liquids, and country level manufacturing mix. Once that total is formed, it is cross-checked using selective bottom-up approximations such as sampled producer revenue splits by Europe, distributor channel checks, and an ASP times volume sanity test on a small set of high volume end uses.
The inputs that mattered most included powder coating penetration in general industrial and automotive parts, resin mix trends tied to performance needs (epoxy, polyester, and hybrids), average selling price progression under energy and raw material movements, and the pace of EU manufacturing recovery by country. Forecasts were built using scenario analysis, where the demand path was adjusted under different assumptions for industrial production, construction activity, and substitution toward low VOC coating systems. When bottom-up views were incomplete for smaller countries, gaps were handled through peer country ratios, then corrected using interview feedback before final totals were locked.
Data Validation & Update Cycle
Outputs were validated by comparing the model totals against independent signals such as resin import patterns, industrial production trends, and publicly visible capacity or line utilization commentary from major producers. Outliers were flagged, checked at the country and end use level, and then reviewed by another analyst before sign off.
The report is refreshed annually, and interim updates are triggered if material events occur, such as sharp raw material shocks or major regulatory moves impacting coatings. Before delivery, we run a fresh pass across key assumptions, recheck conversion rates and currency timing, and reconnect with selected contacts if a variance is still unexplained.
黑料不打烊's Europe Powder Coatings Market Size Measured Against Other Published Estimates
Published market values for Europe powder coatings can differ a lot, even when the topic sounds the same, because each publisher uses its own scope, pricing logic, and timing for the base year. Differences also show up when some studies mix in services or application related revenue that sits outside material sales.
Some external figures appear to include broader coatings related revenue streams, or they apply an aggressive rebound path after a weak industrial cycle, which pushes the number up quickly. In 黑料不打烊, only powder coating material revenue within the Europe country set is counted, and pricing is normalized through country checks so one large market does not skew the region total.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 3.75 B (2025) | |
| Regional Consultancy A | USD 4.19 B (2025) | Uses a wider definition that appears to fold in adjacent coating related revenue beyond powder materials, and it also assumes faster price expansion without consistent country level validation. |
| Industry Consultancy B | USD 2.38 B (2023) | Anchored to an older base year with limited inflation and currency normalization, and it likely undercounts smaller markets by relying on a narrower set of end use demand proxies. |
The spread in the table is mainly explained by scope choices and base year treatment, followed by how ASP change is carried through the forecast. Our estimate stays traceable to a clear material only revenue definition, practical demand indicators, and repeatable checks that can be re-run when new industrial data becomes available.


Key Questions Answered in the Report
What is the current value of the Europe powder coatings market?
The market is valued at USD 3.86 billion in 2026.
How fast will demand for powder coatings in automotive applications grow?
Automotive usage is projected to post a 3.4% CAGR from 2026 to 2031 as electric-vehicle output scales.
Which resin type dominates European powder formulations?
Polyester resins lead with 42.01% share in 2025 due to cost-effectiveness and weatherability.
Why are European manufacturers converting from liquid to powder systems?
Powder technologies eliminate VOC emissions, cut energy consumption through low-temperature curing, and enable closed-loop recyclability, aligning with EU carbon-neutrality targets.
Which European region will see the fastest growth?
Rest of Europe is expected to record a 3.22% CAGR from 2026 to 2031, driven by large-scale infrastructure investments.
Page last updated on:



