
Dining Tables Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 9.23 Billion |
| Market Size (2031) | USD 12.52 Billion |
| Growth Rate (2026 - 2031) | 6.29 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Asia Pacific |
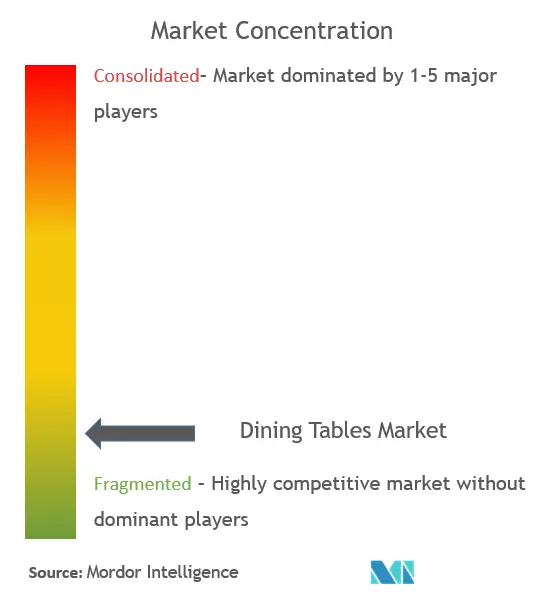
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Dining Tables Market Analysis by 黑料不打烊
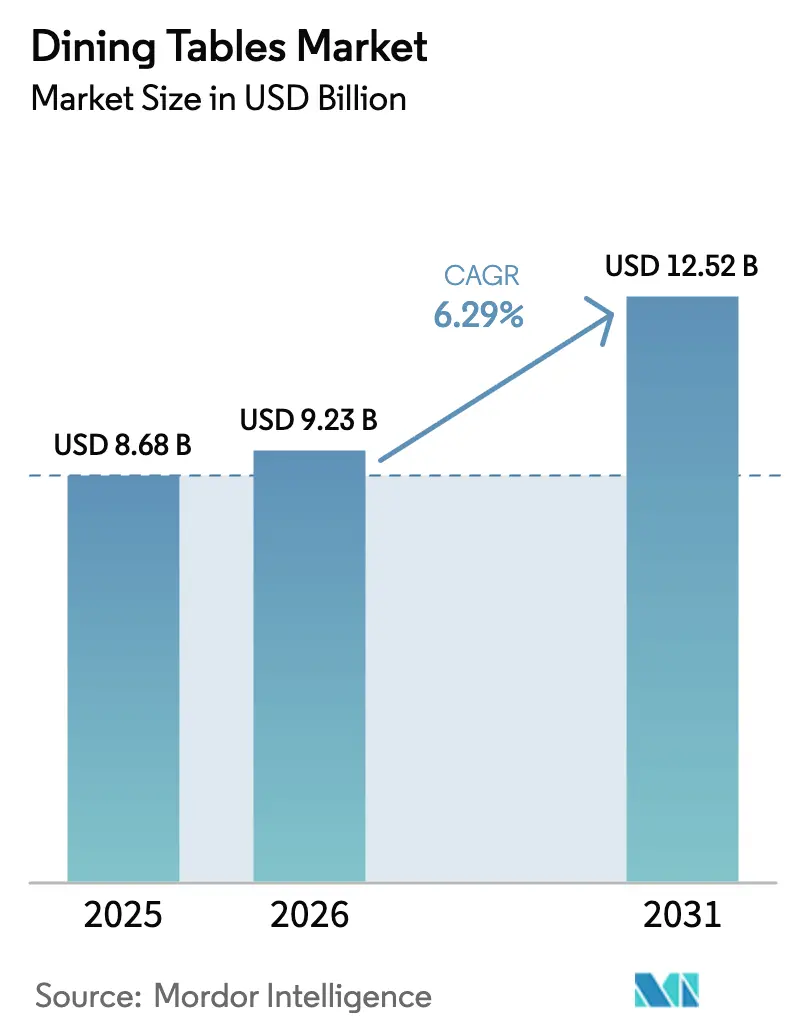
The dining table market size was valued at USD 8.68 billion in 2025 and estimated to grow from USD 9.23 billion in 2026 to reach USD 12.52 billion by 2031, at a CAGR of 6.29% during the forecast period (2026-2031). Robust demand for premium, multifunctional pieces and sustained home-improvement spending keep the dining table market on an upward path even as raw-material and freight inflation persists. Rapid urbanization in Asia-Pacific and expanding online retail access worldwide are enabling both volume growth and product mix upgrades. Meanwhile, sustainability credentials—particularly certified wood and low-VOC finishes—have shifted from niche differentiators to mainstream purchase criteria. Manufacturers are also capitalizing on 3D configuration and AR visualization tools that shorten consideration cycles and lift conversion, especially in secondary and tertiary cities.
Key Report Takeaways
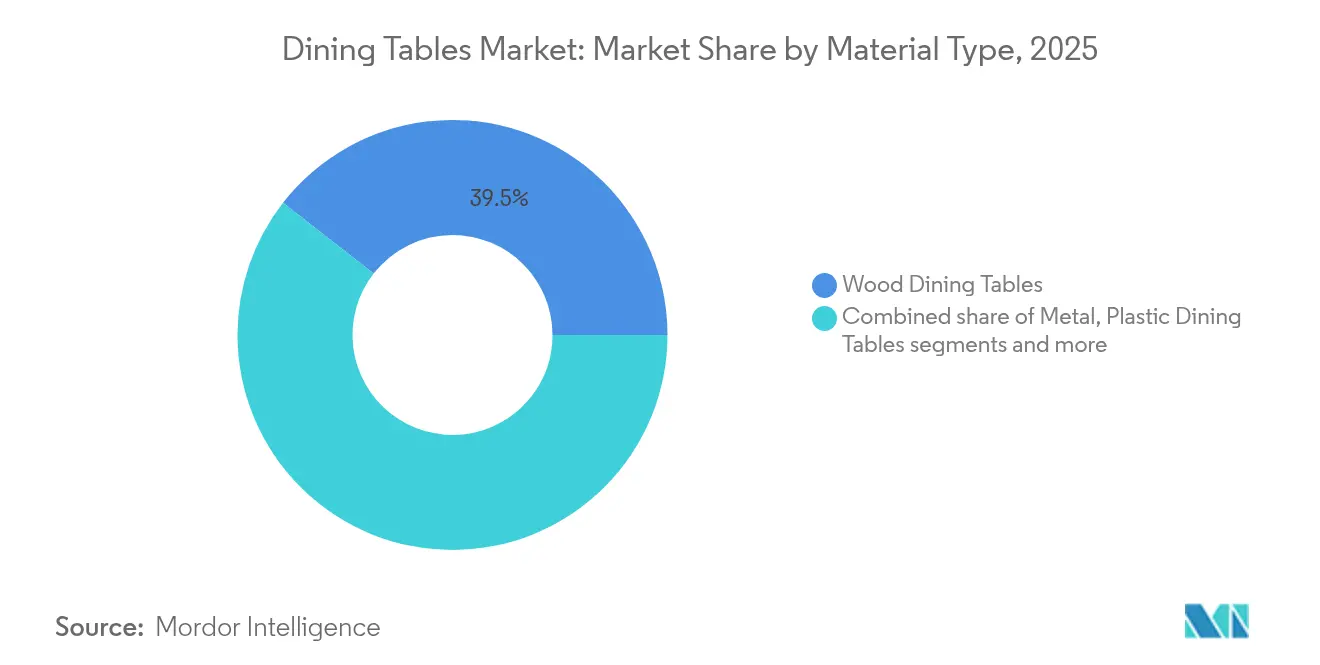
- By material type, wood maintained 39.45% of the dining table market share in 2025, while metal tables are projected to expand at a 6.44% CAGR through 2031.
- By shape, rectangular designs led with 44.20% revenue share in 2025; oval tables are advancing at a 6.72% CAGR to 2031.
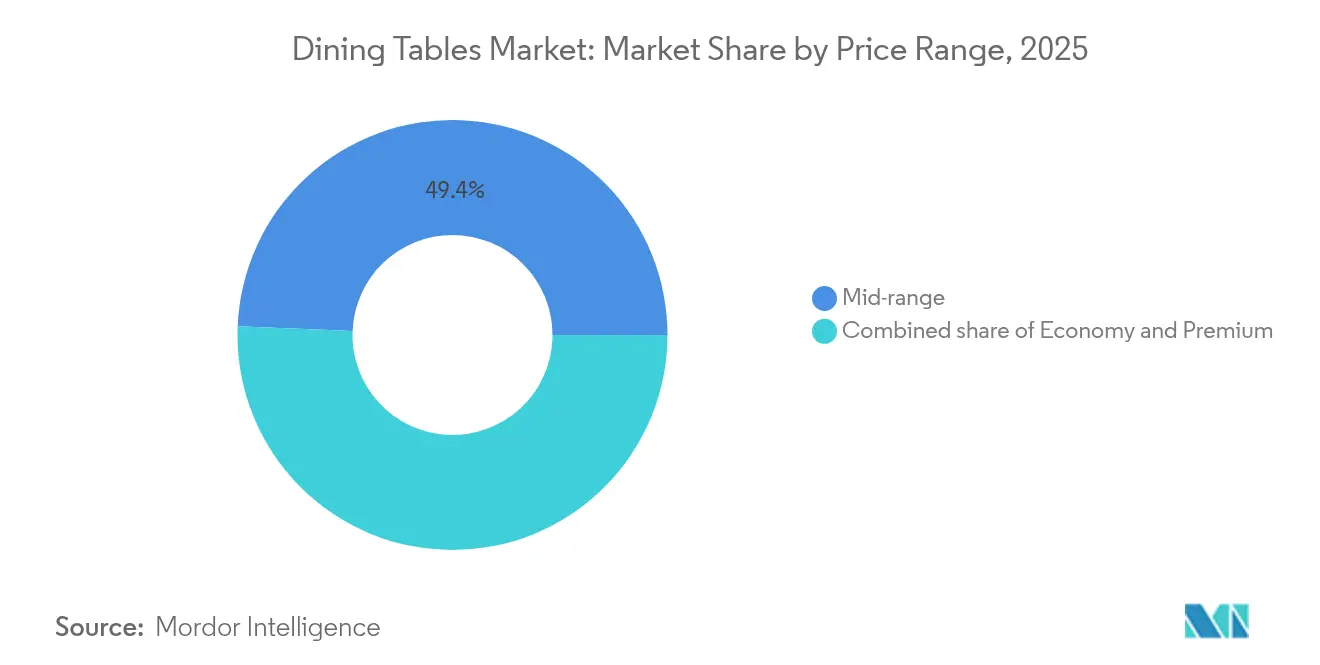
- By price range, the mid-range segment accounted for 49.35% of the dining table market size in 2025, whereas the premium tier is growing at a 7.01% CAGR.
- By distribution channel, specialty furniture stores held a 34.55% share in 2025, but online sales are forecast to rise at a 7.38% CAGR.
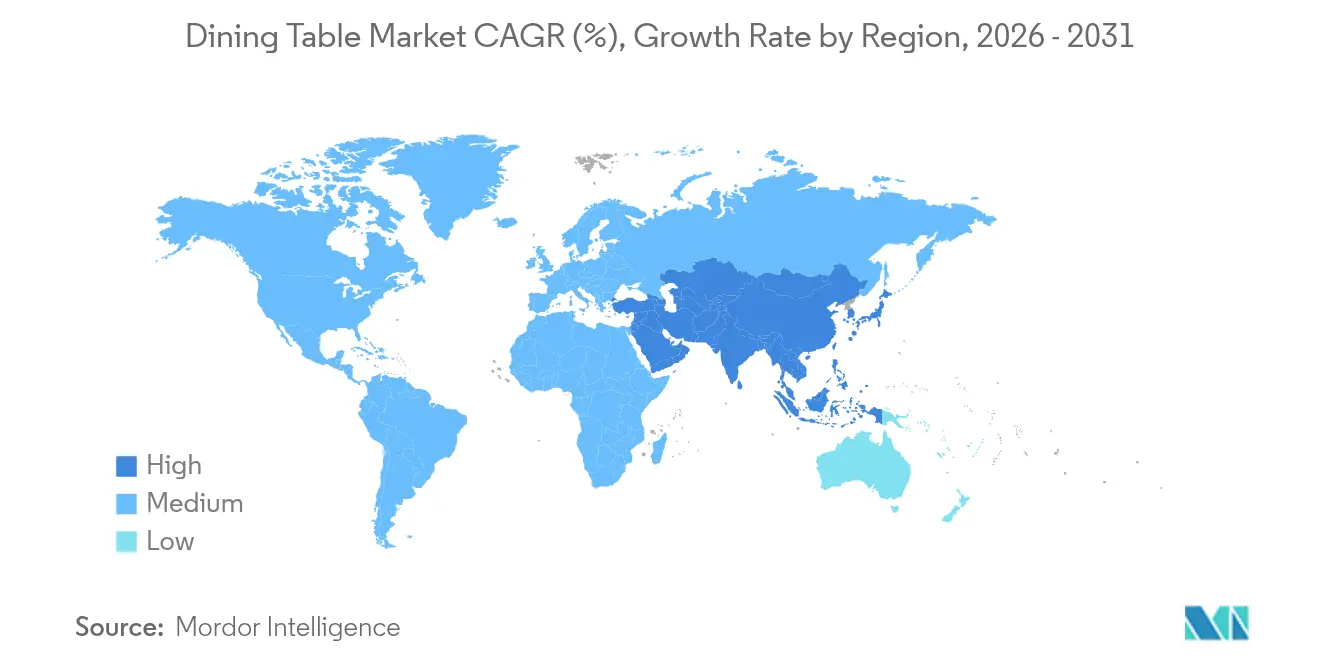
- By geography, Asia-Pacific captured 42.60% of the dining table market share in 2025 and is expected to sustain the fastest regional CAGR of 6.86% to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Dining Tables Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shrinking urban living spaces are boosting demand for compact, extendable tables | +1.8% | Asia-Pacific, Europe | Medium term (2-4 years) |
| Online furniture retail penetration is accelerating market access | +1.5% | North America, Europe | Short term (≤ 2 years) |
| Rising preference for certified sustainable wood and low-VOC finishes | +1.2% | Europe, North America | Medium term (2-4 years) |
| Surge in home-improvement spending energizing residential dining purchases | +1.0% | North America, Asia-Pacific | Short term (≤ 2 years) |
| Mass customization and 3D configurators are elevating average selling prices | +0.7% | North America, Europe | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Urban Living Spaces Shrinking Globally Driving Demand for Compact Extendable Dining Tables
The global trend toward urbanization is creating a structural shift in dining table preferences, with space optimization becoming a critical purchase criterion for urban consumers. Shoppers now search for dining pieces that fold, slide, or butterfly open only when more seats are needed, turning the extendable category into one of the fastest-moving segments. The smart designs that win combine smooth, one-person mechanisms with hidden leaves and under-top storage, so a two-seat setting can quickly host a party of eight without wobble or visual bulk. Adoption is most acute in Tokyo, Singapore, and Hong Kong, where shrinking floor areas amplify the value of furniture that transforms from daily to entertaining modes seamlessly.
Accelerating online furniture retail penetration across continents enhances market access
Online furniture shopping has come a long way. Shoppers can now spin a dining table in 3-D, drop it into a live AR view of their room, and see exactly how much space it leaves to walk around. These tools take the guesswork out of a big-ticket purchase, so return rates fall and confidence rises. Retailers that add AI on top go a step further, recommending pieces that match the buyer’s room size and style without endless scrolling. IKEA, Wayfair, and a growing list of peers already rely on this mix of 3-D visuals and AI suggestions, and it shows in higher conversion and happier customers. The payoff for shoppers is a broader choice: even those in small towns now have access to designs that once sat only in big-city showrooms.
Surge in home-improvement spending is fueling residential dining furniture
After the pandemic, households discovered the dining table doubles as a desk, classroom, and game station, and spending patterns still reflect that change. Homeowners are pouring money into makeovers, and dining rooms are cashing in on the trend. When people gut a kitchen or upgrade a bath, they often round out the project with a new table, chairs, or a sideboard that ties the look together. For instance, as of February 2025, United States furniture and home-furnishing retailers booked a 4% year-on-year sales lift, underlining steady investment in domestic comfort. Budgets earmarked for the dining area now sit well above pre-pandemic levels, reflecting how this space has morphed into a hybrid hub for meals, homework, and video calls.
Mass customization & 3D configurators globally elevating average selling prices
Digital product configurators enable buyers to select finishes, leg styles, and dimensions on demand, raising perceived value and enabling brands to command higher margins without commensurate inventory risk. The strongest uptake is evident in North America and Europe, where bespoke options are becoming mainstream within mid-to-premium price tiers.
Restraints Impact Analysis of Dining Tables Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile timber, steel, and freight costs are compressing manufacturer margins | -0.9% | Asia-Pacific, North America | Short term (≤ 2 years) |
| The growing popularity of kitchen islands & breakfast counters is reducing the need for separate tables | -0.7% | North America, Europe | Medium term (2-4 years) |
| A Fragmented, unorganized manufacturing base is intensifying price competition | -0.5% | Asia-Pacific, South America | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Volatility in timber, steel & freight costs is compressing global manufacturer margins
Timber prices swung up by 35% while steel moved by 28% during 2024, eroding profitability for lean-inventory producers. Although retail furniture prices fell 2.9% between October 2022 and October 2023, the Bureau of Labor Statistics shows 2025 household-furnishing price indices holding steady, indicating that many producers are absorbing volatility rather than passing it through.[1]Bureau of Labor Statistics, “Consumer Price Index – April 2025,” bls.gov This cost pressure accelerates investment in digital manufacturing and supply-chain optimization.
Highly fragmented, unorganized manufacturing base intensifying price competition worldwide
The prevalence of small-scale workshops—especially in Asia-Pacific and parts of Latin America—creates an oversupply of economy-priced tables, pressuring mid-tier brands to differentiate through design, sustainability, or service.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Dining Tables Market Segment Analysis
By Material Type:
Sustainability reshaping traditional preferencesWood retained leadership with a 39.45% share of the dining table market in 2025, confirming its timeless appeal and compatibility with eco-labelling programs. Metal tables, buoyed by aluminum’s lightweight recyclability, are projected to lead growth at 6.44% CAGR, helping expand the dining table market size for contemporary urban consumers. Hybrid concepts blending wood and metal or stone address demand for visual interest and material authenticity. Innovations such as sand-cast aluminum legs paired with oak tops illustrate how durability and design can coexist while meeting rising sustainability expectations.
Material choices now reflect a wider sustainability calculus encompassing sourcing, production energy, and end-of-life recyclability. Manufacturers highlight FSC-certified lumber, recycled steel alloys, and waterborne finishes to secure a share in premium segments. The trend favors local sourcing to cut transport emissions, a strategy adopted by Chromcraft Revington Douglas to align operational efficiencies with environmental commitments. The dining table market continues to evolve toward materials that balance aesthetics, longevity, and ecological integrity, ensuring competitive relevance through 2031.


By Shape:
Oval tables rising as space-efficiency championsRectangular products captured 44.20% of the dining table market share in 2025, yet oval tables are on track for the quickest expansion at 6.72% CAGR through 2031. Their corner-free geometry improves traffic flow in tight apartments, enhancing social interaction while matching rectangular seating capacity. Extendable variants such as Castlery’s Dillon, which expands from 74.8 to 110.2 inches, exemplify this shape’s adaptability to both daily meals and larger gatherings.
Round and square formats retain dedicated followings where intimacy or geometric symmetry is preferred. Innovations in transformation mechanisms permit more free-form designs, feeding consumer appetite for distinctive furniture statements. Oval and round profiles will keep gaining traction as lifestyles gravitate toward casual, multipurpose spaces.
By Price Range:
The Premium segment defying economic headwindsThe mid-range commanded 49.35% of the dining table market size in 2025, but premium products will post the highest 7.01% CAGR to 2031. Affluent customers favor natural stone, porcelain stoneware, and sculptural wood bases that elevate décor while signaling status. Ceramic and teak root tables illustrate how artisanship and rare materials underpin luxury demand.
Direct-to-consumer brands now unlock “accessible luxury” by eliminating traditional retail mark-ups, satisfying aspirational buyers seeking bespoke finishes and verified sustainability attributes. Meanwhile, the economy tier remains relevant for first-time purchasers, though it faces the sharpest competition from flat-pack imports and unorganized local makers.
By Distribution Channel:
Digital transformation reshaping purchase journeysSpecialty furniture stores secured 34.55% of sales in 2025, valued for tactile assurance and design consultation. Yet online platforms will deliver the fastest 7.38% CAGR, reshaping the path to purchase with immersive 3D visualization that places virtual tables into buyers’ rooms, shrinking the consideration phase and lowering return rates.
Home centers preserve a meaningful share by bundling furniture with broader home-improvement lines. Pop-up showrooms and maker-direct channels enrich omnichannel ecosystems, as evidenced by IKEA’s pop-up showcase at Fulton Market that pairs experiential retail with its expanding e-commerce footprint. Successful brands harmonize physical and digital touchpoints to capture research-online, purchase-offline behaviors endemic to high-involvement categories.
Geography Analysis
APAC Dining Tables Market
Asia-Pacific dominated with 42.60% of global revenue in 2025 and will keep the highest 6.86% CAGR, powered by urban apartment proliferation and rising disposable incomes. Chinese furniture sales climbed 11.7% in early 2025, confirming the region’s momentum. India is accelerating via omnichannel expansions by Godrej Interio and Wooden Street, while Southeast Asian cities—Singapore and Jakarta among them—amplify demand for compact, extendable pieces that resolve urban density challenges.
United States Dining Tables Market
North America ranks second, buoyed by resilient consumer spending and an entrenched home-renovation culture. Stable 2025 CPI readings for household furnishings underscore pricing discipline amid input volatility. Multifunctional tables that toggle between dining and remote-work modes are particularly salient in U.S. suburbs, where flexible living spaces gained permanence post-pandemic.
Germany and United Kingdom Dining Tables Market
Europe exhibits slower topline growth yet commands price premiums anchored in sustainability and design authority. Markets such as Germany and the UK increasingly reward verifiable eco-labels, encouraging domestic manufacturers to emphasize circular-economy credentials. The UK’s vibrant online furniture scene—propelled by retailers like John Lewis—confirms e-commerce’s central role in future sales expansion.
South America and MEA Dining Tables Market
South America and the Middle East & Africa remain smaller but growing. Brazil leverages abundant native woods, while UAE and Saudi Arabia fuel premium sales tied to rising expat and tourist influxes.

Value Chain Analysis
The dining table value chain starts with raw-material sourcing (solid wood, engineered panels, metals, glass/stone, coatings, and hardware) and progresses through component processing (kiln drying, panel pressing, casting/extrusion, machining), product engineering, and assembly/finishing (including low-VOC coatings and packaging optimized for parcel and flat-pack). Compliance and testing are built into upstream and midstream steps, with safety and durability standards for domestic tables (for example, DIN EN 12521 and its 2026 update) shaping design tolerances, jointing systems, and validation cycles. These requirements are increasingly tied to wood legality and traceability documentation as large buyers tighten supplier onboarding and audit readiness.
On the downstream side, brands distribute through specialty furniture stores, home centers, and fast-growing online channels supported by 3D/AR visualization. Fulfillment depends on container shipping, regional distribution centers, and last-mile delivery with reverse-logistics capabilities for large parcels. Scale players such as IKEA rely on supplier networks and high-volume procurement to manage input volatility, and 2026 reporting around IKEA adjusting ordering levels from external suppliers highlights how demand planning and supplier allocation can shift across the chain. Operational restructuring also changes supply footprints, as Dorel Industries announced in June 2025 that it would downsize its Home segment and close domestic manufacturing in Cornwall, Ontario, altering the manufacturer-to-distribution balance for affected categories.
Competitive Landscape
The dining table market is moderately fragmented. IKEA leads through vertically integrated scale and omnichannel reach, opening new stores even amid macro headwinds while rolling out circular-economy initiatives that elevate brand equity. Ashley Furniture anchors North American share via breadth and hybrid retail models, whereas Poliform and Ligne Roset dominate the premium end through Italian and French design heritage.
Customization, sustainability, and digital engagement now eclipse pure price competition. Castlery, a direct-to-consumer entrant, gained global visibility in 2025 for extendable tables that solve urban space constraints and meet mid-premium styling preferences. Technology is becoming a frontline differentiator: 3D and AR tools are migrating from novelty to necessity, forcing laggards to invest or cede share.
White-space opportunities emerge in eco-certified mid-price offerings, smart-furniture integration for connected homes, and region-specific designs. Scale leaders exploit supply-chain leverage to counter raw-material volatility, while niche artisans command premiums through craftsmanship narratives. Competitive dynamics will keep evolving as consumer priorities tilt toward personalization, ethical sourcing, and multipurpose functionality.
Dining Tables Industry Leaders
IKEA
Ashley Furniture Industries, Inc.
Yihua Lifestyle Technology Co. Ltd.
Dorel Industries Inc. (Dorel Home)
Sauder Woodworking Co.
- *Disclaimer: Major Players sorted in no particular order
Dining Tables Market Companies Covered in this Report
- IKEA
- Ashley Furniture Industries, Inc.
- Dorel Industries Inc.
- Ethan Allen Global, Inc.
- La-Z-Boy Incorporated
- Poliform S.p.A.
- Ligne Roset
- Calligaris S.p.A.
- Blu Dot
- Sunpan Trading & Importing, Inc.
- Sauder Woodworking Co.
- Stickley Furniture Inc.
- Hooker Furniture Corp.
- Lane Home Furnishings
- Stanley Furniture Co.
- Baker Furniture
- Bassett Furniture Industries, Inc.
- Flat Rock Furniture
- Yihua Lifestyle Technology Co. Ltd.
- Foshan Shunde Furniture Group
- BK Ciandre
- Godrej Interio
- Wooden Street
- Hatil Furniture
- Durian Industries Ltd.

Market Opportunities and Future Outlook
Sustainability compliance is creating whitespace beyond traditional material claims, particularly around documentation, labeling, and test-proven emissions performance. The EU tightening formaldehyde limits for wood-based articles to 0.062 mg/m3 from August 6, 2026 raises the bar for panel selection, adhesives, and finishing systems, which expands opportunities for suppliers of low-emitting boards, waterborne finishes, and in-factory testing and quality assurance programs that reduce rework and returns. At the same time, the Ecodesign for Sustainable Products Regulation (ESPR) is advancing toward Digital Product Passports for categories that include furniture, with delegated acts discussed for 2026-2028, supporting traceability data capture, supplier documentation workflows, and consumer-facing transparency at the SKU level.
Specification-driven differentiation is also widening, particularly where safety, durability, and smart-home-adjacent expectations overlap. China formalized technical requirements for dining tables and chairs through GB/T 24821-2024, which includes performance and material-related provisions that can push manufacturers toward more standardized validation, better hardware, and more consistent finishing. Alongside ongoing adoption of 3D configurators and AR shopping tools by major retailers, these shifts support configurable, compliance-ready product platforms that can be adapted by material, finish, and size without multiplying inventory risk.
Recent Industry Developments in Dining Tables Market
- July 2026: The global launch of KOMPISH?NG expands affordable, portable dining related furniture offerings and increases category penetration in urban living spaces. The initiative strengthens IKEA’s reach in space constrained markets and boosts omnichannel strength for low-to-mid priced segments.
- April 2026: Ashley Luxe, a new furniture collection with five sub-lines, elevates dining assortments in the mid-to-premium segment. The expansion signals brand tiering toward elevated aesthetics at attainable price points, and may influence share in mid-range dining and living room purchases.
- January 2026: Ashley store opening in St. Augustine expands retail footprint with dine and living room exposure. The new 21,000 sq ft location strengthens distribution and local market momentum for Ashley’s dining and multifunction offerings.


Dining Tables Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the dining tables market is defined as revenue earned from the sale of dining tables used in residential and commercial settings, across offline and online channels, measured at the point of sale in each covered geography.
Scope exclusions: This market excludes dining chairs, benches, full dining sets priced as bundles, and non-dining tables such as coffee, side, or outdoor patio tables.
Segments Covered in This Report
- By Material Type
- Wood Dining Tables
- Metal Dining Tables
- Plastic Dining Tables
- Others (Stone,Glass, Plastic & Composite, etc.)
- By Shape
- Rectangular
- Round
- Square
- Oval
- Others (Extendable, Freeform)
- By Price Range
- Economy
- Mid-range
- Premium
- By Distribution Channel
- Home Centers
- Specialty Furniture Stores
- Online
- Other Distribution Channels
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East And Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts with mapping the category and its demand signals, then narrowing it down to dining tables only. We use public information such as UN Comtrade trade statistics, US Census Bureau and Eurostat retail and household indicators, and national statistics offices for housing completions and household formation as context on replacement demand and new-home demand.
To keep the model grounded in product and supply constraints, we review sources such as Forest Stewardship Council (FSC) updates on certified wood, peer-reviewed forestry and materials journals for supply-side constraints, and customs or port releases where shipment congestion affects bulky furniture delivery times. These inputs are complemented with company filings, investor presentations, and retailer disclosures to understand pricing actions, product mix changes, and channel shares, and selected paid subscriptions are used for company financials, patent checks, and import-export shipment level reads where available. This list is illustrative only, and many additional public and proprietary sources were consulted for data collection, cross-checks, and clarification.
Primary Interviews and Surveys
Fieldwork is used to confirm what desk research cannot fully show, especially how unit demand and pricing behave by region and channel. We speak with manufacturers, distributors, large-format retailers, online sellers, and material suppliers, then re-check assumptions with interior fit-out professionals and category managers so adoption drivers and price bands match how purchases typically occur.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 19% | APAC: 42% |
| Mid tier: 48% | Functional/Unit leaders: 35% | EMEA: 33% |
| Smaller Players: 22% | Managers: 46% | Americas: 25% |
Market-Sizing & Forecasting
Sizing begins with a top-down build where household formation, housing completions, and replacement cycles are used to reconstruct the addressable demand pool for dining tables, which is then converted into value using observed price bands. To avoid drift in totals, we corroborate the output with selective bottom-up checks such as sampled ASP times estimated unit volumes from channel checks, plus sanity checks against a roll-up of visible supplier and retailer revenue exposure.
A few inputs that most often move the model are online share of bulky furniture sales, average table price by material mix, apartment size and urbanization signals that shift demand toward compact or extendable designs, and freight plus wood and panel pricing that influences retail pricing. Where a clean supplier roll-up is not possible, gaps are handled through region-level penetration assumptions and distributor margin ranges, then adjusted after interviews. Forecasting is done using scenario analysis supported by simple multivariate regression where variables like housing activity, consumer spending on furnishings, and input cost inflation help explain the direction and speed of change, and then the output is reviewed with primary experts for realism.
Data Validation & Update Cycle
Checks are run at multiple steps so the final number is not driven by a single assumption. Outputs are compared against independent signals such as furniture retail sales trends, import intensity for major consuming regions, and price movement patterns by material type, and then variances are investigated before sign-off.
If an outlier appears, we reopen the driver assumptions, re-check key inputs, and, when needed, go back to respondents to validate the specific point that caused the swing. Reports are refreshed annually, and interim updates are made when material events occur such as major demand shocks, tariff changes, or sustained pricing shifts. Before delivery, a final analyst pass is completed so clients receive the most current view available at the time.
黑料不打烊's Dining Tables Market Size Compared Against Other Published Estimates
Market values for dining tables can look far apart across publications because the boundaries are not always aligned, and the math used to convert demand into dollars can be handled differently. The biggest differences usually come from what is counted as a dining table sale, how bundles are treated, whether residential and contract demand are mixed together, and how quickly the pricing base is refreshed.
By tracking channel-level pricing bands and refreshing currency timing assumptions, 黑料不打烊 keeps the dining tables total limited to table-only revenues rather than broad dining room bundles, which is a common cause of inflation in this category.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 9.23 B (2026) | |
| Trade Journal A | USD 15.00 B (2025) | Uses a wider dining room scope that likely bundles tables with chairs and storage pieces, and it also appears to mix complete dining set revenues into the same total. |
| Research Firm B | USD 7.58 B (2024) | Back-solves dining tables from high level furniture ratios and may omit parts of the contract and hospitality channel, which can understate value in regions with strong out-of-home demand. |
The spread in the table is mainly explained by scope choices and pricing treatment, not by a single growth assumption. When table-only revenues are separated cleanly and the conversion from units to value is tied to observable price bands, the final market size becomes easier to trace and repeat across regions and years.


Key Questions Answered in the Report
What is the current size of the dining table market?
The dining table market size is USD 9.23 billion in 2026.
How fast is the dining table market expected to grow?
The market is forecast to expand at a 6.29% CAGR, reaching USD 12.52 billion by 2031.
Which region leads the dining table market?
Asia-Pacific holds 42.60% of global revenue and is projected to grow the fastest at 6.86% CAGR.
Which material segment is growing quickest?
Metal dining tables are set to post a 6.44% CAGR from 2026 to 2031 due to durability and modern aesthetics.
How is online retail influencing dining table sales?
E-commerce channels are increasing at a 7.38% CAGR, aided by 3D visualization and AR tools that lower return rates.
Why are extendable dining tables gaining popularity?
Shrinking urban living spaces make multifunctional, space-efficient designs appealing, propelling extendable tables to a 6.05% CAGR through 2031.
Page last updated on:



