
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.62 Billion |
| Market Size (2026) | USD 2.80 Billion |
| Market Size (2031) | USD 3.87 Billion |
| Growth Rate (2026 - 2031) | 6.69 % |
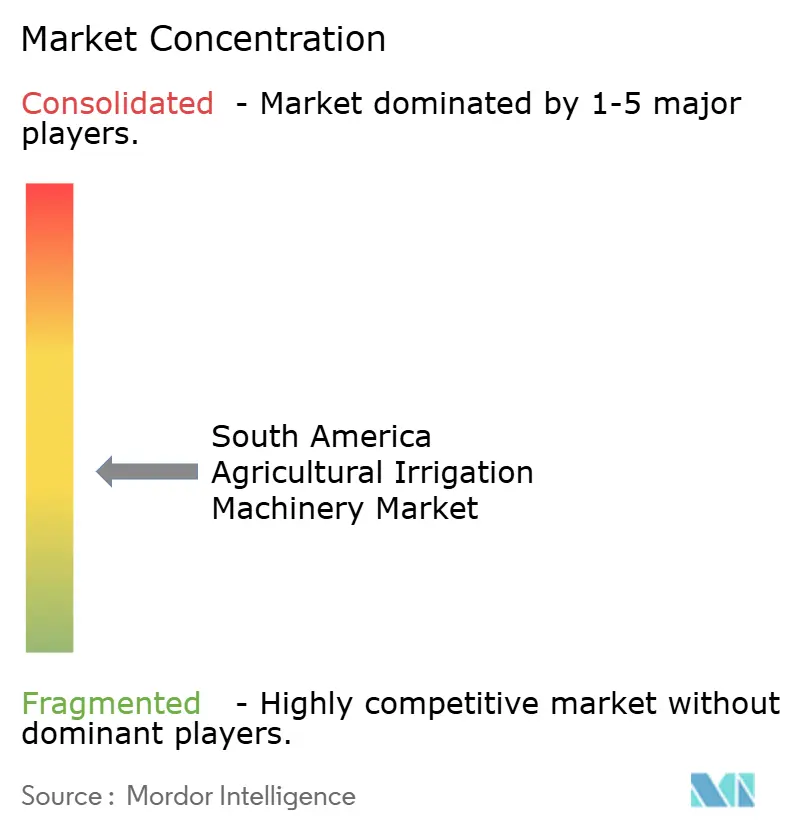
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
South America Agricultural Irrigation Machinery Market Analysis by 黑料不打烊
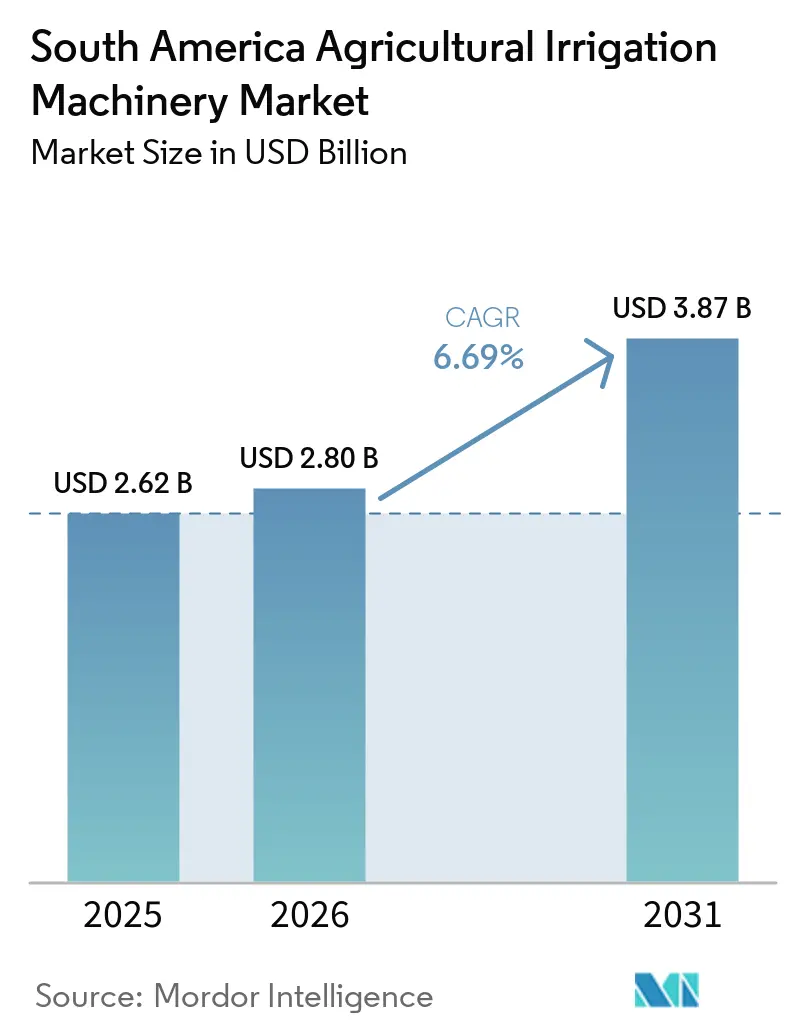
The South America agricultural irrigation machinery market was valued at USD 2.62 billion in 2025 and is forecasted to reach USD 2.80 billion in 2026 and USD 3.87 billion by 2031, registering a CAGR of 6.69% during the forecast period 2026–2031. The market is supported by farms transitioning from rainfall-dependent production to pressurized and monitored irrigation equipment. Brazil’s National Supply Company (CONAB) anticipates a 2.4% increase in grain production for the 2025/26 crop, reinforcing the importance of reliable water management across the country’s large crop areas[1]. Irrigation is increasingly treated as an operating input that supports production consistency, rather than solely as a response to seasonal yield risk. Public programs, export-oriented agriculture, and rising demand for efficient pumping systems are expanding the equipment opportunity. Energy costs, exchange-rate exposure, and uneven access to farm finance continue to shape purchase decisions across the market.
Key Report Takeaways
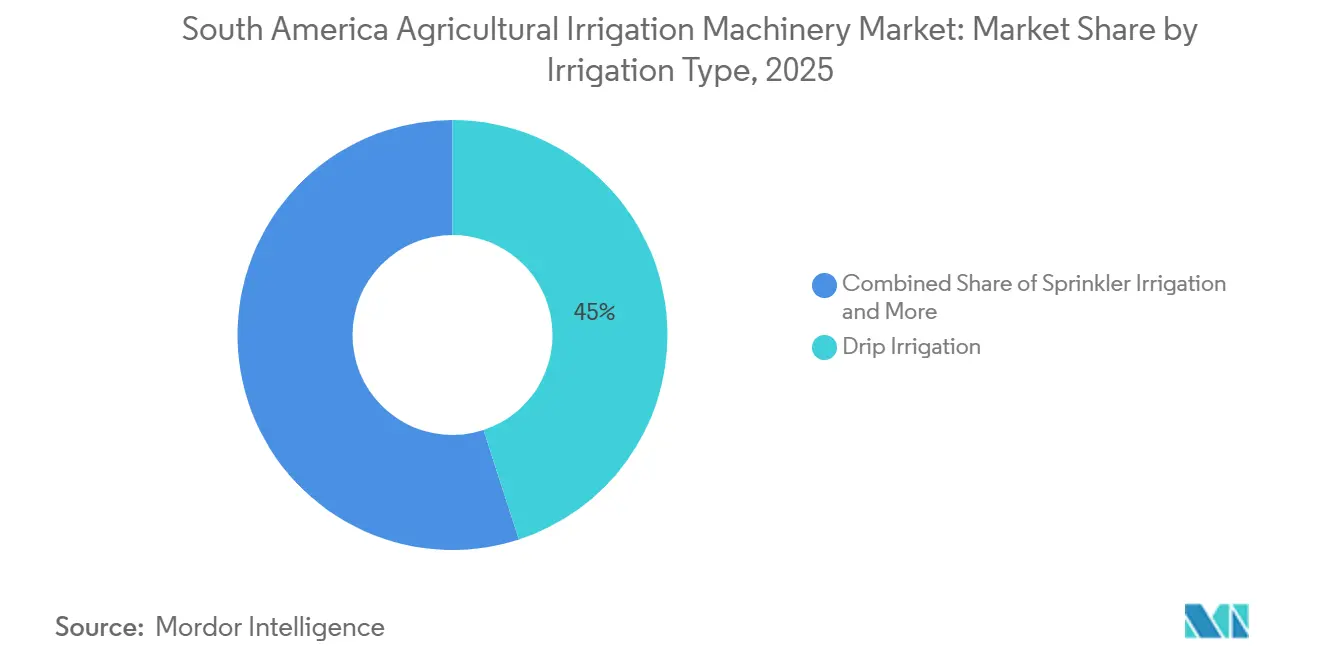
- By irrigation type, drip irrigation was the largest segment, and accounted for 45.0% of the South America agricultural irrigation machinery market share in 2025, while sprinkler irrigation is the fastest-growing segment, forecast to expand at an 8.1% CAGR between 2026 and 2031.
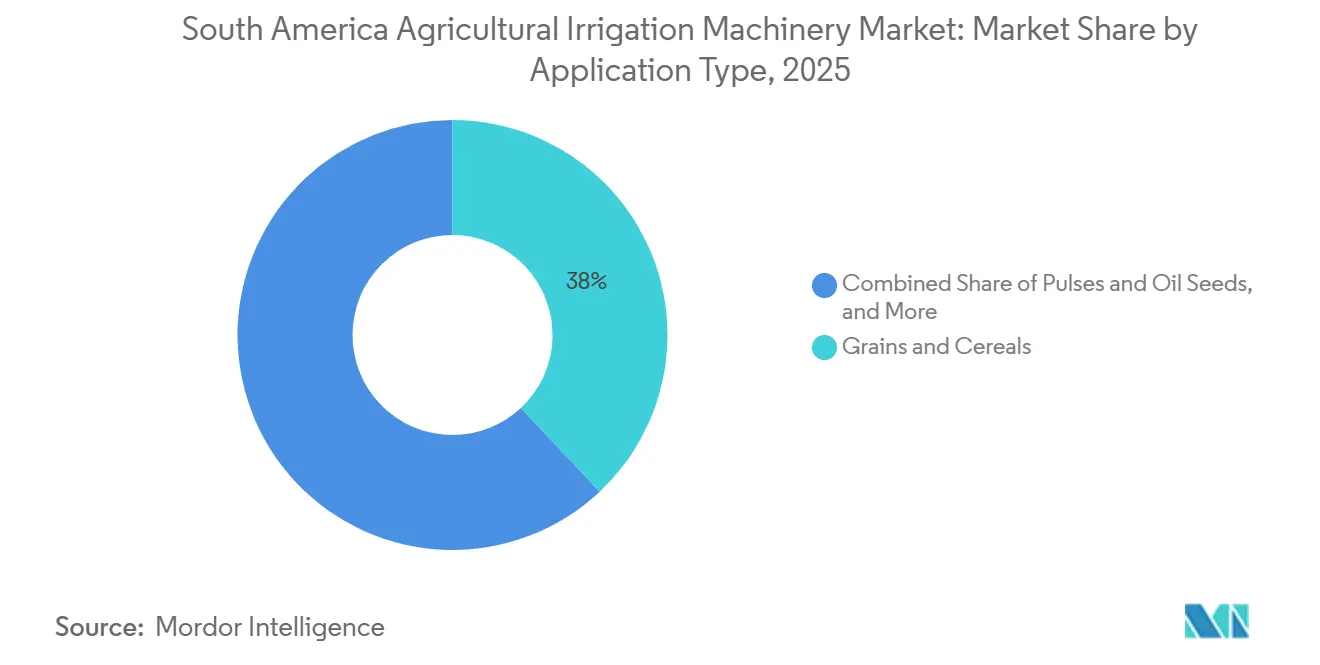
- By application type, grains and cereals were the largest segment, and accounted for 38.0% of the South America agricultural irrigation machinery market size in 2025, while fruits and vegetables are forecast to grow at a CAGR of 9.5% between 2026 and 2031.
- By geography, Brazil was the largest country, and held 46.0% of the market share in 2025, while Peru is the fastest-growing country, forecast to expand at an 8.2% CAGR between 2026 and 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
South America Agricultural Irrigation Machinery Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Irrigated High-Value Crops | +1.4% | Brazil, Peru, and Chile | Medium term (2-4 years) |
| Government and Development-Finance Support for Water-Efficient Irrigation | +1.3% | Brazil, Peru, and Argentina | Short term (≤ 2 years) |
| Climate-Driven Yield Stabilization in Rainfall-Variable Cropping Regions | +1.1% | Brazil, Argentina, and Peru | Long term (≥ 4 years) |
| Expansion of Mechanized Irrigation in Large-Scale Soybean, Corn, Sugarcane, and Fruit Operations | +1% | Brazil, Argentina, and Paraguay | Medium term (2-4 years) |
| Irrigation Retrofit Demand from Electricity and Pumping-Cost Optimization | +0.9% | Brazil, Argentina, Colombia, and Bolivia | Medium term (2-4 years) |
| Export-Oriented Farms Adopting Traceable Water-Use Controls | +0.8% | Argentina, Brazil, Chile, Peru, and Uruguay | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Expansion of Irrigated High-Value Crops
Perennial and export-oriented crops can support sustained demand for irrigation because production reliability is closely linked to farm revenue and investment capacity. In Brazil, Netafim Ltd. reported 20% growth in 2025 compared with 2024, with strong performance in citrus, coffee, and horticulture, and announced an investment of approximately BRL 100 million (USD 17.5 million) to expand its Ribeir?o Preto facility while targeting 12%–15% growth in 2026. In Peru, the Ministry of Agrarian Development and Irrigation (MIDAGRI) reported record agricultural exports of USD 12.7 billion in 2024, including USD 2.27 billion from blueberries, USD 1.71 billion from grapes, and USD 1.25 billion from avocados[2]. The continued expansion of these high-value, export-oriented crops creates a favorable demand base for precision irrigation technologies that provide reliable water delivery and help maintain consistent crop quality.
Government and Development-Finance Support for Water-Efficient Irrigation
Government-backed infrastructure programs are creating a pipeline of irrigation investment across South America. In Peru, the government announced 22 irrigation projects requiring USD 24.1 billion, targeting an additional 1 million hectares of agricultural land, with 85% of investment promotion structured through public-private partnerships (PPPs). Brazil is also expanding irrigation infrastructure through government-supported Irrigated Agriculture Hubs and programs promoting more efficient irrigation technologies. These initiatives are strengthening the project pipeline for irrigation equipment and improving opportunities for suppliers of water-efficient systems across commercial agriculture and family farming, supporting growth in the South America agricultural irrigation machinery market.
Climate-Driven Yield Stabilization in Rainfall-Variable Cropping Regions
Increasing rainfall variability and recurring drought conditions are driving demand for irrigation systems that help stabilize crop production across variable seasons. In Brazil, drought monitoring by the National Center for Monitoring and Early Warning of Natural Disasters (CEMADEN) found that 963 municipalities had at least 80% of their agroproductive areas potentially affected by drought in August 2024, demonstrating the scale of water stress across agricultural regions[3]. These conditions support demand for supplemental irrigation where water availability and pumping infrastructure permit, as producers seek to reduce the operational impact of rainfall gaps and protect crop yields. This represents a structural demand driver for agricultural irrigation machinery across South American regions exposed to variable precipitation and drought risk.
Irrigation Retrofit Demand from Electricity and Pumping-Cost Optimization
Rising electricity and diesel costs are prompting farms that use pressurized irrigation systems to consider more energy-efficient pumping and control technologies. The International Renewable Energy Agency (IRENA) has highlighted the potential of renewable-powered irrigation to reduce reliance on conventional fuels and improve energy-cost resilience, particularly in areas with high diesel or electricity costs. Brazil’s National Council for Fiscal Policy (CONFAZ) coordinates state and Federal District tax arrangements, including agreements governing the Tax on Circulation of Goods and Provision of Interstate and Intermunicipal Transport and Communication Services (ICMS). Convênio ICMS 16/2015 authorizes participating states and the Federal District to grant ICMS exemptions for electricity transactions under the distributed-generation compensation system, supporting the economics of distributed solar generation. These conditions support demand for irrigation retrofits that incorporate energy-efficient pumps, solar power, automation, and digital controls, particularly where lower operating costs can justify the upfront investment in equipment.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Cost and Limited Farm-Finance Access | -0.8% | Brazil, Argentina, and Peru | Medium term (2-4 years) |
| Uneven Grid Reliability and High Energy Cost for Pressurized Systems | -0.6% | Brazil, Argentina, Bolivia, and Paraguay | Long term (≥ 4 years) |
| Fragmented Smallholder Plots and Weak Local Service Coverage | -0.5% | Peru, Bolivia, Ecuador, Colombia, and Brazil | Long term (≥ 4 years) |
| Import-Currency Exposure and Replacement-Part Lead Times | -0.4% | Argentina, Brazil, Chile, and Peru | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
High Upfront Cost and Limited Farm-Finance Access
High upfront capital requirements and limited access to suitable agricultural finance can constrain irrigation adoption, particularly among small and mid-sized farms. Modern irrigation systems often require significant investment in pumps, distribution infrastructure, controls, and installation, creating a higher entry barrier than conventional rainfed production. The Food and Agriculture Organization (FAO) highlighted in 2024 that access to finance is an important determinant of farmers’ ability to invest in productive assets and that financing constraints can limit agricultural investment, particularly for farmers and small and medium-sized agribusinesses. These financing constraints can extend investment payback periods and make sophisticated irrigation technologies less accessible to smaller producers. As a result, the market may face slower adoption among farms that lack collateral, adequate credit history, or financing products suited to agricultural cash flows, making accessible agricultural credit and public financing mechanisms important for broader irrigation-equipment adoption.
Fragmented Smallholder Plots and Weak Local Service Coverage
Fragmented agricultural holdings and challenging terrain can limit the suitability of large mechanized irrigation systems, particularly in Andean farming regions where smallholder production remains important. Peru's irrigation modernization programs illustrate this market structure. The National Program for Technified Irrigation for Climate-Resilient Agriculture (PNRT) specifically targets small farmers and includes parcel-level systems such as valves, laterals, sprinklers, micro-sprinklers, and drip emitters rather than relying solely on large-scale irrigation equipment. In 2025, Peru reported that 24 PNRT projects were being implemented in highland areas, covering crops including potatoes, quinoa, maize, forage crops, and avocado. This structure creates a fragmented equipment opportunity in which demand is distributed across smaller farm-level systems, increasing the importance of local installation, technical assistance, maintenance, and replacement-part availability. Where dealer and service networks are limited, longer response times and higher maintenance costs can further discourage investment in sophisticated irrigation equipment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Irrigation Type: Drip Leads Export-Crop Demand and Sprinkler Gains Large-Field Adoption
Drip irrigation held 45.0% of the South America agricultural irrigation machinery market size in 2025. It is widely used in coffee, citrus, sugarcane, blueberries, and avocados, where controlled water delivery supports high-value crop production. Demand for drip irrigation equipment is supported by the expansion of export-oriented crop cultivation in Brazil and Peru, particularly for high-value crops that benefit from precise water application. Large soybean and corn operations use pivots and reels because these systems can cover broad field areas. Irrigabras Irriga??o do Brasil Ltda. launched Irrigabras Conecta in March 2026, a digital platform that allows field users to access equipment documentation through QR codes. The launch indicates that Brazilian pivot suppliers are extending their offering beyond mechanical equipment.
Sprinkler irrigation is forecast to expand at an 8.1% CAGR between 2026 and 2031. Pivot irrigation remains important in Mato Grosso and Goiás, where grain farms operate across large areas. Flood and furrow irrigation continue to serve farms where investment capacity remains more limited. The Brazilian Agricultural Research Corporation (Embrapa) Low-Carbon Soybean (SBC) Program provides guidance on documenting water use and irrigation practices for participating farms. As a result, metering and water-management controls can influence equipment selection among farms supplying certified export chains. Overall, the South America agricultural irrigation machinery market is shaped by the differing economic and agronomic requirements of localized and mechanized irrigation systems.

By Application Type: Grains and Cereals Provide Volume While Fruits and Vegetables Support Faster Growth
Grains and cereals held 38.0% of the South America agricultural irrigation machinery market share in 2025. Brazil, Argentina, and Paraguay provide a broad base for irrigation used in row crops. The extensive cultivation of soybeans and corn in Brazil supports demand for pivots and reels capable of operating across large planted areas. Pulses and oilseeds are also gaining irrigation coverage as soybean rotations expand. Farms can use installed pivot systems over multiple crop cycles, which increases the utilization value of irrigation assets in large grain operations.
Fruits and vegetables are forecast to expand at a 9.5% CAGR between 2026 and 2031. Peru's export horticulture and Brazil's production belts in Minas Gerais, Bahia, and the S?o Francisco Valley support demand for precise water delivery. Peru’s National Program for Technified Irrigation for Climate-Resilient Agriculture (PNRT) is advancing multiple irrigation projects incorporating drip, sprinkler, and other parcel-level systems, supporting continued demand for modern irrigation equipment. Between 2025 and mid-2026, PNRT launched 19 investment projects totaling approximately PEN 77.6 million (USD 20.7 million), covering more than 1,212 hectares through drip, sprinkler, and multigate irrigation systems. Water documentation requirements in European Union supply chains also support the use of metered equipment on export-oriented horticultural farms, benefiting the South America agricultural irrigation machinery market where premium crops require consistent quality and auditable farm operations.
Geography Analysis
Brazil held 46.0% of the South America agricultural irrigation machinery market share in 2025. Its domestic manufacturing base, large irrigated cropping area, and public financing structure support equipment demand. The 18 Irrigated Agriculture Hubs cover 1.5 million hectares and have potential to expand to 8.6 million hectares. National Irrigation and Agricultural Infrastructure Program (PRONISAF) has supported the inclusion of solar-powered irrigation in family farming programs since November 2025. Brazil's record grain harvest in 2025 also confirmed the scale of its agricultural production base.
Peru is forecasted to expand at a 8.2% CAGR between 2026 and 2031. Its USD 24 billion irrigation program is focused on major projects across the coast, highlands, and Amazon regions. Peru's agricultural exports exceeded USD 12.8 billion in 2024, supporting investment in horticultural production. The 2026 Private Investment Promotion Agency (ProInversión) portfolio includes Chavimochic III, Olmos, and Majes Siguas II. These projects are intended to expand agricultural land and support agro-industrial exports. The country's dry coastal production areas favor drip, sprinkler, and automated systems that use available water efficiently.
According to the Argentina Ministry of Economy, Argentina added 63,400 hectares of irrigated area between 2023 and 2025, with an investment of USD 185 million. The World Bank reported irrigation modernization in the Río Negro Valley in April 2026, covering 4,000 hectares in an apple, pear, and hazelnut production area. Chile has an established base for agricultural digital tools, while Bolivia, Colombia, Ecuador, and Paraguay have lower irrigation penetration. These countries may support demand for lower-cost drip systems as export horticulture develops. Geographic differences in farm scale, energy access, water availability, and service coverage will continue to influence equipment selection. The South America agricultural irrigation machinery market includes both mature commercial operations and earlier-stage farm modernization opportunities.
Competitive Landscape
The South America agricultural irrigation machinery market is moderately fragmented, with the top five players holding a small combined share in 2025. Fockink Indústrias Elétricas Ltda., Irrigabras Irriga??o do Brasil Ltda., Irrigat Agrícola Ltda., Pampa Riego S.A., and Netafim Ltd. compete across different irrigation equipment and technology segments, including center pivots, irrigation reels, pumping and piping equipment, automation, and drip-irrigation systems. The Brazilian manufacturers benefit from proximity to major agricultural regions, local manufacturing capabilities, and equipment support, while Pampa Riego S.A. provides locally manufactured center-pivot systems for the Argentine agricultural market. Irrigabras Irriga??o do Brasil Ltda. offers its Nimbus SAT automation system, which enables remote control of center-pivots via satellite communication across Brazil. These developments indicate that connectivity, automation, and remote operation are becoming increasingly important factors in the competition for irrigation equipment.
Netafim Ltd. (Orbia Advance Corporation, S.A.B. de C.V.) maintains a strong competitive position in the precision-irrigation segment. Netafim's Brazilian operation announced a BRL 100 million (USD 17.5 million) investment in the expansion of its Ribeir?o Preto manufacturing facility in 2026, supporting additional production capacity for the Brazilian market. In June 2026, Orbia Netafim also opened a 30,000-square-meter manufacturing plant in Hermosillo, Mexico. The facility primarily produces thin-wall drip-irrigation solutions, with future heavy-wall dripline production planned, and represents Orbia Netafim's 21st plant worldwide. The expansion strengthens the company's regional manufacturing footprint and is intended to improve supply responsiveness for precision-irrigation products across the Americas. This broader manufacturing platform increases competitive pressure on local suppliers in applications requiring precise water distribution.
Turbom Argentina Industrial y Comercial S.A., Torvil Riegos S.A., Irrigat Agrícola Ltda., Evandro de Castro Silva Fundi??o e Solu??es para Irriga??o Ltda., Hidro Solo Indústria e Comércio Ltda., and Quiver Plast E.I.R.L. add further local manufacturing capabilities across pumps, irrigation equipment, piping, filtration, and irrigation components. Competitive positioning varies by irrigation technology, farm scale, and regional agricultural requirements. Automation, remote monitoring, and precision water-management technologies remain important areas of product development as producers seek greater control over irrigation operations, water use, and equipment performance. The South America agricultural irrigation machinery market therefore remains competitive across locally manufactured equipment and international precision-irrigation technologies.
South America Agricultural Irrigation Machinery Industry Leaders
-
Fockink Indústrias Elétricas Ltda.
-
Irrigabras Irriga??o do Brasil Ltda.
-
Irrigat Agrícola Ltda.
-
Pampa Riego S.A.
-
Netafim Ltd. (Orbia Advance Corporation, S.A.B. de C.V.)
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: Private Investment Promotion Agency (ProInversión) presented a portfolio of 14 irrigation projects requiring approximately USD 20.5 billion, covering about 1.3 million hectares across 11 departments. The portfolio includes major projects such as Chavimochic III, Olmos, and Majes Siguas II and is intended to expand agricultural production and strengthen agro-export capacity.
- June 2026: Netafim Ltd. reported investments of approximately BRL 100–110 million (USD 19.4–21.4 million) in its Brazilian operations, with most of the investment directed toward expanding its Ribeir?o Preto manufacturing facility, along with distribution, logistics, and administrative infrastructure.
- April 2026: World Bank-supported irrigation modernization in the Río Negro Valley enabled agricultural production to expand across approximately 4,000 hectares. The modernization included canal lining, mechanized gates and water-flow sensors serving approximately 500 farms.
South America Agricultural Irrigation Machinery Market Report Scope
Irrigation Machinery is the machinery or equipment that supplies water to agricultural land and crops to promote hydration and growth. The South America Agricultural Irrigation Machinery Market Report is Segmented by Irrigation Type (Sprinkler Irrigation, Drip Irrigation, Pivot Irrigation, and Other Irrigation Types), by Application Type (Grains and Cereals, Pulses and Oilseeds, Fruits and Vegetables, and More), and by Geography (Brazil, Peru, and More). The Market Forecasts are Provided in Terms of Value (USD).
By Irrigation Type
| Sprinkler Irrigation |
| Drip Irrigation |
| Pivot Irrigation |
| Other Irrigation Types |
By Application Type
| Grains and Cereals |
| Pulses and Oilseeds |
| Fruits and Vegetables |
| Other Applications |
By Geography
| Brazil |
| Argentina |
| Peru |
| Rest of South America |
| By Irrigation Type | Sprinkler Irrigation |
| Drip Irrigation | |
| Pivot Irrigation | |
| Other Irrigation Types | |
| By Application Type | Grains and Cereals |
| Pulses and Oilseeds | |
| Fruits and Vegetables | |
| Other Applications | |
| By Geography | Brazil |
| Argentina | |
| Peru | |
| Rest of South America |
Key Questions Answered in the Report
What is the forecasted size of the South America agricultural irrigation machinery market?
The South America agricultural irrigation machinery market size is USD 2.80 billion in 2026 and is forecasted to reach USD 3.87 billion by 2031, at a 6.69% CAGR.
Which irrigation type held the largest share in South America in 2025?
Drip irrigation held the largest share at 45.0% in 2025, supported by perennial export crops including coffee, citrus, blueberries, and avocados.
What is the fastest-growing application for agricultural irrigation machinery in South America?
Fruits and vegetables is anticipated to expand at a 9.5% CAGR between 2026 and 2031, supported by export horticulture in Peru and Brazil.
What factors are driving demand for irrigation equipment across South America?
Export crops, public irrigation programs, variable rainfall, mechanized row-crop production, and demand for energy-efficient pumping systems support equipment demand.