
Nigeria Location-based Services Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
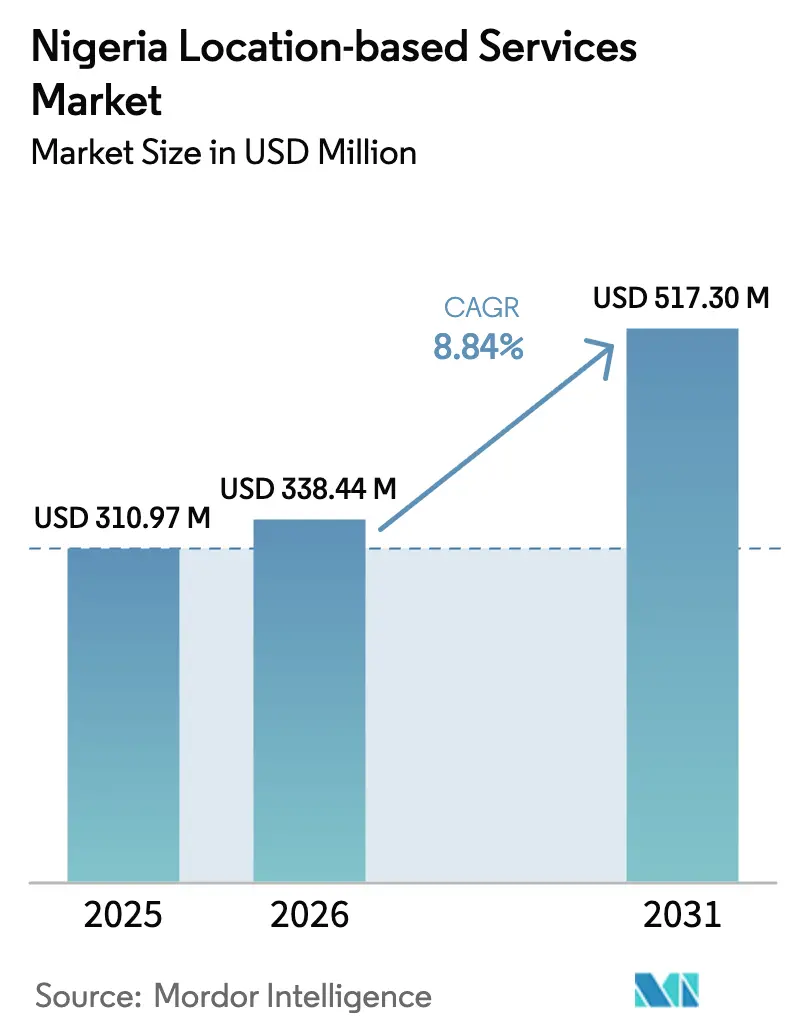
| Base Year Market Size (2025) | USD 310.97 Million |
| Market Size (2026) | USD 338.44 Million |
| Market Size (2031) | USD 517.3 Million |
| Growth Rate (2026 - 2031) | 8.84 % |
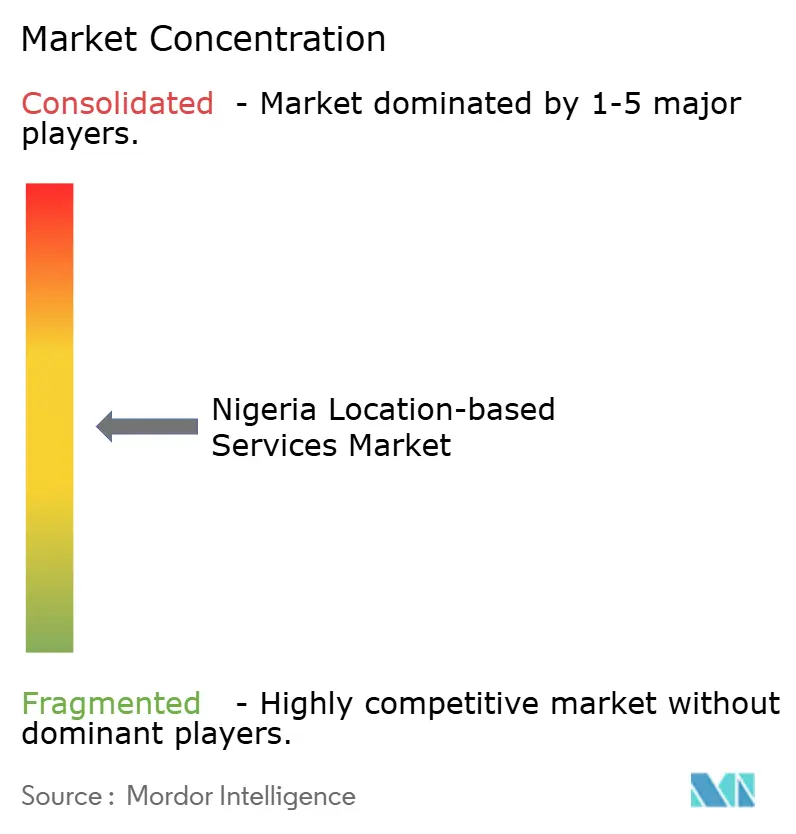
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Nigeria Location-based Services Market Analysis by 黑料不打烊
Nigeria location-based services market size in 2026 is estimated at USD 338.44 million, growing from 2025 value of USD 310.97 million with 2031 projections showing USD 517.3 million, growing at 8.84% CAGR over 2026-2031. Uptake accelerates because mobile data already contributes 13.5% of GDP and policy reforms now require real-time geographic verification for many digital transactions. Fast 5G take-up, satellite back-haul and falling data tariffs extend coverage beyond large cities, enabling platforms in logistics, fintech and healthcare to embed precise location intelligence. Services rather than hardware dominate spending, as enterprises prefer turnkey integration to navigate Nigeria’s complex addressing environment. At the same time, Indoor mapping gains momentum alongside new malls and mixed-use complexes in Lagos and Abuja, indicating a shift from pure outdoor navigation toward hybrid environments.
Key Report Takeaways
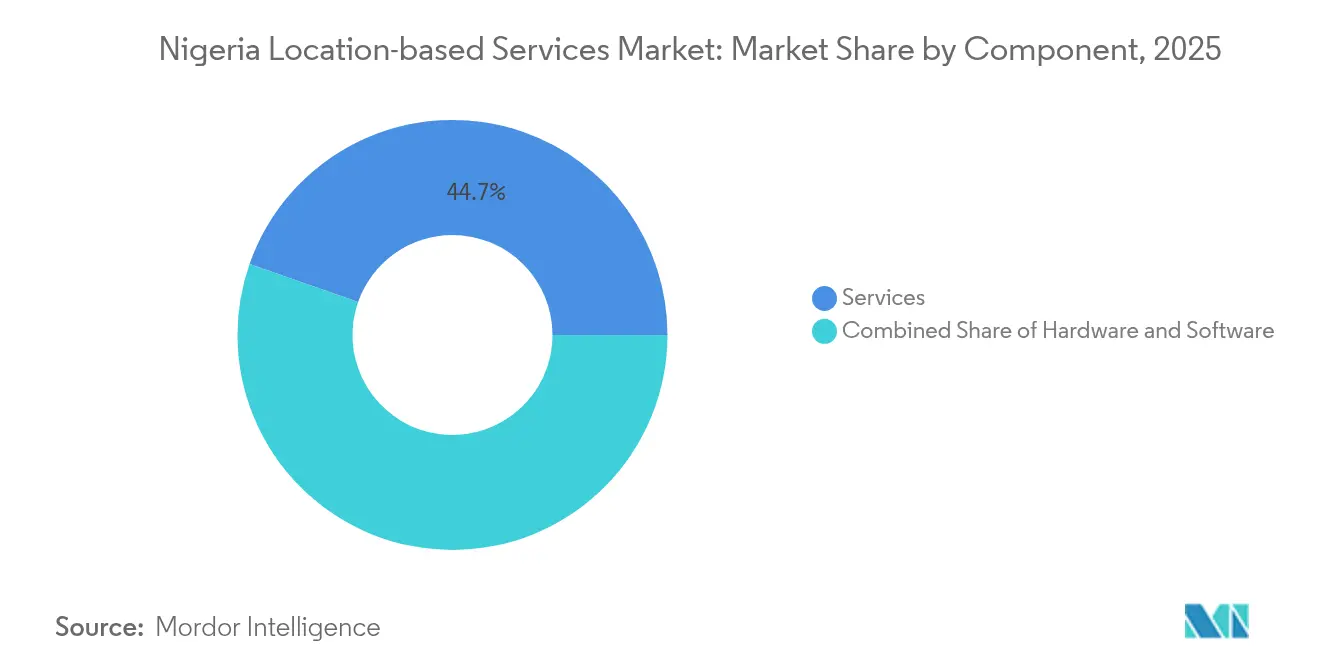
- By component, Services captured 44.65% of Nigeria location-based services market share in 2025 while advancing at a 15.03% CAGR to 2031.
- By location type, Outdoor applications commanded 51.70% share of the Nigeria location-based services market size in 2025, whereas Indoor solutions are expanding at 20.33% CAGR through 2031.
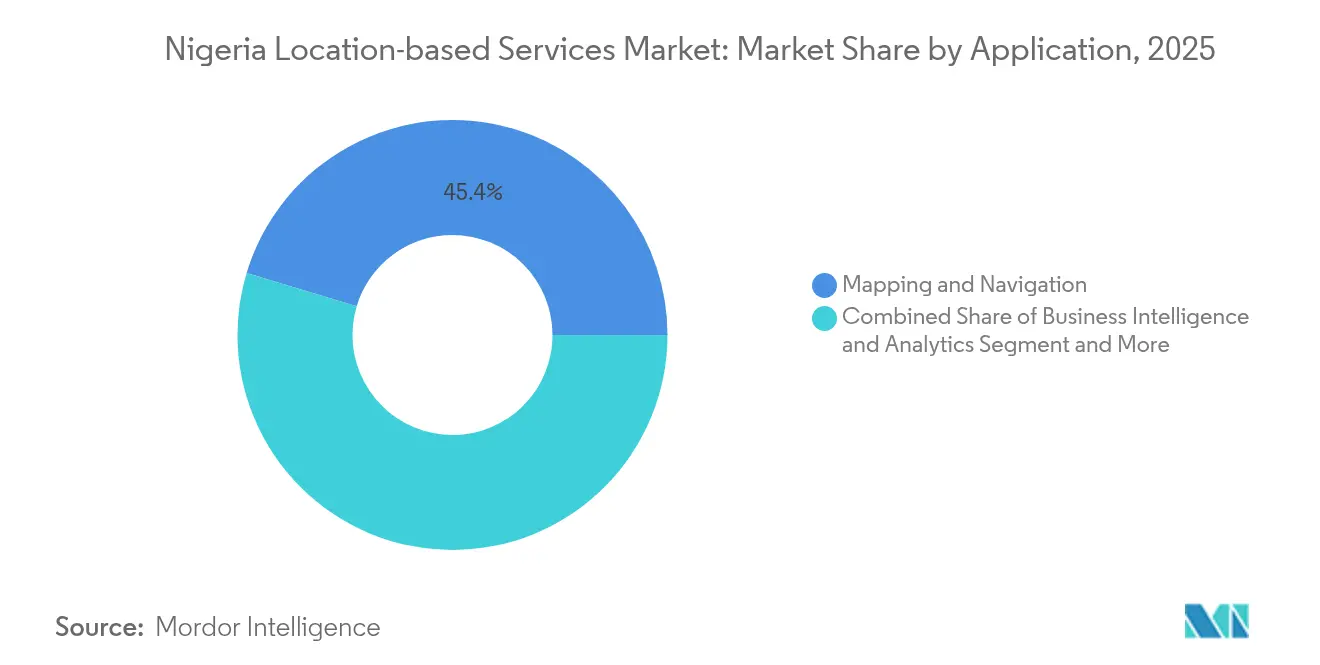
- By application, Mapping & Navigation held 45.35% share of the Nigeria location-based services market size in 2025, yet Social Networking & Entertainment is projected to grow at 25.32% CAGR between 2026-2031.
- By end-user, Transportation & Logistics led with 40.85% of Nigeria location-based services market share in 2025; Healthcare records the fastest forecast CAGR at 18.91% through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Figures recorded within Nigeria feed into a worldwide estimate while studying the global industry. 黑料不打烊's location based services market size captures this aggregation.
Nigeria Location-based Services Market Trends and Insights
Drivers Impact Analysis*
| Driver | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising e-commerce and on-demand delivery boom | +2.1% | Lagos, Abuja, Port Harcourt | Medium term (2-4 years) |
| Rapid smartphone adoption and falling data tariffs | +1.8% | Nationwide, rural catch-up | Short term (≤ 2 years) |
| State-supported digital economy and cash-lite push | +1.5% | National | Long term (≥ 4 years) |
| Telco mini-satellite projects improving coverage | +1.3% | Rural and underserved zones | Medium term (2-4 years) |
| Indoor mapping demand from new mega-malls | +0.9% | Lagos and Abuja retail hubs | Short term (≤ 2 years) |
| Government proof-of-address roll-out | +0.7% | 774 local government areas | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Rising e-commerce and on-demand delivery boom
Nigeria’s online retail revenues surge on platforms such as Jumia, whose national GMV share rose to 40.1% in 2023, making accurate geolocation essential for fraud screening and last-mile routing. Automated locker networks launched in 2024 depend on precise coordinates for parcel sorting. Digital freight start-ups like Kobo360 match cargo with drivers in real time, cutting empty-backhaul miles [1]BBC News, “How Cargo Delivery Is Going Digital in Nigeria,” bbc.com. Supermarket chains are opening fulfilment hubs that require indoor-to-outdoor navigation continuity, pushing demand for advanced mapping APIs. The postal authority’s partnership with What3words further institutionalizes granular addressing that underpins delivery efficiency.
Rapid smartphone adoption and falling data tariffs
Smartphone data usage almost doubled in 2025 as operators trimmed tariffs, even though handset shipments fell 7% amid currency pressure. Existing users therefore spend more time using location-enabled apps, lifting service revenues; MTN’s Q1 2025 data income jumped 51.5% to NGN 1 trillion. Low-latency 5G now covers 35.7% of connections, enabling immersive AR navigation on lower-spec devices. Continued affordability drives depend on easing inflation and local assembly incentives to arrest handset price spikes.
State-supported digital economy and cash-lite push
The National Digital Economy Policy clarifies that geospatial data is critical infrastructure, while the payments vision mandate’s location verification for high-value transfers. Federal upskilling schemes backed by Google.org produce developers able to build secure geolocation modules. The cash-lite mandate lifted proximity-based mobile transfer volumes on banking apps such as GTWorld, reinforcing everyday reliance on precise positioning. Implementation setbacks, like last year’s note redesign shortfall, demonstrate the need for coordinated infrastructure rollouts to sustain momentum.
Telco mini-satellite projects improving coverage
Satellite back-haul initiatives let operators fill rural gaps at lower capex than fibre; Intelsat’s CellBackhaul service and MTN’s Omnispace deal extend signal reach for IoT and navigation apps. AMN is running Starlink-powered base stations that offer consistent latency, a prerequisite for real-time asset tracking. Federal approval for four new surveillance satellites underscores long-term policy support for space-enabled location accuracy. Subscription fees remain high, so hybrid terrestrial-satellite models will dominate until unit costs fall.
Restraints Impact Analysis*
| Restraint | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Data-privacy legislation compliance costs | ?1.2% | Nationwide, multinationals affected | Short term (≤ 2 years) |
| Patchy 4G/5G coverage in hinterland | ?0.8% | Rural and remote districts | Medium term (2-4 years) |
| Fragmented addressing system outside cities | ?0.7% | Semi-urban and rural areas | Long term (≥ 4 years) |
| Low consumer trust in ride-hailing accuracy | ?0.5% | Major cities | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Data-privacy legislation compliance costs
The Nigeria Data Protection Act 2023 obliges major data controllers to register, appoint officers and localise processing, raising fixed costs for smaller geolocation start-ups. Breaches attract fines up to NGN 10 million or 2% of revenue, a risk highlighted by the Central Bank’s NGN 250 million penalty on a fintech in April 2025. Cross-border transfer restrictions force global providers to invest in Nigerian data centres, shifting capex toward compliance rather than product upgrades. Mandatory user consent adds friction, so ride-hailing firms face stricter controls over trip data sharing with regulators.
Patchy 4G/5G coverage in hinterland
Only MTN and Airtel deliver >70% 4G availability, while rural communities often rely on 2G, limiting uptake of latency-sensitive location apps. Operators estimate USD 3-8 billion is still needed for full 5G rollout, delaying nationwide parity. Roughly 40 million citizens remain uncovered, shrinking the immediate addressable base. Satellite alternatives help but remain expensive as Starlink raised tariffs in late 2024.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Services gain from integration complexity
Services hold 44.65% of Nigeria location-based services market share in 2025 because banks and retailers prefer turnkey geolocation suites that integrate compliance and mapping layers. Nigeria location-based services market size for Services is projected to expand at 15.03% CAGR through 2031 as providers like OkHi verify addresses for KYC in minutes. Hardware adoption lags as smartphone imports dip due to currency swings, yet local innovators showcase micro-tracking devices that could spur niche demand when prices stabilise. Software vendors embed modules in existing mobile apps, evident in Access Bank’s “access more” rollout featuring nearby payment prompts. Continuous evolution of the Nigeria Data Protection Act pushes corporates to outsource location compliance rather than build in-house stacks, reinforcing Service dominance.
Conversely, the Hardware slice faces price shocks from import duties and naira devaluation, constraining mass upgrades. Cloud-native Software benefits from low entry barriers, yet fragmentation drives buyers toward end-to-end subscription bundles. The resulting Services premium supports healthy margins and encourages international vendors to seek local partnerships that adapt mapping layers to Nigeria’s dynamic address code systems.


By Location Type: Indoor growth narrows outdoor lead
Outdoor use cases still account for 51.70% of Nigeria location-based services market share thanks to freight, ride-hailing and agriculture. Nigeria location-based services market size for Indoor applications, however, is on track to grow 20.33% CAGR as malls, hospitals and airports deploy Bluetooth beacons to guide visitors . Abuja and Lagos anchor several 20,000 m?-plus mixed-use centres where tenants demand floor-level analytics. Retailers integrate shelf-level heat maps with stock systems to curb lost sales, while hospitals map ward-to-pharmacy routes to cut turnaround time.
Indoor roll-outs face signal attenuation and need hybrid Wi-Fi, Bluetooth and magnetic tech. The arrival of local government proof-of-address databases will ease indoor-to-door delivery, spurring further investment. Outdoor services will keep leading in revenue thanks to road freight volumes, yet address standardization and construction of new malls suggest indoor usage will close the gap by decade-end.
By Application: Social entertainment disrupts navigation leadership
Mapping and Navigation delivers 45.35% of Nigeria location-based services market size in 2025 and remains core infrastructure for third-party apps. Nigeria location-based services market share for Social Networking and Entertainment, though smaller, is forecast to expand at 25.32% CAGR as young urban users share location-tagged video and AR games. Platforms like TikTok reach nearly 24 million adults, encouraging advertisers to target micro-locations. Messaging apps integrate ticket purchases tied to venue coordinates, broadening monetisation. Business Intelligence adopters in fast-food chains overlay footfall data on delivery zones to refine site selection, while targeted advertising faces tighter consent rules under the data act.
Navigation remains mature but diversifies into sector-specific APIs—fleet management, drone corridors and hazard alerts. Entertainment will outpace as 5G AR games bridge social interaction and physical spaces, challenging category definitions.
By End-user Vertical: Healthcare accelerates against transport dominance
Transportation and Logistics comprised 40.85% of Nigeria location-based services market share in 2025 as ko-loc platforms orchestrated everything from ride-hailing to bulk cargo. Healthcare now shows the fastest 18.91% CAGR because telemedicine platforms rely on geotagging to dispatch community nurses and direct patients to nearest facilities.
Location-enabled maternal-care app OMOMi has scaled nationwide usage, illustrating sector potential. Banks deploy proximity transfer features to meet cash-lite mandates, while telecoms harness location analytics to plan base-station upgrades. Government usage rises via cadastral surveys and address verification, and hospitality players use beacons to raise guest satisfaction in a reviving travel market. Manufacturing uptake stays modest until Industry 4.0 pilots move beyond proof-of-concept, leaving room for late-cycle acceleration.
Geography Analysis
Lagos dominates the Nigeria location-based services market because it hosts most corporate headquarters and handles a quarter of national commerce. Starlink’s first Nigerian earth station and MTN’s new USD 150 million Tier III data centre both sit in Lagos, ensuring low-latency processing for ride-hailing and fintech apps. The state’s revised cadastral policy improves spatial data integrity, supporting land-registry digitisation and urban planning. Regulatory activism—such as hearings on ride-hailing commission caps—signals a demanding but structured environment for innovators. Abuja ranks second because federal ministries embed geolocation in public services and incubate e-government tools. Startup grants and the DeepTech training programme attract developers who create sovereign alternatives to foreign APIs. Local deployment of proof-of-address frameworks further deepens demand for secure mapping layers in identity verification and public safety.
Port Harcourt, Kano and Ibadan form the next tier. Port Harcourt’s oil base needs asset tracking and pipeline monitoring that hinge on rugged GPS and satellite links, especially under new local-content directives. Kano’s trading heritage drives cross-border logistics, although patchy coverage elevates interest in satellite back-haul. Ibadan’s trio of malls records higher foot traffic when indoor wayfinding apps are available, showcasing latent commercial potential. Rural belts lag due to 4G gaps that reduce coverage for about 40 million citizens, yet pilot Starlink base stations hint at faster inclusion once terminal costs fall.
黑料不打烊 evaluates the location based services market across all key regional markets, including Africa and Middle East, with deeper country-level insights covering United Arab Emirates, Brazil, South Korea, China, Japan, India, and France.
Regulatory Landscape
Nigeria's location-based services (LBS) environment sits across telecommunications and data governance. The Nigerian Communications Commission (NCC), operating under the Nigerian Communications Act, 2003, provides oversight for operator-led and third-party services delivered over public networks, and it anchors licensing expectations that affect LBS enablers such as value-added services (VAS), aggregators, and related application delivery models. On the data side, the Nigeria Data Protection Act 2023 raises compliance requirements for location data processing, including registration and governance obligations for major data controllers, and explicitly increases downside exposure for non-compliance through financial penalties. This shapes how ride-hailing, logistics, fintech KYC, and targeted advertising use location signals.
Standards and interoperability direction also influence platform design choices. The National Information Technology Development Agency (NITDA) steers digital standards and public-sector IT coordination through instruments such as the Nigeria e-Government Interoperability Framework (Ne-GIF), supporting integration of geospatial and identity-linked datasets across agencies and service platforms. In practice, market participants manage dual alignment: NCC-linked requirements for service delivery over telecom infrastructure, and NITDA-linked governance for personal data handling and cross-system interoperability. Together, these determine onboarding, consent, storage, and partner API-sharing models for LBS deployments.
Value Chain Analysis
The Nigeria LBS value chain starts with positioning and connectivity inputs (GNSS signals, terrestrial mobile networks, and satellite backhaul), then moves into data creation and enrichment, including base maps, address intelligence, points of interest, indoor layouts, and verification datasets. Infrastructure operators and licensed service delivery layers, including NCC-governed VAS providers and aggregators, enable distribution at scale through SIM-based networks and smartphone operating systems. Cloud and data-center capacity in-country also supports low-latency processing and compliance-driven localization for location data workloads.
Application and monetization layers include mapping and navigation apps, mobility and logistics platforms, fintech and KYC address-verification workflows, and government service portals that use geospatial records for planning and public services. Local geospatial firms contribute GIS consulting, drone mapping, and remote-sensing services for both public and private-sector projects, improving accuracy in areas with fragmented addressing. Payment rails and transaction-switching infrastructure, supported by players such as Interswitch, sit downstream as a monetization enabler, helping LBS providers embed location intelligence into checkout, fraud controls, proximity-based offers, and service fulfillment across verticals.
Competitive Landscape
The Nigeria location-based services market hosts a mix of multinationals and agile locals, yielding moderate concentration. Google Maps still anchors most consumer navigation, but banks, logistics firms and health start-ups often prefer niche providers that tailor to Nigeria’s addressing gaps. OkHi and What3words both bid to standardise address codes, driving differentiation through financial-service integrations. MTN, Airtel and Globacom exploit vast subscriber data to upsell location analytics, while Uber and Bolt refine matching algorithms to stay ahead of 2,500 smaller ride-hailing entrants.
Satellite access is an emerging battleground. Starlink rose to second-largest ISP within two years, forcing mobile operators to accelerate rural coverage partnerships. Data-centre builds, exemplified by MTN’s Dabengwa facility, enable global cloud players to keep latency low and comply with data-localisation mandates, favoring deeper collaboration rather than direct rivalry. Compliance with the Data Protection Act screens out under-funded aspirants, subtly raising entry barriers and nudging the market toward higher professionalism.
White-space opportunities lie in indoor analytics, emergency dispatch, and agriculture drones. Providers that embed secure APIs into everyday consumer apps—such as GTBank’s Near Me transfer—gain stickiness without expensive customer acquisition campaigns. Continuous regulatory engagement, local talent development and address-system innovation remain decisive factors for sustained share gains.
Nigeria Location-based Services Industry Leaders
Google LLC
Microsoft Corporation
Apple Inc.
Huawei Technologies Co. Ltd
Uber Technologies Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Near-term whitespace concentrates where Nigeria's addressing fragmentation and compliance needs overlap: address verification for BFSI and fintech onboarding, last-mile logistics routing, and public-sector service delivery that requires auditable geotags. The Nigeria Data Protection Act 2023 has made consent, governance, and data-handling controls a product feature rather than a back-office task. That shift creates room for service-led LBS bundles that combine mapping, verification, and compliance tooling for enterprises that do not want to build in-house stacks. The report's 2025 component mix, with Services holding 44.65% share, also points to a market structure where integration, support, and governance drive procurement decisions.
Opportunities expand further around platform and dataset upgrades that improve baseline map quality and reduce localization friction for enterprises. Microsoft's Bing Maps shift to TomTom Orbis Maps data (rolled out globally and including Nigeria), along with mobility integrations such as Shuttlers publishing routes to Google Maps Transit, increases the utility of consumer and enterprise routing, discovery, and ETA services in major cities. On the supply side, Nigeria's National Digital Economy Policy and Strategy (2020-2030) and NITDA-led standardization and interoperability direction support more government-to-private integrations, which can enable indoor-outdoor continuity for malls, hospitals, and transport hubs, and reinforce location intelligence use cases linked to payments, identity, and e-government workflows.
Recent Industry Developments
- June 2026: Shuttlers integrates its bus routes and scheduling with Google Maps Transit across Lagos, Abuja, and Port Harcourt. The integration extends reach of location-based routing into mass transit, expanding user adoption in urban corridors. It strengthens Nigeria’s shared mobility data ecosystem and visibility for LBS-enabled transit services.
- April 2026: Microsoft Corporation completed a global Bing Maps address data upgrade in Nigeria, adopting TomTom Orbis Maps to improve location accuracy for consumer and enterprise services. The upgrade boosts geospatial accuracy for Nigeria-specific LBS offerings and Azure Maps deployments. This establishes upgraded base-mapping data as foundational for Nigerian LBS players and government applications.
- February 2026: Google LLC met with Nigeria’s Ministry of Foreign Affairs to formalize a strategic partnership focusing on sustainable digital transformation and AI knowledge transfer. The government collaboration shapes Nigeria’s digital transformation trajectory. It signals institutional support and potential regulatory alignment for location-based services growth.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the revenue earned in Nigeria from location based services that use a user or asset location signal to deliver a digital function, such as navigation, analytics, proximity marketing, and tracking, across consumer and enterprise uses.
Scope exclusions: We exclude pure device resale value where location features are incidental, and we exclude general telecom connectivity revenue that is not priced as a location based service.
Segmentation Overview
- By Component
- Hardware
- Software
- Services
- By Location Type
- Indoor
- Outdoor
- By Application
- Mapping and Navigation
- Business Intelligence and Analytics
- Location-based Advertising
- Social Networking and Entertainment
- Other Applications
- By End-user Vertical
- Transportation and Logistics
- IT and Telecom
- Healthcare
- Government
- BFSI
- Hospitality
- Manufacturing
- Other End-users
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the Nigeria-specific demand backdrop and to anchor the model on measurable signals that are refreshed on a predictable cadence. We typically begin with official telecom and broadband indicators, such as publications from the Nigerian Communications Commission, the National Bureau of Statistics, and ITU data series for mobile and internet access.
To link usage to spend, we also review public sources on how mapping, positioning, and digital advertising are developing, including World Bank digital economy notes, GSMA reports, and academic studies on mobility data and location privacy. This is complemented with company filings and investor presentations, reputable press coverage, and selectively, paid subscriptions used for company financials, news screening, patent lookups, and shipment-level import and export checks where relevant. The sources listed here are illustrative only, since many other public references are also used for cross-checks and clarification during the study.
Primary Interviews and Surveys
We consult experts in Nigeria across telecom, mapping, logistics, advertising, fintech, healthcare, and public services. Discussions clarify how providers define paid location features, active users, pricing, state coverage, enterprise demand, and privacy rules. These inputs help fill gaps and reconcile differences between secondary estimates.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 15% |
| Mid tier: 50% | Functional/Unit leaders: 30% |
| Smaller Players: 20% | Managers: 55% |
Market-Sizing & Forecasting
Sizing started from a top-down build that converts Nigeria digital usage into a location services revenue pool by applying penetration and monetization assumptions by major use area, and then splitting the total into components and end-use buckets. Key inputs used in the model include smartphone and mobile internet adoption, the share of app and enterprise workflows that require positioning, the mix of indoor versus outdoor use, and observed pricing patterns for location-enabled software and managed services.
To keep totals realistic, we also ran selective bottom-up approximations as a check, such as sampled buyer spend ranges in logistics and transport, channel feedback on solution deployment volumes, and sanity checks against disclosed revenue mixes where available. Where the evidence was incomplete, gaps were handled by using conservative midpoints from interview ranges, then stress-testing outcomes with scenario analysis.
For forecasting, we used scenario analysis supported by trend-based techniques, tracking expected shifts in data coverage, enterprise digitization speed, and use case maturity in Nigeria. Assumptions were revisited when primary feedback indicated step changes, such as faster adoption of location analytics in fleet management or slower ramp in location based advertising due to measurement limitations.
Data Validation & Update Cycle
Outputs were validated through triangulation across independent signals, before moving the results into internal review. We check for variances across component splits, indoor versus outdoor mixes, and end-user totals, then rework inputs when implied spend per user or spend per enterprise looks inconsistent with what interviews and public indicators suggest.
Anomaly checks are performed at each step, followed by analyst review that challenges growth drivers, price paths, and currency conversion timing. Reports are refreshed annually, and interim updates are triggered when material events occur, including policy changes, major network upgrades, or sharp shifts in inflation and exchange rates. Before delivery, a final pass is completed so clients receive the latest updated view.
黑料不打烊's Nigeria Location Based Services Market Size Measured Against Other Published Estimates
Published numbers for Nigeria location based services can differ even when they appear to describe the same space, since the counted revenue stream is often defined differently. Differences usually come from whether the estimate includes adjacent hardware spending, how indoor use cases are treated, and how exchange rates and inflation are applied to convert local pricing into USD.
The table shows a noticeable spread across estimates, and in 黑料不打烊's model the value is built from software and services-led LBS revenue within Nigeria, with telecom connectivity revenue and non essential device resale kept outside scope so the total remains tied to location-driven monetization.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 310.97 M (2025) | |
| Regional Consultancy A | USD 250.00 M (2024) | Often reported as a narrower 2024 snapshot that leans on consumer app usage signals, which can undercount enterprise contracts in logistics, healthcare, and government deployments. |
| Industry Publisher B | USD 360.00 M (2025) | May fold in adjacent hardware and tracking device revenue or broader geospatial spend, and can apply aggressive pricing uplift assumptions without consistent checks on actual contract mixes. |
Overall, the gap mostly comes down to what is counted as location based services revenue versus nearby spending categories, and how realistic the price and adoption inputs are in the forecast. By keeping scope aligned to monetized location functions and checking implied spend levels against practical buyer behavior, the estimate stays easier to audit and repeat across years.


Key Questions Answered in the Report
What is the current value of the Nigeria location-based services market?
The market is valued at USD 338.44 million in 2026, with a forecast to reach USD 517.3 million by 2031.
Which segment grows fastest in the Nigeria location-based services market?
Social Networking and Entertainment applications show the highest growth trajectory at 25.32% CAGR through 2031.
Why are Services the largest spending category?
Enterprises prefer turnkey geolocation solutions that bundle compliance, mapping and support, giving Services 44.65% market share in 2025.
How does regulation affect market growth?
The Nigeria Data Protection Act raises compliance costs and data-localisation requirements, trimming projected CAGR by 1.2 percentage points.
Page last updated on:



