
UAE Location-based Services Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.62 Billion |
| Market Size (2026) | USD 0.71 Billion |
| Market Size (2031) | USD 1.37 Billion |
| Growth Rate (2026 - 2031) | 14.08 % |
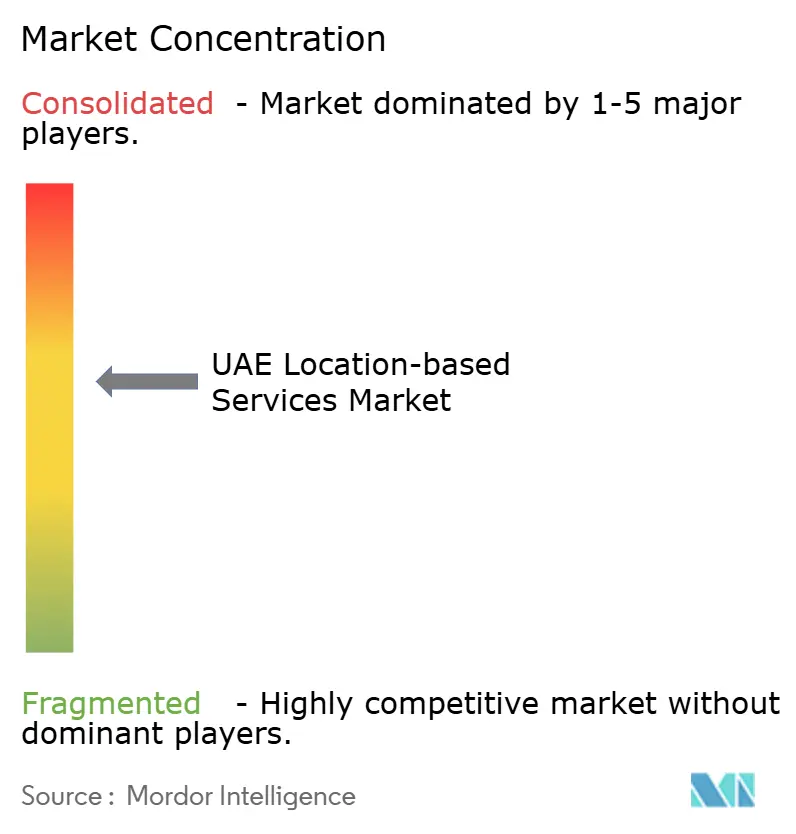
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
UAE Location-based Services Market Analysis by 黑料不打烊
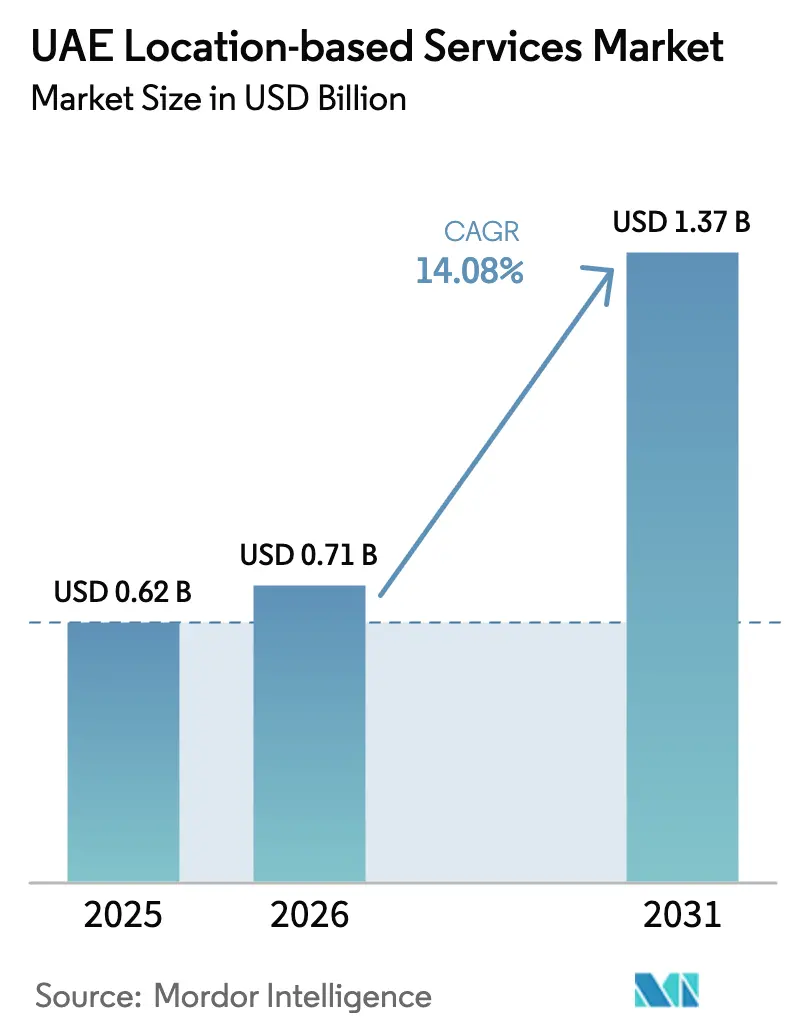
The UAE location-based services market size is expected to grow from USD 0.62 billion in 2025 to USD 0.71 billion in 2026 and is forecast to reach USD 1.37 billion by 2031 at 14.08% CAGR over 2026-2031. Robust 5G coverage, ambitious smart-city programs, and rising enterprise demand for hyper-local analytics jointly accelerate adoption. Hardware still drives data collection, yet spending is shifting to AI-enabled software that turns raw coordinates into commercial insight. Indoor positioning enjoys tailwinds from retail, hospitality, and energy operators seeking worker safety and customer experience gains. E-commerce expansion pushes logistics firms to refine real-time routing, while telecom carriers open network APIs that let third-party developers monetize precise location data.
Key Report Takeaways
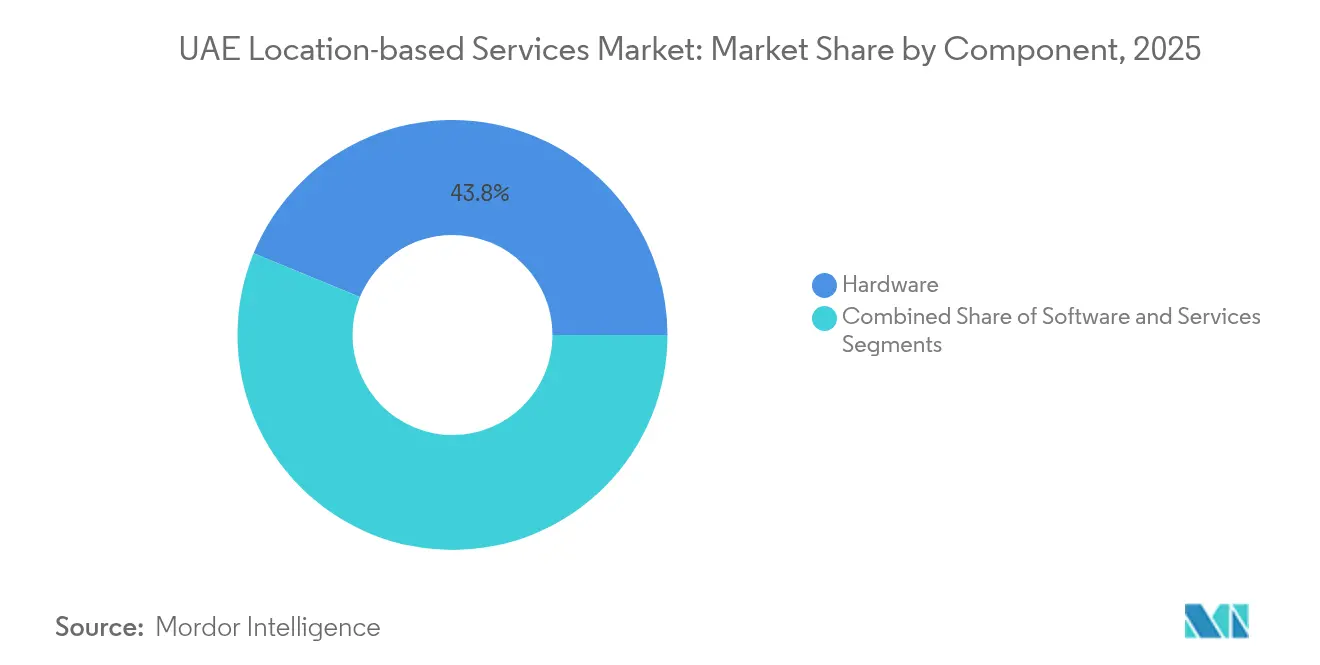
- By component, hardware captured 43.80% of the UAE location-based services market share in 2025; software is forecast to expand at a 26.72% CAGR through 2031.
- By location type, outdoor services held 61.20% revenue share of the UAE location-based services market size in 2025, whereas indoor positioning is advancing at a 27.65% CAGR through 2031.
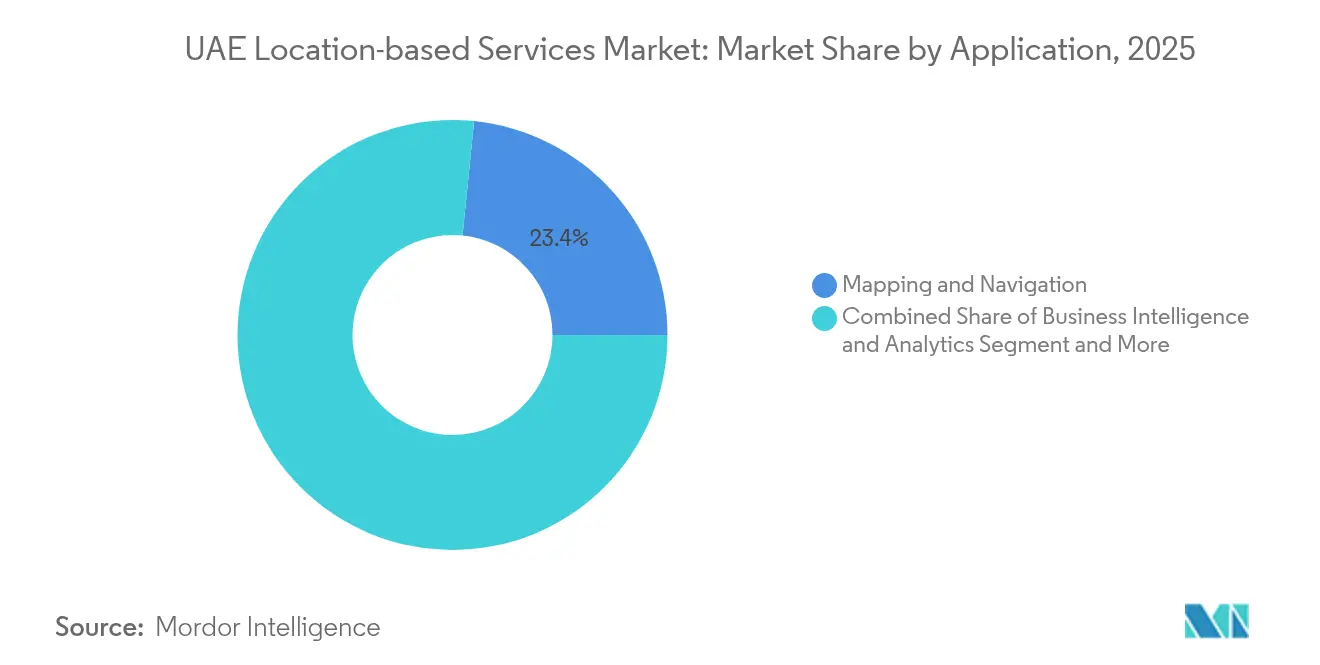
- By application, mapping and navigation accounted for 23.40% of the UAE location-based services market size in 2025 and location-based advertising is growing at a 29.52% CAGR through 2031.
- By end-user vertical, transportation and logistics led with 26.90% share of the UAE location-based services market size in 2025, while IT and telecom is set to post the highest CAGR at 24.76% through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
United arab emirates holds a defined position within a broader international distribution. The location based services market share data by 黑料不打烊 maps that allocation across all contributing countries and regions, globally.
UAE Location-based Services Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Nationwide 5G rollout enabling sub-meter indoor positioning | +3.2% | UAE-wide, concentrated in Dubai and Abu Dhabi | Medium term (2-4 years) |
| Government smart-city initiatives | +2.8% | Dubai and Abu Dhabi | Long term (≥ 4 years) |
| Rapid e-commerce growth driving hyper-local logistics | +2.1% | UAE-wide urban hubs | Short term (≤ 2 years) |
| High smartphone and social-media penetration | +1.8% | UAE-wide | Short term (≤ 2 years) |
| Mandatory e-call/telematics rules for commercial fleets | +1.5% | UAE-wide | Medium term (2-4 years) |
| UWB adoption for worker safety in energy facilities | +1.3% | Abu Dhabi and Northern Emirates | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Nationwide 5G Rollout Enabling Sub-meter Indoor Positioning
Operators recorded live 5G speeds topping 30.5 Gbps, enabling centimeter-level accuracy inside malls, airports, and industrial plants. Release 18 standards add positioning features such as frequency hopping that reduce signal multipath error [1]Ericsson, “5G Advanced positioning in 3GPP Release 18,” ericsson.com . Early private 5G projects, including ADNOC’s 11,000 km? energy network, validate large-scale deployments that merge connectivity and geolocation in a single managed slice. Telecom carriers are exposing these capabilities through open APIs so software firms can embed assured location into consumer and enterprise apps. As coverage densifies across all seven emirates, service latency falls, unlocking AR navigation and autonomous trolley robots in retail stores.
Government Smart-City Initiatives (Smart Dubai, Abu Dhabi 2030)
Dubai earmarked AED 1.6 billion (USD 0.44 billion) for 82 digital projects that embed location analytics into public transport, utilities, and citizen services. The emirate targets 25% autonomous journeys by 2030, a milestone that relies on continuous positioning of vehicles and street assets. Abu Dhabi plans to run every departmental workflow on an AI stack by 2027, backed by AED 13 billion in digital infrastructure spending that prioritizes common geospatial platforms. Unified databases reduce duplication and create demand for high-quality mapping feeds. Super-apps such as TAMM already use location context to cut service-completion steps for residents. These programs produce sustained multi-year orders for mapping vendors and indoor analytics specialists.
Rapid E-commerce Growth Driving Hyper-local Logistics
Parcel volumes surge as cross-border marketplaces localize fulfillment centers inside the UAE. Logistics players such as Aramex automate route sequencing and real-time driver guidance to protect margins amid rising same-day delivery expectations. IoT tags on temperature-sensitive shipments allow shippers to intervene before spoilage. Niche providers supply Bluetooth-enabled pallets that report both coordinates and ambient data to control towers. The UAE ranked among the top ten economies for mobile-commerce spend per capita in 2024, intensifying competition to reach consumers within two-hour windows, a requirement impossible without high-resolution geocoding.
UWB Adoption for Worker Safety in Energy Facilities
Ultra-Wideband anchors achieve centimeter accuracy in metallic, obstructed settings where GPS and Wi-Fi falter. ADNOC expects private 5G plus UWB deployments to unlock USD 1.5 billion in value by reducing accidents and asset downtime. Wearables trigger automated shutdowns when staff enter exclusion zones. Over time, facility managers integrate UWB feeds with AI models that predict unsafe behaviors hours in advance, further boosting demand for unified location dashboards. Pilot successes in oilfields encourage chemical and cement producers to budget similar projects by 2026.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Heightened data-privacy compliance costs | -2.3% | UAE-wide | Short term (≤ 2 years) |
| GNSS signal fade in high-rise and indoor settings | -1.8% | Dubai and Abu Dhabi urban cores | Medium term (2-4 years) |
| High indoor-5G capital costs for malls and hotels | -1.4% | Major tourist districts | Medium term (2-4 years) |
| Fragmented emirate-level open-data APIs | -0.9% | Inter-emirate operations | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Heightened Data-privacy Compliance Costs
The Personal Data Protection Law mirrors GDPR rules and fines violators up to AED 5 million (USD 1.36 Million)[3]Secure Privacy, “Guide to UAE Data Protection Law (PDPL),” secureprivacy.ai. Location providers now appoint data-protection officers, update consent flows, and encrypt historical logs, adding overhead that can reach 8-10% of project budgets. Global vendors face dual audits when processing UAE records in foreign data centers. Compliance has already delayed rollouts of ad-tech platforms that rely on continuous location tracking, prompting some retailers to adopt on-device analytics to minimize data transfers. Government pilots of biometric IDs show regulators will favor privacy-by-design architectures.
GNSS Signal Fade in High-rise and Indoor Settings
Urban canyons in Dubai’s central business district create multipath distortion, degrading GPS accuracy to tens of meters. Studies on Wi-Fi fingerprinting reveal high scan latency and client density issues that further impair indoor resolution. Providers must combine Bluetooth, cellular, and inertial sensors, raising integration complexity and lead time. Solutions such as resonant radio mapping improve baseline performance but still require site surveys every time floor layouts change. Consequently, some mall operators postpone full-scale deployments until chipset support for sensor fusion matures.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Component: Software Accelerates Value Creation
Hardware retained 43.80% revenue in 2025, yet software is set to grow at 26.72% CAGR, far outpacing physical devices. The UAE location-based services market size for software is projected to surpass hardware by 2028 as enterprises favor cloud dashboards that transform coordinates into predictive insights. Price erosion in chipsets pressures margins, pushing vendors toward subscription analytics engines. Microsoft’s AED 2 billion (USD 0.54 Billion) hyperscale data center with du illustrates rising investment in AI accelerators that preprocess location streams.
Service contracts expand as integrators calibrate indoor beacons, align mapping layers with privacy policies, and train users on dashboards. Complex multicloud scenarios, where data flows between Azure and on-premise clusters inside oil refineries, sustain recurring revenue for consultancy arms. Patent filings by Meta and Apple underline a shift to context-aware algorithms that adjust accuracy based on motion state, pointing to continued software innovation.


By Location Type: Indoor Positioning Gains Momentum
Outdoor solutions commanded 61.20% of 2025 spending, driven by fleet telematics and consumer navigation apps. Yet indoor deployments are climbing 27.65% annually, adding hospitals, malls, airports, and refineries to the addressable base. The UAE location-based services market share for indoor systems is expected to exceed 40.00% by 2031 as beacon prices fall and Wi-Fi 6E spreads. Reem Mall’s full-coverage rollout shows visitors engage longer when wayfinding and loyalty vouchers combine in a single app.
Accuracy advances near 20 centimeters using UWB tags, proven in road-worker safety pilots that achieved 97% correct zone classification . Hotels adopt indoor grids to trigger housekeeping alerts when guests leave rooms, reducing wait times. Energy majors embed tags in personal protective equipment to geo-fence hazard zones, meeting compliance with minimal manual checks.
By Application: Advertising Outpaces Traditional Navigation
Mapping and navigation kept 23.40% of 2025 turnover, but advertisers are investing faster as geofencing returns clear sales lifts. Location-based advertising is growing 29.52% per year and will rival navigation revenue by 2029. The UAE location-based services market size for advertising links directly to high smartphone penetration and affluent shopper profiles. Palm ID biometric payments enable instant, location-triggered checkout, letting brands close the loop from notification to purchase.
Business-intelligence dashboards analyze foot-traffic patterns so retailers tailor inventory to micro-catchments. Social apps add ephemeral location pins to foster meet-ups, supporting ad inventory. Healthcare pilots use location to timestamp vitals for chronic patients, illuminating a long-tail of “other” use cases that will collectively approach double-digit share by 2030.
By End-user Vertical: Telecom Leads, Logistics Remains Vital
Transportation and logistics owned 26.90% of 2025 revenue, reflecting early telematics adoption. Yet IT and telecom grows quickest at 24.76% CAGR as carriers seek new revenue beyond data bundles. Operators like eand bundle network slices with indoor analytics, positioning themselves as one-stop platforms for enterprises. The UAE location-based services industry now views location as a service layer rather than a discrete product.
Healthcare networks encrypt patient coordinates across 160 sites under Fortinet security, validating location’s role in sensitive workflows. Government agencies knit together police, fire, and civil services through shared GIS layers that slash response times. Banks push location-aware fraud alerts to reduce card misuse, and hoteliers deploy guest-wayfinding to differentiate premium properties.
Geography Analysis
Dubai and Abu Dhabi dominated roughly 74.60% of 2025 spending thanks to dense populations, tourist flows, and public-sector digital budgets. The UAE location-based services market size in Dubai benefits from autonomous-vehicle pilots that require always-on mapping feeds. Abu Dhabi’s AI-native government plan draws hyperscale datacenters that demand granular geospatial data for model training.
Sharjah, Ajman, and Ras Al Khaimah show double-digit growth as real-estate and tourism investments rise. Sharjah’s IoT firms export cold-chain trackers across the Gulf, highlighting regional spillovers. Ras Al Khaimah’s upcoming Hilton resort intends to merge indoor navigation with loyalty dashboards on opening day.
Fujairah and Umm Al Quwain contribute modest shares but adopt maritime and port logistics solutions that demand precise location to schedule bunkering and cargo transfers. Federal programs aim to unify emirate APIs by 2025, lowering integration friction for cross-border fleets.
黑料不打烊 delivers a comprehensive view of the location based services market across all major regions such as Middle East and Africa, alongside country-level analysis for France, Germany, China, Japan, India, Canada, and Spain, each offering a view of the local market realities.
Regulatory Landscape
The UAE location-based services market operates under a mix of telecom regulation, geospatial governance, and data-protection requirements. The Telecommunications and Digital Government Regulatory Authority (TDRA) regulates telecommunications and network-based service provision under Federal Law by Decree No. 3 of 2003 (as amended), which affects how operators and service providers deliver connectivity and location-enabled services. In parallel, the Federal Geographic Information Center (FGIC), established under Federal Decree-Law No. 5 of 2019, governs national geospatial infrastructure and works to unify geospatial standards while protecting geographic data through mechanisms such as the National Spatial Data Infrastructure.
From a compliance standpoint, TDRA device type approval requirements influence the deployment of GNSS, cellular, Bluetooth, Wi-Fi, and other radio-enabled location hardware that connects to UAE networks, with alignment to applicable GCC technical standards for RF, safety, and EMC. For software-led use cases such as advertising, analytics, and consumer apps, the UAE Personal Data Protection Law tightens scrutiny of consent, retention, cross-border processing, and privacy-by-design, affecting location data collection, profiling, and storage practices across sectors.
Value Chain Analysis
The value chain starts with positioning and connectivity enablers, including device and module suppliers (GNSS, cellular, UWB, Bluetooth/Wi-Fi) and telecom infrastructure operated by e& and du, which provide national coverage and enterprise services that underpin outdoor tracking and indoor positioning. Hardware and connectivity then feed into platform layers that include mapping and content providers, geospatial databases, and cloud and edge compute environments where location streams are processed into usable events, routes, and insights.
System integrators and specialized solution providers assemble end-to-end deployments for enterprise and public-sector buyers, combining sensors, SIMs, gateways, and applications such as fleet management, telematics, and indoor and outdoor wayfinding. Within the UAE ecosystem, firms such as Location Solutions, Smart Navigation System, and Trakker Middle East provide downstream solution delivery, typically integrating international hardware components (GPS/GSM/GPRS/satellite) with software platforms and third-party map SDKs to serve logistics, oil and gas, and emergency response. The chain ends with enterprise users (transport and logistics, government, hospitality, healthcare, and industrial sites) that procure subscriptions, installation and calibration services, and ongoing support under security, data residency, and privacy compliance requirements.
Competitive Landscape
Global map majors HERE, TomTom, and Apple supply SDKs to mobility platforms, while Microsoft courts government accounts through Azure Maps. Telecom incumbents eand and du convert 5G infrastructure into enterprise location clouds, capturing data-sovereignty-sensitive deals. The UAE location-based services market sees mid-tier specialists provide indoor kits and sector-specific dashboards, enabling hospitals and refineries to adopt without building from scratch.
Strategic alliances dominate: eand pairs with IBM on AI governance so clients can audit location flows. Qualcomm teams with eand to bundle edge AI and industrial 5G, accelerating factory uptake. Uber selects HERE for global map refresh and collaborates with WeRide to run robotaxis in both Abu Dhabi and Dubai.
Patent races intensify around UWB discovery and sensor fusion, raising barriers for new entrants. Market consolidation looms as software house valuations hinge on recurring subscription ratios. The top five vendors held just under 60% combined revenue in 2024, indicating a moderately concentrated field open to niche challengers.
UAE Location-based Services Industry Leaders
Google LLC
Location Solutions Telemetics LLC.
TomTom International BV
GapMaps
ALE International
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A key opportunity area is the formalization and scaling of national geospatial data sharing for commercial applications, supported by the UAE National Geospatial Information Policy and FGIC stewardship of the National Spatial Data Infrastructure (NSDI). As authorized access to standardized geospatial layers becomes more practical, solution providers can productize repeatable offerings for routing, addressing, and asset management rather than rebuilding datasets per emirate or per project. Abu Dhabi Addressing, Geonames and Signage System (ADAGS), implemented with service-oriented integration, illustrates the type of addressing and wayfinding backbone that supports logistics optimization and city-scale navigation services.
Another opportunity involves privacy-preserving location analytics that reduces compliance overhead under the UAE PDPL while sustaining performance for use cases such as location-based advertising and footfall intelligence. Providers that push more processing to the device or to in-country cloud zones, while maintaining auditable consent and retention controls, can better serve retailers, hospitality operators, and government entities that need both personalization and governance. On the supply side, UAE-wide 5G densification and operator-led enterprise propositions, including location-enabled network capabilities, create room for packaged indoor positioning offers in malls, airports, hotels, and industrial sites, where buyers increasingly prefer turnkey deployments that bundle connectivity, calibration, and analytics into a single contract.
Recent Industry Developments
- July 2026: TRUXX launched the pilot of the Qawafel national digital land freight platform to enhance pricing visibility and operational efficiency in the UAE logistics sector. The initiative advances UAE digital freight and location-enabled logistics by delivering real-time pricing and route optimization. It strengthens UAE LBS-enabled supply-chain visibility and pricing transparency for the nationwide freight network.
- June 2026: Ras Al Khaimah Tourism Development Authority (RAKTDA) and Huawei expanded strategic partnership to enhance digital tourism capabilities, including integration of location-based services for personalized visitor experiences. The collaboration boosts location-enabled tourism analytics and smart city visitor engagement in northern UAE markets. It expands access to AI driven analytics and digital experiences for tourists.
- June 2026: Google LLC launched Map Your Dubai: Insider Edition in collaboration with the Dubai Department of Economy and Tourism to support the local F and B sector by boosting digital visibility on Google Maps. The initiative strengthens UAE map-based visibility for local F&B and small businesses. It reinforces Google Maps as a core enterprise and consumer LBS platform in the UAE market.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the market covers spending in the UAE on software, services, and enabling components that capture, manage, and use location signals to deliver indoor or outdoor location aware functions across consumer and enterprise use cases.
Scope exclusions: We exclude general IT outsourcing that is not tied to location data generation, processing, or delivery.
Segmentation Overview
- By Component
- Hardware
- Software
- Services
- By Location Type
- Indoor
- Outdoor
- By Application
- Mapping and Navigation
- Business Intelligence and Analytics
- Location-based Advertising
- Social Networking and Entertainment
- Other Applications
- By End-user Vertical
- Transportation and Logistics
- IT and Telecom
- Healthcare
- Government
- BFSI
- Hospitality
- Manufacturing
- Other End-users
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the base demand story and keep assumptions tied to measurable signals in the UAE. We reviewed public references such as telecom and spectrum updates from the UAE Telecommunications and Digital Government Regulatory Authority, national statistics from the Federal Competitiveness and Statistics Centre, UAE policy and smart city releases from government portals, customs and trade references where relevant, and technical papers from IEEE and other peer reviewed venues.
To translate these signals into a market model, we also screened company annual reports, investor presentations, reputable press, and association websites that track digital infrastructure and mobility trends. When needed, we referred to paid subscriptions for company financials and intelligence, patent lookups, and shipment level import export checks to sense hardware and device flows that enable location data. The sources listed here are illustrative only, and many other public and proprietary references were consulted for collection, cross-checking, and clarification.
Primary Interviews and Surveys
Primary work focused on validating what is actually monetized as location based services in the UAE, and how pricing shifts by use case. We spoke with executives, functional leaders, and managers across solution providers, telecom related stakeholders, system integrators, and enterprise users to confirm adoption timing, typical contract structures, and the split between indoor and outdoor deployments. Since the title is country specific, the fieldwork emphasized UAE buyer groups and delivery models, then we rechecked the assumptions for consistency across sectors like logistics, retail, government, and healthcare.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 29% | CXOs: 16% |
| Mid tier: 50% | Functional/Unit leaders: 28% |
| Smaller Players: 21% | Managers: 56% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where telecom readiness, smartphone and mobile data usage, smart city project pipelines, and enterprise digital spend signals are used to reconstruct the spend pool that can reasonably attach to location functionality. Those totals are then pressure tested using selective bottom-up approximations, including sampled contract values for indoor positioning rollouts, route optimization deployments, and location analytics subscriptions, followed by ASP time volume checks for enabling components when pricing is observable.
A few practical inputs that shaped the model include 5G coverage and rollout milestones, the pace of smart city and transport digitization projects, growth in e-commerce driven last mile activity, indoor venue density (airports, malls, and large facilities), and the typical shift from one-time deployment fees to recurring software and managed services. Where bottom-up visibility is limited for smaller deployments, we filled gaps using adoption ranges agreed in interviews, then scaled them with sector level activity indicators.
For forecasting, we used scenario analysis supported by short trend smoothing on key drivers, and then aligned the outlook with expert consensus on penetration progression and price normalization. The final trajectory is kept realistic by applying conservative ramps in segments that are still early, and faster ramps where contracts and budgets are already visible.
Data Validation & Update Cycle
Validation happens in layers so the final number is not dependent on a single assumption. We triangulate the model against independent signals such as telecom network progress, public program timelines, and observed enterprise deployment patterns, then large variances are traced back to either pricing, adoption, or scope tagging.
Before sign-off, another analyst reviews the inputs and recomputes key steps to catch formula errors, unit mismatches, or currency timing issues. If a major inconsistency shows up, we re-contact selected interviewees to retest the specific assumption that is driving the swing. Reports are refreshed annually, and interim updates are made when material events change demand conditions, followed by a final pre-delivery check so clients receive the latest view.
黑料不打烊's UAE Location Based Services Market Size Versus Other Published Estimates
Published figures for UAE location based services can look far apart because the category is easy to stretch into adjacent digital spend. Different studies also use different base years, exchange rate timing, and implied pricing paths, which then changes the math even when the same growth story is used.
Non location digital advertising spend is one common add-on, and it sits outside 黑料不打烊's scope for this market, which keeps the value tied to products and services where location signals are the primary delivered function. Other gaps come from bundling broad maps content licensing, counting full smartphone hardware value, or applying aggressive ASP growth without checking how contracts are structured in the UAE for indoor deployments and enterprise analytics.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 0.62 B (2025) | |
| Regional Consultancy A | USD 0.80 B (2025) | Often folds in wider digital advertising and customer engagement spend tagged as location marketing, and then applies higher take rates on hyperlocal campaigns. |
| Industry Association B | USD 0.54 B (2025) | Tends to emphasize device and telecom network enablement spend only, which can undercount recurring software subscriptions, integration, and managed services tied to location analytics. |
The table shows that the spread mostly comes from what gets counted as location driven revenue and how recurring software and services are treated. By keeping the inputs connected to observable deployment activity, contract pricing ranges, and UAE specific demand drivers, our estimate remains traceable and can be repeated as conditions change.


Key Questions Answered in the Report
What is the current value of the UAE location-based services market?
The market is valued at USD 0.71 billion in 2026 and is forecast to reach USD 1.37 billion by 2031.
Which segment grows fastest in the UAE location-based services market?
Indoor positioning systems exhibit the fastest CAGR at 27.65% thanks to retail, hospitality, and energy deployments.
Why are telecom operators investing heavily in location services?
Carriers such as eand and du monetize 5G network slices and AI platforms, generating new revenue beyond voice and data by offering location analytics to enterprises.
How do privacy regulations affect market growth?
The Personal Data Protection Law increases compliance costs and drives firms to adopt privacy-by-design architectures, trimming the overall CAGR by an estimated 2.3%.
Page last updated on:



