
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.27 Billion |
| Market Size (2026) | USD 3.67 Billion |
| Market Size (2031) | USD 6.54 Billion |
| Growth Rate (2026 - 2031) | 12.23 % |
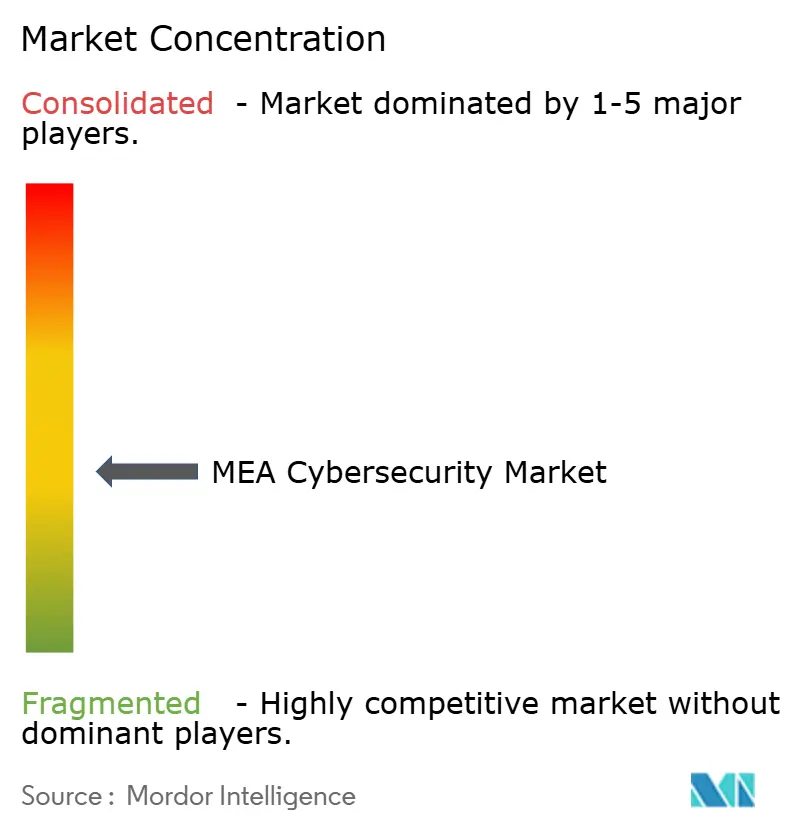
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
MEA Cybersecurity Market Analysis by 黑料不打烊
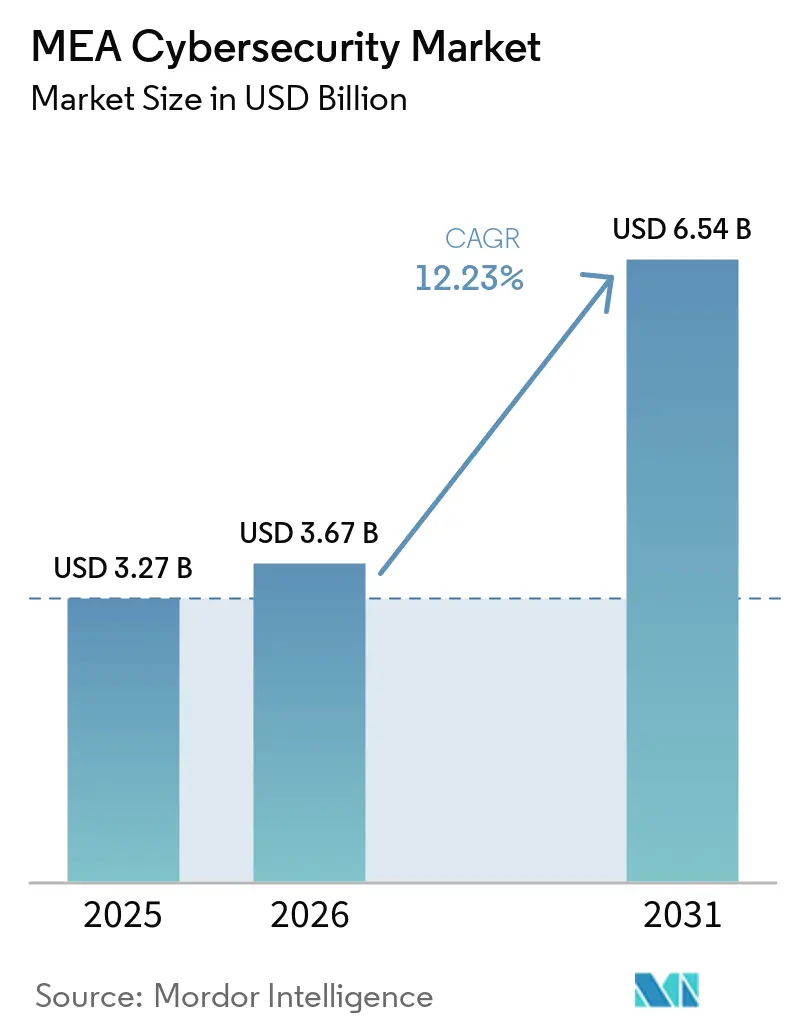
The MEA cybersecurity market size is expected to increase from USD 3.27 billion in 2025 to USD 3.67 billion in 2026 and reach USD 6.54 billion by 2031, growing at a CAGR of 12.23% over 2026-2031. Rapid sovereign cloud rollouts across the Gulf Cooperation Council, mounting operational technology (OT) threats to regional oil and gas assets, and explosive mobile money adoption in Sub-Saharan Africa are converging to drive up security spending. Mega-event pipelines such as Expo 2030 and NEOM drive hardening of critical national infrastructure, while cloud-delivered security gains traction as organizations modernize toward zero-trust architectures. Parallel cost pressures from an acute talent shortage and fragmented data protection laws create opportunities for managed security service providers to capture market share in the Middle East and Africa cybersecurity market.
Key Report Takeaways
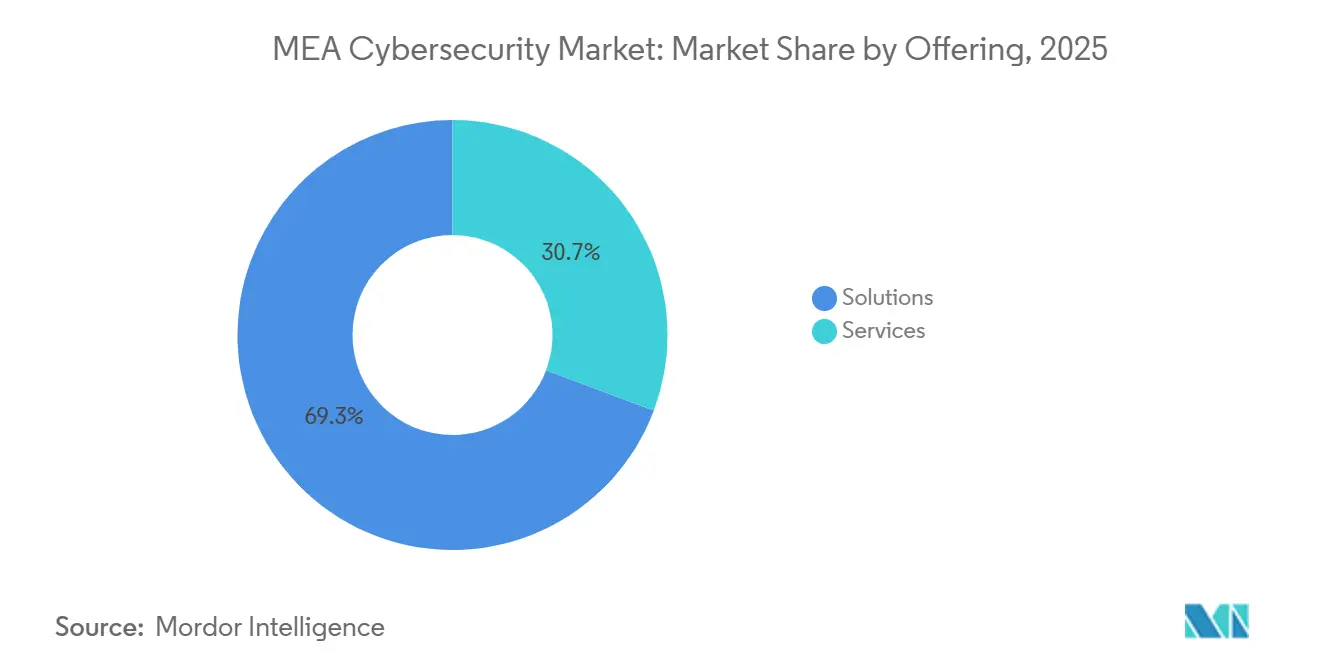
- By offering solutions, the Middle East and Africa cybersecurity market share held by solutions is forecast to reach 69.28% in 2025, whereas services are forecast to expand at a 14.68% CAGR through 2031.
- By deployment mode, cloud commanded a 57.61% share of the Middle East and Africa cybersecurity market in 2025, while cloud-delivered security is set to grow at a 15.43% CAGR.
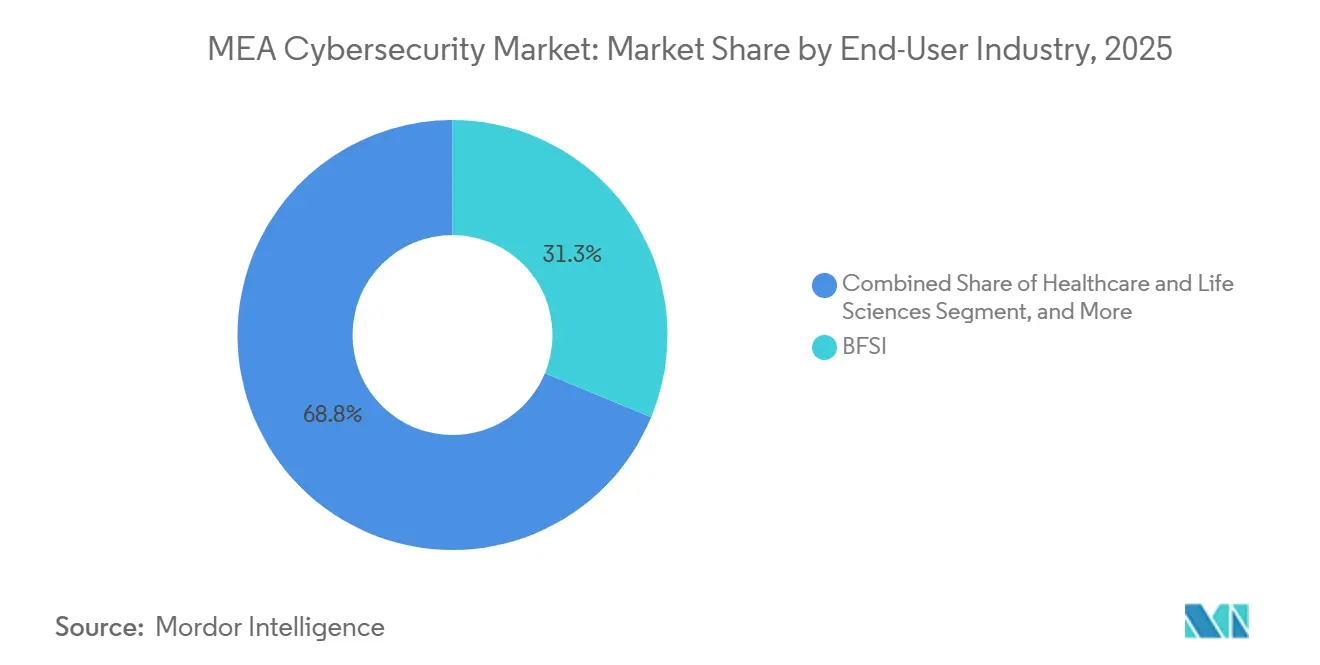
- By end-user vertical, banking, financial services, and insurance (BFSI) led with 31.25% revenue share in 2025, the healthcare and life sciences industry is advancing at a 15.02% CAGR to 2031.
- By enterprise size, large enterprises accounted for 67.45% of spending in 2025, while the SME segment accelerated at a 14.36% CAGR through 2031.
- By country, Saudi Arabia retained a 24.81% share in 2025, and Nigeria is forecast to grow fastest at a 16.42% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
MEA Cybersecurity Market Trends and Insights
Drivers Impact Analysis*
| Driver | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Sovereign-cloud and Residency Mandates across GCC Accelerating SOC Investments | +2.1% | GCC nations | Medium term (2-4 years) |
| Rapid Digital-Banking License Issuance in KSA and UAE Boosting Compliance-led Security Spend | +1.8% | Saudi Arabia, UAE | Short term (≤ 2 years) |
| Escalating OT Cyber-attacks on Oil and Gas Assets Driving ICS/SCADA Security Uptake | +1.6% | Middle East, North Africa | Medium term (2-4 years) |
| Explosive Mobile-Money Adoption in Sub-Saharan Africa Requiring Endpoint and Fraud Protection | +2.3% | Sub-Saharan Africa | Long term (≥ 4 years) |
| Mega-Events Pipeline (Expo 2030, Neom, Dubai Airshow) Intensifying Critical-Infrastructure Hardening | +1.4% | UAE, Saudi Arabia | Short term (≤ 2 years) |
| New National Cyber Regulations (NCA ECC, UAE NESA, Egypt DP Law) Mandating Threat-Intel Sharing | +1.9% | GCC, North Africa | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Sovereign-cloud and Residency Mandates across GCC Accelerating SOC Investments
Mandates under Saudi Arabia’s Essential Cybersecurity Controls 2024 and the UAE National IoT Security Policy required organizations to process data within national borders, prompting enterprises and public-sector entities to invest in local security operations centers and develop indigenous cybersecurity talent pipelines.[1]Clyde & Co LLP, “Saudi Arabia Essential Cybersecurity Controls 2024,” clydeco.comQatar’s National Cybersecurity Strategy 2024-2030 further strengthened this regional shift, with the country targeting a USD 11 billion market value by 2027 and prioritizing managed security services to address persistent talent shortages and operational capacity gaps. These regulatory and strategic initiatives increased demand for localized monitoring, incident response, threat intelligence, and compliance-driven cybersecurity capabilities across the GCC. As a result, local SOC build-outs and the adoption of managed security services are expected to remain key contributors to long-term growth in the cybersecurity market in the Middle East and Africa.
Rapid Digital-Banking License Issuance in KSA and UAE Boosting Compliance-led Security Spend
Saudi Arabia’s cybersecurity regulatory sandbox programs and the UAE’s Personal Data Protection Law required digital banks to establish robust risk management frameworks before launch. In 2025, the rapid issuance of digital banking licenses in KSA and the UAE increased the need for banks and fintech-led entrants to meet strict compliance, data protection, and operational resilience requirements. Multiple regulatory checkpoints, from central banks to commerce ministries, required continuous audits, documentation, and validation of cybersecurity controls. These requirements drove demand for consulting services, third-party risk assessments, penetration testing, governance and compliance tools, and security automation platforms. As license applications increased, compliance-driven cybersecurity investments continued to support growth in the cybersecurity market in the Middle East and Africa.
Escalating OT Cyber-attacks on Oil and Gas Assets Driving ICS/SCADA Security Uptake
Energy operators across the Middle East and Africa are experiencing increasingly sophisticated cyber campaigns targeting operational technology environments, particularly refinery control networks, where successful intrusions can disrupt production, compromise safety, and affect asset reliability. Saudi Aramco’s OT security academy, developed with Dragos, highlights the growing focus on strengthening specialized industrial control system protection and building regional capabilities to address sector-specific cybersecurity risks. The region’s highly interconnected energy corridors also increase the need for air-gapped network architectures, anomaly detection sensors, and 24/7 OT-focused security operations centers (SOCs), thereby strengthening demand for advanced cybersecurity solutions across the Middle East and Africa cybersecurity market.
Explosive Mobile-Money Adoption in Sub-Saharan Africa Requiring Endpoint and Fraud Protection
Mobile money transactions in Sub-Saharan Africa reached record levels, but the rapid expansion of digital financial services also increased exposure to cybercrime, resulting in USD 140 million in losses. SIM-swapping and social engineering tactics remained key contributors to these losses, highlighting the need for stronger identity verification, transaction monitoring, and endpoint security controls. In response, central banks in Nigeria and Kenya introduced mandatory cybersecurity frameworks that require financial service providers to implement multi-factor authentication, real-time fraud analytics, and secure agent networks. As mobile money platforms continue to support financial inclusion across underserved populations, endpoint and fraud management vendors are gaining share in the Middle East and Africa cybersecurity market.
Restraints Impact Analysis*
| Restraint | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Acute Shortage of Cybersecurity Talent Inflating Service Costs | -1.8% | GCC and Africa | Long term (≥ 4 years) |
| Fragmented Data-Protection Laws across African Nations Raising Compliance Complexity | -1.2% | Sub-Saharan Africa | Medium term (2-4 years) |
| Budget Constraints among African SMEs Prioritising Basic Digitisation over Security | -1.4% | Sub-Saharan Africa | Medium term (2-4 years) |
| Import Dependence on Security Appliances Exposed to Geopolitical Supply-Chain Disruptions | -0.9% | Middle East, North Africa | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Acute Shortage of Cybersecurity Talent Inflating Service Costs
Qatar records 434.09 cybersecurity roles per 100,000 residents, yet demand continues to significantly exceed supply, highlighting the scale of the cybersecurity talent gap across the Middle East and Africa. This shortage places sustained pressure on organizations as they seek skilled professionals to manage critical functions, including threat monitoring, incident response, vulnerability assessment, compliance management, and security architecture. In many cases, companies must outsource these functions to managed security service providers or specialized consultants, which increases wage bills, service fees, and overall project implementation costs. The cost impact is especially pronounced among mid-tier enterprises, which typically have more limited budgets and less financial flexibility than larger organizations. As a result, these enterprises often face delays in deploying advanced cybersecurity solutions or may scale back implementation plans to control spending. This situation tempers adoption rates across the region, while the persistent scarcity of skilled professionals remains a structural barrier to scaling cybersecurity capabilities. Despite strong momentum in digital transformation initiatives, the acute shortage of cybersecurity talent is expected to constrain overall market growth.
Fragmented Data-Protection Laws across African Nations Raising Compliance Complexity
Cameroon, Nigeria, and Egypt follow distinct privacy and data protection statutes, requiring multinational service providers to maintain separate compliance frameworks for each jurisdiction. Differences in breach notification timelines, reporting obligations, enforcement practices, and penalty structures increase audit workloads and make regulatory planning more complex. These variations also extend project lead times, as companies must align internal controls, documentation, vendor management practices, and incident response processes with country-specific requirements. Many organizations are adopting a highest-bar approach by applying the strictest compliance controls across their African operations to reduce regulatory risk. However, this approach increases implementation costs, adds operational complexity, and can delay market entry or expansion in the Middle East and Africa cybersecurity market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Offering: Solutions Outpace Services Yet Momentum Shifts
Solutions captured 69.28% of revenue in 2025 as organizations procured endpoint, network, and cloud-security suites in bulk. This dominance shows the purchasing power of large enterprises that still favor on-premise appliances for critical environments. Continued innovation in AI-driven threat detection reinforces solution spend, with vendors like SentinelOne adding security-posture management to defend shadow AI assets.[2]SentinelOne, “AI Security Posture Management Launch,” sentinelone.com The Middle East and Africa cybersecurity market nevertheless shows a rising appetite for managed services, evident in a 14.68% CAGR outlook fueled by acute talent shortages and compliance burdens.
Professional services grow as integrators tailor complex hybrid architectures across sovereign-cloud environments. SMEs in particular gravitate toward SOC-as-a-Service offerings such as Liquid C2, which bundles monitoring, incident response, and regulatory reporting for a predictable fee structure. The shift reallocates share within the Middle East and Africa cybersecurity industry while preserving solution sales for large renovation projects.


By Deployment Mode: Cloud Traction Gains on On-Premise Lead
In the Middle East and Africa cybersecurity market, cloud deployments dominated, accounting for 57.61% of the market share in 2025. This leadership reflected the accelerated adoption of cloud computing across key industries, including BFSI, government, and energy, where scalability, operational resilience, regulatory compliance, and secure digital service delivery remained critical priorities. Enterprises increasingly migrated workloads, applications, and data environments to the cloud to support national digital transformation strategies and comply with regional data protection mandates. The growing need for cloud workload protection, identity governance, secure access management, and zero-trust frameworks further reinforced the central role of cloud deployments in protecting hybrid and multi-cloud ecosystems across the region.
Cloud-delivered security is projected to register a CAGR of 15.43% through 2031, making it the fastest-growing deployment mode in the MEA market. Investments in smart city projects, 5G private networks, and digitalization initiatives across the oil and gas and telecom sectors are driving this growth. Organizations are prioritizing cloud-native security tools to improve threat visibility, automate incident response, and strengthen compliance across distributed IT environments. SMEs are also accelerating cloud adoption and relying on managed security services to address cybersecurity skill shortages, reduce operational complexity, and comply with evolving regulations. As hyperscalers and regional providers integrate AI-enabled detection, automation, and advanced security controls into cloud platforms, cloud security is expected to remain a cornerstone of MEA’s cybersecurity landscape, supporting resilience, business continuity, and innovation across diverse industries.
By End-User Industry: BFSI Retains Lead, Healthcare Surges
Banking, Financial Services, and Insurance (BFSI) institutions represented 31.25% of expenditure in 2025, supported by strict prudential oversight, heightened regulatory scrutiny, and the continued rise in payment fraud incidents. New digital banking licensing rounds in Saudi Arabia and the UAE required ISO 27001-aligned controls, prompting institutions to consolidate security budgets across identity management, fraud prevention, and data loss prevention modules. Meanwhile, healthcare and life sciences spending increased at a 15.02% CAGR, as the growing deployment of connected medical devices expanded the attack surface and increased the need for stronger cybersecurity controls. Research from academic consortia documented malware and ransomware risks across hospital IoT fleets, underscoring the need to secure clinical environments, connected infrastructure, and sensitive patient data.
Government, energy, and manufacturing sectors sustained demand for OT-centric defenses as organizations focused on protecting critical infrastructure, industrial control systems, and operational continuity. Retail and e-commerce companies prioritized payment gateway security as online transactions proliferated and digital payment adoption increased. Telecom carriers invested in back-end hardening and managed security resale programs to strengthen network resilience and expand security-led service offerings. These diversified demand drivers reinforced resilience in the Middle East and Africa cybersecurity market.

By Organization Size: SME Adoption Narrows Gap
Large enterprises accounted for 67.45% of spending in 2025, while SMEs registered the fastest growth trajectory, with a CAGR of 14.36%. Cyberattacks targeted South African small businesses in 43% of incidents, with average losses reaching USD 254,445 per breach. This exposure encouraged SMEs to prioritize cost-effective and scalable cybersecurity solutions. Managed service catalogs, open-source SIEM, and subscription-based endpoint suites reduced entry barriers and enabled SMEs to meet regulatory benchmarks without expanding internal headcount.
Budget allocations also increased. Companies planned annual security-budget uplifts of 9% over the next two years, indicating that the Middle East and Africa cybersecurity market continued to expand beyond established enterprise customers. This shift reflected broader demand from smaller organizations seeking flexible, affordable, and compliance-ready security solutions. Scalable licensing and consumption-based pricing remained critical to unlocking latent SME demand.
Geography Analysis
Saudi Arabia is expected to retain the largest share of the Middle East and Africa cybersecurity market, accounting for 24.81% in 2025. Vision 2030 initiatives underpin this leadership by funding mega-projects such as the NEOM DataVolt AI factory and other large-scale digital transformation programs.[3]NEOM, “DataVolt AI Factory Agreement,” neom.com These projects are expanding domestic data-processing capacity and increasing security requirements, driving demand for advanced solutions in cloud security, identity governance, and zero-trust frameworks. The country’s robust regulatory environment and government-backed investments position Saudi Arabia as the region’s central hub for cybersecurity innovation and adoption.
Nigeria is forecast to be the fastest-growing market, expanding at a CAGR of 16.42% through 2031. The Central Bank’s risk-based guidelines are driving growth by requiring financial institutions to strengthen their cybersecurity postures. Rising digital adoption across the telecom and fintech sectors further supports market expansion. The country’s growing mobile-money ecosystem and increasing exposure to cyberattacks are accelerating investments in managed security services and AI-driven detection platforms. Nigeria’s strong growth trajectory positions it as a key market for vendors seeking opportunities in Africa’s digital economy.
Beyond these two key markets, other geographies in the MEA region are also influencing the market’s trajectory. The UAE continues to invest significantly in sovereign cloud adoption and workforce development, targeting AED 18 billion (USD 4.90 billion) in cybersecurity market value across the MENA region. South Africa leads commercial adoption but continues to face significant whitespace, as most businesses lack adequate protocols. Countries such as Kenya, Egypt, and Ghana are strengthening capacity-building efforts following high-profile cyber incidents, while smaller Gulf states, such as Qatar and Bahrain, are aligning with regional cybersecurity strategies. This geographic diversity reflects a dual market dynamic: mature Middle Eastern economies are driving large-scale projects, while African nations offer substantial untapped opportunities for future growth.
Competitive Landscape
The Middle East and Africa cybersecurity market remains moderately fragmented, with global incumbents such as Cisco Systems Inc., Palo Alto Networks Inc., and IBM Corporation competing alongside regional specialists such as Help AG and StarLink. Vendor consolidation continues to shape the competitive landscape, as larger platform providers acquire point-solution startups to expand portfolio breadth, strengthen integrated security capabilities, and improve customer retention. G42’s reported 2025 acquisition of CPX is expected to combine AI-driven analytics with managed-service scale, demonstrating how vertical integration can help vendors strengthen their competitive positioning and address evolving enterprise security requirements.
Local presence remains a key differentiator for cybersecurity vendors operating across the region. LogRhythm | Exabeam inaugurated its Riyadh headquarters to better align its offerings with Saudi Vision 2030 and support the country’s expanding digital transformation initiatives.[4]Country’s Digital Transformation Initiatives, “National Transformation Program”, www.vision2030.gov.sa Similarly, PureSquare opened two Gulf offices as part of its strategy to target tenfold regional revenue growth. Technology differentiation continues to center on AI, machine learning, and zero-trust frameworks, as enterprises seek more proactive, scalable, and resilient security architectures. For instance, A10 Networks released AI application-security guidelines that align with the priorities of digital-first enterprises focused on securing applications, data, and cloud-driven operations.
White-space opportunities remain concentrated in healthcare, SME enablement, and supply-chain security appliances, where fragmented and legacy solutions are still common. These areas offer significant growth potential for vendors that can deliver cost-effective, compliant, and locally relevant cybersecurity solutions. Emerging disruptors, such as Saudi Arabia’s Cipher and Africa-focused Defendis, are securing funding to scale threat-detection platforms tailored to local attack vectors and regional operating environments. The competitive frontier increasingly favors vendors that combine regulatory fluency, localized support, and talent-development programs with advanced threat analytics, positioning both global leaders and regional innovators to capture growth across the Middle East and Africa cybersecurity market.
MEA Cybersecurity Industry Leaders
Cisco Systems Inc.
Dell Technologies
Kaspersky Lab
IBM Corporation
Check Point Software Technologies Ltd
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- April 2026: IBM announced new cybersecurity measures to help organizations address emerging cyber threats as attackers begin weaponizing frontier AI models. The company noted that attackers are already using these models to accelerate each stage of the attack lifecycle. These models significantly reduce the time, cost, and expertise required to execute sophisticated attacks, increasing the need for organizations to strengthen cyber resilience and prepare for potential business disruption.
- March 2026: Cisco Security acquired two AI security startups to strengthen its predictive analytics and compliance automation capabilities. The acquisitions reinforced Cisco Security’s enterprise portfolio and supported its strategy to deliver more advanced, AI-enabled security solutions for large organizations.
- March 2026: Palo Alto Networks expanded Prisma Cloud with AI-powered defenses against agentic threats and enhanced Cortex XSIAM for SOC automation. The expansion focuses on securing AI workloads across hybrid cloud environments and helping security teams improve threat detection, response, and operational efficiency.
- February 2026: CrowdStrike released autonomous detection modules designed to counter agentic AI threats. The launch enhanced the Falcon platform with real-time adaptive defense capabilities, enabling enterprises to identify, analyze, and respond to emerging threats more efficiently.


MEA Cybersecurity Market Report Scope
The MEA cybersecurity market comprises technologies, solutions, and services across the Middle East and Africa that help organizations protect networks, data, and critical infrastructure. Rising cyber threats, rapid digital transformation, and compliance requirements under regional regulations, including Saudi Arabia’s NCA framework, the UAE National Cybersecurity Strategy, and Africa’s emerging data protection laws, are driving market growth. Enterprises are increasingly deploying cloud security, identity governance, and zero-trust frameworks to secure their digital ecosystems. Continued investments in critical infrastructure protection, smart city initiatives, and 5G private networks are further strengthening demand, positioning MEA as one of the fastest-growing regions for cybersecurity innovation and resilience.
The Middle East and Africa Cybersecurity Market is Segmented by Offering (Solutions [Application Security, Cloud Security, Data Security, Identity Access Management, Infrastructure Protection, Integrated Risk Management, Network Security, and End-point Security], and Services [Professional Services, and Managed Services]), Deployment (On-premise, and cloud), End-User Industry (Banking, Financial Services, and Insurance (BFSI), Healthcare and Life Sciences, IT and Telecommunication, Government and Public Administration, Retail and E-Commerce, Energy and Utilities, Industrial Manufacturing, and Other End-User Industries), Organization Size (Small and Medium Enterprises (SMEs), and Large Enterprises), and Country (Middle East [Saudi Arabia, United Arab Emirates, Qatar, Bahrain, Kuwait, and Rest of Middle East], Africa [South Africa, Egypt, Nigeria, and Rest of Africa]). The market sizes and forecasts are provided in terms of value in (USD).
By Offering
| Solutions | Application Security |
| Cloud Security | |
| Data Security | |
| Identity and Access Management | |
| Infrastructure Protection | |
| Integrated Risk Management | |
| Network Security Equipment | |
| Endpoint Security | |
| Services | Professional Services |
| Managed Services |
By Deployment Mode
| On-Premise |
| Cloud |
By End-User Vertical
| Banking, Financial Services, and Insurance (BFSI) |
| Healthcare and Life Sciences |
| IT and Telecommunication |
| Government and Public Administration |
| Energy and Utilities |
| Retail and E-commerce |
| Industrial Manufacturing |
| Other End-User Industries |
By End-User Enterprise Size
| Small and Medium Enterprises (SMEs) |
| Large Enterprises |
By Geography
| Middle East | Saudi Arabia |
| United Arab Emirates | |
| Qatar | |
| Bahrain | |
| Kuwait | |
| Oman | |
| Turkey | |
| Africa | South Africa |
| Egypt | |
| Nigeria | |
| Kenya | |
| Morocco | |
| Rest of Africa |
| By Offering | Solutions | Application Security |
| Cloud Security | ||
| Data Security | ||
| Identity and Access Management | ||
| Infrastructure Protection | ||
| Integrated Risk Management | ||
| Network Security Equipment | ||
| Endpoint Security | ||
| Services | Professional Services | |
| Managed Services | ||
| By Deployment Mode | On-Premise | |
| Cloud | ||
| By End-User Vertical | Banking, Financial Services, and Insurance (BFSI) | |
| Healthcare and Life Sciences | ||
| IT and Telecommunication | ||
| Government and Public Administration | ||
| Energy and Utilities | ||
| Retail and E-commerce | ||
| Industrial Manufacturing | ||
| Other End-User Industries | ||
| By End-User Enterprise Size | Small and Medium Enterprises (SMEs) | |
| Large Enterprises | ||
| By Geography | Middle East | Saudi Arabia |
| United Arab Emirates | ||
| Qatar | ||
| Bahrain | ||
| Kuwait | ||
| Oman | ||
| Turkey | ||
| Africa | South Africa | |
| Egypt | ||
| Nigeria | ||
| Kenya | ||
| Morocco | ||
| Rest of Africa | ||


Key Questions Answered in the Report
What is the current valuation of the Middle East and Africa cybersecurity market?
The MEA cybersecurity market size is expected to increase from USD 3.27 billion in 2025 to USD 3.67 billion in 2026 and reach USD 6.54 billion by 2031, growing at a CAGR of 12.23% over 2026-2031.
Which segment is growing fastest within the market?
Services post the quickest pace, projected at a 14.68% CAGR through 2031.
Why is healthcare and life sciences cybersecurity expanding rapidly?
Accelerated digital-health programs and rising IoT medical device deployments expose hospitals to ransomware and malware, supporting a 15.02% CAGR outlook.
How are sovereign-cloud mandates influencing security spending?
Data-residency and Saudization rules compel organizations to build local SOCs and adopt managed services, lifting solution and service demand.
What challenges do African SMEs face in cybersecurity adoption?
Budget constraints and acute talent shortages hinder internal capability building, pushing SMEs toward subscription-based managed services for protection.
Page last updated on:



