
Green Buildings Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 461.23 Billion |
| Market Size (2031) | USD 763.12 Billion |
| Growth Rate (2026 - 2031) | 10.59 % |
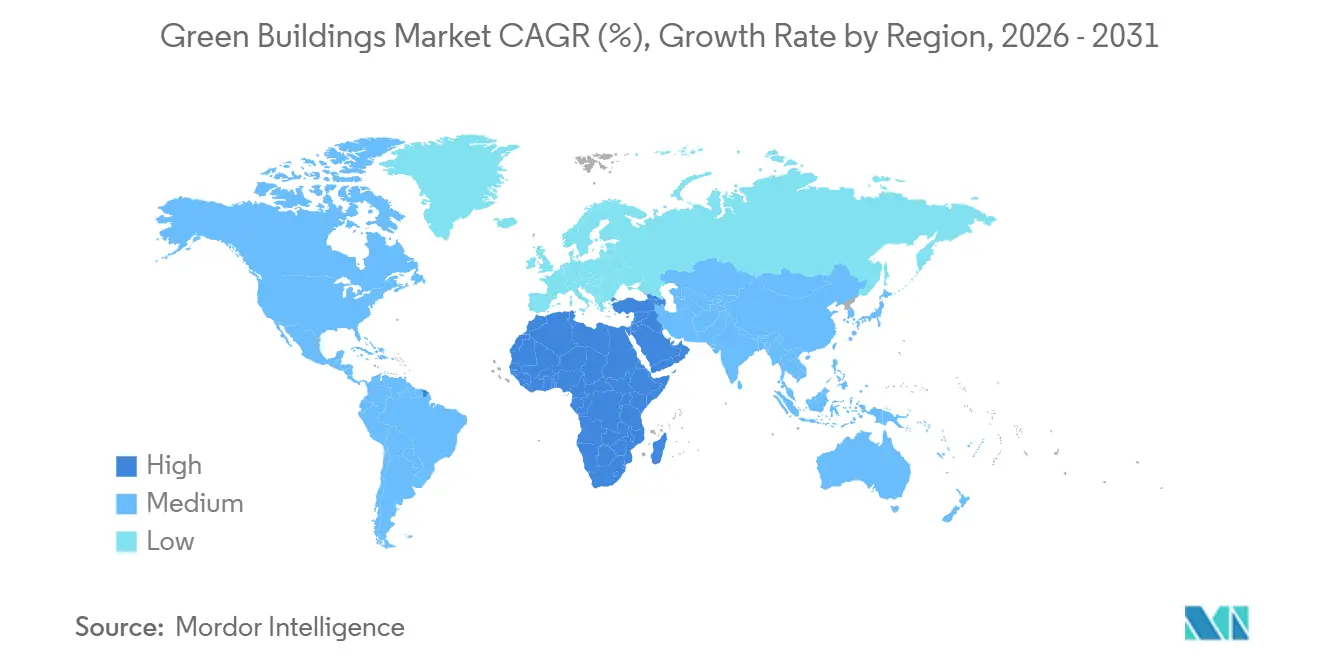
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia Pacific |
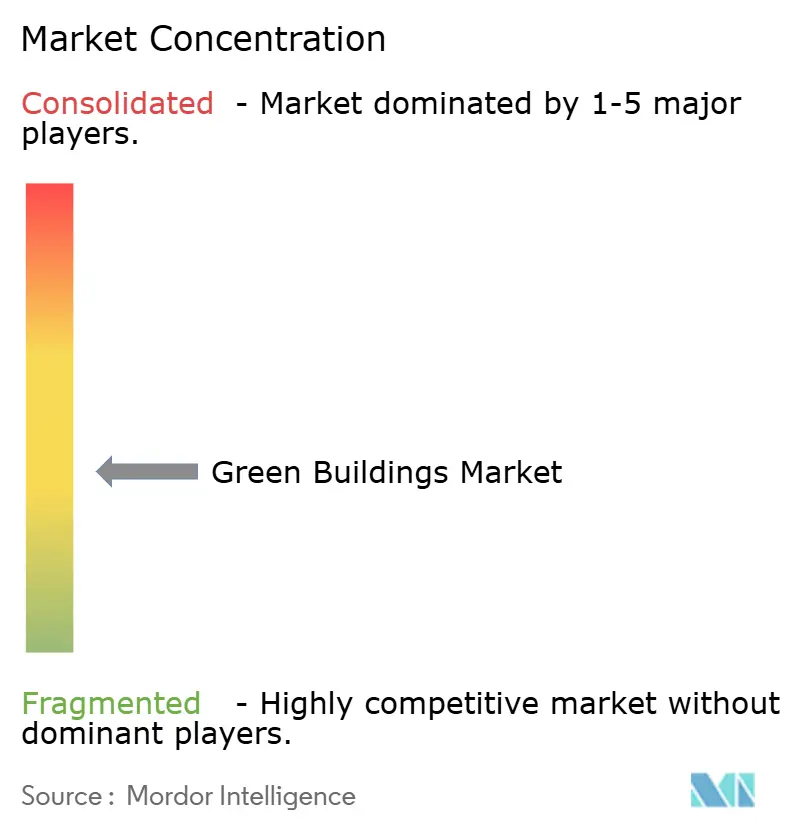
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Green Buildings Market Analysis by 黑料不打烊
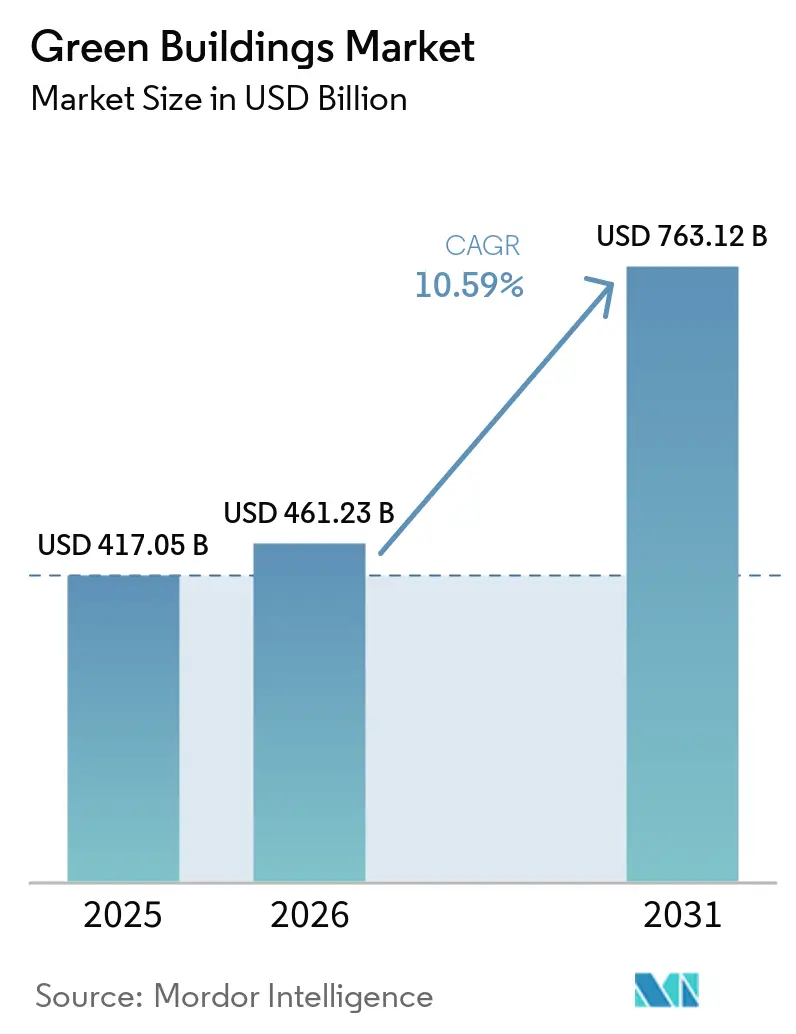
The Green Buildings Market size is projected to be USD 417.05 billion in 2025, USD 461.23 billion in 2026, and reach USD 763.12 billion by 2031, growing at a CAGR of 10.59% from 2026 to 2031.
Mandatory carbon-accounting protocols, energy-performance certificates, and sustainability-linked debt instruments have turned efficiency from a nice-to-have into a financing prerequisite, shrinking the payback window on high-performance envelopes and smart building systems. Rent premiums for certified assets, coupled with lower borrowing costs on green bonds, are steering institutional capital toward projects whose operational data confirm energy reductions. At the same time, retrofit mandates in mature economies and large-scale greenfield projects in emerging regions expand the addressable green building market by diversifying demand across construction stages. Material breakthroughs—from low-carbon concrete to bio-based polyurethane foams—reinforce this momentum by giving owners verifiable pathways to embodied-carbon cuts.
Key Report Takeaways
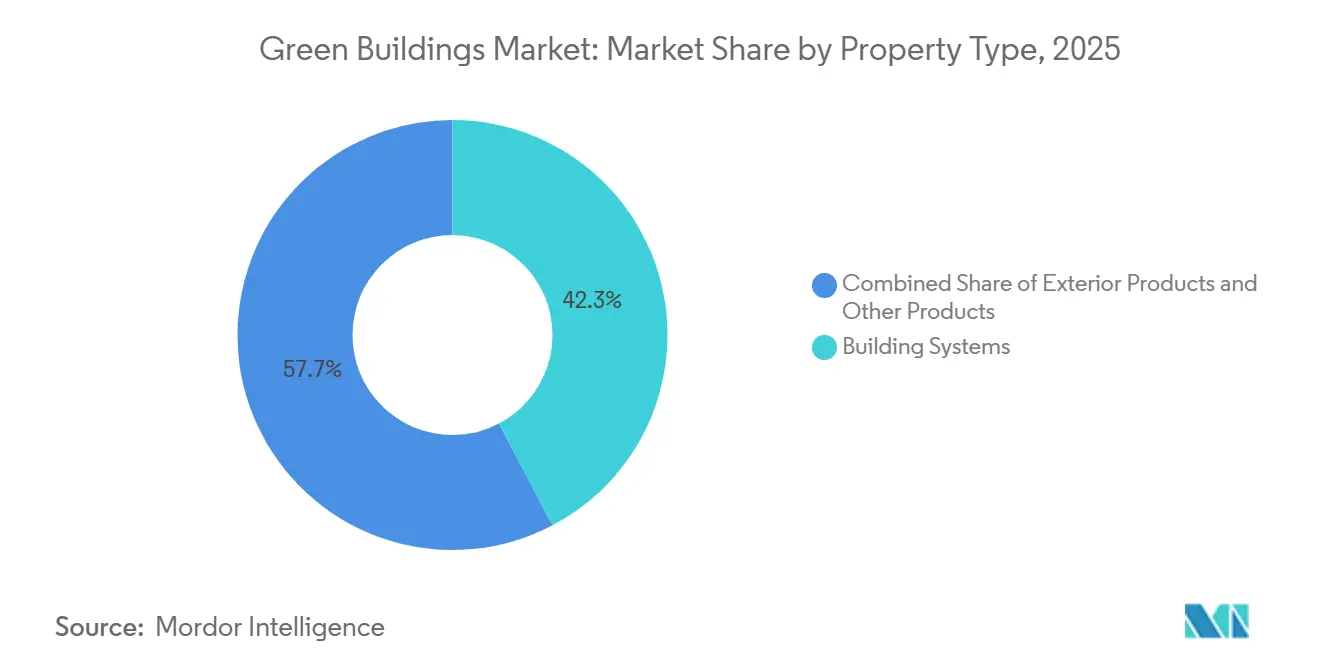
- By product type, building systems held 42.3% of the green building market share in 2025, while exterior products registered the fastest growth at an 11.21% CAGR through 2031.
- By end user, commercial projects dominated with 53.7% revenue in 2025; logistics facilities are projected to expand at an 11.76% CAGR through 2031.
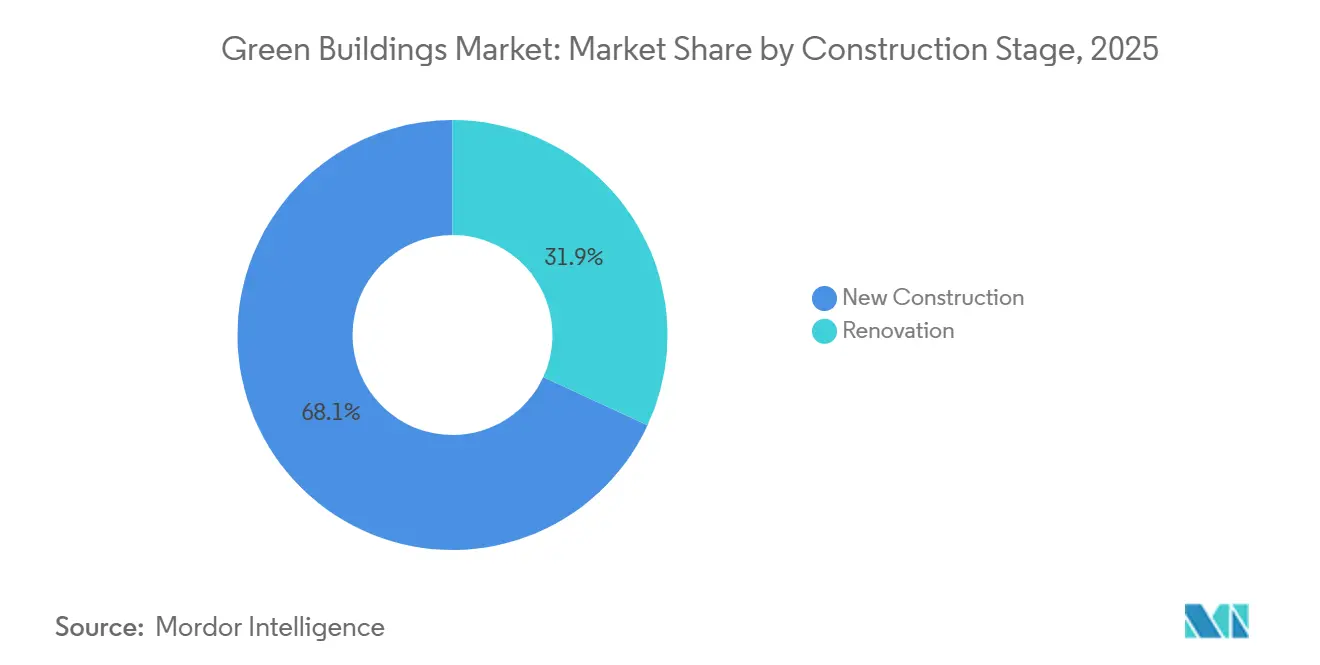
- By construction stage, new builds represented 68.1% of 2025 activity, yet renovation is advancing at an 11.55% CAGR, the fastest among all stages.
- By geography, Asia-Pacific commanded 37.6% of the 2025 value, while the Middle East & Africa region is set to post a 12.23% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Green Buildings Market*
| Drivers | (~) % IMPACT ON CAGR FORECAST | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent green-construction regulations & certification mandates | +2.8% | EU, California, tier-one APAC cities | Medium term (2–4 years) |
| Rising energy prices are boosting demand for high-performance envelopes | +2.1% | Europe, North America, and energy-import-dependent APAC | Short term (≤2 years) |
| Corporate ESG targets opening green-bond & sustainability-linked financing | +2.5% | North America, Europe, APAC financial hubs | Medium term (2–4 years) |
| Rapid urbanization programs with green-building codes in APAC | +1.9% | China, India, Southeast Asia | Long term (≥4 years) |
| Mandatory embodied-carbon disclosure in public procurement | +1.2% | EU, UK, select North America, pilot APAC | Long term (≥4 years) |
| Source: 黑料不打烊 | |||
Stringent Green-Construction Regulations & Certification Mandates
Zero-emission building rules now dictate project underwriting. The EU directive, revised in 2024, compels all new structures delivered after 2030 to achieve zero-operational carbon and forces existing non-residential assets to meet minimum ratings by 2027[1]European Commission, “Energy Performance of Buildings Directive – Revision,” europa.eu . California’s Title 24 adds solar-ready roofs and battery-storage wiring to baseline design, eliminating the ability to defer renewable integration. Certification bodies such as LEED and BREEAM have become gatekeepers to green finance because lenders demand proof of performance before closing. These policies front-load compliance expenses but simultaneously unlock cheaper debt, accelerating uptake across the green building market. Developers unable to meet benchmarks face stranded-asset risk, ensuring regulations continue to steer demand.
Rising Energy Prices Boosting Demand for High-Performance Envelopes
Persistent fuel-price volatility since 2023 has moved energy efficiency to the top of tenant wish lists. Commercial occupiers are now willing to pay higher rents for buildings with triple glazing, thermally broken fa?ades, and reflective roofs that cut HVAC loads by up to 40%[2]International Energy Agency, “Energy Efficiency 2025,” iea.org . Warm-climate data centers and logistics hubs join cold-weather offices in specifying airtight envelopes because cooling costs often eclipse heating bills. With payback periods narrowing to seven years or less, owners can justify premium claddings and window packages even in secondary markets. High-performing envelopes, therefore, anchor growth in retrofit spending across the wider green building market.
Corporate ESG Targets Opening Green-Bond & Sustainability-Linked Financing
Debt markets now price carbon. Real-estate green-bond issuance topped USD 150 billion in 2024, while sustainability-linked loans rose 40% in 2025 as interest rates adjusted to verified energy gains. Smaller developers gain funding access by pledging superior performance, broadening participation in the green building market. Insurers reinforce the trend by lowering premiums for assets with energy intensities below 100 kWh/m?. The feedback loop of cheaper capital for better buildings underpins sustained demand for high-efficiency systems.
Rapid Urbanization Programs with Green-Building Codes in APAC
Asia-Pacific adds close to 1 billion m? of urban floor area each year, virtually all under mandatory green-building codes. India’s Smart Cities Mission grants floor-area bonuses for IGBC-rated projects, incentivizing private builders to exceed minimums. Vietnam and Indonesia mirror this approach in special economic zones to meet multinational tenant standards. Because green metrics are baked into master plans, compliance costs stay low, powering steady volume for system integrators across the region’s green building market.
Restraints Impact Analysis of Green Buildings Market*
| Restraints | (~) % IMPACT ON CAGR FORECAST | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High upfront capital & certification costs | -1.4% | Global, strongest in cost-sensitive residential markets | Short term (≤2 years) |
| Fragmented supply chains for low-carbon materials | -0.9% | Emerging APAC, MEA, South America | Medium term (2–4 years) |
| Skilled-labor shortage in advanced sustainable methods | -1.1% | North America, Europe, advanced APAC | Medium term (2–4 years) |
| Source: 黑料不打烊 | |||
High Upfront Capital & Certification Costs
LEED Gold still adds 8-12% to construction budgets, with consultant fees for modeling and verification topping USD 50,000 on mid-size projects. Affordable-housing developers struggle to monetize that premium, slowing adoption in lower-income segments of the green building market. Some utilities co-finance efficiency upgrades, but programs remain patchy, leaving a financing gap that constrains near-term growth.
Fragmented Supply Chains for Low-Carbon Materials
Cross-laminated timber mills and low-carbon cement plants are clustered in Europe and North America. APAC and Middle Eastern builders must import green building materials, paying freight premiums that erode project returns. Delays of six months or more jeopardize schedules tied to regulatory deadlines. Regional manufacturing ventures and harmonized material standards will ease the bottleneck, yet progress is incremental.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Green Buildings Market Segment Analysis
By Product Type:
Building Systems Dominate Through Verified SavingsBuilding systems accounted for 42.3% of 2025 revenue, making them the largest slice of the green building market. HVAC retrofits, variable-refrigerant-flow heat pumps, and advanced chillers anchor this category by reducing fossil-fuel dependence and complying with new refrigerant rules. Smart building-management platforms integrate HVAC, lighting, and access controls into a unified dashboard that owners use to prove efficiency gains to lenders. With envelope upgrades nearing physical limits, performance data from systems provides the clearest ROI pathway to sustain double-digit growth.
Exterior products-insulated panels, high-performance glazing, reflective roofs-remain essential but grow more modestly as code-driven adoption saturates. Interior items such as low-VOC paint and recycled flooring ride the wellness-certification tailwind, especially in premium offices. Emerging lines-phase-change drywall, electrochromic glass offer upside but await cost reductions. Crucially, suppliers that ensure plug-and-play interoperability with IoT hubs can price at a premium, while legacy stand-alone products risk commoditization. As a result, exterior products are forecast to outpace other categories at an 11.21% CAGR through 2031, narrowing the gap with building systems in the green building market.


By End User:
Commercial Properties Lead Under Tenant PressureCommercial assets generated 53.7% of global outlays in 2025, reflecting tenant demand for verifiable efficiency and associated carbon reporting. Office landlords face a flight-to-quality as occupiers chase lower Scope 3 emissions. Retailers retrofit stores to trim utility costs amidst margin pressure, while logistics operators invest in temperature-controlled warehousing with rooftop solar to meet cold-chain standards. Institutional owners—universities, hospitals—tap green bonds with 20-year tenors aligned to energy-savings paybacks.
Residential uptake is bifurcated. The luxury condos market positions sustainability as a lifestyle badge, but mass-market adoption lags despite policy incentives. City-core multifamily projects must now hit minimum energy scores across Europe and several APAC metros, pushing heat-pump water heaters and gray-water systems into mainstream design. Logistics facilities, the fastest-growing commercial subsegment, are projected to expand at an 11.76% CAGR through 2031 as e-commerce drives warehouse construction linked to net-zero deadlines. Commercial dominance will thus persist, helped by longer hold periods that align with system paybacks in the green building market.
By Construction Stage:
Renovation Accelerates as Deadlines LoomNew construction held 68.1% of 2025 spending owing to emerging-market megaprojects and easier integration of green specs from day one. Yet renovation is the fast mover, set to post an 11.55% CAGR because regulators now require deep retrofits of the poorest-performing stock. EU rules compel upgrades for the worst 15% of buildings by 2027, prompting a surge in insulation, window replacements, and smart controls across mature economies.
Land-constrained cities prefer adaptive-reuse projects that cut embodied carbon by conserving structural shells. Specialized contractors offering turnkey retrofit packages-insulation, airtightness, heat-pump swaps-report backlog growth of over 25% year-over-year. Kingspan’s retrofit-insulation sales in Europe rose 28% in 2025, underscoring this pivot. Although greenfield projects in Asia and the Middle East still dominate volumes, renovation’s share of the green building market will keep rising as existing stock ages, and demolition incurs regulatory penalties.
Geography Analysis
APAC Green Buildings Market
Asia-Pacific accounted for 37.6% of the 2025 green building market revenue, underpinned by China’s dual-carbon policy and India’s quick uptake of green bonds funding urban infrastructure. China surpassed 10 billion m? of certified floor area in 2024, and India’s IGBC listings grew 25% in 2025. Japan and South Korea retrofit 1990-era offices to stringent new codes, while Australia’s state subsidies accelerate rooftop solar-plus-storage in suburban housing. These dynamics ensure Asia-Pacific remains the volume leader, although growth moderates as regulations mature.
MEA Green Buildings Market
The Middle East & Africa region is the fastest climber, expected to record a 12.23% CAGR through 2031 on the back of Saudi Arabia’s USD 500 billion Vision 2030 projects and the UAE’s net-zero-city mandates[3]Public Investment Fund (Saudi Arabia), “Vision 2030 Investment Report,” pif.gov.sa . NEOM’s giga-scale procurement embeds renewable power, district cooling, and recycled-water systems from the outset, creating mega-orders for envelope and system suppliers. The UAE requires 75% of buildings to hold green certification by 2030, spawning a retrofit wave across existing stock. South Africa invests in on-site solar and batteries to escape grid instability, and Lagos pilots codes for public housing, hinting at broader continental adoption.
North America, Europe and LATAM Green Buildings Market
North America and Europe, though mature, remain pivotal. The United States issued USD 45 billion in real-estate green bonds in 2024, funding LEED upgrades in major metros. Canada mandates net-zero federal buildings by 2030, anchoring provincial policy. European renovation accelerates under the Fit-for-55 package, with Germany and France channeling subsidies toward deep-energy retrofits. The UK ties energy-efficiency metrics to building-safety rules, driving fa?ade recladding and new HVAC. Latin America grows selectively; Brazil leads with LEED stock in S?o Paulo, while Mexico adopts green standards to satisfy U.S. nearshoring tenants. Collectively, these regions keep renovation volumes strong, sustaining the global green building market.
黑料不打烊 provides coverage of the green buildings market across other key regional markets, including Asia, Europe, Middle East, and North America, each with their regulatory frameworks and demand patterns.

Regulatory Landscape
Green building compliance is increasingly shaped by mandatory energy performance requirements and disclosure regimes, rather than voluntary adoption alone. In Europe, the revised Energy Performance of Buildings Directive (EPBD) adopted in 2024 tightens minimum performance expectations for existing stock and sets a zero-operational-carbon direction for new buildings delivered after 2030. This is accelerating retrofit programs and increasing documentation needs across design, materials, and operations. Similar policy momentum is visible in high-activity Asian cities, with Shanghai Green Building Regulations taking effect in January 2025 and bringing certification requirements into the mainstream for new builds.
Codes and disclosure also influence procurement and financing. The rollout of IFRS S1 and IFRS S2 sustainability disclosure standards increases pressure on owners and developers to substantiate climate and energy claims with auditable data, which reinforces demand for metering, building management systems, and verified materials documentation. Broader initiatives referenced by bodies such as the Global Alliance for Buildings and Construction (GlobalABC), including commitments to mandatory building energy codes, reinforce convergence around measurable performance and compliance-ready product documentation.
Value Chain Analysis
The green buildings value chain starts with upstream feedstocks and low-carbon inputs (cement, glass, insulation chemistries, metals, timber), progresses through product manufacturing (envelope, interior finishes, and building systems), and then moves into specification and design (architects, engineers, energy modelers, and certification consultants). From there, contracting and installation (general contractors and specialist retrofit firms) feed into operations and performance verification, including commissioning, building management platforms, and ongoing monitoring for lenders and occupiers. To help projects demonstrate energy and carbon outcomes, leading suppliers increasingly bundle materials with digital services and documentation, which aligns with the market shift toward performance-backed financing.
Embodied-carbon transparency is becoming a standard procurement workflow, favoring suppliers that can provide Life Cycle Assessments and Environmental Product Declarations (EPDs) at scale and on schedule. Large manufacturers are also tightening supplier requirements for primary emissions data to manage Scope 3 footprints, while procurement is becoming more structured through curated marketplaces that pre-approve sustainable products (for example, platforms such as ROOT to Market referenced in industry evidence). This is gradually reducing fragmentation for low-carbon materials, but it also increases the importance of traceability, third-party verification, and interoperable data exchange between product suppliers, contractors, and building-operations platforms.
Competitive Landscape
Global insulation and fa?ade giants—Kingspan, Saint-Gobain, Owens Corning—leverage scale and R&D to bundle high-performance materials with digital monitoring, cementing sticky client relationships. Schneider Electric’s EcoStruxure and Johnson Controls’ OpenBlue ecosystems merge hardware with analytics subscriptions that convert one-time sales into service annuities. Competition revolves around proof of energy savings, not just product specs, compelling laggards to partner or risk exclusion from large tenders.
Materials innovation deepens rivalry. Holcim’s low-carbon cement and Interface’s carbon-negative carpet tiles differentiate on embodied carbon, a metric that public procurement now tracks. Start-ups like Sublime Systems chase electrochemical cement technologies that eliminate process emissions, potentially leapfrogging incumbents. Suppliers able to certify cradle-to-gate impacts rapidly win share in projects subject to disclosure rules, underscoring the growing data intensity of the green building market.
Industrialized construction adds another front. Binderholz and RedBuilt expand cross-laminated timber and panelized wall factories to offset skilled-labor shortages and cut site waste. Yet designers worry about aesthetic uniformity, so hybrid solutions—mass-timber cores with bespoke fa?ades—gain favor. Strategic alliances proliferate: Johnson Controls partnered with Microsoft Azure for predictive analytics, and Schneider Electric bought a U.S. software firm for energy-as-a-service offerings. These moves illustrate convergence between construction products and cloud platforms, reshaping competitive dynamics.
Green Buildings Industry Leaders
Kingspan Group PLC
Saint-Gobain SA
BASF SE
Johnson Controls International plc
Owens Corning
- *Disclaimer: Major Players sorted in no particular order
Green Buildings Market Companies Covered in this Report
- Kingspan Group PLC
- Saint-Gobain SA
- BASF SE
- Johnson Controls International plc
- Owens Corning
- Schneider Electric SE
- Holcim Ltd (LafargeHolcim)
- Skanska AB
- CEMEX S.A.B. de C.V.
- Interface Inc.
- Alumasc Group PLC
- Amvik Systems
- Binderholz GmbH
- Bauder Limited
- Kingspan Insulation LLC
- Armstrong World Industries
- RedBuilt LLC
- Homasote Company
- Carrier Global Corporation
- Panasonic Corporation (BIPV)

Market Opportunities and Future Outlook
A key opportunity is the shift from operational-carbon upgrades toward embodied-carbon accountability in materials. This improves the commercial value of verified documentation (EPDs, LCAs) and supports low-embodied-carbon product lines across insulation, coatings, glass, and concrete alternatives. Evidence of this shift shows up in public-sector and institutional procurement frameworks that increasingly require EPD-backed products, pushing manufacturers to expand certified portfolios and upgrade data systems that connect product footprints to project-level reporting. Suppliers that can provide both lower-carbon products and the accompanying compliance pack (third-party verified declarations, chain-of-custody, and compatible digital data formats) gain traction as project teams standardize specifications around auditable claims.
Another area of opportunity is reducing retrofit friction through bundled delivery models. Integrated solutions that combine envelope upgrades with on-site generation and performance monitoring, alongside service-led offerings such as energy management and continuous commissioning, address both capital and operating hurdles. Recent market actions point to this direction, including Kingspan and Zestec Renewable Energy launching a funded solar roofing solution for commercial refurbishment projects in 2026. It targets capital barriers by linking roof renewal to renewable generation. Circularity also supports incremental revenue through recovery and reuse programs (for example, Kingspan RECOVR referenced in industry material), helping contractors and manufacturers monetize end-of-life logistics while meeting waste and carbon objectives.
Recent Industry Developments in Green Buildings Market
- July 2026: BASF SE expanded its portfolio of certified biomass-balanced additives for architectural coatings. The expansion strengthens sustainability credentials and expands green-building material offerings across coatings segment. It supports the adoption of low embodied-carbon materials in modern green buildings.
- July 2026: Kingspan Group PLC powerPanel integrated solar roofing system achieved FM 4478 standard testing. The milestone validates envelope-integrated PV as a constructible, code-compliant option, aiding adoption in retrofit market. It broadens the commercial refurbishment envelope with solar roofing options.
- May 2026: Kingspan Group PLC partnered with Zestec Renewable Energy to launch a funded solar roofing solution for commercial refurbishment projects. The funded solar roofing solution accelerates demand for integrated solar envelopes in commercial refurbishments. The partnership introduces financing-enabled roof upgrades that unlock retrofit projects.


Green Buildings Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the green building market is defined as the revenue linked to designing and delivering buildings that reduce energy and water use and improve indoor conditions through certified or performance-led construction choices.
Scope exclusions: We exclude routine building repairs that do not change energy, water, or material performance, and we also exclude standalone consumer devices that are not part of the building fabric or systems.
Segments Covered in This Report
- By Product Type
- Exterior Products
- Interior Products
- Building Systems
- Others
- By End User
- Residential
- Apartments & Condominiums
- Villas & Landed Houses
- Commercial
- Office
- Retail
- Logistics
- Institutional
- Others (industrial real estate, hospitality real estate, etc.)
- Residential
- By Construction Stage
- New Construction
- Renovation
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle East and Africa
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Rest of Asia-Pacific
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with public construction and building-stock signals so we can anchor the demand pool before we apply any pricing. Sources such as the U.S. Energy Information Administration, the International Energy Agency, the U.S. Census Bureau construction spending series, and Eurostat help us understand energy use, building activity, and renovation cycles.
We then review green certification and policy direction using sources such as the World Green Building Council, USGBC (LEED), and peer reviewed journals covering building energy performance and materials impacts. To cross-check the company side, we use annual reports, investor presentations, and reputable press, and then limited paid subscriptions are used for company financials, patent checks, and shipment-level trade reads where it helps validate assumptions. This list is illustrative only, and many other public and paid sources were also referenced for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work is used to stress-test the desk assumptions, especially what qualifies as a green project in bids and what share of spend is tied to efficiency upgrades. We spoke with a mix of developers, contractors, architects, certification-facing consultants, and building systems stakeholders across major regions so that pricing logic and adoption timing could be checked against project experience.
What we learned from these conversations was applied to refine penetration rates by building type, adjust renovation versus new-build splits, and confirm how certification and code changes are translating into project pipelines.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 38% | CXOs: 12% | APAC: 39% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 36% |
| Smaller Players: 17% | Managers: 53% | Americas: 25% |
Market-Sizing & Forecasting
Sizing is built using a top-down demand reconstruction where construction output and renovation activity are translated into a green-addressable spend pool, and then converted into market value using adoption and pricing assumptions. To keep the model from drifting, we add selective bottom-up checks, including sampling typical project budgets, testing system-level spend shares, and validating implied averages with channel and contractor feedback.
Key inputs that influence the model include new construction versus renovation mix, green certification uptake, energy-code tightening timelines, typical savings-backed retrofit triggers, and average spend shares for building systems like HVAC, lighting, insulation, and controls. Where data is patchy by country, we handle gaps through proxy indicators (construction permits, energy intensity, and policy coverage) and then normalize using expert feedback so outliers do not overstate the total.
For forecasting, scenario analysis is used with a base case tied to expected construction cycles and policy rollouts, followed by sensitivity checks on material and system cost inflation and adoption speed. The final forecast is accepted only after the drivers make sense together, and after the implied per-building values align with what practitioners report in active tenders.
Data Validation & Update Cycle
Outputs are validated through multiple passes where totals are compared against independent signals such as regional construction spending, certification volumes, and reported green project backlogs shared in interviews. If a region shows a sharp jump that cannot be explained by permits, policy changes, or price movement, the assumptions are reopened and the related respondents are contacted again.
Before sign-off, the model and its assumptions are reviewed by another analyst so calculation errors and scope creep are caught early. Reports are refreshed annually, and interim updates are made when material events shift costs, regulations, or construction activity meaningfully. Right before delivery, a final refresh pass is completed so clients receive an up-to-date view.
黑料不打烊's Green Building Market Size Compared With Other Published Estimates
Published market values for green building rarely match because each publisher draws the line around different revenue streams, and then applies different adoption and pricing assumptions across regions and building types. Differences also come from whether the estimate is tied to construction activity and renovation cycles, or if it leans more on broad sustainability spending totals.
The biggest gap drivers typically show up in what gets counted as green, such as whether certification-linked building materials and solar products are bundled into the same number, how renovation work is treated versus new construction, and how fast average project costs are assumed to rise. A smaller but real factor is refresh timing and currency conversion windows, which can shift the base-year value when materials prices move quickly, which is handled differently by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 417.05 B (2025) | |
| Global Research Publisher A | USD 588.37 B (2024) | Uses a broader definition that can bundle green building materials and solar products into the same market total, and it reports an earlier base year that may not reflect later cost normalization across regions. |
| Syndicated Research Portal B | USD 377.00 B (2024) | Appears to apply a tighter 2024 base with limited clarity on what qualifies as green projects versus general construction, and the higher CAGR suggests more aggressive adoption and price escalation assumptions. |
The table shows that most of the spread can be traced back to scope choices and the way adoption and project pricing are carried forward year to year. By keeping the demand pool grounded in construction and renovation activity, and by separating adjacent categories like standalone materials and solar add-ons, the result stays easier to explain and reproduce across regions.


Key Questions Answered in the Report
How large is the green buildings market in 2026?
The green buildings market size is valued at USD 461.23 billion in 2026.
What CAGR is expected for green buildings through 2031?
The green buildings market is projected to grow at a 10.59% CAGR, reaching USD 763.12 billion by 2031.
Which product category contributes the most revenue?
Building systems—including HVAC, smart controls, and lighting—lead with 42.3% of 2025 spending.
Which region is expanding the fastest?
The Middle East & Africa region is forecast to post a 12.23% CAGR through 2031, led by Saudi Arabia and the UAE.
Why are retrofits gaining momentum?
Regulatory deadlines in the EU and major U.S. cities require energy upgrades of existing buildings, driving an 11.55% CAGR in renovation spending.
What hampers the faster adoption of sustainable builds?
Upfront cost premiums, fragmented low-carbon material supply chains, and skilled-labor shortages slow broader market uptake.
Page last updated on:



