
Cold Storage Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 166.16 Billion |
| Market Size (2031) | USD 208.75 Billion |
| Growth Rate (2026 - 2031) | 4.67 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Asia Pacific |
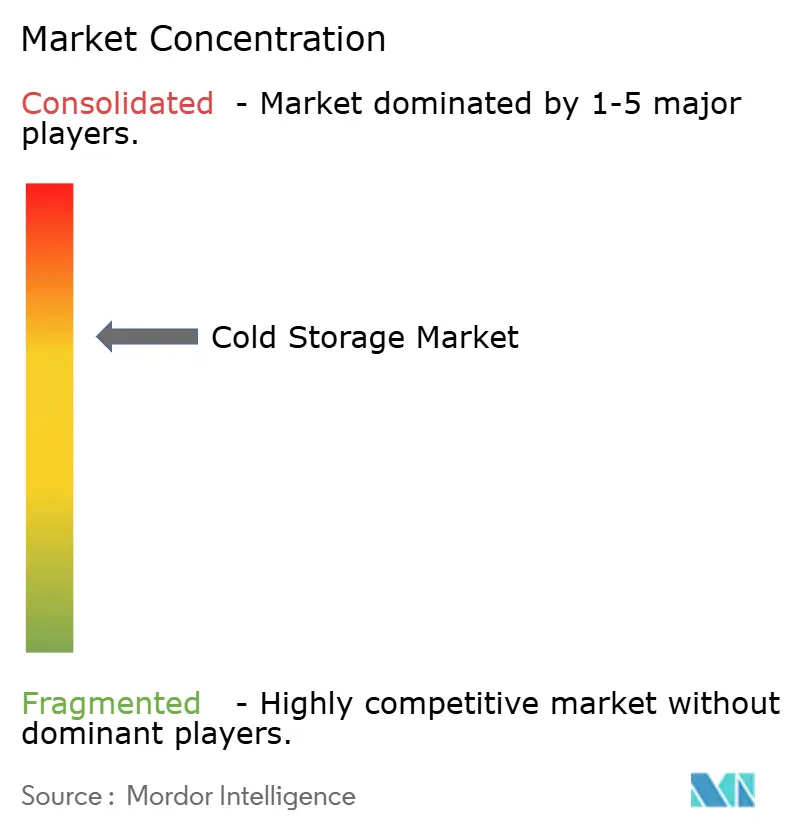
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Cold Storage Market Analysis by 黑料不打烊
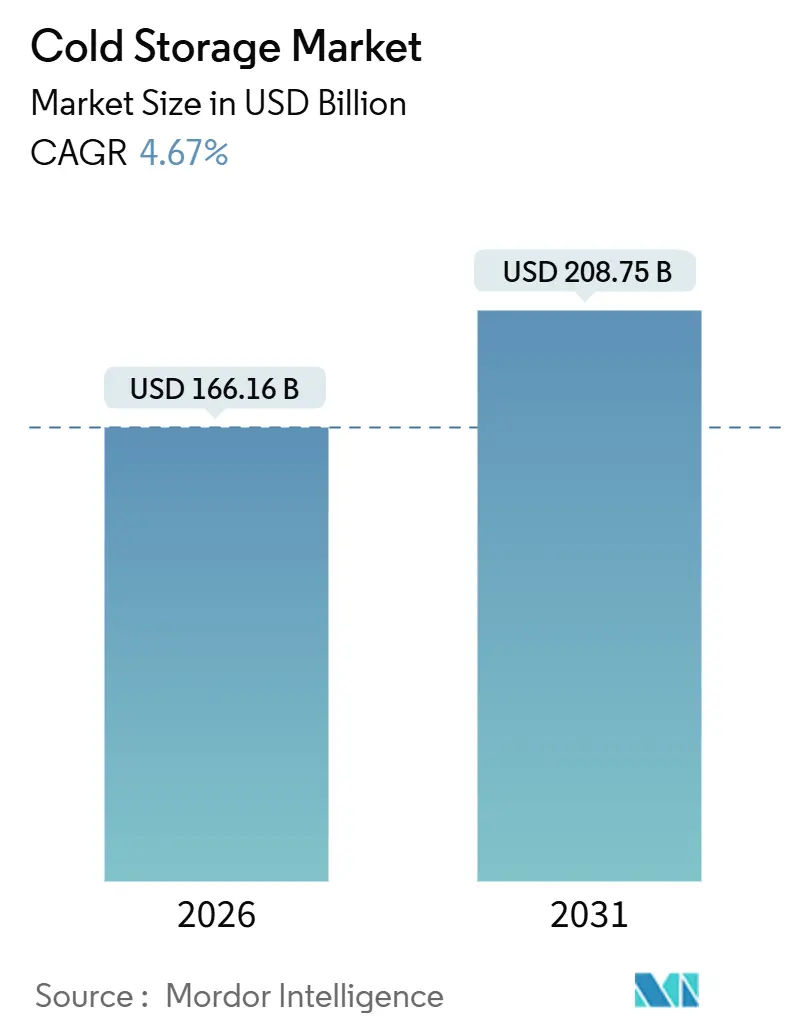
The Cold Storage Market size is estimated at USD 166.16 billion in 2026, and is expected to reach USD 208.75 billion by 2031, at a CAGR of 4.67% during the forecast period (2026-2031).
The global cold storage market expansion is driven less by headline capacity additions and more by structural shifts in consumer behavior, pharmaceutical supply chains, and retail distribution models. Organized retail and e-grocery are demanding urban micro-fulfillment facilities, biologics and cell therapies are pushing temperature thresholds below -20 °C, and automation is becoming a prerequisite for cost control where skilled labor is scarce. Operators able to combine scale, technology, and regulatory expertise are capturing higher-margin niches, while smaller facilities risk obsolescence as energy costs escalate and compliance rules tighten.
Key Report Takeaways
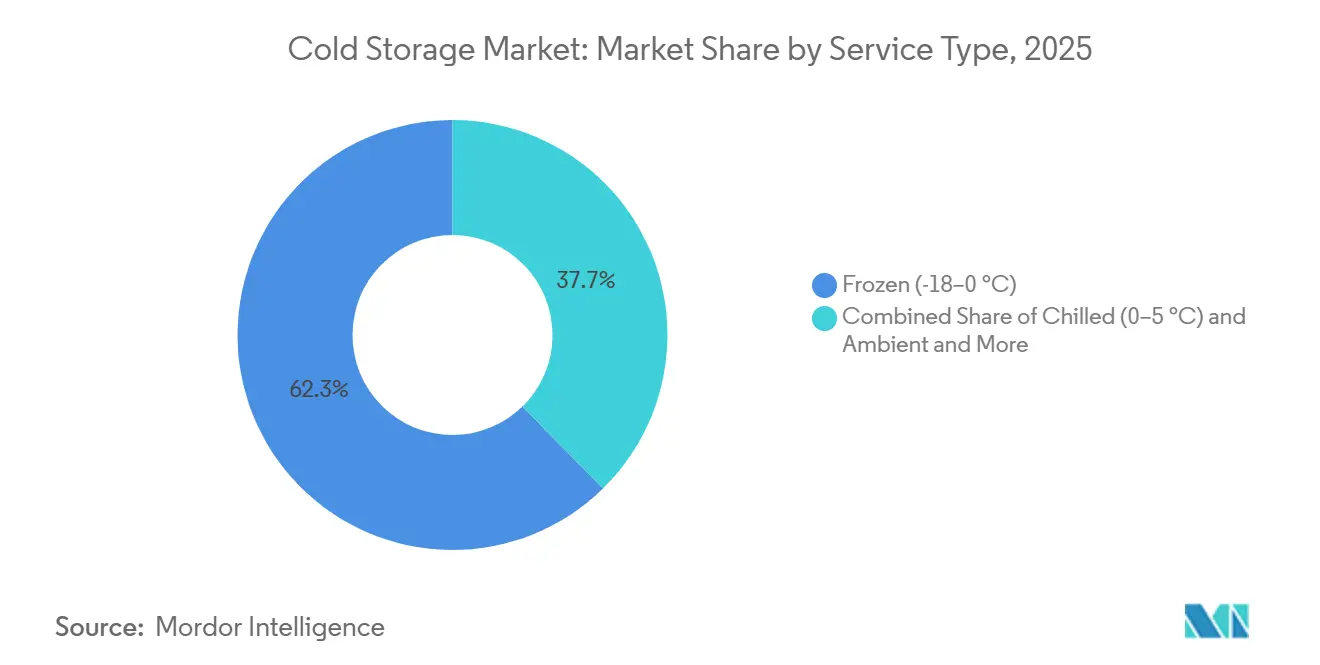
- By temperature type, frozen storage held 62.34% of the cold storage market share in 2025, while deep-frozen and ultra-low facilities are projected to expand at a 13.01% CAGR through 2031.
- By application, fish and seafood led with 17.35% revenue share in 2025; pharmaceuticals and biologics are forecast to advance at an 11.93% CAGR to 2031.
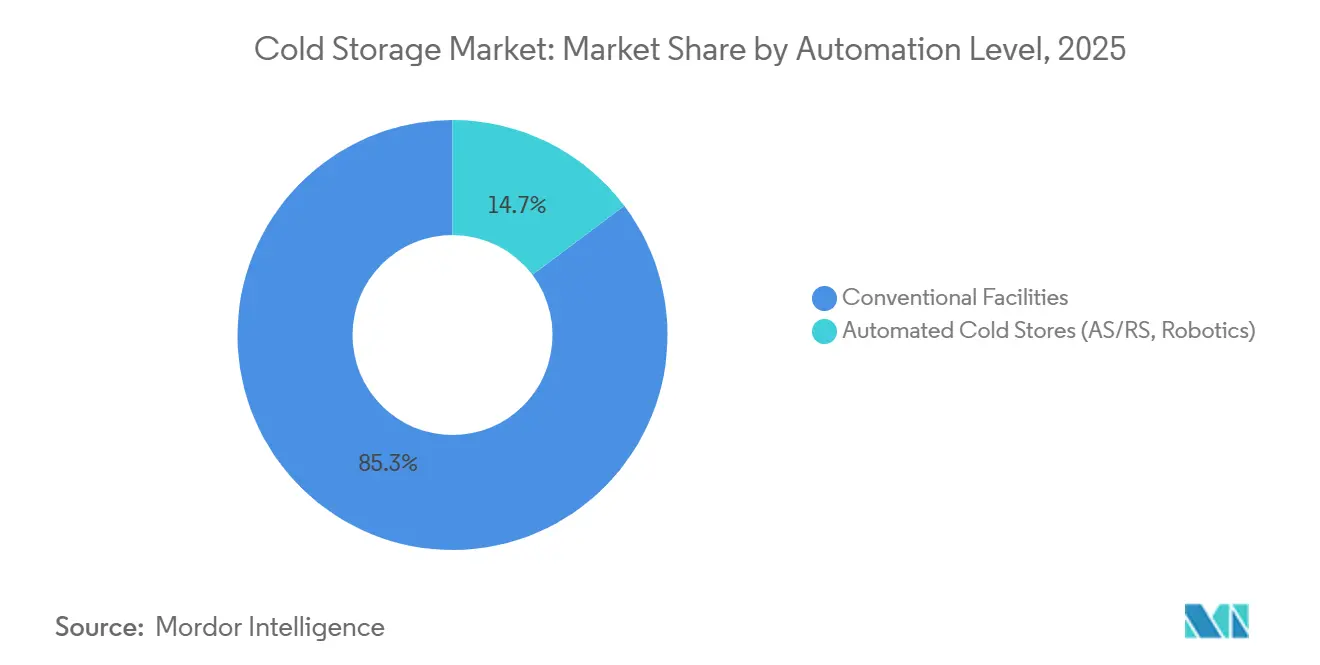
- By automation level, conventional facilities held 85.27% of the global cold storage market size in 2025, whereas automated cold stores are expected to grow at a 16.72% CAGR through 2031.
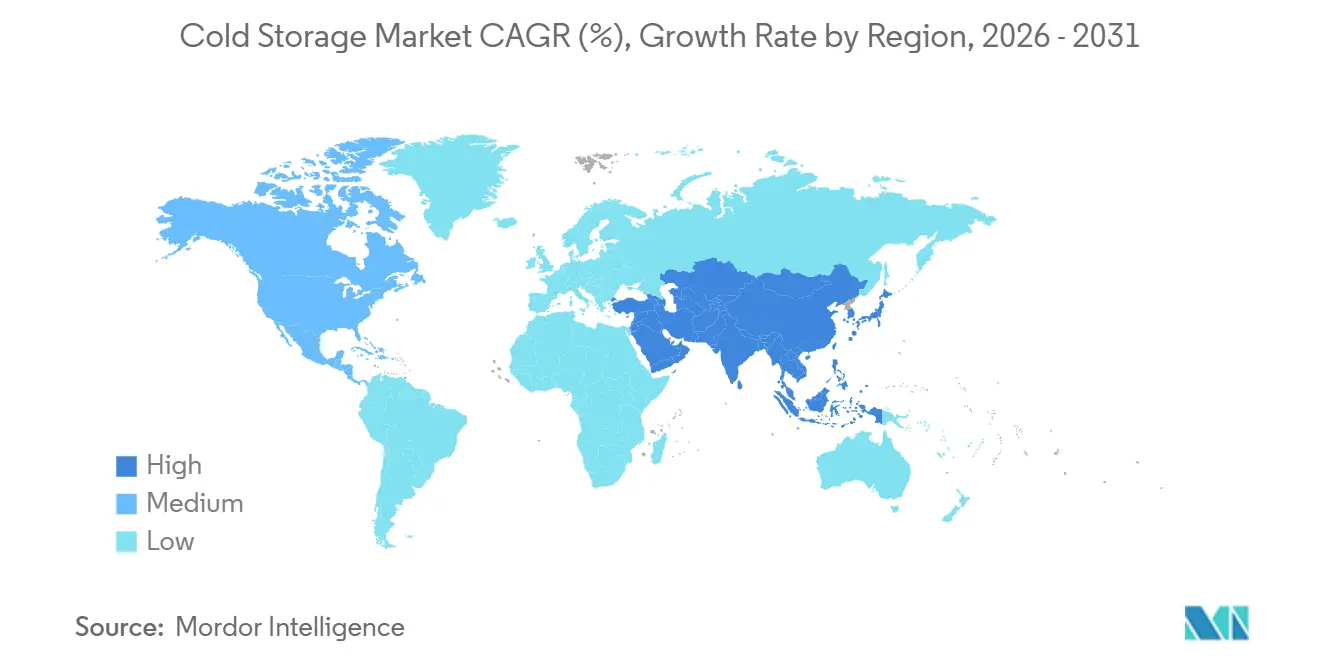
- By region, Asia-Pacific commanded 36.61% of the cold storage market share in 2025 and is poised for the fastest expansion at a 12.02% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global Cold Storage Market Trends and Insights
Drivers Impact Analysis*
| Driver | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth of Organized Retail & E-grocery | +1.3% | Global, concentrated in urban centers | Short term (≤ 2 years) |
| Expansion of Pharmaceutical Cold Chains | +1.1% | North America, Europe, Asia-Pacific | Medium term (2-4 years) |
| Rising Demand for Frozen & Convenience Foods | +0.9% | Global | Medium term (2-4 years) |
| Government Incentives for Cold-Chain Infra | +0.7% | India, China, Southeast Asia, Africa | Long term (≥ 4 years) |
| Solar-Powered Refrigeration | +0.5% | Sub-Saharan Africa, South Asia | Long term (≥ 4 years) |
| Warehouse Automation Adoption | +0.4% | North America, Europe, East Asia | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Growth of Organized Retail & E-grocery
Online grocery is on track to capture 21.5% of total U.S. grocery sales by 2025, reaching the critical mass that justifies purpose-built urban cold stores positioned within 10-15 miles of large population centers. Modern trade formats in India alone are set to rise from USD 790 billion in 2024 to USD 850 billion in 2025, and these outlets require temperature-controlled back-end logistics that legacy wholesale networks cannot supply. Micro-fulfillment designs maximize cubic utilization, often serving more than 100,000 households with a 30-minute delivery window while cutting last-mile costs by up to 50%. The upside is balanced by forecasting challenges: stockouts or spoilage in high-rent urban nodes rapidly erode margin advantages, pushing operators toward sophisticated demand-planning software and advanced analytics.
Expansion of Pharmaceutical Cold Chains
Biologics, cell therapies, and gene therapies now demand storage from -40 °C down to -196 °C, a range far beyond traditional vaccine requirements. SCHOTT Pharma’s polymer syringe validated to -180 °C, launched in 2025, underscores the pace of packaging innovation. GDP certification, automated temperature monitoring, and validated chain-of-custody protocols have raised compliance costs but also created durable barriers to entry, allowing certified facilities to charge 30–50% pricing premiums. Geography is diversifying as manufacturers establish regional depots for resilience, opening opportunities for cold storage operators in secondary markets previously overlooked by pharmaceutical logistics[1].SCHOTT Pharma, “Polymer Syringe for Ultra-Low Temperature Storage,” schott-pharma.com.
Rising Demand for Frozen & Convenience Foods
Per-capita consumption of frozen meals is climbing in mature economies despite stable populations, reflecting improved freezing technologies and changing household time budgets. In the United States, the cold chain logistics value linked to frozen products is projected to move from USD 97.13 billion in 2026 to USD 133.87 billion by 2031 at a 6.63% CAGR. Ready-to-eat meals require rapid blast freezing for texture retention, lengthening dwell times, and tying up warehouse capacity. Operators are responding with hybrid contract models blending dedicated and shared space to smooth utilization curves and secure predictable revenue flows.
Government Incentives for Cold-Chain Infrastructure
India’s PMKSY program has earmarked INR 4,600 crore (USD 550 million) for integrated cold chains through March 2026, already delivering more than 838,000 metric tons of capacity. Provinces in China provide tax holidays and land-use concessions for energy-efficient projects, while the Asian Development Bank’s 2025 integration report lists cold storage as a priority for technical assistance. These incentives now emphasize end-to-end networks over isolated depots, nudging private developers toward hub-and-spoke configurations that link farm gates to city centers[2].Invest India, “Cold Chain Infrastructure and Its Future Potential,” investindia.gov.in
Restraints Impact Analysis*
| Restraint | ( ~ ) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Energy Consumption & Electricity Costs | -0.8% | Global, acute in regions with high tariffs | Short term (≤ 2 years) |
| Heavy Upfront CapEx & Regulatory Compliance | -0.6% | Global, especially in emerging markets | Long term (≥ 4 years) |
| Shortage of Skilled Refrigeration Technicians | -0.5% | Global, severe in secondary cities | Medium term (2-4 years) |
| Rising Insurance Premiums for Ammonia Systems | -0.3% | North America, Europe | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
High Energy Consumption & Electricity Costs
Energy accounts for 50-70% of operating expense in a typical cold store, leaving profitability highly sensitive to tariff swings. In parts of Sub-Saharan Africa, grid unreliability forces diesel backup that can raise operating costs by 25%. Facilities are upgrading building envelopes, installing variable-speed drives, and adopting low-GWP refrigerants such as Honeywell’s Solstice ze, reported to cut energy use by 46%. Capital outlays, however, range from USD 1 million to USD 3 million per 100,000 ft2, slowing adoption in lower-margin facilities[3]Honeywell, “Energy Efficiency Standards in Cold Storage,” honeywell.com.
Heavy Upfront CapEx & Regulatory Compliance
A pharmaceutical-grade warehouse can cost more than USD 200 per ft2, compared with USD 70 for ambient space. Capital intensity is compounded by the EU’s revised F-gas Regulation 2024/573, which bans self-contained units with a GWP above 150 from January 2025, forcing retrofits or replacement. Natural refrigerants such as CO? and ammonia meet environmental rules but require new safety protocols, additional sensors, and higher insurance premiums, creating a two-tier market where well-funded operators pull ahead[4].Laird Thermal Systems, “Decline of F-Gases and Impact on Refrigeration Equipment,” lairdthermal.com
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Temperature Type: Ultra-Low Demand Reshapes Capacity Mix
Frozen storage continues to anchor 62.34% of the cold storage market in 2025 by value. Yet the deep-frozen and ultra-low segment, defined as below -20 °C, is climbing at a 13.01% CAGR to 2031, nearly triple the overall cold storage market growth. Ultra-low freezers operating between -40 °C and -86 °C are indispensable for cell and gene therapies, and demand for cryogenic liquid nitrogen storage below -150 °C is emerging. This high-specification space commands rental rates two to three times higher than standard frozen rooms, cushioning capital costs and supporting premium margins.
Operators investing early enjoy durable advantages. Ultra-low rooms require redundant compressors, backup generators sized for extended outages, stainless-steel racks compatible with cryogenic exposure, and continuous monitoring that integrates with validated laboratory information systems. Upfront capex per pallet slot can exceed USD 1,500, but high utilization and multi-year take-or-pay contracts common in pharma logistics provide revenue certainty. Conversely, the chilled 0-5 °C band retains steady demand for dairy, produce, and non-frozen pharmaceuticals. Pricing pressure is more acute in chilled rooms, prompting consolidation as operators seek scale to spread fixed energy and compliance costs. Hybrid facilities that flex zones among chilled, frozen, and ambient conditions are gaining traction, maximizing cubic throughput and diversifying revenue streams within a single site.


By Automation Level: Robotics reshape throughput economics
Automated stores featuring AS/RS, shuttle systems, and palletizing robots are projected to expand at a 16.72% CAGR through 2031, outstripping the cold storage market overall. The capital requirement of USD 50-100 million per facility favours operators with access to low-cost funding and large anchor tenants willing to commit volume.
Automated palletizers and layer depalletizers reduce dock dwell times by 40%, expanding ship-cum-receive windows. Modern facilities integrate digital twins that model energy draw, labor flow, and inventory turns, enabling operators to tweak algorithms for real-time gains. Cold storage market share captured by automated facilities is forecast to climb as returns on invested capital improve and financing structures mature.
Insurance premiums for automated sites often fall due to lower human exposure risks, partly offsetting capex. In addition, predictive maintenance sensors lower unplanned downtime, a critical metric when handling high-value biologics. Regulatory bodies increasingly accept electronic batch records and automated condition monitoring, streamlining compliance for heavily regulated products.
By Application: Pharma demand outpaces legacy food segments
Fish and seafood retained 17.35% of the cold storage market share in 2025, underpinned by stringent temperature requirements from catch to retail. Pharmaceuticals and biologics, though representing a smaller absolute volume, are on course for an 11.93% CAGR to 2031, making them the principal growth engine. Premium pricing reflects the need for stringent chain-of-custody records, continuous monitoring, and GDP certification.
Meat and poultry volumes remain substantial but exhibit seasonal surges tied to production cycles and holiday demand, necessitating flexible contracts. Fruits and vegetables drive regional dynamics in export-oriented economies, particularly in South America and Southeast Asia. Dairy, frozen desserts, and ready-to-eat meals benefit from improved freezing technology that preserves texture and taste, extending shelf life and global reach. Specialty chemicals and clinical trial materials round out a diverse portfolio that keeps capacity utilization high but demands tailored handling protocols. Successful operators craft mix management strategies that favor year-round, high-margin tenants while allocating shoulder periods to lower-rate, seasonal commodities, thereby smoothing revenue volatility.
Geography Analysis
Asia-Pacific held 36.61% of the cold storage market value in 2025 and is set to outpace all other regions with a 12.02% CAGR to 2031. China’s provincial subsidies and mandatory green-design codes spur investment in energy-efficient warehouses, while India’s government programs underwrite integrated networks from farmgate to megacity. Southeast Asia is maturing into a regional transshipment hub, channeling seafood and pharmaceuticals through Singapore’s and Malaysia’s temperature-controlled ports. Fragmented regulatory frameworks and skills gaps persist, yet savvy operators leverage joint ventures with local partners to navigate permitting and land acquisition hurdles.
North America exhibits a mature yet dynamic landscape. The United States alone controls roughly 3.7 billion cubic feet of refrigerated storage, but average facility age exceeds 40 years, prompting a modernization wave. E-grocery penetration and pharmaceutical growth are redirecting investment toward urban micro-fulfillment nodes and automated mega-warehouses near intermodal corridors. Land scarcity in Tier-1 coastal markets inflates ground rents, pushing development inland along rail-served logistics parks. Canada and Mexico are expanding capacity to support export-oriented agriculture and near-shoring trends, respectively, cementing the region’s integrated supply networks.
South America, Europe, and the Middle East-Africa offer contrasting profiles. Brazil and Peru expand capacity for meat and fruit exports, though currency volatility and high borrowing costs limit smaller projects. Europe’s cold storage market is undergoing a regulatory-driven overhaul as the F-gas ban accelerates adoption of natural refrigerants. Germany, the BENELUX, and the Nordics lead in automation and renewable integration, while Southern Europe deploys hybrid solar-powered plants to offset high electricity tariffs. In the Middle East, the UAE and Saudi Arabia position themselves as regional hubs, while Sub-Saharan Africa experiments with solar-linked micro-storage to cut post-harvest losses, highlighting diverse pathways toward cold chain maturity.

Regulatory Landscape
Cold storage sits at the intersection of food safety, pharmaceutical distribution integrity, and environmental rules governing refrigerants and emissions. In Europe, the EU revised F-gas Regulation (EU) 2024/573 is a major compliance driver, including a ban from January 2025 on certain self-contained refrigeration units with high global warming potential (GWP), which is accelerating retrofits and replacement cycles toward lower-GWP and natural refrigerants. For pharma-grade operations, compliance commonly aligns to EU GDP guidelines and, for U.S.-linked product flows, FDA current good manufacturing practice frameworks such as 21 CFR Parts 211/1, pushing operators toward validated monitoring, audit-ready records, and chain-of-custody controls.
Cross-border cold chain equipment requirements are also tightening around data and performance standards. A June 2026 ASEAN white paper set mandatory technical indicators for imported cold-chain transport equipment (including temperature accuracy requirements and data compliance), reinforcing the need for interoperable telemetry from warehouse to transport. Industry bodies such as the Global Cold Chain Alliance (GCCA) and the UK Cold Chain Federation have continued to advocate for clearer policy recognition of cold chain infrastructure and practical transition pathways for transport refrigeration, shaping how fleets and facilities plan compliance investments.
Value Chain Analysis
The cold storage value chain spans (1) commodity and life-science shippers (seafood, meat, dairy, frozen foods, and pharma/biologics), (2) packaging and handling inputs (insulated packaging, pallets/racking, blast freezing and refrigeration equipment), (3) facility developers and owners (greenfield and brownfield redevelopment), (4) cold storage operators and 3PLs providing warehousing, inventory management, and value-added services (tempering, labeling, order assembly), (5) temperature-controlled transport partners (reefer trucking, intermodal, ocean/air interfaces), and (6) downstream channels including retailers, e-grocery fulfillment, foodservice, and healthcare distributors. As product sensitivity and audit requirements increase, cold storage operators increasingly function as compliance orchestrators, integrating temperature monitoring, electronic records, and exception management across nodes.
Scale and network density shape bargaining power and the range of services offered across the chain. Large operators run multi-country platforms that support lane balancing, standardized processes, and procurement leverage in energy, equipment, and automation. For instance, Lineage operates over 500 facilities with about 3.1 billion cubic feet of capacity, while Americold has extended platform reach through partnerships, including a North American joint venture with EQT spanning 12 facilities and 124 million cubic feet. Industry coordination and capability development also flow through associations such as GCCA, which provides training and forums that support consistent operating practices as customers demand stronger data integration and end-to-end visibility across cold chain partners.
Competitive Landscape
Market concentration is accelerating in developed regions. Lineage Logistics and Americold Realty Trust together control more than 70% of North American capacity, leveraging scale for procurement advantages, proprietary software, and cross-regional service offerings that smaller rivals struggle to match. Lineage’s USD 4.2 billion IPO in 2024 funded further acquisitions and automation rollouts. Americold pursues joint ventures, such as its USD 130 million Kansas City rail-connected site, to expand without over-stretching its balance sheet.
Despite consolidation, fragmentation persists in emerging markets where local knowledge and relationship-based business models still confer advantages. Regional champions in India, China, and Brazil defend their share through deep customer intimacy and agile decision-making, even as global players enter via minority stakes and partnerships. Technology adoption is the fault line: leaders deploy IoT sensors, AI-driven predictive maintenance, and advanced warehouse management systems that compress costs and raise service levels. Smaller facilities lacking capital for upgrades risk relegation to low-margin commodity storage or exit altogether.
White-space opportunities center on pharmaceutical-grade depots, automated micro-fulfillment centers, and solar-powered rural hubs. Specialized providers offering Cooling-as-a-Service, zero-carbon refrigeration, or GDP-certified storage are attracting private equity interest. Competitive intensity is expected to tighten as sustainability disclosures become mandatory and customers prioritize partners able to document carbon footprints and compliance credentials.
Cold Storage Industry Leaders
-
Lineage Logistics
-
Americold Logistics
-
Nichirei Logistics Group
-
Swire Cold Storage
-
Burris Logistics
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Higher-specification segments create whitespace where compliance capability and engineered temperature performance translate into premium pricing, especially in deep-frozen and ultra-low storage (< -20 C) supporting biologics, cell and gene therapies, and clinical materials. The market is also seeing a sharper move toward automation and digital integration, as operators and shippers focus on throughput, traceability, and labor risk reduction. Automated cold stores are increasingly treated as a separate investment track versus conventional facilities.
Platform-scale investment structures and retailer-oriented network redesign are also opening opportunity areas. Evidence of modernization includes Lineage reporting USD 130 million of greenfield expansion and technology investment in Q1 2026. In May 2026, Americold and EQT announced a USD 1.3 billion North American cold storage joint venture (12 facilities, 124 million cubic feet, about 400,000 pallet positions), reflecting how joint ventures help manage capex intensity while expanding footprints. On the demand side, cold chain partners are being evaluated on flexibility and systems connectivity, and industry reporting points to strong pull for flexible storage capacity and improved data integration that supports offerings such as multi-tenant flexible space, integrated WMS and telemetry, and standardized audit-ready reporting across networks. Regionally, in addition to continued build-out in Asia-Pacific supported by government programs, industry leaders have identified Latin America as a priority area for cold chain infrastructure investment in 2026, tied to export-driven perishables and the need for modern, compliance-oriented cold storage nodes.
Recent Industry Developments
- July 2026: Nichirei Logistics Group completed acquisition and renamed two Indonesian companies to Nichirei Mega Logistik and Nichirei Mega Sejahtera, effective July 1, 2026. The expanded Indonesia/SEA cold-storage footprint broadens Nichirei's regional scale and service coverage in APAC. The hub-and-spoke network for temperature controlled logistics is strengthened to support faster regional distribution.
- May 2026: Americold Realty Trust announced a US$1.3 billion North American cold storage joint venture with EQT, covering 12 facilities and 400,000 pallet positions with Americold retaining 30% equity. The deal strengthens North American footprint and the joint-venture model. It supports capital-light expansion while expanding platform reach and asset base, with depth in intermodal and cross-region integration.
- March 2026: Lineage Logistics completed expansion of the Louisville-Winsted cold storage facility in Louisville, Kentucky (84,000 sq ft, 10,400 pallet positions). The expanded capacity marks a key North American capacity addition. It supports scale and throughput efficiency and reinforces Lineage’s lead in automated, high-throughput cold storage.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the cold storage market covers third party and captive refrigerated warehousing services that store temperature-sensitive goods across chilled, frozen, and deep-frozen conditions, including revenues linked to handling and storage inside these facilities.
Scope exclusions: This sizing excludes long-haul refrigerated transportation and sales of refrigeration equipment or construction materials unless they are billed as part of warehouse storage services.
Segmentation Overview
-
By Temperature Type
- Chilled (0–5 °C)
- Frozen (-18–0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (<-20 °C)
-
By Automation Level (Storage)
- Conventional Facilities
- Automated Cold Stores (AS/RS, Robotics)
-
By Application
- Fruits & Vegetables
- Meat & Poultry
- Fish & Seafood
- Dairy & Frozen Desserts
- Bakery & Confectionery
- Ready-to-Eat Meals
- Pharmaceuticals & Biologics
- Vaccines & Clinical Trial Materials
- Chemicals & Specialty Materials
- Other Perishables
-
By Geography
-
North America
- United States
- Canada
- Mexico
-
South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
-
Asia Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
-
Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
-
Middle East And Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
-
North America
Data Sources, Market Sizing, and Validation
Desk Research
We start by mapping what drives cold storage demand, then anchor it with public data series that show how much temperature-sensitive product is moving through the supply chain. We use food and agriculture production and trade statistics from bodies such as the USDA and FAO, and customs and trade data that signals import and export flows of meat, seafood, dairy, and produce.
To avoid relying on only one demand signal, we also use official cold chain and food safety references (such as WHO guidance and national food safety agencies), plus energy and refrigerant policy references that affect operating costs and retrofit pace. On the supply side, we collect warehouse capacity additions, automation announcements, and utilization clues from company filings, investor presentations, and reputable industry press, then cross-check with paid subscriptions that support company financials, patent lookups, and shipment-level import or export checks where applicable. These desk research sources are illustrative rather than exhaustive, and many other references were also used to collect data, validate assumptions, and clarify open questions.
Primary Interviews and Surveys
Our fieldwork focuses on validating how storage revenue is earned and priced in practice, since rate cards and occupancy can shift by commodity mix and season. We speak with a spread of warehouse operators, food and pharmaceutical shippers, retailers, and cold chain advisors across key geographies so secondary signals can be confirmed, gaps can be filled, and assumptions can be aligned to real operating patterns.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 28% | CXOs: 16% | APAC: 39% |
| Mid tier: 52% | Functional/Unit leaders: 30% | EMEA: 35% |
| Smaller Players: 20% | Managers: 54% | Americas: 26% |
Market-Sizing & Forecasting
Our market model starts with a top-down demand pool build that links temperature-sensitive food and pharma throughput to required warehouse space, then converts that space into revenue using observed storage rates and typical occupancy patterns. Because public capacity data can be uneven by country, we corroborate results with selective bottom-up checks, such as rolling up reported cold storage revenue for a sampled set of operators and adjusting for unreported and captive volumes based on interview guidance.
Inputs that materially move the totals include cold storage capacity additions (often described in cubic meters or pallet positions), warehouse occupancy and turn rates, share of chilled versus frozen handling, electricity and refrigerant cost pressure that influences pricing, and the growth of e-commerce grocery and biopharma temperature-controlled requirements. Where a variable is missing for a smaller country, we fill the gap using proxy indicators like trade volumes in key perishables and local food processing output, then validate the resulting intensity against what operators describe as feasible.
For forecasting, we apply scenario analysis so growth can be flexed across base, tighter-capacity, and soft-demand cases, and tie these cases back to what we hear on utilization, pricing power, and planned build-outs. The final curve is kept realistic by checking that implied revenue per pallet position and implied square footage needs do not drift away from observed operating ranges.
Data Validation & Update Cycle
We run consistency checks that compare implied revenue per unit of capacity with independent signals like utilization commentary, expansion announcements, and commodity volume trends. Outliers are reviewed in a second analyst pass, and when a gap is driven by one large assumption, we re-contact sources to confirm it before the number is locked.
Reports are refreshed on an annual cycle, and interim updates are made when there is a material event such as a major capacity wave, a policy shift affecting refrigerants, or a sharp change in energy costs that impacts pricing. Before delivery, the dataset and assumptions get a final review so clients receive an updated view rather than an older snapshot.
黑料不打烊's Cold Storage Market Size Compared Against Other Published Estimates
Published cold storage market values often differ because sources do not always count the same revenue streams, and they may also use different base years and currency timing. We lay out our assumptions clearly so readers can see which parts of warehousing activity are included, and which adjacent activities are kept out.
The biggest gap drivers in this space usually come from mixing up warehouse service revenue with equipment sales, counting real estate asset values instead of operating revenue, or applying a single food demand growth rate without checking occupancy and pricing in local markets. Some estimates also blend cold storage with refrigerated transportation, which can raise the number quickly, while others only capture third-party operators and miss captive facilities used by producers and retailers.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 166.16 B (2026) | |
| Global Consultancy A | USD 173.00 B (2024) | Uses an earlier base year and appears to blend refrigerated warehousing with adjacent cold chain services, which makes the value less comparable to storage-only revenue. |
| Trade Journal B | USD 198.70 B (2023) | Back-solves totals from broad cold chain growth narratives and does not clearly separate chilled and frozen storage service revenue from equipment, real estate, or transport-related value. |
The spread mainly comes down to which market items are counted, where refrigerated transportation and refrigeration equipment sales can sit outside scope, and how capacity and occupancy checks are used to keep storage revenue tied to services billed at the warehouse level, which is how 黑料不打烊 keeps this total consistent.


Key Questions Answered in the Report
What is the 2026 value of the cold storage market?
The cold storage market size is valued at USD 166.16 billion in 2026.
How fast will demand for ultra-low temperature storage grow?
Deep-frozen and ultra-low facilities are projected to expand at a 13.01% CAGR through 2031.
Which region is expected to lead growth to 2031?
Asia-Pacific combines the largest share with the fastest growth, advancing at a 12.02% CAGR.
Who are the dominant players in North America?
Lineage Logistics and Americold Realty Trust together control more than 70% of North American capacity.
What share did frozen storage hold in 2025?
Frozen rooms accounted for 62.34% of cold storage market share in 2025.
Which application segment is growing quickest?
Pharmaceuticals and biologics are forecast to grow at an 11.93% CAGR through 2031 due to rising biologics and gene therapy volumes.
Page last updated on:


