
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 28.29 Billion |
| Market Size (2026) | USD 29.31 Billion |
| Market Size (2031) | USD 34.95 Billion |
| Growth Rate (2026 - 2031) | 3.60 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Canada Office Real Estate Market Analysis by 黑料不打烊
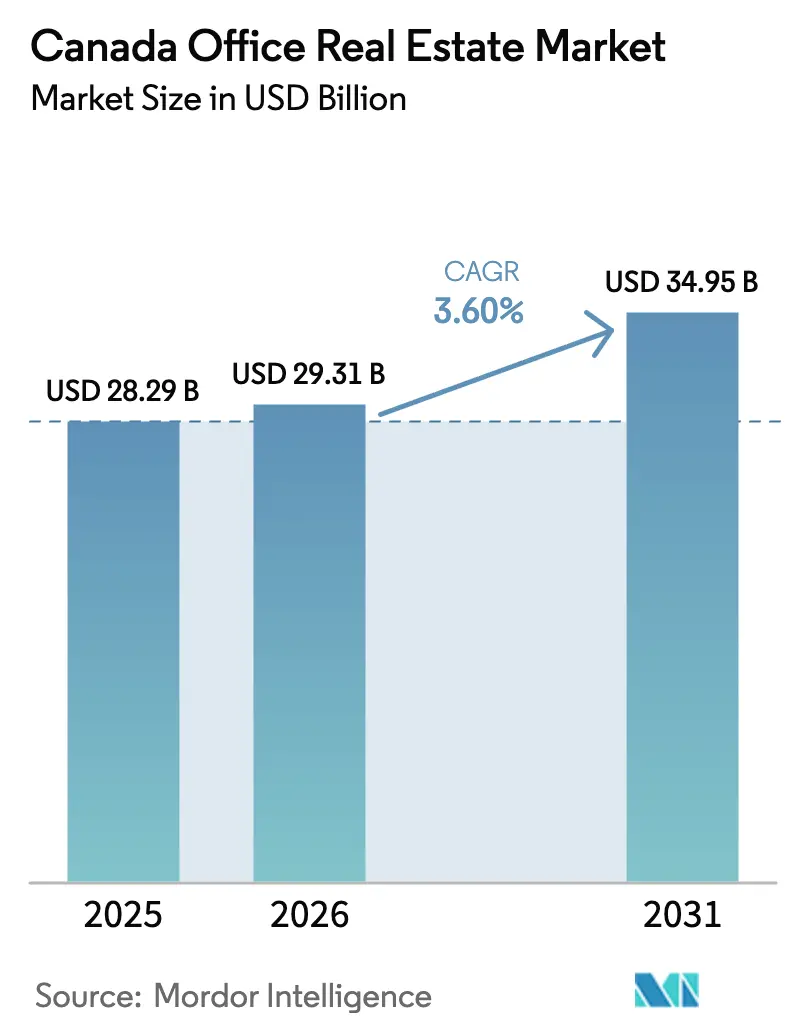
The Canada Office Real Estate Market size is expected to grow from USD 28.29 billion in 2025 to USD 29.31 billion in 2026 and is forecast to reach USD 34.95 billion by 2031 at 3.60% CAGR over 2026-2031. A widening gulf has emerged between premium towers that enjoy healthy absorption and legacy properties whose vacancies remain stubbornly high. Demand is strongest for Grade A assets as employers seek modern air systems, robust digital connectivity, and green credentials that help attract talent and satisfy ESG auditors. Technology, finance, and professional-services tenants account for the bulk of net absorption, pushing landlords to retrofit or reposition older stock. Meanwhile, monetary easing by the Bank of Canada supports refinancing and selective acquisitions even as construction-cost inflation curbs new supply.
Key Report Takeaways
- By building grade, Grade A offices led with 48.92% of the Canada office real estate market share in 2025, while Grade A is set to expand at a 3.98% CAGR through 2031.
- By transaction type, rentals accounted for 68.52% of the Canada office real estate market size in 2025; sales transactions post the fastest growth at a 4.05% CAGR to 2031.
- By end use, information technology and IT-enabled services captured a 28.05% share of the Canada office real estate market size in 2025 and are forecast to rise at a 4.12% CAGR.
- By province, Ontario held 38.12% of the Canada office real estate market share in 2025, whereas Quebec is projected to grow the fastest at a 4.37% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Canada Office Real Estate Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Flight to quality for Class A & sustainable stock | +1.2% | Toronto, Vancouver, Montreal and other major metros | Medium term (2-4 years) |
| Expansion of tech, finance & professional services | +0.8% | Ontario, British Columbia, Quebec urban hubs | Long term (≥ 4 years) |
| Flexible and short-term leasing uptake | +0.6% | Major metropolitan areas | Short term (≤ 2 years) |
| Urban transit-linked infrastructure projects | +0.5% | Toronto, Vancouver, Montreal, Calgary | Long term (≥ 4 years) |
| Federal push for advanced green certifications | +0.4% | Nationwide, early in federal portfolios | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Flight to Quality Driving Demand for Class A and Sustainable Buildings
Tenant migration to premium towers is accelerating as firms compete for skilled workers and must demonstrate credible ESG performance. In Q2 2024 the Class A downtown vacancy rate fell in six of the ten largest markets, widening the rent gap versus secondary space to 35% on new leases. Brookfield reported that fresh Class A leases command rents 35% higher than expiring agreements. The Canada Green Building Council tightened embodied-carbon limits under its Zero Carbon Building Version 4 standard in June 2024, giving certified towers a pricing edge. Federal departments must now run net-zero audits on real-estate portfolios every five years, adding steady institutional demand for top-tier assets. As a result, investors continue to deploy capital into smart HVAC, touchless access, and on-site renewable systems to future-proof assets.
Growth in Tech, Finance, and Professional Services Sectors
High-tech hiring grew 4.6% in 2023 and Toronto alone added 17,600 net tech jobs, lifting the sector to 15.2% of 2024 office leasing activity. Artificial-intelligence labs require dense power loads and secure collaboration zones, steering take-up toward new-build cores. Finance and insurance roles expanded by 79,000 since October 2024, translating into fresh demand in the nation’s banking centres. Advisory and legal practices are consolidating footprints into landmark addresses that signal brand strength while supporting hybrid schedules. Venture-capital inflows rose 13.3% year-on-year, encouraging scale-ups to ink agile leases with expansion clauses that favour downtown tech clusters.
Increased Adoption of Flexible and Short-Term Leasing Solutions
Corporations prize agility amid shifting headcount forecasts. Allied Properties completed 300 lease tours in Q1 2024, achieving 69% tenant retention as it adapted suite sizes and term structures. Premium for short-term leases runs 15-25% above standard terms, which landlords accept to boost near-term cash flow. Federal policies mandating three days in office create fluctuating density, further supporting demand for turnkey coworking floors. Flexible-space operators now anchor major towers, offering enterprise suites with swing-space options that hedge against project uncertainty while preserving a high-service environment.
Urban Infrastructure Investments and Transit Expansions
A USD 30 billion national transit fund is reshaping location calculus, with TOD zoning enabling higher-density offices along rail corridors. Calgary revived its Downtown Development Incentive Program with USD 52.5 million to spur conversions and amenity upgrades. CN committed to a 20-year, 440,000-sq-ft lease at 600 De La Gauchetière W., citing multi-modal access for staff. Prospective high-speed rail connecting major corridors positions parcels near future stations for valuation upside, already influencing underwriting assumptions[1]Government of Canada, “The Largest Public Transit Investment in Canadian History,” canada.ca.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Elevated vacancy in aging & suburban assets | -0.9% | Older urban cores, suburban belts nationwide | Medium term (2-4 years) |
| Slower return-to-office in largest CBDs | -0.7% | Downtown Toronto, Vancouver, Montreal | Short term (≤ 2 years) |
| High borrowing costs & macro uncertainty | -0.5% | Development-heavy markets nationwide | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Elevated Vacancy Rates in Older and Suburban Office Buildings
Overall national vacancy rested at 18.5% in Q2 2024, yet Class B/C inventories see far higher rates as tenants flight to quality. Suburban parks struggle because hybrid policies limit long commutes and encourage consolidation downtown. Although sublet availability fell for five straight quarters to 14.8 million sq ft by Q3 2024, the decline benefits mostly new-build cores. Municipalities promote office-to-residential conversions, but retrofit costs and zoning delays temper the pace of removals, leaving a structural glut among outdated blocks that depresses rents.
Slow Return-to-Office Trends in Major Urban Centers
In May 2024, 18.7% of Canadians still worked from home, far above the 2019 level of 7%. Federal compliance with the three-day directive ranged from 60% at National Defence to 80% at Canada Revenue Agency, underscoring uneven adoption. Slack downtown footfall has lifted Toronto core vacancy to 12.6%, sparking negative headlines about asset write-downs. Landlords must now differentiate on flexibility and tenant experience rather than pure location, trimming effective rents and extending improvement allowances to secure occupants.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Building Grade: Premium Assets Drive Market Differentiation
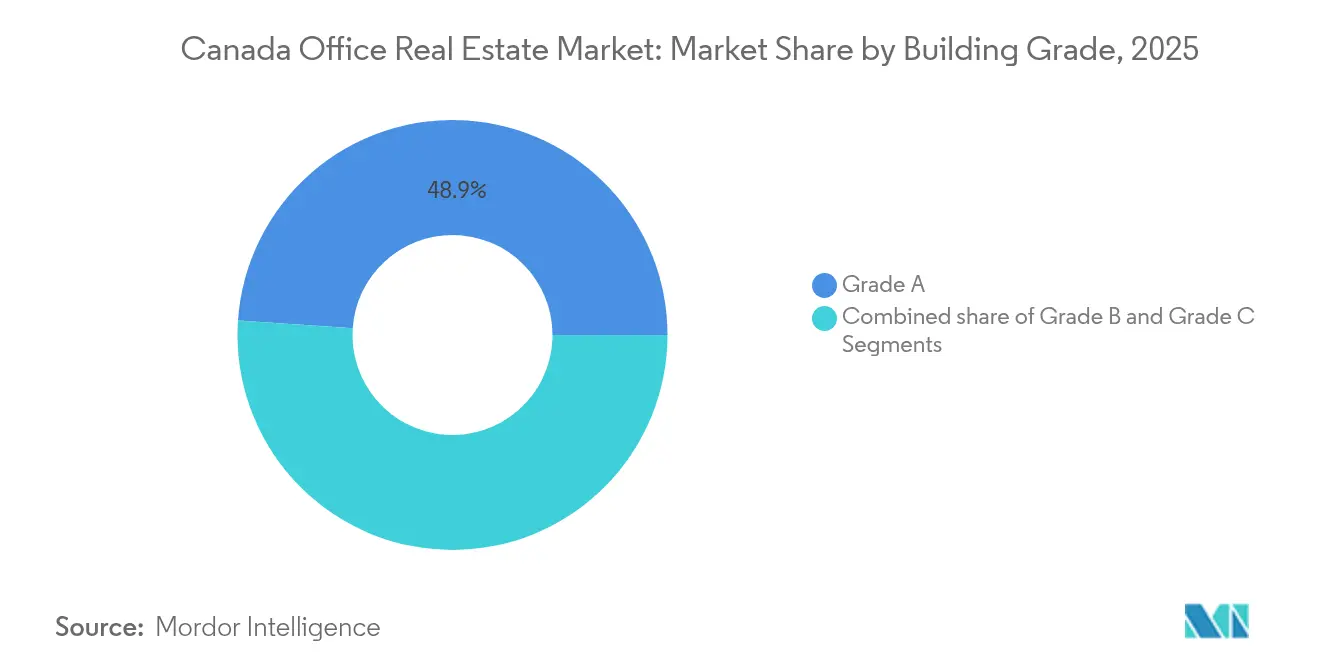
Grade A offices held a commanding 48.92% Canada office real estate market share in 2025, and this cohort is forecast to expand at 3.98% annually to 2031. Flight-to-quality underpins steady leasing, allowing landlords of trophy towers to lift asking rents even as broader vacancies persist. Brookfield leased 27 million sq ft across its global portfolio in 2024, achieving 35% rent uplifts on new Canada mandates, a statistic that underscores pricing power in top-tier stock.
Investor focus has shifted toward deep retrofits that elevate older towers to near-Grade A specifications. Allied Properties is divesting lower-priority buildings worth up to USD 150 million to fund upgrades across its urban workspace holdings. Such capital recycling reflects a recognition that the Canada office real estate market size premium commanded by best-in-class assets justifies intensive spending on HVAC modernization, smart-building platforms, and wellness-oriented amenities. Grade B owners face an existential choice between heavy reinvestment and conversion to alternative uses.


By Transaction Type: Rental Dominance Reflects Market Caution
Rentals represented 68.52% of the Canada office real estate market size in 2025, confirming occupiers’ preference for balance-sheet agility. Shorter terms, pandemic exit clauses, and turnkey spec suites allow tenants to scale space in step with headcount. Allied’s Q1 2024 results showed 4.7% rental re-leasing spreads, an outcome that highlights pricing resilience in well-located buildings despite macro uncertainty.
Sales, though a smaller slice, are forecast to grow faster at 4.05% CAGR. Lower policy rates have revived underwriting appetite, and repricing of legacy portfolios is drawing institutional capital. Canada Pension Plan Investment Board sold two Vancouver towers for roughly USD 300 million at notable discounts, paving a path for value-add operators to reposition these assets for the green economy. Such trades illustrate how the Canada office real estate market share within the investment segment is tilting toward specialists willing to inject capex for carbon-reduction upgrades and flexible-floor plate conversions.
By End Use: Technology Sector Leads Recovery
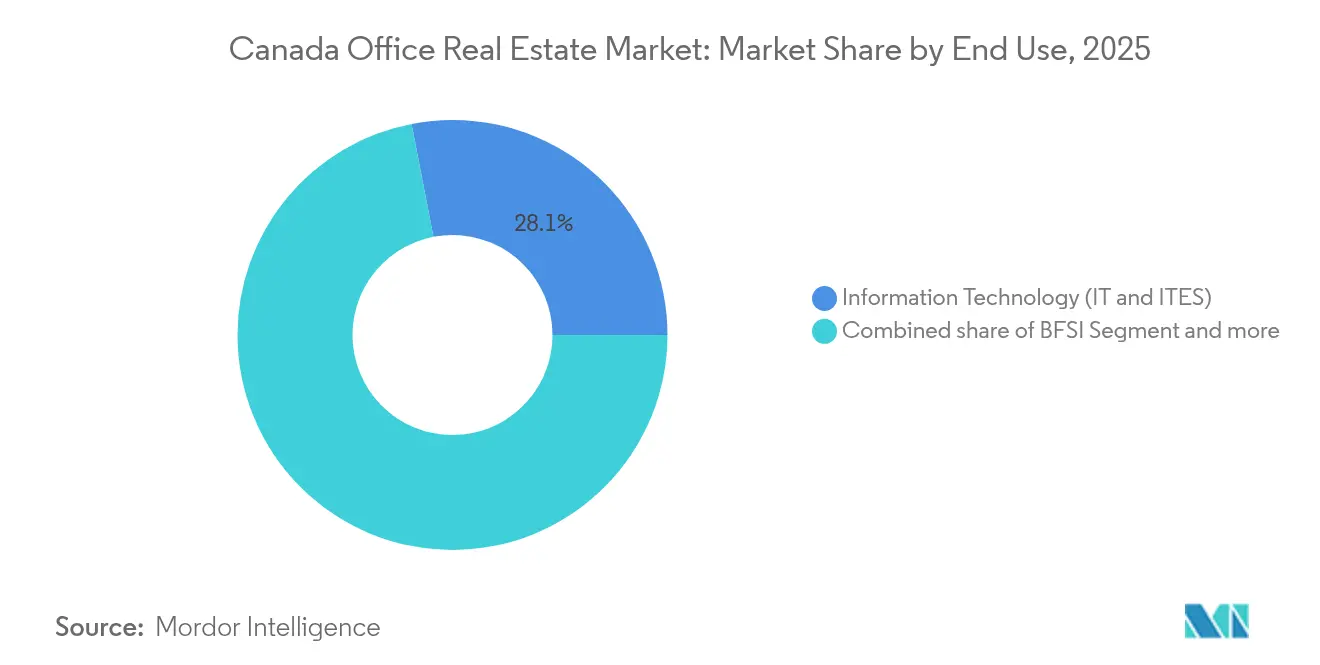
Information technology and IT-enabled services captured 28.05% end-user demand, the largest slice of the Canada office real estate market share in 2025, and will grow at a 4.12% CAGR. Toronto’s tech ecosystem added 17,600 net roles, boosting take-up in AI-ready towers with redundant power and secure fibre loops. Banking and insurance remain sizeable but pace themselves as digital platforms compress desk requirements. Professional-services firms are rightsizing into high-spec collaborative hubs that reinforce culture while trimming under-utilised back-office space.
Start-ups favour campus-style layouts in mixed-use cores offering transit and lifestyle amenities. Lease clauses routinely embed expansion and contraction rights, demonstrating how digital firms’ fluid space needs increasingly dictate the Canada office real estate market size. Laboratory-office hybrids for life-sciences tenants draw premium rents, spotlighting the value of specialised HVAC and safety-code compliance. Energy and legal sectors post steady though flatter take-up, with ESG targets nudging oil-patch occupiers toward efficient builds in Calgary.
Geography Analysis
Ontario’s 38.12% share anchors the Canada office real estate market, yet the province grapples with elevated Class A vacancy of 16.3% as hybrid routines cap daily utilisation. Tech employment growth has moderated but remains positive, ensuring a core of steady demand for leading smart-enabled towers. Provincial funding for GO Transit expansions ties future supply to regional rail, reinforcing downtown valuations for sites near Union Station.
Quebec charts the fastest trajectory at a 4.37% CAGR to 2031. Montreal’s competitive rent profile, deep talent pool, and metro upgrades help lure multinationals seeking bilingual hubs. The provincial administration’s tax incentives for AI and aerospace underpin pre-leasing in new towers, while older stock benefits from conversion grants aimed at reducing surplus inventory.
British Columbia and Alberta represent mature but distinct narratives. Vancouver holds near-single-digit vacancy for downtown Class AAA stock, allowing landlords to raise face rents even as suburban sub-lease space lingers. Morguard’s Telus Garden stake signals sustained investor conviction in that supply-constrained corridor. Calgary reversed years of negative absorption, adding tenants from renewables and logistics that value the city’s cost edge and skilled workforce. Smaller Atlantic and Prairie centres attract back-office expansions by firms chasing workforce affordability and provincial incentives, broadening the geographic base of the Canada office real estate market.
Regulatory Landscape
Canada's office real estate is regulated primarily at the provincial level through land title, planning, leasing, and construction regimes, with Quebec operating under the Civil Code of Quebec rather than the common-law framework used in most provinces. This fragmentation means zoning, development approvals, and landlord-tenant practices can vary materially across provinces and municipalities, shaping leasing structures and redevelopment timelines in markets such as Toronto, Vancouver, Montreal, and Calgary.
At the federal level, policy and enforcement actions affect capital allocation and asset strategy even when office is not the direct target. For example, the Prohibition on the Purchase of Residential Property by Non-Canadians Act has been extended through January 1, 2027, which intersects with office-to-residential conversion feasibility for mixed-use repositioning. Separately, the Competition Bureau has increased scrutiny of restrictive covenants and exclusivity clauses under the Competition Act, influencing how landlords, retail-mixed office owners, and brokers structure leasing restrictions. On building performance, the Canada Green Buildings Strategy and the Canada Green Building Council's evolving standards continue to reinforce retrofit activity, while amendments to Energy Efficiency Regulations targeted for end-2026 are expected to introduce new efficiency or testing requirements for HVAC-related equipment commonly specified in office upgrades.
Value Chain Analysis
The Canada office real estate value chain begins with site control and entitlement, where provincial property law and municipal zoning, permitting, and transit-oriented development rules drive feasibility and timing. Developers, general contractors, and specialist trades deliver new-build and retrofit projects, supported by architectural and engineering firms increasingly designing for higher indoor-air standards, electrification, and measurement-ready ESG features. Building materials and equipment suppliers, particularly HVAC and controls, contribute more to differentiation as premium towers compete on operating performance, digital connectivity, and sustainability metrics.
Capital formation and transactions flow through lenders, mortgage brokerages, and institutional investors, then to owners and asset managers that operate and reposition buildings through leasing, tenant improvements, and property management. Licensed real estate brokers, regulated by provincial bodies, handle leasing and investment sales, while professional services such as legal, appraisal, environmental, and engineering due diligence help de-risk acquisitions and conversion decisions. On the operating side, facilities management, energy services, and technology vendors support smart-building platforms and occupier reporting. Supply-side rebalancing is also underway through removals and repurposing, with 1.5 million sq ft of office product removed from inventory for conversion or demolition in Q1 2026, tightening effective supply in submarkets where older stock is being retired.
Competitive Landscape
Canada’s office arena is moderately concentrated, with the top five landlords controlling a significant share of trophy assets in Toronto, Vancouver, and Montreal. Brookfield stands out, signing 27 million sq ft of leases in 2024 and lifting same-property NOI 4%, evidence of disciplined asset management and ESG-led capex. Allied Properties pivots to a sharpened urban thesis, selling lower-priority blocks to redeploy USD 150 million into high-spec upgrades.
Institutional sellers such as CPPIB are pruning exposure—its USD 300 million Vancouver tower sale underscores an ongoing price reset that opens doors for value-add specialists. Flexible-workspace brands partner with legacy owners, inserting serviced suites and data tracking to raise tenant engagement and retention. Sustainability is the new battleground: landlords publicise carbon-reduction road maps, seek Zero Carbon or LEED Platinum badges, and integrate smart meters to satisfy corporate reporting duties.
Private-equity entrants target conversion plays, snapping up well-located but obsolete blocks for mixed-use transformations that tap housing credits and GST/HST rebates on purpose-built rental components. Cross-border capital is also re-emerging: Ivanhoé Cambridge’s sale of a New York trophy stake to RXR, paired with a USD 300 million modernisation plan, illustrates confidence in premium urban offices when backed by targeted capex. Overall, competitiveness now pivots on measurable ESG outcomes, operational flexibility, and access to transit-rich parcels.
Canada Office Real Estate Industry Leaders
Brookfield Asset Management
Oxford Properties Group
Ivanhoé Cambridge
Cadillac Fairview
Allied Properties Real Estate Investment Trust
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
An opportunity is emerging around upgrading and re-tenanting best-located assets as occupiers concentrate in amenitized, high-quality buildings that support return-to-office policies. That direction aligns with the 2024 tightening of embodied-carbon limits under the Canada Green Building Council's Zero Carbon Building Version 4 standard and with federal portfolio requirements such as recurring net-zero audits, which elevate the value of measurable building performance. Landlords and investors that can execute deep retrofits, smart-building deployments, and HVAC modernization are positioned to compete for tenants in technology, finance, and professional services, which have been key sources of net absorption within the report scope.
Another opportunity lies in reconfiguring obsolete inventory through conversions, selective demolition, and mixed-use redevelopment, supported by policy tools such as the federal 100% GST/HST rebate for new purpose-built rental housing that encourages office-to-residential where zoning and design allow. Market evidence also points to conditions that favor well-capitalized buyers and active asset management: national office construction reached a 22-year low in Q1 2026 (per major brokerage tracking), while activity remains uneven across nodes such as Downtown Toronto, Downtown Montreal, Vancouver, Suburban Calgary, and Kitchener-Waterloo. As transactions and removals reshape local supply-demand, owners that offer flexible leasing structures and turnkey suites can capture demand tied to hybrid utilization patterns and shorter planning horizons, while value-add investors continue to focus on price-reset legacy assets for repositioning.
Recent Industry Developments
- July 2026: Nokia commenced construction on a 750,000 sq ft R&D innovation campus in the Kanata North Tech Park, Ottawa, with Broccolini as development partner. The project highlights ongoing Canada office real estate activity and signals Ottawa's growing tech-campus footprint. The development supports Ottawa's high-tech office demand and contributes to regional office-space absorption.
- November 2025: Brookfield Properties relocated ATB Financial to Suncor Energy Centre in Calgary, occupying 173,000 sq ft. The move reflects a significant tenant relocation within a top Calgary asset. Repositioning of trophy assets to attract anchor tenants and demonstrate ESG and compliance upgrades remains a central theme in core markets.
- June 2025: Oxford Properties Group acquired CPP Investments' 50% interest in seven Western Canadian office properties, gaining 100% ownership. This consolidation of a high-quality Western Canada office portfolio increases control over prime assets and accelerates capital deployment in top markets. It also signals continued investment emphasis on maintaining and upgrading core office holdings.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market is measured as the annual gross value generated by office real estate in Canada, combining rental contract value and sales value, converted into USD for consistent comparison across provinces.
Scope exclusions: Co-working membership revenues, property management fees, and single-family homes informally adapted for office use are not counted in this market size.
Segmentation Overview
- By Building Grade
- Grade A
- Grade B
- Grade C
- By Transaction Type
- Rental
- Sales
- By End Use
- Information Technology (IT & ITES)
- BFSI (Banking, Financial Services and Insurance)
- Business Consulting & Professional Services
- Other Services (Retail, Lifescience, Energy, Legal)
- By Province
- Ontario
- Quebec
- British Columbia
- Alberta
- Rest of Canada
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to set the basic structure of the Canada office real estate demand and supply picture before assumptions are tested in interviews. We focused on public data that signals changes in office stock, building activity, financing conditions, and leasing health, so the model inputs start from observable indicators.
Sources typically include official and non-paywalled references such as Statistics Canada tables on investment in building construction and non-residential capital spending, Bank of Canada rate decisions and credit condition indicators, CMHC publications for broader property market context, and provincial or municipal open data portals that track permits, planning pipelines, or assessments in major metros. We also reviewed items such as public REIT filings, audited annual reports, investor presentations, and reputable press coverage to confirm transaction narratives and repositioning activity. Where needed, paid subscriptions that support company financials, news and financials, and shipment-level trade data for construction inputs were used selectively to verify major capex signals, before being cross-checked back to public disclosures. These sources are illustrative only, and many other references were used for data collection, validation, and clarification during the work.
Primary Interviews and Surveys
Primary work focuses on validating the practical drivers behind the numbers, including how leasing terms are being negotiated, what tenants are taking in net new space, and how rent movement differs by grade and metro. We spoke with a mix of landlords, brokers, asset managers, and corporate occupiers across key Canadian provinces so assumptions on rent progression, absorption, and sales liquidity could be adjusted to current on-the-ground conditions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 33% | CXOs: 16% |
| Mid tier: 45% | Functional/Unit leaders: 26% |
| Smaller Players: 22% | Managers: 58% |
Market-Sizing & Forecasting
Sizing starts with a top-down reconstruction that links addressable office stock and its occupied share to observed rent and sale value patterns, which then yields an annual gross value for the market. Results are subsequently corroborated with selective bottom-up approximations, such as sampled rent per square foot by grade, channel checks on leasing incentives, and a sanity check against disclosed transaction volumes where available.
The model is driven by a small set of fingerprints that can be refreshed regularly, including office inventory additions and removals, vacancy and net absorption direction, Grade A versus older stock mix, average rent movement and concession behavior, and the interest-rate environment that influences deal flow and pricing. When gaps appear by province or by building quality, they are filled using conservative ranges from comparable metros and then pressure-tested in interviews so the totals do not drift away from observed leasing conditions.
Forecasting is built using scenario analysis, supported by variable-level expectations gathered in primary discussions, especially on return-to-office stability, refinancing conditions, and the pace of retrofits that keep older space competitive. Because turning points in vacancy, cap rates, and incentives can shift value even when stock growth is modest, projections are not treated as a simple straight-line extension.
Data Validation & Update Cycle
Validation is done by checking outputs against independent signals, including whether implied occupied space aligns with vacancy and absorption direction, and whether rent and sales value assumptions remain consistent with rate moves and reported deal commentary. When a driver looks off (for example, a rent jump that is not supported by leasing sentiment), the inputs are revisited and then clarified through re-contacts where needed.
Before sign-off, the model and key assumptions go through multi-step analyst review so arithmetic consistency, currency conversion timing, and provincial roll-ups are clean. Reports are refreshed annually, with interim updates when material events occur, and a final pre-delivery pass is performed so clients receive the most current view available at release time.
黑料不打烊's Canada America Office Real Estate Market Sizing Compared With Other Published Estimates
Published market sizes for Canada office real estate can differ even when they sound similar, because teams select different value definitions and then treat leasing and transaction activity in their own way. The gaps usually show up around what is counted as office real estate value versus adjacent revenue pools.
Key drivers here include whether co-working membership receipts are included, whether property management income is mixed into the total, and how flex floors are treated when they are marketed like standard office premises. Another source of spread is how quickly vacancy and absorption assumptions are refreshed during periods when rate changes affect tenant decisions and deal flow. Estimates that focus on purpose-built, multi-story office buildings and convert rental contracts plus sales into an annual gross value will typically land lower than figures that also add service revenues, which is the scope discipline applied by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 28.29 B (2025) | |
| Global Consultancy A | USD 31.10 B (2025) | This figure appears to add co-working membership revenue and select service income alongside office rents, which lifts the total versus a buildings-only gross value view. |
| Industry Association B | USD 25.70 B (2024) | This estimate uses an earlier base year and more conservative rent reset and vacancy inputs, which can understate value when leasing performance differs sharply by grade and metro. |
The table suggests that scope choices and base-year timing explain most of the spread, with some sources blending adjacent revenues into the total and others lagging fast-moving occupancy and rent signals. By keeping inputs tied to stock, vacancy, absorption, and rent behavior, the result stays traceable to repeatable steps that can be rechecked during updates.


Key Questions Answered in the Report
What is the current value of the Canada office real estate market?
The market is valued at USD 29.31 billion for 2026 and is projected to reach USD 34.95 billion by 2031.
Which building grade holds the largest market share?
Grade A offices command 48.92% of 2025 demand and are forecast to grow at a 3.98% CAGR.
How big is the technology sector’s footprint in Canadian offices?
Technology and IT-enabled services account for 28.05% of end-user demand and should expand at 4.12% annually.
Which province is growing the fastest?
Quebec leads with a projected 4.37% CAGR between 2026 and 2031, buoyed by infrastructure spending and cost advantages.
Why are flexible leases becoming more popular?
Hybrid work patterns and economic uncertainty push firms to prioritise agility, resulting in rental premiums of 15-25% for short-term, plug-and-play space.
How are sustainability mandates shaping office demand?
Federal net-zero audits and tougher carbon standards make certified green buildings more attractive, supporting higher rents and lower vacancies in that segment.
Page last updated on:



