
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 391.07 Billion |
| Market Size (2026) | USD 412.12 Billion |
| Market Size (2031) | USD 535.61 Billion |
| Growth Rate (2026 - 2031) | 5.38 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Asia-Pacific Office Real Estate Market Analysis by 黑料不打烊
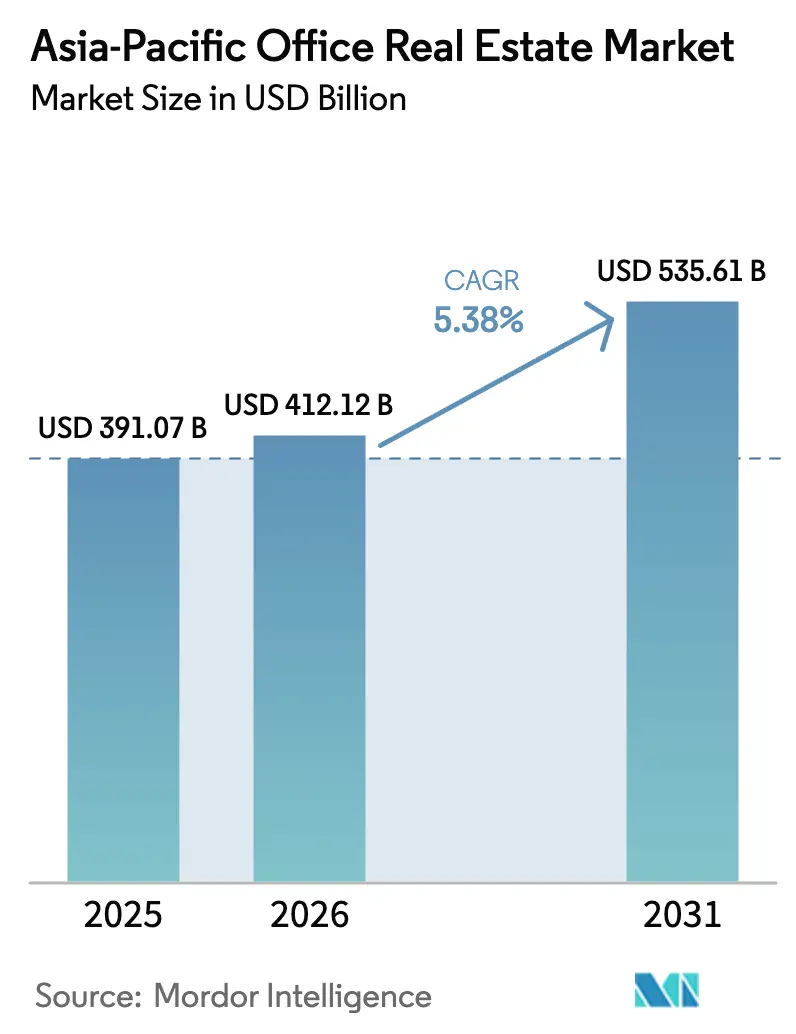
The Asia-Pacific Office Real Estate Market size is projected to expand from USD 391.07 billion in 2025 and USD 412.12 billion in 2026 to USD 535.61 billion by 2031, registering a CAGR of 5.38% between 2026 to 2031.
Growth is anchored in the region’s pivot toward knowledge-economy hubs, widespread adoption of sustainability-certified buildings, and a rental model that still accounts for more than three-quarters of transactional value. Green certification delivers consistent 1-4% rental premiums, encouraging landlords to prioritize WELL, LEED, and Green Mark ratings even as hybrid work keeps per-employee footprints at historically low levels. Institutional emphasis on Grade-A assets and asset-management technologies continues to compress yields in Singapore, Tokyo, and Sydney while offering wider spreads in Jakarta and Mumbai. Forward pipelines remain disciplined because construction-cost inflation in 2024 rose 6-15%, and policy-rate hikes in India, Australia, and Japan lifted borrowing costs for leveraged developers.
Key Report Takeaways
- By business model, rental commanded 77.2% of the 2025 value, while sales transactions are projected to expand the fastest at a 6.71% CAGR through 2031.
- By building grade, Grade-A stock held 64.1% of the 2025 value and is also the fastest-growing category at a 6.35% CAGR through 2031.
- By end use, IT and IT-enabled services accounted for 42.4% of 2025 demand, whereas life sciences led growth with a CAGR above 6.98% to 2031.
- By country, India captured 22.7% of regional value in 2025, while Indonesia records the steepest trajectory at a 7.29% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Asia-Pacific Office Real Estate Market Trends and Insights
Drivers Impact Analysis*
| Drivers | (~) % IMPACT ON CAGR FORECAST | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tech, GCC, and life-sciences expansion in cost-advantaged markets | +1.5% | India, Vietnam, China coastal cities | Medium term (2-4 years) |
| Economic diversification and services growth in India and Southeast Asia sustaining net absorption | +1.2% | India (Bengaluru, Hyderabad, Pune), Indonesia, Vietnam, Philippines | Medium term (2-4 years) |
| Flight-to-quality and green premiums elevating Grade-A demand | +0.9% | Singapore, Tokyo, Sydney, Hong Kong | Medium term (2-4 years) |
| Flexible workspace models supporting hybrid operating patterns | +0.6% | Singapore, Hong Kong, Sydney, secondary India cities | Short term (≤2 years) |
| Data-led asset management improving operating margins | +0.4% | Singapore, Japan, Australia, China Tier-1 markets | Long term (≥4 years) |
| Source: 黑料不打烊 | |||
Economic Diversification and Services Growth In India And Southeast Asia: Sustaining Net Absorption
Global-capability centers added 1.9 million employees across Bengaluru, Hyderabad, and Pune in 2024, and state incentives such as Karnataka’s “Beyond Bengaluru” scheme continue to reduce stamp duty for compliant developers[1]Government of Karnataka, “Beyond Bengaluru Program,” karnataka.gov.in . Jakarta, Ho Chi Minh City, and Manila replicate this pattern with robust population growth and constrained Grade-A supply that keeps vacancy near single digits. Employers favor these metros for deep talent pools and tax perks, which together extend the demand runway well beyond 2028. Consequently, net absorption outpaces new completions in cost-advantaged corridors even while some Tier-1 Chinese submarkets struggle with oversupply. The dynamic signals durable occupier confidence despite the macro-rate environment.
Flight-To-Quality And Green Premiums Elevating Grade-A Demand
More than 51% of regional inventory carried a formal sustainability label in 2024 after Singapore required Green Mark certification for new projects above 5,000 m?[2]Building and Construction Authority, “Green Mark 2021 Framework,” bca.gov.sg . Tokyo and Hong Kong each report green penetration above 90%, and landlords command premiums that vary from 1 % in secondary nodes to 4 % in prime CBDs. For every five square feet of tenants' requests for fully certified assets, only two square feet are presently available, so occupiers lock in longer leases or pre-commit to projects under construction. Tight certified supply accelerates the obsolescence cycle for older buildings and incentivizes capital recycling into retrofit funds. As disclosure mandates tighten across Australia and Japan, green premiums are expected to widen, reinforcing the landlord flight-to-quality thesis.
Tech, GCC, And Life-Sciences Expansion in Cost-Advantaged Markets
Technology firms and captive centers absorbed 44% of India’s third-quarter 2024 leasing, led by million-square-foot campus deals from Cognizant, HCLTech, and Infosys. Microsoft, UBS, and Flutter each secured more than 500,000 ft? in Hyderabad and Bengaluru to capitalize on labor arbitrage and fiscal holidays. Life sciences demand in Hyderabad’s Genome Valley, Singapore’s Biopolis, and Shanghai’s Zhangjiang draws multinationals that need wet-lab infrastructure, pushing pre-let ratios above 60%. Mainland China shows a shift toward consolidated, hyper-efficient campuses driven by the country’s dual-carbon mandate, compressing footprints in secondary nodes. This sector mix raises average rents but introduces cyclical sensitivity to global tech hiring.
Flexible Workspace Models Supporting Hybrid Operating Patterns
Average lease tenor has dropped from 10 years before the pandemic to 3-5 years in 2024 as enterprises embed hybrid schedules. Landlords, therefore, align with operators such as WeWork through management contracts that transfer vacancy risk in exchange for revenue shares. Managed-office penetration reached 12% of Grade-A space in Singapore and Hong Kong by mid-2024, double the 2022 level, and activity-based layouts now allocate only 80-120 ft? per employee, making densification viable. Despite smaller footprints, 70% of firms still require staff to attend at least three days each week, so demand does not collapse; instead, it shifts to flexible floors within premium towers. Owners of traditional long-lease buildings lacking amenity depth face longer downtime between tenants.
Restraints Impact Analysis*
| Restraint | (~) % IMPACT ON CAGR FORECAST | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Elevated financing costs and construction inflation compressing supply economics | -1.1% | Australia, India, Indonesia, Japan | Medium term (2-4 years) |
| Hybrid work and densification reducing per-employee space needs | -0.8% | Australia, Japan, Singapore | Short term (≤2 years) |
| Oversupply and slow permitting for conversions in some CBDs | -0.6% | Guangzhou, Shenzhen, Melbourne | Long term (≥4 years) |
| Source: 黑料不打烊 | |||
Hybrid Work and Densification: Reducing Per-Employee Space Needs
Average allocations fell from 150-200 ft? per employee before 2020 to 100-150 ft? in 2024, a 33% contraction that immediately softens headline demand. Sydney and Melbourne report 30-40% vacancy in older towers as tenants retreat to fewer, amenity-rich floors. Survey data show peak occupancy above 80% in only 43% of monitored buildings, leaving structurally underused stock. Tokyo companies now average 1.3 staff per desk, letting occupiers surrender entire floors while maintaining headcount. Buildings without transit adjacency or wellness features suffer the sharpest occupancy erosion, pressuring rents and reducing asset liquidity.
Elevated Financing Costs and Construction Inflation Compressing Supply Economics
Construction-cost escalation reached 15% in Australia, 12% in India, and 8% in China during 2024, fueled by steel, cement, and labor price spikes. Meanwhile, benchmark policy rates hold at 6.5% in India, 4.35% in Australia, and 0.25% in Japan, increasing interest expense for new projects. Developers in Jakarta and Mumbai paused excavation while renegotiating loan covenants because capitalized yields no longer cleared hurdle rates. Retrofit ambitions are also cool, as payback periods for LEED Gold upgrades now exceed 10 years at prevailing finance costs unless green premiums widen further. Slower pipeline deliveries limit future supply but can delay market equilibrium.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Business Model: Rental Dominance Anchors Institutional Capital
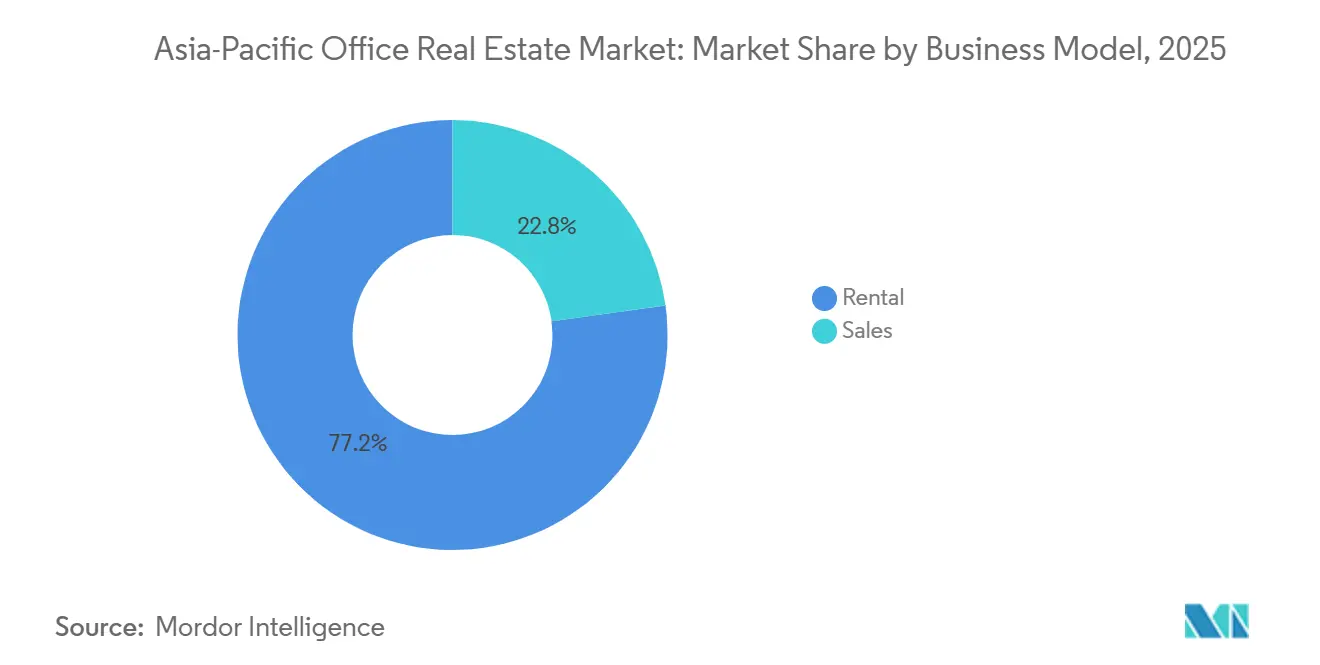
Rental transactions captured 77.2% of 2025 turnover, confirming that the Asia-Pacific office real estate market prefers predictable, lease-backed cash flows. Institutional owners value 5-7-year average lease lengths in India and 3-5-year terms in Southeast Asia that mute near-term revenue volatility. REITs rebalanced USD 3.5 billion of portfolios in 2024, typified by Keppel REIT’s purchase of a 50% interest in Mumbai’s Pinnacle Office Park for SGD 239 million (USD 177 million)[3]Keppel REIT, “Acquisition of Pinnacle Office Park,” keppelreit.com . Sales transactions, only 22.8% by value, are nonetheless forecast to advance at a 6.71% CAGR, led by strata-title deals in Jakarta, where the Golden Indonesia visa encourages offshore ownership. Rental yields compress to 3.0-3.5% in Tokyo and 3.5-4.5% in Singapore, while Mumbai and Jakarta still trade near 8-9.5%, attracting yield-hungry foreign funds despite currency risk.
Core investors continue to chase stabilized portfolios, whereas value-add capital focuses on assets that can be repositioned for flexible workspace or upgraded to higher green certifications. The differential between Grade-A and Grade-B rents widens most in Singapore and Tokyo, encouraging developers to monetize completed buildings outright even as they retain management contracts. Over the forecast horizon, the Asia-Pacific office real estate market size for rental assets is projected to climb steadily, while the sales tranche benefits from opportunistic pricing in select metros.


By Building Grade: Grade-A Assets Command A Rising Premium
Grade-A stock accounted for 64.1% of the 2025 value and leads growth at a 6.35% CAGR through 2031. Green Mark, WELL, and LEED credentials underpin 1-4% rent premiums, and Singapore already requires such certification for every new building over 5,000 m?. Tokyo’s Grade-A vacancy rate printed at only 3% in the third quarter of 2024, the tightest reading regionally. Older Grade-B and Grade-C assets confront rising vacancy, with Guangzhou and Shenzhen above 22% because retrofits cost USD 15-25 per ft? and repay slowly under current interest rates. Many owners re-scope these buildings into managed offices to capture hybrid demand or weigh demolition if conversion economics fail.
The Asia-Pacific office real estate market share of Grade-A stock will continue to expand as tenants chase certified, amenity-rich towers that support environmental targets. In contrast, Grade-C supply may shrink through adaptive reuse or removal, creating a two-tier market where obsolescence accelerates for non-compliant assets. Investors with green-ready pipelines, therefore, command pricing power across almost every CBD.
By End Use: IT & ITES Propel Current Absorption While Life Sciences Accelerate
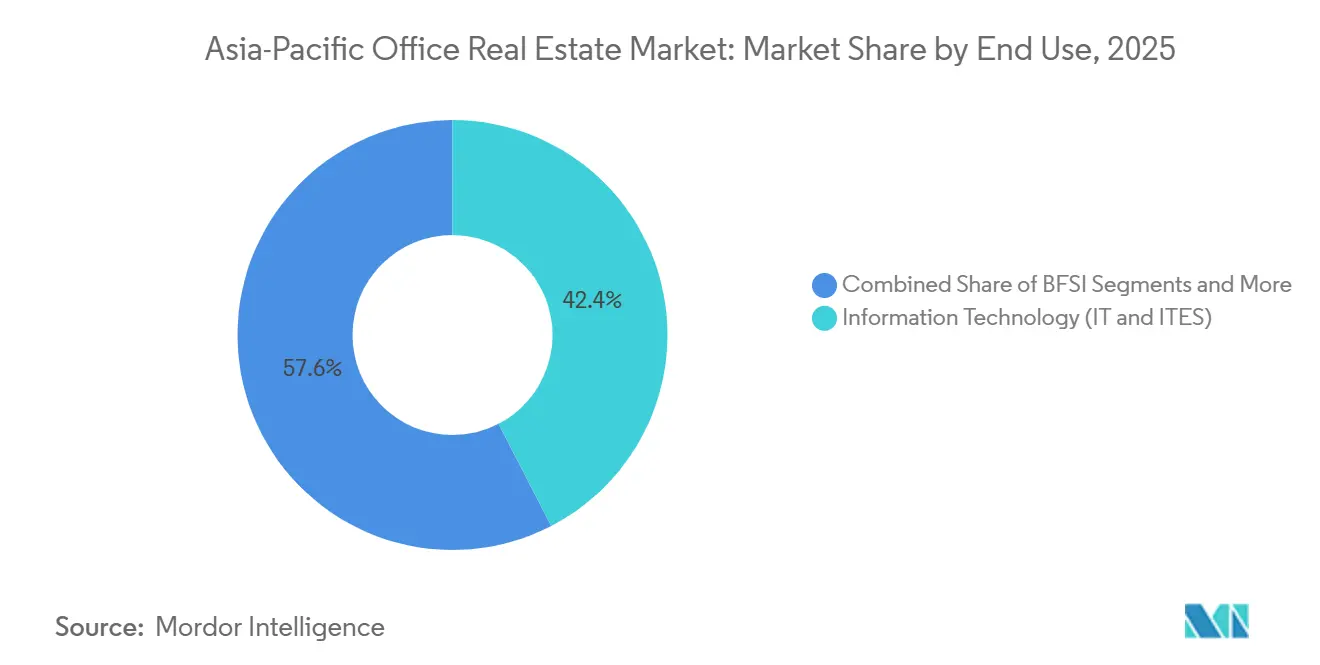
IT and ITES users delivered 42.4% of 2025 take-up, an anchor segment that maintains a 6.98% CAGR through 2031. GCC operators such as HCLTech and Infosys each executed million-square-foot leases in Hyderabad or Bengaluru during 2024, reflecting structural labor cost advantages. Banking and insurance occupiers rationalize back-office space yet still consolidate flagship premises in Singapore, Hong Kong, and Tokyo, leading to steady Grade-A absorption. Life-sciences footprints, while smaller in absolute terms, expand fastest as drug makers lease wet-lab-enabled floors in Genome Valley, Biopolis, and Zhangjiang. This specialty demand pulls average rents higher and supports longer lease tenors of 8-10 years because fit-out investments are capital-intensive.
Retail and conventional energy companies represent a shrinking slice of demand, displaced by e-commerce growth and decarbonization policies. The mix shift toward knowledge-heavy occupiers elevates rental income resilience but increases exposure to tech employment cycles. Nonetheless, the Asia-Pacific office real estate market size linked to technology tenants remains fundamental to absorption in India and Southeast Asia.

Geography Analysis
India’s 22.7% slice of the Asia-Pacific office real estate market rests on large-scale GCC expansion supported by state concessions, deep STEM talent, and rental yields of 7.5-9.0% in Mumbai and Bengaluru. Construction-cost inflation of 8-12% squeezes margins, but pre-leasing in Pune and Chennai stays robust, indicating durable occupier appetite for modern campuses. Telangana’s T-Hub and Karnataka’s “Beyond Bengaluru” accelerate decentralization toward Tier-2 nodes where land costs remain 40-50% below Tier-1 benchmarks, broadening the investable universe.
Indonesia’s trajectory is defined by scarce supply and regulatory liberalization. Jakarta reports 7.4% Grade-A vacancy, the lowest among Southeast Asian capitals, which pushes rents to IDR 400,000-500,000 per m? monthly (USD 25-31 per m?). The Omnibus Law cut project licensing timelines in half, and the Golden Indonesia visa confers 5- to 10-year residency to investors who inject at least USD 350,000, channeling fresh capital into strata-title office floors. Developers such as Autograph Tower and Plaza Office Tower 2 target technology and finance tenants, while offshore REITs absorb stabilized assets priced at 8-9.5% yields.
China, Japan, South Korea, and Australia illustrate diverging fundamentals. Oversupply keeps Guangzhou and Shenzhen vacancy above 22%, and conversion hurdles delay adaptive-reuse rollouts. Tokyo remains undersupplied with only 3% vacancy and continues to attract blue-chip tenants despite Japan’s first rate hike in 17 years. Seoul’s 8.5% vacancy is moderate, with Gangnam rents supported by Samsung, LG, and Hyundai consolidations. In Australia, hybrid work leaves 30-40% vacancy in older CBD towers; however, assets within walking distance of new metro lines trade at meaningful premiums as institutional buyers pivot toward transit-oriented strategies.
Regulatory Landscape
Regulation in Asia-Pacific office real estate increasingly links development rights and asset liquidity to buildability, green performance, and disclosure. Singapore’s Building and Construction Authority (BCA) tightened approval pathways that influence design and procurement, including the Buildability Type Approval route effective April 30, 2026 for larger projects (5,000 square meters or more). The city-state also continues to anchor green compliance through Green Mark requirements for new developments above 5,000 m2. These frameworks, along with occupier-driven standards such as WELL and LEED, reinforce the regional tilt toward certified Grade-A stock, which already earns 1-4% rent premiums in prime CBDs.
Other markets are using policy levers to accelerate redevelopment and capital formation. Hong Kong’s Lands Department is rolling out the "Pay for What You Build" pilot scheme effective June 1, 2026, changing how land premium is assessed and affecting project feasibility and redevelopment sequencing. The Hong Kong 2026-27 Budget also earmarked funding for the Construction Innovation and Technology Fund (HKD 1.4 billion). In India, regulatory frameworks enabling Small and Medium REITs broaden pathways for fractionalized and smaller-ticket office portfolios, while Thailand’s Building Energy Code (BEC 2021) and sustainable finance taxonomies add another layer of compliance signaling reflected in tenant selection and lender underwriting.
Value Chain Analysis
The office real estate value chain in Asia-Pacific starts with land sourcing and entitlements, moves through planning and design (architects and engineers), construction and fit-out (contractors, MEP, and building materials and equipment), and then leasing and marketing (brokerage and workplace strategists). It ends with asset management and capital markets, including REITs, institutional funds, lenders, and transaction advisors. In 2025, office leasing activity across 11 key regional markets reached 9.8 million square meters, keeping demand for brokerage, tenant-representation, and workplace delivery services high and increasing focus on speed-to-occupancy for pre-leased Grade-A projects.
Two cost and performance constraints shape how value is captured across the chain. Construction-cost pressure in developed markets raises the hurdle for new development and pushes developers toward standardized specifications, repeatable components, and productivity-led procurement. This raises the influence of large contractors, prefab suppliers, and engineering firms that can deliver predictable outcomes. Separately, occupier demand for energy-smart buildings, including localized energy solutions and improved building controls, shifts value toward retrofit specialists, smart BMS providers, and asset managers using data-led operations to protect NOI, especially as hybrid work increases churn and compresses lease tenors to 3-5 years in several markets.
Competitive Landscape
The Asia-Pacific office real estate market features moderate fragmentation, with global advisories - JLL, CBRE, Cushman & Wakefield, Colliers, Knight Frank, and Savills - competing for brokerage and consulting mandates. JLL deepened PropTech capabilities in 2024 by acquiring a Mumbai-based software integrator that supplies tenant-experience and energy-dashboard solutions. CBRE simultaneously launched a region-wide ESG advisory, guiding occupiers through carbon-reduction roadmaps and green certifications. Cushman & Wakefield partnered with WeWork to operate enterprise-grade flexible suites in Singapore, Hong Kong, and Tokyo, diversifying landlord revenue streams.
Developers cluster into two strategic camps. CapitaLand, DLF, and Keppel REIT execute build-to-core plays—constructing Grade-A towers, leasing them to stabilization, and holding them for income. Mitsubishi Estate, Henderson Land, and China Resources Land focus on prime CBD redevelopment, integrating retail and residential components to capture mixed-use premiums. REITs rebalanced USD 3.5 billion of holdings in 2024, selling suburban assets to fund CBD acquisitions in Mumbai, Singapore, and Tokyo, reinforcing the flight-to-quality narrative.
Whitespace opportunities gravitate toward Tier-2 Indian cities, supply-constrained Southeast Asian capitals, and retrofit programs in Chinese CBDs if permitting relaxes. PropTech disruptors providing occupancy analytics, predictive maintenance, and tenant-engagement apps consistently cut operating expense ratios by up to 200 basis points, a gap that investors increasingly monetize. Regulation also shapes competition: Singapore’s tightened Green Mark rules and China’s dual-carbon timetable favor landlords with certified portfolios and embedded smart-building infrastructure, while owners of outdated stock face costly upgrades or accelerated depreciation.
Asia-Pacific Office Real Estate Industry Leaders
JLL
CBRE
Cushman & Wakefield
Colliers
Knight Frank
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
A near-term opportunity set centers on upgrading and repositioning existing stock rather than adding new supply, particularly where older CBD towers face structurally lower utilization from densification. Markets showing visible obsolescence, including parts of Australia and select Chinese CBDs with elevated vacancy, create room for adaptive reuse, management-to-green strategies, and conversion programs where permitting allows. This aligns with the observed gap in certified inventory, where tenant demand for fully certified space continues to outstrip availability in many prime nodes. Developers and owners that can deliver WELL, LEED, and Green Mark-aligned refurbishments and amenity upgrades have a clearer pathway to capturing the 1-4% rental premium tied to green certification.
Capital-formation and platform opportunities are also expanding as investment structures and advisory capabilities deepen across the region. India’s move toward enabling Small and Medium REIT frameworks supports smaller stabilized office portfolios and mixed city strategies, while Indonesia’s liberalization and investor programs, including the Golden Indonesia visa referenced in market activity, keep attention on strata-title and yield-driven acquisitions in Jakarta and secondary corridors. On the demand side, continued build-out by IT and ITES users and the rise of life-sciences clusters, such as Genome Valley, Biopolis, and Zhangjiang, support specialized office formats including wet-lab-enabled floors and managed-office suites. This reinforces whitespace for operators and landlords that can standardize fit-outs, shorten delivery cycles, and pair flexible leasing with data-led asset management.
Recent Industry Developments
- July 2026: LaSalle (a JLL subsidiary) acquired the 14-storey Zenith Minami Shinjuku office building in Tokyo from Hines. The acquisition expands Tokyo's CBD presence and supports a broader investment strategy in prime markets. It enhances portfolio quality and occupier appeal in the core market.
- May 2026: Lendlease secured a new capital partner for The Exchange TRX development in Malaysia, acquiring 40% interest in the retail mall and 60% interest in the office asset. Malaysia mixed-use development milestone is underscored by this financing progress. Capital structure secured for flagship Exchange TRX project; potential impact on local office and retail dynamics.
- May 2026: JLL reported Asia Pacific commercial real estate investment volumes of USD 47.0 billion for Q1 2026, up 31% YoY. APAC investment momentum in office real estate reflects strengthening market activity in the region. Signals strong funding environment and demand for Grade-A assets in the region.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the market is defined as the total value generated from office real estate across Asia-Pacific, covering owner-occupied transactions and leased office space activity, captured in USD terms across key countries in the region.
Scope exclusions: Excludes residential, retail, industrial, and hotels, and also excludes coworking-only offerings when they are not contracted as office real estate space.
Segmentation Overview
- By Business Model
- Sales
- Rental
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure for Asia-Pacific and to keep the country level picture consistent across time. We relied on public indicators such as GDP and employment by sector, inflation and interest rate trends, and urban development pipelines, which are closely linked to office demand and pricing.
For office specific signals, we referred to non-paywalled sources such as national statistics offices and central banks (for macro inputs), city planning and building permit portals (for pipeline cues), and publications from groups such as the Asian Development Bank, BIS, and the World Bank for comparable regional data series. We also reviewed listed company filings, investor presentations, stock exchange disclosures, and reputable press coverage to understand leasing momentum, asset transactions, and shifts in tenant preferences. Where needed, paid subscriptions for company financials and intelligence, news and financials, and patent databases were used to cross-check company exposure and major project announcements. The desk sources mentioned here are illustrative only, and many other public documents and datasets were also used for collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on validating what desk sources cannot fully show, especially how rents, vacancy, incentives, and take-up are moving across major Asia-Pacific office cities. We spoke with a mix of owners, developers, brokers, asset managers, and large occupiers, and we kept the inputs balanced across the region so country level assumptions could be checked before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 39% | CXOs: 15% |
| Mid tier: 45% | Functional/Unit leaders: 34% |
| Smaller Players: 16% | Managers: 51% |
Market-Sizing & Forecasting
Market sizing was built using a top-down approach where office demand pools and value are reconstructed from country and city indicators, and then adjusted to reflect office specific cycles. Key inputs included net absorption and vacancy movement, new supply completions, Grade A and Grade B rent direction, tenant mix shifts (such as IT and ITES and BFSI footprint changes), and broader financing conditions that influence sales activity.
To keep totals realistic, the outputs were corroborated through selective bottom-up approximations, such as sampled rent per square foot multiplied by occupied stock, and channel checks on transaction activity across core cities, which are then used to correct outliers. Where data gaps existed in smaller markets, proxy assumptions were applied using comparable city benchmarks and then pressure-tested with primary inputs.
Forecasting relied mainly on scenario analysis, since office markets can swing with policy rates, work style patterns, and supply timing. Assumptions for rent growth, vacancy normalization, and supply delivery risk were aligned to the consensus range obtained from interviews, and the resulting country forecasts were rolled up to the regional total.
Data Validation & Update Cycle
Validation was done through multiple passes, starting with basic checks on unit consistency, currency conversions, and year-on-year variance, followed by cross-checks against independent signals like city leasing releases, pipeline announcements, and investment volume trends. When a market output looked inconsistent with what is seen on the ground, we revisited the drivers, rechecked desk inputs, and re-contacted select respondents to clarify the assumption.
Before sign-off, the model and narratives go through an internal analyst review so key logic steps can be traced back to the underlying drivers. The report is refreshed annually, and interim updates are made when material events occur, such as sharp rate changes, major regulatory moves, or large supply shocks. Right before delivery, a final refresh pass is completed so clients receive an updated view based on the latest available information.
黑料不打烊's Asia Pacific Office Real Estate Market Size Compared Against Other Published Estimates
Published market values for Asia-Pacific office real estate can differ across sources because the scope choices are not always the same, and the conversion from local market metrics into a single USD value is handled in different ways. Differences also come from how quickly a dataset is updated and whether assumptions were rechecked with local market participants before the figures were finalized.
The main gap comes from whether the estimate counts the full asset value transacted and leased across sales and rentals, and how currency timing is applied to country roll-ups, where 黑料不打烊 treats the market as a value model built from rental and sales activity by country, and then revalidated using rent, vacancy, and supply pipeline checks before regional totals are locked.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 391.07 B (2025) | |
| Global Brokerage Research A | USD 48.80 B (2024) | Measures office investment transaction volume for a single year, which excludes leased-space value flows and does not represent the full office real estate market value across the region. |
| Industry Research Desk B | USD 450.00 B (2026) | Uses a broader definition that can inflate totals by mixing office with adjacent commercial property activity in some countries, and may apply simplified rent and FX assumptions without city-level vacancy and supply reconciliation. |
The table shows that the spread is mainly explained by what each source counts. Some focus on investment volumes, while others blend in adjacent commercial categories. By keeping sales and rental activity within an office-only scope and checking outputs against practical indicators like vacancy, net absorption, and delivered supply, the final number remains traceable to clear drivers and repeatable steps.


Key Questions Answered in the Report
How is hybrid work reshaping leasing strategy in Asia-Pacific?
The market is valued at USD 412.12 billion in 2026 and is projected to reach USD 535.61 billion by 2031.
How fast is Grade-A inventory growing across the region?
Grade-A stock is expanding at a 6.35% CAGR as occupiers target certified, energy-efficient buildings.
Which country offers the highest rental yields for premium office assets?
Jakarta and Mumbai provide 8-9.5% gross yields, outperforming Singapore and Tokyo where yields hover below 4%.
Why are green building certifications important for landlords?
Certified buildings achieve 1-4% rental premiums and higher tenant-retention rates, offsetting upfront retrofit costs.
How is hybrid work reshaping leasing strategy in Asia-Pacific?
Enterprises shorten lease terms to 3-5 years and favor flexible suites, prompting landlords to partner with workspace operators.
Where are investors finding the fastest growth opportunities?
Indonesia leads with a 7.29% CAGR, while Tier-2 Indian cities attract capital through state incentives and strong GCC demand.
Page last updated on:



