
Tissue Paper Converting Machines Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 1.67 Billion |
| Market Size (2031) | USD 1.98 Billion |
| Growth Rate (2026 - 2031) | 3.47 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
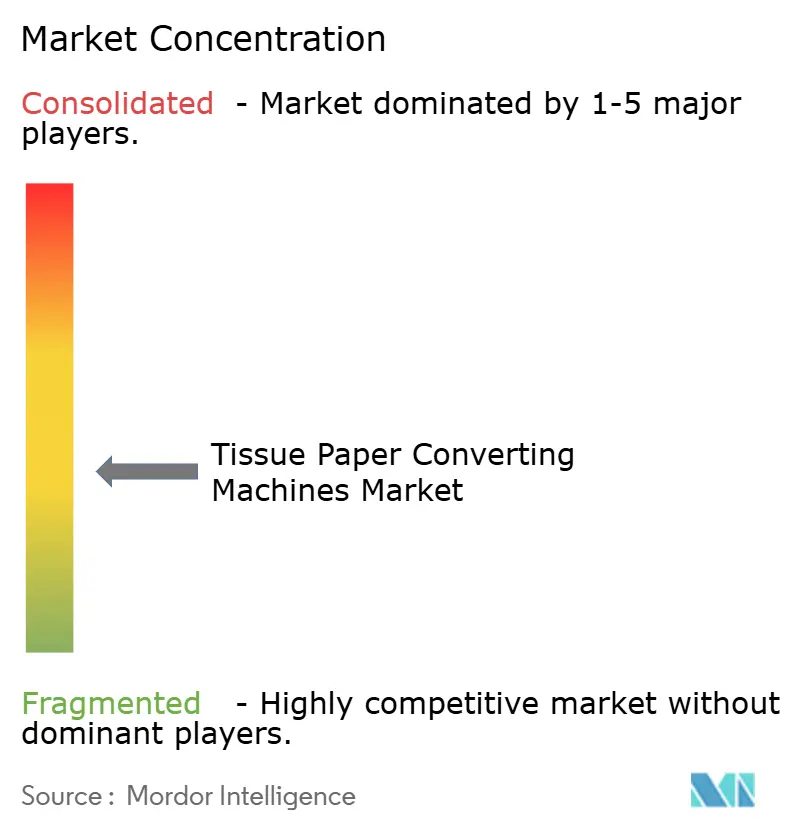
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Tissue Paper Converting Machines Market Analysis by 黑料不打烊
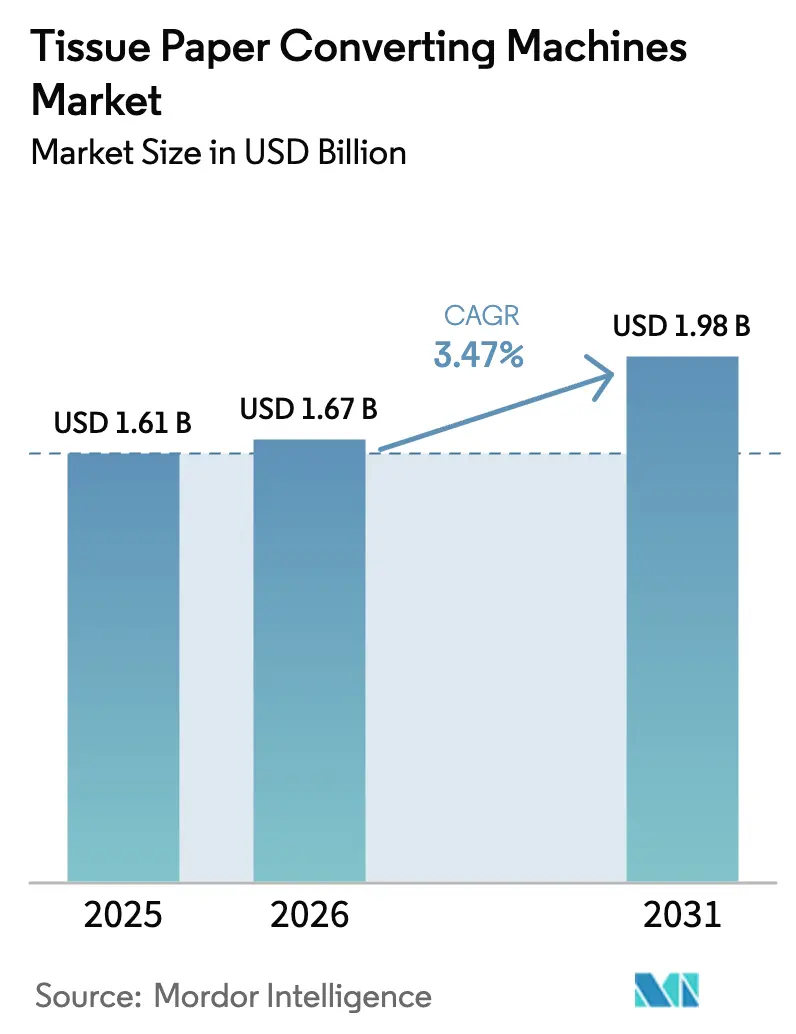
Tissue paper converting machines market size in 2026 is estimated at USD 1.67 billion, growing from 2025 value of USD 1.61 billion with 2031 projections showing USD 1.98 billion, growing at 3.47% CAGR over 2026-2031. Consistent consumption of tissue products, steady equipment replacement cycles, and rising factory automation keep demand on a clear upward path. Automatic technology already accounts for 65.67% of global installations, reflecting an industry‐wide shift toward unmanned, data-driven production lines. Sustainability targets further accelerate upgrades as converters adopt energy-efficient dryers, induction-heated Yankee cylinders, and low-waste embossing units. Digital transformation rounds out the growth narrative; predictive-maintenance platforms and digital-twin models now inform purchasing decisions as much as mechanical design.
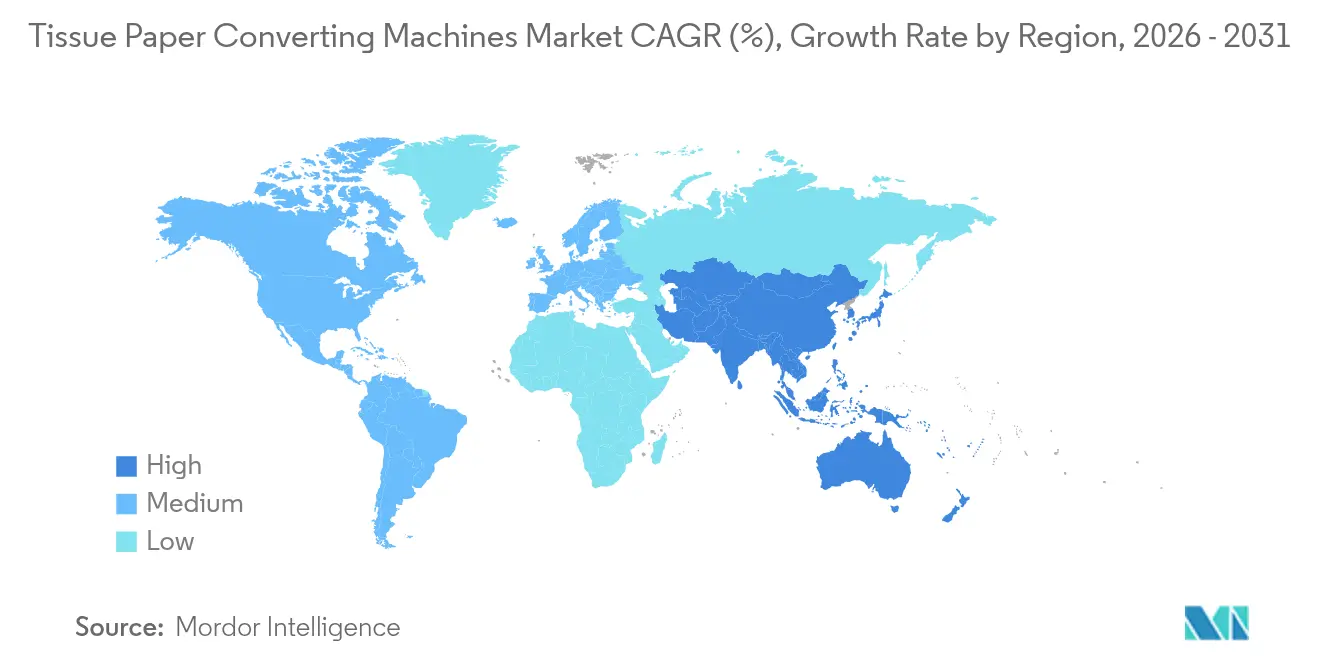
Key markets show different but complementary trajectories. North America held 40.56% share in 2024, anchored by large-scale modern mills and strong brand loyalty. Asia-Pacific delivers the fastest rise at 6.78% CAGR to 2030 as hygiene awareness and converting capacity expand across China, India, and Southeast Asia. Machine-type preferences also shift: toilet-roll lines still lead with 45.34% share, yet kitchen-roll systems advance at 7.29% CAGR on the back of premium kitchen-towel demand. High-speed lines of at least 800 m/min already command 52.34% share and grow 5.49% a year as converters chase lower unit costs.
Key Report Takeaways
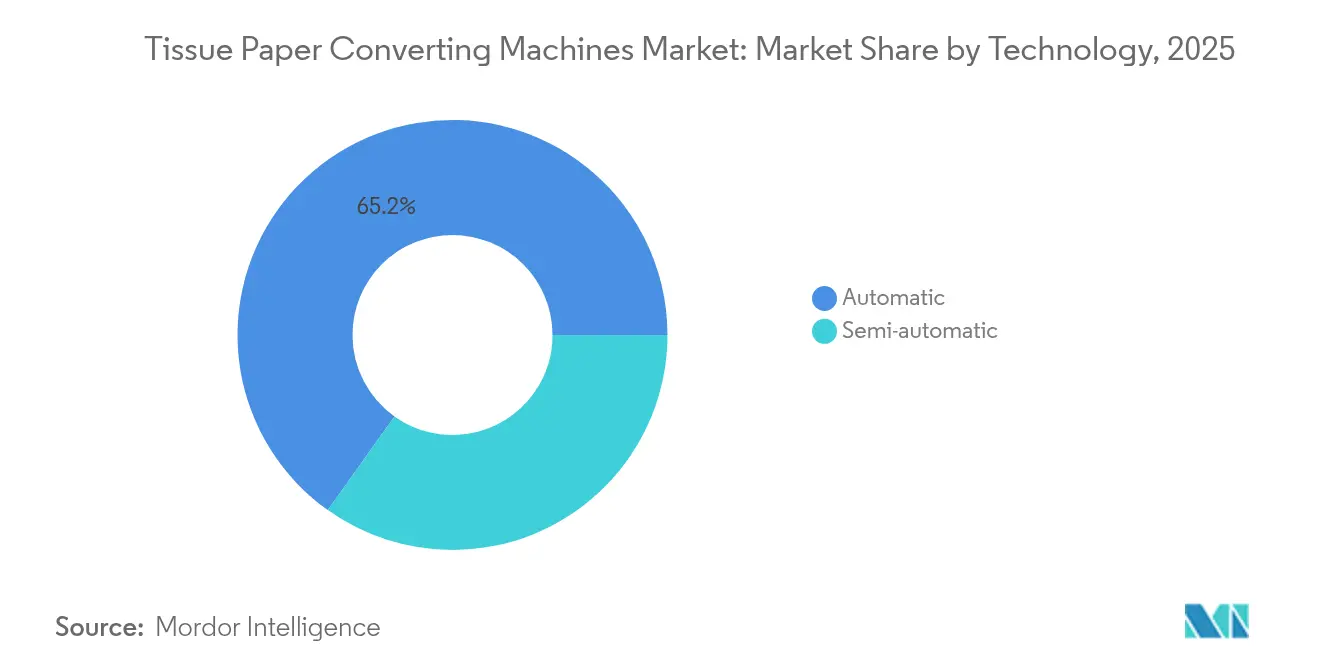
- By technology, automatic lines captured 65.15% of tissue paper converting machines market share in 2025 while expanding at a 4.66% CAGR through 2031.
- By machine type, toilet-roll equipment led with 44.92% revenue share in 2025; kitchen-roll systems are forecast to move ahead at a 7.12% CAGR to 2031.
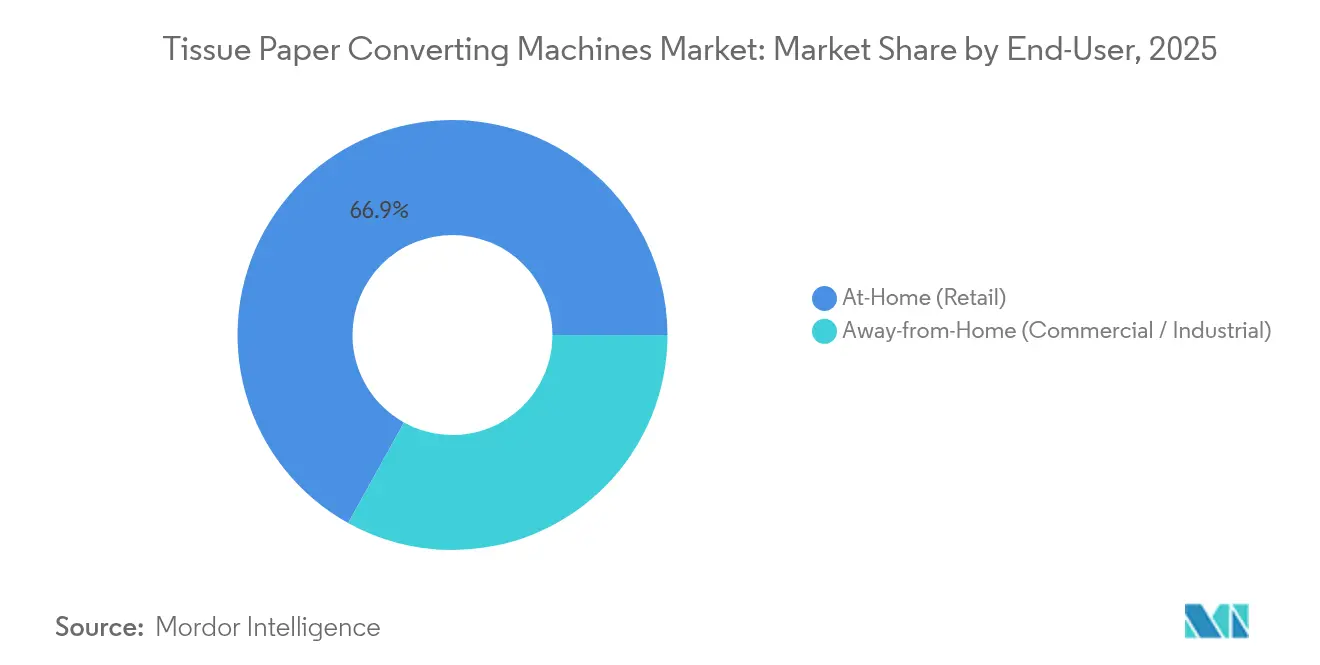
- By end-use, the At-Home segment accounted for 66.93% of the tissue paper converting machines market size in 2025, whereas Away-from-Home demand shows the fastest growth at 4.28% through 2031.
- By production speed, high-speed lines (≥800 m/min) held 51.78% share of the tissue paper converting machines market size in 2025 and will lift output at a 5.41% CAGR to 2031.
- By geography, North America dominated with 40.12% share in 2025, yet Asia-Pacific registers the highest 6.63% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Tissue Paper Converting Machines Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising global tissue consumption and hygiene awareness | +0.8% | Global, with accelerated adoption in Asia-Pacific and MEA | Medium term (2-4 years) |
| Growing trend of automation in tissue converting | +1.2% | North America and Europe core, expanding to Asia-Pacific | Long term (≥ 4 years) |
| Sustainability-oriented innovations in converting tech | +0.6% | Europe leading, North America following, Asia-Pacific emerging | Long term (≥ 4 years) |
| Digital-twin and IoT boosting OEE | +0.4% | Developed markets initially, global rollout by 2028 | Medium term (2-4 years) |
| Surge in private-label AfH short-run demand | +0.3% | North America and Europe primarily | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Rising Global Tissue Consumption and Hygiene Awareness
Sustained post-pandemic hygiene priorities keep tissue volumes on an upward curve. Institutional buyers now request premium converting lines that can handle softer substrates, deeper embossing, and rapid changeovers for differentiated branding.[1]Simon Matthis, “Toscotec Launches New Concept Machine for a More Sustainable Structured Tissue,” Pulpaper News, pulpapernews.com New energy-efficient machines such as Toscotec’s INGENIA cut energy use by 35% yet maintain through-air-dried quality, a combination that unlocks both cost and environmental gains. Commercial kitchens and food-service chains fuel steady orders for kitchen-roll formats with higher absorbency standards, pushing converters toward multi-emboss units and in-line ply bonding. Product mix complexity encourages factories to add flexible unwind stands and programmable knife systems, enabling them to shift between retail and institutional SKUs without long downtime. This sustained demand backdrop undergirds the tissue paper converting machines market and encourages continued equipment modernisation despite moderate headline growth.
Growing Trend of Automation in Tissue Converting
Automation now shapes competitive advantage. Automatic systems already represent two-thirds of installed capacity and grow faster than the broader tissue paper converting machines market. TAPPI’s Tissue 101 and Tissue 202 courses highlight the sector’s commitment to up-skilling operators for such lines.[2]TAPPI, “Registration Now Open: Essential In-Person Tissue Training Courses,” tappi.org BW Converting’s MIAC 2024 showcase introduced high-speed interfolders and coreless rewinding modules, proving that automation opens new product avenues. Fully integrated drives, servo knife positions, and automatic roll-handling robots shorten changeovers and trim labor costs while improving safety. Factories without such technology risk falling behind on cost, quality, and delivery reliability, prompting a replacement wave that keeps the tissue paper converting machines market expansion intact.
Sustainability-Oriented Innovations in Converting Tech
Regulators tighten energy rules and brand owners pledge Scope 3 emission cuts. Equipment builders have responded with electric induction Yankee dryers that eliminate direct fossil fuel use and lower dryer shell temperatures, thereby improving safety. Valmet’s Advantage QRT technology demonstrates 45% energy reduction while preserving softness and bulk.[3] Valmet, “Valmet and K?rber Joint Venture Advances Digital Offering,” valmet.com Upcoming efficiency standards for electric motors from 2027 will reinforce demand for such upgrades. Early adopters secure lower operating costs and favorable ESG profiles, spurring peers to accelerate investment and sustaining healthy order books for the tissue paper converting machines market.
Digital-Twin and IoT Boosting OEE
Data frameworks now accompany most capital orders. Valmet’s 2024 acquisition of FactoryPal embeds AI analytics into everyday production decisions, helping mills cut unplanned downtime and lift overall equipment effectiveness. ANDRITZ’s Metris platform lets operators model line performance virtually, tweak recipe settings, and then deploy the optimal code to the machine. Remote dashboards reset the operating baseline toward predictive rather than reactive maintenance. Converters extract greater capacity from existing assets, thereby justifying incremental digital retrofits alongside major mechanical rebuilds. This use of digital twins grows in tandem with the tissue paper converting machines market as new lines ship with edge-ready sensors and secure cloud gateways as standard.
Restraints Impact Analysis of Tissue Paper Converting Machines Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capex for greenfield converting plants | -0.5% | Global, particularly impacting emerging markets | Medium term (2-4 years) |
| Volatile pulp and energy prices | -0.3% | Global, with regional variations in energy costs | Short term (≤ 2 years) |
| Shortage of skilled operators for advanced lines | -0.4% | Developed markets primarily, spreading to Asia-Pacific | Medium term (2-4 years) |
| Stricter noise and energy rules on machinery | -0.2% | Europe leading, North America following | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High Capex for Greenfield Converting Plants
A new integrated mill demands hundreds of millions of dollars. First Quality Tissue recently earmarked USD 984 million for two Thru-Air-Dried lines plus converting halls in Ohio. Even for established firms, such sums dictate lengthy payback horizons. Smaller companies often forgo large-scale builds and instead upgrade existing lines, which tempers incremental capacity growth in the tissue paper converting machines market. Interest-rate swings further complicate investment timing, especially in emerging regions where credit costs stay elevated.
Volatile Pulp and Energy Prices
Fluctuations in pulp and power prices compress converter margins and can delay machinery orders. Norske Skog’s multibillion-krone pulp project underscores the industry’s drive to secure raw-material self-sufficiency and insulation from price swings. Energy-intensive converting lines face the same volatility; high grid prices make a compelling case for energy-saving drives but can postpone full-line replacements until cost pressures ease, dampening near-term machinery shipments.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Tissue Paper Converting Machines Market Segment Analysis
By Technology:
Automatic Lines Redefine OperationsAutomatic lines hold 65.15% of tissue paper converting machines market share in 2025 and expand at a 4.66% CAGR through 2031. These smart systems integrate servo drives, robotic roll handling, and camera-based defect detection. Their superior throughput and lower labor-to-output ratio lift factory productivity, helping purchasers offset higher sticker prices over the asset life. Semi-automatic units remain relevant to niche converters needing flexibility at modest capex, especially in developing economies where wage structures still favor manual intervention.
Advanced automation also provides the foundation for digital overlays. FactoryPal, now majority-owned by Valmet, feeds real-time data from automatic lines into AI models that propose set-point changes for uptime improvement. As more converters upgrade, the tissue paper converting machines market size for fully automatic solutions is projected to expand steadily, reinforcing the technology’s dominant status.


By Machine Type:
Kitchen-Roll Systems AccelerateToilet-roll lines remain the volume backbone, accounting for 44.92% of the tissue paper converting machines market size in 2025. Yet kitchen-roll lines post the strongest 7.12% CAGR, reflecting consumer preference for thicker kitchen towels and heightened cleaning routines in food-service outlets. Embossing-pattern flexibility and ply bonding quality now influence purchase decisions more than raw speed, spurring OEMs to offer rapid-change print and emboss cassettes.
Folded-tissue and paper-napkin lines serve institutional catering, airlines, and hospitality. Although these segments grow slower, quick pack count changeovers and inline folding accuracy retain importance. OEMs developing multi-format platforms attract buyers aiming to amortise capex across diversified product portfolios, strengthening competition inside the tissue paper converting machines market.
By End-Use Sector:
Commercial Demand Gains PaceRetail At-Home consumption supplies 66.93% of total sales. Growth is steady but less dynamic than in prior years as penetration nears parity in developed economies. In contrast, Away-from-Home demand advances at a 4.28% CAGR. Institutional customers need dispensable hand towels, jumbo rolls, and logo-printed napkins delivered in smaller, more frequent batches. Converters therefore invest in modular unwind decks, automatic tail gluing, and integrated packers that cater to varying sheet counts without long stops.
This segmental divergence means factories often configure hybrid layouts: high-speed toilet tissue assets for core retail volumes and flexible finishing cells for AfH custom jobs. Such hybridisation adds floor-space efficiency and helps maintain balanced utilisation, supporting sustainable growth of the tissue paper converting machines market.
By Production Speed:
High-Speed Lines DominateLines rated at ≥800 m/min command 51.78% share of installations and post a 5.41% CAGR. They drive margin optimisation through higher throughput per shift and better energy per tonne metrics when paired with low-friction drivetrains. Toscotec’s INGENIA reaches 2,000 m/min while cutting energy consumption by one-third, an illustration of technology catching efficiency and speed in one design.
Medium-speed and low-speed lines retain roles where product complexity outweighs volume, for example in multi-ply facial tissues with complex lotions or scents. A two-tier machinery strategy allows converters to respond flexibly to market swings and supports the overall resilience of the tissue paper converting machines market.
Geography Analysis
North America Tissue Paper Converting Machines Market
North America led the tissue paper converting machines market with 40.12% share in 2025. Recent commitments such as Kimberly-Clark’s USD 2 billion multiyear upgrade program and First Quality Tissue’s nearly USD 1 billion Thru-Air-Dried expansion illustrate continuous reinvestment in advanced assets. Retrofit activity also remains robust as mills pursue energy savings and digital dashboards to counter tight labor pools. Mature demand limits headline growth but underpins a reliable service and upgrade market for OEMs.
APAC Tissue Paper Converting Machines Market
Asia-Pacific represents the principal growth engine with a forecast 6.63% CAGR to 2031. China’s converters scale quickly, ordering European high-speed lines to raise domestic quality standards. Regional suppliers such as Baosuo and Dalian Mach provide cost-efficient alternatives, intensifying competition and broadening equipment access. Rising middle-class incomes raise per-capita tissue use, while government hygiene campaigns spur institutional consumption. These factors together promise the strongest absolute gains for the tissue paper converting machines market across all regions.
Europe Tissue Paper Converting Machines Market
Europe balances technology leadership with strict sustainability codes. Italian brands OMET, Maflex, and K?rber Tissue keep market clout by coupling mechanical performance with noise and energy compliance. Valmet’s joint venture with K?rber on digital services signals further innovation clustering in Europe. Although demand volumes rise modestly, premium equipment pricing and high aftermarket spend make Europe strategically important for technology diffusion across the global tissue paper converting machines market.

Regulatory Landscape
Regulation affecting tissue paper converting machines is mainly shaped by cross-industry rules on machinery safety, workplace exposure, and environmental performance, which influence how new converting lines are designed, installed, and operated. In Europe, CE marking requirements under the Machinery Directive/Regulation framework and harmonized safety standards affect guarding, emergency stops, and control-system design, while noise-control and energy-consumption compliance increasingly show up in equipment specifications for large projects such as Metsa Tissue's Future Mill in Mariestad, Sweden, which has procured complete converting lines and packaging solutions.
Environmental policy pressure is also turning into procurement requirements for energy-efficient drives and lower-emission site utilities in integrated tissue investments that include downstream converting. Examples include Valmet deliveries that bundle papermaking, converting equipment, and site utilities such as a biomass boiler for Suzano in Aracruz, Brazil, and multi-line capacity expansions such as Faderco Group's project in Algeria, where suppliers are positioned to meet customer ESG requirements through higher-efficiency machinery and digital condition-monitoring packages that support documented operational performance.
Competitive Landscape
The sector shows moderate concentration. Top European OEMs—Valmet, OMET, K?rber Tissue, Toscotec, and A.Celli—combine long pedigrees with deep application expertise. Their portfolios span high-speed rewinders, embossing units, and turnkey stock-preparation systems. Asian entrants such as Baosuo, Jin Sung Ent, and Dalian Mach gain share in mid-speed and semi-automatic categories by leveraging cost advantages and shorter lead times, especially within domestic Asia-Pacific orders.
Strategic differentiation now revolves around digital readiness and sustainability credentials. Valmet’s FactoryPal acquisition embeds AI into production optimisation, a service model rather than pure hardware sale. Toscotec’s electric Steel Yankee Dryer points to process breakthroughs that reduce carbon intensity while elevating safety. Joint ventures, tech swaps, and licensing deals accelerate innovation dissemination and keep competitive dynamics fluid.
Service contracts, spare-parts logistics, and operator training increasingly shape long-term customer allegiance. OEMs with globe-spanning service hubs secure renewal orders and recurring revenue streams, fortifying their positions in the tissue paper converting machines market. Market consolidation remains possible as capital intensity rises and smaller factories seek partners for next-generation lines.
Tissue Paper Converting Machines Industry Leaders
C.G. Bretting Manufacturing Company, Inc.
Valmet Oyj
9.Septembar Tissue Converting
Serv-o-Tec GmbH
SDF Schnitt-Druck-Falz Spezialmaschinen GmbH
- *Disclaimer: Major Players sorted in no particular order
Tissue Paper Converting Machines Market Companies Covered in this Report
- C.G. Bretting Manufacturing Company Inc.
- Valmet Oyj
- 9. Septembar Tissue Converting
- SERV-O-TEC GmbH
- SDF Spezialmaschinen GmbH
- Zambak Kagit
- OMET Srl
- Kawanoe Zoki Co. Ltd
- MTorres Dise?os Industriales S.A.U
- Baosuo Paper Machinery Manufacture Co. Ltd
- A.Celli Paper SpA
- United Converting Tissue SRL
- Futura SpA
- Paper Converting Machine Company (PCMC)
- Fujian TMX Machinery Mfg. Co. Ltd
- Chan Li Machinery Co. Ltd
- Unimax Group Engineering & Development Corp.
- ICM Makina
- Gambini SpA
- K?rber Tissue (K?rber Solutions)

Market Opportunities and Future Outlook
Opportunities show up most clearly where tissue producers are running large, integrated modernization and capacity projects that link papermaking with downstream converting and packaging, which supports demand for turnkey delivery, commissioning, and lifecycle services. Valmet's project pipeline points to this shift, including converting line orders tied to the Metsa Tissue Future Mill in Mariestad, Sweden, and tissue-line expansions such as Faderco Group in Algeria, alongside orders supporting capacity additions in the United States and Indonesia; these programs raise the value of suppliers that can provide integrated automation, digital services, and operator training rather than standalone machines.
A second area is retrofit-led upgrading of installed converting assets to reduce energy use and stabilize output quality, aligned with converters' sustainability targets and tightening site-level requirements on noise and power consumption. With automatic technology already representing 65.15% of global installations in 2025, OEMs and integrators have room to sell add-on automation, digital monitoring, and packaging integration to semi-automatic fleets, particularly for Away-from-Home short-run production where fast changeovers and consistent pack quality support private-label and institutional purchasing needs.
Recent Industry Developments in Tissue Paper Converting Machines Market
- June 2026: 9.Septembar published technical content detailing the tissue converting process for napkin production. The release highlights process insights that can guide equipment choices and efficiency improvements in converting lines. This supports ongoing knowledge sharing in the napkin segment and helps speed adoption of optimized line configurations.
- October 2025: Valmet Oyj announced an order for an Advantage ThruAir tissue line for Sofidel America to be installed at an undisclosed facility with startup scheduled for the second quarter of 2028. The engagement supports Sofidel's capacity to meet growing demand in premium tissue products. The project also reflects continued modernization of U S based converting operations and advances digital and energy efficient line technology.
- January 2025: Valmet Oyj announced agreement to deliver a third Advantage ThruAir Drying tissue machine and associated converting lines to Irving Consumer Products in Macon, Georgia, USA, with startup planned for 2027. The addition expands Irving's tissue production footprint to support rising domestic demand. The deal further reflects Valmet's role in expanding automated, high productivity lines within North America.


Tissue Paper Converting Machines Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers equipment used to convert parent tissue reels into finished tissue formats through steps like unwinding, embossing, perforation, rewinding, and cutting, including integrated lines and key modules sold for converting operations.
Scope exclusions: We exclude tissue paper raw material production machinery (pulping, papermaking, and tissue machines), and we also exclude downstream packaging-only equipment unless it is sold as part of a converting line.
Segments Covered in This Report
- By Technology
- Automatic
- Semi-automatic
- By Machine Type
- Toilet-Roll Converting Lines
- Kitchen-Roll Converting Lines
- Folded-Tissue Converting Lines
- Paper-Napkin Converting Lines
- Stand-alone Systems
- By End-Use Sector
- At-Home (Retail)
- Away-from-Home (Commercial / Industrial)
- By Production Speed
- High-speed Lines (greater than 800 m/min)
- Medium-speed Lines (400-799 m/min)
- Low-speed Lines (less than 400 m/min)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to map the industry structure and build the first set of volume and pricing assumptions for converting equipment. Public sources that help with foundational context include trade and production statistics from sources such as UN Comtrade, manufacturing indicators from sources such as the US Census Bureau and Eurostat, and macro and industrial series from sources such as the World Bank and OECD.
We also reviewed sources that describe tissue capacity additions, capital spending themes, and technology upgrades, using company annual reports, investor presentations, press releases, and association materials such as TAPPI publications and event presentations. Where relevant, patent databases were used to sanity-check the pace of innovation in automation features, energy saving systems, and product format flexibility. The list above is illustrative only, and many other public and paid sources were also used for data collection, cross-checks, and clarification.
Primary Interviews and Surveys
Primary work was used to verify what is actually being bought and installed, and how pricing changes with speed, automation level, and included modules. We spoke with a mix of machine suppliers, component partners, converters, and plant engineering and procurement roles across major demand regions, so gaps from desk research could be closed and assumptions could be aligned with real project timelines.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 28% | CXOs: 12% | APAC: 45% |
| Mid tier: 53% | Functional/Unit leaders: 30% | EMEA: 29% |
| Smaller Players: 19% | Managers: 58% | Americas: 26% |
Market-Sizing & Forecasting
The market is sized using a top-down build that starts from the addressable converting equipment demand pool, reconstructed using tissue consumption growth signals, capacity additions, and replacement cycles at converting sites, and then translated into annual machine orders and installations. After forming that base, we corroborate it with selective bottom-up checks, such as rolling up sampled order values by line type, running channel checks on typical line configurations, and applying observed average selling price ranges to validated shipment volumes.
Inputs used in the model include tissue production and consumption trends by region, announced mill and converting capacity additions, line speed mix (for example, high-speed lines at and above 800 m/min), automation penetration, and typical refurbishment and replacement timing for converting lines. Pricing is handled through a simple configuration logic, where base line pricing is adjusted for automation level, speed class, and whether key modules are bundled, and then normalized to a consistent currency timing. For forecasting, we run scenario analysis around capex sentiment, lead times, and the pace of capacity expansion, and then reconcile the outcome with expert views so the growth curve stays realistic. Where shipment visibility is incomplete, gaps are filled using region-level installation rates and the observed share of projects that use integrated lines versus modular upgrades.
Data Validation & Update Cycle
Validation is done through multiple checks so the final value is not driven by one data series. We compare outputs with independent signals such as tissue capacity additions, conversion line utilization narratives from operators, and import-export movements for relevant machinery categories, and then review outliers before sign-off.
Assumptions are rechecked in internal analyst reviews, and follow-up calls are triggered when a major variance appears, such as a sudden shift in line pricing, delays in large projects, or an unexpected change in automation adoption. The report is refreshed annually, and interim updates are made when material events occur that can move equipment spending. Before delivery, a fresh pass is completed so the shared view reflects the latest available information.
黑料不打烊's Tissue Paper Converting Machines Market Sizing Compared With Other Published Estimates
Published market numbers for tissue paper converting machines can look far apart, even when they appear to describe the same industry. In our checks, the main reasons were differences in what equipment gets counted, how the model treats retrofits versus new lines, and how quickly pricing and currency timing are refreshed.
Some estimates widen the scope to include papermaking or broader paper machinery, and then totals can rise fast due to the larger upstream equipment base. For 黑料不打烊, only converting-focused equipment revenue is counted, and packaging-only machines are excluded unless they are bundled within a converting line, which keeps the value tied to the converting capex cycle.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 1.61 B (2025) | |
| Global Research House A | USD 1.73 B (2025) | Uses a faster growth setup and tends to treat a wider set of converting-adjacent equipment as in-scope, which can lift totals when modular add-ons and refurbishments are priced like full line orders. |
| Industry Publisher B | USD 1.65 B (2024) | Anchors sizing to an earlier base year and applies a simplified ASP uplift, which can understate recent price shifts for higher-speed, higher-automation lines and can also miss timing effects from long project lead times. |
The table shows that most of the spread is explained by scope expansion and by how pricing and timing are handled across upgrades and new installations. By keeping assumptions traceable to capacity additions, replacement behavior, and configuration-based pricing, the final market value stays repeatable and can be reconciled back to practical demand signals.


Key Questions Answered in the Report
What is the current value of the tissue paper converting machines market?
The tissue paper converting machines market size reached USD 1.67 billion in 2026 and is forecast to reach USD 1.98 billion by 2031.
Which technology segment leads the market?
Automatic tissue paper converting lines held 65.15% of global installations in 2025 and are growing at a 4.66% CAGR.
Why are kitchen-roll lines growing faster than toilet-roll lines?
Kitchen-roll equipment benefits from higher household cleaning standards and expanding food-service demand, resulting in a 7.12% CAGR through 2031 while toilet-roll lines grow more slowly.
Which region is expanding the fastest?
Asia-Pacific records the highest 6.63% CAGR on expanding capacity, rising hygiene awareness, and investment in modern high-speed equipment.
Page last updated on:



