
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 13.45 Billion |
| Market Size (2026) | USD 14.47 Billion |
| Market Size (2031) | USD 20.81 Billion |
| Growth Rate (2026 - 2031) | 7.55 % |
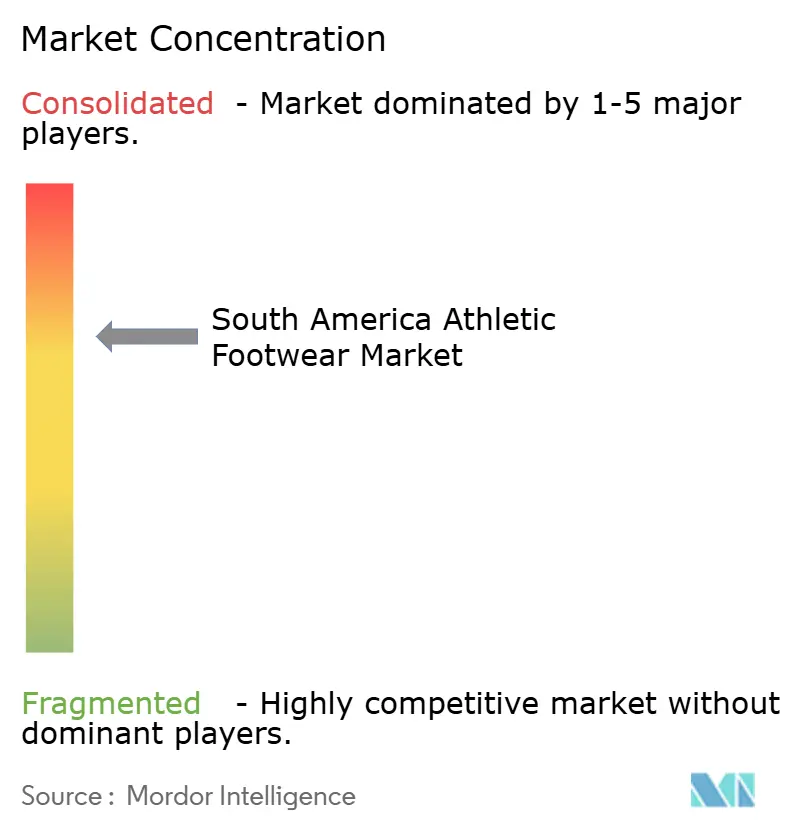
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
South America Athletic Footwear Market Analysis by 黑料不打烊
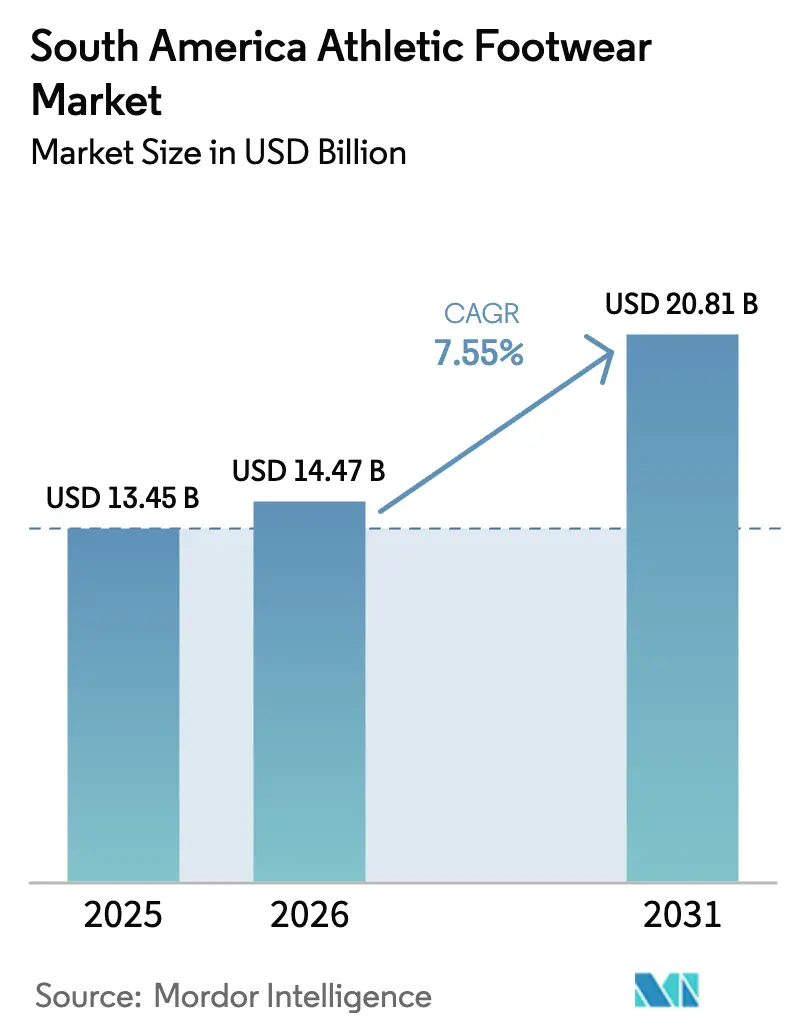
The South American athletic footwear market size was valued at USD 13.45 billion in 2025 and estimated to grow from USD 14.47 billion in 2026 to reach USD 20.81 billion by 2031, at a CAGR of 7.55% during the forecast period (2026-2031). The market growth is driven by increasing health awareness, middle-class population growth, and rising sports participation. The expansion of international brands and the growth of e-commerce platforms have improved athletic footwear accessibility across South American consumer segments. The market encompasses various product categories, including running shoes, training footwear, sports-specific shoes, and casual athletic footwear. Brazil and Argentina represent the largest markets in the region, followed by Colombia and Chile. Local manufacturers are increasingly competing with global brands by offering cost-effective alternatives, while premium segments continue to be dominated by international players. The market also benefits from growing fitness trends, urbanization, and increasing disposable income among young consumers.
Key Report Takeaways
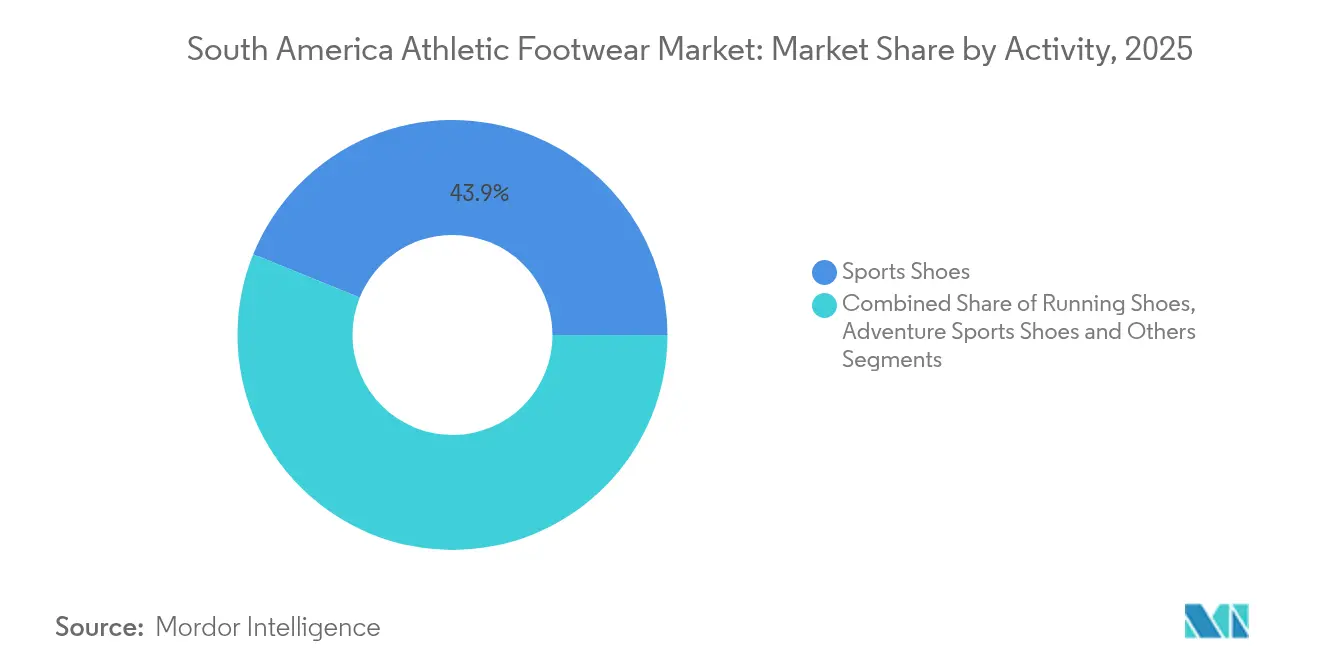
- By activity, sports shoes held 43.88% revenue share in 2025; running shoes are on track for an 8.05% CAGR through 2031.
- By product type, shoes secured 83.10% of the South American athletic footwear market share in 2025, while boots are set to advance at 7.78% CAGR by 2031.
- By end user, men commanded 64.72% of the South American athletic footwear market size in 2025; the kids segment is rising at an 8.15% CAGR through 2031.
- By category, mass-market lines captured 67.85% of sales in 2025; premium price points are forecast to post an 8.35% CAGR.
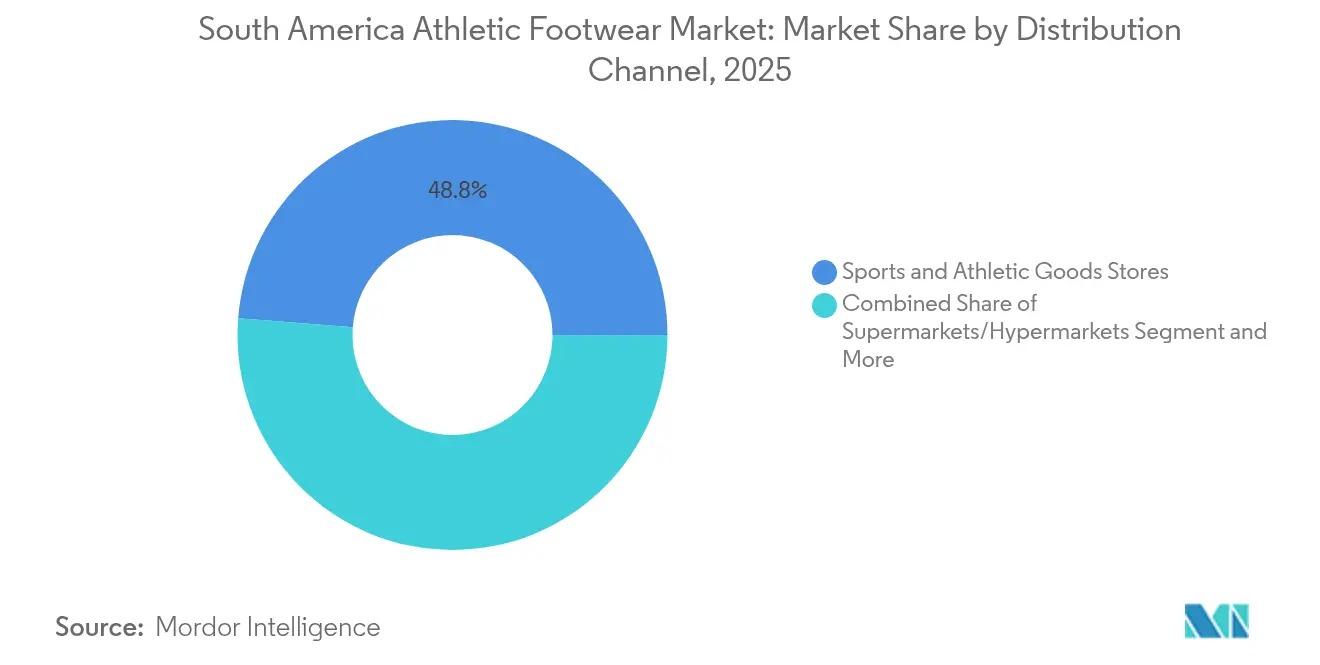
- By distribution channel, sports and athletic goods stores led with a 48.76% share in 2025; online sales are expanding at a 8.92% CAGR.
- By geography, Brazil contributed 32.12% of 2025 revenue; Argentina is the fastest climber at 9.10% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
South America Athletic Footwear Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Influence of Social Media Platforms and Celebrity Endorsements | +3.35% | Brazil, Argentina, Rest of South America | Medium term (2-4 years) |
| Favourable Government Initiatives to Promote Sports Culture | +2.25% | Brazil, Argentina | Long term (≥ 4 years) |
| Significant Growth in Women Sports Participation Rate | +1.55% | Brazil, Argentina, Rest of South America | Medium term (2-4 years) |
| Technological Innovations in Product Formulations | +1.25% | Brazil, Argentina | Short term (≤ 2 years) |
| Government initiatives promoting sports and physical activities | +2.00% | Brazil, Argentina, Rest of South America | Long term (≥ 4 years) |
| Growing urbanization and the emergence of fitness trends | +1.80% | Brazil, Argentina, Rest of South America | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Influence of Social Media Platforms and Celebrity Endorsements
Social media platforms have fundamentally transformed athletic footwear marketing strategies in South America through the implementation of direct-to-consumer distribution mechanisms. Nike's strategic collaborations with professional athletes, including LeBron James, Michael Jordan, and Serena Williams, exemplify this methodological approach to market penetration. These athletes function as authorized brand representatives, a factor of considerable significance in South America, where sports figures, predominantly football professionals, maintain substantial cultural influence. Social commerce platforms, specifically Facebook, Instagram, and TikTok, have evolved beyond product discovery to establish comprehensive procurement mechanisms for athletic footwear. The presence of 112.55 million Facebook users in Brazil in 2024 demonstrates the platform's significant market penetration within the geographical region [1]Source: Facebook, "Countries with the most Facebook users", www.facebook.com.
Favourable Government Initiatives to Promote Sports Culture
Government initiatives across South America have implemented comprehensive sports development programs as strategic public health measures and economic catalysts, subsequently increasing the demand for athletic footwear. Brazil's strategic investments in sports infrastructure, following its role as host of major international sporting events, have facilitated expanded access to athletic facilities beyond metropolitan regions. Argentina's implementation of trade liberalization policies has restructured the athletic footwear market through increased international market participation and enhanced consumer options within premium segments. The systematic incorporation of sports programs within educational institutions throughout the region has established sustained youth participation in athletic activities, developing a robust foundation for continued market expansion.
Significant Growth in Women's Sports Participation Rate
The increasing participation of women in sports activities throughout South America is generating consistent demand for women-specific athletic footwear products. Athletic footwear manufacturers in the region are implementing comprehensive product development initiatives and targeted marketing strategies. At the 2024 Summer Olympic Games, Brazil's delegation comprises 276 athletes competing across 39 sports disciplines, with female athletes representing 55% (153 athletes) of the contingent, according to the Brazilian Olympic Committee (COB) [2]Source: Brazilian Olympic Committee (COB), "Brazil’s women Olympians outnumber men for first time", www.cob.org.br. Manufacturers are implementing scientifically engineered footwear designs specifically tailored to female biomechanics, diverging from the conventional approach of modifying existing men's footwear models. The strategic incorporation of performance specifications with aesthetic elements has extended the utilization of women's athletic footwear beyond athletic activities, resulting in increased purchase frequency and enhanced customer lifetime value within this market segment.
Technological Innovations in Product Formulations
Technological advancements in athletic footwear have substantially enhanced performance capabilities, prompting consumers across price segments to invest in upgraded footwear solutions. In December 2024, Freudenberg introduced a sophisticated solvent-free vegan suede manufactured from microfiber nonwovens at Brazil's Inspiramais trade fair. The organization implemented increased utilization of recycled materials in its product portfolio, incorporating vamp liners and insoles with 35% to 100% recycled content to address consumer requirements for sustainable products. Nike's implementation of the Athlete Imagined Revolution (AIR) project employs artificial intelligence technology to develop customized footwear based on comprehensive athlete data analysis. The widespread distribution of advanced technologies across multiple price points has established elevated performance standards in mass-market segments, necessitating manufacturers to accelerate their innovation initiatives to maintain competitive differentiation in the South American market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Proliferation of Counterfeit Products | -1.45% | Brazil, Argentina | Medium term (2-4 years) |
| High import duties and taxes increase retail prices | -1.20% | Brazil, Argentina, Rest of South America | Short term (≤ 2 years) |
| Consumer preference for traditional footwear limits market growth | -0.80% | Brazil, Argentina, Rest of South America | Long term (≥ 4 years) |
| Economic instability and currency fluctuations impact purchasing power | -1.10% | Brazil, Argentina, Rest of South America | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Proliferation of Counterfeit Products
The counterfeit athletic footwear market in South America undermines market integrity through its impact on brand value, consumer trust, and legitimate sales channels. INTERPOL reports indicate seizures valued at USD 225 million in 2024 [3]Source: INTERPOL, "Over 11 million illicit and counterfeit products seized in South American operation", www.interpol.int/en. Counterfeit operations have evolved from basic imitations to sophisticated replicas that closely mirror authentic products, complicating both consumer identification and brand protection efforts. According to the OECD's "Mapping Global Trade in Fakes 2025" report, counterfeit footwear reached USD 467 billion, representing 2.3% of total global imports (OECD/EUIPO). The expansion of e-commerce has inadvertently facilitated counterfeit distribution through small parcel shipments that evade detection systems, prompting brands to implement advanced authentication technologies and consumer awareness programs to mitigate market impact.
High import duties and taxes increase retail prices
Import duties and taxes imposed on athletic footwear products substantially increase retail prices, thereby constraining market growth and consumer accessibility. In countries such as Colombia and Argentina, importers and retailers encounter significant cost implications due to elevated tariffs. Colombia's implementation of a 35% duty extension on imported footwear exemplifies these market conditions. These additional costs are subsequently transferred to consumers through increased retail prices, reducing athletic footwear accessibility, particularly within price-sensitive emerging markets. The consequent price increases diminish demand, restrict market expansion, and potentially foster informal market imports as consumers pursue affordable alternatives. Furthermore, substantial duties serve as a deterrent for international brands considering market entry or expansion, subsequently reducing consumer choice and competition, which impacts product innovation and price competitiveness.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Activity: Running Shoes Lead Performance Revolution
Sports Shoes hold the dominant position with a 43.88% market share in 2025, driven by their versatility in both athletic activities and casual wear. Running Shoes are expected to achieve the highest growth rate at 8.05% CAGR from 2026 to 2031, driven by the expanding running culture and increased participation in marathons and community events. The segment's growth is enhanced by technological advancements, including Nike's AI-optimized Air technology, which improves performance and customization options. The South American athletic footwear market's activity segmentation reflects distinct consumer preferences influenced by global fitness trends and regional sporting traditions.
Adventure Sports Shoes are experiencing increased demand in Brazil and Argentina, where diverse topography supports outdoor activities among urban consumers. The segment's growth is supported by technical innovations such as Freudenberg's breathable waterproof membranes, which improve performance in challenging conditions. The Other Product Types segment, encompassing footwear for tennis, basketball, and volleyball, maintains consistent growth through specialized sporting communities and international sporting events. The market continues to evolve as athletic functionality merges with fashion preferences, particularly in urban areas where sports footwear serves both performance and style purposes.


By Product Type: Shoes Maintain Dominance While Boots Gain Momentum
Shoes hold 83.10% market share in 2025, driven by their versatility, cost-effectiveness, and suitability for the region's climate. The South American athletic footwear market demonstrates distinct consumer preferences across product types. Adidas reported a 17% increase in global footwear sales in 2024, with Latin America achieving 28% growth. The company projects double-digit growth in Latin America for 2025.
The boots segment is expected to grow at 7.78% CAGR from 2026 to 2031, exceeding the market's overall growth rate. This expansion stems from increased participation in adventure sports and outdoor activities, particularly in Brazil and Argentina. Technical innovations, including Freudenberg's specialized insoles and waterproof membranes, improve performance and comfort in demanding conditions. The segment experiences seasonal demand fluctuations, with peak sales during winter months in southern Argentina and Chile. This seasonality creates inventory management challenges for retailers while enabling premium pricing opportunities during high-demand periods.
By End User: Men Lead While Kids Segment Shows Highest Growth Potential
Men's footwear holds the largest market share at 64.72% in 2025, driven by higher sports participation rates and greater purchasing power across South American countries. Major athletic footwear brands focus extensively on this segment through diverse product offerings and targeted marketing campaigns. The women's segment demonstrates consistent growth, supported by increasing sports participation and the blend of athletic and fashion footwear preferences. The South American athletic footwear market shows distinct patterns across end-user segments.
The children's segment is expected to achieve the highest growth rate at 8.15% CAGR from 2026 to 2031, surpassing both adult segments. This growth stems from several factors: increased emphasis on children's physical activities, expanded school sports programs, and children's growing influence on family purchases. The segment benefits from frequent replacement needs due to children's growth patterns and active usage. Athletic footwear manufacturers are developing products with specialized technologies for children's biomechanical requirements while incorporating designs that appeal to young users, helping establish early brand relationships that can continue into adulthood.
By Distribution Channel: Traditional Retail Leads While E-commerce Surges
Sports and Athletic Goods Stores dominate the athletic footwear distribution in South America with a 48.76% market share in 2025. These specialized retailers excel through product expertise, fitting services, and brand-focused shopping experiences. Their role remains essential for consumers purchasing premium and technical footwear, where professional guidance is valuable. Supermarkets/Hypermarkets serve as key channels for mass-market athletic footwear, providing accessibility and competitive prices for basic and casual products. Other Distribution Channels, including department stores and brand outlets, maintain a consistent market presence.
Online Retail Stores are expected to achieve a 8.92% CAGR from 2026 to 2031, driven by digital transformation and evolving shopping preferences in the region. The expansion of logistics networks, digital payment solutions, and increased consumer confidence in online footwear shopping support this growth. Brands are strengthening their online presence through direct-to-consumer platforms. The online channel growth enables international brands to enter the market without extensive physical retail networks, increasing market competition and product variety.
By Category: Mass Market Dominates While Premium Segment Accelerates
The Mass category holds a 67.85% market share in 2025, primarily serving price-sensitive consumers across the region. This segment's dominance is notable in countries with substantial middle and lower-middle-income populations, where price remains the key purchasing factor. The mass segment has grown through the wider availability of athletic footwear technologies, as features once limited to premium products are now accessible at lower price points. Brazil's Vulcabras exemplifies this trend, becoming the country's largest athletic footwear manufacturer by offering value-focused products with competitive performance features. The South American athletic footwear market is divided into two main categories, reflecting regional economic conditions and consumer preferences.
The Premium segment accounts for 32.15% of the market share in 2025 and is expected to grow at 8.35% CAGR from 2026 to 2031. This growth is driven by an expanding affluent consumer base and increased consumer investment in high-performance athletic footwear. The segment's expansion is further supported by the "masstige" trend, where premium products become more accessible to the aspirational middle class. Consumers in this segment seek products that combine mass-market accessibility with prestige, driven by both personal satisfaction and social recognition.
Geography Analysis
Brazil accounts for 32.12% of the South American Athletic Footwear Market in 2025, driven by its economic position and population size. The country's established retail networks and high sports participation rates, especially in football, running, and fitness activities, support market growth.
The Brazilian Association of Footwear Industries forecasts growth rates of 3% in 2024 and 2% in 2025 for the footwear sector. Argentina demonstrates the strongest growth potential in the region, with an expected CAGR of 9.10% from 2026 to 2031. The market has evolved through trade liberalization, resulting in a doubling of international footwear brands in 2025 following import regulation changes.
However, persistent economic instability and the reduction in domestic manufacturing capabilities constitute significant impediments to market development. The Rest of South America, comprising Chile, Colombia, Peru, and Uruguay, offers distinct market opportunities based on their economic development, retail infrastructure, and sports participation levels. These markets necessitate strategic approaches that correspond to regional consumer preferences, distribution infrastructure, and competitive market dynamics.
Regulatory Landscape
Trade and customs rules remain a swing factor for athletic footwear pricing and sourcing across South America. A key anchor is the provisional application of the EU-Mercosur trade pillar from May 1, 2026, which introduced common origin certification and rules of origin that typically cap non-originating inputs at about 40-50% of ex-works value, with certain lower-value footwear requiring 60% regional content to qualify for preferences. Tariff protection continues to shape in-region competition, including Colombia's policy posture around elevated footwear duties, cited in the market as a 35% duty extension on imports, which affects landed costs for international brands and cross-border assortment strategies.
On product compliance, the Andean Community maintains mandatory technical requirements for footwear labeling through Resolution No. 2107 (covering Bolivia, Colombia, Ecuador, and Peru). The rules require permanent Spanish labeling, including origin and material composition disclosures, which impacts packaging design and SKU management for brands selling across multiple South American markets. Enforcement against illicit trade is another regulatory pressure point given the scale of counterfeiting referenced in the broader market context (INTERPOL-reported seizures in 2024), pushing brands and marketplaces toward stronger authentication, channel control, and documentation practices.
Competitive Landscape
The South American Athletic Footwear Market maintains a moderately concentrated structure, with major global companies like Nike, Inc., Adidas AG, Puma SE, Decathlon S.A., and Under Armour Inc. controlling significant market share through their local manufacturing capabilities and market expertise. Argentina's trade liberalization policies have intensified market competition, leading to increased participation across various price segments and distribution channels.
Companies compete primarily through technological advancement, sustainability initiatives, and digital capabilities. Nike's implementation of the Athlete Imagined Revolution (AIR) project demonstrates this trend, using artificial intelligence to develop customized footwear based on athlete data. The market presents opportunities in specialized segments, particularly sustainable athletic footwear. For instance, Freudenberg introduced solvent-free vegan suede made from microfiber nonwovens at Brazil's Inspiramais trade fair. The growth of e-commerce has transformed competitive dynamics, reducing entry barriers for digital-first brands while pushing traditional retailers to strengthen their omnichannel presence.
Moreover, Brazil and Argentina, buoyed by a youthful population and proactive government sports initiatives, are at the forefront of the market, showcasing both size and growth potential. Meanwhile, regional players and newcomers are spurring innovation and competition, especially in the realms of sustainable and specialized footwear.
South America Athletic Footwear Industry Leaders
-
Nike, Inc.
-
Adidas AG
-
Puma SE
-
Decathlon SA
-
Under Armour Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Regional manufacturing and export positioning create whitespace alongside the market's fast-growing online channel. The EU-Mercosur trade pillar applied provisionally from May 1, 2026 offers a clear path for South American suppliers to compete in Europe under preferential access. Origin requirements, including cases where 60% regional content is needed, also raise the incentive to deepen localization of uppers, components, and finishing steps within Mercosur-linked supply networks. For brands and manufacturers, this shifts the opportunity toward supplier development, regional tier-2 materials, and compliance-ready origin documentation, rather than relying primarily on fully imported product that is more exposed to duties and freight volatility.
Nearshoring inside South America is also reflected in new capacity decisions tied to local cost and tax regimes. Paraguay's Maquila framework (Law No. 7,547/2025) has already attracted investment into athletic-footwear production, including Grupo Dass's USD 40 million facility at Parque Industrial Almasol in Asuncion to supply major brands such as Nike and Adidas. This capacity addition supports faster replenishment programs for sports and athletic goods stores, the largest channel in 2025, and for e-commerce fulfillment, while helping brands manage compliance and pricing in markets where import duties remain a constraint.
Recent Industry Developments
- June 2026: Launched 'Future' soccer boots designed by KidSuper, inspired by the Phoenix, for Neymar Jr. in Brazil. The launch targets high profile football boot segment in Brazil and strengthens football lifestyle positioning.
- June 2026: Released the 'TRVL WEAR' collection in Brazil in partnership with Salehe Bembury, featuring Velum SB NITRO sneakers. The collection expands football inspired lifestyle footwear in key South American markets.
- May 2026: Opened a new production facility at Parque Industrial Almasol in Asuncion, Paraguay, with USD 40 million investment to supply Nike, Adidas, and other brands across South America. The facility improves regional supply security and lowers lead times, strengthening South America footprint for global brands.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the market includes revenue generated from athletic footwear sold across South America for sports, fitness, and active lifestyle use. Sales are counted at the point of sale through retail and online channels, and tracked in USD.
Scope exclusions: This sizing excludes non-athletic casual footwear and apparel-only spending, and it does not count used or informal secondhand transactions.
Segmentation Overview
-
By Activity
- Running Shoes
- Sports Shoes
- Adventure Sports Shoes
- OtherProduct Types
-
By Product Type
- Shoes
- Boots
-
By End User
- Men
- Women
- Kids/Children
-
By Category
- Premium
- Mass
-
By Distribution Channel
- Sports and Athletic Goods Stores
- Supermarkets/Hypermarkets
- Online Retail Stores
- Other Distribution Channels
-
By Geography
- Brazil
- Argentina
- Rest of South America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set market boundaries and build the base demand picture by country, then assumptions were tested through interviews. We referenced public statistics and industry releases such as UN Comtrade trade data for footwear, national statistics bodies for CPI and household spending indicators, central bank FX time series, and labor and demographic tables from sources such as the World Bank.
We also reviewed customs and tariff documentation where available, sports participation and health trend materials from ministries and public health agencies, and sustainability or labeling guidelines that influence product mix. Company filings, investor presentations, association websites, and reputed press were used to understand channel shifts like e-commerce and multi-brand retail dynamics. Paid subscriptions were used selectively for company financial intelligence, news and financials tracking, and patent databases to spot innovation themes that can move average selling price and replacement cycles. These sources are illustrative, and many other references were also used for data collection, cross-checks, and clarification during the analysis.
Primary Interviews and Surveys
We conduct interviews and surveys with footwear manufacturers, importers, distributors, retailers, e-commerce specialists, and sports buyers across South America. Responses test retail prices, sell-through, channel mix, local production, import activity, and demand shifts, helping us challenge secondary assumptions and close gaps before the final analysis is triangulated.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 25% | CXOs: 15% |
| Mid tier: 55% | Functional/Unit leaders: 30% |
| Smaller Players: 20% | Managers: 55% |
Market-Sizing & Forecasting
Market sizing was built using a top-down demand pool assessment. Population, income, and urbanization signals, sports participation proxy trends, and footwear import and local supply indicators were used to reconstruct addressable spend by country. After country totals were formed, they were split using market fingerprints such as men-women-kids mix, premium versus mass share, and the share moving through online channels.
To keep the totals realistic, we corroborated the outputs with selective bottom-up checks. These included sampled price bands by key activity types, channel-level reality checks from retailers and distributors, and sanity checks against disclosed regional revenue signals from public companies when available. Where country data was thin, gaps were handled by using transparent proxy variables, and then the assumptions were stress-tested during interviews.
Forecasts were created using scenario analysis supported by variable-level views gathered in primary conversations, especially on price progression, promotional cadence, and e-commerce penetration. The model was then re-run for alternative FX and inflation paths so the growth story remains explainable and consistent with observable economic conditions.
Data Validation & Update Cycle
Outputs were cross-checked against independent signals such as trade flows, consumer price trends, and observable channel expansion to confirm that growth and pricing moved in a believable range. When variances appeared at the country level, we revisited the drivers, followed by a second pass on assumptions like category mix, imported versus locally supplied share, and currency conversion timing.
Before sign-off, the model and narrative were reviewed in multiple analyst steps so calculation logic, units, and definitions stayed consistent across sections. Reports refresh annually, and material events such as sharp FX moves, major policy changes, or channel disruptions can trigger an interim check. Just before delivery, a final update pass is completed so clients receive the most current view available at that time.
黑料不打烊's South America Athletic Footwear Market Size Compared With Other Published Estimates
Published market sizes for South America athletic footwear can differ because the market boundary is not always handled the same way. Pricing assumptions and currency timing choices can also shift the USD total. Some studies also mix broader sports footwear with adjacent casual sneakers, which changes the counted demand pool.
By tracking realized price bands and promotion intensity by country and then refreshing FX conversion timing inside the model, 黑料不打烊 keeps the estimate tied to sell-through for athletic footwear only. This avoids blending in lifestyle-only sneaker demand or assuming a single regional price curve.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 13.45 B (2025) | |
| Trade Journal A | USD 12.10 B (2025) | Uses a narrower tracked channel set that underweights specialty retail and online sales, and applies conservative pricing that does not fully reflect premium mix in Brazil and Argentina. |
| Regional Consultancy B | USD 15.20 B (2025) | Folds broader sports footwear and some lifestyle sneaker demand into the same bucket, and relies on uniform regional ASP uplift without separating country-level promo and FX effects. |
The spread across sources mainly comes from what is counted as athletic footwear, how country pricing is treated, and whether FX and inflation effects are timed consistently. Our approach stays repeatable because each country total is built from clear demand signals and then checked through channel and pricing discussions before the final number is locked.


Key Questions Answered in the Report
What is the current size of the South America athletic footwear market?
The market generated USD 14.47 billion in 2026 and is on track to approach USD 20.81 billion by 2031.
Which country contributes the largest revenue to South America athletic footwear sales?
Brazil leads with 32.12% share in 2025, thanks to its sizeable population, domestic manufacturing, and football culture.
Which segment is growing the fastest?
Running shoes post the highest activity-based CAGR at 8.05%, driven by urban marathon participation and individual fitness trends.
How big is the premium segment compared with mass-market footwear?
Mass-tier products hold 67.85% of 2025 sales, but premium categories are expanding faster at an 8.35% CAGR due to technology adoption and rising incomes.
Page last updated on:



