
Single-Use Bioprocessing Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 33.03 Billion |
| Market Size (2031) | USD 64.12 Billion |
| Growth Rate (2026 - 2031) | 14.20 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Single-Use Bioprocessing Market Analysis by 黑料不打烊
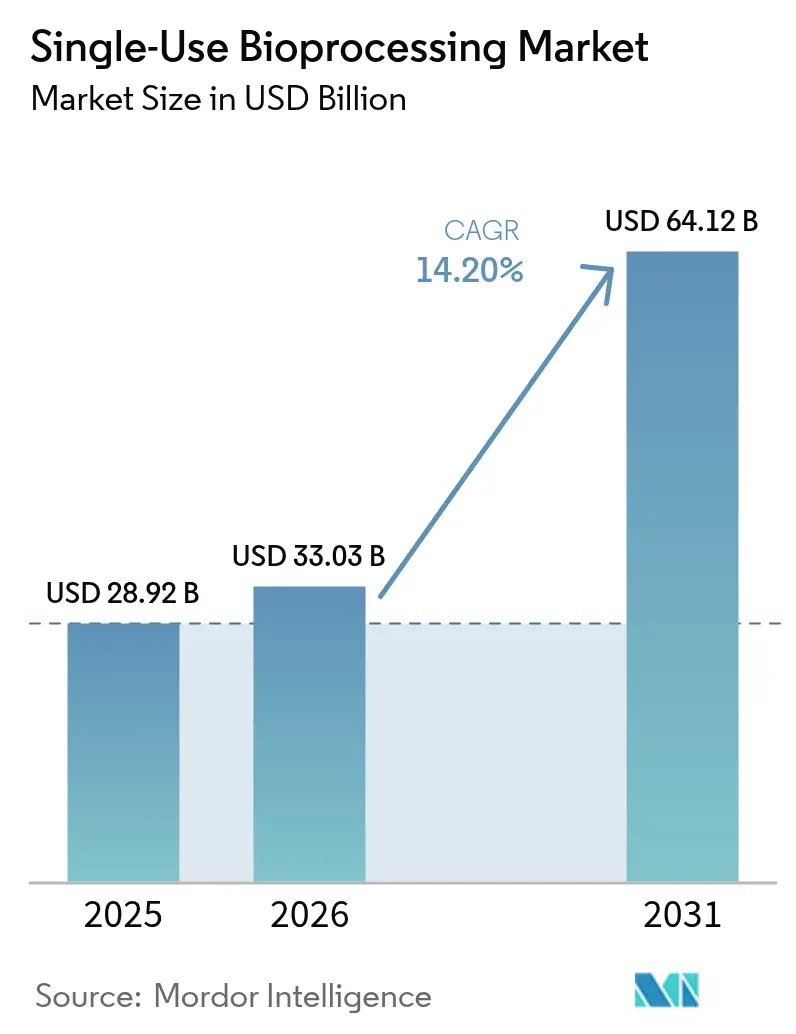
The single-use bioprocessing market size was valued at USD 28.92 billion in 2025 and estimated to grow from USD 33.03 billion in 2026 to reach USD 64.12 billion by 2031, at a CAGR of 14.2% during the forecast period (2026-2031). Single-use bioprocessing market adoption accelerated as manufacturers sought faster facility build-outs, lower capital outlays, and the flexibility to run multiple biologics without cross-contamination risk. Regulatory bodies in the United States and Europe published technology-friendly guidance in 2025, effectively removing a lingering compliance barrier. Downstream operations are now pivoting toward membrane-based purification formats that match high-titer antibody processes, while AI-enabled control loops elevate demand for disposable inline sensors. Medical-grade polymer supply shocks in late 2025 revealed upstream vulnerabilities and triggered vertical-integration moves by leading suppliers. Sustainability pressure, especially in the European Union, is catalyzing take-back pilots and design tweaks that enable polymer recovery rather than incineration.
Key Report Takeaways
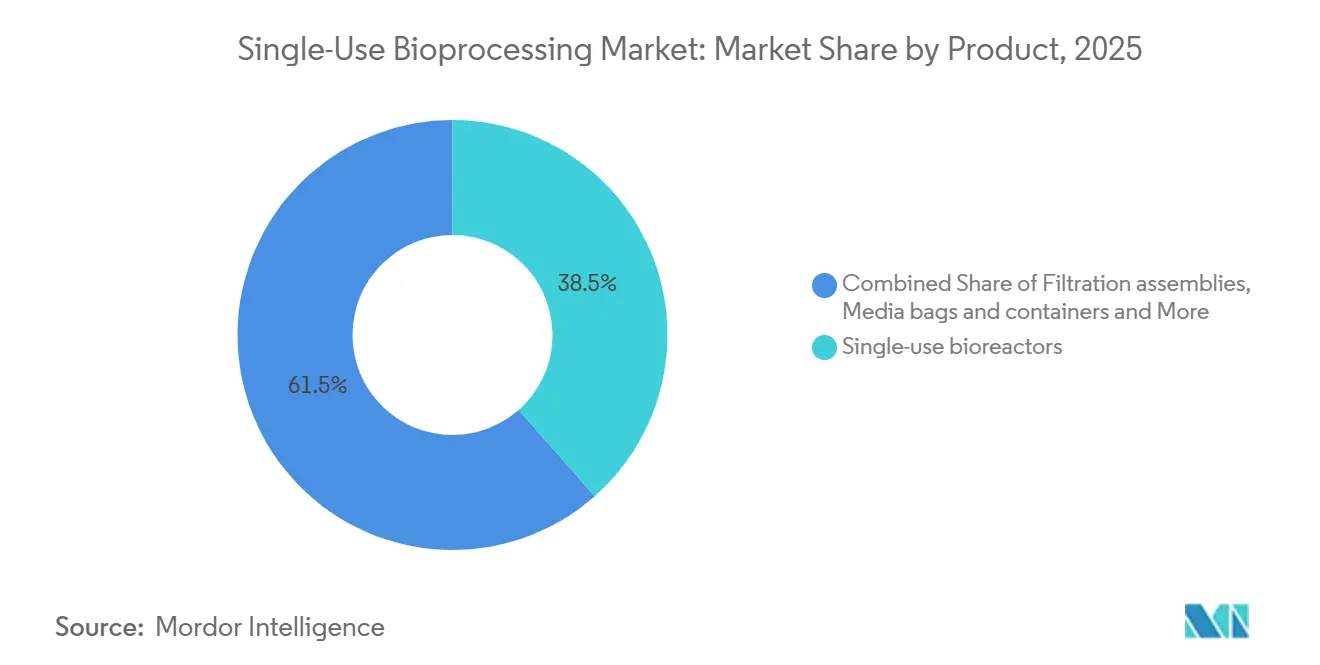
- By product category, single-use bioreactors led with 38.55% of the single-use bioprocessing market share in 2025. Sensors and analytics are forecast to expand at a 16.25% CAGR through 2031 as the fastest-growing product line.
- By workflow stage, upstream processing accounted for 52.53% of 2025 revenue, while downstream operations are projected to grow at a 15.75% CAGR to 2031.
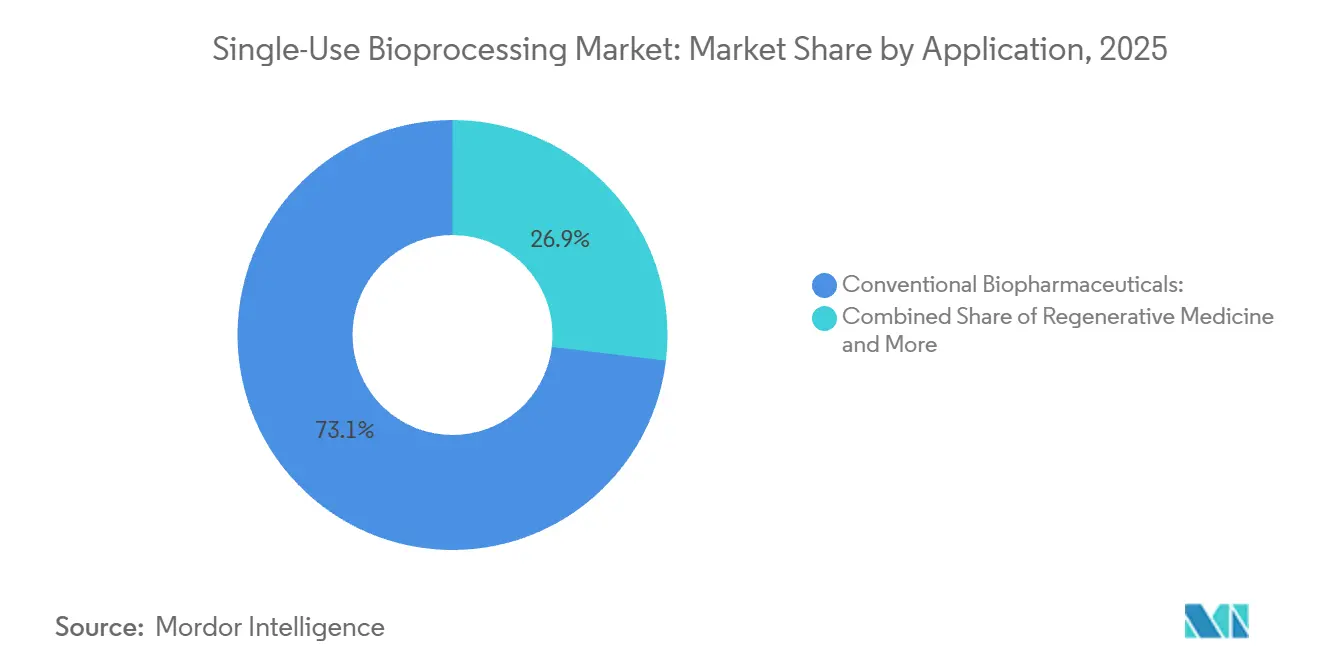
- By application, conventional biopharmaceuticals accounted for an estimated 73.12% of market revenue in 2025; regenerative medicine (advanced therapies) is projected to grow at a 15.91% CAGR to 2031.
- By scale, the commercial scale held 66.65% revenue share in 2025, rising at 15.32% CAGR to 2031.
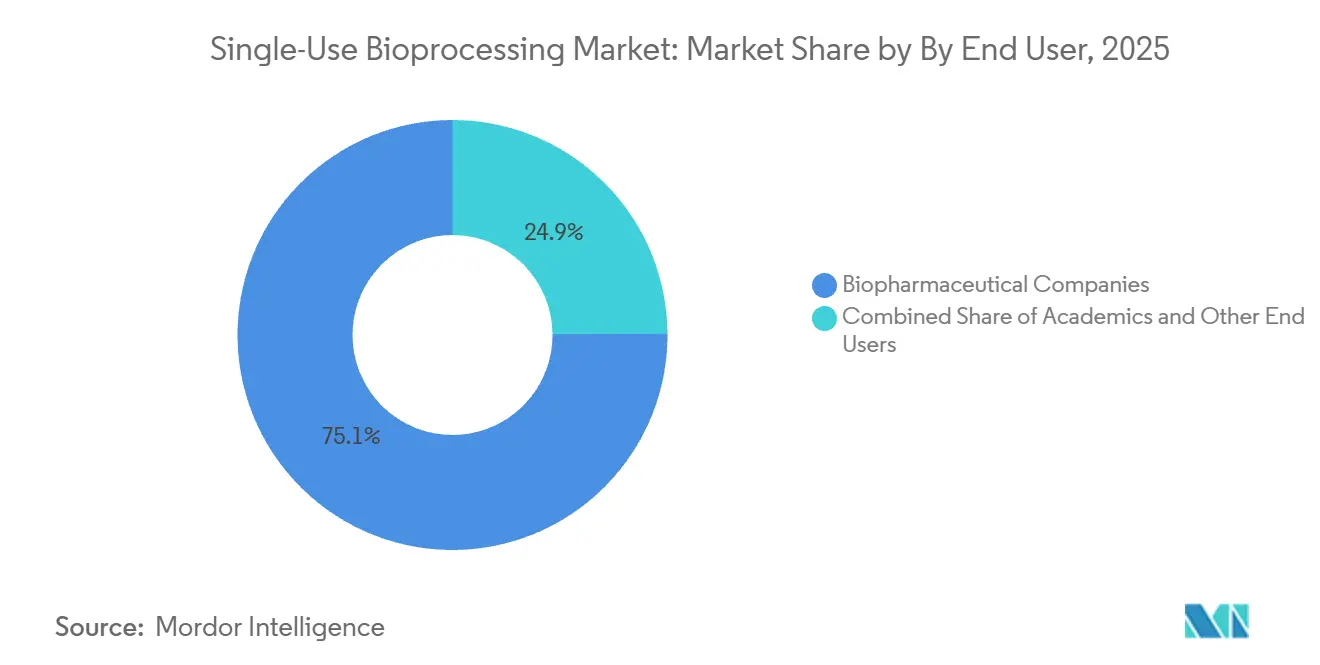
- By end user, biopharmaceutical companies held 75.15% revenue share in 2025; contract research organizations (CROs) contract development and manufacturing organizations are advancing at a 14.82% CAGR through 2031.
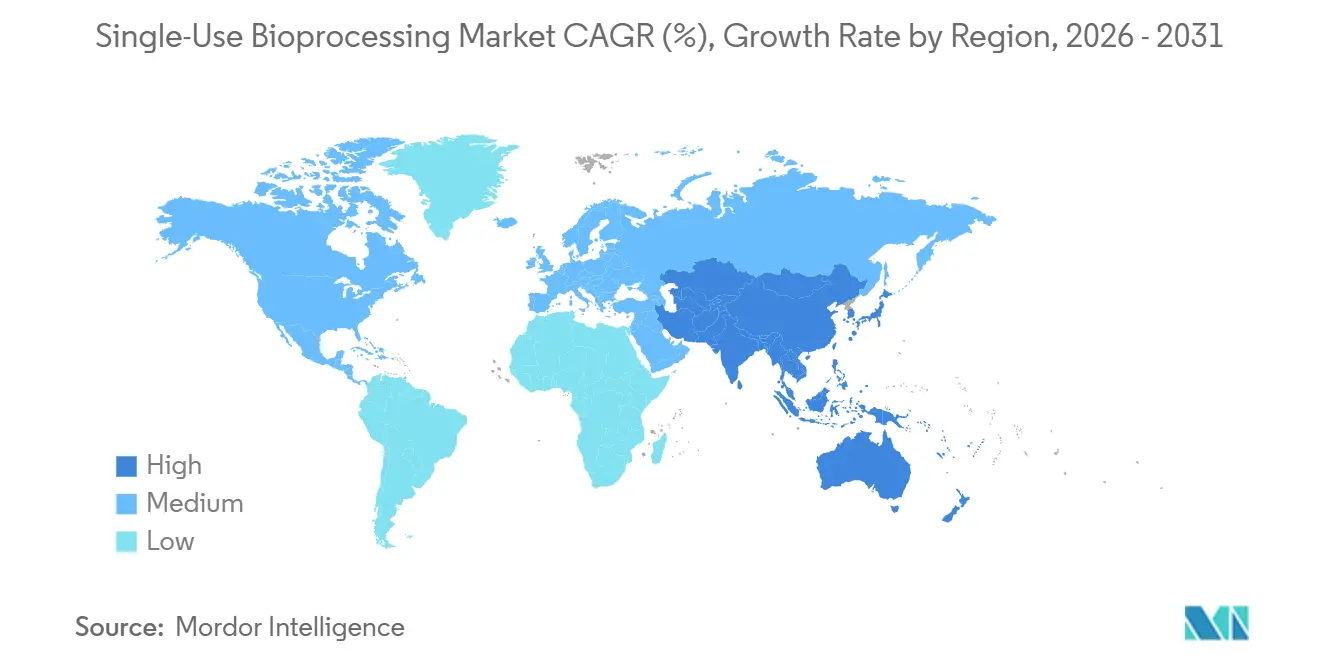
- By geography, North America captured 35.23% of 2025 revenue, whereas Asia-Pacific is poised for the highest regional growth at a 15.42% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Single-Use Bioprocessing Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cost & CAPEX avoidance vs. stainless-steel plants | +3.2% | Global, strongest in North America and Europe | Medium term (2-4 years) |
| CDMO and CMO Capacity Expansion | +2.8% | Global; APAC biosimilar wave accelerating | Long term (≥ 4 years) |
| Rapid scale-up needs for mRNA vaccines & personalized therapies | +2.1% | North America and Europe core, spillover to APAC | Short term (≤ 2 years) |
| Circular-economy mandates favoring polymer recovery | +1.5% | Europe regulatory, voluntary in North America | Long term (≥ 4 years) |
| Plug-and-play microbial single-use fermentors ≥3,000 L | +1.3% | Global, strongest in U.S. and China | Medium term (2-4 years) |
| AI-enabled hybrid-continuous control loops | +1.1% | North America and Europe early adopters | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Cost & CAPEX Avoidance vs. Stainless-Steel Plants
Replacing clean-in-place and steam-in-place hardware with disposable assemblies compresses green-field project timelines by up to two years and cuts capital budgets nearly in half. Peer-reviewed modeling of a 2,000 L monoclonal antibody campaign showed breakeven at only 12 batches a year, a level typical for multi-product CDMO facilities. Lonza reported that 70% of mammalian capacity added since 2023 employs single-use lines, citing quicker client onboarding[1]Lonza Group, “Annual Report 2024,” Lonza.com. Updated FDA guidance allows stainless vessels to be swapped with validated disposables without triggering new comparability studies, further tilting the economic balance. These factors collectively underpin the structural shift captured in the single-use bioprocessing market.
CDMO and CMO Capacity Expansion
Global expansion of contract development and manufacturing capacity reflects a structural shift toward more agile and scalable biomanufacturing ecosystems. As biologics pipelines grow in complexity and diversification, manufacturers are increasingly prioritizing infrastructure that enables rapid deployment, multi-product flexibility, and reduced time-to-market. This evolution is particularly pronounced in advanced therapy segments such as cell and gene therapy, where batch sizes are smaller and sterility requirements are stringent. Fujifilm invested over USD 3.2 billion in its Holly Springs facility in North Carolina, USA, in April 2024, establishing it as one of the largest biologics CDMO sites globally. Additionally, the company allocated USD 1.6 billion to expand cell-culture capacity in Denmark. Both facilities are designed for large-scale biologics manufacturing, incorporating flexible designs with single-use systems for cell culture. These investments reflect the industry's shift toward modular biomanufacturing infrastructure, with single-use technologies driving market growth.
Rapid Scale-up Needs for mRNA Vaccines & Personalized Therapies
BARDA’s USD 1.2 billion program contracted modular suites capable of pivoting from pandemic vaccines to commercial products within six weeks. BioNTech is retrofitting its Marburg site with single-use fermentors for individualized cancer vaccines, a conversion financially unrealistic for stainless assets. Every FDA-approved autologous cell therapy facility now operates closed disposable paths to avoid patient cross-contamination. A recent CAR-T case study documented batch-turnaround cuts of one-third after eliminating cleaning validation steps. These speed demands reinforce growth in the single-use bioprocessing market.
Circular-Economy Mandates Favoring Polymer Recovery
The EU’s revised Single-Use Plastics Directive requires take-back schemes for polyethylene and polypropylene films over 10 kg per unit, directly impacting bioreactor bags. Sartorius and Veolia launched a Lyon pilot diverting 120 tons of film waste annually from incineration through mechanical recycling. Enzymatic depolymerization research shows promise but must contend with gamma-irradiation chain scission. ISPE quantified 0.8 tons of plastic per 2,000 L batch, a metric now embedded in many European tenders. Procurement teams increasingly weigh circularity alongside performance, shaping supplier roadmaps in the single-use bioprocessing market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Leachables & extractables compliance risk | -1.8% | Global; heightened scrutiny in North America and EU | Short term (≤ 2 years) |
| Plastic-waste disposal & ESG regulations | -1.3% | Europe regulatory; voluntary in North America and APAC | Medium term (2-4 years) |
| Viscosity/shear limits in high-volume downstream steps | -0.9% | Global; acute in high-titer mAb production | Medium term (2-4 years) |
| Medical-grade polymer supply-chain tightness | -1.1% | Global; exacerbated by regional resin shortages | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Leachables & Extractables Compliance Risk
FDA’s ANDA guidance now mandates extractables and leachables studies for every disposable component contacting drug substance, adding six to nine months and roughly USD 200,000 per product. ICH Q3E sets a 1.5 ?g/day genotoxic threshold that some plasticizers can surpass, forcing tighter gamma-irradiation controls. MilliporeSigma recalled 800 tubing sets after phthalate levels hit 4.2 ppm. USP chapters <665> and <1665> now require mass-spectrometry characterization above 0.1 ppm, a hurdle for small suppliers. Compliance costs temper near-term momentum in the single-use bioprocessing market.
Plastic-Waste Disposal & ESG Regulations
The EU directive imposes 30% recycling targets by 2028, compelling suppliers to finance take-back logistics. A sustainability review pegged plastic intensity at 0.8 t per 2,000 L antibody batch, with incineration still dominant in North America and APAC. Sartorius diverted 18% of returned disposables via French and German pilots but cited gamma-irradiation degradation as a technical hurdle. Investor coalitions managing USD 4 trillion demanded plastic-waste disclosures from the top 10 suppliers in early 2025. These ESG headwinds shave growth from the single-use bioprocessing market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product: Sensors Drive Margin Expansion
Single-use bioreactors dominated 2025 revenue, yet inline sensors are the fastest-growing product class. FlowVPE spectroscopy alone generated USD 42 million in its launch year, underscoring how analytics attach high margins to consumable sales[2]Repligen Corporation, “Investor Presentation 2025,” Repligen.com. Filtration cassettes and media bags underpin buffer prep, while proprietary tubing geometries lock in recurring demand. Mixers benefit from continuous-manufacturing trends, with magnetic designs shortening media-prep cycles from eight hours to 90 minutes. The single-use bioprocessing market size for sensors is projected to expand briskly as AI-centric control schemes spread.
The competitive battleground pivots on ecosystem lock-in. Sartorius and Cytiva secure share through connector and bag exclusivity, discouraging third-party component substitution. Chromatography formats trail because reusable columns still underpin high-volume antibody workflows, yet membrane adsorbers are gaining as titers rise. Supplier R&D now funnels toward integrating disposable sensors, ensuring that data-rich operation remains inseparable from the broader single-use bioprocessing market.


By Workflow Stage: Downstream Gains Momentum
Upstream assets, especially bioreactors, accounted for a 52.53% single-use bioprocessing market share in 2025, reflecting long-standing maturity. Downstream units, however, post the quickest gains as continuous filtration and single-use TFF systems displace steel Protein A columns at high titers. A 0.5 m? disposable TFF cassette introduced in 2025 processes 500 L in a single pass, removing a 12-hour cleaning step. The single-use bioprocessing market size for downstream modules is projected to climb alongside hybrid continuous lines.
Continuous chromatography pilot data show 95% step yields with membrane adsorbers, cutting validation times and water consumption. Regulatory clarity from ICH Q13 accelerates adoption by defining control-strategy expectations. Fill-finish operations also lean on disposable tubing and pump heads that reduce product changeovers from eight hours to two. Collectively these shifts rebalance value from upstream to downstream within the single-use bioprocessing market.
By Application: Conventional Biopharma Leads, Regenerative Medicine Accelerates
Conventional biopharmaceuticals accounted for the majority of the single-use bioprocessing market revenue in 2025, supported by the continued production of monoclonal antibodies (mAbs), recombinant proteins, vaccines, and biosimilars. Biopharmaceutical manufacturers increasingly utilize single-use bioreactors, filtration systems, and mixing technologies to reduce capital expenditure, minimize contamination risks, and accelerate production timelines. The flexibility offered by disposable platforms is particularly valuable for multiproduct facilities, where rapid changeovers and reduced cleaning requirements improve operational efficiency and manufacturing throughput.
Regenerative medicine (advanced therapies) represents the fastest-growing application segment, driven by the expansion of cell therapies, gene therapies, and tissue-engineered products. These therapies are typically manufactured in small batches with highly specialized processes, making single-use systems an ideal solution due to their scalability, closed-system operation, and lower cross-contamination risk. The increasing number of clinical trials and commercial approvals for autologous and allogeneic therapies is accelerating demand for disposable bioprocessing technologies across upstream, downstream, and fill-finish operations.
By Scale: Commercial Dominates, Clinical Accelerates
Commercial-scale programs held two-thirds of 2025 revenue, widening as biosimilar launches crest. Disposable bioreactors now span 50 L to 5,000 L, letting firms use one platform from Phase I to launch. Cytiva said 40% of 2024 XDR sales were to customers planning dual clinical-commercial use, compressing tech-transfer timelines. A 2,000 L campaign reaches cost parity versus stainless steel at roughly 12 batches a year, a threshold most commercial antibodies exceed.
Retrofit activity is meaningful: 30% of Sartorius STR units shipped in 2024 replaced legacy steel vessels at multiproduct plants. For clinical-stage autologous therapies, disposables are non-negotiable due to patient-specific batch segregation. Collectively, these dynamics keep the single-use bioprocessing market on a steep adoption curve across both scales.
By End User: CDMOs Outpace Innovators
Biopharmaceutical innovators captured three-quarters of 2025 revenue, yet CDMOs exhibit the steeper trajectory. A BioProcess International survey reported 68% of CDMOs citing disposables as their principal multi-product enabler. Lonza deploys single-use formats in 85% of small-client suites, shortening cleaning turnarounds that would otherwise erode utilization. Government grants to universities and public labs also stipulate disposable platforms to maximize shared-facility uptime.
Academic demand is steady, anchored by flexibility needs in early trials. EMA guidance now lets Phase I and II batches run fully disposable without stainless comparability, unlocking early investment at smaller scales. As autologous therapies proliferate, end-user segmentation will continue to tilt toward organizations managing many products in parallel, a core advantage of the single-use bioprocessing market.
Geography Analysis
North America’s 35.23% revenue share in 2025 stemmed from BARDA’s pandemic-preparedness build-out, which specified modular disposable suites[3]Biomedical Advanced Research and Development Authority, “mRNA Vaccine Manufacturing Investment Program,” Phe.gov. FDA’s advanced-manufacturing framework further validated the approach, prompting retrofit programs in legacy facilities. Canada directed CAD 2.2 billion (USD 1.6 billion) to bolster vaccine and biologic capacity, stipulating single-use platforms for multi-product flexibility. Mexican CDMOs expanded to capture nearshoring demand from U.S. biopharma, choosing disposables for rapid deployment.
Europe blends regulatory push and sustainability pull. The Single-Use Plastics Directive mandates producer take-back, nudging adoption of recyclable bag films. Germany earmarked EUR 800 million (USD 880 million) for continuous single-use hubs, while the UK MHRA updated validation guidance to cover hybrid workflows. France installed 18 new suites for biosimilar output, and Southern European facilities added roughly 10,000 L of disposable bioreactor capacity in 2025, primarily for fill-finish programs.
Asia-Pacific is set for the fastest growth at 15.42% CAGR. China’s 47 biosimilar approvals in 2025 sparked facility expansions that favor disposable trains over steel. India’s USD 500 million upgrade fund names single-use equipment an eligible expense. Japan’s PMDA guidance now permits disposables without comparability studies for biosimilars, accelerating local uptake. South Korean majors added 120,000 L of new capacity over 2024-2025, positioning the peninsula as a global CDMO hub. Emerging regions join the trend: the UAE committed USD 300 million to a disposable-based biosimilar JV, and South Africa’s Biovac installed a 2,000 L suite for vaccine surge capacity.

Regulatory Landscape
Regulatory expectations for single-use systems are tightening around polymer characterization, extractables and leachables (E&L), and sterile contamination control, while remaining broadly supportive of validated disposable substitutions for stainless equipment. In the United States, USP <665> became effective on May 1, 2026, formalizing baseline requirements for plastic components and systems used in manufacturing biopharmaceutical drug substances and products; this raises the bar for material traceability and testing packages across bags, tubing, connectors, and assemblies. In Europe, EU GMP Annex 1 continues to anchor sterile manufacturing through a contamination control strategy (CCS) and risk-based qualification that extends to single-use fluid paths, filters, and aseptic connections. For advanced therapies, the EMA guideline on quality, non-clinical, and clinical requirements for investigational ATMPs (effective July 1, 2025) reinforces robust manufacturing controls and documentation for closed, disposable workflows common in autologous cell therapies. Industry alignment efforts also advanced in April 2026 when BioPhorum and BPSA published an updated Single-Use User Requirements (SUUR) Toolkit aligned with ASTM E3051-25 and EU GMP Annex 1, helping standardize user-supplier communication for single-use qualification and change management.
Competitive Landscape
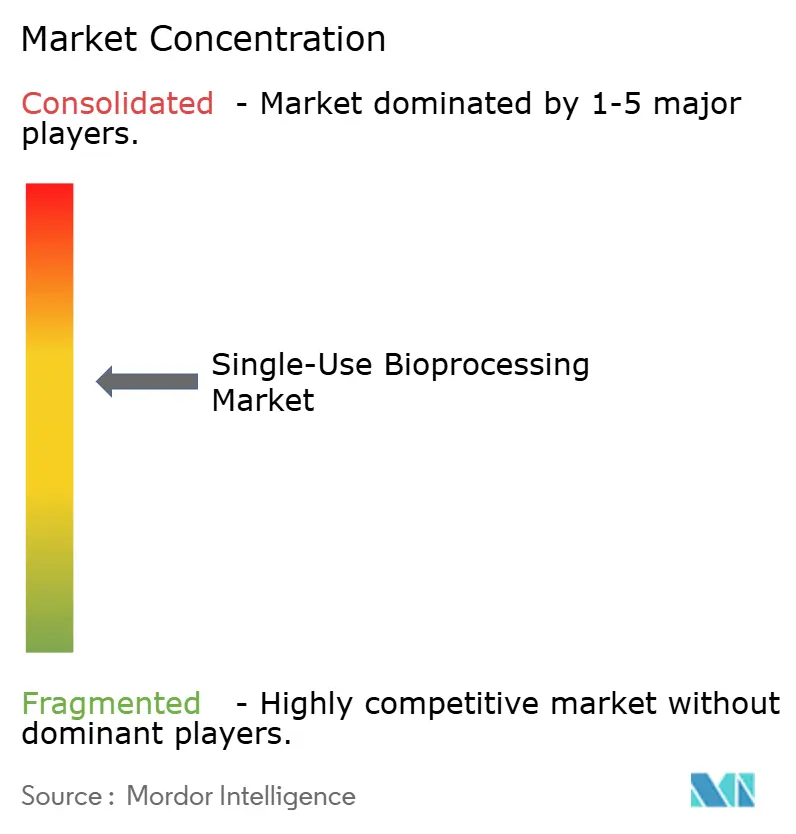
Market concentration is moderate. Cytiva and Sartorius collectively dominate bioreactor volumes through proprietary bag geometries and sensor integration, discouraging cross-platform mixing. Suppliers compete on volume range, plug-and-play assemblies, and data connectivity. Repligen’s FlowVPE sensor illustrates how inline analytics add high-margin attachments to consumables. Patents filed with the USPTO in 2024-2025 show 40% focus on sensors or data platforms, underlining this pivot.
Smaller entrants exploit niches. PBS Biotech targets oxygen-intensive microbial fermentations, while Cellexus serves closed cell-therapy workflows unmet by stirred-tank incumbents. Downstream continuous processing remains white space; membrane adsorber and high-capacity TFF launches aim to displace resin-heavy columns. Sustainability differentiation is nascent but rising: the Sartorius-Veolia polymer-recovery pilot offers early-mover credibility ahead of expected EU take-back mandates.
Supply-chain resilience surfaced as a strategic priority after a 2025 European resin-plant fire doubled lead times for 200 L bags. Thermo Fisher’s January 2026 joint venture with a polyolefin producer exemplifies vertical integration to lock in film supply. Similar moves are anticipated from other top-tier vendors as raw-material risk management becomes integral to sustaining the single-use bioprocessing market.
Single-Use Bioprocessing Industry Leaders
-
Sartorius AG
-
Thermo Fisher Scientific
-
Eppendorf AG
-
Merck KGaA
-
Danaher Corporation (Cytiva)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Opportunities are concentrating around capacity build-outs that standardize on single-use trains, plus enabling technologies that reduce changeover time and increase process control fidelity across multiproduct facilities. Multiple 2026 expansions highlight where demand is being operationalized: FUJIFILM Biotechnologies opened a USD 540 million expansion in Teesside, England featuring 2,000 L and 5,000 L single-use bioreactors (February 2026), WuXi Biologics completed its first GMP production campaign at its 9,000 L MFG17 drug substance facility in Shanghai using single-use bioreactors (June 2026), and Bora Biologics added a Rockville, Maryland site in July 2026, taking installed single-use bioreactor capacity to 20,000 L across two FDA-registered facilities. These projects expand the addressable pull-through for recurring consumables (bags, tubing, sterile connectors, filters) and for the supporting validation and E&L documentation demanded by customers operating under US and EU GMP frameworks.
White-space persists in downstream and in facility-wide interoperability where buyers want faster setup, fewer sterility breach points, and smoother digital integration. The push toward standardized sterile connection and fluid-management hardware is reinforced by new single-use disconnect formats introduced in 2026, while BioPhorum roadmapping work keeps attention on modularity, flexibility, and automation/analytics as enabling capabilities. Sustainability and circularity pressures, especially in Europe, also create room for take-back logistics and designs that support polymer recovery, with pilots such as the Sartorius-Veolia effort in Lyon providing a template for suppliers to differentiate beyond pure performance in tenders that increasingly include plastic-intensity and end-of-life requirements.
Recent Industry Developments
- July 2026: CPC Biotech launched the RevolveSD Series, a one-inch, single-use sterile disconnect designed to avoid traditional clamps or sealers during fluid-path changes. The product targets faster and more consistent aseptic setups in complex single-use assemblies, supporting higher-throughput operations in multiproduct suites.
- June 2026: Sartorius and LFB Biomanufacturing expanded their partnership to provide an integrated DNA-to-Phase I clinical drug substance program. The broadened scope ties single-use upstream and downstream workflows more tightly to CDMO-style rapid execution, increasing demand for qualified disposable assemblies and standardized documentation.
- June 2025: Sartorius Stedim Biotech almost doubled cleanroom space in France to 9,000 m2 to support demand for single-use solutions. The added controlled manufacturing space strengthens supply availability for consumables and assemblies, which is critical for customers managing lead-time risk in commercial and clinical production.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the single-use bioprocessing market covers revenues generated from disposable, pre-sterilized systems and consumables used to develop and manufacture biologics, across upstream steps, downstream steps, and supporting operations in biomanufacturing.
Scope exclusions: we exclude general lab plastics that are not qualified for bioprocess manufacturing use, along with non-bioprocess single-use medical disposables used in patient care.
Segmentation Overview
-
By Product
- Single-Use Bioreactors
- Filtration Assemblies
- Media Bags & Containers
- Mixers & Blenders
- Tubing & Connectors
- Single-Use Sensors & Analytics
- Chromatography & Purification Columns
- Sampling & Aseptic Transfer Systems
- Other Components (Single-Use Sampling Probes and Single-Use Mixing Impellers, among others)
-
By Workflow Stage
- Upstream Processing
- Downstream Processing
- Ancillary Operations (Formulation and Fill-Finish)
-
By Application
- Conventional Biopharmaceuticals
- Regenerative Medicine (Advanced Therapies)
- Other Applications (Diagnostics, Research, among others)
-
By Scale
- Clinical Scale
- Commercial Scale
-
By End User
- Biopharmaceutical Companies
- Academic and Research Institutes
- Contract Research Organizations (CROs) and Contract Development and Manufacturing Organizations (CDMOs)
-
By Geography
-
North America
- United States
- Canada
- Mexico
-
Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
-
Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
-
Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
-
South America
- Brazil
- Argentina
- Rest of South America
-
North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with public life science production indicators and regulatory context, and then it was narrowed to signals that map closely to single-use adoption. Sources reviewed included, as examples, FDA databases and guidance pages, EMA public documents, OECD health and biotech statistics, UN Comtrade trade codes for relevant polymers and biotech equipment groups, and peer-reviewed journals covering single-use materials, leachables, and extractables.
We also used company annual reports, investor decks, earnings call transcripts, and reputable press to capture capacity additions, therapy pipeline momentum, and product mix movement between upstream and downstream operations. To avoid over-relying on narrative claims, we cross-checked select company financials and patent activity using approved paid subscriptions for company intelligence and patent databases. The desk sources listed above are illustrative and not exhaustive, and many other public references were used for data collection, validation, and research clarification.
Primary Interviews and Surveys
Primary work was used to pressure-test adoption rates, typical spend per facility, and how quickly end users are moving from stainless to hybrid or fully single-use lines. We spoke with manufacturers, component suppliers, contract manufacturing teams, and engineering or quality stakeholders across the Americas, EMEA, and APAC so the final model reflects different production scales and compliance practices.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 12% | APAC: 40% |
| Mid tier: 48% | Functional/Unit leaders: 40% | EMEA: 36% |
| Smaller Players: 17% | Managers: 48% | Americas: 24% |
Market-Sizing & Forecasting
Sizing was built using a top-down approach where biologics manufacturing activity and capacity expansion signals were translated into a demand pool for single-use systems, and then filtered through realistic adoption and replacement patterns. To keep totals grounded, we corroborated with selective bottom-up checks, such as sampled pricing for major consumable groups multiplied by typical run-rate volumes for a defined set of facilities, followed by distributor and integrator channel checks.
Key inputs that shaped the model included biologics and vaccine manufacturing capacity additions, the share of facilities running multi-product campaigns, typical batch scale progression from clinical to commercial, single-use penetration by workflow step (for example, upstream versus filtration-heavy downstream), and average replacement frequency for bags, assemblies, and sensors. When part of the chain had limited visibility, gaps were handled by using conservative ranges agreed in interviews, and then the assumptions were tightened until they aligned with independent activity indicators.
For forecasting, scenario analysis was used so adoption paths could reflect different build-out speeds and sustainability-related constraints (such as waste handling or polymer availability). The final growth path was then sanity-checked against expert consensus on pipeline-driven demand and regional investment cycles, and only then were the segment totals rolled up to the market level.
Data Validation & Update Cycle
Outputs were validated through multi-step checks that compare the model to independent signals, including biomanufacturing expansion announcements, public regulatory activity that affects production readiness, and observable shifts toward modular facilities. Outliers were reviewed, assumptions were revisited, and follow-up calls were triggered when a variance could not be explained by geography, product mix, or timing.
Before sign-off, the work is reviewed by another analyst to confirm math accuracy, consistent definitions, and reasonable input ranges. The report is refreshed annually, and interim updates are made when material events occur, such as major capacity additions, supply constraints, or policy changes. Right before delivery, a final pass is completed so clients receive the most current view available at that time.
黑料不打烊's Single Use Bioprocessing Market Size Versus Other Published Estimates
Published market values for single-use bioprocessing often disagree because firms do not always count the same things, or they pick different starting years and currency timings. Differences also show up when one estimate treats ancillary operations and downstream assemblies as a smaller add-on, and another includes them more broadly.
Key gap drivers in this market usually come from how workflows are scoped (upstream only versus end-to-end), how fast average selling prices are assumed to rise for consumables, and whether the forecast path assumes steady capacity ramping or a faster scale-up linked to cell and gene therapy activity. Facility build-out signals and region-by-region investment timing also matter, because the mix of clinical-scale and commercial-scale production can move quickly and it changes typical consumable usage.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 28.92 B (2025) | |
| Industry Publisher A | USD 36.13 B (2025) | Uses a broader revenue scope that can pull in adjacent single-use services and peripheral lab-use consumables, and it applies a higher near-term penetration level for downstream and support assemblies. |
| Industry Publisher B | USD 31.94 B (2025) | Builds the value as an all-in market that may mix goods with service value capture, and it can reflect a different inflation pass-through and short-window growth assumption for 2024 to 2025. |
Capacity expansion announcements, stated single-use line conversions, and workflow-level adoption checks are the evidence points that keep 黑料不打烊 tied to biomanufacturing-qualified single-use systems rather than peripheral lab consumables or bundled services, which explains most of the spread seen across published 2025 values.


Key Questions Answered in the Report
How fast is the single-use bioprocessing market expected to grow between 2026 and 2031?
It is forecast to expand at a 14.2% CAGR, rising from USD 33.03 billion in 2026 to USD 64.12 billion by 2031.
Which region will register the highest growth?
Asia-Pacific is projected to post the fastest pace at 15.42% CAGR through 2031, driven by Chinese and Indian capacity additions.
What product line is growing quickest?
Disposable sensors and analytics are set to increase at a 16.25% CAGR, propelled by AI-enabled control requirements.
Why are CDMOs adopting single-use platforms rapidly?
Serving many clients demands fast changeovers, and single-use assemblies replace multi-day cleaning with quick bag swaps, enabling a 14.82% CAGR for CDMOs.
What is the main supply-chain risk?
Tight availability of medical-grade polymer film, highlighted by an eight-week shortage after a 2025 European plant fire, has led suppliers to seek vertical integration.
How are regulators influencing adoption?
FDA and EMA guidance in 2024-2025 explicitly support validated disposable replacements for stainless steel, removing prior comparability study hurdles.
Page last updated on:



