
Saudi Arabia Data Center Server Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
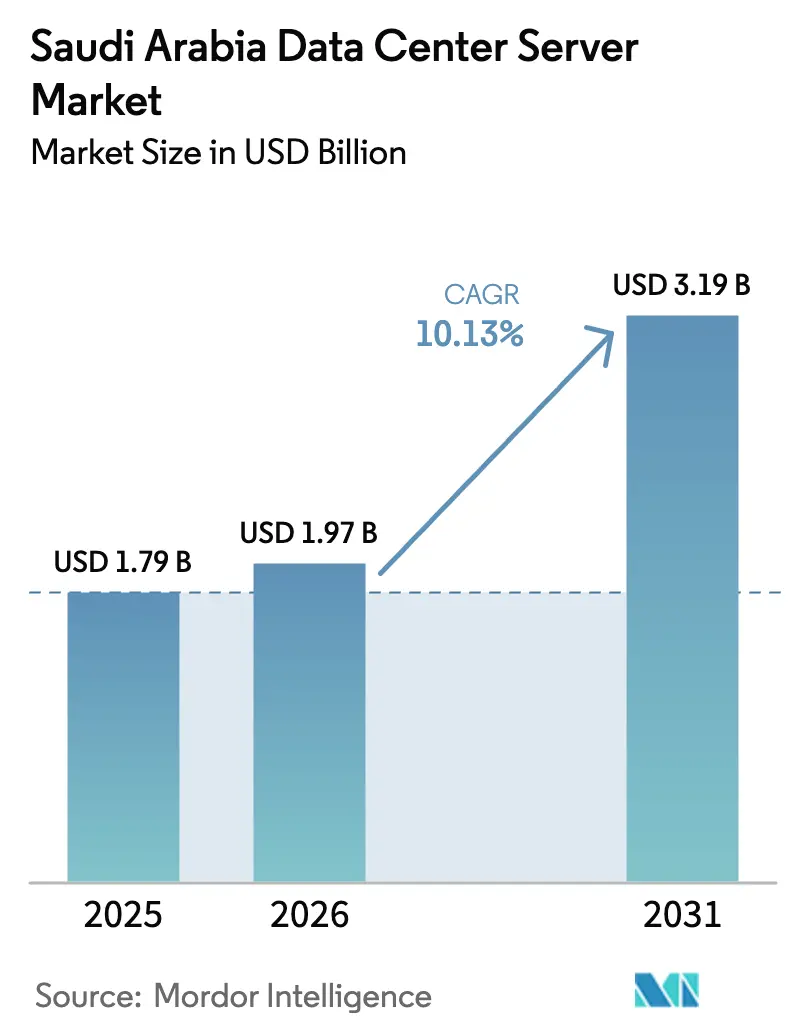
| Base Year Market Size (2025) | USD 1.79 Billion |
| Market Size (2026) | USD 1.97 Billion |
| Market Size (2031) | USD 3.19 Billion |
| Growth Rate (2026 - 2031) | 10.13 % |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Saudi Arabia Data Center Server Market Analysis by 黑料不打烊
Saudi Arabia data center server market size in 2026 is estimated at USD 1.97 billion, growing from 2025 value of USD 1.79 billion with 2031 projections showing USD 3.19 billion, growing at 10.13% CAGR over 2026-2031. Sustained growth is anchored in Vision 2030, which positions the Kingdom as the Gulf’s digital hub; mandatory data-residency rules and large-scale hyperscale capital commitments continue to accelerate demand for locally deployed servers. Rising AI projects, sovereign cloud mandates, and green energy incentives in Special Economic Zones are combining to reshape procurement patterns toward high-density, liquid-cooled systems. Hyperscale operators that entered the market only recently are now outspending traditional telco-dominated data center operators, shifting revenue toward rack-scale GPU platforms. Meanwhile, talent shortages and supply-chain gaps for advanced cooling components temper near-term deployment velocity but do not alter the longer-term expansion outlook of the Saudi Arabia data center server market.
Key Report Takeaways
- By data-center tier, Tier 3 installations commanded 71.28% of the Saudi Arabia data center server market share in 2025; Tier 4 is the fastest-growing tier, advancing at a 12.08% CAGR.
- By form factor, half-height blades accounted for 62.74% of the Saudi Arabia data center server market size in 2025, whereas quarter-height and micro-blade servers are growing at a 10.36% CAGR.
- By application, AI/ML workloads occupied 36.42% of market revenue in 2025; virtualization and private cloud workloads show the highest forecast CAGR at 10.56% to 2031.
- By data-center type, colocation facilities led with 53.62% revenue share in 2025, while hyperscale providers are projected to expand at a 11.74% CAGR through 2031.
- By end-use industry, IT & telecom retained 31.88% share in 2025, while manufacturing and Industry 4.0 workloads are projected to grow at an 10.96% CAGR.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Saudi Arabia Data Center Server Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Accelerating hyperscale cloud provider investments | +2.8% | National, concentrated in Riyadh, Jeddah, Dammam | Medium term (2-4 years) |
| Government-backed digital transformation (Vision 2030 & smart cities) | +2.1% | National, with early gains in NEOM, Red Sea Project | Long term (≥ 4 years) |
| Rapid growth in 5G and IoT traffic | +1.7% | Urban centers, expanding to rural areas | Short term (≤ 2 years) |
| Rising demand for AI/ML & HPC workloads | +2.4% | National, with concentration in Riyadh tech corridors | Medium term (2-4 years) |
| Mandatory local data-residency regulations | +1.8% | National, particularly government and BFSI sectors | Short term (≤ 2 years) |
| Green-energy pricing incentives in SEZs | +0.9% | Special Economic Zones, NEOM, industrial cities | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Accelerating Hyperscale Cloud Provider Investments
Hyperscale commitments have redrawn the capital map of the Saudi Arabia data center server market. AWS allocated USD 5.3 billion to new cloud zones, Microsoft partnered with Aramco Digital on sector-specific clouds, and Google Cloud sealed local partnerships that require rack-scale liquid-cooled GPU clusters.[1]Armada,"Aramco, Armada, and Microsoft Collaborate to Deploy World’s First Industrial Distributed Cloud," armada.aiThese deployments favor micro-blade and quarter-height architectures to maximise compute density and drive down watts-per-teraflop. Cost-recovery models centre on economies of scale, putting pressure on legacy vendor margins even as overall unit demand rises. Competitive entrance of multiple global platforms is therefore simultaneously enlarging and commoditising hardware supply.
Government-backed Digital Transformation (Vision 2030 & Smart Cities)
Vision 2030 embeds digital infrastructure across every megaproject, from NEOM’s USD 5 billion net-zero AI factory to nationwide cloud-first directives. The Saudi Data and AI Authority enforces data-sovereignty rules that guarantee steady domestic server demand. Edge nodes placed along Riyadh and Jeddah smart-traffic corridors handle high-volume camera streams and public-safety analytics, while 100,000 nationals are enrolled in government-funded ICT upskilling to staff new facilities. As a result, the Saudi Arabia data center server market now prioritises edge-hardened, renewable-powered designs that can operate in desert climates without compromising compute density. NEOM's USD 5 billion AI factory partnership with DataVolt exemplifies how megaprojects are creating demand for specialized server configurations that integrate renewable energy systems with high-performance computing clusters. [2]NEOM,' DataVolt and NEOM to develop regions first net-zero AI factory." neom.com
Rapid Growth in 5G and IoT Traffic
Telecommunications operators deploy ruggedised micro-blades to support autonomous vehicle telemetry, industrial automation, and AR/VR services that demand sub-20 ms latency. Manufacturing plants leveraging Industry 4.0 produce sensor floods that must be processed locally for predictive maintenance. The Saudi Arabia data center server market therefore sees rising demand for small-footprint, high-core-count units capable of operating in non-traditional data-hall environments.
Rising Demand for AI/ML & HPC Workloads
Sovereign AI spending shapes server configurations across the Kingdom. HUMAIN procured 18,000 NVIDIA Blackwell GPUs, while Aramco’s Dammam-7 supercomputer delivers 55.4 petaflops for reservoir simulation. New Arabic LLM initiatives require petascale clusters fitted with direct liquid cooling. Healthcare AI for imaging and BFSI AI for fraud detection intensify the need for GPU-dense servers with ultralow latency. The Saudi Arabia data center server market is consequently tilting toward power-hungry, accelerator-rich racks that necessitate facility-wide electrical and cooling upgrades.
Restraints Impact Analysis*
| Restraint | (~)% Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing number of data-security breaches | -0.8% | National, particularly affecting government and BFSI sectors | Short term (≤ 2 years) |
| High CAPEX for next-gen server hardware | -1.2% | National, with greater impact on SME deployments | Medium term (2-4 years) |
| Shortage of bilingual (Arabic/English) DC talent | -0.9% | National, acute in specialized AI and HPC roles | Long term (≥ 4 years) |
| Supply-chain delays for liquid-cooling components | -0.7% | National, affecting hyperscale and AI-focused deployments | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Increasing Number of Data-Security Breaches
Rising cyber incidents prompt the Saudi Arabian Monetary Authority to mandate hardware-level security modules and encrypted drives. Compliance adds 15–20% to server bill-of-materials and elongates procurement cycles because only a handful of global vendors meet EAL4+ certification thresholds.[3]Saudi Arabian Monetary Authority,"Cyber Security Framework Saudi Arabian Monetary Authority," sama.govAir-gapped configurations demanded for critical national infrastructure further swell capital outlays as redundant clusters are provisioned to maintain isolation.
High CAPEX for Next-Gen Server Hardware
GPU-accelerated nodes cost up to 5× more than legacy x86 servers. When coupled with 25–30% additional spend for liquid cooling and high-density power distribution, many firms—especially SMEs—delay refresh cycles. The pricing gap drives some enterprises toward OPEX-based public cloud, moderating direct hardware demand and affecting the slope of the Saudi Arabia data center server market growth curve.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Data-Center Tier: Mission-Critical Workloads Drive Tier 4 Adoption
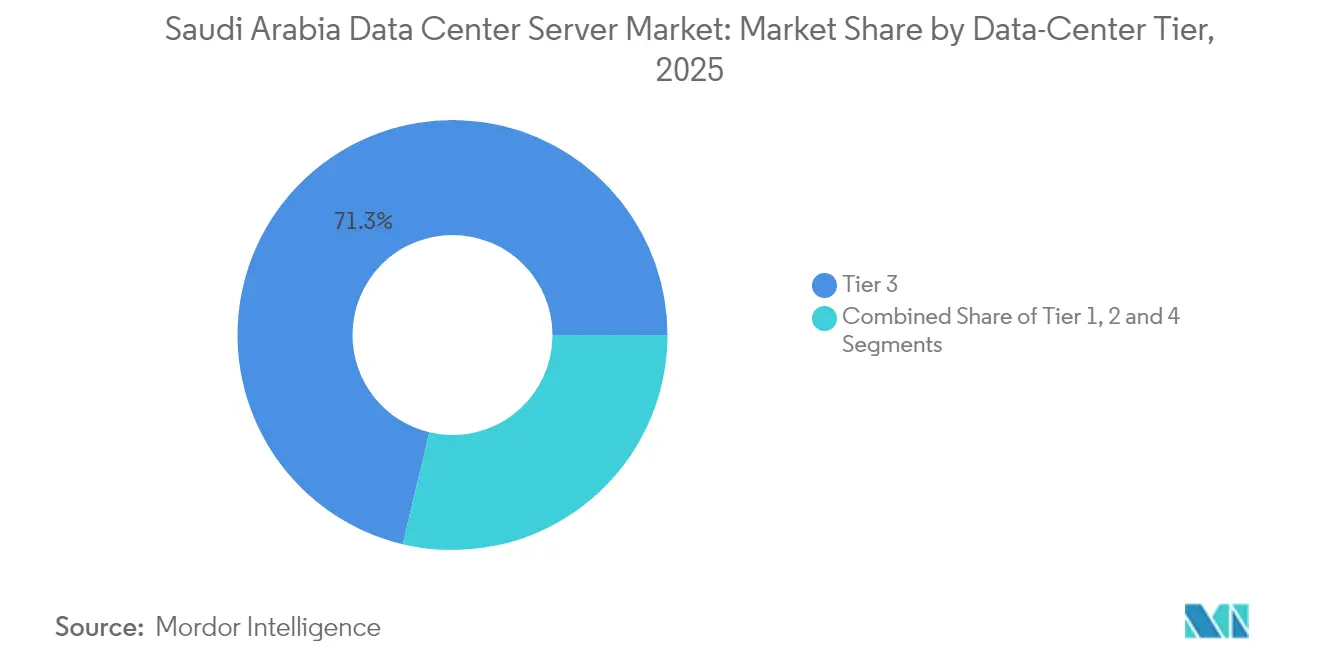
Tier 3 facilities captured 71.28% of 2025 shipments, giving the Saudi Arabia data center server market size a dominant mid-tier profile. Enterprises appreciate concurrent maintainability without the premium of full fault tolerance. Yet Tier 4 racks, essential for AI training pipelines and high-value transactions, are growing 12.08% annually. Government policy mandating 99.995% availability for national AI services accelerates this shift. Over the forecast window, Tier 4 clusters inside hyperscale campuses and financial data centers are expected to erode the Tier 3 share as service-level agreements tighten.
Continued migration away from Tier 1 and Tier 2 is evident: legacy web-hosting workloads are being re-platformed into multitenant Tier 3 halls, while low-risk dev-test environments increasingly spin up in public cloud. The Saudi Arabia data center server industry therefore pays closer attention to future-proofing Tier 4 designs with recycled water loops and grid-interactive UPS systems that align with net-zero mandates


By Form Factor: Micro-Blades Gain Traction in Edge Deployments
Half-height blades owned 62.74% revenue in 2025, underscoring their versatility across mixed enterprise loads. Nevertheless, quarter-height and micro-blade nodes are projected to grow at 10.36% CAGR as telecom operators and smart-city integrators deploy compute at the edge. These smaller blades shorten the distance between sensor and inference, crucial for traffic analytics and industrial controls. The Saudi Arabia data center server market size for edge-class micro-blades is therefore forecast to rise alongside 5G densification.
Supermicro’s rack-scale partnership with DataVolt pairs chassis-level liquid cooling with 100 kW racks, illustrating how form-factor evolution aligns with thermal management innovation. Full-height blades remain relevant for single-server peak-performance tasks but are niche compared with density-optimised micro-blade designs.
By Application/Workload: AI/ML Leads Despite Virtualization Growth
AI/ML workloads already command 36.42% share of deployed compute in 2025. This share should persist until 2031 because sovereign AI factories and language-model research consume multi-node GPU clusters. In parallel, virtualization and private-cloud workloads expand at 10.56% CAGR as medium-sized enterprises modernise infrastructure, leveraging abstraction to boost utilisation. This dual dynamic supports stable demand across both accelerator-rich and CPU-centric SKUs, further diversifying the Saudi Arabia data center server market.
High-performance computing (HPC) remains concentrated in energy and academia, while storage-heavy archival nodes grow to satisfy regulatory retention rules.

By Data Center Type: Hyperscalers Challenge Colocation Dominance
Colocation held 53.62% share in 2025, benefiting from enterprises that want control without building proprietary sites. Hyperscale footprints, however, are rising at 11.74% CAGR as global clouds roll out kingdom-specific regions, absorbing the lion’s share of next-generation GPU orders. This evolution directly lifts the Saudi Arabia data center server market share for ODM-style white-box suppliers who cater to cloud specifications.
Enterprise and edge micro-data centers remain niche yet strategically important where latency or sovereignty prohibits shared infrastructure. Telcos now reposition their mega halls as carrier-neutral hubs, bundling managed cloud and interconnect services to fend off hyperscale encroachment.
By End-Use Industry: Manufacturing Emerges as Growth Leader
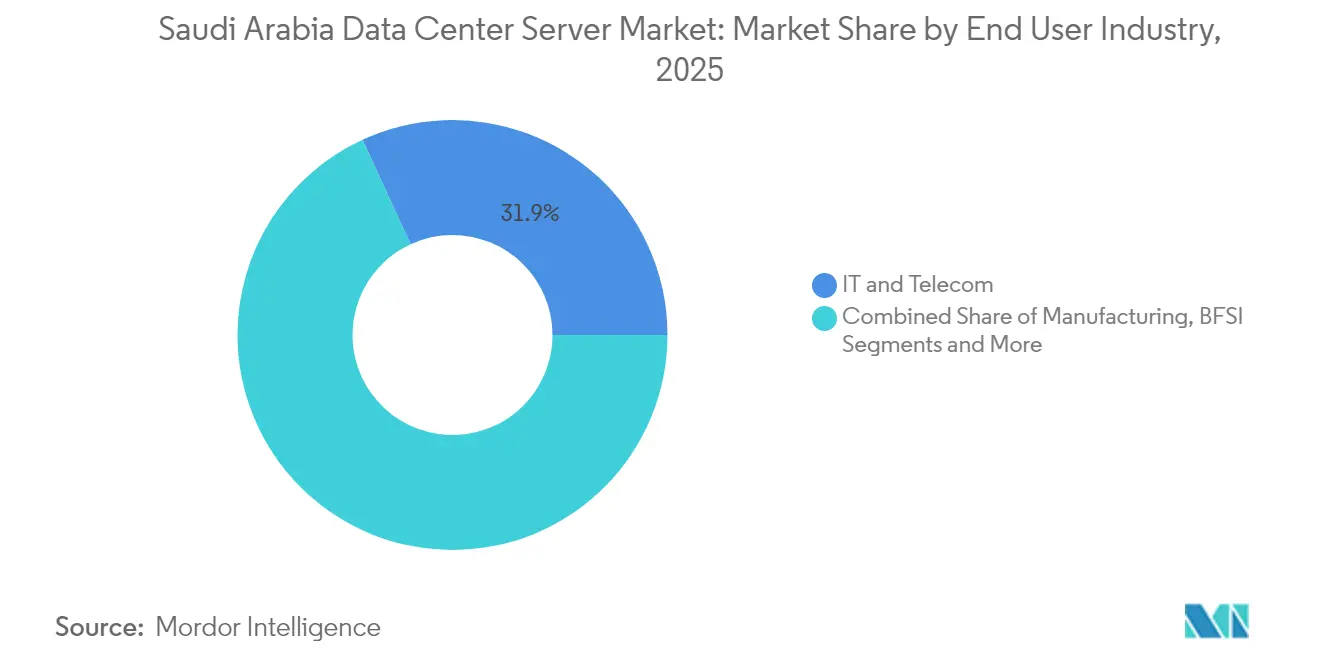
IT and telecom organisations still occupy 31.88% of 2025 shipments, but manufacturing and Industry 4.0 workloads accelerate at an 10.96% CAGR as Aramco and NEOM embed predictive maintenance, robotics, and quality-control AI. These deployments require deterministic latency and rugged design, pulling specialised server SKUs into factory floors. The Saudi Arabia data center server industry thus gains a diversified demand base, less reliant on pure IT refresh cycles.
BFSI adoption benefits from open-banking regulations and faster payment rails, spurring GPU-enabled fraud-detection clusters. Healthcare digitisation adds imaging-specific accelerators, while government and defence prioritise hardened, sovereign nodes with dedicated key-management hardware.
Geography Analysis
Riyadh anchors major share of national server-rack shipments, housing ministry data centers, fiscal headquarters, and the majority of hyperscale cloud zones. Jeddah leveraging international subsea cables and logistics-driven demand that extends into hospitality and pilgrimage-supporting smart-city projects. Dammam and the Eastern Province represent the industrial heartland, where petrochemical and energy HPC clusters run subsurface modeling and refinery optimisation simulators.
NEOM introduces a northern pole of growth with its USD 5 billion DataVolt AI factory. Once operational, this plant alone will lift the Saudi Arabia data center server market size materially, particularly for liquid-cooled GPU sleds powered by on-site renewables. Secondary cities such as Al-Khobar, Taif, and Medina begin to adopt mini-hubs as digitisation policies trickle outward, although share remains capped by limited power redundancy and talent pools.
Regional distribution is therefore evolving from a Riyadh-centric topology to a multi-hub network that aligns with submarine cable landings, industrial corridors, and smart-city clusters. This dispersion creates new edge-node opportunities, extending the Saudi Arabia data center server market into non-traditional localities.
Regulatory Landscape
Saudi Arabia regulates data center and cloud operations through a multi-body framework that shapes in-country server procurement. The Communications, Space, and Technology Commission (CST) enforces Data Centre Services Regulations (in force since January 1, 2024) and operates a provider registration regime with four categories (Qualifying, Limited, Standard, and Advanced). Registrations are valid for three years with renewal provisions and zero fees, and include requirements such as energy management and sustainability planning. Data governance requirements are reinforced by the Saudi Data and AI Authority (SDAIA) under the Personal Data Protection Law (PDPL), while the National Cybersecurity Authority (NCA) sets cloud cybersecurity controls, raising compliance expectations for sovereign and regulated workloads that must remain locally hosted.
Beyond ICT rules, large data center developments are increasingly coordinated with national power and infrastructure planning through entities such as the Ministry of Energy and the Saudi Electricity Regulatory Authority (SERA). This coordination increases the importance of power availability, efficiency, and sustainability documentation in site and equipment decisions. Together, licensing and control frameworks push operators toward compliant, auditable hardware configurations, including security modules and encrypted storage where required by sector policies, and support demand for high-density systems that meet performance needs within tighter energy and reporting constraints.
Competitive Landscape
The Saudi Arabia data center server market exhibits moderate concentration. Chinese vendors Huawei and Inspur challenge incumbents with price-competitive, vertically integrated platforms. ODM suppliers—Supermicro, Quanta, and Wiwynn—expand rapidly by fulfilling hyperscale custom SKUs, often bypassing traditional distributors.
Strategy is tilting toward verticalisation; vendors develop energy-sector-specific cabinets certified for hazardous zones, or fintech-grade blades with hardware roots-of-trust. DataVolt’s USD 20 billion order for Supermicro’s rack-scale GPU systems exemplifies this pivot, giving rise to locally headquartered system integrators capable of bridging global supply chains with compliance know-how. Meanwhile, the shortage of bilingual engineers drives joint academies between vendors and universities to safeguard future talent intake.
Regulatory uncertainty around forthcoming Global AI Hub Law may alter competitive rules by permitting “data embassies” that operate under foreign jurisdiction. Vendors able to guarantee sovereign enclaves without contravening residency law will secure differentiated positioning in the Saudi Arabia data center server market.
________________________________________
Saudi Arabia Data Center Server Industry Leaders
-
Dell Technologies
-
Hewlett Packard Enterprise
-
IBM Corporation
-
Lenovo Group Ltd
-
Cisco Systems Inc.
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
One clear opportunity is the build-out of AI-optimized and sovereign-capable compute inside Saudi Arabia, supported by named national programs and capacity targets. MCIT and SDAIA have communicated a national target of 1.5 GW of data center capacity by 2030, with more than 60 data centers operational as of 2026, total investments exceeding SAR 16 billion, and operational IT load reaching 440 MW in 2025 (up from 68 MW in 2021). As campuses move from shell capacity to fitted halls, server demand concentrates on GPU-dense racks, liquid-cooling compatible platforms, and secure configurations aligned with CST provider obligations, PDPL governance, and NCA cloud controls, especially for public sector workloads and sovereign AI initiatives such as HUMAIN.
A second opportunity is infrastructure localization and deployment models that reduce lead times and compliance friction for operators scaling beyond core hubs. Evidence points to rapid capacity additions and diversification across Riyadh (enterprise and government), Jeddah (Red Sea cable gateway), and the Eastern Province (industrial demand and Gulf connectivity). This mix supports demand for standardized server platforms that can be qualified across multiple sites and tiers, along with edge nodes for smart-city and industrial workloads. The combination of CST registration categories, energy-management requirements, and sustainability planning creates room for suppliers and integrators that bundle compliant server configurations with thermal and power design, particularly where liquid-cooling components and specialized talent remain constraints.
Recent Industry Developments
- July 2026: Quantum Switch Tamasuk (QST) signed a business principle agreement with MCIT to develop and operate 300MW of data center capacity by 2026. The initiative expands capacity in line with Saudi digital ambitions and signals government-backed support for hyperscale deployments.
- July 2026: Saudi Telecom Company (STC) and Humain signed a Memorandum of Understanding through Center3 to form a data center joint venture targeting 1GW capacity (initial 250MW). The collaboration accelerates hyperscale and AI workloads deployment in the country and leverages local and international partnerships to scale capacity quickly.
- June 2026: MagnAI (Magna AI) and Emaar Executive Company signed a strategic collaboration to plan, develop, and deliver sovereign AI data centers and AI Factory infrastructure. The alliance strengthens sovereign AI compute footprint and localized data residency capabilities.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of servers deployed in data centers located in Saudi Arabia, including new installations and refresh purchases across operator-led and enterprise-led facilities. The figures are counted at the equipment level in USD.
Scope exclusions: We exclude data center construction and fit-out items (power, cooling, racks, building works), along with software and managed services that may be bundled in broader data center spending.
Segmentation Overview
-
By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
-
By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
-
By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
-
By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
-
By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- Other End Users
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is used to establish the factual base for supply, demand, and investment signals that drive server purchasing in Saudi Arabia. We review public and official sources such as the Communications, Space and Technology Commission publications, Saudi Central Bank indicators, General Authority for Statistics releases, Saudi Authority for Intellectual Property patent search outputs, and ITU connectivity statistics to understand digital adoption and infrastructure build activity.
The model is then grounded with operator and supplier signals from company annual reports, investor presentations, press releases, reputable business media, and procurement notices where available. To tighten assumptions on shipment timing and pricing ranges, we also use paid subscriptions for company financials and intelligence, news and financials, patent databases, and selective import and export shipment-level views. The desk sources listed here are illustrative, and we checked additional public references for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focuses on clarifying how data center operators and large buyers plan server orders, and what changes in configurations are happening (CPU versus GPU mix, memory intensity, and storage attach). We speak with a mix of data center operators, system integrators, distributors, and enterprise IT leaders across key Saudi hubs to validate demand drivers, typical deal structures, and realistic refresh cycles, and then we recheck the most sensitive assumptions when gaps appear.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 14% |
| Mid tier: 59% | Functional/Unit leaders: 27% |
| Smaller Players: 14% | Managers: 59% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where data center capacity additions and live IT load expectations are translated into server demand, and then converted into USD using realistic configuration-level pricing. To keep the math traceable, inputs include announced and under-construction data center capacity, typical rack densities, virtualization intensity, the share of high-performance compute nodes, average replacement cycles, and import-led lead times that can shift purchases between years.
Those results are then corroborated with selective bottom-up approximations, such as rolling up a sampled set of channel shipments, system integration deal flows, and ASP times volume checks by form factor. When certain tiers or applications lack clean public indicators, gaps are handled by using bounded ranges from interviews and then testing them against capacity and utilization constraints. Forecasting is done using scenario analysis supported by a simple multivariate view, where the capacity pipeline, cloud adoption pace, and AI-related compute intensity are the main drivers agreed with industry respondents.
Data Validation & Update Cycle
Outputs are validated through triangulation across multiple signals, and outliers are investigated before final sign-off. We compare implied server counts and value against independent checks like capacity additions, procurement timing patterns, and typical configuration shifts, and then we run variance checks across years to catch pricing or mix errors.
A multi-step review is completed internally, and re-contacts are triggered when assumptions move beyond agreed interview ranges or when a material announcement changes deployment timing. Reports are refreshed annually, with interim updates when major capacity awards, policy changes, or supply constraints materially alter the outlook. Before delivery, a final review pass is made so clients receive the latest updated view.
黑料不打烊's Saudi Arabia Data Center Server Market Estimate Compared With Other Published Estimates
Published market values for Saudi Arabia data center servers can look far apart because the term is defined differently across sources, and because price and timing assumptions move quickly during an infrastructure build cycle. Differences usually come from what is included in the equipment basket, how hyperscale orders are treated, and whether values are captured at shipment, installation, or contract-commitment stage.
A common gap driver in this market is mixing server spending with full data center build spend, which adds power and cooling and can inflate totals. Another driver is whether accelerator-heavy systems are priced using current high-end configurations or averaged down using legacy enterprise refresh pricing, which can understate the value in expansion years. The spread also widens when estimates are not rechecked after major capacity award changes, which is why our sizing keeps the server-only basket and the timing of deployments explicit before the final number is locked. This modeling choice is used in 黑料不打烊's approach.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 1.79 B (2025) | |
| Trade Journal A | USD 1.33 B (2024) | Uses a broader data center market context and then applies an assumed IT-infrastructure share, which can dilute server value in years where high-end configurations rise. |
| Industry Brief B | USD 3.90 B (2030) | Tracks total data center market investment through 2030, which blends IT equipment with facilities capex and therefore does not isolate server-only spending. |
Looking across the table, the main takeaway is that numbers move based on whether the estimate is server-only, IT-infrastructure only, or full data center investment, and on whether pricing reflects newer compute mixes. By anchoring demand to capacity and deployment timing, and then stress-testing pricing and refresh cycles with interview feedback, the final estimate stays repeatable and easier to reconcile with real procurement behavior.


Key Questions Answered in the Report
What is the current size of the Saudi Arabia data center server market?
The market is valued at USD 1.97 billion in 2026 and is projected to reach USD 3.19 billion by 2031.
Which server workload segment holds the largest share?
AI/ML workloads lead with 36.42% of 2025 revenue, driven by sovereign AI initiatives and large GPU deployments.
Which data-center tier is expanding the fastest?
Tier 4 facilities show the highest growth, advancing at a 12.08% CAGR through 2031 as fault tolerance becomes critical.
Why are micro-blade servers gaining popularity in Saudi Arabia?
Edge computing for 5G, smart-city applications, and industrial IoT demands compact, high-density form factors that micro-blades provide.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities worldwide, split by facility type, component and tier.
- Data Center Cooling Market Cooling across all regions, split by cooling technology, cooling component and facility type.
- Saudi Arabia Hyperscale Data Center Market Saudi Arabia hyperscale sites, split by facility type, component and tier.
- Saudi Arabia Data Center Storage Market Storage demand across Saudi Arabia, covering storage technology, storage type and facility type.
- Saudi Arabia Data Center Cooling Market Cooling demand across Saudi Arabia, covering cooling technology, type and end-user industry.
- Saudi Arabia Data Center Physical Security Market Physical security demand across Saudi Arabia, covering solution type and service type.
- Saudi Arabia Artificial Intelligence (AI) Data Center Market Saudi Arabia's AI facilities, split by facility type, component and tier.
- Saudi Arabia Data Center Processor Market Processors demand across Saudi Arabia, covering processor type, application and architecture.
- Singapore Data Center Rack Market Racks in Singapore, split by rack size, rack height and rack type.
- Saudi Arabia Data Center Construction Market Saudi Arabia construction, split by tier.



