
Riyadh Construction Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 3.17 Billion |
| Market Size (2026) | USD 3.3 Billion |
| Market Size (2031) | USD 4.04 Billion |
| Growth Rate (2026 - 2031) | 4.12 % |
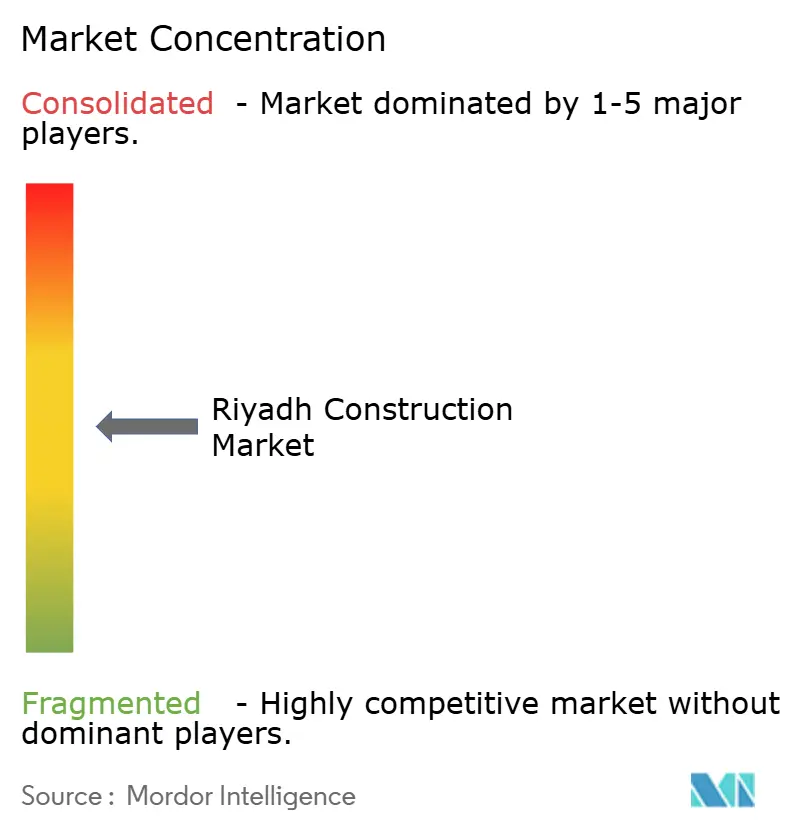
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Riyadh Construction Market Analysis by 黑料不打烊
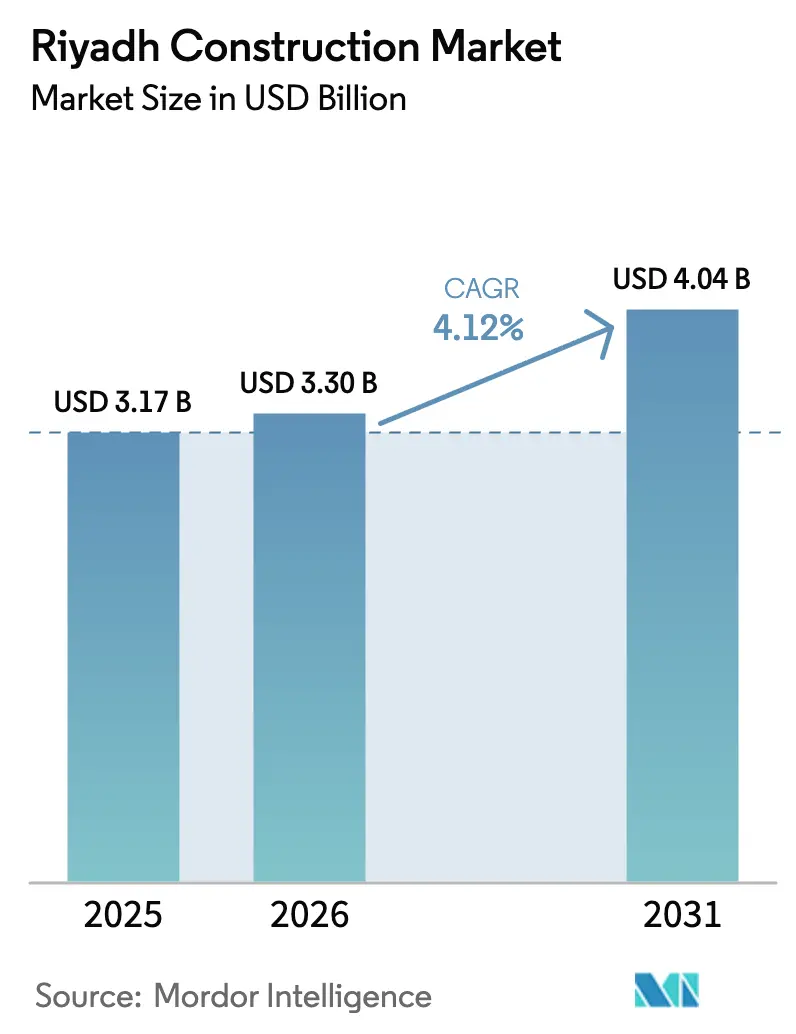
The Riyadh Construction Market size was valued at USD 3.17 billion in 2025 and estimated to grow from USD 3.3 billion in 2026 to reach USD 4.04 billion by 2031, at a CAGR of 4.12% during the forecast period (2026-2031). This steady expansion flows from Vision 2030’s USD 400 billion city-focused investment pool, which is reshaping land use, transportation, housing, and public amenities across the capital. The push is anchored by catalytic schemes such as the USD 180 billion New Murabba downtown and the King Salman International Airport, each positioned to elevate Riyadh’s global standing while unlocking large, multi-year workloads for contractors. Rapid contract-award momentum, stronger private-sector participation, and the institutionalization of digital design mandates further stabilize the growth path. At the same time, material-cost swings and labor shortfalls test profit margins, spurring faster uptake of modular building systems and localized material production hubs.
Key Report Takeaways
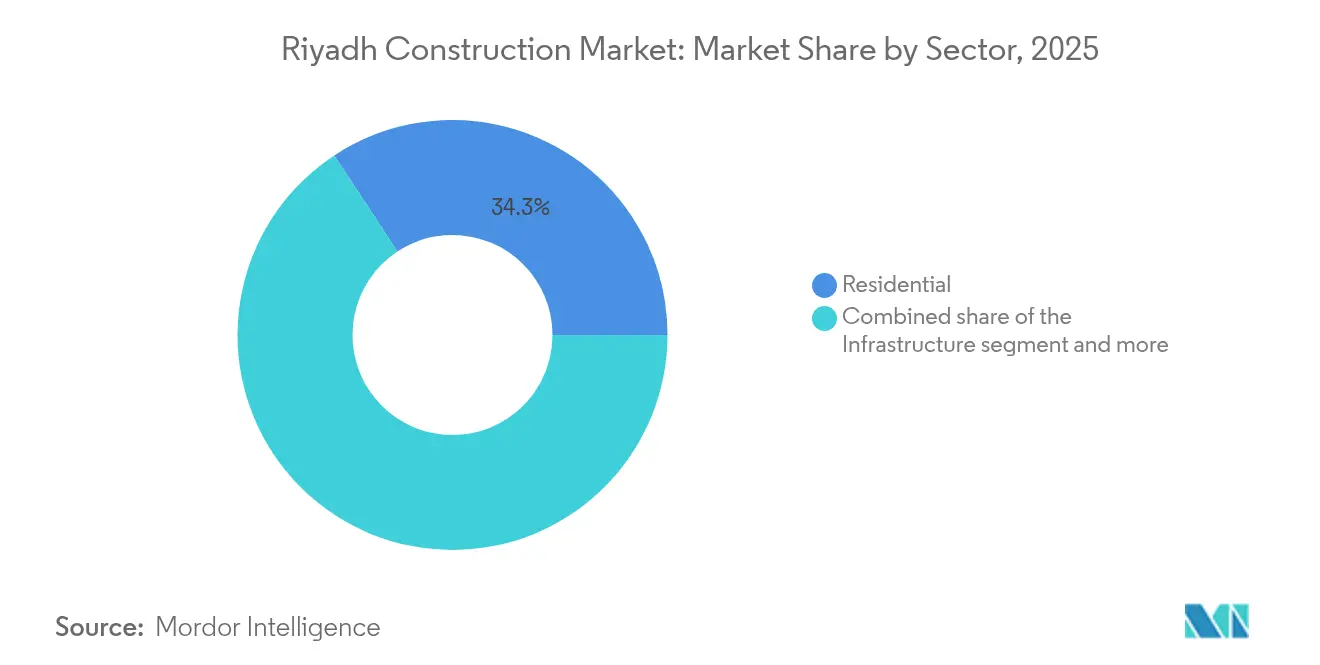
- By sector, residential construction led with 34.27% of the Riyadh construction market share in 2025, while infrastructure is projected to expand at a 5.91% CAGR through 2031.
- By construction type, new-build activity accounted for 79.45% of the Riyadh construction market size in 2025, whereas renovation is advancing at a 4.99% CAGR to 2031.
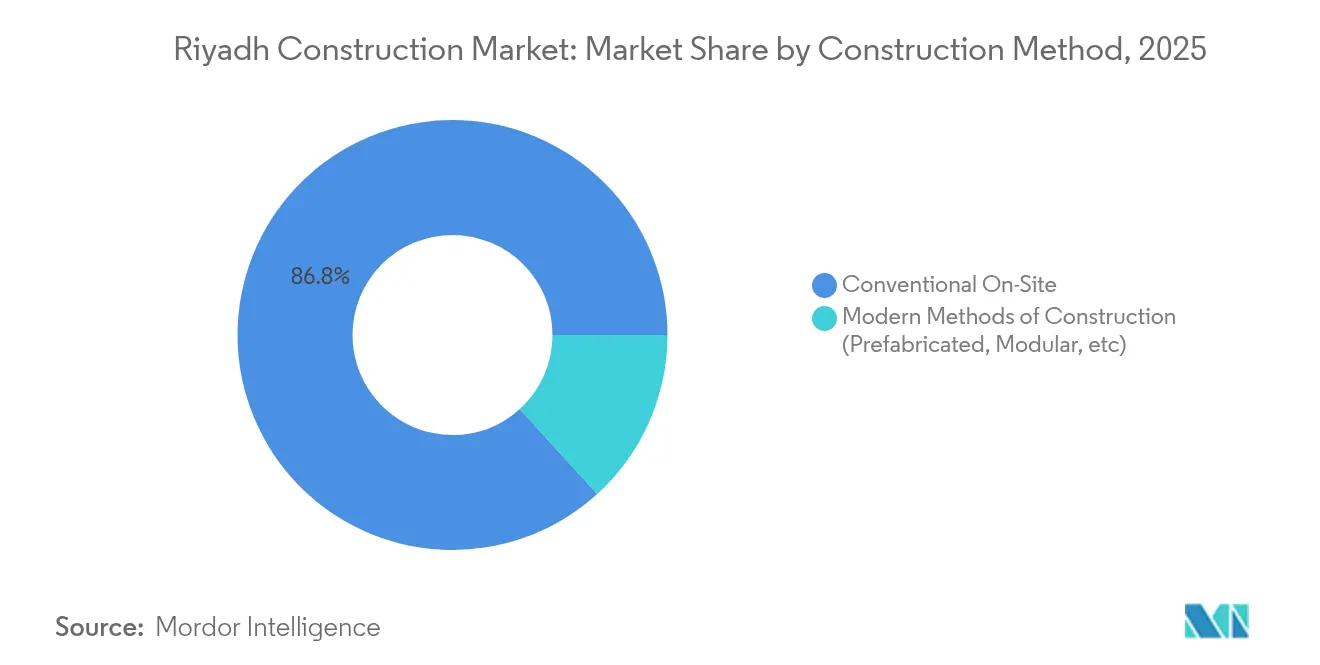
- By construction method, conventional on-site techniques retained 86.75% share of the Riyadh construction market size in 2025, yet modern methods are moving ahead at a 6.50% CAGR.
- By investment source, the public sector captured a 60.78% share of the Riyadh construction market size in 2025; the private segment records the higher CAGR at 5.73% through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Riyadh Construction Market Trends and Insights
Drivers Impact Analysis*
| Driver | (%) Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Vision 2030 giga-project pipeline acceleration | +1.5% | Riyadh core, NEOM & Red Sea tie-ins | Long term (≥ 4 years) |
| Surge in contract awards under Vision 2030 | +1.2% | Riyadh metro area; Eastern Province spillover | Long term (≥ 4 years) |
| Green & sustainable-building mandates | +0.8% | National; early roll-out in Riyadh & Jeddah | Medium term (2-4 years) |
| Modular/off-site methods were adopted to ease labor gaps | +0.6% | Riyadh & major urban nodes | Medium term (2-4 years) |
| Riyadh Expo 2030 urban-revamp program | +0.4% | Riyadh metropolitan area | Short term (≤ 2 years) |
| Digital-twin requirements for new developments | +0.3% | Key cities; Riyadh smart-city focus | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Vision 2030 Giga-Project Pipeline Acceleration
Saudi Arabia’s public ledger lists a pipeline of USD 1.1 trillion, with 70% of allocations in housing, leisure, and cultural developments centered on Riyadh. The King Salman International Airport alone is being developed to handle 100 million passengers annually and targets LEED Platinum status. Qiddiya’s USD 1 billion multipurpose stadium and Diriyah’s USD 63.2 billion heritage complex reinforce the capital’s tourism proposition. Project phasing has been sequenced so that workload peaks around 2025-2026, smoothing resource deployment. Broad use of Building Information Modeling (BIM) across packages reduces design clashes and rework, compresses schedules, and supports a 1.5 percentage-point boost to the overall growth rate.
Surge in Contract Awards Under Vision 2030
High-velocity tendering defines current demand conditions. The Royal Commission for Riyadh City alone released more than USD 3.47 billion equivalent in road projects during 2024, supplying predictable backlogs for civil contractors. Nationally, construction contract value grew 47% year-on-year to USD 49.3 billion in H1 2024, with real-estate and infrastructure schemes in the capital as top contributors. Financing risk is muted because the Public Investment Fund (PIF) commonly sits as an anchor sponsor, signaling payment reliability. Stricter capacity criteria set by the Saudi Contractor Authority further filter entrants, keeping bid lists manageable and margins comparatively stable. Taken together, these factors lift revenue visibility and add roughly 1.2 percentage points to the five-year CAGR outlook[1]ABDULLAH BIN TURKI, “SR13 Billion Riyadh Road Upgrades Awarded,” Royal Commission for Riyadh City, rcrc.gov.sa.
Green & Sustainable-Building Mandates
The 2024 update to the Saudi Building Code introduces SBC 601 energy-performance thresholds, effective June 2025. Requirements around thermal-insulation values, district-cooling hookups, and LEED gold targeting in marquee projects add specialist consulting and materials demand. Local concrete producers, such as Abdallah Abdin Ready-Mix, have already secured Concrete Sustainability Council certification, signaling an early-mover advantage. Government programs like Mostadam provide scoring frameworks that will soon influence refinancing costs, thus embedding sustainability into capital-allocation decisions. The mandate’s incremental efficiency upgrades and corresponding material substitutions lift long-run activity by an estimated 0.8 percentage points[2]KHALID AL-ABDULRAHMAN, “Saudi Building Code 2024—SBC 601 Energy Efficiency Requirements,” Ministry of Municipal, Rural Affairs and Housing, momrah.gov.sa.
Modular/Off-Site Methods were Adopted to Ease Labor Gaps
China Harbour Engineering Company opened a 200,000 m? modular facility in February 2025 to supply Sedra’s prefabricated villas, leveraging robotics for rapid panel assembly. Modular prototypes at NEOM’s The LINE demonstrate 25-30% time savings versus conventional builds, which in turn promote faster revenue recognition for developers. Factory settings improve worksite safety, a factor tied to Saudization rules that require 30% Saudi employment in technical positions. Off-site solutions, therefore, cushion labor-supply shocks while advancing quality control, adding 0.6 percentage points to medium-term CAGR[3]FEIYANG LI, “China Harbour Starts Riyadh Modular Building Factory Operations,” China Harbour Engineering Company, chec.bj.cn.
Restraints Impact Analysis*
| Restraint | (%) Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating building-material costs | -0.9% | National; sharpest in Riyadh hub | Short term (≤ 2 years) |
| Skilled-labor scarcity | -0.7% | Riyadh plus other build-intense zones | Medium term (2-4 years) |
| Lengthy permitting & land-assembly hurdles | -0.5% | Riyadh metropolitan area | Medium term (2-4 years) |
| Water-scarcity compliance costs | -0.3% | Countrywide; water-heavy trades | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Escalating Building-Material Costs
In 2024, cement touched 16-year highs, even as steel shed 4% over nine months, illustrating divergent commodity trajectories. Iron prices fell 10% to roughly USD 769 per ton, whereas cable prices rose 2.6%, blunting any savings from rebar declines. Contractors respond by splitting purchase orders across multiple suppliers and expanding local fabrication footprints, as shown by MS-Metals’ automated plant in Tabuk. Yet volatility complicates fixed-price bids, prompting clients to accept price-escalation clauses. The mix of uncertainties chips 0.9 percentage points off near-term CAGR.
Skilled-Labor Scarcity
Delayed wages, low remuneration, and site-accommodation issues depress retention, especially among specialized trades. Saudization decrees now mandate a 30% local quota across 269 engineering professions, tightening the labor pool. Private institutes such as Nesma High Training Institute are scaling vocational programs, but upskilling cycles take time. Modular factories lighten onsite head-count needs, yet not enough to fully offset shortages. Collectively, the constraint subtracts 0.7 percentage points from growth across the medium horizon.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Sector: Infrastructure Acceleration Outpaces Residential Dominance
The residential segment preserved leadership with 34.27% of the Riyadh construction market share in 2025, backed by National Housing Strategy initiatives to raise ownership to 70% by 2030. Infrastructure, however, registers the swiftest expansion at a 5.91% CAGR through 2031, lifted by USD 3.47 billion worth of road programs and the USD 6.13 billion Riyadh Metro build-out. This pivot enlarges the Riyadh construction market size for heavy civil works and signals widening procurement opportunities for specialized EPC contractors.
Rapid transportation upgrades, such as the 56-kilometer southern ring road, complete with 32 bridges, underscore the shift toward integrated mobility corridors. Energy and utilities projects, including the USD 544 million Jubail desalination link, add resilient demand streams as the urban population swells. Commercial development rides Expo 2030 timelines, while logistics platforms rise amid manufacturing-diversification pushes. Overall, sector interplay keeps order books balanced, maintaining a broad earnings base amid cyclical housing swings.


By Construction Type: Renovation Gains Momentum Despite New-Build Leadership
New construction absorbed 79.45% of spending during 2025, reflecting ground-up mega-projects such as the USD 180 billion New Murabba district. Yet renovation work edges higher at a 4.99% CAGR thanks to retrofits mandated by updated building codes. These upgrades expand the Riyadh construction market size for energy-efficiency solutions and smart-asset management systems.
Legacy road networks are being widened, utilities are modernized to optimize capacity, and public venues undergo green retrofits in advance of Expo 2030. The Saudi Building Code’s retroactive clause pushes older assets to install insulation, high-efficiency glazing, and district-cooling interfaces. Digital CMMS deployments further reduce lifecycle costs, validating the business case for renovation despite higher initial outlays.
By Construction Method: Modern Methods Challenge Conventional Dominance
Conventional on-site activity still claims 86.75% of 2025 volume, driven by established procurement structures and cost familiarity. However, modern methods clock a 6.50% CAGR as labor constraints, safety concerns, and schedule pressures converge. Each new modular factory, exemplified by China Harbour’s 200,000 m? facility, extends capacity to serve giga-projects without logistical bottlenecks.
Industry 4.0 advances, such as 3D printing and robotics, are progressively embedded into off-site lines, yielding consistent component tolerances. BIM integration across design, manufacturing, and assembly stages minimizes errors and supports just-in-time deliveries to congested urban sites. The LINE at NEOM showcases modular high-rise construction at unprecedented scale, setting benchmarks that ripple back into the Riyadh construction market. Given demonstrated time savings of up to 30%, project financiers increasingly favor modern methods to de-risk delivery windows.
By Investment Source: Private-Sector Momentum Builds on Public Foundation
Public funding remained dominant in 2025 at 60.78%, reflecting the PIF’s sponsorship of transformative assets. Yet private capital posts the sharper 5.73% CAGR as clearer legal frameworks and special economic zones reduce entry barriers. The Civil Transactions Law, live since December 2023, bolsters the enforceability of contracts and accelerates dispute resolution, enhancing lender confidence.
Recent examples include USD 10 billion in maritime-industrial offtake deals at Ras Al-Khair and cross-border ventures such as Petro Rabigh’s specialty-chemicals tie-up with India’s Rossari. FDI inflows also track incentive packages of low taxation and customs relief across newly designated zones. The evolving mix invites fresh project-delivery models, PPP, concession, and build-operate-transfer, broadening the Riyadh construction market’s financing toolkit.
Geography Analysis
Riyadh captures the lion’s share of Saudi contract allocations, anchored by mega-schemes like the USD 180 billion New Murabba and the forthcoming airport designed for 100 million annual passengers. The Royal Commission’s road‐upgrade portfolio alone spans 500 kilometers and supports the city’s ambition to double its population by 2030. Capital-city advantages include proximity to regulatory agencies, a mature contractor network, and direct PIF oversight, all of which increase project-execution velocity. Expo 2030 status injects deadline-driven procurement, concentrating activity in the next four years and amplifying auxiliary builds in hospitality and transport.
Beyond the capital, the national map shows complementary but differentiated demand nodes. The Eastern Province leads hydrocarbon-driven civil works, contributing 41% of total contract awards in H1 2024. In the northwest, NEOM’s USD 500 billion blueprint underwrites steady orders for tunneling, utilities corridors, and smart-city infrastructure, though much of the design is managed in Riyadh. The Red Sea Project and Diriyah heritage cluster extend tourism-centric construction, forming an ecosystem of regional mega-projects that share suppliers, labor pools, and technology workflows. Common regulatory baselines such as the 2024 Saudi Building Code unify practices nationwide, but Riyadh remains the administrative nerve center for approvals and finance.
Inter-regional synergies are furthered by nationwide rail and highway linkages, reducing material-delivery times and balancing resource allocation. Contractors headquartered in Riyadh increasingly establish satellite yards near remote giga-projects, yet maintain design hubs in the capital to leverage advisory clusters and digital-twin labs. While water scarcity constraints affect the whole kingdom, Riyadh’s dense consumption profile triggers earlier adoption of reuse systems, providing pilot learnings for replication elsewhere. Overall, the city’s primacy in policy, capital flow, and workforce makes it the fulcrum of the Saudi construction narrative through 2030.
Regulatory Landscape
Construction activity in Riyadh operates under a tightening national framework led by the Ministry of Municipalities and Housing (MOMAH) and the Saudi Building Code (SBC) Center. The 2024 edition of the Saudi Building Code, including SBC 601 energy-efficiency requirements, became mandatory from June 2025, which raises compliance needs around insulation, mechanical-systems integration, and performance documentation on new projects and major upgrades. Permitting and approvals increasingly route through the Balady platform, aligning licensing, inspections, and occupancy procedures, with the occupancy certificate acting as a practical gate for utility activation on completed buildings.
On execution and market entry, government-funded work links to contractor governance through the Saudi Contractors Authority (SCA), which requires registration and relevant classifications for participation in public-sector tenders. Professional practice is controlled via the Saudi Council of Engineers (SCE) for engineering accreditation, including requirements that affect foreign engineering professionals. Legal accountability is reinforced through ten-year solidarity liability for structural defects from the date of delivery, which increases the value of qualified design supervision, documented QA/QC, and insurance-ready contracting structures across Riyadh’s high-value mixed-use and infrastructure packages.
Value Chain Analysis
Riyadh’s construction value chain starts with raw-material procurement (cement, steel, ready-mix, cables, and MEP equipment), then moves through design and engineering, project development, procurement, construction, commissioning, and handover. On the client side, public sponsors and master developers under Vision 2030 set program requirements and delivery models, while procurement and tendering for government work is shaped by classification and participation rules enforced by the Saudi Contractors Authority (SCA). Upstream activities like design, permitting, and compliance depend on engineering consultancies and supervising engineers holding Saudi Council of Engineers (SCE) accreditation, while projects also increasingly align with Saudi Building Code enforcement and digital permitting through Balady.
Downstream, tier-one EPC and construction contractors coordinate delivery through multi-tier subcontracting across civil, MEP, and finishing trades, and they rely on factory-based supply when modern methods are adopted. Integrated delivery approaches are visible among larger players that span engineering, construction, commissioning, and operations, including Nesma & Partners, which positions itself as an end-to-end provider and cites a workforce exceeding 70,000. The chain also reflects growing demand for program management and digital delivery (BIM and digital-twin outputs on public projects), tightening interfaces between designers, contractors, and specialist technology and O&M providers through commissioning and asset-management handover.
Competitive Landscape
Riyadh’s construction arena exhibits moderate concentration: domestic majors, global EPC firms, and joint-venture consortiums jostle for capacity-draining giga-projects. Nesma & Partners, buoyed by PIF affiliations, leads large mixed-use packages and broadened its engineering reach by completing Kent’s acquisition in early 2024. El Seif Engineering, China State Construction Engineering Corporation (CSCEC), and Midmac operate in alliances, exemplified by their USD 1.4 billion Diriyah Opera House win, signaling a preference for consortium formats to share risk and aggregate specialized skills. Egis Group’s purchase of Riyadh designer Omrania brings high-end architectural talent under an international umbrella, sharpening the firm’s cultural-asset credentials.
Technology adoption shapes competitive edges. BIM is mandatory on public projects since 2024, and digital-twin deliverables spark demand for data analytics capability that smaller firms may lack. Robotics-ready modular factories, China Harbour’s new facility being the bellwether, function as competitive moats, allowing rapid unit turnarounds and consistent quality. Firms investing early in such capacity secure repeat orders from giga-projects chasing compressed timelines. Local content targets under Saudization rules reward players with active training programs; Nesma’s vocational institute and CSCEC’s Saudi graduate initiatives showcase the trend.
White-space opportunities blossom in green-material supply chains, carbon-capture-ready cement, and integrated O&M packages that extend revenue beyond handover. Emerging disruptors include AI scheduling platforms that cut idle time and energy analytics firms that optimize district cooling loads. Although newcomers lack scale, they forge partnerships with tier-one builders seeking specialist inputs. As Vision 2030 spending enters peak disbursement, differentiation will hinge on cost-certainty guarantees, ESG compliance, and the ability to localize advanced manufacturing footprints swiftly within Riyadh’s industrial zones.
Riyadh Construction Industry Leaders
Bechtel
Nesma & Partners Contracting
Fluor Corporation
KEO International Consultants
Parsons Corporation
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Regulatory and delivery-system changes create whitespace for compliance-led services and products in Riyadh, especially around the Saudi Building Code 2024 update (SBC 601) becoming mandatory from June 2025. Energy-performance thresholds and documentation requirements drive demand for energy modeling, fa?ade and insulation upgrades, commissioning, and retrofit project management, with renovation activity gaining momentum on the back of code-driven upgrades cited across the market narrative. Digitalized permitting through Balady also favors firms that can industrialize approvals documentation and integrate design, compliance, and inspection readiness early in the project lifecycle.
A second opportunity band centers on governed, program-scale delivery capability and industrialized construction capacity. Vision 2030’s city-focused investment programs and the scale of Riyadh mega-packages (including New Murabba and King Salman International Airport) expand the role of program management, interface coordination, and schedule certainty, where global and local majors compete for framework-style engagements. Modern methods of construction remain a practical lever to address skilled-labor constraints and compressed timelines, supported by capacity additions such as China Harbour Engineering Company’s 200,000 m2 modular facility opened in February 2025 to supply prefabricated villas for Sedra. That expansion supports a wider supply ecosystem for prefabrication, robotics-ready production lines, logistics, and just-in-time site assembly services across the Riyadh metropolitan build cycle.
Recent Industry Developments
- July 2026: Fluor Corporation was selected by Aramco as a Program Management Consultancy contractor under a Long-Term Agreement to support its global capital projects portfolio, including pre-FEED, FEED, engineering, project management, and construction management. The engagement strengthens Fluor's international PMO presence and signals growing demand for governed delivery across Saudi mega-projects.
- May 2026: Nesma & Partners Contracting Co. was awarded a SAR 547.3 million infrastructure development contract by Emaar, The Economic City for the Industrial Valley and Special Economic Zone at King Abdullah Economic City, including Phase 1 of the King Salman Automotive Cluster. The award expands the Riyadh-region industrial ecosystem footprint and accelerates automotive cluster development, driving construction activity.
- January 2026: Nesma & Partners Contracting Co. was winner of the main utilities and civil works package for the Expo 2030 Riyadh site, covering 50km of infrastructure networks. The contract establishes Nesma as a key delivery partner for the Expo-scale program, reinforcing Riyadh megaproject ecosystem participation.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the total value of construction activity delivered within Riyadh, counted as revenues linked to building and civil works across the city, including new build and renovation work executed by contractors and related delivery partners.
Scope exclusions: it does not count stand alone real estate transactions, land values, or pure design-only consulting that is not bundled into delivered construction work.
Segmentation Overview
- By Sector
- Residential
- Apartments/Condominiums
- Villas/Landed Houses
- Commercial
- Office
- Retail
- Industrial and Logistics
- Others
- Infrastructure
- Transportation Infrastructure (Roadways, Railways, Airways, others)
- Energy & Utilities
- Others
- Residential
- By Construction Type
- New Construction
- Renovation
- By Construction Method
- Conventional On-Site
- Modern Methods of Construction (Prefabricated, Modular, etc)
- By Investment Source
- Public
- Private
Data Sources, Market Sizing, and Validation
Desk Research
Desk work starts by mapping the Riyadh project environment to numbers that can be checked in public sources and repeated over time. We use official and widely cited references, including Saudi government budget releases and spending statements, the General Authority for Statistics for population and housing indicators, SAMA for macro and credit signals, and Riyadh city and national program releases under Vision 2030 for planned infrastructure direction. Where useful, construction permitting and planning announcements, plus customs and trade statistics for key materials, are used as a reality check on activity levels.
To turn these signals into a workable sizing base, we also review annual reports, investor presentations, and audited financial filings of listed contractors and developers with meaningful Riyadh exposure, plus reputable press coverage for contract awards and schedule changes. In addition, we use paid subscriptions for company financials and intelligence, along with shipment-level import and export data and contracts and tenders tracking, so assumptions on project starts and award timing can be cross-verified. The desk sources listed above are illustrative, and other public and paid references were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Riyadh-based interviews and surveys with contractors, developers, consultants, suppliers, and public project stakeholders test award conversion, delivery timing, pricing, and payment conditions. We use these checks to challenge desk assumptions, fill gaps, and triangulate the final Riyadh estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 30% | CXOs: 18% |
| Mid tier: 45% | Functional/Unit leaders: 32% |
| Smaller Players: 25% | Managers: 50% |
Market-Sizing & Forecasting
Sizing begins with a top-down build that reconstructs Riyadh construction demand from the city's project pipeline, public capex direction, and the rate at which awards typically convert into executed work over a year. That view is then corroborated with selective bottom-up approximations, such as sampled project values by sector, channel checks on key materials movement, and spot checks of contractor revenue exposure. This helps us adjust when awards are delayed or re-scoped and the executed timeline shifts.
Key inputs that shape the model include the pace of contract awards and tenders, the split between new construction and renovation activity, residential delivery momentum (housing starts and handover targets), infrastructure execution timing, construction cost inflation for core materials, and labor availability signals that influence productivity. Forecasts are developed using scenario analysis, where these drivers are moved in realistic bands and aligned to what interviewees expect on award cadence and execution constraints. Where bottom-up clues are incomplete for smaller projects, we fill gaps using sector-level average project sizes and typical conversion ratios, and then re-check totals against city-level demand signals before finalizing.
Data Validation & Update Cycle
Model outputs are cross-checked against independent signals like major award announcements, public spending direction, and the implied workload needed to meet stated delivery timelines. When a number looks off, we run variance checks by sector and construction type, then revisit assumptions that usually drive the difference, such as price escalation or conversion timing from awarded to executed work.
Before sign-off, the work goes through multi-step analyst review so calculation logic, units, and year alignment are consistent across the full time series. The report is refreshed annually, and interim updates are made when material events occur, such as major program re-phasing, large award waves, or sharp input cost moves. Right before delivery, we complete a fresh validation pass so clients receive the latest updated view.
黑料不打烊's Riyadh Construction Market Estimate Compared With Other Published Estimates
Published estimates for Riyadh construction can look far apart because some sources track contract values or announced pipelines, while others try to measure executed annual construction output. Differences also come from how sources define Riyadh versus nearby areas, and whether the number includes only building and civil works or also folds in adjacent services.
By tracking award-to-execution timing and keeping currency timing assumptions consistent, 黑料不打烊 keeps the Riyadh construction value tied to delivered work in a specific year, rather than mixing multi-year contract totals into a single-year market size.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 3.17 B (2025) | |
| Trade Journal A | USD 54.00 B (2024) | This figure reflects the value of existing construction contracts around Riyadh, which can represent multi-year awarded work and can include surrounding areas, so it is not the same as one-year executed market output. |
| Industry Report B | USD 15.00 B (2025) | The estimate is presented as a headline market value, although the scope and conversion from pipeline to annual output are not clearly explained, and it may blend broader Riyadh-region activity and pricing assumptions without stated validation checks. |
The spread across sources is mainly explained by what is being measured, where the boundary is drawn, and how multi-year projects are converted into a single-year number. Our approach stays traceable because inputs like award flow, execution lags, and cost movement are made explicit, then re-checked through interviews and practical consistency tests.


Key Questions Answered in the Report
How large is the Riyadh construction market in 2026?
The industry’s market size is USD 3.3 billion in 2026 and is projected to climb to USD 4.04 billion by 2031 on a 4.12% CAGR trajectory.
Which segment is growing fastest within Riyadh’s construction activity?
Infrastructure shows the most rapid expansion, advancing at a 5.91% CAGR through 2031 as mega-roads, metro lines, and airport packages dominate new awards.
Why are modular building systems gaining traction?
Modular approaches cut delivery times by up to 30%, ease skilled-labor shortages, and align with Saudization efforts; China Harbour’s new 200,000 m? factory exemplifies this shift.
What role does the private sector play in upcoming projects?
Although public entities still fund most builds, private capital records the higher 5.73% CAGR as legal reforms and special economic zones reduce investment risk.
How will Expo 2030 affect construction timelines?
Expo-related contracts worth USD 7.8 billion compress schedules between 2025 and 2029, intensifying demand for fast-track design-build solutions.
Page last updated on:



