
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 21.33 Billion |
| Market Size (2026) | USD 22.29 Billion |
| Market Size (2031) | USD 27.17 Billion |
| Growth Rate (2026 - 2031) | 4.04 % |
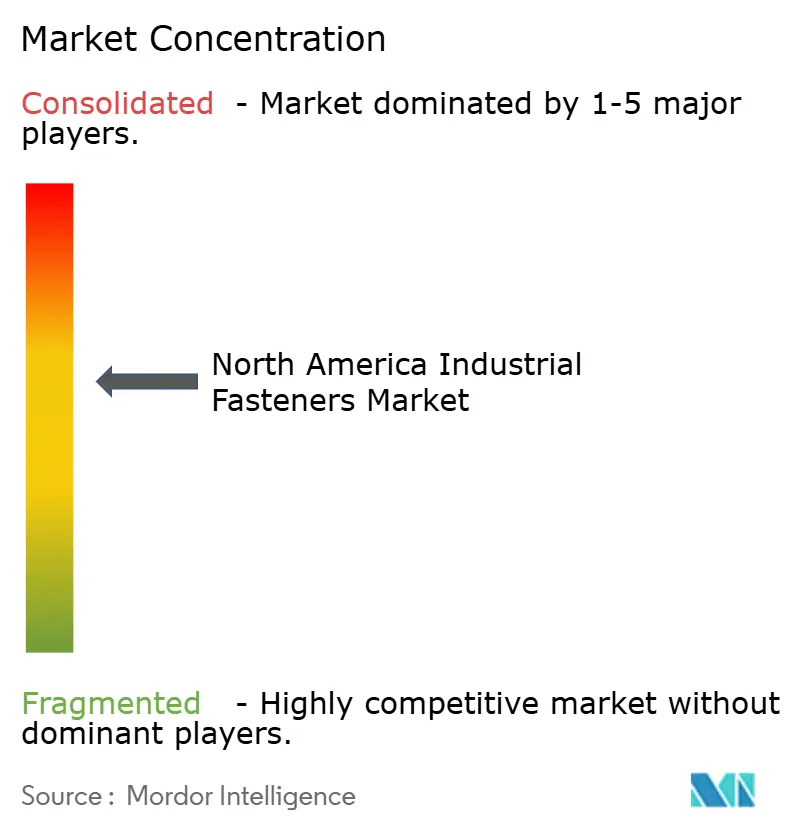
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
North America Industrial Fasteners Market Analysis by 黑料不打烊
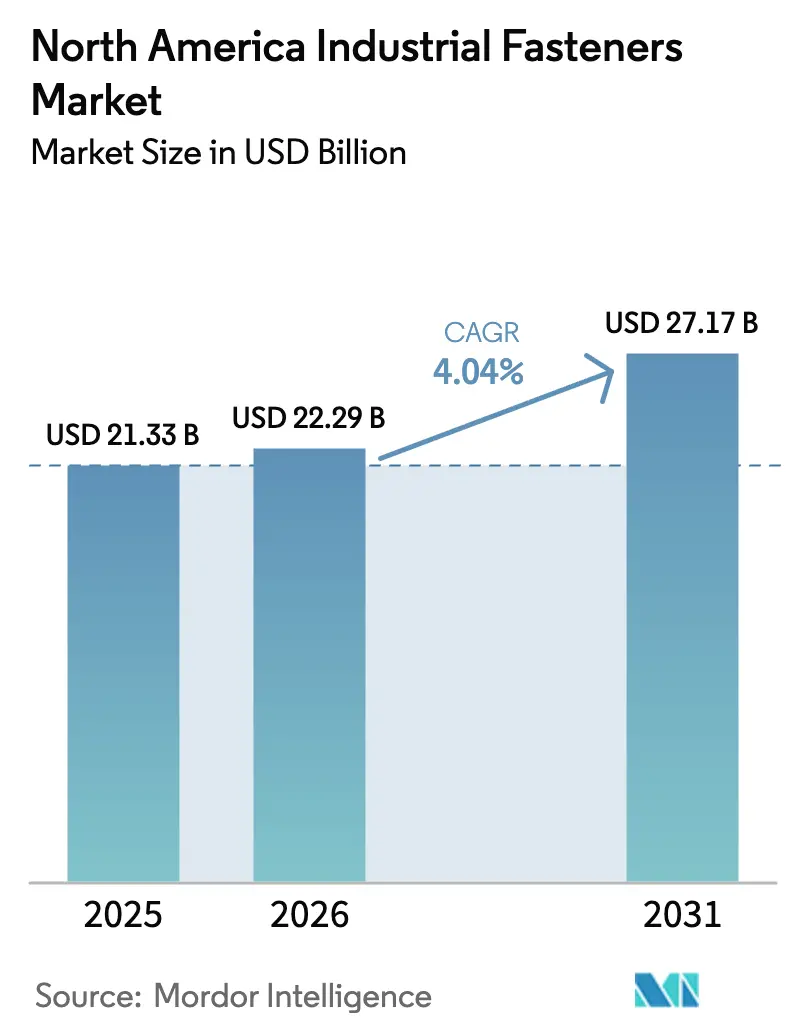
The North America Industrial Fasteners Market size is projected to be USD 21.33 billion in 2025, USD 22.29 billion in 2026, and reach USD 27.17 billion by 2031, growing at a CAGR of 4.04% from 2026 to 2031.
Demand is shifting toward lighter, higher-performance products as electric vehicle and next-generation aircraft programs require aluminum, titanium, and composite fasteners that cut weight without sacrificing strength. Reshoring and Buy America rules are tightening local supply, prompting OEMs to lock in multi-year contracts while distributors install IoT vending to guarantee uptime. Environmental regulations banning hexavalent chromium elevate PTFE and zinc-nickel finishes, and raw-material volatility is encouraging inventory hedging among tier-two suppliers. Digital traceability, from QR codes to RFID, is becoming a baseline requirement rather than a premium feature.
Key Report Takeaways
- By material, metal fasteners led with 84.23% of the North America industrial fasteners market share in 2025, while composite and specialty variants are forecast to advance at a 4.62% CAGR through 2031.
- By grade, standard products held a 67.13% share in 2025, whereas high-performance grades are projected to grow at a 4.49% CAGR over the same period.
- By product type, externally threaded fasteners captured 52.13% revenue share in 2025, and application-specific designs are poised for the fastest 4.87% CAGR to 2031.
- By end-user application, the OEM segment accounted for 47.35% of the North America industrial fasteners market size in 2025 and is expanding at a 4.56% CAGR.
- By coating type, zinc-plated finishes dominated with a 39.02% share in 2025, yet PTFE and other specialty coatings are set to rise at a 4.91% CAGR through 2031.
- By geography, the United States accounted for 73.67% of 2025 demand, while Mexico is the fastest-growing market, with a 4.68% CAGR forecast to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
North America Industrial Fasteners Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Automotive and Aerospace Manufacturing | +1.2% | United States and Mexico | Medium Term (2–4 Years) |
| Rapid Growth of North American EV Supply Chain | +0.9% | United States Core, Mexico Hubs | Short Term (≤2 Years) |
| Growth of the Construction Sector | +0.7% | United States and Canada | Medium Term (2–4 Years) |
| Advances in Corrosion-Resistant Coatings | +0.4% | Region-Wide | Long Term (≥4 Years) |
| Buy-American Acts Driving Local Sourcing | +0.5% | United States | Long Term (≥4 Years) |
| Digital Traceability and Smart-Fastener Initiatives | +0.3% | United States and Canada | Long Term (≥4 |
| Source: 黑料不打烊 | |||


Expansion Of Automotive and Aerospace Manufacturing
Ongoing multi-billion-dollar plant expansions by General Motors and Stellantis are translating into long-run orders for aluminum-compatible bolts and self-locking nuts that prevent galvanic corrosion inside battery packs. Hyundai is building the largest single automotive complex in U.S. history, an investment scheduled to come online in 2027 and consume roughly 150 million fasteners each year. Aerospace output is also climbing, with GE Aerospace adding turbine capacity in Ohio, which is boosting demand for nickel-based Inconel 718 screws capable of withstanding temperatures above 650 °C. Certified suppliers who can trace heat lots and meet NADCAP audit requirements have a competitive edge, pushing less-equipped rivals toward commodity niches. Collectively, these moves compress lead times for specialty parts and intensify local content requirements across the North America industrial fasteners market.
Rapid Growth Of North American EV Supply Chain
Battery gigafactories added 58 GWh of nameplate capacity in 2025, introducing demand for stainless-steel and aluminum fasteners engineered to ISO 16047 torque standards.[1]International Council on Clean Transportation, “North America Battery Manufacturing Capacity Report,” theicct.org Tesla’s Texas plant alone used about 80 million fasteners during the year, with M6 and M8 aluminum bolts topping the volume list. EV powertrains eliminate thousands of combustion-engine screws, yet battery enclosures, inverter housings, and motor mounts require vibration-resistant designs that survive intense thermal cycling. Argonne National Laboratory notes that forging capacity is struggling to keep pace with EV ramp-ups, stretching lead times for custom parts. Suppliers capable of drop-in design support and regional warehousing are therefore securing long-term volume commitments.
Growth Of The Construction Sector
Non-residential construction spending is trending 3.1% higher for 2025, led by data center builds that specify seismic-rated bolts and corrosion-proof coatings [2]American Institute of Architects, “Consensus Construction Forecast,” aia.org. Infrastructure funding under the Bipartisan Infrastructure Law is driving steady orders for hot-dip galvanized anchor bolts in highway and bridge projects. While single-family starts dipped amid high mortgage rates, multifamily and industrial projects offset the slowdown, providing mixed volume but richer margin profiles for fasteners meeting ASTM A325 and A490 specifications. The construction rebound supports stable baseline growth across the North America industrial fasteners market, especially for distributors with job-site vending programs that capitalize on just-in-time deliveries.
Advances In Corrosion-Resistant Coatings
The EPA’s ban on hexavalent chromium is accelerating migration toward trivalent alternatives, zinc-nickel alloy plating, and PTFE topcoats that meet 1,000-hour salt-spray tests without carcinogenic by-products. SAE research finds PTFE finishes cut installation torque by as much as 30%, reducing galling on stainless threads and trimming assembly times in aerospace production.[3]SAE International, “Study on PTFE Coating Performance in Aerospace Applications,” sae.org Automotive OEMs now mandate zinc-nickel coatings for underbody components exposed to de-icing salts, prompting plating shops to overhaul chemistry controls. Dorken’s Delta-Protekt solution is gaining share after demonstrating extended corrosion life while remaining compliant with new regulations. These shifts lift average selling prices and raise qualification barriers for offshore suppliers, reinforcing domestic share in the North America industrial fasteners market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatility In Steel And Non-Ferrous Metal Prices | -0.8% | North America | Short Term (≤ 2 Years) |
| Rising Adoption Of Structural Adhesives | -0.6% | United States And Canada | Medium Term (2–4 Years) |
| Stringent Environmental Regulations On Plating | -0.4% | United States | Medium Term (2–4 Years) |
| Reshoring-Led Capacity Bottlenecks For Specials | -0.3% | United States | Short Term (≤ 2 Years) |
| Source: 黑料不打烊 | |||
Rising Adoption Of Structural Adhesives
Henkel’s automotive adhesives unit grew 12% in 2025, displacing bolts in body-in-white assemblies where weight savings reach 12 kilograms per vehicle. Adhesives distribute load, reduce corrosion, and enhance NVH, motivating OEMs to redesign joint architectures. 3M acrylic foam tapes and Sika polyurethane systems now secure exterior trims and battery trays, trimming cycle times and tooling complexity. Serviceability concerns persist, so hybrid solutions pairing low-count fasteners with bonding agents are emerging. Fastener makers respond with screw-and-adhesive combos that cure in situ, but net demand pressure remains negative for basic hardware across the North America industrial fasteners industry.
Volatility In Steel And Non-Ferrous Metal Prices
Benchmark hot-rolled coil traded between USD 700 and USD 900 per ton in 2025, whipsawing annual contracts and squeezing margins for standard-grade fastener suppliers.[4]World Steel Association, “Global Crude Steel Production Statistics,” worldsteel.org Nickel touched USD 22,000 per ton, inflating stainless-steel costs just as EV battery demand accelerated, boosting nickel demand. Aluminum premiums remain elevated due to Section 232 tariffs, adding USD 400 per ton to domestic purchases. While larger distributors hedge and diversify sources, smaller fabricators lack liquidity for inventory carries, creating uneven supply reliability and occasional line stoppages for OEMs. Persistent price swings remain a headwind for the North America industrial fasteners market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Material – Metal Dominance Masks Specialty Gains
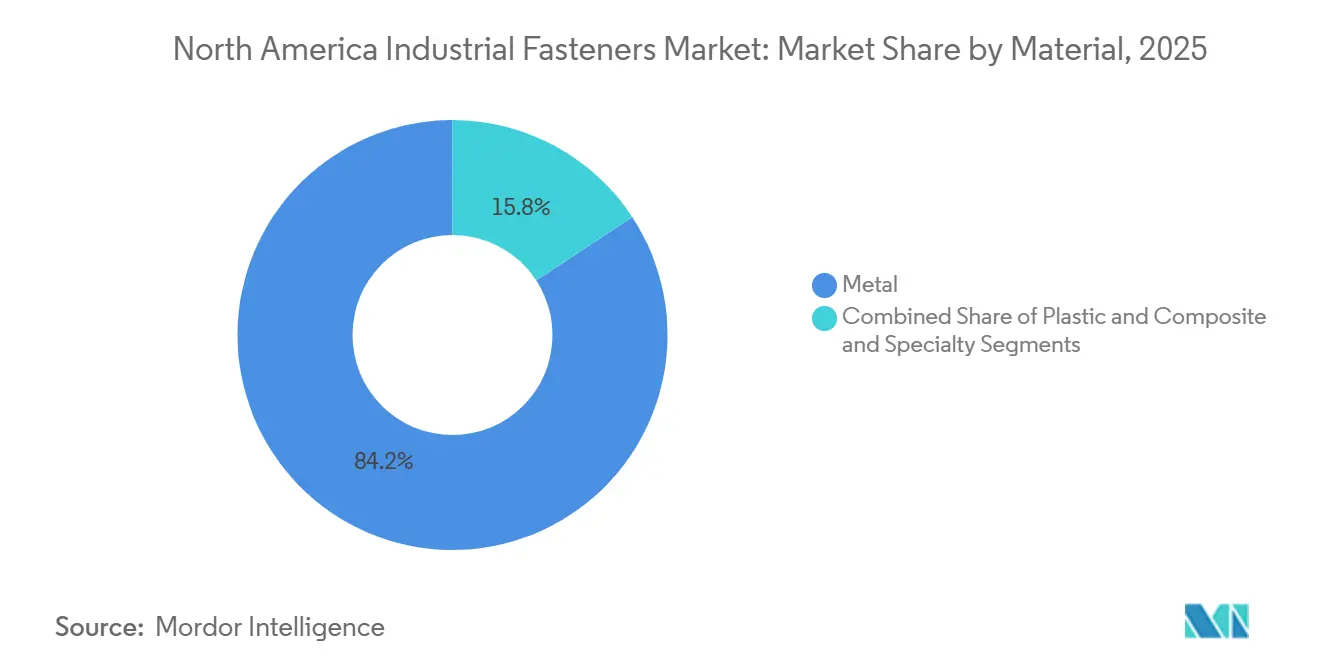
Metal fasteners accounted for 84.23% of 2025 revenue, underscoring their entrenched role in automotive crash structures, machinery housings, and steel-frame construction. Carbon steel meets most volume requirements thanks to favorable strength-to-cost ratios, while alloy and stainless grades serve higher-tensile or corrosive applications, such as underbody suspension points and chemical-processing equipment. Plastic clips and push-pins thrive in dashboards, white goods, and electronics where dielectric insulation or scratch avoidance matters more than high pull-out strength. Composite and specialty options, although niche, are expanding at a 4.62% CAGR as OEMs fight weight while guarding against galvanic corrosion between metals and carbon-fiber substrates.
Rapid shifts in product design are recasting bill-of-material choices. Airbus and Boeing have increased their composite fuselage share, driving the adoption of CFRP screws that match the thermal expansion of airframes and avoid galvanic couples. Titanium Grade 5 bolts, priced at more than USD 50 per kilogram, hold a secure position in jet engines and orthopedic implants where biocompatibility and 3:1 strength-to-weight superiority over stainless steel remain decisive. In the North America industrial fasteners market, PennEngineering’s self-clinching studs for thin aluminum casings reduced strip-out failures by 30%, demonstrating how process innovation can boost specialty penetration. PEEK screws, meanwhile, win spinal fixation work because they are radiolucent on post-op imaging, a clinical benefit that justifies a tenfold premium over 316L stainless alternatives.


By Grade – High-Performance Segment Captures Premium Applications
Standard-grade bolts conforming to ASTM A307 and SAE Grade 2 delivered 67.13% of 2025 turnover, riding construction and MRO staples where cost and immediate availability outweigh deeper engineering metrics. These fasteners move through distribution hubs in pallet quantities, with branch managers optimized for line-item fill rate rather than tensile curve education. Price erosion remains an issue, so scale logistics and automated picking stand out as the only sustainable levers for margin defense in this layer of the North America industrial fasteners market.
High-performance grades are charting a 4.49% CAGR into 2031 by shadowing electrification, LNG projects, and advanced civil aircraft. Grade 8 carbon-alloy bolts, heat-treated to 150,000 psi tensile, populate agricultural sprayers and heavy haulers that encounter extreme torsion. Metric Grade 10.9 studs now anchor EV motor mounts because regenerative braking subjects joints to higher reversed-stress cycles than gasoline engines. Howmet’s USD 28 million Inconel 718 line widens the moat around nickel-based fasteners that hold turbine sections together above 650 °C. KAMAX’s proprietary post-quench temper raised fatigue life 25%, granting OEMs more warranty cushion and fetching 40% price premiums that buoy overall value captured within the North America industrial fasteners market.
By Product Type – Application-Specific Variants Lead Innovation
Externally threaded products, namely bolts, screws, and studs, generated 52.13% of 2025 revenue by spanning everything from drywall screws to aircraft-grade titanium bolts. Nuts, inserts, and other internally threaded pieces trail but mirror demand because every bolt needs a mate. Rivets, pins, and retaining rings round out non-threaded categories that support permanent or one-way assemblies in aerospace skins and consumer electronics. Yet the application-specific subset is growing the fastest, at 4.87%, as OEMs ask suppliers to consolidate sealing, vibration damping, and grounding into a single engineered part.
Innovation stories abound: PennEngineering’s broaching studs create their own internal mating surface, removing a tapping step and cutting assembly time by 18 seconds per EV battery tray. Simpson Manufacturing pairs laser-cut brackets with preinstalled nails, letting framers meet seismic codes without field calculations. Bossard is piloting sensor-embedded rivets that tally load cycles and feed data into predictive-maintenance dashboards, a design that commercial airlines are eyeing for real-time structural health. TriMas disclosed that engineered specials captured gross margins 12 points higher than catalog items, confirming that feature integration is the fastest path to profit uplift in the North America industrial fasteners market.
By End-User Application – OEM Segment Drives Specification Evolution
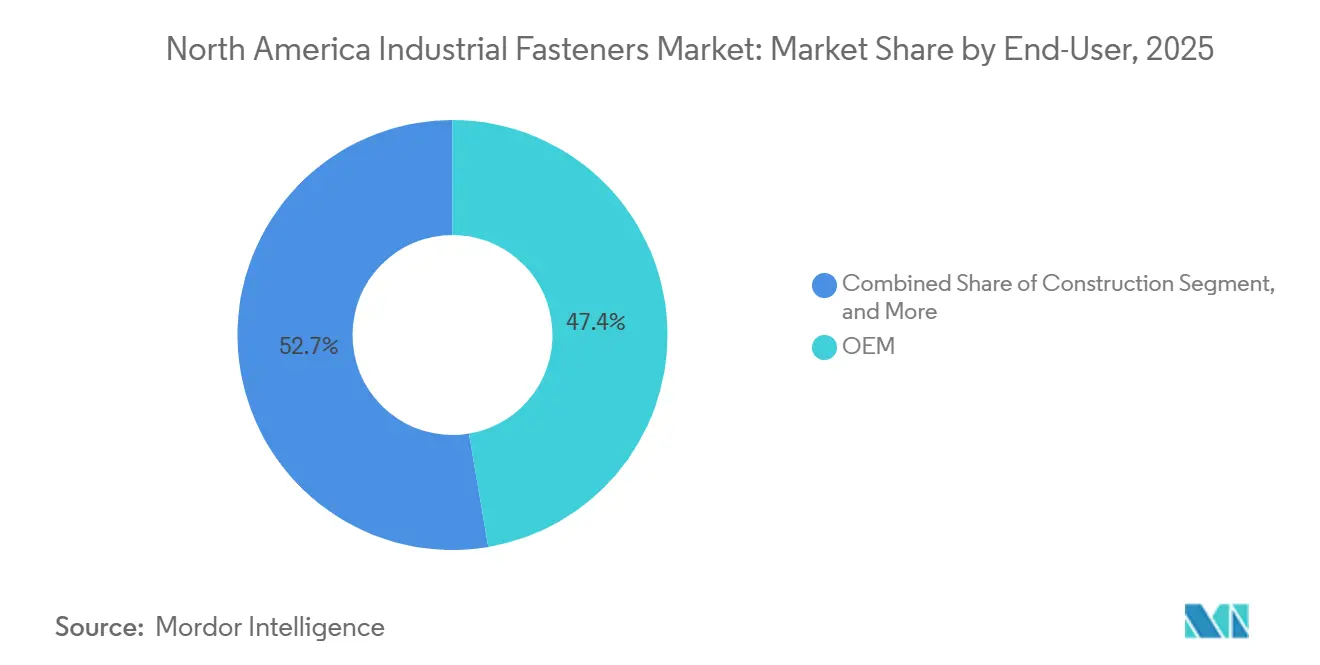
OEMs accounted for 47.35% of the North America industrial fasteners market in 2025 and will grow at a 4.56% CAGR as automakers, aircraft builders, and machinery firms pursue localized supply chains. Electric vehicles shed roughly 700 fasteners when engines and transmissions disappear, yet add new torque-critical joints in battery housings, inverters, and e-axles that demand narrow preload windows and conductive coatings for thermal pathways. A single commercial jet harbors more than 2 million fasteners, split across titanium, Inconel, and aluminum variants, each tagged to heat-lot certifications that raise unit economics to USD 15.
Heavy equipment and agricultural OEMs continue to specify Grade 8 or ASTM A490 bolts to tolerate shock loads and corrosive fertilizer exposure. MRO remains indispensable: Fastenal’s 100,000-strong vending fleet dispenses screws and washers on plant floors, logging pull data and auto-reordering to reduce line stoppages by 30%. Construction contractors purchase pallet loads of hot-dip galvanized rods for concrete anchor applications tied to the Bipartisan Infrastructure Law pipeline. Together, these demands cement OEMs as the bellwether while keeping aftermarket and site-build channels integral to volume stability across the North America industrial fasteners market.
By Coating And Finish – PTFE Variants Gain On Regulatory Tailwinds
Zinc plating, with a 39.02% share in 2025, remains relevant by offering sacrificial protection at a price accessible to most production budgets. Electro-plated layers between 5 ?m and 25 ?m serve indoor or moderate exposure, whereas hot-dip galvanized coatings above 50 ?m endure roadside salt and marine spray but carry a 60% cost premium. Plain, uncoated steel maintains a niche in climate-controlled interiors and disposable fixtures where penny-pinching trumps performance considerations.
Specialty coatings, led by PTFE, zinc-nickel, and hybrid silane layers, are growing at 4.91% through 2031 because they straddle compliance, assembly, and lifecycle cost. PTFE finishes lower the required drive torque by as much as 30%, cutting battery-pack assembly time that would otherwise require powered tools to be calibrated every shift. Zinc-nickel formulations pass 1,000-hour salt-spray tests and meet OEM underbody rules without carcinogenic chromium, securing back-to-back approvals from multiple Detroit Three automakers in 2025. Nanoceramic topcoats for medical implants resist autoclave sterilization, preventing pitting and maintaining thread class after repeated cycles. By delivering extended field life and regulatory peace of mind, specialty finishes are a high-margin lever for suppliers entrenched in the North America industrial fasteners market.
Geography Analysis
The United States generated 73.67% of 2025 demand, fueled by aerospace clusters in Washington, Texas, and South Carolina and an automotive corridor stretching from Michigan through Tennessee to Georgia. Boeing programs alone absorbed roughly 400 million fasteners, while federally backed infrastructure poured USD 110 billion into road and bridge work that specified ASTM and AASHTO bolts. Fastenal, Wurth, and MSC Industrial Supply stock branch networks capable of next-day coverage, underpinning a service expectation that shapes buying patterns across the North America industrial fasteners market.
Mexico is on a 4.68% CAGR trajectory through 2031, leveraging USMCA content rules that encourage OEMs to localize stamping, battery, and sub-assembly lines south of the border. Guanajuato, Puebla, and Aguascalientes host vehicle plants from General Motors, Stellantis, and Volkswagen, each fostering ecosystems of tier-one fastener cold forgers. Aerospace primes now authorize Mexican vendors for titanium lugs and Inconel studs, using Hermosillo and Monterrey as logistics bridges into Arizona and Texas final-assembly plants.
Canada trails in share but remains strategically interlocked with U.S. supply chains. Ontario’s auto belt relies on timely shipments from Midwestern fastener makers, and Quebec’s aerospace scene around Montreal feeds Bombardier and Pratt and Whitney programs that consume AS9100-certified titanium screws. Exchange rate swings dictate cautious inventory holds, so distributors center stock near Toronto and Quebec City to shorten customs cycles. Overall, complementary growth across the three nations sustains regional output and innovation momentum for the North America industrial fasteners market.
Regulatory Landscape
In the United States, the Fastener Quality Act (FQA) under NIST oversight sets baseline compliance for covered metallic fasteners, emphasizing conformance to consensus standards and the use of accredited laboratory testing and traceable documentation. For safety-critical structural hardware entering U.S. ports, U.S. Customs and Border Protection (CBP) expanded import compliance expectations in May 2026 for tension control (TC) bolts by adding ASTM F2329 coating adhesion testing for hot-dip galvanized or zinc flake coated product and requiring thermal fatigue torque-decay testing aligned to ASTM F3125-2026 Grade 12.9 on incoming shipments. This raises the importance of shipment-level test packages and heat-lot traceability.
In Canada, the Canada Border Services Agency (CBSA) administers trade remedy enforcement under the Special Import Measures Act (SIMA), including anti-dumping and countervailing measures on carbon steel fasteners from China and Chinese Taipei, which can create duty and compliance exposure for importers during administrative reviews. In parallel, Global Affairs Canada updated administration of steel-related import controls in June 2026 via revised tariff-rate quotas for steel goods. The Department of Finance Canada concluded domestic supply consultations in April 2026 that can influence tariff remission decisions relevant to industrial inputs such as fasteners.
Value Chain Analysis
The regional value chain runs from steel and non-ferrous inputs (carbon steel, stainless, aluminum, titanium, and nickel alloys) through cold heading/forging, thread rolling, heat treatment, and plating/coating, followed by inspection, certification, and packaging into OEM kits or MRO assortments. Demand-side specifications pull the chain toward higher documentation intensity, including ASTM/SAE compliance, ISO 16047 torque behavior for EV-related joints, and aerospace audit readiness (for example, NADCAP-linked process controls referenced in supplier qualification behavior), which elevates the role of in-house labs and qualified sub-tier processors for heat treat and finishing.
Distribution and point-of-use fulfillment are increasingly control points for service differentiation. Fastenal and Wurth scale automated replenishment via vending and bin systems that convert consumption data into scheduled replenishment. Automation investments are also reshaping midstream logistics, with Supply Technologies announcing a USD 50 million investment in June 2026 that includes a new distribution center in Union, Ohio, targeting automated kitting for end markets such as AI data centers and robotics. This reinforces hub-and-spoke models and increases the value of regional warehousing and kitting capabilities as OEMs and large MRO buyers push for shorter lead times and fewer line stoppages.
Competitive Landscape
Roughly 45% of 2025 revenue accrued to the top 10 suppliers, indicating moderate fragmentation. No single company surpasses an 8% share, so competitive levers center on service models, certification scope, and engineered product breadth rather than price alone. Fastenal and Wurth embed over 100,000 vending machines that lock in MRO spend and provide real-time data, reducing customer stockouts by 40%. Manufacturers such as Illinois Tool Works cross-sell powertrain-specific fasteners through captive distribution networks, shielding margins from pure-play resellers.
Vertical integration is deepening: Howmet Aerospace forges titanium bar, machines close-tolerance screws, heat-treats them in-house, and validates through NADCAP labs, collapsing external lead time. Bossard leverages SmartBin weight sensors to trigger cloud-based replenishment orders, trimming on-site stock by one-third and freeing working capital for OEM users. Patent filings highlight corrosion-resistant coatings, self-locking geometries, and sensor integration, revealing where incremental value creation lies in the North America industrial fasteners market.
Specialists are exploiting profitable niches. ARaymond push-in clips replaced screws in door-panel programs, cutting 25 seconds per vehicle from line time. Optimas consolidates vendor-managed inventory for mid-tier OEMs lacking internal procurement scale, and TriMas secured AS9100 Rev D to bid on U.S. defense work. While barriers to entry remain moderate for commodity parts, aerospace and automotive accreditation standards create defensible moats, reinforcing the current moderate concentration dynamic.
North America Industrial Fasteners Industry Leaders
Illinois Tool Works Inc.
Howmet Aerospace Inc.
Stanley Black and Decker, Inc.
Würth Group
Fastenal Company
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Qualification-driven demand is creating whitespace for suppliers that can combine material know-how (aluminum-, titanium-, and Inconel-class fasteners) with documented torque and corrosion performance and digital traceability suitable for EV and aerospace programs. The report base year highlights EV supply chain activity and process requirements such as ISO 16047 torque standards, while the market also absorbs environmental shifts away from hexavalent chromium toward zinc-nickel and PTFE-style specialty coatings. Product and service opportunities cluster around engineered specials, compliant coating systems, and “assembly-ready” delivery formats such as kitted fasteners, where distributors and manufacturers can attach value through validated specifications, labeling, and lot-level traceability.
On the supply side, investments in automated distribution and embedded supply-chain platforms support higher service levels and broaden the addressable share of wallet beyond catalog parts. Supply Technologies’ June 2026 USD 50 million investment in a new Union, Ohio distribution center, aimed at automated kitting for automation-heavy end markets including AI data centers and robotics, is a concrete signal of where value is accruing in the channel. In parallel, stricter port-of-entry compliance actions in May 2026 for TC bolts, covering coating adhesion and thermal fatigue testing tied to ASTM updates, reinforce opportunities for domestic or regionally integrated suppliers and distributors that can deliver complete test documentation packages and reduce clearance and rework risk for infrastructure and other safety-critical applications.
Recent Industry Developments
- April 2026: Stanley Black and Decker completed the sale of its Consolidated Aerospace Manufacturing (CAM) business to Howmet Aerospace for about USD 1.8 billion. The divestiture sharpened Stanley Black and Decker’s focus on its core businesses while transferring a major aerospace fastener and engineered components platform to a supplier positioned to expand capacity and vertical integration for aircraft programs in North America.
- December 2025: Howmet Aerospace announced an agreement to acquire Consolidated Aerospace Manufacturing (CAM) from Stanley Black and Decker for approximately USD 1.8 billion. The deal expanded Howmet’s aerospace fastening and components footprint and supported tighter control over certified manufacturing and supply continuity for safety-critical aerospace customers.
- June 2024: Wurth opened a 250,000 sq ft automated distribution hub in Dallas, improving order-picking speed and throughput for industrial supply customers across the region. The investment strengthened next-day fulfillment economics and supported vendor-managed inventory programs that depend on high fill rates and predictable lead times.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the value of industrial fasteners sold for use in North America across key end-use activity, including OEM demand, MRO demand, and construction-related demand, captured at the market level in USD.
Scope exclusions: Consumer retail fasteners and hand tools used for fastening are excluded from this market sizing.
Segmentation Overview
- By Material
- Metal
- Plastic
- Composite and Specialty
- By Grade
- Standard
- High-Performance
- By Product Type
- Externally Threaded
- Internally Threaded
- Non-Threaded
- Application-Specific/Specialty
- By End-User Application
- OEM
- Motor Vehicles/Automotive
- ICE Light Vehicles
- ICE Medium and Heavy Trucks/Buses
- Electric Vehicles
- Aerospace
- Machinery and Capital Goods
- Electrical and Electronics
- Fabricated Metals
- Medical Equipment
- Other OEM Applications
- Motor Vehicles/Automotive
- Maintenance, Repair and Operations (MRO)
- Construction
- OEM
- By Coating/Finish
- Plain (Uncoated)
- Zinc-Plated
- Hot-Dip Galvanized
- PTFE and Specialty Coatings
- By Country
- United States
- Canada
- Mexico
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with building a clean fact base for demand drivers and trade flows that influence fastener consumption across the United States, Canada, and Mexico. We review public sources such as the US Census Bureau manufacturing and construction releases, the US International Trade Commission trade statistics, Statistics Canada industry tables, and Mexico INEGI manufacturing indicators, which helps anchor directionally correct volume and activity trends.
Next, we connect those activity signals to fastener usage patterns by using technical references and policy cues, such as ASTM standards documentation, ASME threads and fastener standards references, and publicly available materials from industry bodies such as the Industrial Fasteners Institute. Company annual reports, investor presentations, and reputable business press are also used to understand the pricing environment, mix shifts (standard versus high-performance), and coating preferences. We then use selective paid subscriptions only for company financials, patent landscaping, and shipment-level trade checks where public granularity is limited. These examples are not exhaustive, and other public sources were reviewed for data collection, validation, and clarification during the research.
Primary Interviews and Surveys
Primary work is used to test key assumptions that are hard to confirm from public sources, especially mix splits by grade, typical pricing bands, and how fasteners move across OEM, MRO, and construction channels. We speak with a spread of stakeholders such as manufacturers, distributors, and procurement or quality teams at end users across the United States, Canada, and Mexico. We then revisit outliers until the final model aligns with what participants describe in orders, lead times, and sourcing patterns.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 26% | CXOs: 16% |
| Mid tier: 55% | Functional/Unit leaders: 31% |
| Smaller Players: 19% | Managers: 53% |
Market-Sizing & Forecasting
Market sizing begins with a top-down build that reconstructs demand from end-use activity in North America and then converts it into fastener value using practical pricing and mix assumptions. To keep the model grounded, inputs are tied to real-world indicators such as manufacturing output trends, construction spending cycles, vehicle and aerospace production momentum, import and export movement for fasteners and fastener inputs, and the observed shift between standard and high-performance grades.
After the first pass, totals are checked with selective bottom-up approximations, including sampled ASP multiplied by estimated usage volumes for major applications, plus channel checks with distributors to sense-test MRO share. Where direct volume proxies are weak, for example for specialty, application-specific fasteners, we fill gaps using mix shares validated in interviews and then apply conservative ranges until the variance narrows.
For forecasting, scenario analysis is used so the outlook can reflect different paths for industrial output, construction starts, and automotive and aerospace build rates, which are the demand signals most respondents consistently track. Assumptions like coating mix and price progression are refreshed with interview feedback and supported by observed trade and materials cost direction, and then the forecast is rolled forward annually for the full period.
Data Validation & Update Cycle
Validation is done by comparing model outputs against independent signals such as trade movement, manufacturing activity direction, and end-market production indicators, then checking whether the implied pricing and mix are realistic for each country. When results look inconsistent, we re-check conversions, re-run sensitivity on key variables, and re-contact select respondents to understand whether variance is coming from short-term pricing spikes, inventory moves, or demand slowdowns.
Before sign-off, the work is reviewed in steps so calculation logic, assumptions, and country roll-ups are consistent, and any unusual jumps are explained in straightforward terms. Reports are refreshed annually, with interim updates when a material event changes demand or pricing, and a final pre-delivery review is completed so clients receive the latest updated view.
黑料不打烊's North America Industrial Fasteners Market Size Compared With Other Published Estimates
Published market sizes for industrial fasteners in North America can differ even when they sound similar, because data owners do not always count the same product scope, the same end-use coverage, or the same timing for price conversion. We keep the comparison focused on what gets counted, how the base year is set, and how the forecast path is formed.
Hand tools and fastening tools sit outside 黑料不打烊's scope, which is one reason the 2025 total can look lower than figures that loosely combine fasteners with adjacent tooling spend. Other differences usually come from whether construction and MRO are counted at full value, how imported fasteners are treated versus domestically produced fasteners, and whether pricing is held flat or stepped up using clear grade and coating mix logic.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 21.33 B (2025) | |
| Trade Event Publisher A | USD 20.70 B (2024) | Uses a different base year and is presented as a shorter-horizon outlook, and the public summary does not clarify how grade, coating, and end-use mix were handled in the value build. |
| Newswire Summary B | USD 22.75 B (2027) | Starts from an earlier base year and reports a later-year value, and the summarized method does not state how imports, channel margins, or OEM versus MRO splits were validated for North America. |
The spread across the three figures is mainly explained by timing and by what is included in the value build, rather than a disagreement that demand exists. By tying the model to observable end-use signals, validating mix and pricing in interviews, and keeping inclusions clearly stated, we produce a balanced number that can be re-checked as new trade and industrial activity data comes in.


Key Questions Answered in the Report
What is the projected size of the North America industrial fasteners market by 2031?
The market is forecast to reach USD 27.17 billion.
Which material segment is growing the fastest?
Composite and specialty fasteners are expanding at a 4.62% CAGR through 2031.
Why are specialty coatings such as PTFE gaining share?
They provide superior corrosion protection and comply with EPA chromium bans while reducing installation torque by up to 30%.
Which country offers the highest growth rate in the region?
Mexico, with a forecast 4.68% CAGR, driven by expanding automotive and aerospace production.
How are distributors using technology to retain customers?
Firms like Fastenal deploy IoT-enabled vending machines that automate replenishment and improve retention by 15%.
What impact do structural adhesives have on mechanical fastener demand?
Adhesives replace some bolts in body-in-white assemblies, reducing vehicle weight, though hybrid joints still use fewer high-specification fasteners.
Page last updated on:



