
North America Golf Cart Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 1.05 Billion |
| Market Size (2026) | USD 1.12 Billion |
| Market Size (2031) | USD 1.53 Billion |
| Growth Rate (2026 - 2031) | 6.49 % |
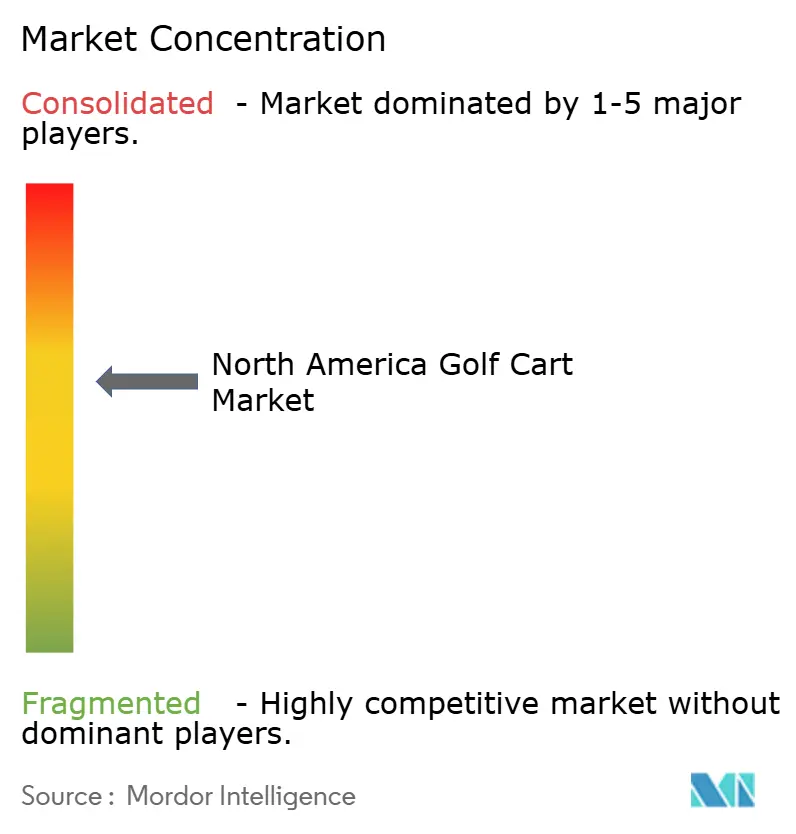
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
North America Golf Cart Market Analysis by 黑料不打烊
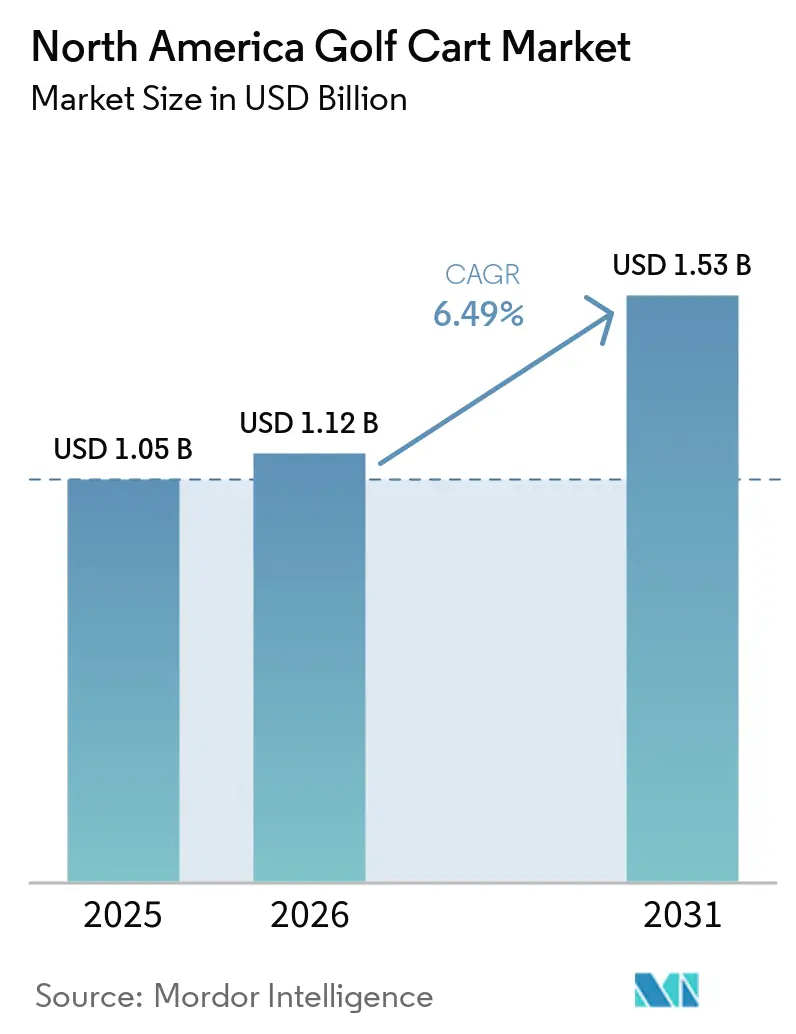
The North America golf cart market size was valued at USD 1.05 billion in 2025 and is projected to expand from USD 1.12 billion in 2026 to USD 1.53 billion by 2031, registering a 6.49% CAGR between 2026 and 2031. Demand is pivoting beyond fairways, with gated communities, corporate campuses, and hospitality districts normalizing the use of carts for short-range mobility. Lithium-iron-phosphate (LFP) batteries, solar-integrated canopies, and fleet-as-a-service contracts are compressing lifetime operating costs, accelerating fleet renewals. Provincial and state pilots that legalize low-speed vehicles on roads posted at 50 km/h or less are unlocking fresh addressable volume, while semiconductor shortages and tightening lead-acid disposal rules temper near-term supply growth. Competitive focus has shifted from chassis hardware toward battery chemistry, connectivity, and rental-platform software, reshaping how incumbents and challengers defend share.
Key Report Takeaways
- By propulsion type, electric led with 67.15% of the North America golf cart market share in 2025, whereas solar-hybrid variants are advancing at an 8.59% CAGR through 2031.
- By application, golf courses accounted for 46.35% of the North American golf cart market size in 2025, while personal transportation is expanding at 6.93% CAGR to 2031.
- By seating capacity, 2-seater models held 55.03% share of the North America golf cart market in 2025; 6-seater-and-above configurations are growing 8.02% annually.
- By ownership model, personal buyers represented 47.24% share in 2025, yet rental and shared services are rising at 7.65% CAGR.
- By country, the United States generated 82.33% of 2025 revenue, while Canada is forecast to grow at a 7.13% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Worldwide, activity is shaped by contributions from multiple regions, with North america representing one of the more structurally developed among them. The global report on golf cart market by 黑料不打烊 reflects how these regional layers combine into a single system.
Market Trends and Insights
Drivers Impact Analysis of North America Golf Cart Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Uptake of Lithium-Iron-Phosphate Batteries | +0.9% | Early adoption in U.S. rental fleets and Canadian resorts | Short term (≤ 2 years) |
| Electrification Mandates in Gated Communities | +0.8% | United States (Florida, Texas, Arizona); Canada (British Columbia) | Medium term (2-4 years) |
| Resort-Based Real-Estate Boom | +0.7% | United States (Southeast, Southwest); Canada (British Columbia, Ontario) | Medium term (2-4 years) |
| Corporate Fleet Decarbonization Programs | +0.6% | North America-wide, concentrated in U.S. campuses | Long term (≥ 4 years) |
| Emergence of Solar-Integrated Roofs | +0.5% | U.S. Sun Belt states; global resort properties | Medium term (2-4 years) |
| Subsidies for Low-Speed EVs | +0.4% | Select U.S. states and Canadian provinces | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Rapid Uptake of Lithium-Iron-Phosphate (LFP) Batteries
Fleet operators, leveraging LFP packs, enjoy significantly longer lifespans compared to lead-acid batteries, resulting in notable long-term cost savings. Rental firms, like Ocala Golf Cart Rentals, have made a complete shift to lithium, capitalizing on its rapid charging capabilities between hires. Yamaha’s G31EPs, launched mid-2025, integrate proprietary LFP modules that reduce power use 30% from prior chemistries [1]“G31EPs LFP Battery Introduction,” Yamaha Motor, global.yamaha-motor.com. As pack prices decline, they have become more accessible for personal buyers, spurring a surge in secondary-market conversions.
Electrification Mandates in Gated Communities
Master-planned communities such as Nocatee in Jacksonville restrict gasoline carts to preserve air quality and reduce noise, converting carts from amenities to regulated infrastructure. EverRange, opening in 2026, is engineering its pathways for electric low-speed vehicles from inception, locking in future demand. Homeowners’ associations enforce compliance through fines and registration denials, ensuring sustained replacement demand. States with high retiree in-migration—Florida, Texas, Arizona—are the epicenter, where daily cart use displaces short automobile trips. Electric-only clauses reshape purchasing decisions by integrating mobility rules into real-estate covenants.
Boom in Resort-Based Real-Estate Developments
Hospitality operators are integrating dedicated cart fleets into their master plans, achieving significant reductions in internal combustion shuttle costs while promoting sustainability to their guests. In 2026, Predator Ridge in British Columbia, after expanding its plant, procured a new all-electric fleet from Simolo Customs. The Preserve at Fields, located next to PGA Frisco, is designing frontage roads for carts, predicting high ownership penetration. Operators are favoring multi-passenger 4- and 6-seater models, emphasizing guest throughput over individual convenience. Real-estate sales materials are increasingly spotlighting cart accessibility, alongside proximity to golf courses.
Corporate Fleet Decarbonization Programs
Campus-style enterprises are opting for carts over full-size vans, achieving Scope 1 targets with reduced capital expenditure. By 2030, DHL aims to electrify a significant portion of its fleet, with a focus on low-speed vehicles. Merchants Fleet, witnessing substantial growth in light EV deployments, is integrating maintenance and telematics into subscription contracts, mitigating risks associated with technology adoption. An electric cart servicing most intra-campus journeys stands in stark competition to a van, hastening procurement decisions. Stricter corporate policies on residual values for internal-combustion assets are tilting the scales in favor of battery carts in total-cost-of-ownership assessments.
Restraints Impact Analysis of North America Golf Cart Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Golf-Cart-Grade Semiconductor Supply | ?0.6% | North America-wide | Short term (≤ 2 years) |
| Restrictions on Non-Road Vehicles | ?0.5% | U.S. and Canadian cities | Long term (≥ 4 years) |
| Lead-Acid Disposal Regulations | ?0.4% | United States; Canada | Medium term (2-4 years) |
| Rising Theft and Vandalism | ?0.3% | U.S. retirement communities and resorts | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Under-Supply of Golf-Cart-Grade Semiconductors
Controller lead times have doubled since 2025 as OEMs compete with passenger-EV manufacturers for identical battery-management chips. Textron flagged supply constraints in its 2025 annual report, redirecting scarce components to higher-margin trims. Feature-rich solar-hybrid and telematics variants are most affected because they require additional microcontrollers, prompting some brands to de-content entry models to keep assembly lines running. Relief hinges on incremental foundry capacity expected online from late 2027.
Zoning Restrictions on Non-Road Vehicles in Urban Cores
Transport Canada caps low-speed vehicle speed at 40 km/h, delegating road-access authority to municipalities, which creates patchwork legality [2]“Low-Speed Vehicle Regulation,” Transport Canada, tc.canada.ca . Major cities like Toronto and Vancouver still exclude carts from arterial corridors, limiting multi-modal integration. Similar constraints persist in U.S. metros where carts are restricted to roads below 35 mph, reducing utility for mixed-purpose trips and suppressing adoption in dense urban zones.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Golf Cart Market Segment Analysis
By Propulsion Type:
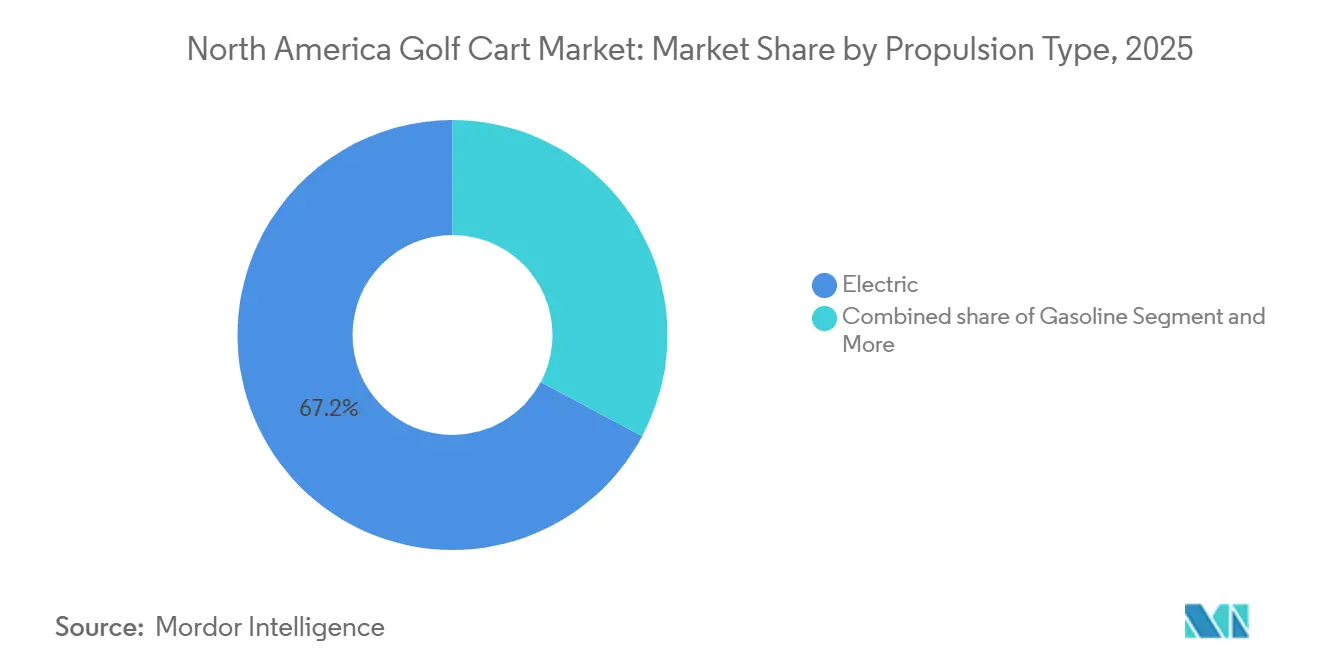
Solar-Hybrid Gains Traction Despite Electric DominanceElectric carts dominated the North American golf cart market with 67.15% share in 2025 as battery prices fell and charging infrastructure spread. However, solar-hybrid configurations, which integrate 300-620 W flexible panels, are expanding at an 8.59% CAGR because resort and municipal fleets value 15–25 km of daily off-grid range. Grid-connected fleets are expected to stay all-battery, yet operators in remote locations increasingly specify solar kits as standard equipment. Gasoline carts endure in rural clubs that require instantaneous refueling, but emissions scrutiny is eroding their install base. By 2031, North America's golf cart market, driven by battery-based platforms, is expected to grow significantly, as hybrid and exploratory hydrogen prototypes emerge under a unified electric umbrella.
Solar-hybrid adoption is accelerating in Sun Belt resort corridors where photovoltaic payback windows shrink below two years, unlocking continuous duty cycles without costly charging pedestals. OEM roadmaps indicate roof-integrated solar will migrate from aftermarket kits to factory options by 2028 as patent coverage broadens and module costs fall.


By Application:
Personal Transportation Closes the Gap on Golf Course UseGolf courses retained 46.35% share of the North America golf cart market in 2025, yet personal transportation is advancing at 6.93% CAGR as retirees and families replace second cars with carts in gated neighborhoods. Commercial and utility uses—campus shuttles, warehouse logistics—are also expanding, urged by corporate decarbonization goals that favor low-speed electric vehicles for sub-50 km routes. Street-legal low-speed-vehicle (LSV) variants with headlights, seatbelts, and VINs now account for a rising portion of OEM shipments, signifying normalization beyond golf turf.
Peer-to-peer rental apps and resort fleet-as-a-service models further democratize cart access, enabling try-before-buy experiences that convert occasional users into owners. As cart-friendly master plans proliferate, the North American golf cart market share held by golf courses will likely fall significantly by 2031, though absolute unit demand in that channel should remain stable.
By Seating Capacity:
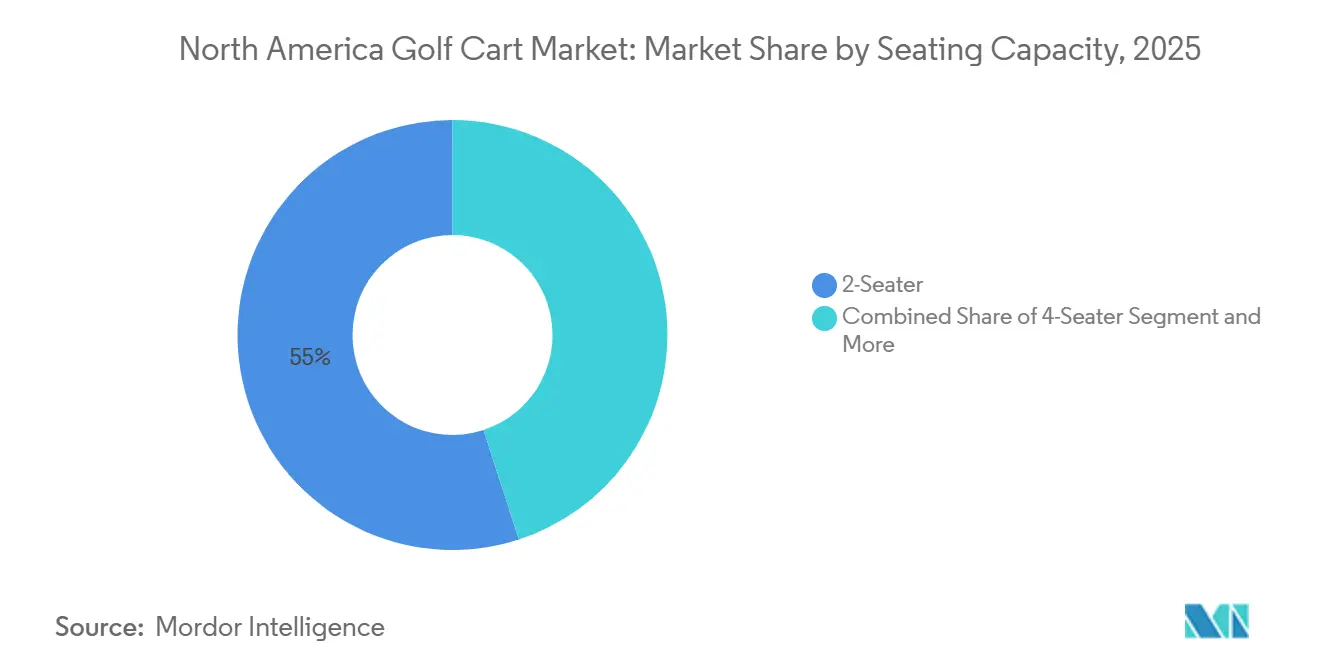
Larger Configurations Serve Multi-Passenger DemandTwo-seater carts commanded 55.03% share in 2025 because they match foursome play and individual ownership economics. Yet 6-seater-and-above models are rising 8.02% annually, favored by resorts and corporate campuses that consolidate three 2-seater trips into one six-seater run, trimming labor and energy outlays. Four-seater vehicles bridge family and light shuttle roles, giving flexibility where fleet diversity is limited.
Original Equipment Manufacturers (OEMs) are channeling investments into longer wheelbases and more powerful engines to better handle shuttle demands. Notably, Yamaha's G31EP 5-seater has made waves by introducing proprietary LFP batteries and AC motors, significantly enhancing its runtime. With the hospitality and logistics sectors expanding, projections indicate that by 2031, the contribution of large-capacity models to the North American golf cart market will grow substantially.
By Ownership Model:
Rental and Shared Services Disrupt Personal Ownership DefaultPersonal buyers still constituted 47.24% of 2025 revenue, but platform-enabled rentals are expanding at 7.65% CAGR, propelled by Joyride’s Revii software, which notched 70% trip growth in 2024. Universities, resorts, and municipalities increasingly adopt fleet-as-a-service contracts that bundle vehicles, maintenance, insurance, and telematics into fixed monthly fees, easing budget planning.
Residents can now monetize idle golf carts thanks to peer-to-peer models, easing the burden of upfront ownership. As insurance frameworks and zoning ordinances stabilize over the years, usage-based access is expected to grow significantly within the North American golf cart industry.
Geography Analysis
United States Golf Cart Market
The United States generated 82.33% of 2025 revenue owing to high golf-course density, Sun Belt retirement migration, and favorable road-use ordinances such as Texas House Bill 1548, which permits carts on roads up to 35 mph in designated municipalities [3]“HB1548 Low-Speed Vehicle Statute,” Texas Legislature, capitol.texas.gov. Florida hosts numerous golf courses and master-planned communities designed with dedicated cart paths and parking bays. Corporate commitments to electrification, seen in entities like DHL and various university campuses, contribute to a steady institutional demand. However, fragmented municipal zoning poses a significant challenge.
Canada Golf Cart Market
Canada is the fastest-growing geography at 7.13% CAGR, catalyzed by provincial pilots in Alberta, Ontario, and British Columbia that legalized on-road carts under defined bylaws. Simolo Customs’ new British Columbia factory underscores domestic production scaling to meet resort and community demand. Alignment of Transport Canada’s CMVSS 500 with U.S. FMVSS 500 allows OEMs to certify once for both markets, lowering compliance burden.
Mexico and Caribbean Golf Cart Market
The rest of North America—principally Mexico and Caribbean resort islands—accounts for a smaller slice yet experiences steady hospitality-driven adoption. Resorts in Cancún, Riviera Maya, and Turks and Caicos deploy electric fleets to cut shuttle van emissions and support eco-branding. While these jurisdictions lack the demographic tailwinds of the United States, consistent tourism occupancy provides predictable utilization that justifies capital investment.
Competitive Landscape
Combined, Textron (E-Z-GO), Club Car, and Yamaha capture a significant share of the North American golf cart market, leveraging entrenched dealer networks and multi-decade course relationships. Textron’s Onyx in-vehicle solution was launched in January 2026 and became available by Q2 2026. The solution integrates RTK GPS and geofencing to differentiate utility models and maintain premium positioning [4]“2025 Annual Report,” Textron, textron.com. Club Car’s 2025 Tempo update introduced automatic park-brake and wireless charging, targeting safety-oriented fleets. Yamaha secured exclusive North American distribution rights for Pilotcar LSVs in Q1 2025, signaling strategic expansion beyond traditional two-seat platforms.
Niche specialists such as ICON and Garia address lifestyle and street-legal niches with premium aesthetics and infotainment. ICON’s EPIC FX Series won Golf Channel’s “Best New Golf Cart/LSV of 2025,” validating demand for high-spec, road-worthy models. Software enablers, notably Joyride, embed white-label rental platforms that let resorts and municipalities spin up fleets without custom IT, diluting OEM bargaining power.
Intellectual property around solar integration and autonomy is emerging. SC Autosports’ design patent for roof-mounted photovoltaics could cement licensing royalties as solar canopies become mainstream. Consolidation is underway: Whisper Carts acquired American Landmaster assets in October 2025 to broaden its off-road and utility catalog, indicating an appetite for scale among challenger brands. Overall, software differentiation and battery chemistry are eroding traditional hardware moats, ensuring competitive intensity rises as the market diversifies.
North America Golf Cart Industry Leaders
Textron Specialized Vehicles Inc. (E-Z-GO)
Club Car
Yamaha Motor Co., Ltd.
ICON Electric Vehicles
Garia A/S
- *Disclaimer: Major Players sorted in no particular order
North America Golf Cart Market Companies Covered in this Report
- Textron Specialized Vehicles Inc. (E-Z-GO)
- Club Car
- Yamaha Motor Co., Ltd.
- ICON Electric Vehicles
- Garia A/S
- Cruise Car Inc.
- Suzhou Eagle Electric Vehicle Mfg. Co. Ltd.
- JH Global Services Inc. (Star EV)
- Polaris Inc.
- Nordic Group of Companies Ltd.
- AEV Technologies
- Marshell Electric Vehicle
- Bintelli Electric Vehicles
- Evolution Electric Vehicles
- HDK Electric Vehicles

Recent Industry Developments in North America Golf Cart Market
- March 2026: GOTRAX, a leader in electric mobility solutions, unveiled its new Fairway 200 Golf Cart during a Lowe's product launch event, expanding its electric vehicle lineup. Designed for recreation and everyday utility, the GOTRAX Fairway 200 golf cart seats four passengers comfortably, with two forward-facing seats and a rear-facing backseat configuration.
- January 2026: Daedong Mobility debuted its GA900 limousine cart and an LSV concept for North America at the PGA Show, outlining an AI-enabled autonomous service roadmap.
- August 2025: Simolo Customs secured a 42,000-sq-ft facility in Spallumcheen Industrial Park, boosting Canadian production capacity.
- February 2025: Quintana Roo legislature authorized 400 golf carts as public transport in Tulum, formalizing low-speed mobility within tourism zones.


North America Golf Cart Market Report Scope
The scope includes segmentation by propulsion type (electric, gasoline, and solar-hybrid), application (golf course, personal transportation, and commercial/utility services), seating capacity (2-seater, 4-seater, and 6-seater and above), and ownership model (personal ownership, fleet/corporate, and rental and shared services). The analysis also covers country-level segmentation, including the United States, Canada, and rest of North America. Market size and growth forecasts are presented by value in USD.
| Electric |
| Gasoline |
| Solar-Hybrid |
| Golf Course |
| Personal Transportation |
| Commercial/Utility Services |
| 2-Seater |
| 4-Seater |
| 6-Seater and Above |
| Personal Ownership |
| Fleet/Corporate |
| Rental and Shared Services |
| United States |
| Canada |
| Rest of North America |
| By Propulsion Type | Electric |
| Gasoline | |
| Solar-Hybrid | |
| By Application | Golf Course |
| Personal Transportation | |
| Commercial/Utility Services | |
| By Seating Capacity | 2-Seater |
| 4-Seater | |
| 6-Seater and Above | |
| By Ownership Model | Personal Ownership |
| Fleet/Corporate | |
| Rental and Shared Services | |
| By Country | United States |
| Canada | |
| Rest of North America |


Key Questions Answered in the Report
How large will the North American golf cart market be by 2031?
It is forecast to reach USD 1.53 billion by 2031, up from USD 1.12 billion in 2026.
Which propulsion type is growing fastest?
Solar-hybrid carts are advancing at an 8.59% CAGR as operators seek off-grid range extensions.
Why is Canada growing faster than the United States?
Provincial pilot programs that legalize on-road carts are driving a 7.13% CAGR, the region’s highest rate.
What ownership models are emerging?
Rental and shared-service platforms are expanding by 7.65% annually, challenging traditional personal ownership.
Page last updated on:



