
North America Data Center Server Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
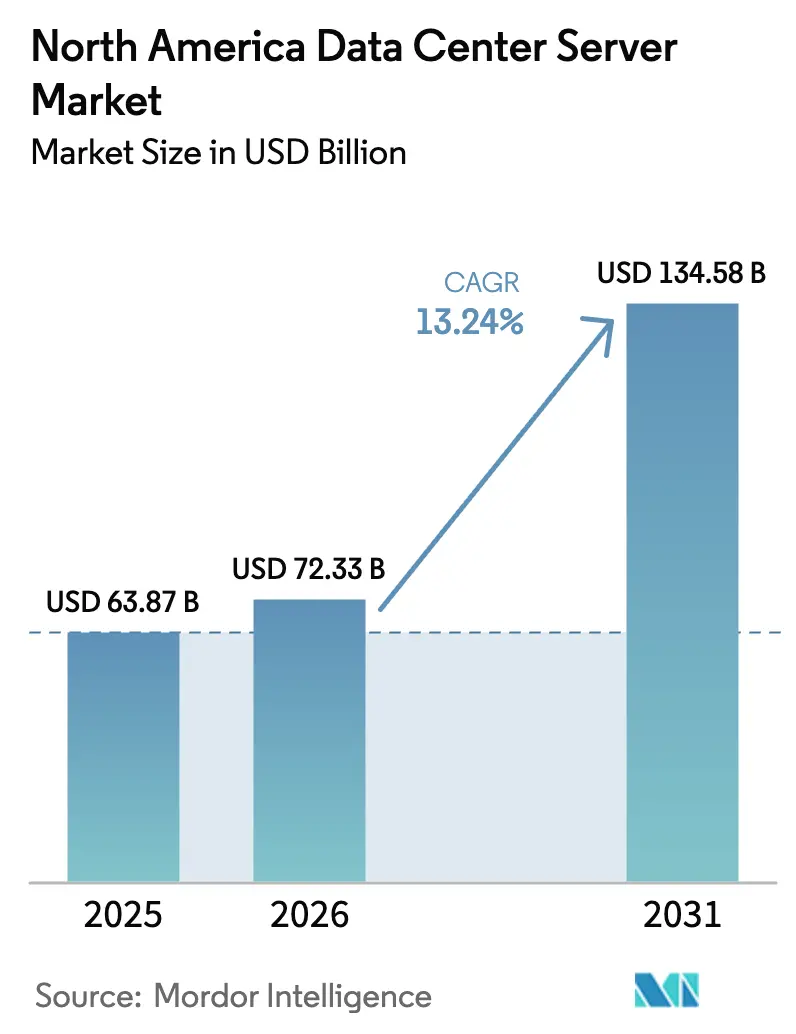
| Base Year Market Size (2025) | USD 63.87 Billion |
| Market Size (2026) | USD 72.33 Billion |
| Market Size (2031) | USD 134.58 Billion |
| Growth Rate (2026 - 2031) | 13.24 % |
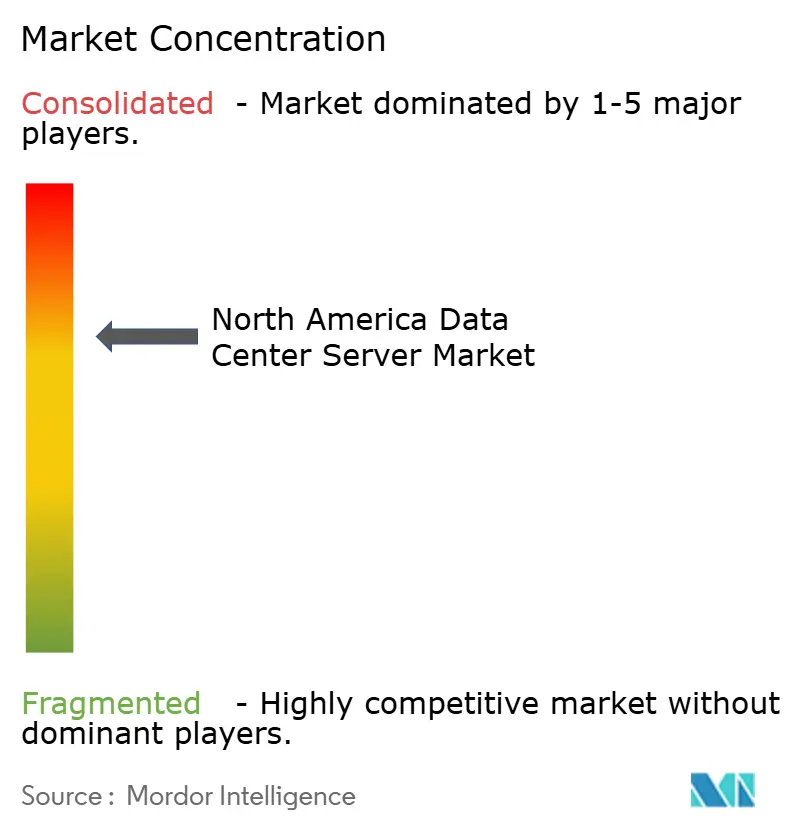
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
North America Data Center Server Market Analysis by 黑料不打烊
The North America data center server market size is expected to grow from USD 63.87 billion in 2025 to USD 72.33 billion in 2026 and is forecast to reach USD 134.58 billion by 2031 at 13.24% CAGR over 2026-2031. Expanding artificial-intelligence deployments, heightened network traffic and stricter data-sovereignty rules are reshaping procurement strategies as organizations modernize legacy facilities to manage power densities exceeding 100 kW per rack. Server suppliers now compete on liquid-cooling efficiency, GPU density and rapid configuration lead times rather than raw processor speed. In parallel, escalating nearshoring in Mexico and sovereign-cloud mandates in Canada are redirecting capital toward secondary metros that still offer power headroom. Colocation vendors, cloud hyperscalers and edge specialists are each scaling capacity faster than traditional enterprise data centers, tightening competition across the value chain.
Key Report Takeaways
- By application, artificial intelligence and machine learning held 38.84% of the North America data center server market share in 2025, while virtualization and private-cloud workloads are projected to record a 17.02% CAGR through 2031.
- By data-center tier, Tier 3 facilities led with 74.60% revenue share in 2025; Tier 4 is poised to expand at 18.56% CAGR to 2031 as hyperscalers demand fault-tolerant GPU clusters.
- By form factor, half-height blades accounted for 61.55% of the North America data center server market size in 2025, whereas quarter-height and micro-blades are forecast to grow at 17.92% CAGR edgeir.
- By data-center type, colocation operators captured 57.70% of the North America data center server market share in 2025; hyperscaler facilities are on track for a 20.64% CAGR through 2031.
- By geography, the United States led with an 85.80% share in 2025, while Canada is projected to post a 19.05% CAGR to 2031 on the back of CAD 240 million in AI-focused data-center funding.
- By end-use industry, IT & Telecom commanded 34.58% of 2025 revenue; manufacturing and Industry 4.0 workloads are anticipated to expand 18.05% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Data Center Server Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI/ML training demand for GPU-dense servers | +4.2% | United States, Canada | Short term (≤ 2 years) |
| Commercial 5G roll-outs driving edge build-outs | +2.1% | North America, Mexico border regions | Medium term (2-4 years) |
| Rising adoption of cloud and IoT workloads | +2.8% | US metros | Medium term (2-4 years) |
| Data-sovereignty mandates in Canada and Mexico | +1.9% | Canada, Mexico | Long term (≥ 4 years) |
| Evergreen hardware refresh cycles | +1.5% | North America enterprise | Long term (≥ 4 years) |
| On-prem sovereign-cloud designs for US public sector | +1.1% | United States | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
AI/ML Training Demand for GPU-Dense Servers
Artificial-intelligence workloads already consume up to one-fifth of data-center electricity, forcing operators to revamp racks for extreme densities and liquid cooling coresite. NVIDIA’s US 1.4 trillion data-center opportunity projection has accelerated procurement of specialized servers that can host as many as eight GPUs per chassis. Super Micro’s 100,000-GPU liquid-cooled cluster illustrates the market’s pivot toward direct-cooling architectures. HPE’s USD 1 billion order from X signals that large private buyers now rival hyperscalers on single-deal size. These shifts cement high-density AI racks as the primary growth engine for the North America data center server market.
Commercial 5G Roll-outs Driving Edge Build-outs
Ultra-low-latency 5G services are steering compute away from core campuses toward metropolitan edge sites that sit within a one-digit-millisecond round-trip of end users.[1]EdgeIR, “5G Edge AI Rollout Gains Pace,” edgeir.com GPU-as-a-service launches inside micro-colo hubs such as Cologix Toronto provide proof that AI inference will increasingly reside at the edge. Server OEMs have responded by releasing quarter-height and other micro-blade designs tuned for shallow racks and constrained footprints. This distributed topology unlocks new revenue for regional fiber operators and municipal utilities that can guarantee clean power and right-of-way permits. The trend sustains a double-digit expansion streak for edge systems within the broader North America data center server market.
Rising Adoption of Cloud and IoT Workloads
Enterprise architects are rationalizing workload placement across multicloud, on-prem and colocation assets to optimize cost and compliance. Dell’s AI Factory portfolio, which couples servers, storage and networking for hybrid deployment, exemplifies the converged-infrastructure shift. IoT sensor proliferation in logistics and energy adds torrents of time-series data that must be filtered near source to reduce backhaul cost. HPE’s Private Cloud AI bundles show how traditional virtualization stacks now ship with GPU options to cover inferencing tasks inside the same chassis hpe. As organizations right-size their estates, virtualization retains momentum, further widening the addressable base for the North America data center server market.
Data-Sovereignty Mandates in Canada and Mexico
Government rules that citizen data stay on local soil have triggered a building boom north and south of the US border. Eighty-eight percent of Canadian IT leaders insist on domestic hosting, prompting OVHcloud and hyperscalers alike to add capacity in Ontario. Mexico’s nearshoring wave is pushing US manufacturers to process cross-border data inside newly commissioned Queretaro campuses so that both NAFTA and local privacy rules are met. These mandates lengthen contract tenures and raise switching costs, fortifying recurring revenue for operators that satisfy local compliance. Over the long term, sovereignty laws will continue to enlarge the North America data center server market footprint beyond traditional US cores.
Restraints Impact Analysis of North America Data Center Server Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating data-center CapEx and land costs | -2.3% | US metros, Toronto | Short term (≤ 2 years) |
| Supply-chain volatility for custom silicon | -1.8% | North America | Medium term (2-4 years) |
| Grid-power constraints in key metros | -2.1% | Northern Virginia, Dallas, Silicon Valley | Short term (≤ 2 years) |
| Sustainability / Scope-3 emissions compliance | -1.2% | Corporate mandates | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Escalating Data-Center CapEx and Land Costs
Speculative real-estate bidding in Loudoun County and Santa Clara has doubled parcel prices within 18 months, inflating greenfield project budgets well above earlier pro-formas.[2]Quartz, “Data-Center Land Prices Signal Bubble,” qz.com Build costs rise further when liquid-cooling loops and high-amp busways required by AI servers are included. Microsoft and Amazon have slowed several planned sites, choosing to redeploy capital to secondary regions with cheaper acreage while demand remains intact. Locked-in land premiums cascade through lease rates, potentially delaying smaller entrants’ expansion. Unless permitting fast-tracks or rezoning unlocks fresh parcels, the North America data center server market could experience periodic supply gaps.
Grid-Power Constraints in Key Metros
Utilities in Northern Virginia now face transformer lead times surpassing 150 weeks, holding up energization of pre-leased halls that are otherwise construction-ready.[3]T&D World, “Transformer Shortage Challenges Grid,” tdworld.com Analysts forecast AI data centers could consume up to 12% of US electricity by 2028, a tripling from 2024 levels qz. Southwest providers NV Energy and APS have logged connection requests topping 10 GW, rivaling entire state loads. Power scarcity steers investors toward hydro-rich provinces or Midwest wind corridors, altering historical clustering patterns. Persistent grid headwinds temper short-term capacity expansions for the North America data center server market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Data Center Server Market Segment Analysis
By Data-Center Tier:
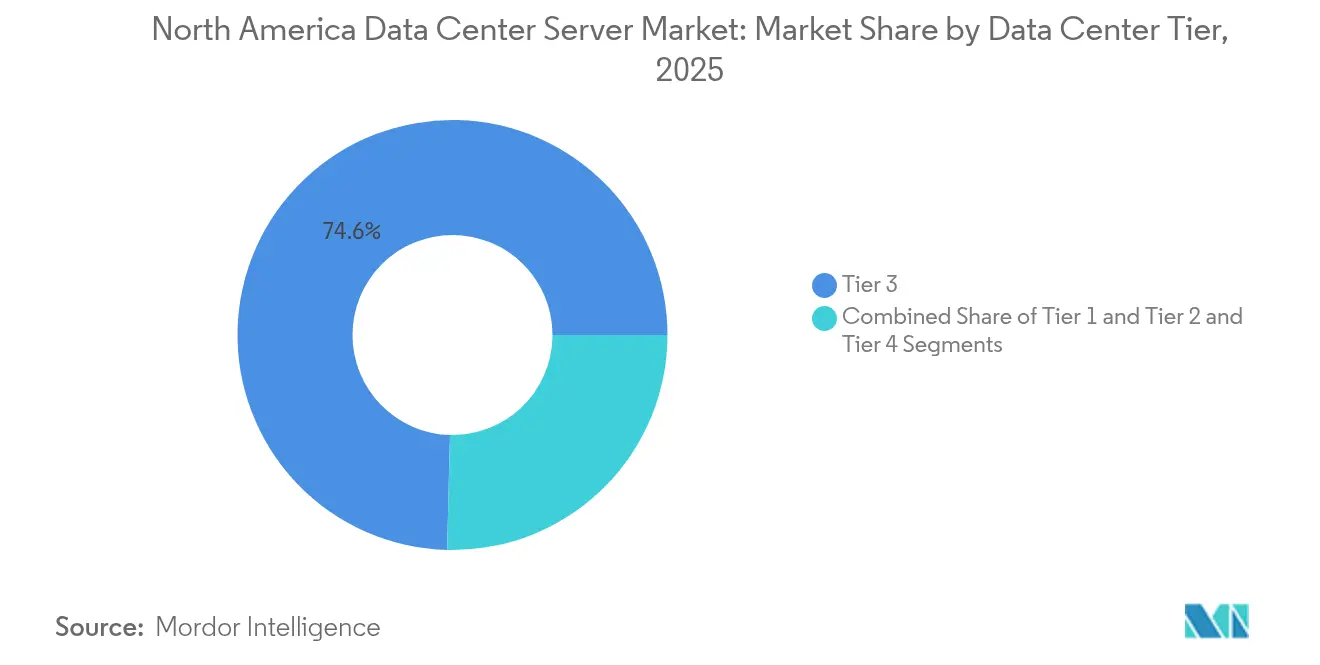
Balanced Tier 3 Dominance and Tier 4 MomentumTier 3 facilities captured 74.60% of 2025 revenue in the North America data center server market, underscoring their appeal for enterprise workloads requiring N+1 resilience without the premium of 2N architectures. Tier 3 build specifications satisfy most virtualization, backup and cloud-gateway tasks while retaining favorable operating economics. Yet hyperscalers training multi-trillion-parameter models now prize Tier 4 environments where concurrent maintenance and fault tolerance are mandatory for uninterrupted GPU clusters that cost tens of millions of USD. As a result, Tier 4 revenue is projected to rise 18.56% CAGR through 2031, gradually lifting its North America data center server market size contribution.
The Tier 4 surge has spurred innovations in modular data halls pre-configured with lithium-ion UPS, rear-door heat exchangers and redundant spine-leaf fabrics. Vendors such as Vertiv recently introduced factory-integrated “360AI” blocks that shorten deployment to under 26 weeks, shaving months off customary greenfield schedules. Meanwhile, Tier 1 and Tier 2 camps remain useful for content caching, local manufacturing execution systems and other edge roles. Over the forecast window, the coexistence of multiple tiers improves workload placement flexibility, sustaining diverse revenue streams inside the North America data center server market.


By Form Factor:
Half-Height Stability and Micro-Blade AccelerationHalf-height blades held a commanding 61.55% share in 2025 as enterprises continue to favor familiar 42-U racks that balance compute density with airflow requirements. The design supports two-socket x86 boards paired with modest power budgets, keeping cooling retrofits minimal. However, the North America data center server market size for micro-blade and quarter-height systems is projected to grow fastest at 17.92% CAGR, propelled by the edge build-out associated with IoT and 5G workloads.
Quarter-height frames can slip into telco street cabinets or factory closets where space and weight are constrained. Advancements in system-on-chip architecture and PCIe Gen5 have allowed vendors to embed AI accelerators onto these compact sleds, making them useful for real-time inference. Full-height blades continue to serve HPC and oil-and-gas seismic imaging, yet their marginal growth underscores a pivot toward smaller, power-efficient nodes. The net effect is an expanding portfolio that lets operators mix dense AI training racks at the core with lightweight micro-blades in metro rings, enriching the overall value proposition of the North America data center server market.
By Application/Workload:
AI/ML Ascendancy and Hybrid Virtualization GrowthArtificial-intelligence and machine-learning tasks accounted for 38.84% revenue in 2025, cementing the segment as the single largest within the North America data center server market. Generative models, recommendation engines and autonomous-vehicle simulations require tightly coupled GPU fabrics and ultra-fast NVMe storage, pushing power envelopes to unprecedented levels. Suppliers that can guarantee direct-liquid-cool ready chassis and out-of-band telemetry for thermal optimization increasingly win large blocks of business.
Virtualization and private cloud services, while more mature, are forecast to post a robust 17.02% CAGR through 2031 as firms rationalize SaaS spend and bring steady-state workloads back on-prem. This migration aligns with data-sovereignty rules and helps reduce egress fees. High-performance computing retains a niche among life-sciences and energy majors but benefits indirectly when AI-adjacent simulation workflows grow. Storage-centric and edge-gateway tasks round out the mix, ensuring that product managers must support a spectrum of I/O profiles if they aim to capture wallet share within the North America data center server market.
By Data-Center Type:
Colocation Leadership and Hyperscaler SurgeColocation operators supplied 57.70% of North America data center server market share in 2025, leveraging interconnection ecosystems and pay-as-you-grow models that appeal to mid-market enterprises. Providers such as CoreSite now advertise NVIDIA DGX-Ready suites with 70 kW per rack and chilled-door heat rejection, proving that shared facilities can meet AI demands previously reserved for owner-operated campuses. Flexible lease terms also help tenants hedge against fast-moving GPU roadmaps.
Hyperscalers, on the other hand, are scaling physical footprints at 20.64% CAGR as Microsoft, Google and Meta each pledge multi-billion-dollar annual capital outlays. Their proprietary network fabrics and custom silicon designs intensify vertical integration, although many still sub-lease capacity inside carrier-neutral mega-halls during construction. Edge and enterprise self-builds continue to fulfill ultra-low-latency or compliance-led workloads. From a strategic standpoint, the coexistence of multiple facility archetypes expands the addressable North America data center server market size and cushions operators against single-segment volatility.

By End-Use Industry:
IT and Telecom Core and Manufacturing UpswingThe IT and Telecom vertical consumed 34.58% of servers shipped in 2025, reflecting its historical role as a first adopter of new processor generations and higher-speed interconnects. Telecom carriers are upgrading central offices into mini-data centers to deliver 5G-enabled edge computing, while SaaS providers are expanding colocation racks to control latency. Because these workloads are evergreen, the segment remains foundational to the North America data center server market.
Manufacturing and Industry 4.0 is projected to be the fastest-growing sector at an 18.05% CAGR, driven by computer-vision quality control and predictive maintenance systems embedded on factory floors. GPU-equipped micro-nodes crunch telemetry streams locally before archiving to core clouds, reducing downtime costs. Healthcare, BFSI, energy, and public-sector deployments follow similar patterns, each layering AI inference on top of legacy virtualization estates. The diversified end-user base mitigates cyclicality and broadens revenue streams within the North America data center server market.
Geography Analysis
United States Data Center Server Market
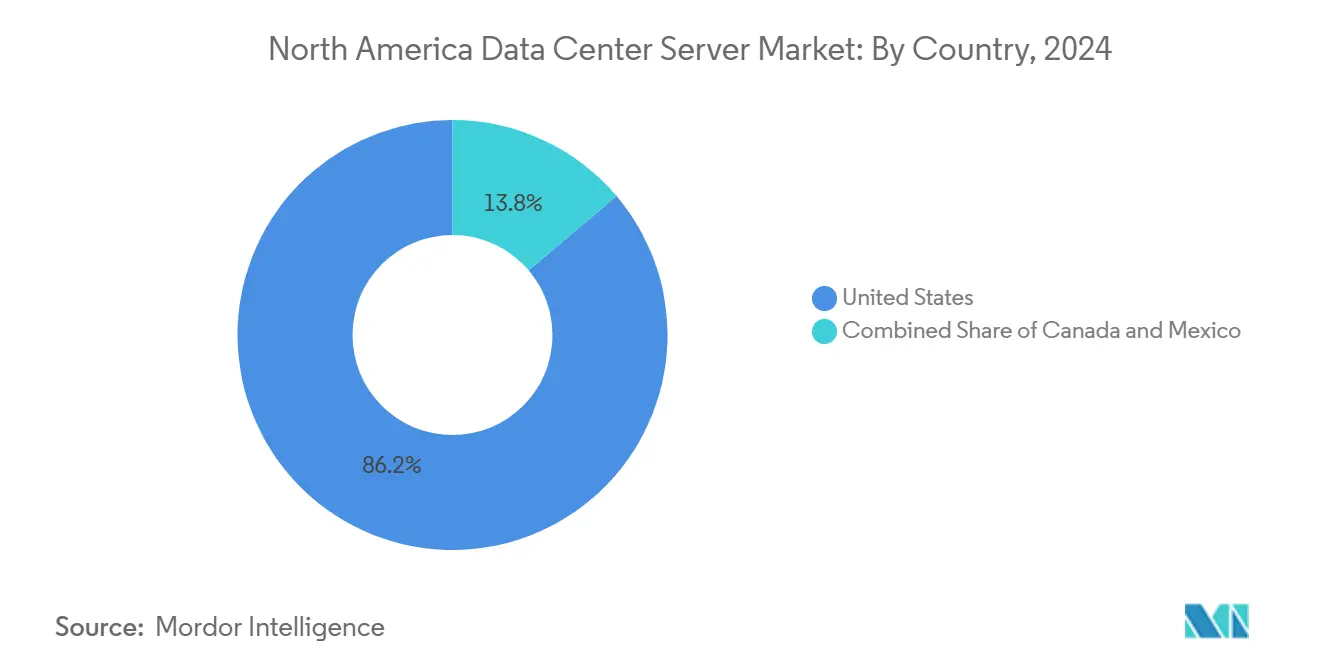
The United States retained 85.80% of 2025 revenue thanks to Northern Virginia, Dallas-Fort Worth and Silicon Valley clusters that house the largest hyperscale footprints globally northspyre. Yet skyrocketing land prices and grid bottlenecks now prompt operators to scout secondary markets such as Columbus and Kansas City where utilities can still promise multi-hundred-megawatt blocks. Policy incentives, including investment-tax credits for clean-energy-powered facilities, further shape site-selection models, ensuring the North America data center server market continues extending into new US regions.
Canada Data Center Server Market
Canada, forecast to grow 19.05% CAGR, benefits from abundant hydroelectric power and cooler ambient temperatures that lower PUE levels. The federal CAD 240 million AI-infrastructure program and provincial grants accelerate build starts in Toronto-Waterloo and Montréal. Cyber-security rankings that place the nation fifth worldwide also reassure regulated industries such as finance and healthcare. With 88% of enterprises demanding in-country hosting, server shipments into Canadian halls are set to outpace the broader North America data center server market.
Mexico Data Center Server Market
Mexico’s Queretaro corridor has emerged as Latin America’s fastest-rising hub, anchored by ODATA’s USD 3 billion, 400 MW campus that addresses US nearshoring supply-chain strategies mexicobusinessnews. Renewable-energy targets of 45% clean electricity by 2030 align with corporate ESG scorecards, drawing hyperscalers that require low-carbon grids. However, talent-pipeline constraints and regulatory fluidity must be resolved to maximize Mexico’s contribution to the North America data center server market.
Regulatory Landscape
Regulation affecting North America data center servers increasingly combines data-security oversight with grid and local-permitting controls. In the United States, the Department of Justice Bulk Data Rule and the Department of Commerce proposed know-your-customer style requirements for IaaS providers (customer verification and monitoring for malicious cyber activity) add compliance-driven scrutiny around where workloads run and how customers are onboarded. On the infrastructure side, the Federal Energy Regulatory Commission opened Docket RM26-4-000 on April 16, 2026, to develop more uniform approaches for interconnecting large electrical loads of 20 MW or greater and allocating associated costs, a material variable for new high-density AI server halls.
State and local requirements also shape site selection, generator sizing, and project timelines. Virginia DEQ rules effective July 1, 2026 tighten runtime-related constraints for certain backup diesel generators in air-quality nonattainment areas, influencing resiliency design choices (including gas alternatives) for facilities supporting Tier 3 and Tier 4 builds. By mid-2026, numerous states had adopted some form of foreign ownership restriction tied to real property or critical infrastructure, and South Dakota enacted SB 135 and HB 1038 on March 24, 2026 with structured disclosures and cost-allocation protections for data centers of 10 MW or larger, reinforcing the broader shift toward power plus permission planning rather than power-only site decisions.
Competitive Landscape
Competition in the North America data center server market is intensifying as differentiation shifts toward AI-optimized thermals, rapid configuration services, and co-design with GPU vendors. Dell’s Infrastructure Solutions Group posted USD 11.6 billion revenue during Q2 2025, up 80% in servers and networking, demonstrating resilience across both enterprise and AI pipelines. Hewlett-Packard Enterprise consolidated its position through turnkey liquid-cooled racks aligned with NVIDIA’s MGX reference platform, while fulfilling a USD 1 billion single-customer AI order that validated scale-out capacity.
Super Micro leveraged original-design-manufacturer agility by partnering closely with NVIDIA on accelerated roadmaps, lifting quarterly revenue to nearly USD 6 billion and capturing greenfield AI clusters where legacy OEMs could not match delivery speed. Colocation operators such as CoreSite and Cologix are moving up the stack with DGX-Ready bays and GPU-as-a-service, courting enterprises that prefer Opex-based experimentation before scaling. Power-and-cooling specialists Eaton and Siemens Energy now co-develop on-site natural-gas plants that eliminate diesel generators and cut CO? emissions by 50%, illustrating convergence between IT and energy supply chains eaton. The resulting ecosystem complexity compels customers to engage multi-vendor consortia, reinforcing service-led sales motions across the North America data center server market.
North America Data Center Server Industry Leaders
Dell Inc.
Hewlett Packard Enterprise
Lenovo Group Limited
Cisco Systems Inc.
Supermicro
- *Disclaimer: Major Players sorted in no particular order
North America Data Center Server Market Companies Covered in this Report
- Dell Technologies Inc.
- Hewlett Packard Enterprise Co.
- Lenovo Group Ltd.
- Cisco Systems Inc.
- IBM Corporation
- Super Micro Computer Inc.
- Quanta Computer Inc.
- Wiwynn Corp.
- Inspur Group
- Foxconn Technology Group
- Gigabyte Technology Co. Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- NEC Corp.
- AMAX Information Technologies
- Penguin Computing (SMART Global)
- ASUStek Computer Inc.
- Hewlett-Packard Enterprise Services
- Huawei Technologies Co. Ltd.*
- Tyan Computer Corp.

Market Opportunities and Future Outlook
Opportunity centers on AI-optimized server platforms and the supporting ecosystems needed to deploy them at speed under power, permitting, and sovereignty constraints. Vendor roadmaps are moving toward very high GPU density, liquid-cooling readiness, and rack-scale integration for AI/ML and emerging agentic AI use cases. Dell and HPE both announced NVIDIA Vera CPU-based server platforms in 2026, which signals an active competitive cycle in next-generation AI server architectures.
The scale of AI server demand is also visible in supplier financing and fulfillment actions, including Supermicro's June 2026 announcement of a USD 7.0 billion financing plan to support fulfillment of approximately USD 39 billion in recent AI server orders. This points to whitespace for component partners, integrators, and colocation operators that can deliver power and cooling for dense GPU deployments. Geographic whitespace is also forming where grid constraints and permitting complexity in mature US metros push capacity planning into secondary markets and cross-border options. Canada remains an active outlet for sovereignty-led deployments, supported by federal CAD 240 million AI infrastructure funding and strong preference for in-country hosting among Canadian enterprises, which supports local demand for compliant server installations and managed GPU capacity. In 2026, the siting model is increasingly framed as power-plus-permission, favoring developers and suppliers that pair server delivery with community engagement, noise and water planning, and transparent cost-allocation practices. That dynamic creates openings for standardized, modular designs (including Tier 4-ready blocks) and service-led offerings that shorten time-to-energization for new halls.
Recent Industry Developments in North America Data Center Server Market
- June 2026: Dell Technologies introduced the PowerEdge XE8812 server featuring NVIDIA Vera Rubin NVL4 architecture, capable of up to 144 GPUs per rack. The AI-optimized, high-GPU-density platform expands Dell's leadership in data-center AI infrastructure in North America and increases competitive pressure on peers to offer denser GPU configurations.
- June 2026: Dell Technologies launched the PowerEdge R9822 and M9822 servers built with NVIDIA Vera CPUs to support agentic AI. The agentic AI capable compute hardware strengthens Dell's enterprise and CSP offerings and reinforces the shift to Vera CPU based AI workloads in the market.
- June 2026: HPE announced the ProLiant Compute DL394 Gen12 server, powered by NVIDIA Vera CPU, for agentic AI workloads. The Vera CPU integration in enterprise-ready servers pivots HPE's AI server strategy and increases competition in agentic AI ready infrastructure.


North America Data Center Server Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers revenue generated from servers deployed in data centers across North America, covering commonly shipped server types and form factors used for enterprise, colocation, and hyperscale environments, and counted as hardware market value in USD.
Scope exclusions: We exclude software, data center construction and power equipment, and ongoing managed services revenue that sits outside the server hardware bill.
Segments Covered in This Report
- By Data-Center Tier
- Tier 1 and 2
- Tier 3
- Tier 4
- By Form Factor
- Half-height Blades
- Full-height Blades
- Quarter-height / Micro-blades
- By Application / Workload
- Virtualisation and Private Cloud
- High-Performance Computing (HPC)
- Artificial Intelligence/Machine Learning and Data Analytics
- Storage-centric
- Edge / IoT Gateways
- By Data Center Type
- Hyperscalers/Cloud Service Provider
- Colocation Facilities
- Enterprise and Edge
- By End-use Industry
- BFSI
- IT and Telecom
- Healthcare and Life-Sciences
- Manufacturing and Industry 4.0
- Energy and Utilities
- Government and Defence
- Geography
- United States
- Canada
- Mexico
Data Sources, Market Sizing, and Validation
Desk Research
Desk research is first used to set the overall demand context, then to pin down the measurable supply and deployment signals that a server market model needs. We referenced public statistical and technical sources such as the US International Trade Commission data portal, US Census trade series, Bureau of Labor Statistics price indexes, Statistics Canada releases, and energy related datasets from the US Energy Information Administration, since data center activity often shows up through power and capacity signals.
Alongside these, we reviewed company annual reports, earnings call transcripts, and investor decks to understand capex cycles, platform transitions, and procurement patterns. Patent databases were also checked to spot shifts in acceleration, memory, and cooling related designs that influence pricing and shipment mix. In a few places, paid subscriptions that consolidate company financials and track shipment level imports were used to speed up cross checks, though the final model still depended on openly explainable inputs. The desk sources mentioned here are illustrative only, and many other public documents and datasets were also used for validation and clarification.
Primary Interviews and Surveys
Primary work was run to pressure test the desk assumptions and to convert qualitative signals into model inputs that can be applied year by year. We spoke with a mix of server ecosystem participants such as OEM channel partners, data center operators, colocation firms, and large enterprise infrastructure teams across the United States and Canada, then compared responses across buyer types to avoid single cohort bias.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 35% | CXOs: 13% |
| Mid tier: 51% | Functional/Unit leaders: 32% |
| Smaller Players: 14% | Managers: 55% |
Market-Sizing & Forecasting
Sizing starts with a top-down build that reconstructs the server spending pool from data center expansion and refresh activity, and then allocates it across North America based on deployment intensity by country. To keep totals realistic, the outputs were corroborated with selective bottom-up approximations such as sampled average selling price (ASP) ranges by form factor, channel feedback on annual shipment direction, and quick roll ups of visible supplier revenue exposure to data center servers.
A few inputs that mattered most in this market were server refresh cadence in hyperscale and colocation fleets, AI and accelerated compute mix that lifts ASPs, rack density and power availability signals that cap near term deployments, virtualization and private cloud workload growth that affects general-purpose server demand, and cross border trade indicators that help sanity check shipment momentum. Where bottom-up views had gaps (for example, limited disclosure on specialty configurations), we used primary ranges and applied conservative share bounds, which were then revisited in analyst review.
For the forecast, we used scenario analysis supported by a simple multivariate regression check, since demand can swing based on capex timing and GPU heavy configuration mix. Assumptions were finalized only after primary respondents aligned on the direction and relative strength of the key drivers, and then the model was run consistently across the forecast window.
Data Validation & Update Cycle
Validation is handled through multiple checks that look for internal consistency first, followed by external reasonableness tests. We compare the final market totals against independent signals such as trade value trends, data center build activity proxies, and observed ASP movement patterns, and then investigate any large variance before sign-off.
A second analyst review is completed to challenge key assumptions, especially on ASP progression and hyperscale refresh rates, and follow up calls are triggered if the range between interview inputs stays wide. Reports are refreshed annually, and interim updates are made when material events change procurement cycles or pricing. Before delivery, a final pass is performed so clients receive an updated view that matches the latest available inputs.
黑料不打烊's North America Data Center Server Market Sizing Compared With Other Published Estimates
Published market numbers for North America data center servers can look far apart, even when they appear to talk about similar hardware. The main reasons usually come down to what counts as a server in the dataset, whether the estimate mixes enterprise and edge hardware with data center deployments, and how pricing is treated when AI focused configurations become a larger share.
Some external figures lean narrower by focusing mainly on rack server shipments or by applying a single blended ASP across years, which tends to mute the impact of accelerators and high memory builds. Other estimates go broader by bundling additional data center infrastructure or by using older currency timing and a slower refresh assumption. In 黑料不打烊, the total is counted only for server hardware revenue deployed in data centers across the United States and Canada, and adjacent software and facility equipment are kept out of the value to avoid inflating the number.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 63.87 B (2025) | |
| Trade Journal A | USD 21.50 B (2024) | Often tracks rack server shipments with a narrow hardware definition, which can exclude higher value configurations and understate AI driven ASP uplift, and it also reflects a different base year. |
| Industry Bulletin B | USD 29.90 B (2033) | Uses a long range projection with a low growth path and limited refresh cycle differentiation, and the scope is commonly summarized at a high level which makes unit mix and pricing steps hard to replicate. |
The comparison shows that the spread is mostly explained by scope and pricing mechanics rather than simple math differences. By keeping the market tied to data center server hardware value in the two country region and by updating the key inputs that move ASPs and refresh timing, the estimate stays traceable to a repeatable set of steps.


Key Questions Answered in the Report
How large is the North America data center server market today?
The market generated USD 72.33 billion in 2026 and is projected to reach USD 134.58 billion by 2031, delivering a 13.24% CAGR.
What workload segment leads server purchases?
AI and machine-learning servers account for 38.84% of 2025 revenue, reflecting the rise of GPU-dense racks deployed for generative AI training.
Which facility type is growing fastest?
Hyperscale data centers are expanding at a 20.64% CAGR as cloud providers commit multi-billion-dollar budgets to support AI services.
Why is Canada attracting new data centers?
Abundant hydro power, cooler climates and strict data-sovereignty rules underpin Canada’s 19.05% CAGR growth forecast.
What limits capacity expansion in the United States?
Grid-power constraints and soaring land prices in prime metros delay energization of new halls, moderating short-term supply additions.
How will 5G influence future server demand?
5G roll-outs drive edge computing nodes that require quarter-height and micro-blade servers, pushing high-growth pockets at metro aggregation points.
Page last updated on:
- Artificial Intelligence (AI) Data Center Market AI facilities across the global market, covering facility type, component and tier.
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Data Center Services Market Managed services across the global market, covering service, tier and end-user industry.
- North America Artificial Intelligence (AI) Data Center Market North America AI facilities, split by facility type, component and tier.



