
Integrated Traffic System Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 44.27 Billion |
| Market Size (2031) | USD 69.05 Billion |
| Growth Rate (2026 - 2031) | 9.30 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Integrated Traffic System Market Analysis by 黑料不打烊
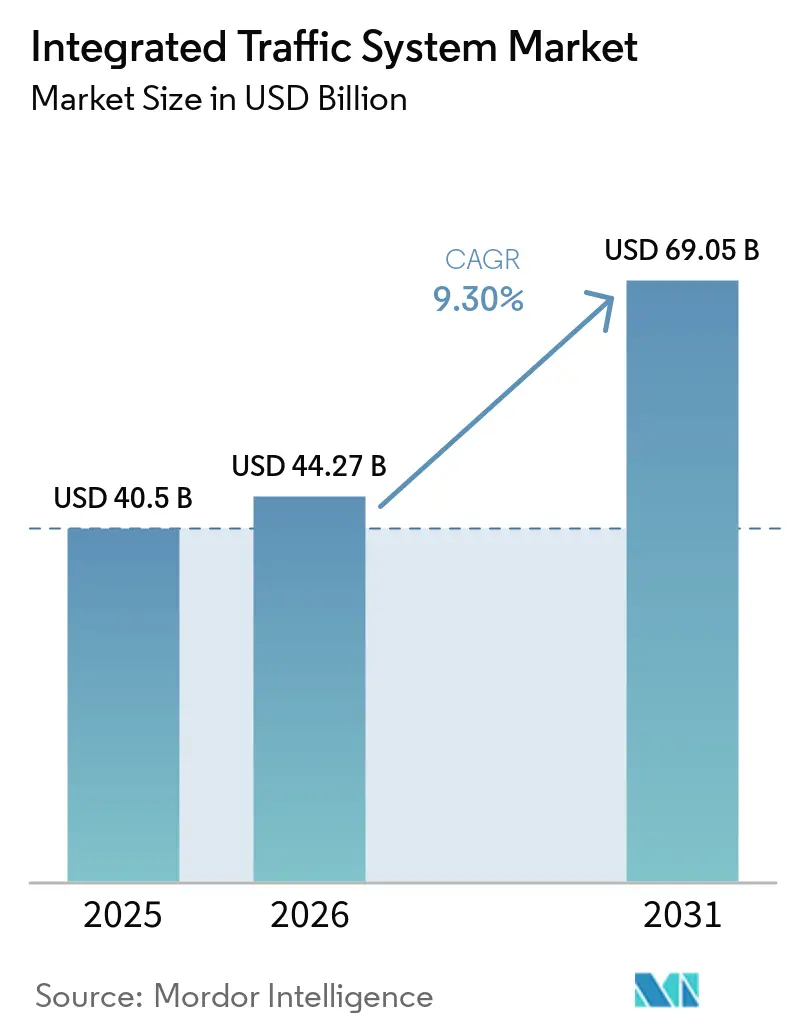
The integrated traffic system market size was valued at USD 40.50 billion in 2025, is estimated at USD 44.27 billion in 2026, and is projected to reach USD 69.05 billion by 2031, growing at a CAGR of 9.30 % from 2026 to 2031. The integrated traffic system market is being shaped by wider use of AI-based signal control, continued public spending on cooperative transport infrastructure, and a move toward predictive traffic operations. Cities are seeking systems that combine signal control, monitoring, enforcement, and traveler information in one operating environment. Growing vehicle volumes in Asian and Middle Eastern cities are increasing pressure on roads that cannot be expanded quickly. Lower equipment costs are also making integrated deployments more practical for smaller cities. Procurement is shifting toward software, analytics, and managed services, which gives providers with interoperable platforms and recurring service models a stronger position.
Key Report Takeaways
- By solution, Traffic Monitoring and Detection Systems held 24.01% of the integrated traffic system market share in 2025, while Adaptive Traffic Control Systems are forecast to grow at a 10.84% CAGR through 2031.
- By component, Hardware held 49.33% of the integrated traffic system market share in 2025, while Services are forecast to grow at an 11.47% CAGR through 2031.
- By sensor type, Infrared Sensors held 37.15% share in 2025, while Radar Sensors are forecast to grow at a 10.65% CAGR through 2031.
- By function, Traffic Control held a 41.27% share in 2025 and is forecast to grow at a 9.61% CAGR through 2031.
- By application, Urban Traffic held a 62.14% share in 2025 and is forecast to grow at a 10.02% CAGR through 2031.
- By deployment model, On-Premise deployments held a 68.13% share in 2025, while Cloud-Hosted deployments are forecast to grow at an 11.76% CAGR through 2031.
- By geography, North America held a 39.21% share in 2025, while Asia-Pacific is set to grow with the fastest CAGR of 11.05% through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global Integrated Traffic System Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| AI-Based Adaptive Control | +2.1% | Global | Medium term (2-4 years) |
| Smart-City and Cooperative-ITS | +1.8% | Global, with Asia-Pacific focus | Short term (≤ 2 years) |
| Connected-Vehicle Probe Data | +1.5% | North America and Europe | Medium term (2-4 years) |
| Automated Traffic Enforcement Expansion | +1.0% | Asia-Pacific, with spillover to Middle East and Africa | Medium term (2-4 years) |
| Congestion Pricing and Charging | +0.9% | North America and Europe | Long term (≥ 4 years) |
| Multi-Modal Corridor Optimization | +0.8% | Global | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
AI-Based Predictive Adaptive Signal Control
AI-based adaptive signal control is changing how traffic agencies manage busy intersections and corridors. A 2025 scientific study found that privacy-preserving federated edge architectures improved traffic-flow efficiency versus centralized systems, with latency below real-time thresholds. These designs reduce dependence on uninterrupted cloud connections in areas with limited fiber coverage. A 2026 German technical paper described model-based reinforcement learning that tests signal strategies in simulation before live deployment. As a result, the integrated traffic system market favors providers combining simulation, edge processing, and operational control, especially as agencies assess privacy, resilience, and procurement risk.
Smart-City and Cooperative-ITS Funding
Public capital programs continue to support demand for integrated traffic technology. The European Commission awarded nearly EUR 2.8 billion (approximately USD 3.05 billion) across 94 Connecting Europe Facility Transport projects in July 2025[1]“CEF Transport: EUR 2.8 Billion for 94 Projects to Boost Sustainable and Connected Mobility Across Europe,” European Climate, Infrastructure and Environment Executive Agency, cinea.ec.europa.eu., covering sustainable and connected mobility, including Cooperative ITS, under the 2021-2027 budget framework. In Germany, the CRG-3 project supports C-ITS across six urban pilot sites, with Hamburg expected to equip 2,000 buses and 600 traffic lights by 2030. In the United States, the SMART Grant Program provides USD 100 million annually for smart signals, connected vehicles, and system coordination, strengthening interoperability-led procurement.
Connected-Vehicle Probe Data Integration
Probe data is becoming a valuable source of real-time speed and location information for traffic operations. An infrastructure engineering assessment documented significant probe-data penetration across monitored corridors, with higher levels during peak periods, supporting real-time signal adaptation beyond long-range planning. An NSF-supported study modeled vehicle-probe-based signal management at a candidate intersection and found significant reductions in queue length, average eastbound travel time, and vehicle emissions. Commercial fleet, ride-hail, logistics, and transit data can supplement roadside detection where fixed infrastructure remains incomplete. The integrated traffic system market benefits when platforms combine probe streams with controller data and roadside equipment, provided agencies address data quality, privacy controls, and operational integration.
Automated Traffic Enforcement Expansion
Automated enforcement is expanding the role of traffic technology beyond monitoring and safety management. Authorities use AI-enhanced cameras and automated number plate recognition systems to identify violations and support digital enforcement. These systems generate operational data for traffic control, road safety, and corridor management. The Chennai Intelligent Transport System project, funded through a Japan International Cooperation Agency loan, demonstrates the scale to which such deployments can be scaled in Indian metropolitan areas. The integrated traffic system market has an opportunity to embed enforcement platforms within wider traffic management systems. Automated workflows can reduce manual intervention and connect enforcement with vehicle registration databases where institutions allow. Providers that integrate enforcement, control, and analytics functions can address this demand more effectively.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Legacy-System Complexity | -1.5% | Global | Long term (≥ 4 years) |
| Procurement and Budget Volatility | -1.0% | Global | Short term (≤ 2 years) |
| Cybersecurity Compliance Cost | -0.8% | North America and Europe | Medium term (2-4 years) |
| Spectrum and Connectivity Constraints | -0.5% | Emerging Markets | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Legacy-System Integration Complexity
Legacy infrastructure can slow deployment, even when an agency has committed funding for a new platform. The United States Department of Transportation’s transition guidance identifies software, computing hardware, business processes, IT architecture, and staffing as simultaneous areas of complexity during traffic management system migration. It also notes that agencies often operate old and new systems in parallel [2]“Traffic Management System Transition Guidance,” Research and Innovative Technology Administration, rosap.ntl.bts.gov.. An industry assessment identified aging controllers, unsegmented IP networks, and inconsistent protocol implementations as common road infrastructure issues. These conditions increase implementation work beyond visible equipment and software costs. Therefore, the integrated traffic system market must address migration as a core product and service requirement. Vendors with documented legacy modernization approaches are better positioned in capital-constrained municipal procurement.
Municipal Procurement and Budget Volatility
Municipal procurement cycles do not always align with urgent congestion, safety, or transit reliability needs. Local authorities may defer controller replacements, software upgrades, and maintenance when public budgets face pressure. Digital traffic systems can face disadvantages when funding processes favor visible construction projects over software and service investments. Contract language for traditional infrastructure may not support subscription software or managed operating models, extending awards and delaying implementation. The integrated traffic system market faces challenges when public agencies cannot convert operational needs into executable procurement plans. Agencies with national or supranational funding can continue deployments, while other cities may maintain existing equipment and delay modernization. Cooperative purchasing, modular pricing, and clear service-funding models can reduce procurement barriers.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Solution: Monitoring Infrastructure Leads; Control Intelligence Accelerates
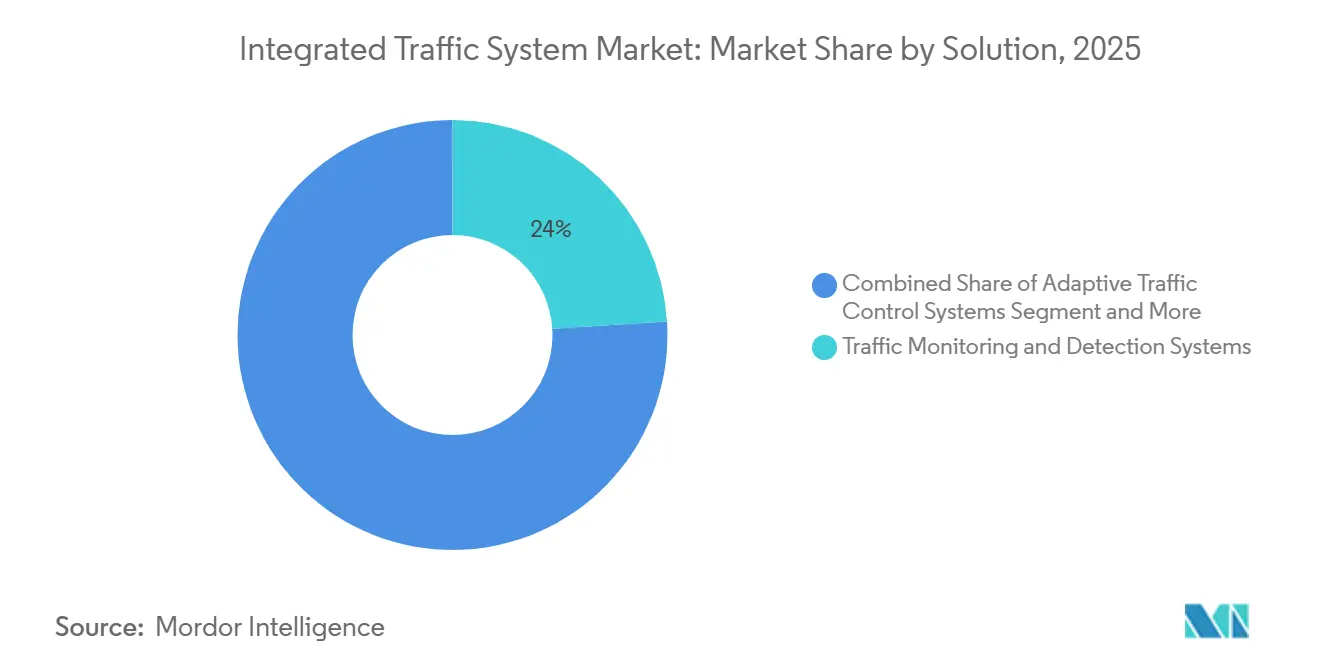
Traffic monitoring and detection systems held 24.01% of the integrated traffic system market share in 2025. Cities often establish reliable traffic visibility before committing to active control platforms. Monitoring systems collect the movement, occupancy, queue, and incident information needed for later decisions. This installed data layer can support a later move toward adaptive signal control. Traffic Signal Control Systems and Integrated Corridor and Incident Management Platforms add operational value when agencies seek a unified view of arterials and highways. Enforcement Camera and ANPR Systems also form part of the solution landscape in markets where safety and compliance priorities are strong.
Adaptive Traffic Control Systems are forecast to grow at a 10.84% CAGR through 2031. The integrated traffic system market size for adaptive control is supported by agencies that have completed earlier monitoring deployments and are ready to use the information for live control. Dynamic Message and Driver Information Systems extend this approach by communicating conditions and guidance to road users. Intelligent Driver Information Systems also become more relevant as connected-vehicle services develop. The sequence from monitoring to active control creates a durable upgrade cycle rather than a one-time equipment purchase. Providers that integrate these solution types can address the full path from detection to response.


By Component: Hardware Dominates; Services Revenue Reshapes Vendor Economics
Hardware held a 49.33% share of the integrated traffic system market size in 2025. Sensor networks, controllers, communications equipment, and physical refresh programs continue to account for substantial spending. Hardware remains especially important in markets building new road corridors or modernizing a large installed base. It provides the field layer that connects intersections and highways to the traffic management center. However, its share can decline over the contract life as software, analytics, support, and operations services become more important. Cities increasingly consider the operating value of the full system rather than the initial device purchase alone.
Services are forecast to grow at an 11.47% CAGR through 2031, the fastest rate among component categories. Agencies are outsourcing traffic management operations and advanced analytics when internal capacity is limited. A 2026 peer-reviewed study found that path-based multimodal signal progression optimization reduced average bus and passenger car delays against conventional benchmarks. This type of evidence supports the case for software and specialist service providers. Vendors with only hardware revenue face pressure as buyers seek outcome-based contracts and recurring operating support. The component mix is therefore moving toward longer-term customer relationships.
By Sensor Type: Infrared Holds Share; Radar Climbs on All-Weather Performance
Infrared sensors held a 37.15% share in 2025. They are established tools for vehicle counting, classification, and queue detection at signalized intersections. Their installed base supports their continuing role in the integrated traffic system market. Infrared detection can provide input for control strategies without requiring high-bandwidth video transmission. Inductive Loop Detectors also remain operationally familiar, although replacement needs in aging infrastructure can create refresh opportunities. Weigh-In-Motion Sensors serve separate enforcement and pavement-management applications on arterials and highways.
Radar Sensors are forecast to grow at a 10.65% CAGR through 2031. Their all-weather performance is valuable in rain, fog, and glare, where camera and infrared systems can face limits. Radar can measure vehicle speed, classification, and trajectory at the same time. Video and computer-vision sensors are also gaining attention as AI-based analytics improve their detection economics. Road-condition, visibility, and weather sensors matter in regions with extreme climate conditions. Acoustic sensors remain relevant for specialized uses, including noise monitoring and pedestrian detection at critical crossings.
By Function: Traffic Control Anchors Spending; Multimodal Optimization Grows
Traffic control accounted for 41.27% of the integrated traffic system market size in 2025 and is forecast to grow at a 9.61% CAGR through 2031. This reflects the priority that agencies place on real-time management of intersections and corridors. Traffic monitoring provides the data that enables these decisions, while control systems apply timing changes and priority rules. Information Provision includes dynamic message signs, traveler information portals, and in-vehicle notifications. These tools help cities move from passive observation toward active management of demand and network conditions. Traffic control remains the main operational link between collected data and street-level outcomes.
Multimodal corridor optimization is an important part of this growth because cities need to improve transit reliability without ignoring general traffic flow. Coordinated signal strategies for buses and private vehicles reduce total stops compared to conventional methods. This supports adoption of systems that consider several user groups within the same corridor. The integrated traffic system market is responding to a need for traffic operations that combine transit signal priority with broader movement management. Providers that offer flexible control logic can address these operating requirements.
By Application: Urban Traffic Dominates; Tunnel and Port Verticals Gain Complexity Value
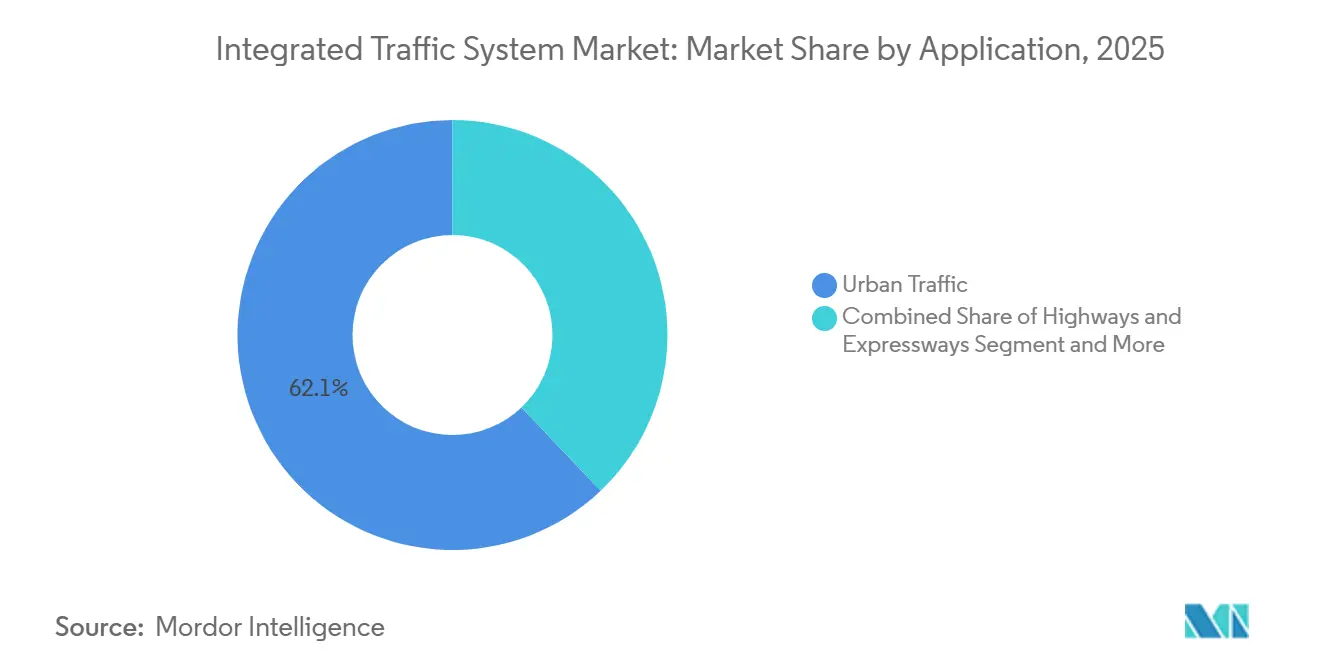
Urban traffic held a 62.14% share in 2025 and is forecast to grow at a 10.02% CAGR through 2031. Dense city networks contain large numbers of intersections and competing mobility demands. Downtown congestion management is also a visible political and operating priority. Urban corridors can require systems that handle transit, pedestrians, cyclists, delivery vehicles, and private vehicles at the same time. The integrated traffic system market is therefore centered on city applications where the value of coordinated control is most direct. Highways and Expressways remain important but have different procurement cycles and operating needs.
Highways and Expressways depend on variable speed limits, incident detection, tolling links, and long refresh cycles. Tunnels and Bridges are specialized applications with high safety and compliance requirements. Kapsch TrafficCom received a May 2025 award to manage five tunnels in Sharjah, showing the technical depth required in this application [3]“Kapsch TrafficCom to Manage Five Tunnels in Sharjah,” Kapsch TrafficCom, kapsch.net. Ports, Airports, and Intermodal Hubs are smaller application areas, but traffic flow is directly tied to facility throughput. These sites offer strong value where traffic disruption can affect broader transport operations.
By Deployment Model: On-Premise Persists; Cloud Migration Gains Momentum
On-premises deployments held a 68.13% share in 2025. Data sovereignty concerns, real-time latency needs, and established traffic management centers support continued on-premise use. Many agencies already have operational processes and equipment built around local control environments. These systems can provide direct oversight of signal operations and sensitive traffic data. The integrated traffic system market share held by on-premise models also reflects the cost and complexity of replacing existing infrastructure. For many cities, a full migration will take place in stages rather than through one system change.
Cloud-Hosted deployments are forecast to grow at an 11.76% CAGR through 2031. SaaS traffic analytics, remote monitoring, and AI inference can lower the infrastructure burden for agencies with limited local IT capacity. Edge-Hosted and Hybrid approaches offer a practical middle ground where fast local decisions are needed alongside centralized analytics. The United Kingdom's Integrated Transport Digital Twin Fund provides GBP 30 million for 2026 to 2030 and supports cloud-based digital twin trials at selected local transport authorities [4]“Applying for the Integrated Transport Digital Twin Fund,” UK Government, gov.uk. . This public support indicates greater confidence in cloud-based transport applications. Deployment decisions will continue to depend on latency, resilience, local data rules, and the ability to connect with existing controllers.
Geography Analysis
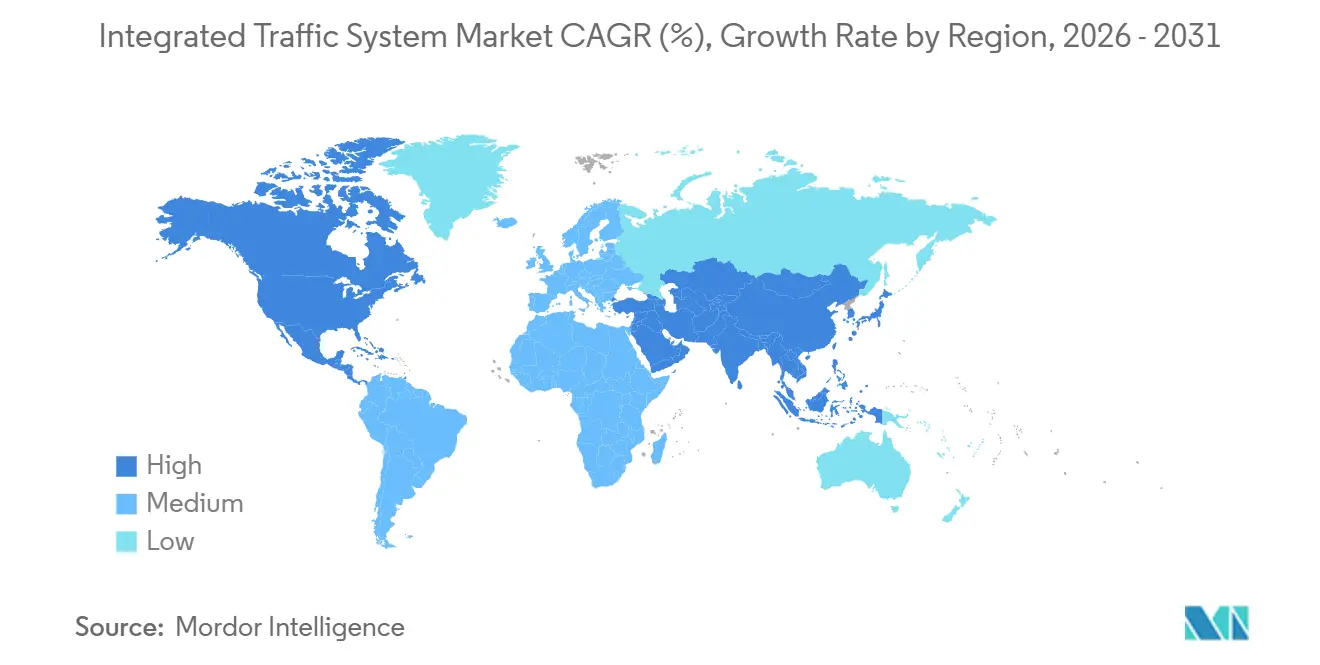
North America held 39.21% of the integrated traffic system market share in 2025. Federal grant programs, mature municipal procurement channels, and a developed vendor base support regional demand. The U.S. SMART Grant Program provides funding each year for smart traffic signal, connected-vehicle, and systems-coordination demonstrations. This funding helps cities test technology before making larger commitments. New York City's congestion-pricing program launched in January 2025 and reduced entries into the Congestion Relief Zone by 27 million in its first year. The program cut traffic and generated significant net revenue for transit infrastructure.
Asia-Pacific is forecast to grow at an 11.05% CAGR through 2031. India, South Korea, Southeast Asia, Japan, China, and Australia each contribute different sources of demand. South Korea is expected to select cities through its 2026 Smart City Development Project competition and award Suwon funding for AI-driven traffic and smart mobility systems. Chennai’s Intelligent Transport System, funded by the Japan International Cooperation Agency, aims to improve traffic management, road safety, and public transport services. Mature markets are also expected to continue investing in upgrades, as illustrated by Kapsch TrafficCom’s Melbourne EastLink tolling upgrade award in 2026. The region combines the needs of large metropolitan areas with smaller city deployments, which are becoming more feasible as equipment costs decline.
Europe is growing at a measured pace, supported by a strong regulatory and funding framework. The European Commission’s 2025 CEF Transport awards are expected to provide a funding base for Cooperative ITS rollouts and related connected-mobility projects. Kapsch TrafficCom received an award to deploy its EcoTrafix platform across intersections in Madrid. This trend supports frequent city-level projects with renewal potential. South America and the Middle East, and Africa remain earlier-stage, project-led markets where contract scale and procurement conditions vary. The integrated traffic system market in these regions depends on stable funding availability, local integration capacity, and clear public operating priorities.

Competitive Landscape
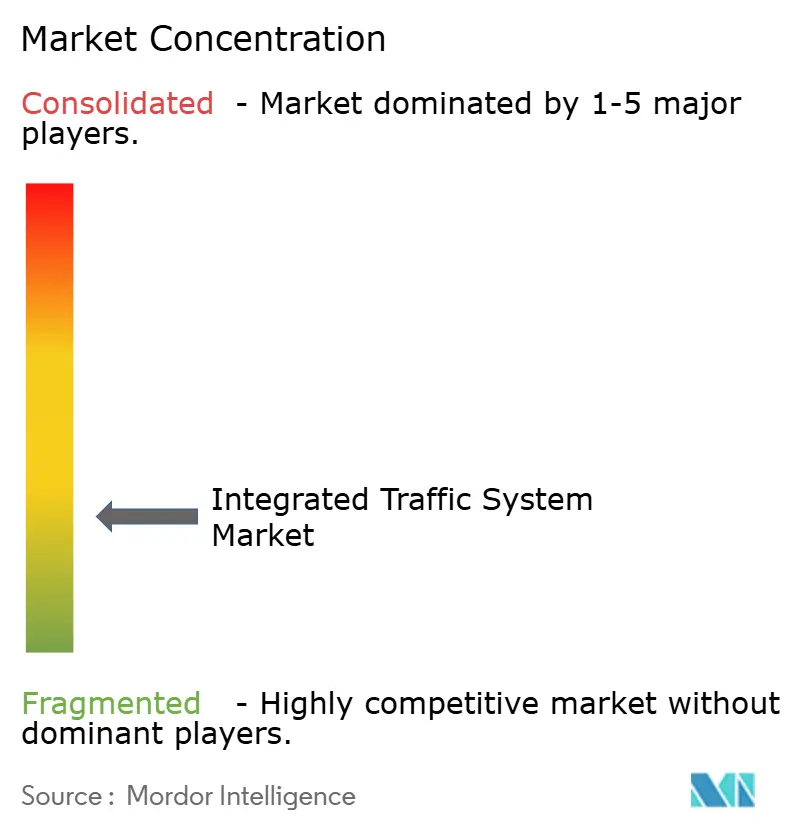
The integrated traffic system market is moderately fragmented. Siemens AG, Kapsch TrafficCom, and SWARCO compete for major city and national contracts alongside AI-focused software providers and specialized sensor companies. Incumbents benefit from long maintenance relationships, standards compliance, and established agency contacts. Kapsch operates 8 traffic management centers across the United States and has maintained Barcelona's northern traffic infrastructure for more than 30 years. These operating relationships can make procurement decisions less dependent on initial equipment price. They also create a strong need for new entrants to prove technical reliability and integration capability.
Competitive strategies are moving toward partnerships, software alliances, and targeted acquisitions. SWARCO has established a dedicated ITS business, while Umovity, Econolite, and PTV Group have been associated with AI-based adaptive signal work in Hamburg. Iteris acquired ThruGreen Technology in November 2025 to improve cloud-to-controller connectivity. The move addressed the practical need to connect cloud analytics with different intersection controllers without replacing field hardware. The integrated traffic system market rewards companies that can add software capability while protecting existing customer investments. This is why partnerships and acquisitions have become important alternatives to building every capability internally.
AlmavivA acquired Iteris for USD 335 million in November 2024, placing a traffic sensor and analytics provider within a larger digital services group. The transaction highlights interest in traffic platforms with service and recurring-revenue potential. Miovision expanded its TomTom partnership in January 2026, extending probe-data coverage to more than 300,000 intersections through hundreds of millions of mobile endpoints. Edge AI in connectivity-limited locations, multimodal transit priority, and cybersecurity support for older controllers remain important areas of competition. Compliance with industrial and automotive cybersecurity standards can be a significant entry barrier for smaller providers.
Integrated Traffic System Industry Leaders
Siemens AG
Kapsch TrafficCom AG
SWARCO AG
Cubic Corporation
Parsons Corporation
- *Disclaimer: Major Players sorted in no particular order

Recent Industry Developments
- August 2026: Hamburg's State Authority for Roads, Bridges and Waterways signed a partnership agreement with Umovity to develop a cloud-based, AI-powered adaptive traffic signal control system. The PULS project aims to replace predefined, rule-based signal control with a system that learns from live traffic conditions.
- July 2026: Hitachi Rail completed the acquisition of U.S.-based Clever Devices, a provider of ITS solutions for public transportation deployed across 8 of the 10 largest transit agencies in North America, with projected 2026 revenues exceeding USD 220 million. The acquisition expands Hitachi Rail's multimodal mobility platform, HMAX, and strengthens its North American integrated transit management presence.
- June 2026: The INR 530 crore (~USD 64 million) Chennai Intelligent Transport Systems project is expected to become fully operational by August. The Japan International Cooperation Agency-funded project is installing infrastructure across major roads and junctions to improve traffic management, road safety, and public transport services.
- April 2026: Ahmedabad rolled out an AI-powered traffic management system to reduce congestion and long signal wait times. The city deployed its Adaptive Traffic Control System at 10 key junctions as a pilot project.


Global Integrated Traffic System Market Report Scope
The scope includes segmentation by solution (traffic monitoring and detection systems, adaptive traffic control systems, traffic signal control systems, enforcement camera and automatic number-plate recognition systems, dynamic message and driver information systems, integrated corridor and incident management platforms, and intelligent driver information systems), component (hardware (sensors, controllers, cameras, and others), software, and services), sensor type (infrared sensors, weigh-in-motion sensors, acoustic sensors, inductive loop sensors, radar sensors, video and computer-vision sensors, and road-condition and weather sensors), function (traffic monitoring (automatic vehicle detection, journey-time measurement, and traffic data collection and dissemination), traffic control (adaptive signal control, parking and curb management, and incident detection and response), information provision (dynamic message signs and multi-modal traveler information)), application (urban traffic, highways and expressways, tunnels and bridges, and ports, airports, and intermodal hubs), and deployment model (on-premise, cloud-hosted, and edge-hosted and hybrid). The analysis also covers regional-level segmentation, including North America, South America, Europe, Asia-Pacific, the Middle East, and Africa. Market size and growth forecasts are presented by value in USD.
| Traffic Monitoring and Detection Systems |
| Adaptive Traffic Control Systems |
| Traffic Signal Control Systems |
| Enforcement Camera and Automatic Number-Plate Recognition Systems |
| Dynamic Message and Driver Information Systems |
| Integrated Corridor and Incident Management Platforms |
| Intelligent Driver Information Systems |
| Hardware | Sensors |
| Controllers | |
| Cameras | |
| Others | |
| Software | |
| Services |
| Infrared Sensors |
| Weigh-In-Motion Sensors |
| Acoustic Sensors |
| Inductive Loop Detectors |
| Radar Sensors |
| Video and Computer-Vision Sensors |
| Road-Condition, Visibility, and Weather Sensors |
| Traffic Monitoring | Automatic Vehicle Detection |
| Journey-Time Measurement | |
| Traffic Data Collection and Dissemination | |
| Traffic Control | Adaptive Signal Control |
| Parking and Curb Management | |
| Incident Detection and Response | |
| Information Provision | Dynamic Message Signs |
| Multi-Modal Traveler Information |
| Urban Traffic |
| Highways and Expressways |
| Tunnels and Bridges |
| Ports, Airports, and Intermodal Hubs |
| On-Premise |
| Cloud-Hosted |
| Edge-Hosted and Hybrid |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East and Africa | Saudi Arabia |
| United Arab Emirates | |
| Turkey | |
| South Africa | |
| Rest of Middle East and Africa |
| By Solution | Traffic Monitoring and Detection Systems | |
| Adaptive Traffic Control Systems | ||
| Traffic Signal Control Systems | ||
| Enforcement Camera and Automatic Number-Plate Recognition Systems | ||
| Dynamic Message and Driver Information Systems | ||
| Integrated Corridor and Incident Management Platforms | ||
| Intelligent Driver Information Systems | ||
| By Component | Hardware | Sensors |
| Controllers | ||
| Cameras | ||
| Others | ||
| Software | ||
| Services | ||
| By Sensor Type | Infrared Sensors | |
| Weigh-In-Motion Sensors | ||
| Acoustic Sensors | ||
| Inductive Loop Detectors | ||
| Radar Sensors | ||
| Video and Computer-Vision Sensors | ||
| Road-Condition, Visibility, and Weather Sensors | ||
| By Function | Traffic Monitoring | Automatic Vehicle Detection |
| Journey-Time Measurement | ||
| Traffic Data Collection and Dissemination | ||
| Traffic Control | Adaptive Signal Control | |
| Parking and Curb Management | ||
| Incident Detection and Response | ||
| Information Provision | Dynamic Message Signs | |
| Multi-Modal Traveler Information | ||
| By Application | Urban Traffic | |
| Highways and Expressways | ||
| Tunnels and Bridges | ||
| Ports, Airports, and Intermodal Hubs | ||
| By Deployment Model | On-Premise | |
| Cloud-Hosted | ||
| Edge-Hosted and Hybrid | ||
| By Geography | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | Saudi Arabia | |
| United Arab Emirates | ||
| Turkey | ||
| South Africa | ||
| Rest of Middle East and Africa | ||


Key Questions Answered in the Report
What is the projected size of the integrated traffic system market by 2031?
The integrated traffic system market is forecast to reach USD 69.05 billion by 2031, expanding at a 9.30% CAGR from 2026.
Which solution category leads spending?
Traffic Monitoring and Detection Systems held 24.01% share in 2025, while Adaptive Traffic Control Systems are the fastest-growing solution category at a 10.84% CAGR.
Why are managed services gaining importance?
Services are forecast to grow at 11.47% CAGR as agencies outsource traffic operations and analytics instead of building all capabilities internally.
Which region has the largest share of integrated traffic systems?
North America held 39.21% share in 2025, supported by public grant programs, established procurement channels, and a mature vendor base.
Page last updated on:



