
India Wall Decor Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
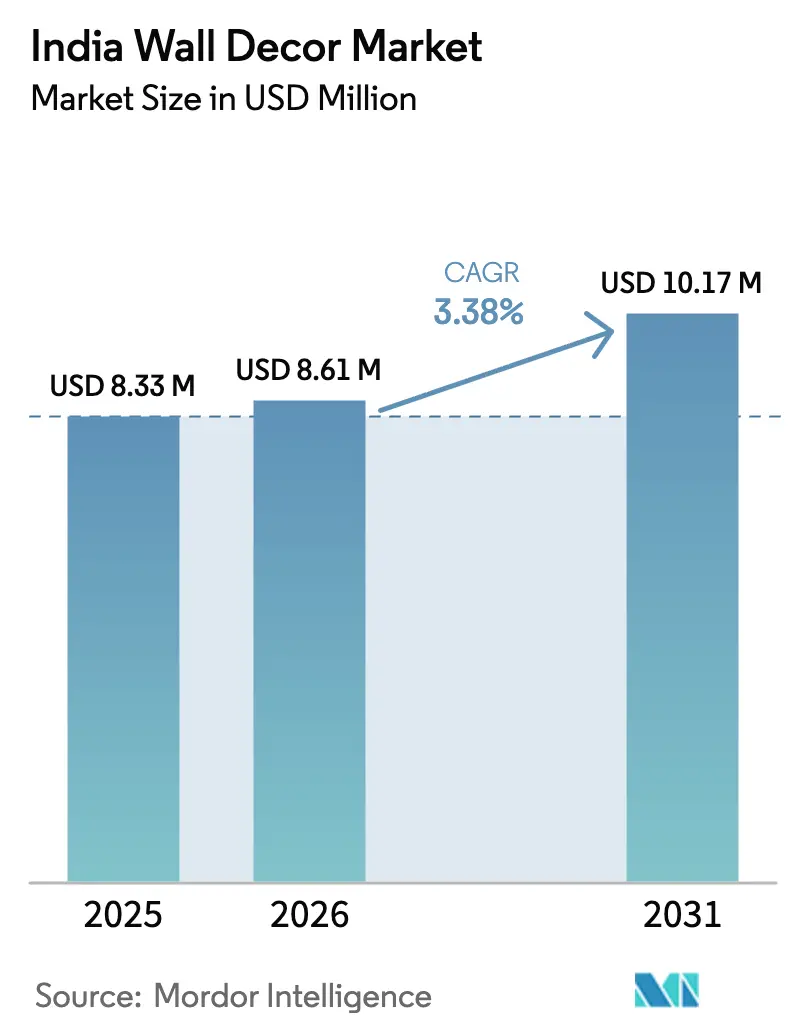
| Base Year Market Size (2025) | USD 8.33 Million |
| Market Size (2026) | USD 8.61 Million |
| Market Size (2031) | USD 10.17 Million |
| Growth Rate (2026 - 2031) | 3.38 % |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
India Wall Decor Market Analysis by 黑料不打烊
The India wall decor market size was valued at USD 8.33 billion in 2025 and estimated to grow from USD 8.61 billion in 2026 to reach USD 10.17 billion by 2031, at a CAGR of 3.38% during the forecast period (2026-2031). Accelerating urbanization, a persistent housing pipeline, and higher per-capita disposable income continue to pull first-time buyers into organized décor retail. Online platforms deepen category awareness by highlighting design inspirations while transparent pricing nudges consumers toward formal brands. Luxury housing sales, which climbed from 16% to 34% of national transactions between 2018 and 2024, lift premium demand in metropolitan clusters. Simultaneously, quick-commerce experiments shorten delivery windows, encouraging impulse décor purchases for mid-cycle renovations. Evolving sustainability norms and BIS quality mandates are steering manufacturers toward certified, low-VOC materials that broaden appeal among health-conscious homeowners.
Key Report Takeaways
- By product type, wallpaper led with 25.08% revenue share of the India wall decor market in 2025, while digitally printed wallpaper is projected to advance at a 18.51% CAGR through 2031.
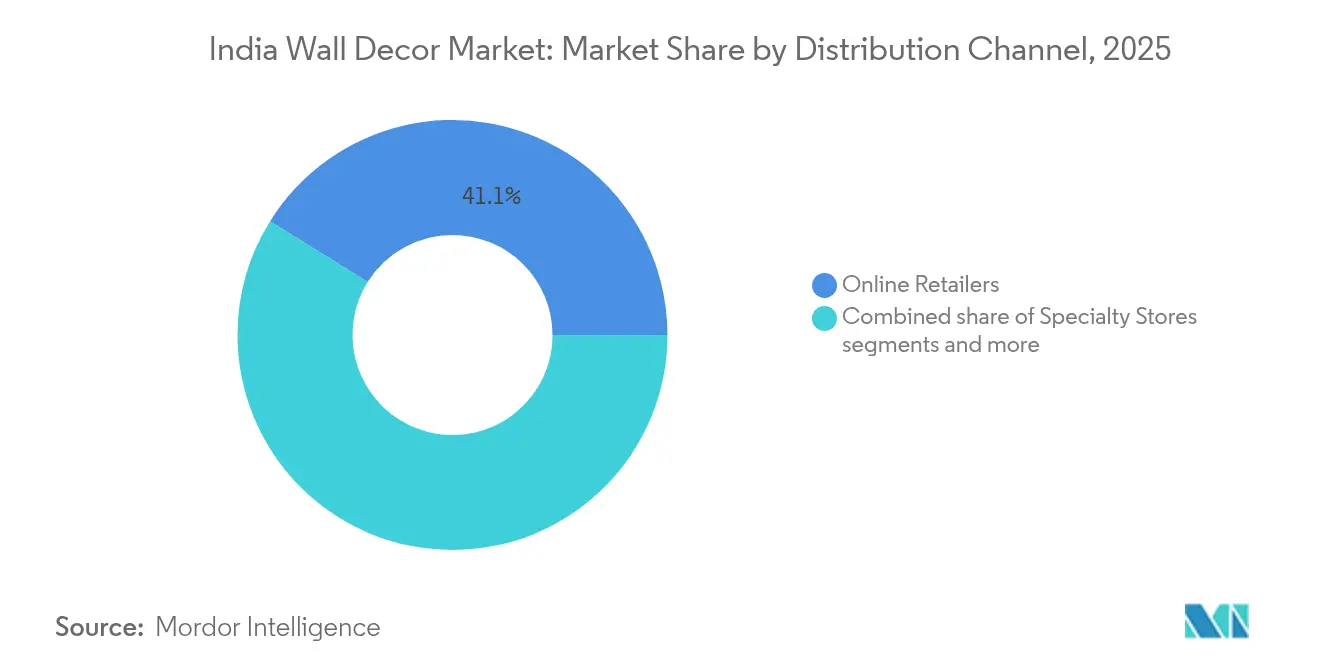
- By distribution channel, online retailers held 41.12% of the India wall decor market size in 2025, whereas specialty stores are forecast to post the fastest 22.40% CAGR to 2031.
- By end user, residential applications accounted for 68.15% of the India wall decor market size in 2025, and co-living spaces are poised for 15.10% CAGR growth through 2031.
- By geography, West India captured 22.54% of the India wall decor market size in 2025; North-East India is projected to register the highest 14.23% CAGR between 2026 and 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Wall Decor Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising disposable incomes & residential real-estate boom | +1.2% | West India, North India, with spillover to Central India | Medium term (2-4 years) |
| Explosive growth of e-commerce and omnichannel furniture retail | +0.8% | National, with early gains in Delhi-NCR, Mumbai, Bengaluru | Short term (≤ 2 years) |
| Shortening home-renovation cycles among urban millennials | +0.6% | Metro cities across all regions | Medium term (2-4 years) |
| Premiumisation and demand for custom/DIY wall décor | +0.4% | West India, South India premium segments | Long term (≥ 4 years) |
| Co-living & co-working footprints driving bulk decorative fit-outs | +0.3% | Tier-1 cities with institutional operator presence | Short term (≤ 2 years) |
| Handicraft-cluster incentives boosting artisanal wall décor supply | +0.2% | North India, Central India craft clusters | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||


Rising Disposable Incomes and Residential Real-Estate Boom
Escalating household earnings underpin the India wall decor market by enlarging budgets for aesthetic upgrades[1]Praxis Global Alliance, “What’s Shaping the Indian Home & Interiors Market,” praxisga.com. . Record housing launches rose 20% year-on-year in 2024, creating fresh blank canvases for décor spending. Luxury micro-markets such as Pune’s Baner corridor posted 15% annual price appreciation, signaling sustained appetite for premium wall solutions. Younger homebuyers prioritize design expression, replacing the older durability-only mindset. Developers increasingly bundle branded wallcoverings to differentiate projects and raise ticket sizes. Government incentives for affordable housing add depth at entry-level price points, broadening the addressable base. Renovation cycles now average 10–12 years, turning each new housing cohort into recurring customers sooner than before.
Explosive Growth of E-Commerce and Omnichannel Furniture Retail
Digital platforms expose consumers to thousands of SKUs, fuelling trial and repeat purchase within the India wall decor market[2]Aritra Ghosh, “India’s E-commerce Set to Hit USD 300 Billion by 2030,” Indian Retailer, indianretailer.com. . IKEA India secures over 30% of Delhi-NCR orders online, validating the click-first preference among time-pressed urbanites. Influencer-led social commerce drives discovery for niche D2C labels, widening choice beyond dominant national brands. Faster last-mile networks and warehouse automation cut delivery times for bulky panels and mirrors, reducing purchase hesitation. ONDC integration promises lower onboarding costs for artisans, enlarging regional supply diversity. Omnichannel retailers invest in AR visualization tools that let shoppers preview wallpapers at scale, increasing conversion. Traditional wholesalers adopt drop-ship models to remain competitive, blending age-old relationships with new digital efficiencies.
Shortening Home-Renovation Cycles Among Urban Millennials
Urban millennials have compressed renovation timelines from traditional 15-year cycles to 10-12 years, driven by lifestyle evolution and social media influence on interior aesthetics. This behavioural shift creates recurring demand patterns that benefit wall decor categories offering easy installation and style updates, particularly wallpapers and modular wall systems. The trend gains momentum through design-focused content consumption and peer influence via platforms highlighting interior transformations, where wall treatments serve as cost-effective room refreshes. Professional interior design services adoption, with companies like HomeLane and Design Café achieving combined revenues exceeding USD 120 million (INR 1,000 crore), institutionalizes renovation frequency through systematic design consultations and project management. Metro markets exhibit the strongest renovation velocity due to higher exposure to global design trends and disposable income availability. The acceleration particularly benefits digitally printed wallpaper segments, where customization capabilities and rapid production cycles align with millennial preferences for personalized, Instagram-worthy interiors.
Premiumization and DIY Wall Décor Demand
Consumer sophistication drives premiumization across wall decor categories, with design ranking as the top purchase criterion, superseding traditional durability considerations. Asian Paints' strategic expansion into custom wallcoverings, launching 50+ collections including designer collaborations like Sabyasachi, exemplifies how established players capture premium segments through product differentiation. DIY culture proliferation, supported by YouTube tutorials and social media inspiration, democratizes custom wall treatments while creating demand for user-friendly installation products and tools. Technology integration through 3D printing, laser cutting, and digital design tools enables mass customization at accessible price points, particularly benefiting D2C brands like WallMantra and Artociti. The premiumization trajectory aligns with sustainability consciousness, where eco-friendly materials command price premiums among environmentally aware consumers. West and South India lead premium adoption due to higher income concentrations and exposure to global design trends through expatriate communities and international business presence.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Volatile input prices for timber, metal, décor paper, and forex | -0.7% | Nationwide | Short term (≤ 2 years) |
| Proliferation of low-grade or counterfeit products | -0.5% | Tier-2/3 & rural markets | Medium term (2-4 years) |
| Tightening indoor-air-quality & low-VOC compliance for adhesives/inks | -0.6% | Urban & metro regions | Medium term (2-4 years) |
| Shortage of skilled installers & digital-printing technicians | -0.4% | Nationwide | Short term (≤ 2 years) |
| Source: 黑料不打烊 | |||
Volatile Input Prices for Timber, Metal, Décor Paper, and Forex
Commodity cycles drive unpredictable swings in raw-material costs, squeezing thin operating margins for wallpaper printers and frame makers. February 2025 BIS orders on MDF and plywood tightened import supply, raising lead times and holding costs for manufacturers reliant on Southeast Asian panels [3]Global Wood, “International Tropical Logs & Sawnwood Market Reports,” globalwood.org. . Currency fluctuations amplify landed-cost volatility for premium printed substrates sourced from Europe. Smaller firms lack hedging mechanisms, forcing ad-hoc price hikes that can erode brand loyalty. Construction inflation of 3-5% compounds installation budgets, delaying nonessential décor projects. Domestic forestry reforms could ease timber pressure, yet short-term uncertainty persists. Industry players prioritize backward integration and FSC-certified sourcing to tame supply risk.
Proliferation of Low-Grade or Counterfeit Products
The unorganized sector's dominance, representing approximately 75% of India's furniture industry, enables proliferation of low-quality replicas that erode brand equity and depress pricing across wall decor categories. Counterfeit products particularly impact premium segments, where design replication and substandard materials undermine consumer confidence in branded offerings. E-commerce marketplaces face ongoing challenges in policing counterfeit listings, with IKEA specifically warning consumers about unauthorized marketplace sellers and fake product listings. Quality inconsistencies in unorganized supply chains create consumer skepticism toward new entrants and artisanal products, requiring significant brand-building investments to establish credibility. The February 2026 BIS certification mandate for furniture products may partially address quality concerns through mandatory standards compliance, though enforcement challenges in tier-2 and tier-3 markets remain substantial.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Wallpaper Drives Digital Transformation
Wallpaper captured 25.08% of the India wall decor market share in 2025, reflecting its design versatility and speed of application. Digitally printed variants are on course for a staggering 18.51% CAGR through 2031 as mass customization aligns with shorter renovation cycles. The India wall decor market registers elevated search traffic for peel-and-stick murals, suggesting consumer appetite for hassle-free makeovers. Modular shelves maintain 21.74% revenue contribution, leveraging compact-home storage demand in urban apartments. Mirror works, holding an 17.62% share, benefit from space amplification trends in luxury housing corridors. Clocks and hangings occupy niche but enduring user segments, fulfilling functional and aesthetic niches. BIS-mandated quality norms are expected to consolidate share toward compliant wallpaper manufacturers, thereby stabilizing price bands over time.
Technology upgrades such as UV-gel printing enhance durability and color fidelity, allowing Indian producers to satisfy both domestic and export orders. Asian Paints leverages its 10.5% market led to introduce theme-based wallcovering collections that pair with paint palettes for coordinated room makeovers. D2C upstarts deploy AI-driven configurators, letting shoppers scale patterns to exact wall dimensions, shrinking the measurement-error margin. Import duties on Chinese décor paper redirect sourcing toward Korea and Germany, diversifying supply risks. Suppliers court architects through virtual sample libraries that expedite specification cycles for commercial fit-outs. Sustainability preferences push demand for PVC-free substrates, with European certifications acting as proof points in marketing communication. Decorative acoustics panels emerge as a high-margin adjacency, tapping the same installer ecosystem.


By Distribution Channel: Online Dominance Accelerates Specialty Revival
Online retailers controlled 41.12% of the India wall decor market size in 2025 thanks to deep assortments, price transparency, and rapid fulfilment. Yet specialty stores are projected to clock the fastest 22.40% CAGR through 2031 as experiential shopping regains footing post-pandemic. The India wall decor market now sees malls dedicating entire wings to interior décor, mirroring global lifestyle center formats. Hypermarkets retain a 17.5% slice by bundling budget-friendly art pieces with in-house installation services. Wholesale distributors continue supplying tier-2 storefronts that thrive on personal relationships and cash credit. Quick-commerce pilots deliver décor under 30 minutes during festival seasons, expanding impulse consumption.
Omnichannel leaders like IKEA blend online reach with showroom storytelling, blurring channel boundaries in the India wall decor market. Specialty boutiques differentiate through VR-aided mock-ups that visualize custom murals in actual room photos. E-retailers integrate live-chat design advice, mitigating the touch-and-feel deficit. ONDC lowers digital adoption barriers for craft clusters, funnelling indigenous products into nationwide demand pools. Tier-3 penetration rides on vernacular UI rollouts that demystify décor jargon. Return-friendly policies increase willingness to trial large wall panels online. Loyalty programs spanning web and store channels nurture repeat sales by rewarding cumulative décor spending.
By End User: Residential Stability Meets Commercial Innovation
Residential customers represented 68.15% of overall demand in 2025, underscoring the homocentric growth engine within the India wall decor market. Affluent homeowners allocate rising budgets toward statement walls, integrating smart lighting and textured panels for immersive ambiences. Co-living facilities headline commercial momentum with a projected 15.10% CAGR, banking on standardized décor packages that ensure quick turnovers. Grade-A office expansions in tier-2 IT hubs create new B2B avenues for acoustic wall treatments. Educational campuses adopt inspirational murals to reinforce institutional branding and student engagement. Hospitality refurbishments align with India’s tourism push, emphasizing locally sourced handicrafts to deliver authentic guest experiences.
Developers bundle turnkey décor to boost apartment sales velocity, choosing branded suppliers to guarantee post-handover service reliability. Rental-friendly offerings such as removable decals expand share among mobile workforces, reinforcing recurring revenue. Facilities managers prioritize easy-clean finishes that cut maintenance downtime, influencing product innovation roadmaps in the India wall decor market. Smart-home proliferation sparks interest in IoT-enabled art frames that rotate digital prints. Green-building certifications prompt use of low-VOC adhesives, repositioning eco-compliant suppliers as preferred partners. The corporate sector’s DEI commitments inspire inclusive wall graphics, opening bespoke design briefs for mural artists.
Geography Analysis
West India leads the India wall decor market with 22.54% value share in 2025, underwritten by luxury residential projects in Mumbai and Pune that consistently demand high-end wall finishes. Superior retail infrastructure, coupled with port proximity for imported materials, sustains a vibrant premium ecosystem. Micro-markets like Pune’s Nagar Road recorded 27% annual price appreciation, magnifying discretionary décor budgets. Developers curate sample apartments featuring designer wallpapers to entice buyers seeking turnkey aesthetics. Organized retailers deploy large-format stores in Navi Mumbai, leveraging high footfalls and affluent catchments. Suburban expansion toward Thane and Panvel adds steady mid-segment volumes, balancing the region’s price ladder. Industrial belt growth around Ahmedabad stimulates staff-housing colonies, further diversifying demand concentricity.
North-East India, though still nascent, is the fastest climber with a forecast 14.23% CAGR between 2026 and 2031, fueled by highway upgrades and rising spiritual tourism. Bamboo craftsmanship and textile weaving flourish under the SFURTI cluster backing, channelling authentic décor pieces into formal retail lanes. Hospitality development around Guwahati and Shillong introduces modern design sensibilities that co-exist with indigenous aesthetics, opening cross-category bundling. Improved air connectivity shortens supplier lead times, encouraging national chains to pilot compact décor outlets in state capitals. Local consumers, buoyed by sustained income growth, exhibit mounting interest in branded wallpapers. Government procurement for public spaces adopts ethnic motifs, offering volume contracts to local artisans. Furniture cooperatives experiment with e-commerce kiosks, feeding regional creations into the wider India wall decor market.
South India sustains 21.90% contribution, anchored by technology-driven income pools in Bengaluru, Hyderabad, and Chennai. IT corridors precipitate premium housing that routinely specs accent walls and glass-embedded artwork. Cultural affinity for handcrafted teak and silk translates into hybrid décor fusing traditional motifs with contemporary formats. Export-oriented manufacturing hubs in Tamil Nadu ship carved MDF panels overseas, drawing foreign design influences back into domestic assortments. Retail developers in Hyderabad install design studios adjoining furniture anchors, creating one-stop consumption clusters. Kerala’s NRI-fuelled homebuilding continues to favor ornate wooden ceilings and murals, adding regional texture to the India wall decor market. State policy support for cottage industries accelerates the formalization of supply chains, improving product consistency.
Regulatory Landscape
Wall decor materials and adjacent categories (frames, panels, and furniture-like wall storage) operate under India’s standards regime led by the Bureau of Indian Standards (BIS) under the BIS Act, 2016. A key inflection for organized players is the Furniture (Quality Control) framework, including the Furniture (Quality Control) Amendment Order, 2026 dated 13 February 2026 and the Furniture (Quality Control) Second Amendment Order, 2026 (S.O. 1125(E), 2 March 2026), which reinforces mandatory BIS certification for notified furniture products and tightens quality compliance across the broader home interiors ecosystem.
The 2026 amendments also add compliance provisions that affect sourcing and product development timelines, including a 180-day transitional relief window for certain pre-implementation imports, an R&D exemption allowing limited quantities (up to 200 units per financial year) without BIS certification for testing and development, and exemptions for export-oriented imports of components or sub-assemblies used exclusively for exports. For wall decor brands selling modular wall storage or integrated wall systems, these measures shape go-to-market planning, documentation, and supplier qualification. At the same time, the tightening standards raise the bar for unorganized and counterfeit supply that competes primarily on price without consistent quality controls.
Value Chain Analysis
The India wall decor value chain begins with raw materials (decor paper and substrates for wallpaper, inks and coatings for digital printing, wood-based panels such as MDF and plywood for frames and wall-mounted storage, glass and hardware for mirrors, and adhesives and installation consumables). Manufacturing covers both mass production and custom runs. Digitally printed wallpaper and made-to-measure murals depend on design files, color management, and short-batch printing, while frames, shelves, and mirror works rely more on panel processing, finishing, and assembly. Sourcing combines domestic production with imports for premium substrates and components, and quality and lead-time management becomes more structured as BIS-related compliance expectations extend further into furniture-adjacent wall decor.
Downstream, distribution increasingly mixes large e-commerce marketplaces and brand.com storefronts with specialty retail and experience centers that support visualization, sampling, and design assistance. Organized players are also compressing the chain by integrating services: Asian Paints, through its Beautiful Homes Service and related wallcoverings offerings, connects selection to execution by coordinating design, product supply, and installation through a managed service model. Large-format retailers such as IKEA India combine global sourcing with an expanding local sourcing footprint and omnichannel fulfillment, improving access to coordinated wall decor and home-furnishing bundles and enabling project-led sales alongside standard retail demand.
Competitive Landscape
The Indian wall décor market remains moderately fragmented, with the top five branded suppliers holding a notable share of total revenues, highlighting potential for consolidation. Asian Paints leads the segment by offering an integrated experience through its Beautiful Homes platform, combining paints, wallpapers, and décor services. IKEA India follows closely, tapping into global sourcing and local assembly to target the mass-premium audience. HomeLane’s acquisition of Design Café in September 2024, valued at USD 361 million (INR 3,000 crore), underscores the trend of vertically integrated players scaling through strategic takeovers. At the same time, D2C brands like WallMantra leverage social media reach and AI-driven configurators to bypass traditional intermediaries and disrupt legacy margins.
Incumbents are increasingly using R&D to build differentiation and brand equity. Asian Paints has filed 142 patents, focusing on innovations such as stain-resistant coatings designed to pair with wallcoverings. Sustainability is becoming a core selling point, driven by builders pursuing green certifications; Pidilite’s low-carbon tile adhesive line reflects this market shift. International players are also entering the fray, with Swedish wallpaper brand Bor?stapeter partnering with a Mumbai distributor in 2025. The upcoming BIS certification deadline in February 2026 may increase compliance costs for informal players, prompting consolidation and acquisition activity by more organized brands.
Capital and capability continue to reshape the competitive landscape. WoodenStreet is preparing for an IPO, following plans to quadruple revenue in three years, attracting private equity interest. Omnichannel strategies are now essential: IKEA’s Gurgaon fulfilment center enables next-day delivery to surrounding cities, while Asian Paints enhances customer experience with mobile AR-based color consultations. Brick-and-mortar stores are reinventing engagement through design masterclasses and influencer-led styling events. In response to counterfeit risks, brands are deploying QR-code verification tools to protect authenticity. Export councils are also stepping in, training artisans on EU deforestation norms to improve India's global standing in wooden décor exports.
India Wall Decor Industry Leaders
Asian Paints (Nilaya & Beautiful Homes service)
IKEA India
Pepperfry
Fabindia
Urban Ladder
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Customization-led wall decor is a practical whitespace, especially for digitally printed, made-to-measure wallpaper and murals that fit shorter renovation cycles and online discovery behavior. Wallpaper also remains the largest product category by revenue share in 2025, so brands that combine design tools (AR visualization, configurators, and curated collections) with reliable measurement, installation, and after-sales support can improve conversion and reduce returns. This is most visible in metros where premiumization and branded interiors services are becoming more mainstream.
A second opportunity sits at the intersection of organized retail expansion, local sourcing, and project/B2B channels. In January 2026, IKEA announced plans to more than double its investment in India to over INR 200 billion over the next five years, alongside a broader push that includes scaling stores and local sourcing. That footprint expansion increases the addressable surface for coordinated wall decor add-ons sold with furniture and room solutions. The developer-led push is also reflected in IKEA’s June 2026 collaboration with Nila Spaces on the VIDA project in Ahmedabad, where homes are planned and furnished through IKEA. This creates a repeatable path for wallpapers, frames, mirrors, and modular wall storage to enter homes through standardized fit-outs rather than only post-handover retail purchases. On the supply side, BIS-linked quality control momentum in furniture-adjacent products supports room for compliant, traceable materials and branded warranty-backed offerings, while the R&D exemptions in the 2026 amendments give manufacturers space to pilot new substrates and finishes without fully scaling certification at the earliest prototype stage.
Recent Industry Developments
- July 2026: Pepperfry plans to open 35 new stores across metropolitan, Tier-I and Tier-II cities by end of August 2026 to support omnichannel expansion. The retailer is expanding its physical footprint for the India wall decor category. It strengthens regional reach ahead of the festive season.
- July 2026: Asian Paints partnered with Zomato for a 15-day campaign integrating colour identifiers into the Zomato experience to promote the Rang Hi Asli Pata Hai initiative, linked to Asian Paints' Colour Warranty. The collaboration ties color warranty messaging to dining touchpoints and broadens consumer engagement. It also expands cross-brand visibility across online and offline channels.
- June 2026: IKEA India VIDA project in Ahmedabad enabling residential units to be planned and furnished by IKEA as part of its B2B growth strategy. The project expands product and service integration in new housing developments. It links with real estate developers and scales local sourcing and project-based deployments.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this methodology, the India wall decor market is the value of products bought to decorate walls in homes and commercial spaces, covering commonly sold decor items across offline and online channels in India.
Scope exclusions: We exclude services such as interior design fees, installation labor, and broader home furnishing items that are not primarily wall focused.
Segmentation Overview
- Segmentation by Product Type
- Shelves
- Wallpaper / Stickers
- Clocks
- Hangings
- Frameworks
- Mirror Works
- Segmentation by Distribution Channel
- Wholesalers / Distributors
- Hypermarkets / Supermarkets
- Specialty Stores
- Online Retailers
- Segmentation by End Users
- Residential
- Commercial
- Segmentation by Geography
- North India
- South India
- West India
- East India
- Central India
- North-East India
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts by building the demand context for home improvement and decor spending in India, and then it is narrowed down to wall related purchase patterns. We use public statistics and standards to keep definitions consistent, and then we map them to retail and manufacturing signals to avoid over counting.
Common references include sources such as the Ministry of Housing and Urban Affairs programs and housing updates, the National Sample Survey Office consumption surveys, RBI macro indicators for inflation and discretionary spending, Directorate General of Commercial Intelligence and Statistics trade data for related decor imports, and BIS standards that influence material choices and labeling. We also review company filings, investor presentations, and credible press coverage for category momentum and channel expansion, and selected paid subscriptions are used for company financials, patent checks, and shipment level import-export reads when public series are not detailed enough. This list is illustrative only, and many other sources were also reviewed for data collection, validation, and clarifications.
Primary Interviews and Surveys
Primary work is used to test what desk research cannot answer cleanly, such as how shoppers split spend across product types, and how price points move by city tier and channel. We speak with manufacturers, distributors, large format retailers, online sellers, and commercial buyers so assumptions around volumes, discounting, and mix can be corrected before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 25% | CXOs: 14% |
| Mid tier: 59% | Functional/Unit leaders: 41% |
| Smaller Players: 16% | Managers: 45% |
Market-Sizing & Forecasting
Sizing is built using a top-down approach where housing additions, renovation cadence, and decor purchase frequency are translated into an addressable spending pool, and then allocated into wall decor using category mix learned from channel checks. To keep the total realistic, selective bottom-up approximations are also run, such as sampled retailer sales productivity checks and ASP multiplied by indicative unit volumes for key product groups.
Inputs that matter in this market include urban housing pipeline and household formation, online share of decor purchases, average ticket size by product type, discount intensity during major sale periods, and commercial fit-out activity for offices and hospitality. When a variable is not available as a clean public series, gaps are handled using anchored ranges from expert interviews, followed by sensitivity checks so no single assumption dominates the output.
Forecasting is done using scenario analysis supported by light multivariate regression, where the forward path is tied to income growth signals, housing and renovation momentum, and channel expansion assumptions validated by market participants. If a short-term shock changes pricing or discretionary spending, the year-by-year path is rebalanced rather than forcing a smooth curve.
Data Validation & Update Cycle
Model outputs are cross-checked against independent signals, including relative movement in home improvement spend, import trends for related decor inputs, and channel-side feedback on sell-through. Outliers are reviewed, assumptions are revisited, and the logic is re-run before sign-off so that variance drivers are understood and documented.
Reports are refreshed annually, and interim updates are made when a material event shifts demand, supply, or pricing. Before delivery, a final review pass is completed so clients receive the latest updated view based on the newest public releases and fresh re-contacts where needed.
黑料不打烊's India Wall Decor Market Size Versus Other Published Estimates
Published estimates for India wall decor do not always match because each publisher may draw the line differently on what counts as wall decor, which years they use, and how they convert and normalize pricing. Differences also show up when some models lean more on long-range projections, while others stay closer to near-term retail and housing signals.
Key gaps usually come from whether adjacent wall covering and wall panel categories are folded in, how online discounting is treated in realized pricing, and whether the time basis is FY versus calendar year, which changes the currency and inflation timing. The spread is also influenced by refresh cadence, since assumptions on category mix and channel shares can shift within a year, and those updates are handled differently across publishers, a modeling choice applied by 黑料不打烊.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 8.33 B (2025) | |
| Industry Publisher A | USD 5.80 B (2026) | Uses a longer forecast window and a broader product list that can change the mix, and it anchors on a different base year which makes near-term values look lower versus a 2025 base. |
| Industry Publisher B | USD 13.02 B (2035) | Carries the projection further out with a higher growth case and includes modern wall solutions like 3D panels and LED integrated installations more explicitly, which expands the counted spend. |
Taken together, the table shows that year choice and category inclusion are the two biggest reasons for the gap, followed by how pricing and channel mix are updated over time. By keeping assumptions tied to observable housing and retail indicators, and then checking them with market participants, the final number stays traceable and repeatable even when only limited public data is available.


Key Questions Answered in the Report
What is the current value of the India wall decor market?
The India wall decor market size is USD 8.61 billion in 2026.
How fast is the sector expected to grow?
Market value is forecast to reach USD 10.17 billion by 2031, reflecting a 3.38% CAGR.
Which product category leads sales?
Wallpaper is the largest category, accounting for 25.08% share in 2025.
Which channel is expanding the quickest?
Specialty stores are projected to post the fastest 22.40% CAGR through 2031.
Which region shows the highest growth potential?
North-East India is expected to register the highest 14.23% CAGR over 2026-2031.
Who holds the largest individual market share?
Asian Paints leads with an estimated 10.5% share of organized sector revenues.
Page last updated on:



