
India Data Center Cooling Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.38 Billion |
| Market Size (2026) | USD 2.99 Billion |
| Market Size (2031) | USD 9.28 Billion |
| Growth Rate (2026 - 2031) | 25.47 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
India Data Center Cooling Market Analysis by 黑料不打烊
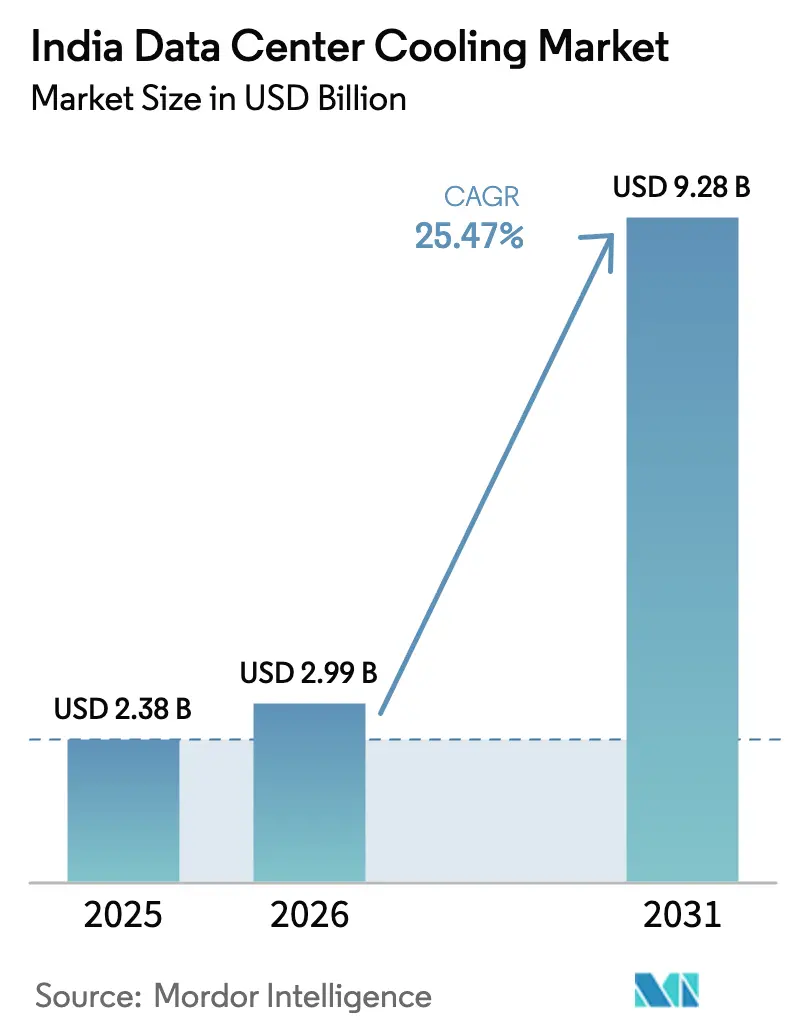
India data center cooling market size in 2026 is estimated at USD 2.99 billion, growing from 2025 value of USD 2.38 billion with 2031 projections showing USD 9.28 billion, growing at 25.47% CAGR over 2026-2031. Sustained hyperscale cloud build-outs, data-sovereignty mandates, and large-scale government digital programs are the primary growth catalysts for the India data center cooling market. Cooling demand is intensifying as rack densities cross the 15 kW threshold, prompting rapid evaluation of liquid-based solutions alongside incremental upgrades to traditional air-cooling assets. Policy-led incentives that streamline land acquisition and renewable power sourcing strengthen project economics, while escalating carbon-pricing deadlines reinforce the business case for high-efficiency systems. Vendors that combine hardware, software, and lifecycle services are gaining traction because operators seek predictable performance, reduced downtime risk, and measurable energy savings across multi-site portfolios.
Key Report Takeaways
- By data center type, hyperscalers led with 42.18% of India data center cooling market share in 2025 and are expanding at a 25.78% CAGR to 2031.
- By tier classification, Tier 3 facilities commanded 62.85% share of the India data center cooling market size in 2025, while Tier 4 facilities are projected to grow at 26.88% CAGR through 2031.
- By cooling technology, air-based solutions held 66.35% revenue share in 2025; liquid solutions represent the fastest growth at 27.34% CAGR.
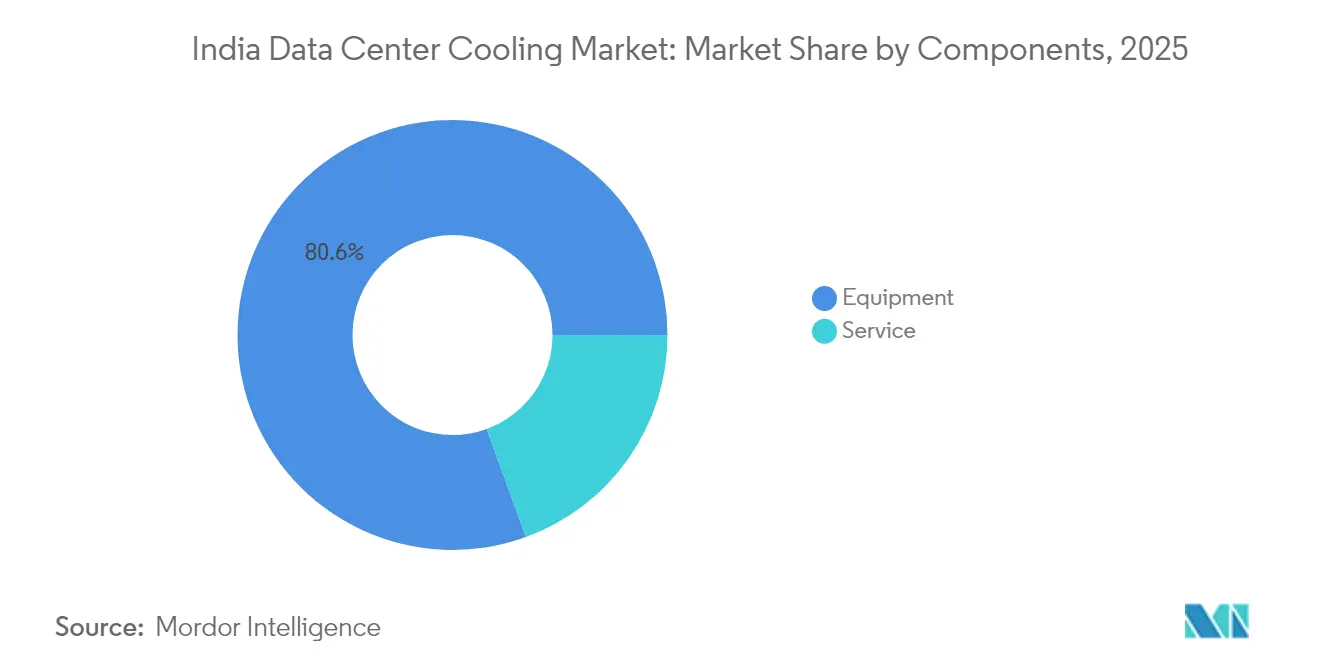
- By component, equipment accounted for 80.55% share of the India data center cooling market size in 2025, and services are advancing at 26.12% CAGR.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
India Data Center Cooling Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Hyperscale cloud build-outs accelerating capacity additions | +6.8% | Mumbai, Chennai, Hyderabad | Medium term (2-4 years) |
| Government-backed digital initiatives expanding data generation | +5.2% | National metro clusters | Long term (≥ 4 years) |
| Rising rack power densities heightening cooling intensity requirements | +4.1% | Tier 1 cities, fringe Tier 2 markets | Short term (≤ 2 years) |
| Edge data-center roll-outs in Tier 2/3 cities creating niche demand | +3.4% | Pune, Ahmedabad, Kochi | Medium term (2-4 years) |
| Carbon-pricing deadlines pushing liquid-cooling adoption | +2.8% | Corporate hubs | Medium term (2-4 years) |
| Rapid decline in renewable power LCOE enabling retrofits | +2.1% | Solar-rich states | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Hyperscale cloud build-outs accelerating capacity additions
Hyperscale operators continue to redefine the India data center cooling market through multibillion-dollar capacity expansions that require advanced thermal management. Sify Technologies’ USD 5 billion AI campus exemplifies the shift toward GPU-dense facilities that mandate liquid cooling for racks beyond 20 kW. [1]Data Center Dynamics, “Sify Technologies Commits USD 5 Billion to AI Campus,” datacenterdynamics.com Vertiv recorded a 60% jump in organic orders in Q1 2024 as hyperscale clients accelerated procurement of high-density cooling platforms. Long-term offtake contracts with these operators enable vendors to allocate larger R&D budgets to immersion and direct-to-chip systems, establishing Mumbai, Chennai, and Hyderabad as concentrated innovation hubs.
Government-backed digital initiatives expanding data generation
Nationwide programs such as Digital India and the Digital Personal Data Protection Act are scaling data creation and promoting onshore storage, thereby extending the addressable base for the India data center cooling market. Mandates tied to Aadhaar integrations push both public and private entities to maintain domestic infrastructure, stimulating demand for dependable cooling systems in metro and edge environments.
Rising rack power densities heightening cooling intensity requirements
AI and high-performance computing workloads are now driving average rack densities beyond 15 kW; certain GPU clusters surpass 40 kW, outstripping the efficiency envelope of conventional air arrangements. PhonePe’s collaboration with Dell Technologies achieved 26% power savings using alternative cooling architectures, reinforcing the operational payoff of liquid solutions.[2]Dell Technologies, “Driving Efficiency in PhonePe’s Data Center,” dell.com Facility layout, power distribution, and control software are therefore being redesigned to handle higher thermal footprints, accelerating the technology transition within the India data center cooling market.
Edge data-center roll-outs in Tier-2/3 cities creating niche cooling demand
Latency-sensitive content delivery and industrial IoT deployments are stimulating edge data center builds across tier-2 and tier-3 cities. Pi Datacenters anticipates that capacity outside primary metros will triple in five years, underscoring a fresh revenue pool for modular cooling vendors. Elevated ambient temperatures and intermittent utilities necessitate autonomous, ruggedized solutions, creating headroom for regional integrators that can furnish responsive after-sales support.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Large upfront capex for advanced liquid cooling systems | -3.2% | National, SME operators | Short term (≤ 2 years) |
| Elevated power tariffs and intermittent grid reliability | -2.8% | Northern states, industrial zones | Medium term (2-4 years) |
| Shallow domestic supply chain for specialized components | -2.1% | National, acute in Tier 2/3 | Long term (≥ 4 years) |
| Water-use restrictions in drought-prone states | -1.6% | Maharashtra, Karnataka, Tamil Nadu | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Large upfront capex for advanced liquid cooling systems
Capex premiums of 40-60% over air-cooled deployments deter rapid adoption among smaller operators. Custom engineering, specialized pumps, and skilled labor extend deployment cycles, elongating payback beyond 3-4 years.[3]Verne Global, “Liquid Cooling TCO Analysis,” verneglobal.comWhile OPEX savings are material, financing hurdles persist unless project sponsors can lock in long-term workloads or secure incentive backing.
Elevated power tariffs and intermittent grid reliability increasing OPEX volatility
Electricity constitutes as much as 70% of data-center OPEX, with cooling systems responsible for up to 40% of that usage. Regions with higher tariffs force operators to weigh location versus redundancy investments. Pending guidelines to standardize thermal set points could further restrict cooling flexibility, prompting larger operators to integrate renewable energy and intelligent controls to mitigate tariff shocks.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Data Center Type: Hyperscalers drive cooling innovation
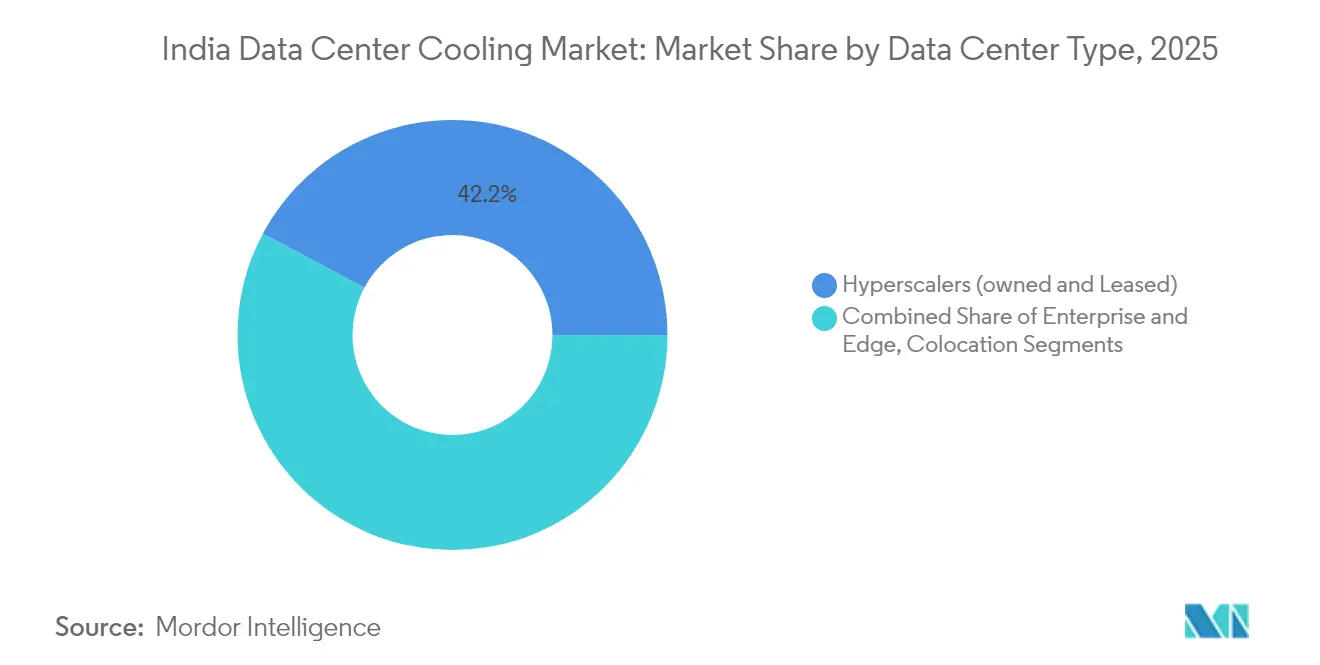
Hyperscale facilities captured 42.18% India data center cooling market share in 2025 and are projected to record a 25.78% CAGR through 2031. Extensive AI training clusters and stringent data-localization clauses compel hyperscalers to specify liquid-ready architectures capable of 40+ kW racks. Microsoft, Google, and Amazon Web Services are standardizing direct-to-chip cooling to improve power usage effectiveness, shaping vendor roadmaps. The enterprise and edge cohort remains substantial but fragmented, often starting with incremental CRAH upgrades before considering immersion solutions. Colocation providers balance legacy and next-generation workloads, deploying hybrid cooling to serve a diverse tenant base. As a result, integrated service suites that cover design, deployment, and predictive maintenance are becoming a default requirement across operator classes.
Hyperscale procurement volumes are reshaping supplier dynamics. Vertiv’s USD 2,036 million Q1 2025 net sales highlight demand concentration among large cloud clients. Enterprise operators are evaluating densification projects to consolidate smaller server rooms into purpose-built cores that leverage higher-efficiency chillers. Colocation players, keen to differentiate, advertise rack-ready liquid cooling pods aimed at GPU tenants while retaining air-cooled halls for conventional IT stacks. The resultant mixed-technology footprint amplifies the role of software-defined thermal management that orchestrates varied equipment profiles within a single site, reinforcing lifecycle revenue for OEMs and integrators.


By Tier Type: Tier 4 facilities lead growth despite Tier 3 dominance
Tier 3 sites accounted for 62.85% India data center cooling market size in 2025, favored for cost-reliability balance. Tier 4 builds, though fewer, are expanding fastest at 26.88% CAGR, driven by sectors where downtime penalties exceed incremental capex. Financial services, healthcare, and sovereign clouds prioritize N+1 or 2N redundancy across chillers, distribution pumps, and heat rejection stacks. Yotta Infrastructure’s NM1 facility illustrates engineered resiliency with dual independent cooling loops available for live maintenance. Tier 1 and Tier 2 installations focus on edge aggregation and price-sensitive content caching where partial redundancy suffices.
Growth in Tier 4 adoption is encouraging multi-vendor redundancy schemes, heightening integration complexity and favoring suppliers with open-protocol control platforms. Meanwhile, Tier 3 operators are retrofitting adiabatic units and free-cooling coils to contain PUE targets within regulatory thresholds. Government purchasing guidelines are increasingly referencing Uptime Institute standards, indirectly steering adoption of higher-tier designs and by extension more robust cooling investments. As the uptime imperative intensifies, lifecycle service contracts that guarantee performance are gaining prominence, especially among Tier 4 facilities where SLA breaches carry steep penalties.
By Cooling Technology: Liquid solutions gain momentum
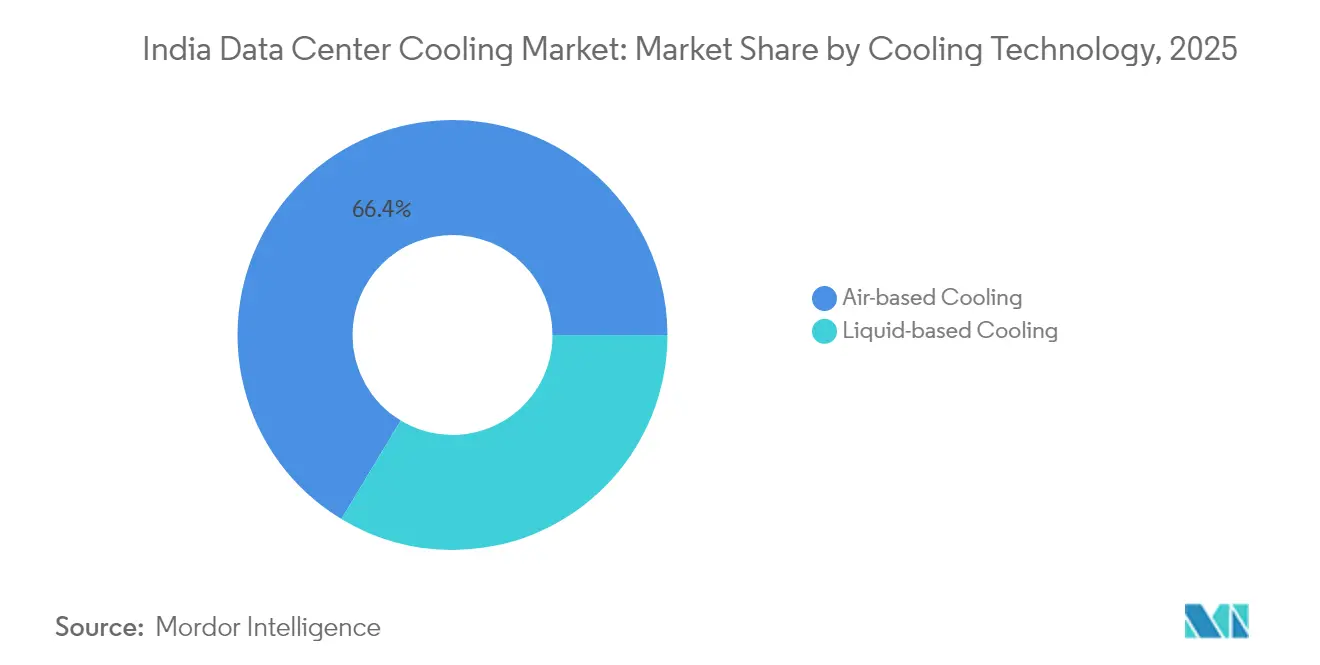
Air-based solutions retained 66.35% revenue share in 2025, including chillers, CRAH units, and cooling towers adapted for India’s climatic variance. Liquid methods—immersion, direct-to-chip, and rear-door heat exchangers—are, however, growing at 27.34% CAGR, forming the fastest-rising share within the India data center cooling market. Submer’s USD 55.5 million fundraising underscores investor conviction in immersion technology for GPU-centric loads. Vertiv’s CoolPhase Flex platform blends air and liquid pathways, letting operators migrate incrementally while protecting legacy assets.
Liquid technology uptake is closely tied to rack density. At 15-20 kW, rear-door heat exchangers present a transitional path with minimal floorplan disruption. Once racks exceed 30 kW, direct-to-chip loops outclass air systems on energy and space metrics. Immersion pools see adoption where white-space availability is tight and water restrictions curb evaporative towers. Policy debate around refrigerant GWP is another lever steering adoption toward sealed liquid loops that minimize refrigerant charge volumes.
By Component: Services emerge as growth driver
Equipment continued to dominate with 80.55% share in 2025, yet services represent the strongest growth vector at 26.12% CAGR. Consulting, installation, and predictive maintenance are indispensable as operators face multiple cooling technologies within a single campus. Johnson Controls’ creation of a Global Data Center Solutions division indicates a strategic shift to service-centric revenue that complements hardware pull-through. Nxtra by Airtel’s deployment of an AI-driven SmartSense platform demonstrates operators’ willingness to pay for analytics that shave energy consumption and pre-empt faults.
Lifecycle service bundles now include capacity planning, CFD modeling, regulatory compliance support, and on-site training, all billed under long-term contracts. Integrators that can deliver turnkey packages—combining chillers, CDUs, software, and field support—are distancing themselves from equipment-only competitors. As liquid cooling spreads, specialist maintenance skills command premium margins, reinforcing services’ share of wallet in the India data center cooling market.
Geography Analysis
Supply constraints and rising real estate premiums are pushing new builds toward Navi Mumbai, where zoning permits large footprints. Despite these challenges, Mumbai remains the preferred launchpad for international cloud entrants, sustaining outsized demand for high-density cooling modules. Chennai stands out as the fastest-growing metro due to port proximity and cost advantages, with Equinix investing USD 65 million for a 4,950-cabinet campus powered entirely by renewable energy. This pipeline positions Chennai as a showcase for sustainable liquid-ready facilities in humid coastal climates.
Delhi-NCR and Bengaluru form secondary hubs with steady enterprise and hyperscale activity, albeit tempered by power-distribution bottlenecks that add lead-time risk to cooling deployments. Government parks in Noida and Greater Noida are incentivizing greenfield builds with subsidized power tariffs, spurring interest in hybrid cooling approaches that balance upfront cost with energy resilience. Hyderabad registers the fastest MW-scale expansion, rising from 44 MW to 128 MW, supported by state incentives and availability of large parcels that permit modular campus layouts
Regulatory Landscape
India data center cooling deployments are increasingly shaped by a mix of national standard-setting and state-level investment policies rather than a single binding national data center policy. The Bureau of Indian Standards (BIS) notified Indias first-ever voluntary standards for cloud computing and data centres on February 25, 2026 under the BIS Rules, 2018, including a methodology to calculate a Cooling Efficiency Ratio (CER) that anchors procurement and performance benchmarking for thermal management systems. Alongside this, data centers above 5 MW received infrastructure status in 2022, which supports financing and approvals for higher-capex cooling upgrades in large campuses.
Compliance and governance mandates are also tightening operational requirements for operators and their cooling estates. The Digital Personal Data Protection Rules notified on November 13, 2025 provide an 18-month compliance runway ending May 13, 2027, reinforcing onshore processing and storage requirements that sustain domestic build-outs and associated cooling demand. In parallel, with no single national data center policy in force, around 15 states continue to use their own IT/industrial policies and incentive frameworks to attract facilities, which can affect location choices and, in turn, technology decisions linked to power sourcing, water constraints, and efficiency reporting.
Competitive Landscape
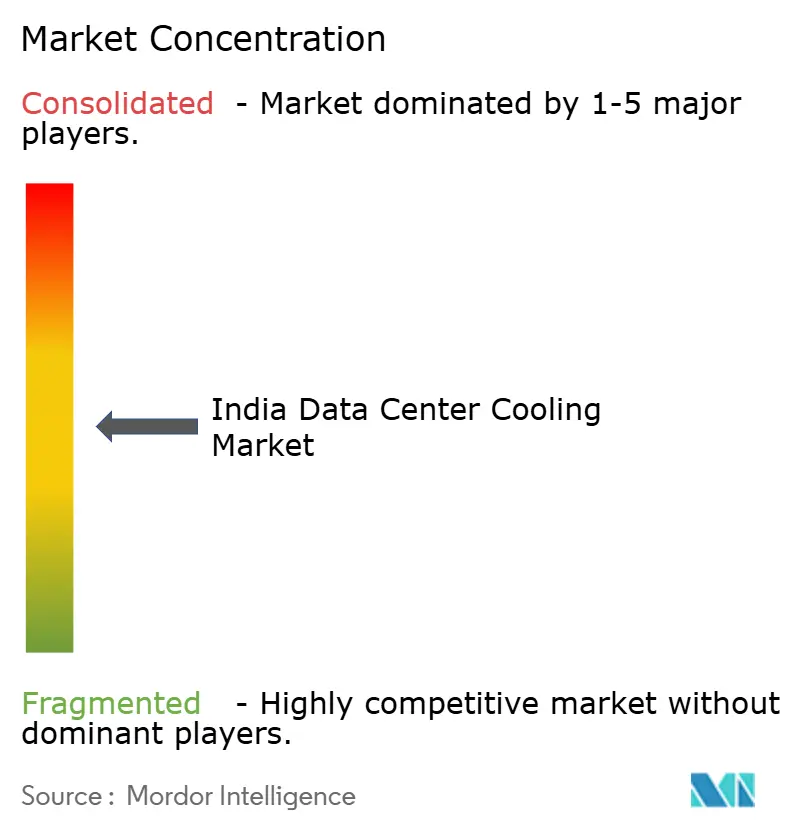
The India data center cooling market is moderately fragmented, with no vendor holding a dominant share. Global OEMs—Vertiv, Schneider Electric, and Johnson Controls—extend broad product lines and established global supply chains, securing the bulk of hyperscale contracts. Regional brands such as Blue Star and Kirloskar Chillers offer cost-competitive units tailored to local climatic conditions, serving mid-market colocation and enterprise segments. Recent strategic moves highlight the pivot toward integrated solutions. Schneider Electric acquired Motivair to reinforce its liquid cooling depth, while Vertiv bought centrifugal chiller IP from BiXin Energy to upgrade its high-performance compute portfolio
Partnership strategies are emerging as vendors align with renewable developers to offer bundled cooling-plus-power propositions that meet carbon intensity targets. Service specialization is another theme: Johnson Controls formed a Global Data Center Solutions unit to deliver design-build-operate packages inclusive of predictive analytics. Disruptive entrants like Submer focus solely on immersion technology, pushing incumbents to accelerate R&D. White-space opportunities persist in Tier-2/3 edge deployments where local system integrators can differentiate through rapid response times and region-specific support.
India Data Center Cooling Industry Leaders
Vertiv Co.
Stulz GmbH
Schneider Electric SE
Rittal GmbH & Co. KG
Alfa Laval AB
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
The main near-term opportunity is the build-out of AI-ready, high-density halls that push beyond conventional air-cooling envelopes, creating room for direct-to-chip and rear-door heat exchangers, plus supporting infrastructure such as coolant distribution units and dry coolers. This shift is reinforced by supplier actions in India: Schneider Electric (Motivair) established a liquid cooling solutions factory in Bengaluru in February 2026, and Vertiv partnered with Netweb Technologies in February 2026 to deliver liquid-cooled rack solutions for AI data centers. Together, these steps improve local access to liquid-cooling hardware and enable rack-scale integration.
A second opportunity zone sits in public-sector and regulated-workload demand that anchors capacity additions outside purely discretionary enterprise spend. Government sovereign compute requirements under the GI Cloud (Meghraj) program provide a stable base of domestic hosting, while the BIS notification of voluntary standards in February 2026 (including cooling efficiency measurement via CER) creates a more comparable framework for operators to specify and verify energy-performance outcomes. Emerging data center locations such as Telangana, Kolkata, and Ahmedabad also support modular, ruggedized cooling packages designed for varied grid conditions and ambient climates, especially where operators prioritize faster deployment and serviceability over bespoke central-plant builds.
Recent Industry Developments
- February 2026: Schneider Electric (Motivair) launched Motivair liquid cooling solutions factory in Bengaluru, first production site for Motivair technology in India. The move creates a local manufacturing footprint for Motivair in India and broadens access to high-density cooling for AI data centers. It also supports domestic capacity to meet demand for efficient cooling in hyperscale facilities and indicates a deeper commitment to localizing critical infrastructure components.
- February 2026: Vertiv and Netweb Technologies to deliver advanced liquid-cooled rack solutions for AI data centers in India. The collaboration delivers advanced liquid-cooled rack solutions for AI data centers in India. The partnership accelerates deployment of liquid cooling in hyperscale Indian facilities to support AI workloads, improving performance, reliability, and energy efficiency across large-scale deployments.
- November 2025: Vertiv MOU with IIT Bombay to develop cooling solutions for AI-driven data centers. The MOU aims to advance cooling solutions R&D in AI data centers. It strengthens local R&D capability and partnerships to meet growing data center cooling demand in India, and positions Vertiv to engage early with academic insights and talent pipelines.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this study, the India data center cooling market covers spending on equipment and systems used to remove heat and maintain thermal conditions inside data centers located in India, reported in value terms for the defined period.
Scope exclusions: We exclude general building HVAC used mainly for offices or non-data-center spaces, and any cooling assets installed outside India even if procured by India headquartered operators.
Segmentation Overview
- By Data Center Type
- Hyperscalers (owned and Leased)
- Enterprise and Edge
- Colocation
- By Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Cooling Technology
- Air-based Cooling
- Chiller and Economizer (DX Systems)
- CRAH
- Cooling Tower (covers direct, indirect and two-stage cooling)
- Others
- Liquid-based Cooling
- Immersion Cooling
- Direct-to-Chip Cooling
- Rear-Door Heat Exchanger
- Air-based Cooling
- By Component
- By Service
- Consulting and Training
- Installation and Deployment
- Maintenance and Support
- By Equipment
- By Service
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts by building a fact base on India data center build activity and the mechanical infrastructure demand that follows from it. We refer to public sources such as the Ministry of Power and Bureau of Energy Efficiency for efficiency context, India Meteorological Department for temperature and humidity patterns, and India customs trade statistics to sense-check import dependence for relevant cooling equipment categories.
To connect demand with addressable spending, we also review sources such as Central Electricity Authority power data, published guidelines and releases linked to Digital India and state IT policies, and peer reviewed studies discussing PUE and cooling performance in hot climates. Alongside these, company annual reports, investor presentations, and reputable press coverage are used to validate expansion timelines. In parallel, select paid subscriptions for company financials, patent tracking, and shipment-level trade checks help close obvious information gaps. These examples are indicative only, and many other sources were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary interviews and surveys are used to confirm what cooling is actually being specified, how projects are procured, and how pricing changes as rack density and redundancy expectations rise. We cover a mix of operators, engineering and facility consultants, and component suppliers across major Indian data center hubs, so desk research can be adjusted where field reality differs.
Feedback from respondents is then used to validate the split between chilled water and direct expansion setups, early liquid cooling adoption for higher density racks, and typical replacement or upgrade cycles. These inputs are used to triangulate the totals before forecasting.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 27% | CXOs: 22% |
| Mid tier: 51% | Functional/Unit leaders: 22% |
| Smaller Players: 22% | Managers: 56% |
Market-Sizing & Forecasting
The sizing model uses top-down and bottom-up approaches together. The main build comes from a top-down demand pool that links India data center capacity additions to cooling system intensity. In practice, expected capacity build and retrofit activity are translated into cooling needs, which are then converted into market value using spend-per-capacity style factors that reflect India operating conditions.
Key inputs include installed and planned data center capacity (MW), typical rack density bands and their cooling implications, target PUE levels and redundancy expectations, climate conditions that affect economizer use, and the share of projects using chilled water versus direct expansion and early liquid cooling. When public numbers are incomplete, gaps are handled using ranges from interviews and then set to conservative mid-points. This is followed by selective bottom-up approximations such as sampled project BoQ logic and ASP x volume checks by component.
For forecasting, scenario analysis is used and then cross-checked with a light multivariate view where capacity build-out, efficiency upgrades, and higher density compute are treated as the leading drivers. The final trajectory is aligned to respondent views on realistic commissioning timelines, not only announced pipeline dates.
Data Validation & Update Cycle
Model outputs are checked against independent signals such as capacity announcements, mechanical capex shares, and observed moves toward higher efficiency designs, and then larger variances are investigated. When a number looks unusual, inputs are revisited, unit assumptions are re-checked, and selected respondents are re-contacted to confirm what changed.
Before sign-off, the work goes through multi-step analyst reviews so the calculations and scope treatment stay consistent across the time series. Reports are refreshed annually, with interim updates when material events shift demand or pricing, followed by a final pre-delivery refresh pass so clients receive the latest view.
黑料不打烊's India Data Center Cooling Market Size Compared With Other Published Estimates
Published estimates for India data center cooling can vary because the market boundary is not applied the same way, and small scope differences add up quickly as capacity is built out. The spread also reflects different base years, currency timing, and whether projections assume faster uptake of liquid cooling as rack densities rise.
The table shows a clear gap across sources. Under 黑料不打烊's scope, the market is anchored to a 2025 base year value of USD 2.38 B, with the growth run-rate stated for 2026-2031. This reduces year-mixing between early build cycles and later retrofit-heavy spending.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 2.38 B (2025) | |
| Trade Journal A | USD 2.10 B (2024) | Uses a different base year and may reflect announced project pipelines before commissioning, which can undercount retrofits while also pulling forward new-build demand into the same year. |
| Business Publication B | USD 1.80 B (2023) | Presented as an industry valuation with a broad growth rate, and it is not clear if controls, installation, and service content are included consistently, which can shift totals in early years. |
Across the three numbers, most variance is explained by timing, what is counted inside cooling spend, and how upgrades are handled versus greenfield builds. By tying the model to capacity adds, efficiency targets, and interview-validated pricing bands, the final estimate stays traceable to a repeatable set of steps and practical checks.


Key Questions Answered in the Report
What is the current size of the India data center cooling market?
The market is valued at USD 2.99 billion in 2026 and is projected to reach USD 9.28 billion by 2031.
Which data center type generates the largest cooling demand?
Hyperscale facilities account for 42.18% of cooling spend in 2025 and will continue to lead growth at 25.78% CAGR through 2031.
Why is liquid cooling gaining popularity in India?
AI and high-performance computing workloads push rack densities beyond 15 kW, making liquid solutions more energy-efficient than traditional air systems.
Which Indian metro is the fastest growing data center hub?
Chennai shows the highest capacity growth trajectory due to lower costs, strong policy support, and strategic cable connectivity.
Page last updated on:
- Data Center Construction Market Construction across the global market, covering tier, facility size and facility type.
- Data Center Server Market Global servers demand, split by tier, facility size and facility type.
- Data Center Immersion Cooling Market Immersion cooling across the global market, covering type, cooling fluid and application.
- India Artificial Intelligence (AI) Optimised Data Center Market AI facilities demand across India, covering facility type, component and tier.
- United States Data Center Construction Market The US construction, split by tier, facility size and facility type.


