
Germany Data Center Storage Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
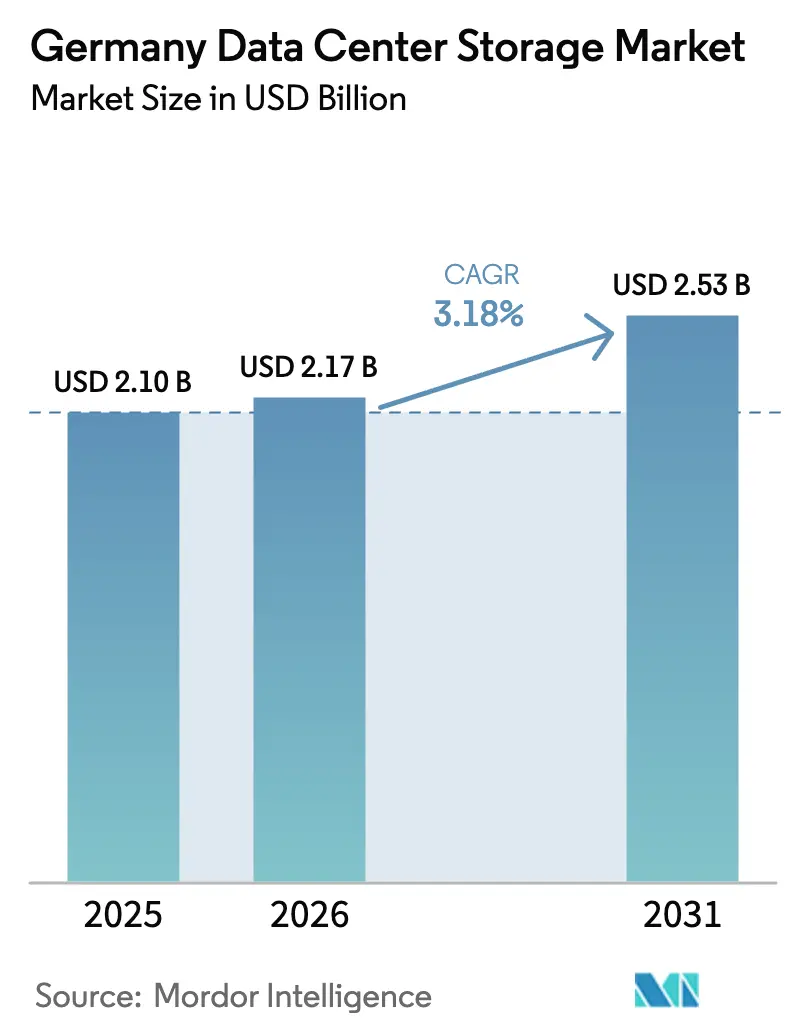
| Base Year Market Size (2025) | USD 2.10 Billion |
| Market Size (2026) | USD 2.17 Billion |
| Market Size (2031) | USD 2.53 Billion |
| Growth Rate (2026 - 2031) | 3.18 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Germany Data Center Storage Market Analysis by 黑料不打烊
Germany data center storage market size in 2026 is estimated at USD 2.17 billion, growing from 2025 value of USD 2.10 billion with 2031 projections showing USD 2.53 billion, growing at 3.18% CAGR over 2026-2031. This steady trajectory reflects a maturing environment in which infrastructure consolidation, energy-efficient operations and regulated data residency take priority over rapid capacity build-outs. Hybrid cloud strategies that let enterprises stage workloads across on-premises, colocation, and sovereign cloud nodes continue to underpin demand for storage technologies that guarantee low latency, encryption at rest, and transparent audit trails. Edge build-outs tied to Industry 4.0, NVMe acceleration for AI inference and the growing use of liquid cooling are reinforcing interest in modular, software-defined platforms that reduce power draw per terabyte. Meanwhile, electricity-price volatility caused by the Energiewende is prompting operators to favor flash arrays and intelligent tiering engines that can spin down idle capacity and shift I/O when spot prices spike, extending hardware life cycles while curbing operating expenses.
Key Report Takeaways
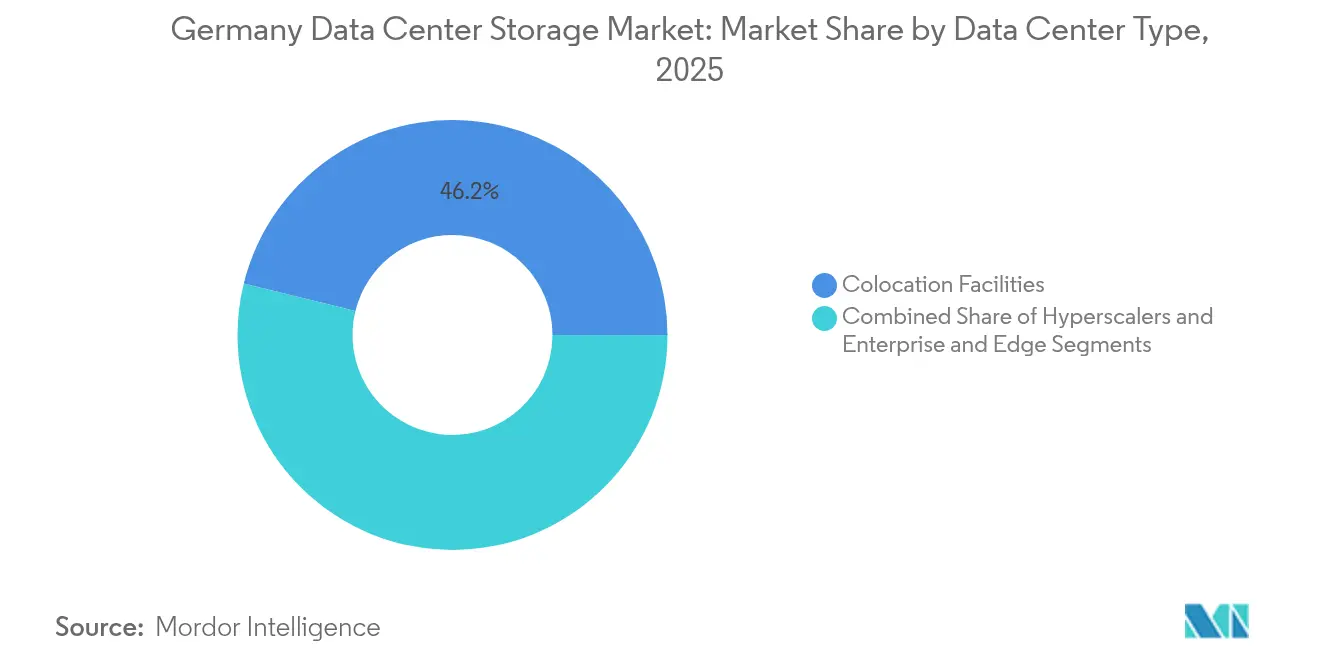
- By data-center type, colocation facilities led with 46.15% of Germany data center storage market share in 2025, whereas hyperscalers are projected to clock the fastest 4.95% CAGR to 2031.
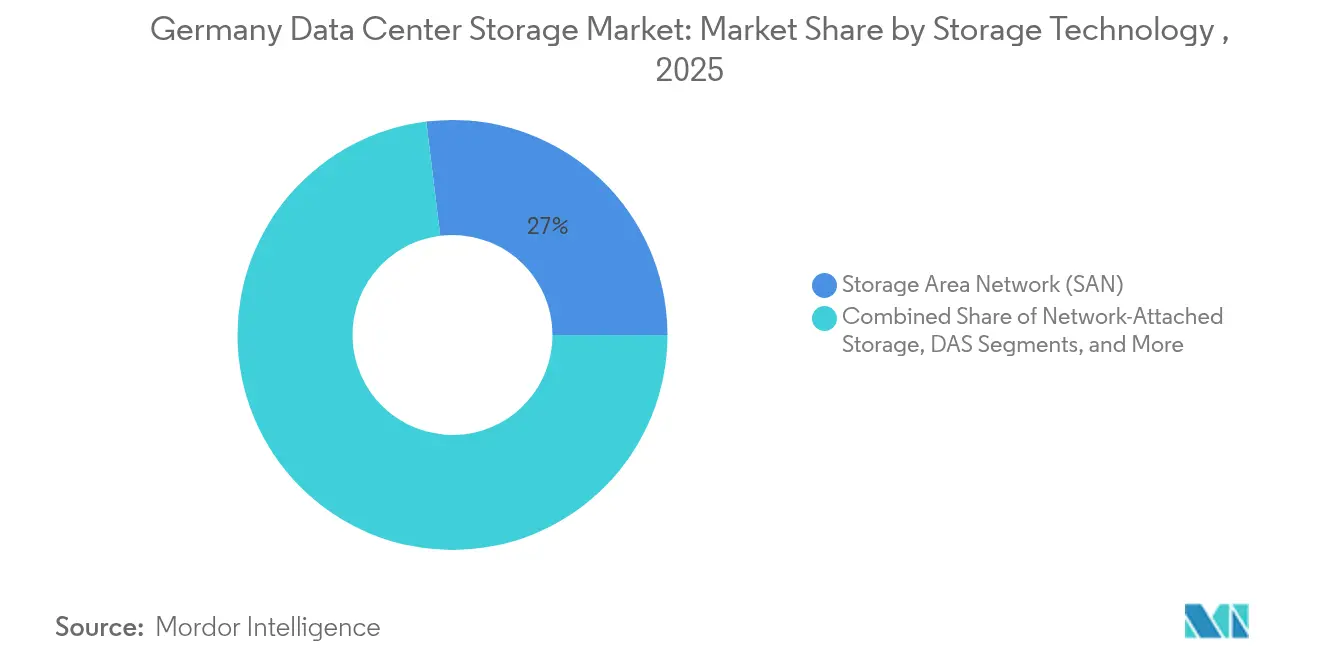
- By storage technology, Storage Area Networks captured 26.95% of revenue in 2025, while Network Attached Storage is advancing at a 3.58% CAGR through 2031.
- By storage type, HDD arrays accounted for 43.05% of the German data center storage market size in 2025; all-flash arrays are set to grow at a 4.12% CAGR during the period.
- By end user, IT & Telecommunications held 27.75% share of the Germany data center storage market size in 2025, but BFSI is expanding at 3.87% CAGR on the back of digitized banking and real-time risk analytics.
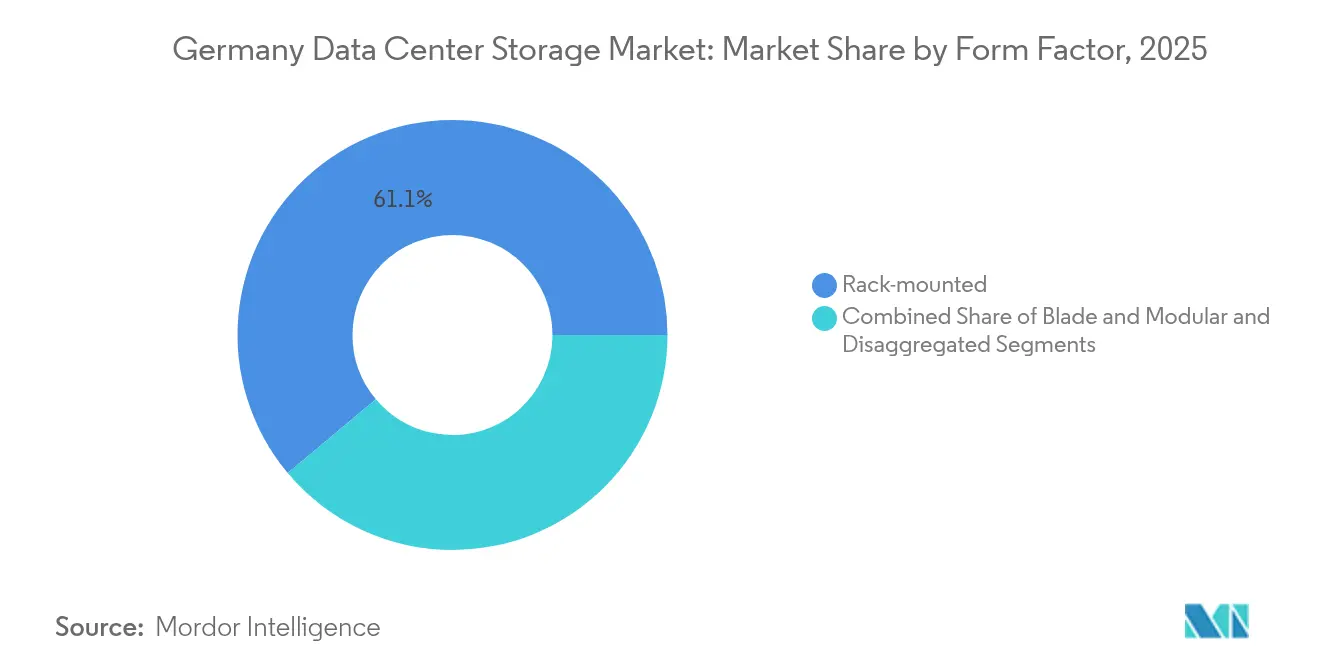
- By Form Factor, Rack-mounted held 61.10% share of the Germany data center storage market size in 2025, but Disaggregated / Composable is expanding at 5.12% CAGR on the back of digitized banking and real-time risk analytics.
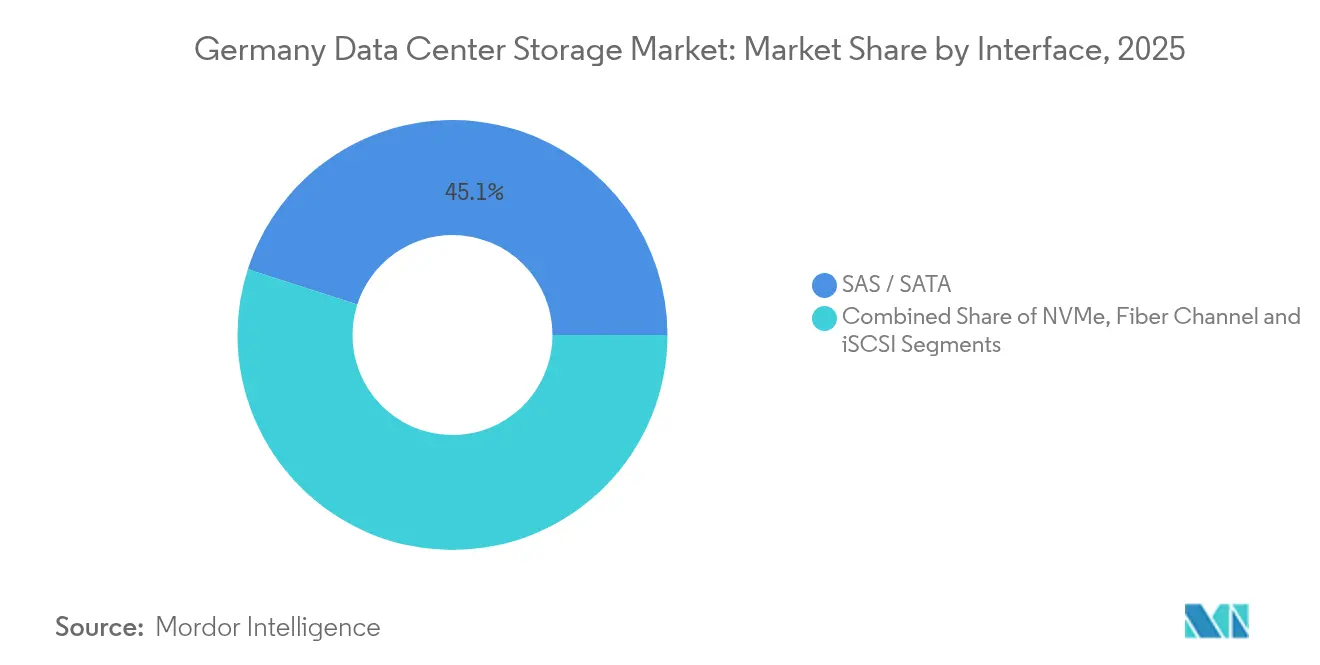
- By Interface, SAS / SATA held 45.05% share of the Germany data center storage market size in 2025, but NVMe is expanding at 5.25% CAGR on the back of digitized banking and real-time risk analytics.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Germany Data Center Storage Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cloud-computing boom among German enterprises | +1.2% | Frankfurt, Munich, Berlin metros | Medium term (2-4 years) |
| Shift to green / energy-efficient data centers | +0.8% | Baden-Württemberg, North Rhine-Westphalia | Long term (≥ 4 years) |
| Accelerated AI and Gen-AI workloads driving flash adoption | +0.6% | Nationwide industrial clusters | Short term (≤ 2 years) |
| Edge-location build-out for Industry 4.0 / 5G | +0.4% | Manufacturing belt | Medium term (2-4 years) |
| Surplus-heat reuse subsidies effective 2025 | +0.3% | Urban district-heating zones | Long term (≥ 4 years) |
| Bundesbank-backed Gaia-X sovereign cloud push | +0.2% | Financial-services nodes | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Cloud-Computing Boom Among German Enterprises
German firms are migrating workloads to cloud platforms at a controlled pace that preserves on-premises investments while unlocking elastic compute for analytics. A Fraunhofer IESE survey shows systems-engineering complexity scoring 7.6 today and rising to 8.7 within five years, revealing that legacy stacks can no longer cope with real-time integration demands.[1]Fraunhofer IESE, “Systems Engineering Trends 2025–2030,” iese.fraunhofer.de Hybrid storage that bridges data center, colocation and Gaia-X compliant sovereign clouds, therefore finds favor, supporting gradual refactoring without breaching residency rules. Frankfurt, Munich and Berlin remain hubs thanks to latency-sensitive BFSI and SaaS workloads. Federal incentives for digitalization, detailed in the 2024 Haushaltsplan, are further lowering adoption barriers through tax breaks on cloud spending.
Shift to Green / Energy-Efficient Data-Centres
Germany’s carbon-neutrality target for 2045 has moved PUE and recyclability to the top of procurement scorecards. Operators are adopting liquid and immersion cooling to manage thermals in high-density racks where air cooling hits physical limits. AI-driven orchestration platforms, such as Dell Technologies’ Concept Astro, now simulate server and storage loads in a digital twin to modulate fan speeds and CPU states, cutting power draw up to 14% in field tests.[2]C. Jones, “Dell’s Concept Astro Cuts Data-Center Power by 14%,” CIO, cio.com Demand is rising for modular enclosures built from recyclable alloys so components can be swapped without energy-intensive refits.
Accelerated AI / Gen-AI Workloads Driving Flash Adoption
Automotive and manufacturing leaders are embedding vision-based quality control and predictive maintenance algorithms that require millisecond response. Traditional spinning-disk arrays cannot meet those service-level objectives, driving NVMe flash uptake even in capex-constrained environments. Edge micro-data centers in Bavaria and Baden-Württemberg now deploy disaggregated NVMe-over-Fabrics clusters that provide central manageability while hosting inference models locally for privacy compliance. Variable I/O profiles of training versus inference make fine-grained tiering essential to cap energy bills.
Edge-Location Build-Out for Industry 4.0 / 5G
Private 5G networks inside factories are pushing compute and storage closer to robots and machine-vision stations. BSI’s 2025 Open RAN guidelines underscore that local media retention is mandatory when networks degrade, obliging ruggedized NAS or DAS nodes to buffer telemetry until backhaul resumes.[3]Bundesamt für Sicherheit in der Informationstechnik, “Sicherheitsanforderungen 5G Open RAN v2.0,” bsi.bund.deAutomated data-placement tools help cache critical control data at the edge while archiving less-urgent logs in central repositories, balancing cost and resilience.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Up-front capex & stringent data-sovereignty audits | ?0.5% | BFSI, public sector | Short term (≤ 2 years) |
| Volatile electricity prices linked to Energiewende | ?0.3% | Regions with high renewables | Medium term (2-4 years) |
| Lengthy power-grid connection lead times | ?0.4% | Industrial zones | Long term (≥ 4 years) |
| Scarcity of skilled storage engineers (Fachkr?ftemangel) | ?0.2% | Metropolitan clusters | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Up-Front Capex & Stringent Data-Sovereignty Audits
Before procuring new arrays, banks and ministries must complete exhaustive privacy impact assessments that can extend project cycles by six months. The Palantir litigation in Hesse shows how platforms face scrutiny for potential mass-surveillance risk, elevating encryption, key custody and audit log features as must-haves. Custom secure configurations push bill-of-materials costs above standard SKUs, dampening short-term volume.
Volatile Electricity Prices Linked to Energiewende
Wholesale electricity spot rates fluctuated by up to 93 EUR/MWh in 2024, compelling operators to seek arrays that throttle idle power and schedule replication during off-peak windows. HDD-based systems that draw steady wattage regardless of I/O utilization become less attractive than flash that can enter deep sleep states. Procurement teams now model total cost of ownership over 10-year horizons, factoring grid-price hedging and potential carbon taxes.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Storage Technology: SAN Leadership Faces NAS Disruption
Storage Area Networks provided the robustness that mission-critical SAP HANA and core-banking workloads demanded, holding 26.95% revenue in 2025. Yet NAS systems, helped by software-defined file services, are projected to record 3.58% CAGR. Adoption is strongest among software-as-a-service vendors that value simplified scale-out and REST-API integration. Direct-attached storage retains a role in line-side robotics cells where deterministic latency trumps shared fabric convenience. Object storage paired with tape remains vital for compliance archives, ensuring immutable copies that satisfy BaFin retention rules.
German operators favor iterative refresh cycles. Fraunhofer IESE notes a sector-wide pivot toward model-driven development that reduces bespoke scripting. Consequently, platform teams gravitate to NAS clusters with familiar NFS and SMB semantics, limiting retraining and freeing scarce storage engineers for optimization work.


By Storage Type: Flash Transition Accelerates Despite HDD Resilience
HDD arrays continued to dominate capacity-oriented tiers, representing 43.05% share in 2025. However, all-flash arrays will expand at 4.12% CAGR as NVMe pricing falls and AI inference gains traction. Hybrid arrays provide a hedge, enabling automatic placement of hot datasets on TLC or QLC NAND and cold files on high-capacity disks, supporting compliance retention yet satisfying performance SLAs. HDD vendors counter with helium-filled 30 TB drives shipping in 2026, delaying full conversion in backup tiers.
By Data Center Type: Colocation Dominance Reflects Sovereignty Priorities
Colocation vendors delivered 46.15% revenue in 2025, supplying sovereign racks and flexible lease tenors. Hyperscalers, after adopting European Processor Initiative chips and opening local regions, will post 4.95% CAGR, driven by analytics sandboxes and disaster-recovery environments. Enterprises keep tier-0 data inside colocation cages to maintain key custody yet burst analytics to the cloud when usage peaks. The Germany data center storage market continues to prize auditability; vendors that expose encryption chipset certificates and support client-supplied HSMs see faster uptake. Edge micro data centers proliferate along autobahn logistics corridors, caching telemetry for last-mile tracking.
By End User: IT Leadership Challenged by BFSI Growth
IT & Telecommunications users maintained 27.75% share in 2025, anchored by SaaS back-ends and streaming platforms. BFSI workloads, spanning real-time risk engines and RegTech analytics, will generate 3.87% CAGR. German banks must store tick-level trade data for ten years, inflating capacity plans. Government digitization, energized by the Onlinezugangsgesetz deadlines, sustains steady demand for compliant systems. Media producers keep editing files on high-throughput NAS, while healthcare accelerates imaging archive migration to hybrid clouds aligned with Gematik guidelines.
By Form Factor: Rack-Mounted Stability Meets Composable Innovation
Rack-mounted enclosures held 61.10% revenue in 2025 due to entrenched data-center designs. Composable infrastructure that pools flash, GPU, and CPU over PCIe-based fabrics is forecast to post a 5.12% CAGR as research labs and semiconductor fabs seek granular scaling. Blade storage sees uptake in space-constrained branch offices. The Germany data center storage industry increasingly values chassis that accept both EDSFF and U.3 flash, future-proofing investments.
By Interface: SAS / SATA Incumbency Faces NVMe Disruption
SAS / SATA remained the default at 45.05% share in 2025. NVMe will attain 5.25% CAGR, driven by microservice architectures that demand sub-100 μs latency. Fibre Channel persists in core banking SANs where dual-path redundancy is entrenched. iSCSI continues to support SMBs transitioning from DAS. NVMe-over-Fabrics pilots in Berlin show 40% CPU utilization drop versus legacy stacks by offloading storage processing.
Geography Analysis
The Frankfurt Rhine-Main cluster dominates capacity demand as Europe’s financial gateway and DE-CIX interconnection hub. Operators there deploy dense all-flash tiers to clear end-of-day settlement batches under BaFin deadlines. Munich’s proximity to automotive OEMs drives edge-ready, low-latency storage to power autonomous-driving simulations. In North Rhine-Westphalia, brownfield steel plants are refitted with Industry 4.0 sensors, spurring rollout of rugged DAS nodes inside milling halls.
Renewables penetration varies: Schleswig-Holstein sources 110% wind power on windy days, letting data-center operators renegotiate green energy PPAs for lower tariffs. Conversely, Bavaria’s grid constraints incentivize on-site solar plus battery storage. Regional regulators interpret GDPR and the new EU Data Act differently; Hesse’s tech-neutral stance benefits multipurpose colocation, whereas Baden-Württemberg imposes stricter audit checkpoints, lengthening go-live lead times. Vendors offering “compliance as code” templates win contracts by speeding state-level certification.
Regulatory Landscape
Germany data center storage procurement is shaped by security assurance frameworks from the Bundesamt fuer Sicherheit in der Informationstechnik (BSI) and by energy-efficiency rules that increasingly affect infrastructure design choices. For critical infrastructure and regulated hosting or housing environments, BSI sector-specific standards such as the B3S for Housing, Hosting, and CDN (valid through October 1, 2028) influence controls around auditability, logging, and resilience. This, in turn, reinforces demand for storage platforms with strong encryption, immutable backup options, and verifiable operational evidence.
On cloud assurance, BSI updated its Cloud Computing Compliance Criteria Catalogue (C5:2026), aligning requirements more closely with European certification trajectories, including EUCS. Legislative updates to the BSI Act (BSIG) were published effective March 17, 2026 to implement EU 2022/2557 on critical-entity resilience, raising the bar on operational continuity. Energy governance adds another layer: from January 1, 2026, mandatory energy management system certification applies to data centers above a non-redundant nominal power threshold of 1 MW (or 300 kW for public sector). In June 2026, the federal cabinet approved a draft to amend the Energy Efficiency Act (EnEfG), including adjustments such as a PUE limit of 1.3 for new data centers commissioned after July 1, 2026 and extended transition periods. These requirements feed into storage refresh decisions toward higher-efficiency architectures and better power telemetry.
Competitive Landscape
Five global incumbents, Dell Technologies, HPE, NetApp, IBM, and Pure Storage, collectively held major revenue in 2024. They emphasize firmware-upgradable architectures and AI-enabled management rather than disruptive hardware shifts. Dell’s Concept Astro applies reinforcement learning to model thermals and power, cutting array wattage and fan wear. NetApp is integrating BlueXP backup across on-premises and Gaia-X clouds, streamlining compliance evidence packets in audits. HPE’s Alletra platform offers consumption-based pricing that hedges energy-price swings.
Start-ups targeting NVMe disaggregation, such as VAST Data and Fungible, partner with German AI labs seeking exabyte-scale file repositories. Meanwhile, traditional HDD vendors Western Digital and Seagate collaborate with colocation providers to certify helium-filled drives for extended humidity ranges typical in indirect adiabatic cooling halls.
Germany Data Center Storage Industry Leaders
Dell Technologies
Hewlett Packard Enterprise
NetApp
IBM
Huawei Technologies
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Compliance-led modernization creates whitespace for storage stacks that shorten audit cycles while meeting BSI-aligned controls, especially for colocation and regulated end users that need to demonstrate encryption, key custody, and retention practices across hybrid footprints. The publication of BSI C5:2026 and the continued use of sector-specific BSI guidance in hosting or housing environments support demand for platform features such as policy-driven immutability, tamper-evident logs, and standardized compliance reporting across on-premises, colocation, and sovereign-cloud nodes.
Energy and sovereignty programs also steer opportunities toward high-efficiency, high-density storage for AI and data-lake workloads, where liquid cooling and power constraints shape infrastructure choices. The EnEfG regime, including energy management system certification requirements effective January 1, 2026 and the June 2026 draft amendment process that adjusts PUE compliance parameters for new facilities after July 1, 2026, increases the value of arrays that provide granular power monitoring, intelligent tiering, and workload-aware replication scheduling. On the demand side, Germany's data center strategy, as discussed in legal and advisory analyses, frames a policy objective to expand national capacity by 2030 and highlights sovereign cloud infrastructure and AI training clusters as investment priorities. This widens the addressable need for NVMe-accelerated file and object storage in both the Frankfurt core and emerging hubs such as Berlin, where operators seek to reduce concentration risk and latency for regulated workloads.
Recent Industry Developments
- June 2026: Dell Technologies announced the Dell PowerEdge XE8812 server, part of the Dell AI Factory with NVIDIA, designed for high-density HPC and AI workloads. The rollout supports AI workloads in German data centers. It strengthens Germany-focused AI infrastructure capabilities for data center storage.
- May 2026: Dell Technologies introduced the Dell PowerStore Elite storage platform with AI-driven software, scheduled for availability in July 2026. It expands AI-driven storage options in Germany. It enhances software-defined storage leadership in German data centers.
- March 2026: Hewlett Packard Enterprise committed to building AI factory infrastructure at the Hochstleistungsrechenzentrum Stuttgart (HLRS) to support the EU-AI-Factory HammerHAI initiative. It aligns German research centers with sovereign AI infrastructure. It advances Germanys AI data-center capabilities and sovereign storage workloads.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers the revenue generated from data center storage products and related storage software sold and deployed in Germany for enterprise and service-provider workloads, across on-premises facilities, colocation sites, and cloud data centers.
Scope exclusions: It excludes general purpose servers, networking-only hardware, and building infrastructure like power and cooling that is not sold as part of the storage stack.
Segmentation Overview
- By Storage Technology
- Network Attached Storage (NAS)
- Storage Area Network (SAN)
- Direct Attached Storage (DAS)
- Object and Tape Storage
- By Storage Type
- Traditional HDD Arrays
- All-Flash Arrays (AFA)
- Hybrid Storage
- By Data Center Type
- Colocation Facilities
- Hyperscalers/Cloud Service Providers
- Enterprise and Edge
- By End User
- IT and Telecommunication
- BFSI
- Government and Public Sector
- Media and Entertainment
- Healthcare and Life Sciences
- Manufacturing
- By Form Factor
- Rack-mounted
- Blade and Modular
- Disaggregated / Composable
- By Interface
- SAS / SATA
- NVMe
- Fibre Channel and iSCSI
Data Sources, Market Sizing, and Validation
Desk Research
We started by building a fact base on Germany data center demand and expansion patterns, because storage spend usually follows installed IT capacity and refresh cycles. Public sources such as Destatis, Eurostat, the Bundesnetzagentur, and BSI publications were used to understand the local digital infrastructure context, compliance signals, and energy related constraints that can shape storage choices.
To translate the demand signals into sizing inputs, we also reviewed materials such as company annual reports, investor presentations, trusted press coverage, and data center association releases that discuss capacity additions and technology shifts. In addition, paid subscriptions were used selectively for company financials and intelligence, news and financials tracking, and patent databases to check product cycles and pricing direction. These desk research sources are illustrative only, and many other references were used for data collection, cross-checking, and clarification.
Primary Interviews and Surveys
We validated the desk view through expert interviews and structured surveys with data center operators, colocation managers, enterprise IT teams, and channel participants that touch storage purchasing decisions in Germany. Discussions covered workload mix, refresh timing, interface preferences, and how security and data residency expectations change architecture choices, and then the responses were used to tighten assumptions where public data was not detailed enough.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 26% | CXOs: 14% |
| Mid tier: 59% | Functional/Unit leaders: 27% |
| Smaller Players: 15% | Managers: 59% |
Market-Sizing & Forecasting
Sizing was built using a top-down demand reconstruction that links Germany data center storage spending to the country's data center footprint and refresh behavior, and then it was checked against selective bottom-up approximations. In practice, we mapped storage demand to indicators such as installed IT capacity growth, rack and server density trends, the share of flash versus HDD in mixed workloads, and average refresh cycles by data center type, which then guide a reasonable price per usable terabyte pathway.
To keep the totals realistic, sampled vendor and channel checks were used to sanity-check the model, using combinations such as estimated shipment volumes times observed average selling prices, and then adjusting for resale, bundling, and multi-year contracting where it was repeatedly highlighted by interviewees. When inputs were missing, gaps were filled with conservative ranges anchored to what buyers reported as typical configurations, and the ranges were narrowed through follow-up calls.
For forecasting, we used scenario analysis supported by variable-by-variable expectations from primary respondents, since storage demand in Germany is sensitive to cloud migration pace and local compliance priorities. Key modeled drivers included virtualization and container adoption rates, NVMe penetration in performance tiers, data growth from regulated industries, energy cost pressure influencing tiering, and the pace of colocation capacity additions in major metros.
Data Validation & Update Cycle
We cross-validated outputs by comparing implied spend per rack and per MW against independent signals, and then reviewing any sharp jumps that did not match the timing of capacity additions or refresh cycles. If a variance looked material, inputs were re-checked, assumptions were re-run, and respondents were re-contacted to confirm whether a one-off event or a definitional issue caused the change.
Before sign-off, the model goes through multiple analyst review steps, including checks on currency conversion timing, price trend logic, and segment totals that must add up cleanly to the overall number. Reports are refreshed annually, and interim updates are made when a material event changes demand conditions. Right before delivery, a fresh update pass is done so clients receive the latest view.
黑料不打烊's Germany Data Center Storage Market Size Compared Against Other Published Estimates
Published market values for Germany data center storage can look far apart because each publisher draws the line differently on what counts as storage, and then uses different pricing and timing assumptions. The table points to that spread clearly, and it usually comes down to scope boundaries, base year choice, and how refresh cycles are treated.
The benchmark table shows a lower value than some broader estimates, and in 黑料不打烊's model the count is limited to data center storage products and storage software sold for data center use in Germany, instead of folding in adjacent server or networking spend. Other gaps that shift totals include whether cloud provider internal purchases are treated as market revenue, whether aggressive flash price declines are assumed too early, and whether currency conversion uses annual averages versus a point-in-time rate.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 2.17 B (2026) | |
| Regional Consultancy A | USD 2.35 B (2026) | Uses a wider scope that blends some storage attached server spending into the storage total, and applies faster NVMe adoption with less offset from price compression. |
| Trade Journal B | USD 1.95 B (2026) | Leans on conservative replacement timing and uses a narrower view of external purchases, which can undercount refresh-driven upgrades in colocation and enterprise facilities. |
Reading the three numbers together, the main lesson is that scope and pricing pathways move the total as much as demand does. By anchoring the model to observable capacity and refresh signals, and then checking it with practical channel and buyer inputs, the estimate stays traceable to clear steps that can be repeated and reviewed.


Key Questions Answered in the Report
What is the current value of the Germany data center storage market?
The Germany data center storage market size is USD 2.17 billion in 2026
How fast is the market expected to grow?
It is forecast to expand at a 3.18% CAGR, reaching USD 2.53 billion by 2031.
Which data-center type generates the highest storage demand?
Colocation facilities lead with 46.15% of Germany data center storage market share as of 2025 due to data-sovereignty requirements.
Why are all-flash arrays gaining traction?
AI and Gen-AI workloads need sub-millisecond latency, and flash arrays cut power usage compared with HDDs while meeting performance SLAs.
Page last updated on:
- Data Center Server Market Servers across all regions, split by tier, facility size and facility type.
- Artificial Intelligence (AI) Data Center Market Global AI facilities demand, split by facility type, component and tier.
- Data Center Construction Market Construction across all regions, split by tier, facility size and facility type.
- Mexico Hyperscale Data Center Market Hyperscale sites in Mexico, split by facility type, component and tier.
- South Korea Data Center Server Market South Korea's servers, split by data-center tier, form factor and application / workload.



