
Electrically Conductive Coating Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 26.01 Billion |
| Market Size (2031) | USD 34.49 Billion |
| Growth Rate (2026 - 2031) | 5.81 % |
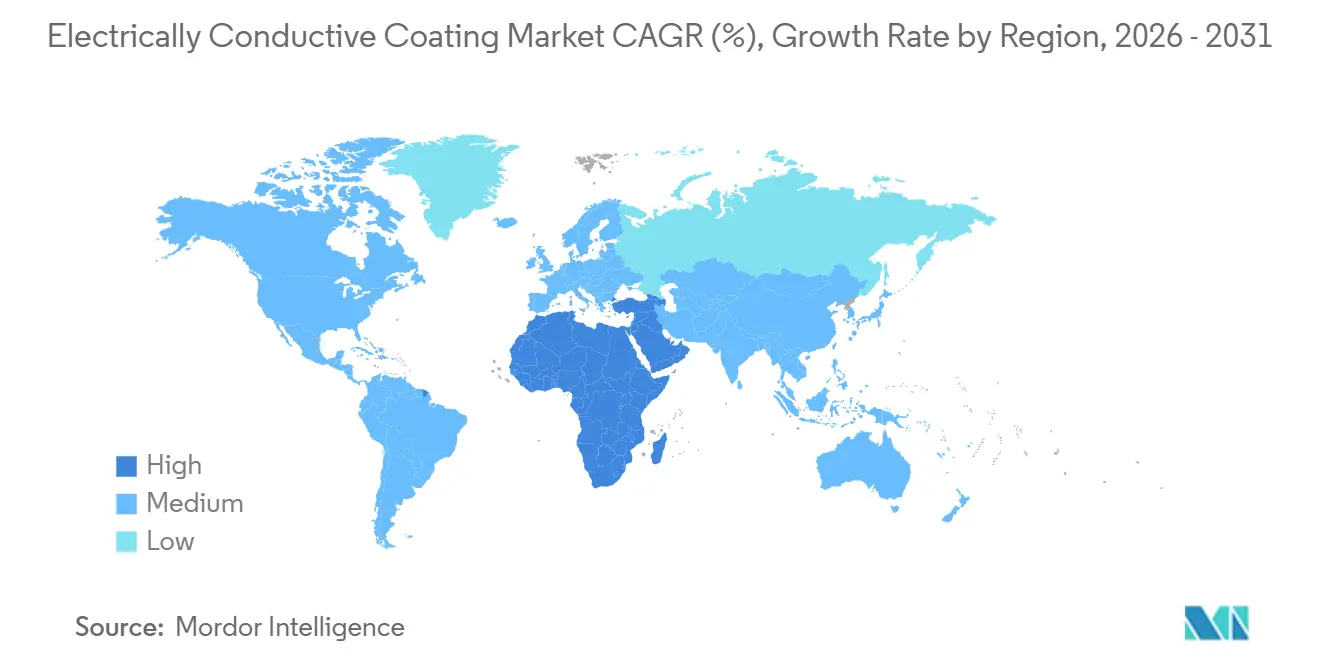
| Fastest Growing Market | Middle East and Africa |
| Largest Market | Asia Pacific |
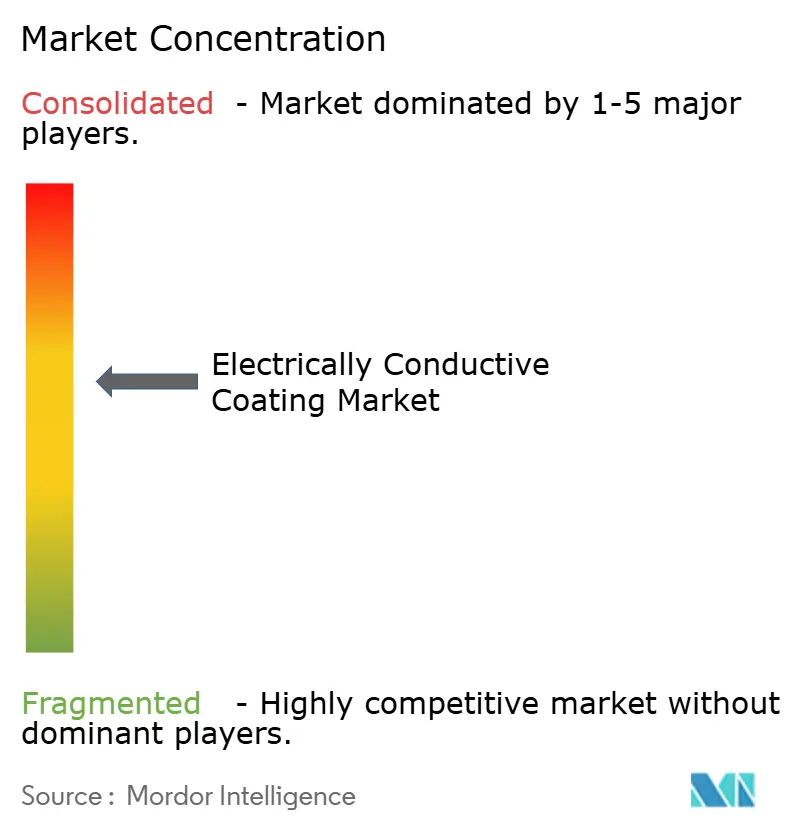
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. | |
Electrically Conductive Coating Market Analysis by 黑料不打烊
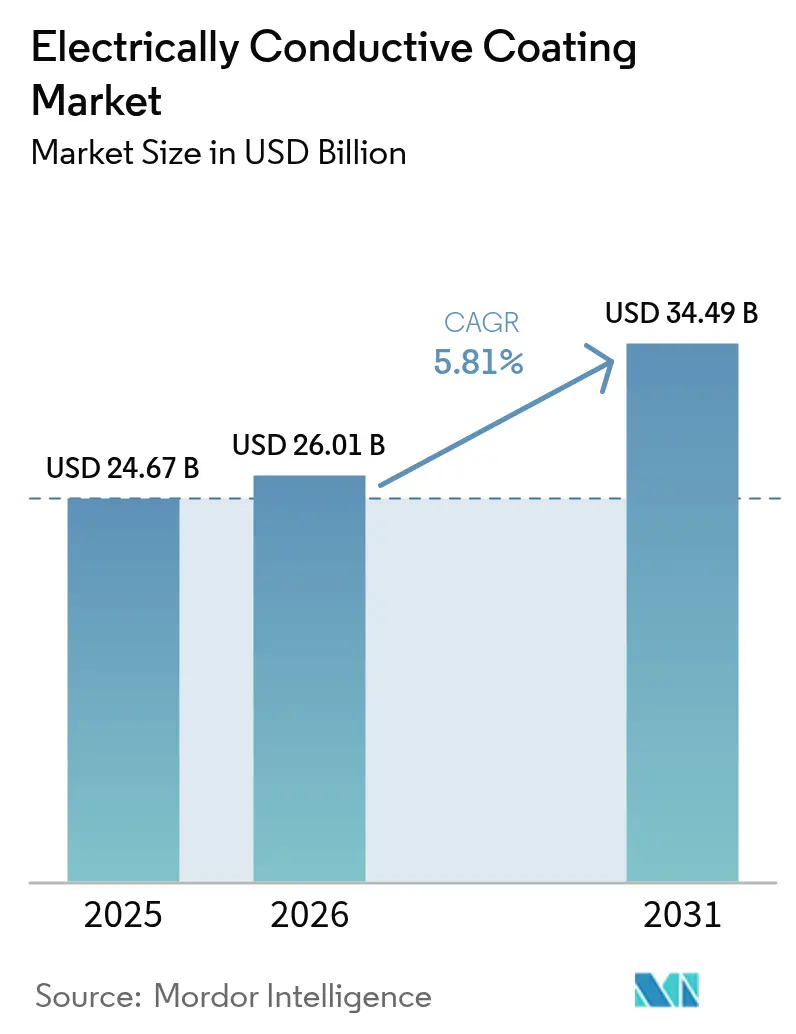
The Electrically Conductive Coating Market size is projected to grow from USD 24.67 billion in 2025 to USD 26.01 billion in 2026, and reach USD 34.49 billion by 2031, growing at a CAGR of 5.81% from 2026 to 2031. End-users are raising performance thresholds for electromagnetic interference (EMI) control even as form-factors shrink and component density rises, making spray- or dip-applied conductive layers indispensable. Demand is further amplified by 5G macro- and small-cell roll-outs, where enclosure interiors need 40–60 dB of shielding, and by wearable medical devices that must balance biocompatibility with electrical conductivity. Raw-material substitution is accelerating: copper fillers are clawing share from silver in mid-tier consumer electronics because a 70% material-cost gap outweighs the conductivity delta, while polyurethane chemistries are outgrowing acrylics as automakers and smartwatch brands insist on coatings that survive 100,000 flex cycles. Supply-chain strategies are shifting too, with tier-one suppliers acquiring filler producers to stabilize prices after silver swung between USD 28 and USD 34 per troy ounce in 2025.
Key Report Takeaways
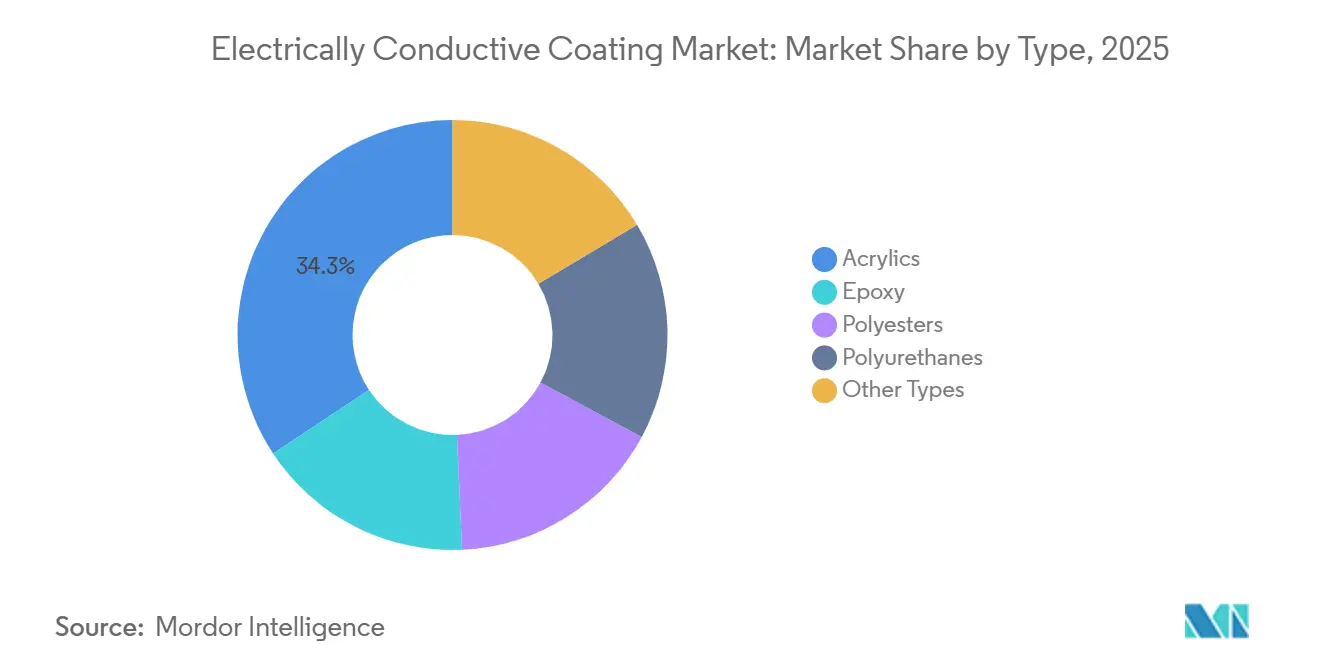
- By type, acrylics accounted for 34.28% of the electrically conductive coating market size in 2025, yet polyurethanes are advancing at a 6.22% CAGR to 2031.
- By conductive filler material, silver led with 46.41% of the electrically conductive coating market share in 2025, whereas copper is forecast to expand at a 6.34% CAGR through 2031.
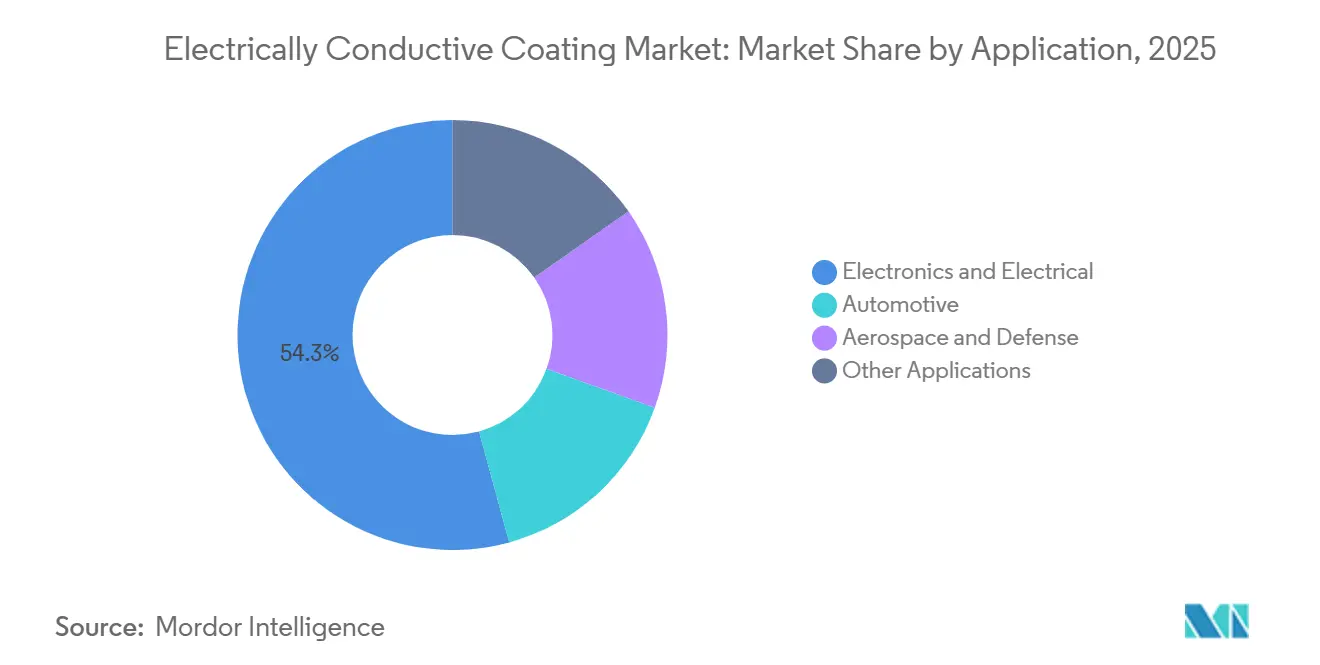
- By application, electronics and electrical captured 54.25% revenue share in 2025, while automotive is set to record the fastest 6.15% CAGR to 2031.
- By geography, Asia-Pacific dominated with 48.37% of revenue in 2025; the Middle East and Africa is projected to register the highest 5.98% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Electrically Conductive Coating Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising applications for anti-static protection | +0.9% | Global, concentrated in APAC semiconductor hubs (Taiwan, South Korea, Singapore) | Medium term (2–4 years) |
| Growing demand from electrical and electronics industry | +1.3% | Global, led by APAC manufacturing corridors and North America design centers | Long term (≥ 4 years) |
| Surge in adoption of EMI/RFI shielding in 5G infrastructure | +1.1% | APAC core (China, India, Japan), spill-over to Middle East and North America | Short term (≤ 2 years) |
| Rapid miniaturization in wearable electronics | +0.8% | North America and Europe for Research and Development, APAC for volume production | Medium term (2–4 years) |
| Conductive bio-compatible coatings for implants | +0.5% | North America and Europe (FDA, CE Mark pathways), emerging in APAC | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
Rising Applications for Anti-Static Protection
Semiconductor fabs are tightening electrostatic-discharge thresholds below 10 V as gate oxides narrow toward 3 nm, pushing conductive floor and workbench coatings into all new cleanroom builds. Cleanroom additions in Taiwan and South Korea climbed 22% in 2025, with each square meter finished in fast-curing acrylic layers that dissipate charge within 0.1 seconds. Extreme-ultraviolet lithography magnifies risk because a single ESD event can destroy a USD 150,000 reticle; consequently, fabs now specify surface resistivity between 10? and 10? Ω/square. Smaller contract manufacturers in Malaysia and Vietnam are adopting water-based chemistries to meet ISO 14644 particulate limits without volatile-organic-compound penalties, a trajectory that supports mid-single-digit volume growth through 2028. Collectively, these forces are anchoring anti-static coatings as a baseline requirement rather than an optional upgrade.
Growing Demand from Electrical and Electronics Industry
Printed-circuit boards (PCBs) surpassed 820 million m? of global output in 2025, with conductive coatings applied to roughly 35% of that area to ground high-speed traces. Flagship smartphones now integrate more than 18 layers, and each layer needs selective coatings for via fill and EMI suppression. As 5G handsets doubled antenna counts, conformal coatings that maintain conductivity across curved solder joints became mandatory, lifting demand in China, South Korea, and Japan. Display makers are embedding touch sensors into OLED stacks, displacing brittle indium tin oxide with silver-nanowire dispersions that better tolerate flexing. This architecture shift should add an incremental 120 million m? of coating demand annually by 2029.
Surge in Adoption of EMI/RFI Shielding in 5G Infrastructure
Global 5G base-station installs topped 3.2 million in 2025, each housing power amplifiers and beamforming arrays that emit radio-frequency interference unless shielded internally. Conductive polyurethane sprayed onto enclosure interiors achieves 40–60 dB attenuation above 3 GHz, a level unattainable with gaskets alone. India added 450,000 stations during 2025, each consuming about 0.8 m? of coating to meet national Telecom Engineering Centre specs. Urban millimeter-wave deployments demand coated plastic radomes because leakage at 28 GHz can degrade throughput by 20%. China’s regulator now mandates EMI compliance for all small-cell enclosures, accelerating uptake among second-tier vendors.
Rapid Miniaturization in Wearable Electronics
Average circuit-board real estate in wearables shrank 18% year-on-year to 2025, removing space for metal cans and favoring spray-coated alternatives under 50 ?m thick. Smartwatches integrate electrocardiogram sensors on flexible polyimide substrates that rely on stretchable silver-flake inks surviving 10,000 bends at 5 mm radius. The FDA green-lit continuous-glucose monitors with PEDOT: PSS layers in 2025, demonstrating biocompatible coatings that metallic fillers struggle to match. With a 290 million installed base of wearable medical devices, even 2–5 grams of coating per unit translates to multi-kiloton demand. New EU medical-device rules now require biocompatibility testing for any coating touching skin for over 30 days, raising entry barriers for commodity suppliers[1]J. Doe et al., “Flexible Silver-Flake Inks for Wearable Electronics,” Nature, nature.com .
Restraints Impact Analysis of Electrically Conductive Coating Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Toxicity and environmental concerns of heavy-metal fillers | -0.7% | Europe and North America, widening to APAC | Medium term (2–4 years) |
| Volatility in silver and copper prices | -0.5% | Global, most acute in APAC and South America | Short term (≤ 2 years) |
| Dispersion issues of nano-fillers causing defects | -0.4% | Global, concentrated in facilities lacking high-shear mixing | Medium term (2–4 years) |
| Source: 黑料不打烊 | |||
Toxicity and Environmental Concerns of Heavy-Metal Fillers
RoHS caps cadmium at 100 ppm and lead at 1,000 ppm in electronics, forcing reformulation of legacy coatings that once relied on cadmium oxide for corrosion resistance. Compliance testing adds about USD 50,000 per SKU and can double the qualification timetable for aerospace or automotive programs. REACH dossiers for nano-silver now require aquatic-toxicity data, as LC50 values below 10 ?g/L for Daphnia magna triggered hazard classification and stricter transport rules. China’s draft heavy-metal limits signal that similar rules will land in APAC by 2027. Although graphene and carbon nanotubes can substitute, their production costs run 30–40% above silver flakes, slowing broad adoption.
Volatility in Silver and Copper Prices
Silver fluctuated between USD 28 and USD 34/oz in 2025, compressing gross margins from 32% to 26% at suppliers without hedges[2]World Bank Commodities Data, “Monthly Metals Price Index,” worldbank.org . Copper traded from USD 8,200 to USD 9,800/ton, and although cheaper than silver, its propensity to oxidize demands encapsulation that lifts cost by 10–15%. Many Indian and Southeast Asian coaters lack futures-market access, so spot swings can erase a quarter’s profit. Automotive OEMs are now favoring long-term supply agreements that lock filler pricing for three-year model cycles, advantaging vertically integrated formulators who own or partner with metal-flake mills.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Electrically Conductive Coating Market Segment Analysis
By Type:
Polyurethanes Gain on Flexibility DemandsAcrylics retained 34.28% share of the electrically conductive coating market in 2025, owing to fast UV curing and compatibility with roll-to-roll PCB lines. Polyurethanes, however, are projected to grow at a 6.22% CAGR, outpacing the overall electronically conductive coating market size growth because EV battery packs, automotive interiors, and health-wearables need coatings that endure 100,000 flex cycles without cracking. Epoxies remain the choice for high-heat avionics that see ≥150 °C, while polyesters fill outdoor telecom niches where weatherability matters more than ultimate conductivity.
Polyurethane adoption is accelerating in battery-management systems that swing from ?40 °C to 85 °C, conditions that delaminate acrylics within 500 cycles. Automakers now specify room-temperature-curing two-component urethanes, trimming oven energy costs and cutting takt time. Acrylic vendors are responding with hybrid chemistries that graft polyurethane oligomers onto acrylic backbones, but these blends sacrifice the 30-second tack-free cure that once gave acrylics a throughput edge.


By Conductive Filler Material:
Copper Challenges Silver’s PremiumSilver captured 46.41% of 2025 revenue owing to unrivaled corrosion resistance and 63 MS/m conductivity. Yet copper is growing 6.34% annually because flakes priced at USD 18–22/kg versus USD 650–750/kg for silver unlock a 70% bill-of-materials saving in mid-range smartphones, shifting the electrically conductive coating market share equation. Aluminum holds niche positions in aerospace radomes where light weight trumps peak conductivity, while graphene, carbon nanotubes, and PEDOT: PSS collectively account for 8–10% of volume but command biomedical premiums.
Core-shell fillers—copper cores with silver or nickel skins—retain 90% of copper’s cost edge while resisting oxidation, and adoption surged among Chinese PCB fabricators in 2025. Silver will remain entrenched in >10 GHz high-frequency apps and in implants where antimicrobial properties are desired. Aluminum’s use is capped by galvanic corrosion risk when paired with copper traces, an issue that forced several radar module recalls in 2024. Graphene’s biocompatibility and flexibility appeal to wearables, even though the cost runs 3–4 times above silver.
By Application:
Automotive Electrification Accelerates Coating DemandElectronics and electrical applications held a commanding 54.25% slice of the electrically conductive coating market size in 2025, covering PCB shielding, display sensors, and semipackaging. Automotive is the fastest-growing end-use at a 6.15% CAGR, propelled by battery-electric vehicles that pack 3–5× more electronic control units than combustion cars, each needing EMI suppression. Aerospace and defense demand is steady but hamstrung by multi-year qualifications and budget cycles.
Automotive uptake centers on China, Europe, and North America, where revised CISPR 25 rules cut allowable radiated emissions by 6 dB. Battery-management enclosures now cycle coatings through 2,000-plus charge events, creating a replacement market non-existent in legacy drivetrains. Electronics growth will moderate as smartphone and PC volumes plateau, but satellite mega-constellations could lift aerospace demand; 15,000 low-Earth-orbit craft are slated before 2030, each needs conductive thermal and EMI layers.
Geography Analysis
APAC Electrically Conductive Coating Market
Asia-Pacific controlled 48.37% of global revenue in 2025, underpinned by vertically integrated clusters in Shenzhen, Suzhou, and Penang, where coating formulators, PCB shops, and final assemblers operate within the same-day trucking lanes. China alone consumed 180,000 tons of conductive coatings in 2025 on the back of 9 million EVs produced and aggressive 5G roll-outs. India’s Production-Linked Incentive scheme lifted domestic electronics output 28%, expanding coating imports as local capacity rose from 12,000 tons to 18,000 tons. Japan and South Korea dominate high-value niches such as biocompatible and high-temperature epoxies, commanding 20–30% price premiums. Southeast Asian nations are winning assembly work relocating from China, but resin and filler ecosystems lag, keeping them import-dependent.
North America Electrically Conductive Coating Market
North American electrically conductive coatings demand is concentrated in automotive, aerospace, and data-center hardware. The U.S. Inflation Reduction Act incentivizes coatings made near battery plants; three facilities totaling 25,000 tons/year will open by 2027 in Michigan and Georgia. Canada anchors specialty epoxy demand for avionics built in Quebec, while Mexico’s nearshoring boom lifted electronics production 16% as wire-harness and medical-device assemblers expanded, albeit still reliant on imported coatings.
EMEA and South America Electrically Conductive Coating Market
Europe captured significant market share in 2025, with Germany, France, and the U.K. driving automotive and industrial demand. Stringent RoHS and REACH rules are accelerating the pivot to copper and graphene while hiking compliance costs that push smaller suppliers to exit. The EU Battery Regulation mandates EMI shielding on traction batteries exceeding 2 kWh, locking in a recurring volume stream from electric-vehicle lines. South America and the Middle East and Africa share 9% of revenue; the latter is the fastest-growing region at 5.98% CAGR, powered by Saudi and UAE data-center builds that demand 60 dB shielding for high-density racks. Brazil’s flex-fuel vehicles absorbed around 4,500 tons of coatings in 2025, but Argentina’s market dragged due to tariffs and currency volatility.

Value Chain Analysis
The value chain starts with upstream suppliers of conductive fillers (silver flakes and nanowires, copper powders and flakes including core-shell architectures, aluminum, carbon black, carbon nanotubes, graphene) and binder systems (acrylic, epoxy, polyurethane, polyester, and conductive polymers such as PEDOT:PSS). Formulators compound fillers into coatings using high-shear dispersion, mixing, and filtration, then validate shielding and resistivity with in-line and lab metrology, a capability that has gained prominence as end-users tighten defect tolerance in electronics, battery packs, and data-center hardware.
Application specialists and converters deploy these materials through spray, dip, screen printing, inkjet, and roll-to-roll lines to meet thickness and uniformity targets, while managing nano-filler dispersion issues that can degrade shielding performance. Downstream demand concentrates in electronics and electrical manufacturing, automotive electrification (battery-management systems and enclosures), and infrastructure such as 5G and data centers where EMI/ESD control is specified at the enclosure and surface level. Distribution typically combines direct supply to large OEMs and tier-one integrators with regional channels supported by application labs for qualification and line trials, and co-development with customers is common to balance durability and conductivity trade-offs (for example, automotive programs pushing polyurethane systems for flex and thermal cycling). Recent upstream innovation and supply-security efforts are visible in new additive introductions such as Sparc Technologies graphene-based SparcES (June 2026) for ESD and conductive coatings, along with continued emphasis on alternative filler architectures (copper-core/silver-shell) that reduce cost exposure while maintaining electrical performance for high-volume programs.
Competitive Landscape
The electrically conductive coating market is moderately consolidated. Global players leverage scale procurement to hedge metal price swings and maintain regional application labs that shorten customer qualification cycles. Regional specialists compete on custom formulations and two-week lead times, often favored for prototype runs in wearables or medical implants. Technology pivots toward water-based systems meeting volatile-organic-compound mandates without losing conductivity. IP activity is intensifying around stretchable inks; Henkel filed 14 patents in 2025 covering silver-nanowire networks embedded in thermoplastic polyurethane, foreshadowing standard interfaces for health wearables. Graphene-focused startups are disrupting high-margin niches: Italy-based BeDimensional raised EUR 12 million in 2025 to scale automotive battery thermal-management coatings that double in-plane conductivity while cutting weight by 20%.
Electrically Conductive Coating Industry Leaders
Akzo Nobel NV
PPG Industries Inc.
The Sherwin-Williams Company
Henkel AG & Co. KGaA
Axalta Coating Systems
- *Disclaimer: Major Players sorted in no particular order
Electrically Conductive Coating Market Companies Covered in this Report
- A & A Coatings
- Akzo Nobel NV
- Ameetuff Technical Paints Industries
- Axalta Coating Systems
- BeDimensional
- CAIG
- Creative Materials Inc.
- Cromas Paints
- Gelest Inc.
- Henkel AG & Co. KGaA
- Holland Shielding Systems BV
- MG Chemicals
- Parker-Hannifin Corporation
- PPG Industries Inc.
- RS Coatings
- Specialty Coating Systems Inc.
- The Sherwin-Williams Company

Market Opportunities and Future Outlook
Material substitution and multifunctional performance requirements create whitespace for coating suppliers that can deliver conductivity alongside corrosion resistance, flexibility, and processability on heat-sensitive substrates. The market is actively exploring conductive polymers and hybrid systems: the 2025 PEDOT roadmap published by IOP Publishing in June 2026 highlighted PEDOT directions across electronics, energy, and bioelectronic platforms, reinforcing interest in processing routes such as vapor-phase polymerization, electropolymerization, and additive manufacturing to improve scalability and performance.
At the same time, productization of copper-based and core-shell filler systems is being pushed by the need to reduce reliance on heavy-metal fillers and manage silver price volatility, which aligns with commercial formulations using copper-core/silver-shell architectures for EV electronics and enclosure shielding. Extreme-environment and high-reliability applications also offer scope where qualification barriers support pricing power. Research published in 2026 demonstrated conductivity control in polymer-derived ceramic coatings (for example, SiHfBCN-Mo) aimed at high-temperature environments, pointing to conductive-coating pathways for industrial and aerospace use cases where conventional organics face thermal limits. Aerospace structures are another differentiated opening, supported by technical work on silver-based conductive polymer coatings for lightning strike protection, reflecting OEM priorities on weight and structural integrity as carbon-fiber composite designs shift away from heavier metallic foils. In infrastructure, suppliers are packaging conductive and dissipative systems as broader offerings for data centers and telecom, reinforced by vendor focus on end-to-end solutions and application services rather than standalone product sales.
Recent Industry Developments in Electrically Conductive Coating Market
- May 2026: AkzoNobel commenced commercial release of an ecosparc graphene-enhanced version of its Interzone 954 protective coating in Australia, developed with Sparc Technologies. The move places graphene additives into an established high-build coating platform, creating a clearer pathway from additive suppliers to scaled coatings adoption. It also expands the set of conductive and dissipative material options available for harsh-environment assets where protective performance and functional additives are increasingly combined.
- April 2026: PPG introduced an end-to-end set of protective coatings solutions and application services for data centers, highlighting dissipative and conductive coating systems for infrastructure needs. By bundling products with services and application support, PPG raised the competitive bar for qualification speed and field performance assurance in large-build environments. The focus reinforces data centers as a high-volume downstream channel for conductive and ESD-control coatings.
- July 2024: AkzoNobel introduced a one-spray powder coating technology under the Resicoat brand aimed at electric vehicle battery electrical protection. The single-application approach targets manufacturing efficiency and more consistent coverage in battery-related components, where electrical protection and durability requirements are tightly specified. This development underscores the shift toward integrated coating solutions tailored to EV battery systems and associated electronics.


Electrically Conductive Coating Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers coatings formulated to carry electrical current, mainly used for EMI shielding and electrostatic discharge control on parts and assemblies across major end-use industries, and measured as total revenue generated from sales of these coatings in USD.
Scope exclusions: This sizing excludes upstream raw metals and fillers sold as standalone materials and also excludes non-conductive protective coatings that do not meet conductivity performance needs.
Segments Covered in This Report
- By Type
- Acrylics
- Epoxy
- Polyesters
- Polyurethanes
- Other Types
- By Conductive Filler Material
- Copper
- Aluminum
- Silver
- Other Material Types
- By Application
- Electronics and Electrical
- Automotive
- Aerospace and Defense
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk work is used to map the demand pool and keep assumptions realistic before we speak to the market. We mainly rely on public references such as US Census Bureau manufacturing statistics, Eurostat industrial output series, UN Comtrade trade flows for relevant chemical and coating categories, and International Energy Agency updates that help track electronics and mobility related demand signals.
We also review technical and adoption signals from sources such as IEEE and peer-reviewed materials journals (for filler choices like silver, copper, and aluminum, and for performance tradeoffs), plus patent databases to gauge recent filing intensity in conductive formulations. Company annual reports, investor presentations, and association publications are used to validate capacity announcements, end-market exposure, and regional footprint. Where public data is too aggregated, we use paid subscriptions to cross-check company financials and shipment-linked trade indicators. The sources mentioned above are illustrative, and many other public and paid references were also checked for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary discussions are used to validate what actually gets purchased and at what price points, which is hard to see from public data alone. We spoke with a mix of coating manufacturers, raw material stakeholders, and downstream users across APAC, EMEA, and the Americas. The inputs were used to confirm assumptions on application mix, typical coating loading levels, and realistic price movement over the forecast period.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 28% | CXOs: 19% | APAC: 43% |
| Mid tier: 52% | Functional/Unit leaders: 35% | EMEA: 37% |
| Smaller Players: 20% | Managers: 46% | Americas: 20% |
Market-Sizing & Forecasting
Sizing starts with a top-down build where coating demand is reconstructed from end-use output and adoption rates, and then translated into value using application-level price ranges. In practice, the model is tied to the most repeatable market signals, such as electronics production and assembly trends, automotive build rates (including EV-related electronics content), aerospace and defense spending direction, and trade movement for coating and chemical categories used in conductive formulations.
Once the demand pool is set, it is stress-tested using selective bottom-up checks, including sampled supplier revenue splits, distributor and channel feedback on run-rate volumes, and a volume times ASP view for a limited set of common applications. When gaps appear in the bottom-up view, we handle them by using conservative penetration bands, then re-checking with interview feedback until totals remain consistent by region and by application.
For forecasting, scenario analysis is used so the base case stays aligned with what industry participants expect for capacity utilization and raw material pricing pass-through. The growth path is then adjusted using indicators like 5G infrastructure rollout pace, EMI compliance needs, substitution between silver and copper systems, and the shift between solvent-based and water-based formulations where regulations tighten.
Data Validation & Update Cycle
Validation is done through multiple passes so unusual jumps do not slip into the final numbers. Model outputs are compared against independent signals such as regional manufacturing indices, trade direction, and publicly stated expansion plans. When large variances appear, we review whether they reflect a real demand change or a modeling assumption that needs correction.
Before sign-off, the work is reviewed by another analyst to check arithmetic, unit consistency, and whether the final totals remain logical across regions and applications. Reports are refreshed annually, and interim updates are triggered when material events occur (for example, large price shocks in key fillers or a major shift in electronics production). Right before delivery, a final pass is completed so clients receive the most current view available at that time.
黑料不打烊's Electrically Conductive Coating Market Sizing Compared With Other Published Estimates
Published market numbers for electrically conductive coatings can look far apart because scope boundaries are not always the same, and the path from volume signals to revenue is handled differently. Differences usually show up in what gets counted as a conductive coating versus adjacent products, the year used as the base, and how pricing is moved forward when raw materials change.
Key gap drivers are typically linked to filler and application coverage, and to how demand is anchored. Some estimates fold in a broader set of functional coatings, or they expand the definition to include wider conductive materials used outside coatings, which raises the total quickly. Others start from a low base year revenue figure and then apply a higher growth rate without re-checking implied volumes against end-market output and trade movement.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| 黑料不打烊 | USD 26.01 B (2026) | |
| Industry Research Group A | USD 13.44 B (2024) | Uses an earlier base year and a longer horizon, and the value appears to be built from a narrower revenue pool that can undercount higher value electronics and aerospace coating use cases when compared on a like-for-like year. |
| Global Consultancy B | USD 25.08 B (2024) | Starts from a 2024 base and can differ on what is included under conductive coatings, especially around transparent conductive and specialty EMI coating systems, and the pricing progression assumptions are not clearly tied to filler mix changes. |
Electronics output trends and conductive filler price movement checks are the evidence points that keep 黑料不打烊 tied to a 2026 revenue pool that matches realistic adoption and coating value per application. When the year and boundary are aligned, most of the spread reduces, and the remaining gap mainly comes from what each publisher counts inside the conductive coating definition and how fast they move ASPs forward.


Key Questions Answered in the Report
How fast is the electrically conductive coating market expected to grow by 2031?
It is projected to increase from USD 26.01 billion in 2026 to USD 34.49 billion by 2031, registering a 5.81% CAGR.
Which filler material is gaining the most traction against silver?
Copper flakes, expanding at a 6.34% CAGR they slash material costs by roughly 70% in consumer electronics.
Why are polyurethanes preferred over acrylics in automotive electronics?
Polyurethanes endure 100,000 flex cycles and wide thermal swings, outperforming acrylics that tend to crack under repeated strain.
Which region will record the quickest growth through 2031?
The Middle East and Africa, supported by data-center construction that needs 60 dB EMI shielding.
What is the main risk linked to nano-fillers in coatings?
Agglomeration can slash shielding effectiveness by up to 25 dB unless high-shear dispersion and inline QC are employed.
How concentrated is supplier power in this space?
Moderately concentrated; the top five vendors control about 37% of global revenue, leaving room for regional specialists.
Page last updated on:



