
Electric Motorcycle Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 1.45 Billion |
| Market Size (2031) | USD 4.54 Billion |
| Growth Rate (2026 - 2031) | 25.72 % |
| Fastest Growing Market | South America |
| Largest Market | Asia-Pacific |
| Market Concentration | Low |
Major Players
*Disclaimer: Major Players sorted in no particular order Image ? 黑料不打烊. Reuse requires attribution under CC BY 4.0. |
|
Electric Motorcycle Market Analysis by 黑料不打烊
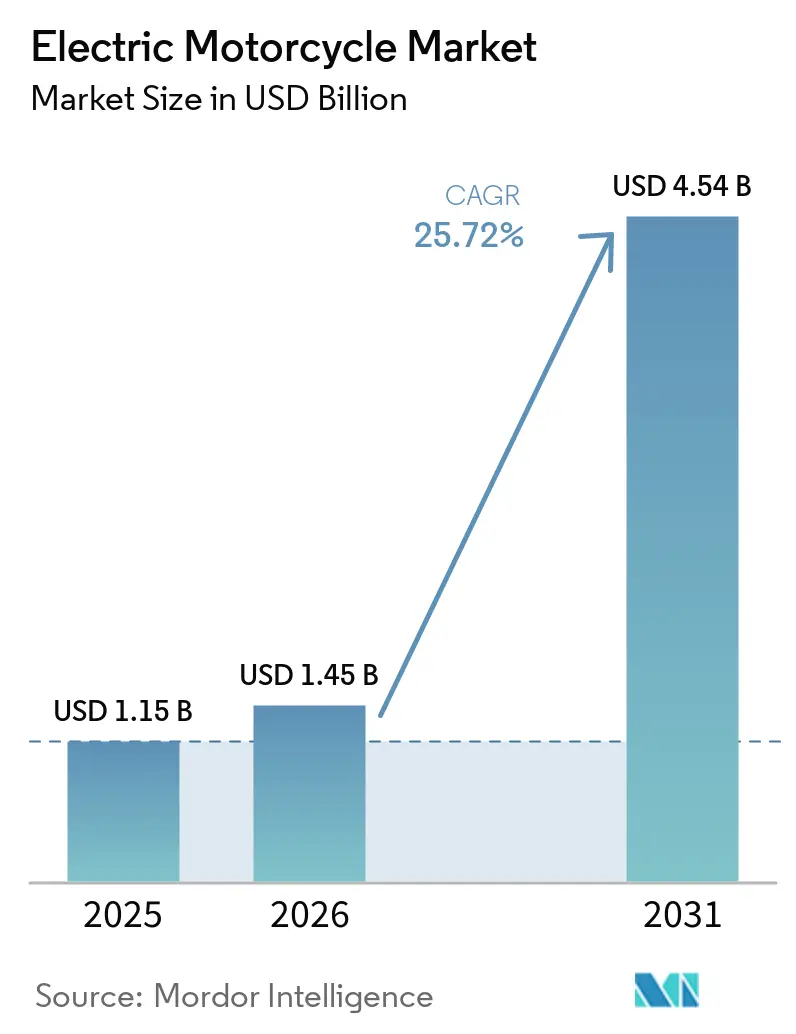
The electric motorcycle market was valued at USD 1.15 billion in 2025 and is expected to grow from USD 1.45 billion in 2026 to USD 4.54 billion by 2031, at a CAGR of 25.72% during the forecast period (2026–2031). Momentum reflects the convergence of urban commuters, delivery fleets, and performance riders on a single technology path that couples battery innovation with policy support. Charging and swap networks are expanding across dense megacities, closing convenience gaps that once favored gasoline. Manufacturers are expanding their product portfolios from entry-level scooters to 60 kW sport bikes, a range that reframes electric two-wheelers as mainstream rather than a novelty. The competitive field remains open, with regional specialists leveraging localized incentives and vertically integrated platforms to win share.
Key Report Takeaways
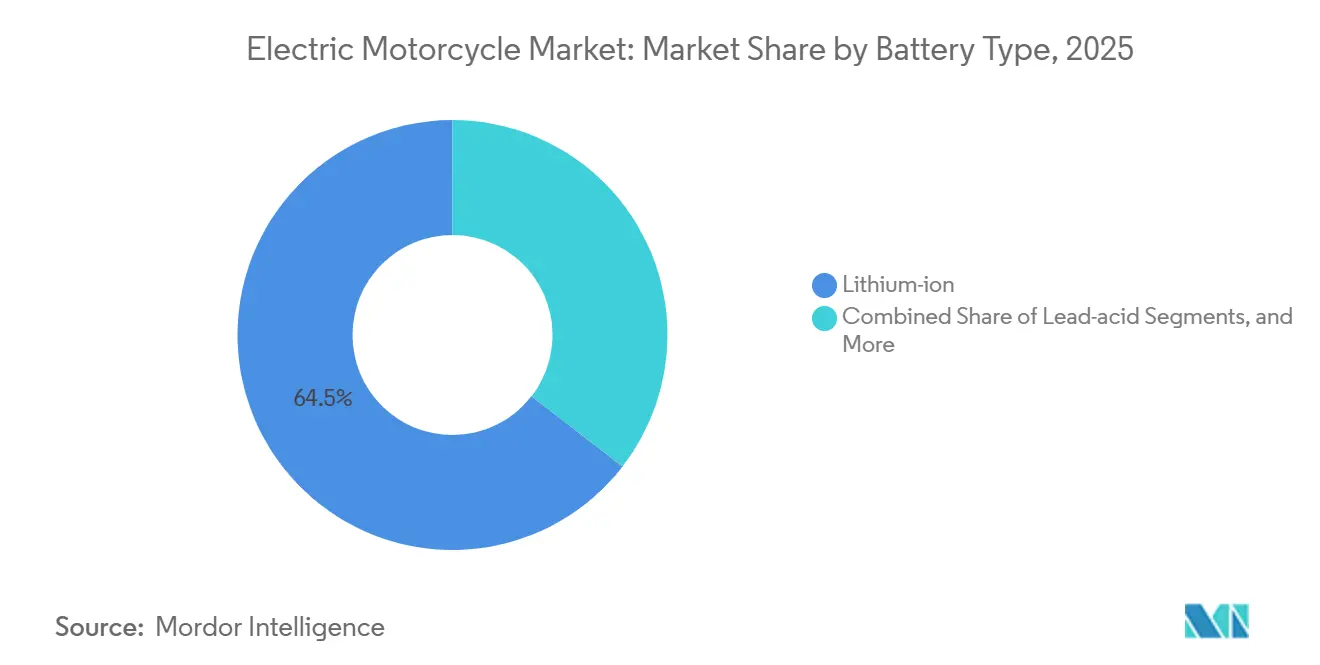
- By battery type, lithium-ion held 64.52% of the electric motorcycle market share in 2025, while sodium-ion and other emerging chemistries are projected to record a 26.92% CAGR through 2031.
- By power output, motorcycles below 3.6 kW led with 44.21% of the electric motorcycle market share in 2025; those above 10 kW are forecast to post the fastest CAGR, at 28.39% through 2031.
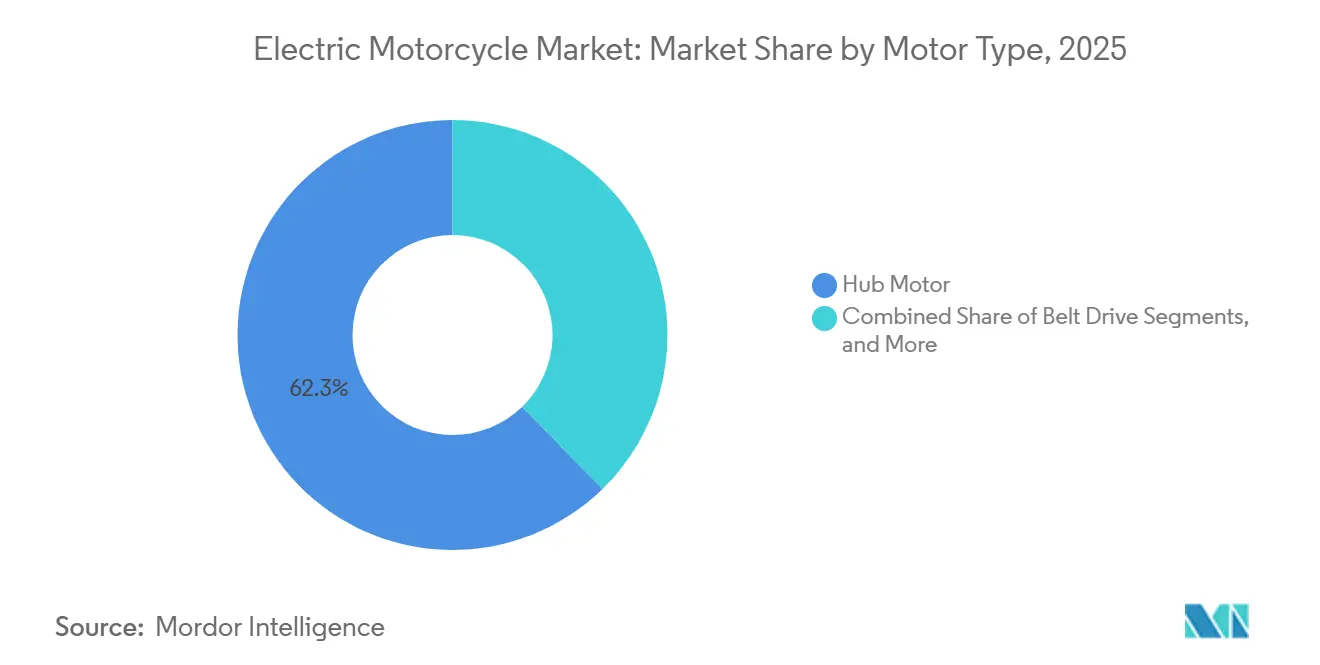
- By motor type, hub motors captured 62.29% of the electric motorcycle market share in 2025, whereas mid-drive motors are anticipated to grow at a 28.49% CAGR through 2031.
- By end-use, personal ownership accounted for 78.31% of the electric motorcycle market size in 2025, and delivery & logistics fleets are advancing at a 29.34% CAGR to 2031.
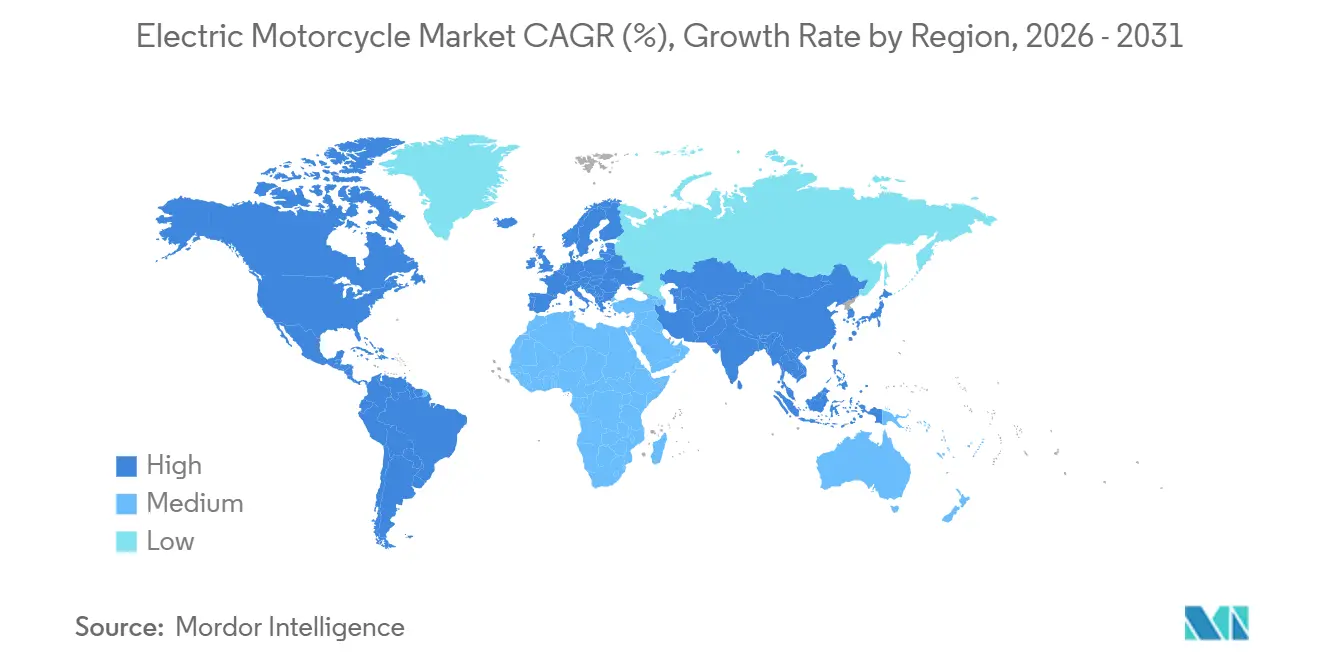
- By geography, Asia-Pacific commanded 73.28% of the electric motorcycle market share in 2025, and South America is expanding the fastest at a 27.07% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using 黑料不打烊’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Electric Motorcycle Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Li-Ion Cost Drop and Energy Density Gains | +3.8% | Global, with strongest impact in Asia-Pacific and Europe | Medium term (2-4 years) |
| Govt Incentives and Zero-Emission Mandates | +3.3% | North America and EU core, expanding to Asia-Pacific markets | Short term (≤ 2 years) |
| 2W Charging and Swap Network Expansion | +2.9% | Asia-Pacific core, spill-over to South America and MEA | Medium term (2-4 years) |
| Micromobility Fleets Lower TCO, Drive Adoption | +2.7% | Global, with early commercialization in China and India | Long term (≥ 4 years) |
| Breakthrough Sodium-Ion and Solid-State Chemistries | +2.4% | Urban centers globally, concentrated in North America and Europe | Short term (≤ 2 years) |
| OTA Connectivity and In-Vehicle Data Monetization | +1.8% | Developed markets first, expanding to emerging economies | Medium term (2-4 years) |
| Source: 黑料不打烊 | |||
Falling Lithium-Ion Battery Costs and Rising Energy Density
Cell suppliers have trimmed per-kilowatt-hour pricing consistently since 2024, a decline matched by consistent gains in watt-hours per kilogram[1]Andy Colthorpe, "Li-ion battery pack prices fell 8% since last year despite metals prices rising," Energy-Storage.News, www.energy-storage.news. The result is smaller packs that carry riders farther without enlarging chassis envelopes. As warranties stretch beyond five years, resale values improve, shrinking the depreciation gap with gasoline models. Supply chains are also diversifying into iron-rich chemistries that avoid price-volatile cobalt, further stabilizing cost curves. Together, these advances make electric drivetrains the default choice for price-sensitive commuters.
Government Purchase Incentives and Zero-Emission Mandates
National and state programs continue to lower acquisition costs for buyers who once viewed electric motorcycles as premium luxuries. India renewed its PM E-DRIVE scheme and simultaneously outlined a follow-on FAME-II outlay, keeping subsidies visible for 2-3 years. California retains point-of-sale rebates, and Brazil’s MOVER framework pairs tax relief with local assembly incentives [2]"Brazil Automotive Incentives for EV Competition and Innovation," ITA, trade.gov. These measures shorten payback periods, especially for commercial fleets that clock high daily mileage. The policy momentum also sends a demand signal that supports the expansion of domestic manufacturing.
Expansion of Two-Wheeler Charging and Swap Networks
Swap hubs and fast-charge posts now dot city blocks in Taipei, Hanoi, Jakarta, and S?o Paulo. Riders can exchange a depleted pack in seconds or top up during a coffee stop, erasing range anxiety for daily use. Infrastructure providers often partner with convenience-store chains or fuel retailers, leveraging existing real estate for rapid rollouts. Subscription models bundle energy access with maintenance, turning charging into a predictable operating expense. As networks interconnect across borders, cross-regional touring without lengthy stops becomes feasible.
Micromobility Delivery Fleet Adoption (Lower TCO)
Courier and food-delivery operators measure cost per kilometer in pennies, so eliminating gasoline and oil changes delivers immediate savings. Electric powertrains excel in stop-and-go duty cycles where regenerative braking recovers energy and maintenance needs are minimal. Municipal clean-air zones grant electric fleets priority curb space, translating environmental compliance into shorter routes and faster drops. Financial institutions have begun underwriting battery-as-a-service contracts that align monthly payments with revenue flows, easing capital-outlay concerns. As algorithms optimize dispatch using connected-vehicle data, fleet utilization climbs and economics improve further.
Restraints Impact Analysis of Electric Motorcycle Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Upfront Cost vs. ICE Motorcycles | -2.8% | Global, with strongest impact in price-sensitive emerging markets | Short term (≤ 2 years) |
| Limited Range and Slow Charging Above 7kW | -2.1% | Global, particularly affecting highway and long-distance applications | Medium term (2-4 years) |
| Thermal Safety Challenges in Tropical Fleets | -1.6% | Tropical regions including Southeast Asia, India, and parts of South America | Medium term (2-4 years) |
| Weak Battery End-of-Life Collection in Emerging Markets | -1.3% | Emerging markets in Asia-Pacific, Africa, and South America | Long term (≥ 4 years) |
| Source: 黑料不打烊 | |||
High Upfront Price Premium vs ICE Motorcycles
Even after subsidies, many entry-level electric motorcycles still list at nearly double the sticker price of comparable gasoline models. The differential remains a hurdle where financing options are sparse, and household budgets are tight. Import tariffs in several South American countries keep landed costs elevated. Manufacturers are piloting pay-per-use batteries and lease-to-own plans, but these depend on credit scoring and residual-value certainty that are not yet universal. Bridging this gap hinges on deeper local assembly and continued declines in battery costs.
Limited Real-World Range and Slow Charge Above 7 kW
Advertised range figures assume urban speeds and mild temperatures that few riders experience year-round. Sustained highway cruising or winter chills can halve practical autonomy. Fast-charging hardware exceeding 7 kW is still concentrated in capital cities, leaving rural riders tied to overnight Level 2 outlets. Thermal management throttles charging rates as packs near full, making pit stops feel longer than five-minute fuel fills. Until breakthroughs in chemistry or infrastructure shrink charge windows below the coffee-break threshold, long-distance touring will remain an edge case.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Electric Motorcycle Market Segment Analysis
By Battery Type:
Diversification Beyond Lithium Takes HoldLithium-ion held 64.52% of the electric motorcycle market share in 2025, confirming its role as the default chemistry for mainstream price and performance expectations. Sodium-ion packs, projected to expand at a 26.92% CAGR, appeal to manufacturers seeking relief from lithium supply constraints and cobalt volatility. Smaller players leverage sodium’s tolerance for deep discharges to extend warranty confidence. Component standardization also improves cross-model compatibility, enabling second-life deployments in stationary storage.
A broader chemistry toolkit helps brands match battery attributes to rider priorities. Cost-sensitive commuters opt for durable, slower-charging packs, while performance enthusiasts lean toward high-power variants with stringent thermal control. The emerging mosaic reduces systemic supply risk and encourages localized cell production, an advantage for regions with abundant sodium or iron feedstocks. As chemistries proliferate, after-sales models evolve to handle mixed recycling streams and chemistry-specific diagnostics.


By Power Output:
Performance Tiers Reshape Market PerceptionMotorcycles below 3.6 kW captured 44.21% of the electric motorcycle market share in 2025, favored by urban riders and regulators that classify them under moped licensing rules. The above-10 kW class, forecasted to grow at a 28.39% CAGR, demonstrates that electric drivetrains can satisfy thrill seekers without compromise. Premium brands showcase brisk acceleration and track-day capability, reframing electric two-wheelers as legitimate substitutes for mid-displacement sport bikes.
As energy density inches upward, mid-range 7.2–10 kW machines bridge daily commutes and weekend highway hops. Riders discover that instant torque flattens city gradients and merges effortlessly into traffic. Dealers report fewer test-ride skeptics once buyers experience silent launches and regenerative braking. These qualitative gains matter as much as raw kilowatts, nudging fence-sitters toward electric adoption.
By Motor Type:
Mid-Drive Systems Win Enthusiast ApprovalHub motors accounted for 62.29% of the electric motorcycle market share in 2025, driven by their low maintenance requirements and straightforward manufacturing. Manufacturers favor these systems because they integrate directly into the wheel, reducing mechanical complexity and assembly costs. Mid-drive units are projected to record the fastest CAGR of 28.49%, preferred by riders who require balanced weight distribution and selectable gearing. These units replicate gasoline torque curves, reducing the adjustment period for experienced riders transitioning to electric motorcycles.
Chain- and belt-driven variants occupy smaller market segments, each addressing specific maintenance preferences and noise considerations. Belt drives, for instance, appeal to urban commuters who prioritize quiet operation, while chain drives remain common in performance-oriented applications. Suppliers now offer modular frames compatible with both hub- and mid-drive architectures, enabling manufacturers to respond quickly to shifting demand patterns. This range of drivetrain options allows the market to serve both cost-focused fleet operators and performance-oriented consumers while maintaining economies of scale.
By End-Use:
Commercial Fleets Gain Strategic WeightPersonal ownership accounted for 78.31% of the electric motorcycle market share in 2025, while delivery and logistics fleets are growing at the fastest rate, with a CAGR of 29.34%. Fleet managers are attracted to predictable maintenance schedules and fuel savings that accumulate across thousands of daily stops. In many cities, electric vehicle registrations allow access to curb-side areas during peak-hour restrictions, a non-monetary benefit that improves delivery density. These practical advantages make electric two- and three-wheelers a logical choice for fleet operators managing tight margins and strict delivery timelines.
Micromobility operators are also expanding, though their share remains modest relative to personal ownership. Subscription and pay-per-minute models introduce occasional users to electric riding, potentially supporting future retail demand. Corporate sustainability requirements are prompting enterprises to replace staff fleets with zero-emission options, reinforcing a shift from individual purchase decisions to institutional procurement cycles. As organizations set measurable emissions targets, fleet electrification is increasingly treated as an operational priority rather than an optional upgrade.
Geography Analysis
APAC Electric Motorcycle Market
Asia-Pacific dominates the electric motorcycle market, holding 73.28% of the global share in 2025. Dense cities, established two-wheeler cultures, and strong fiscal incentives combine to accelerate turnover from petrol to battery power. Battery-swap ecosystems in China, Taiwan, and Indonesia keep refueling downtime competitive with gasoline, while India’s policies sustain high unit growth despite subsidy tapering. Japan and South Korea progress at a measured pace, balancing the protection of domestic industry with decarbonization targets. The region’s ecosystem now attracts component suppliers looking to colocate pack assembly near vehicle plants.
South America Electric Motorcycle Market
South America is poised for the fastest CAGR of 27.07% to 2031, supported by Brazil’s MOVER industrial framework and a growing network of regional assembly sites. Local content rules and tax waivers entice manufacturers to plant stakes, lowering exposure to currency swings. Argentina’s tariff structure tempers near-term momentum but may ease as policymakers weigh emissions goals against consumer affordability. Infrastructure rollouts cluster around megacities such as S?o Paulo and Buenos Aires, where congestion charges and rideshare demand overlap.
EMEA and North America Electric Motorcycle Market
Europe and North America adopt at moderate speeds, shaped by a mosaic of national incentives and urban clean-air zones. London, Paris, and Milan penalize gasoline two-wheelers in central districts, pushing couriers toward electric leases. In the United States, California and Oregon spearhead state-level rebates, while broader uptake waits on long-range touring models that fit into weekend leisure culture. Middle East and Africa remain early-stage: swap pilots in Kenya and Rwanda illustrate creative solutions in grid-constrained settings, and Gulf states couple electric mandates with large-scale charging investments to align with net-zero roadmaps.

Competitive Landscape
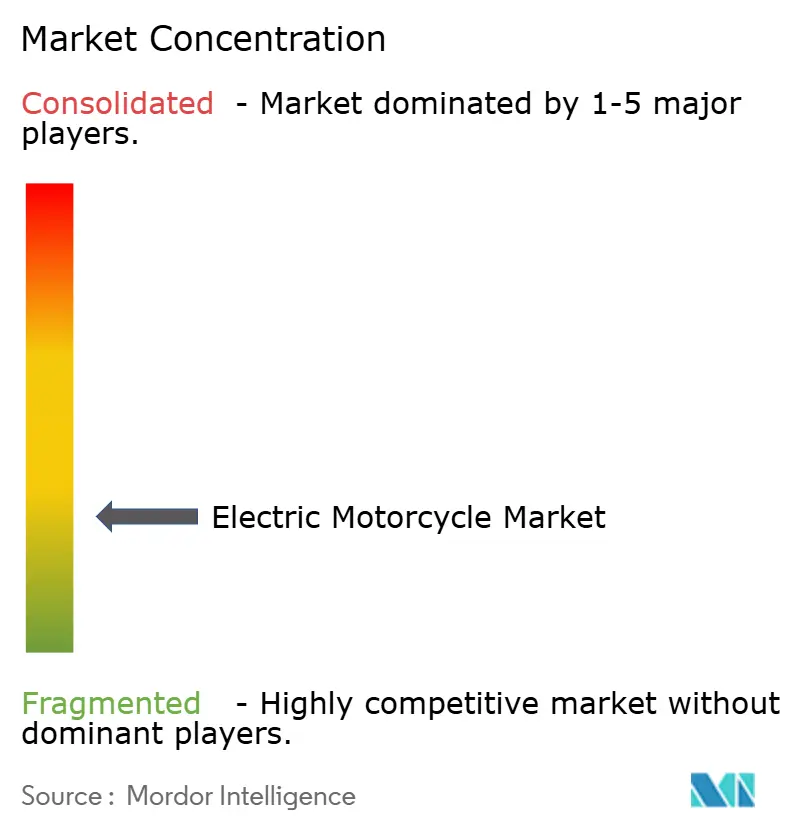
The electric motorcycle market remains fragmented, with the five largest brands—NIU Technologies, Yadea Group, LiveWire, Vmoto, and Zero Motorcycles—collectively accounting for only a small share of global volume. This fragmentation creates significant opportunities for new entrants. NIU differentiates itself through software, using over-the-air updates and a monthly subscription tier to generate recurring revenue and keep its hardware up to date. This model reduces warranty costs and strengthens customer retention. LiveWire, which Harley-Davidson spun off, mitigates R&D risk by co-developing platforms with KYMCO. Its joint S2 maxi-scooter targets first-time electric vehicle buyers in Europe and Asia. Vmoto and Zero Motorcycles complete the leading group by combining Western brand appeal with contract manufacturing in Asia, enabling them to maintain lean cost structures while preserving premium market positioning.
A second layer of competition comes from agile start-ups that specialize in performance niches. Stark Future’s 60 kW motocross bike illustrates how small teams can leapfrog legacy players by sourcing turnkey powertrains and focusing on lightweight frames and distinctive styling. These brands allocate capital to composite materials and advanced thermal management rather than large dealer networks, relying instead on direct-to-consumer channels and pop-up test-ride events. Battery suppliers increasingly court such specialists with modular packs that integrate battery management systems, thereby cutting engineering lead times.
Regional assemblers and component makers further fragment the field. Kenyan and Rwandan start-ups pair battery-swap infrastructure with locally assembled two-wheelers, tailoring durability for rough roads and monetizing energy subscriptions rather than vehicle sales. European accessory suppliers now offer plug-and-play mid-drive kits that let boutique labels launch limited runs without full homologation cycles. Cloud-based telematics platforms provide over-the-air diagnostics and predictive maintenance analytics, enabling even small brands to match the connectivity features of larger rivals.
Electric Motorcycle Industry Leaders
-
NIU Technologies
-
Yadea Group Holdings Ltd.
-
LiveWire EV, LLC
-
Vmoto Limited
-
Zero Motorcycles Inc.
- *Disclaimer: Major Players sorted in no particular order
Electric Motorcycle Market Companies Covered in this Report
- Yadea Group Holdings Ltd.
- NIU Technologies
- Vmoto Limited
- Zero Motorcycles Inc.
- Energica Motor Company S.p.A
- LiveWire EV, LLC
- HORWIN Inc.
- Revolt Intellicorp Private Limited (Revolt Motors)
- Honda Motor Co. Ltd.
- Yamaha Motor Co. Ltd.
- Oben EV SPA
- Verge Motorcycles O?
- Damon Inc.
- LAND Moto

Recent Industry Developments in Electric Motorcycle Market
- August 2026: Hero MotoCorp confirmed that it would launch its first electric motorcycle in 2027, expanding the VIDA portfolio beyond scooters and entering India’s nascent electric motorcycle segment.
- July 2026: Honda launched the WN7, its first full-size electric motorcycle, in Europe, now available at dealerships, marking its entry into the premium electric motorcycle market.
- April 2026: Kenyan manufacturer Roam introduced the Roam Air Gen 3, adding a theft-resistant, fast-charge battery tailored to Africa’s delivery sector.
- April 2026: Royal Enfield unveiled the Flying Flea C6, a lightweight model with a forged aluminum frame designed for urban agility.


Global Electric Motorcycle Market Report Scope
The electric motorcycle market is segmented by battery type, power output, motor/drive type, end use, and geography.
By Battery Type, the market is segmented into Lead-acid, Lithium-ion, Lithium-ion Polymer, Sodium-ion & Emerging. By Power Output, the market is segmented into the following ranges: Below 3.6 kW, 3.6 - 7.2 kW, 7.2 - 10 kW, and Above 10 kW. By Motor / Drive Type, the market is segmented into Hub Motor, Belt Drive, Chain Drive, and Mid-drive Motor. By End-use, the market is segmented into Personal / Individual, Commercial & Corporate, Micromobility Service, and Delivery & Logistics. By Geography, the market is segmented into North America (United States, Canada, and Rest of North America), South America (Brazil, Argentina, and Rest of South America), Europe (United Kingdom, Germany, Spain, Italy, France, Russia, and Rest of Europe), Asia-Pacific (India, China, Japan, South Korea, and Rest of Asia-Pacific), and Middle East & Africa (United Arab Emirates, Saudi Arabia, Turkey, Egypt, South Africa, and Rest of Middle East & Africa).
Market forecasts are provided in terms of Value (USD) and Volume (Units).
| Lead-acid |
| Lithium-ion |
| Lithium-ion Polymer |
| Sodium-ion & Emerging Chemistries |
| Below 3.6 kW |
| 3.6 - 7.2 kW |
| 7.2 - 10 kW |
| Above 10 kW |
| Hub Motor |
| Belt Drive |
| Chain Drive |
| Mid-drive Motor |
| Personal / Individual |
| Commercial & Corporate Fleets |
| Micromobility Service Providers |
| Delivery & Logistics |
| North America | United States |
| Canada | |
| Rest of North America | |
| South America | Brazil |
| Argentina | |
| Rest of South America | |
| Europe | United Kingdom |
| Germany | |
| Spain | |
| Italy | |
| France | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | India |
| China | |
| Japan | |
| South Korea | |
| Rest of Asia-Pacific | |
| Middle East and Africa | United Arab Emirates |
| Saudi Arabia | |
| Turkey | |
| Egypt | |
| South Africa | |
| Rest of Middle East and Africa |
| By Battery Type | Lead-acid | |
| Lithium-ion | ||
| Lithium-ion Polymer | ||
| Sodium-ion & Emerging Chemistries | ||
| By Power Output | Below 3.6 kW | |
| 3.6 - 7.2 kW | ||
| 7.2 - 10 kW | ||
| Above 10 kW | ||
| By Motor / Drive Type | Hub Motor | |
| Belt Drive | ||
| Chain Drive | ||
| Mid-drive Motor | ||
| By End-use | Personal / Individual | |
| Commercial & Corporate Fleets | ||
| Micromobility Service Providers | ||
| Delivery & Logistics | ||
| By Region | North America | United States |
| Canada | ||
| Rest of North America | ||
| South America | Brazil | |
| Argentina | ||
| Rest of South America | ||
| Europe | United Kingdom | |
| Germany | ||
| Spain | ||
| Italy | ||
| France | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | India | |
| China | ||
| Japan | ||
| South Korea | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | United Arab Emirates | |
| Saudi Arabia | ||
| Turkey | ||
| Egypt | ||
| South Africa | ||
| Rest of Middle East and Africa | ||


Key Questions Answered in the Report
How large will the electric motorcycle market be by 2031?
It is forecasted to reach USD 4.54 billion, expanding at a 25.72% CAGR from 2026 to 2031.
Which battery chemistry grows fastest in electric two-wheelers?
Sodium-ion packs are projected to rise at a 26.92% CAGR through 2031, outpacing lithium variants.
Which power segment shows the highest momentum?
Motorcycles above 10 kW are expected to post the fastest 28.39% CAGR to 2031.
Which region commands the largest share of current electric motorcycle sales?
Asia-Pacific held 73.28% of global revenue in 2025.
Page last updated on:



